
 Scrubber Dryer Market | 2026-2036
Scrubber Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Scrubber Dryer Market Analysis
Buyer concentration in the hospitality sector is shifting as hotel chains consolidate property management under fewer national operators. Tennant Company leverages its North American service network to sustain long-term contracts with these consolidated buyers. Alfred Kärcher SE & Co. KG anchors European demand through its dense distributor presence in German-speaking markets. Nilfisk Group competes on robotic technology leadership, positioning its autonomous scrubber lines for labor-cost-sensitive facility managers.
A scrubber dryer is a powered floor-cleaning machine that applies cleaning solution, scrubs surfaces with rotating brushes or pads at 200-400 RPM, and recovers wastewater through a vacuum squeegee system for immediate drying. The equipment serves commercial and industrial environments where foot traffic, hygiene protocols, or safety regulations prohibit wet floors during operating hours. Ride-on configurations dominate margin pools in large-format retail and logistics warehouses where operator productivity scales with machine size. Robotic technology represents the fastest-expanding segment as autonomous navigation systems reduce labor dependency in overnight cleaning windows. Walk-behind units remain the mature volume base in healthcare and education settings where capital budgets constrain upfront investment.
OSHA workplace safety standards in the United States mandate slip-resistant surfaces, directly shaping scrubber dryer specifications for squeegee recovery efficiency and drying speed. The EU Green Deal and REACH chemical frameworks restrict cleaning solution formulations, pushing manufacturers toward water-recycling systems and biodegradable detergent compatibility. Stakeholders must monitor how battery regulations from the EPA and emerging state-level right-to-repair legislation affect equipment lifecycle economics and aftermarket service revenue structures.
Market Dynamics
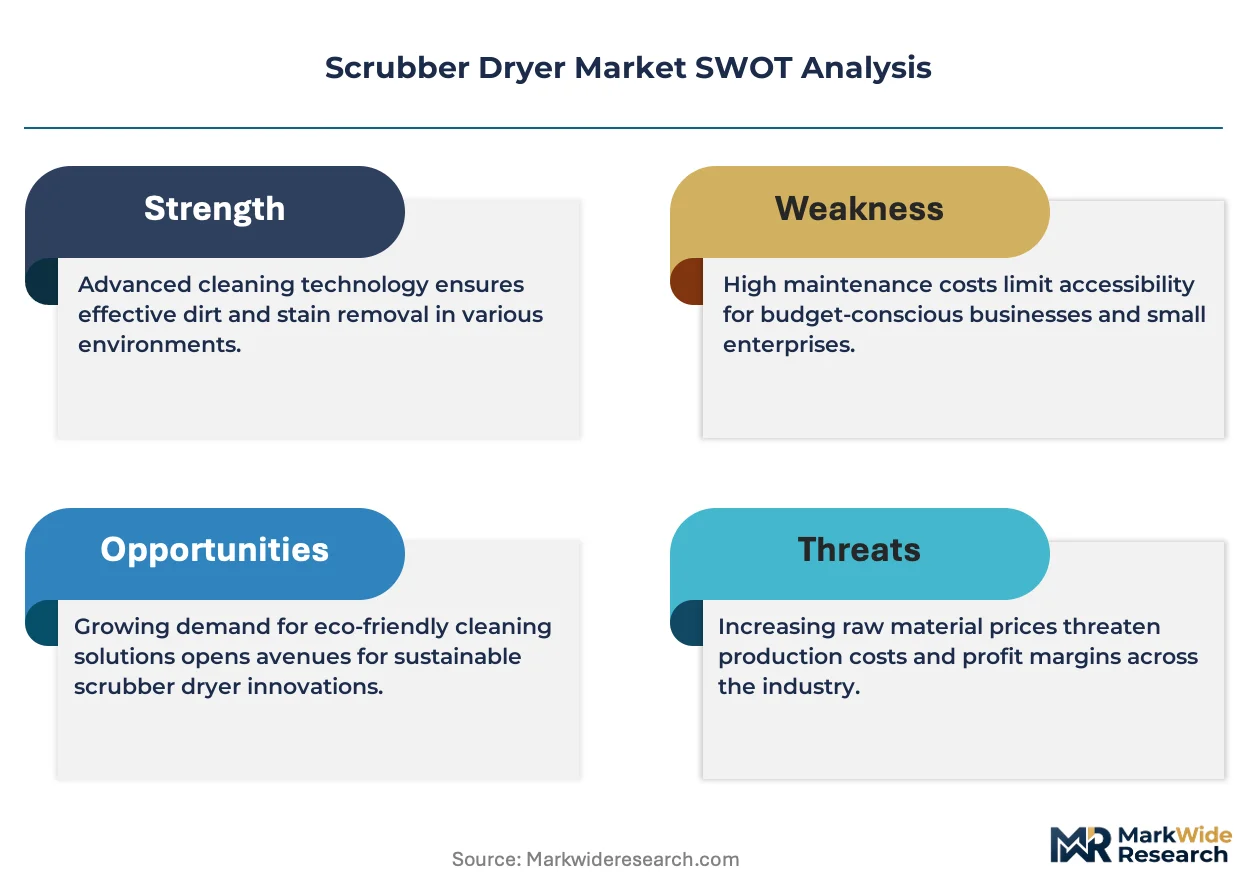
Battery chemistry evolution is compressing equipment replacement cycles as lithium-ion runtime improvements render legacy lead-acid fleets economically obsolete across commercial cleaning operations.
Growth Catalysts
- Joint Commission sanitation mandates:US healthcare facilities face escalating audit pressure for HAI prevention, driving automated floor equipment procurement in hospitals and outpatient clinics.
- EU Green Deal water-recycling requirements:REACH framework restrictions on chemical discharge push manufacturers toward closed-loop detergent systems and greywater recovery technology.
- Industrial manufacturing concentration in Germany:Berufsgenossenschaft workplace safety rules sustain premium equipment replacement cycles in automotive and logistics facilities.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing OEMs to geopolitical supply disruption and input cost volatility.
- Capital intensity of robotic navigation:LIDAR and SLAM sensor suites add 40-60% to base machine cost, constraining penetration in budget-constrained education and municipal segments.
- Right-to-repair legislative friction:Emerging US state-level repair mandate proposals threaten manufacturer control over proprietary battery management systems and software-locked components.
Strategic Opportunities
- Autonomous overnight cleaning windows:Robotic scrubber deployment in logistics warehouses and distribution centers addresses labor scarcity while eliminating daytime traffic interference.
- India BIS certification pathway:Formal adoption of IEC 60335 safety standards for battery-powered cleaning equipment opens institutional procurement channels in hospitality and healthcare.
- Service contract unbundling:Fleet management platforms enable predictive maintenance monetization separate from equipment sale, shifting revenue toward recurring software and consumables.
Industry Challenges
- Electromechanical technician scarcity:Maintenance of brush drive systems, vacuum motors, and battery management electronics requires specialized training unavailable in standard janitorial workforces.
- Legacy fleet integration complexity:Mixed-vendor environments complicate centralized fleet management software deployment and unified operator training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scrubber Dryer Market |
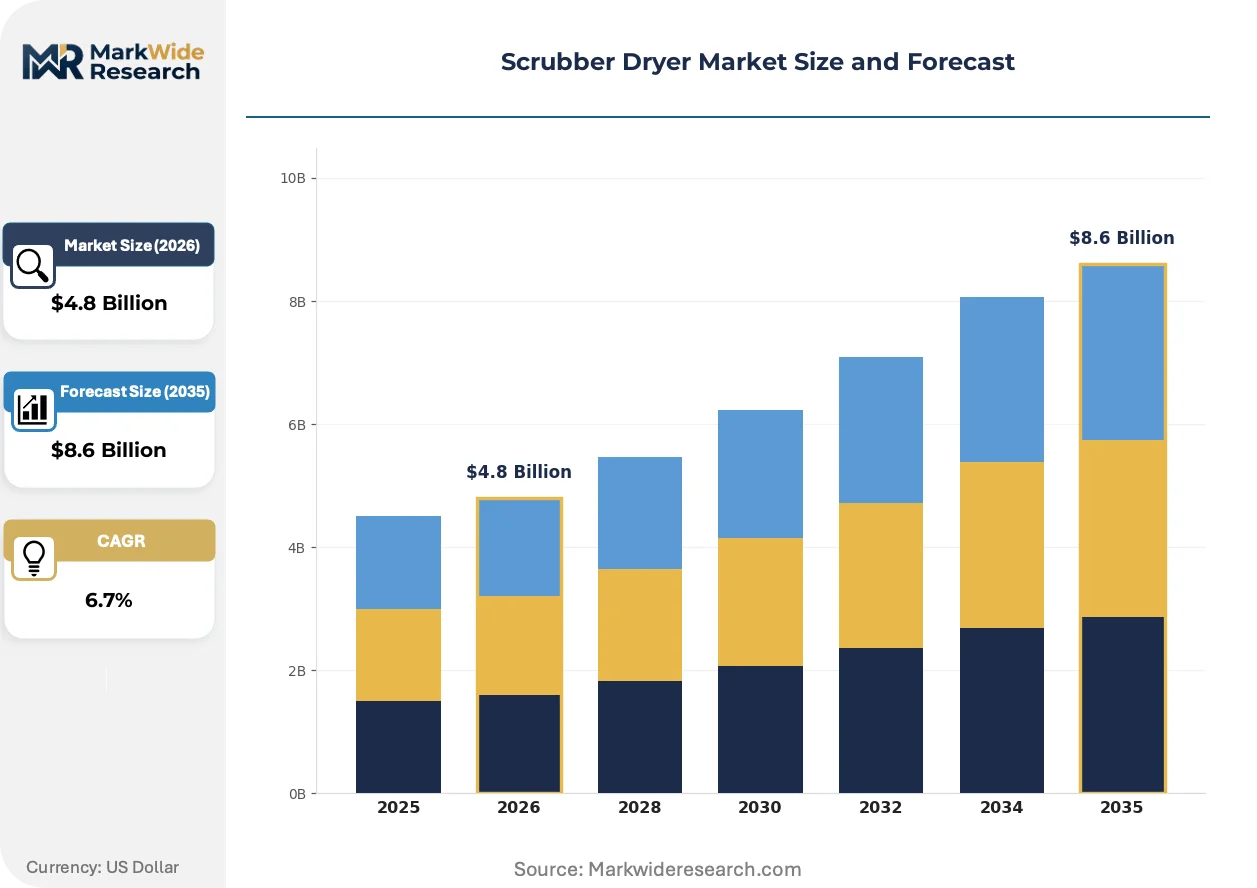
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Behind, Ride-On, Compact, Industrial Technology: Manual, Automatic, Hybrid, Robotic End User: Manufacturing, Hospitality, Retail, Healthcare Distribution Channel: Online, Direct Sales, Wholesale, Distributors |
| Companies Covered | Tennant Company, Alfred Kärcher SE & Co. KG, Nilfisk Group, Hako Group, Taski, Numatic International, Fimap, IPC Eagle, Advance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scrubber Dryer Market Emerging Trajectories
Equipment intelligence is migrating from standalone machines toward connected fleet ecosystems, reshaping how facility managers optimize cleaning coverage, labor allocation, and total cost of ownership.
Autonomous navigation is unifying scrubber and sweeper functions into single-pass robotic platforms. Third-party logistics operators in Germany and the United States are piloting these hybrid units in 500,000+ square foot distribution centers. The technology is unifying previously separate capital equipment categories into consolidated procurement decisions.
REACH chemical framework revisions are restricting quaternary ammonium compound concentrations in commercial cleaning solutions. Equipment manufacturers must redesign solution tanks and pump systems for biodegradable surfactant compatibility. Walk-behind unit producers serving European healthcare and food processing verticals face the most intensive engineering adaptation timelines.
Consolidated property management companies are centralizing equipment procurement through national fleet agreements. Hotel chains and retail operators now specify standardized machine configurations across hundreds of locations. This concentration is most visible in the United States, where three national hospitality operators control equipment selection for over 12,000 properties.
Scrubber Dryer Market Segmentation
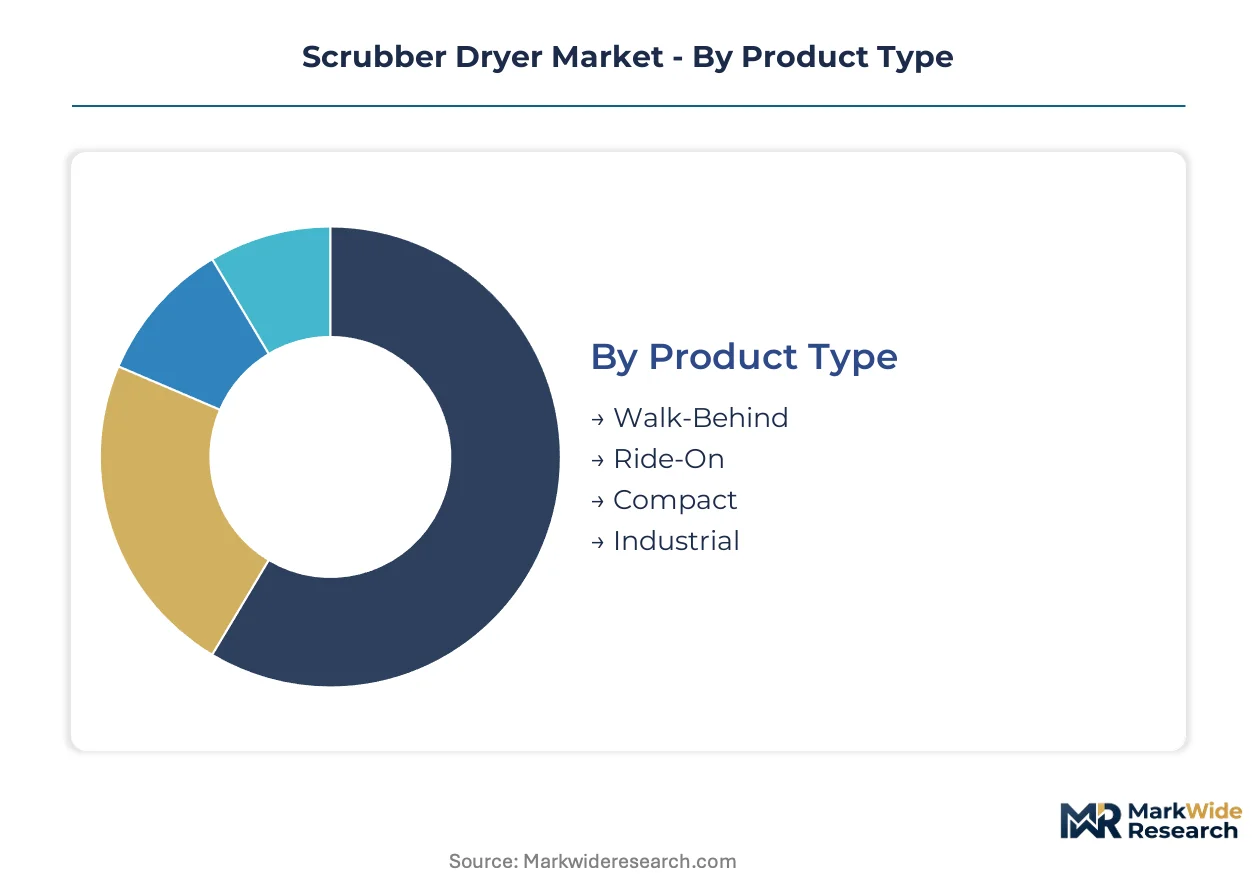
Scrubber dryer procurement patterns diverge sharply across equipment configurations and operational contexts. Facility managers align capital deployment with labor economics, floor area, and regulatory compliance burdens specific to their vertical.
Product Type:
Replacement cycles and productivity thresholds determine equipment selection as facilities balance upfront capital against lifetime operating cost.
- Ride-On:These machines carry 200-400 liter solution tanks and operate at 6-10 km/h cleaning speeds across 10,000+ square meter facilities. Logistics warehouses in Germany specify ride-on units under Berufsgenossenschaft productivity mandates that tie equipment capability to operator hourly output targets.
- Robotic:Autonomous navigation systems using LIDAR and SLAM sensors eliminate operator labor entirely for overnight cleaning windows. Third-party logistics operators in the United States deploy these units in 500,000+ square foot distribution centers where labor scarcity constrains manual cleaning crews.
- Walk-Behind:Compact 40-60 liter tank configurations serve healthcare and education settings where capital budgets limit upfront investment.
- Compact:Narrow 50cm cleaning paths navigate confined retail aisles and restaurant kitchens with restricted maneuvering space.
- Industrial:Heavy-duty brush systems handle manufacturing floor contaminants including metal shavings, oil residues, and chemical spills.
Ride-On configurations sit at the top of the volume ranking, with Robotic systems climbing the fastest.
Technology:
Automation intensity separates cost tiers as facilities evaluate labor substitution against capital recovery timelines.
- Robotic:Fully autonomous units integrate fleet management software for predictive maintenance and coverage optimization. German automotive plants deploy these systems to satisfy EU Green Deal requirements for overnight energy consumption scheduling.
- Automatic:Semi-autonomous features including solution dosing and brush pressure adjustment reduce operator training requirements. US hospital chains specify automatic units to meet Joint Commission sanitation consistency standards.
- Manual:Operator-controlled functions dominate budget-constrained municipal and education procurement.
- Hybrid:Selectable automation modes allow manual override for irregular floor layouts or emergency spill response.
Manual technology retains the largest installed base, while Robotic platforms show the steepest expansion trajectory.
End User:
Regulatory pressure and operating hour constraints shape vertical-specific equipment specifications.
- Healthcare:HAI prevention protocols mandate immediate floor drying and solution recovery efficiency. US outpatient clinics expand automated fleets to satisfy Joint Commission audit requirements for environmental hygiene.
- Manufacturing:Contaminant-specific brush configurations handle oil, grease, and particulate matter. German automotive facilities replace equipment on compressed cycles under workplace safety rules.
- Hospitality:Consolidated hotel chains centralize procurement through national fleet agreements covering thousands of properties.
- Retail:Large-format stores prioritize ride-on productivity for overnight cleaning windows before opening hours.
Manufacturing commands the highest equipment replacement frequency, with Healthcare gaining share fastest on regulatory compliance spending.
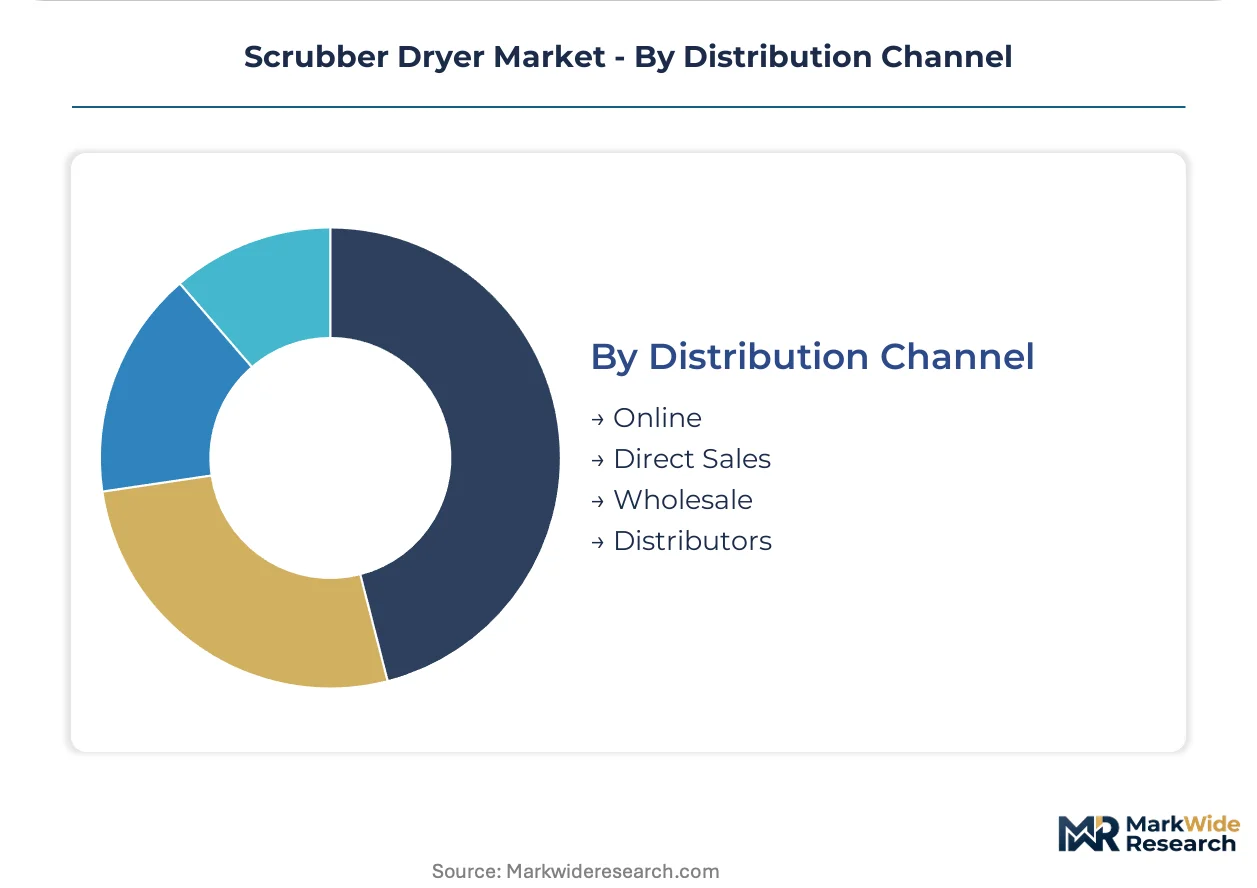
Distribution Channel:
Service integration and procurement scale determine channel selection across customer segments.
- Distributors:Dense regional networks provide same-day parts availability and technician dispatch. Alfred Kärcher SE & Co. KG anchors European demand through German-speaking market distributor relationships.
- Direct Sales:National fleet agreements with consolidated hospitality and retail operators bypass intermediary margins. Tennant Company leverages its North American service network to sustain long-term direct contracts.
- Online:Digital procurement platforms serve small facilities and replacement part purchases.
- Wholesale:Volume aggregators supply independent cleaning contractors and municipal purchasers.
Distributors maintain the broadest geographic coverage, with Direct Sales expanding fastest on consolidated buyer concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electromechanical technicians cluster in German industrial regions and US Midwest manufacturing belts, anchoring aftermarket service capacity for automated cleaning equipment.
United States
Consolidated hospitality operators control procurement for over 12,000 properties, driving standardized fleet specifications. OSHA slip-resistance mandates shape squeegee recovery efficiency requirements. Third-party logistics operators in Dallas-Fort Worth and Chicago deploy autonomous units in 500,000+ square foot distribution centers.
Germany
Automotive and logistics facilities sustain premium equipment replacement cycles under Berufsgenossenschaft workplace safety rules. EU Green Deal water-recycling requirements push manufacturers toward closed-loop detergent systems. Stuttgart and Wolfsburg manufacturing corridors anchor demand for heavy-duty industrial configurations.
China
Battery cell manufacturing concentration exposes OEMs to cathode material processing bottlenecks. GB standards and dual carbon goals reshape equipment energy efficiency specifications. Shanghai and Shenzhen logistics hubs pilot robotic overnight cleaning to address labor scarcity in warehouse operations.
India
Formal adoption of IEC 60335 safety standards for battery-powered cleaning equipment opens institutional procurement channels. BIS certification pathways enable hospitality and healthcare vertical expansion. Mumbai and Bangalore facility managers evaluate compact walk-behind units for constrained retail and clinic footprints.
United Kingdom
REACH chemical framework revisions restrict quaternary ammonium compound concentrations in commercial cleaning solutions. Healthcare estates in London and Manchester expand automated fleets to satisfy environmental hygiene audit protocols. Distribution networks concentrate in Midlands logistics corridors serving consolidated retail chains.
Scrubber Dryer Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology and service tiers. Market structure tilts toward consolidation at the premium end while fragmenting across mid-market walk-behind segments. Three archetypes dominate: integrated manufacturers with captive battery supply, regional distributors with dense service networks, and robotics specialists with autonomous navigation IP. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure lithium-ion cell allocation and LIDAR sensor supply.
Among North American integrated manufacturers, Tennant Company anchors premium-tier positioning through its direct sales and service infrastructure. Alfred Kärcher SE & Co. KG exemplifies the European distributor-dense model with concentrated presence in German-speaking markets. Nilfisk Group occupies the robotics-forward archetype, positioning autonomous product lines for labor-cost-sensitive facility managers. These three represent divergent strategic paths: captive service monetization, geographic density advantage, and technology-led automation substitution.
| Leading Market Players |
|---|
| Tennant Company |
| Alfred Kärcher SE & Co. KG |
| Nilfisk Group |
| Hako Group |
| Taski |
| Numatic International |
| Fimap |
| IPC Eagle |
| Advance |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between lithium-ion autonomous fleets and lead-acid manual units manifests in both pricing stratification and supply chain configurations, with premium tiers commanding captive service bundling while commodity walk-behind segments compete on distributor margin compression.
Pricing Analysis
Capacity additions in Chinese battery cell manufacturing are reshaping price floors for lithium-ion scrubber configurations, compressing margins on legacy lead-acid equipment. Pricing stratifies across premium autonomous, standard automatic, and economy manual tiers, with differentiation driven by runtime certification and fleet software integration. Pricing pressure stems from right-to-repair legislative threats to proprietary battery management revenue. Municipal and education buyers exhibit highest price sensitivity, while consolidated hospitality operators absorb premium pricing for standardized national fleet agreements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode material processing and cell manufacturing clusters, exposing OEMs to geopolitical disruption and input cost volatility. Lithium carbonate, LIDAR sensor arrays, and brush drive motors draw from concentrated East Asian supply bases. Tariff exposure on battery components represents the dominant structural risk. Distribution runs through dense regional distributor networks in German-speaking markets and direct sales infrastructure serving consolidated North American buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scrubber dryer market reads as a late-cycle quality story, with procurement shifting toward premium autonomous specifications that satisfy labor scarcity and overnight cleaning window requirements.
For Market Incumbents: Cement service contract unbundling as the primary defensive perimeter, separating predictive maintenance software revenue from equipment sale economics. Deepen backward integration into lithium-ion cell allocation to secure supply against Chinese processing bottlenecks. Counter emerging robotics specialists by accelerating LIDAR sensor partnerships and SLAM algorithm development.
For New Entrants and Emerging Players: Begin with compact robotic units targeting India's BIS-certified institutional procurement channels, where IEC 60335 compliance creates a formal barrier to established Western suppliers. Penetrate the hospitality vertical through fleet management platform offerings that bypass capital-intensive equipment manufacturing. Deploy direct digital sales to circumvent entrenched distributor relationships in German-speaking markets.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-market walk-behind specialists lack autonomous navigation IP and captive battery supply. Frame long-term viability around recurring software and consumables revenue rather than transactional equipment margins. Target acquisition candidates with dense regional service technician networks, as electromechanical maintenance capability scarcity intensifies. Watch for inflection where right-to-repair legislation forces proprietary battery management system unbundling.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation against Chinese cathode processing concentration. |
| Autonomous Navigation Partnership | Accelerates LIDAR and SLAM deployment for labor-cost-sensitive facility managers. |
| Service Contract Unbundling | Shifts revenue toward recurring predictive maintenance and fleet software monetization. |
| Certification Investment | Opens India BIS and EU CE marking pathways for institutional procurement access. |
| Backward Integration | Captures battery management system and brush drive motor production in-house. |
Methodological Framework
Bottom-up facility fleet modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combine with secondary validation from customs trade data, SEC equipment manufacturer filings, and Berufsgenossenschaft workplace safety documentation. Triangulation across these sources ensures demand-side estimates align with supply-side production disclosures.
Input-output matrices connect end-use verticals, equipment configurations, and technology tiers across the projection horizon. Segmentation dimensions span product type, automation intensity, end-use sector, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated against replacement cycle dynamics and capital expenditure intentions. Forecast inputs incorporate lithium-ion runtime improvement trajectories and Joint Commission audit frequency trends.
Caveats apply where battery supply disruption, right-to-repair legislative passage, or autonomous navigation cost compression could materially shift the outlook. Forecasts reflect documented assumptions about labor scarcity persistence and consolidated buyer procurement concentration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Global Tubular Heating Elements Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market