
 Egg Albumin Protein Market | 2026-2036
Egg Albumin Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Albumin Protein Market Foresight
REACH compliance is realigning the cost-of-entry calculus for European egg albumin suppliers, forcing reformulation investments and supply-chain documentation that smaller processors struggle to fund. Merck KGaA leverages its pharmaceutical-grade purification infrastructure to serve high-specification nutraceutical contracts. Kewpie Corporation anchors its position through backward integration into Japanese egg farming and proprietary lyophilization technology. Rembrandt Foods competes on industrial-scale liquid albumin output for North American bakery and meat-processing clients.
Egg albumin protein denotes the water-soluble globular protein fraction of egg white, comprising approximately 80% ovalbumin alongside ovotransferrin and ovomucoid, with typical gelation temperatures of 62–65°C and foam stability critical to aerated food matrices. Its primary commercial purpose centers on foaming, gelling, and binding functionalities across formulated foods and cell-culture media. Powder formulations command the deepest margin pools due to extended shelf life and reduced cold-chain dependency, while liquid albumin dominates volume in industrial bakery applications. Health supplements represent the fastest-growing application segment as protein fortification migrates from sports nutrition into mainstream functional foods.
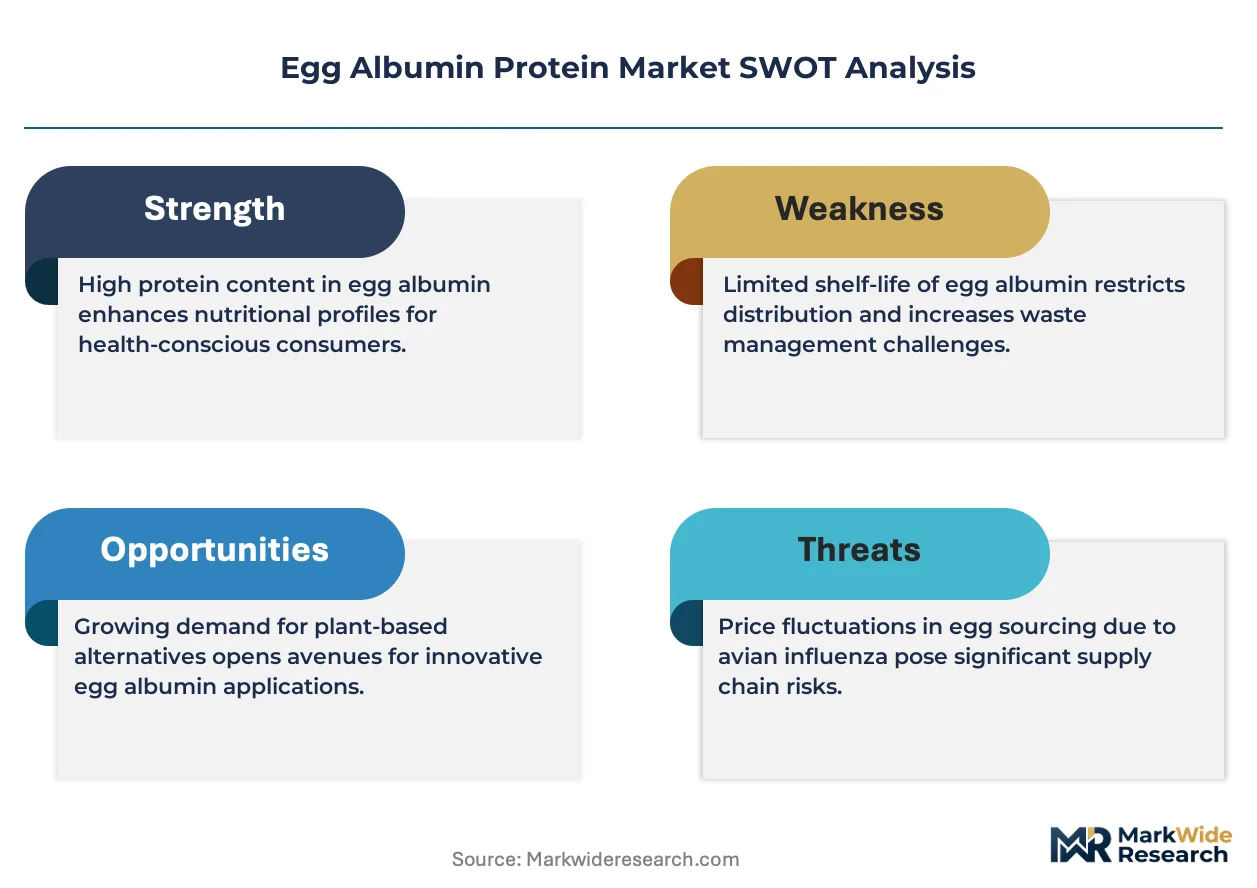
FDA oversight of Generally Recognized as Safe (GRAS) notifications and USDA egg-product inspection standards govern United States market access, while EFSA and EMA frameworks shape European food-grade and pharmaceutical-grade specifications respectively. These regulatory layers elevate testing burdens but simultaneously reward certified suppliers with preferred-supplier status at multinational food manufacturers. Stakeholders must monitor evolving allergen-labeling mandates and cultivated-protein alternatives that could displace conventional egg albumin in select premium applications.
Market Dynamics
REACH compliance is realigning the cost-of-entry calculus for European egg albumin suppliers, forcing reformulation investments and supply-chain documentation that smaller processors struggle to fund.
Growth Catalysts
- EU Green Deal feed-sourcing mandates:The regulation tightens emissions rules for egg-derived ingredients, advantaging processors with verified sustainable supply chains in Germany and the Netherlands.
- Health supplement protein fortification:Consumer prioritization of functional nutrition pulls egg albumin into mainstream functional foods beyond traditional sports nutrition.
- Lyophilization technology maturation:Advanced drying processes extend powder shelf life and reduce cold-chain dependency, opening distribution to emerging markets.
Market Restraints
- Feed cost volatility:Corn and soybean price swings squeeze processor margins, particularly for industrial-scale liquid albumin operations.
- Dutch-German supply concentration:Processing clusters in these two countries create geographic vulnerability to avian influenza outbreaks and transport disruptions.
- Cultivated protein substitution threat:Precision fermentation-derived egg white alternatives attract premium nutraceutical contracts from sustainability-focused buyers.
Strategic Opportunities
- Cell-culture media expansion:Pharmaceutical-grade albumin demand accelerates as biologics manufacturing scales in North American and Asian production hubs.
- Clean-label bakery reformulation:EFSA allergen-labeling clarity enables processors to market ovalbumin-rich fractions as natural emulsifier replacements.
- Direct-to-manufacturer digital procurement:Online platforms bypass traditional ingredient distributors, capturing margin and shortening lead times for mid-sized food formulators.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA validation protocols demand extended stability testing that delays product launches by 18-24 months.
- Legacy ERP integration with traceability systems:Batch-level documentation requirements strain smaller processors without dedicated IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Albumin Protein Market |
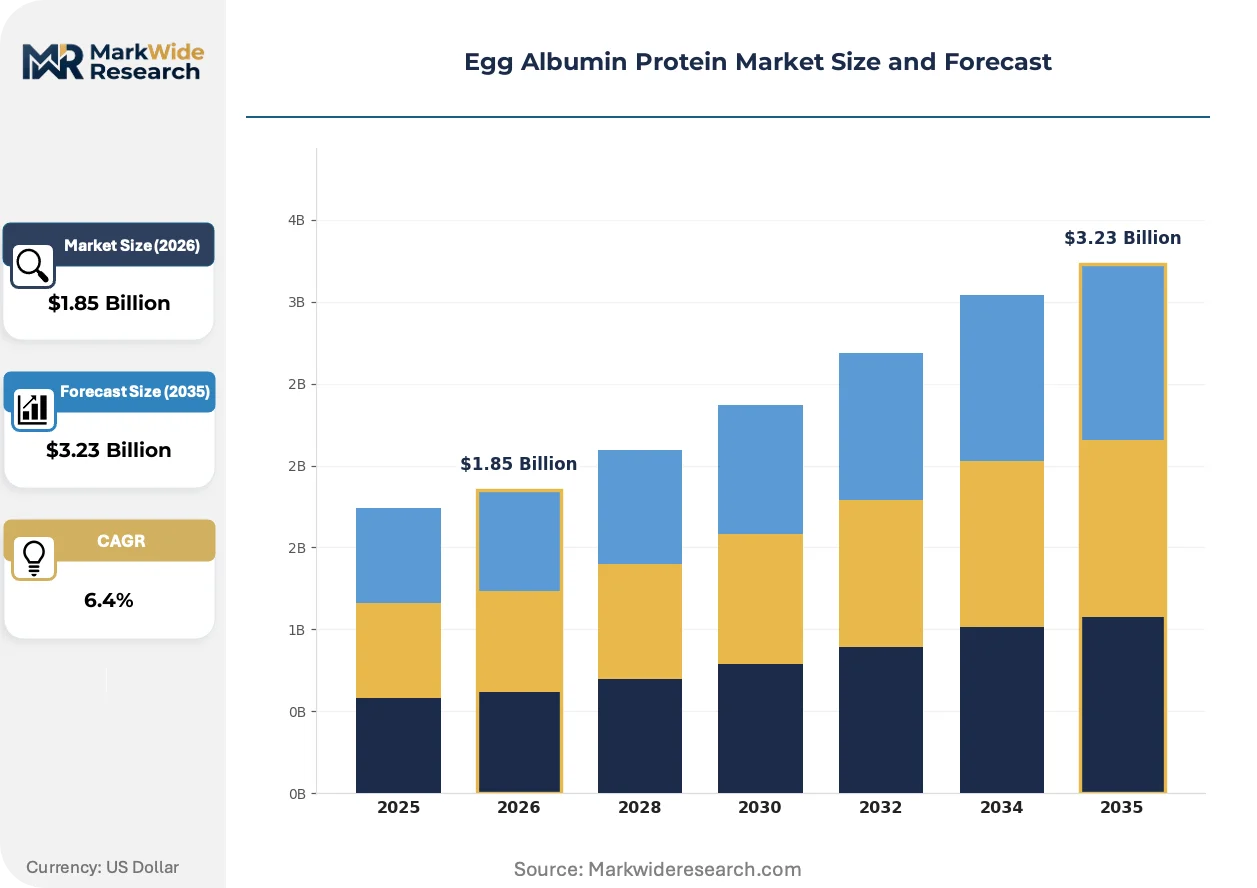
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Dried, Gel Application: Baking, Health Supplements, Confectionery, Meat Products End User: Food Industry, Beverage Industry, Nutraceuticals, Catering Services Packaging Type: Bags, Tins, Bottles, Sachets |
| Companies Covered | Merck KGaA, Kewpie Corporation, Rembrandt Foods, Rose Acre Farms, Taiyo Kagaku Co. Ltd, HiMedia Laboratories Pvt. Ltd, IGRECA, Now Health Group, Sanovo Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Albumin Protein Market Shifts & Advancements
Processing technology and regulatory transparency are converging to reshape competitive positioning across food-grade and pharmaceutical-grade segments. Three developments merit particular attention.
Membrane filtration is decentralizing protein fractionation by enabling mid-scale processors to isolate specific globulins without capital-intensive chromatography infrastructure. Regional bakery ingredient suppliers in Spain and Italy are adopting this technology to produce custom ovalbumin concentrates for local artisan manufacturers. The shift compresses the traditional dominance of centralized Dutch processors in premium fraction supply.
REACH substance registration deadlines are tightening documentation requirements for egg-derived proteins imported into European Union markets. Industrial users must now verify full supply-chain chemical safety data for albumin batches, elevating compliance costs for non-EU suppliers. German nutraceutical contract manufacturers are responding by consolidating purchases toward REACH-registered domestic and Dutch sources.
Buyer concentration among multinational food manufacturers is compressing switching cycles and unbundling technical service from commodity supply. Procurement teams at leading bakery and meat-processing groups now separate ingredient sourcing from formulation support, pressuring mid-tier albumin suppliers to compete purely on specification compliance and logistics reliability. This pattern is most visible in North American industrial bakery procurement, where annual supplier reviews have replaced multi-year agreements.
Egg Albumin Protein Market Segmentation
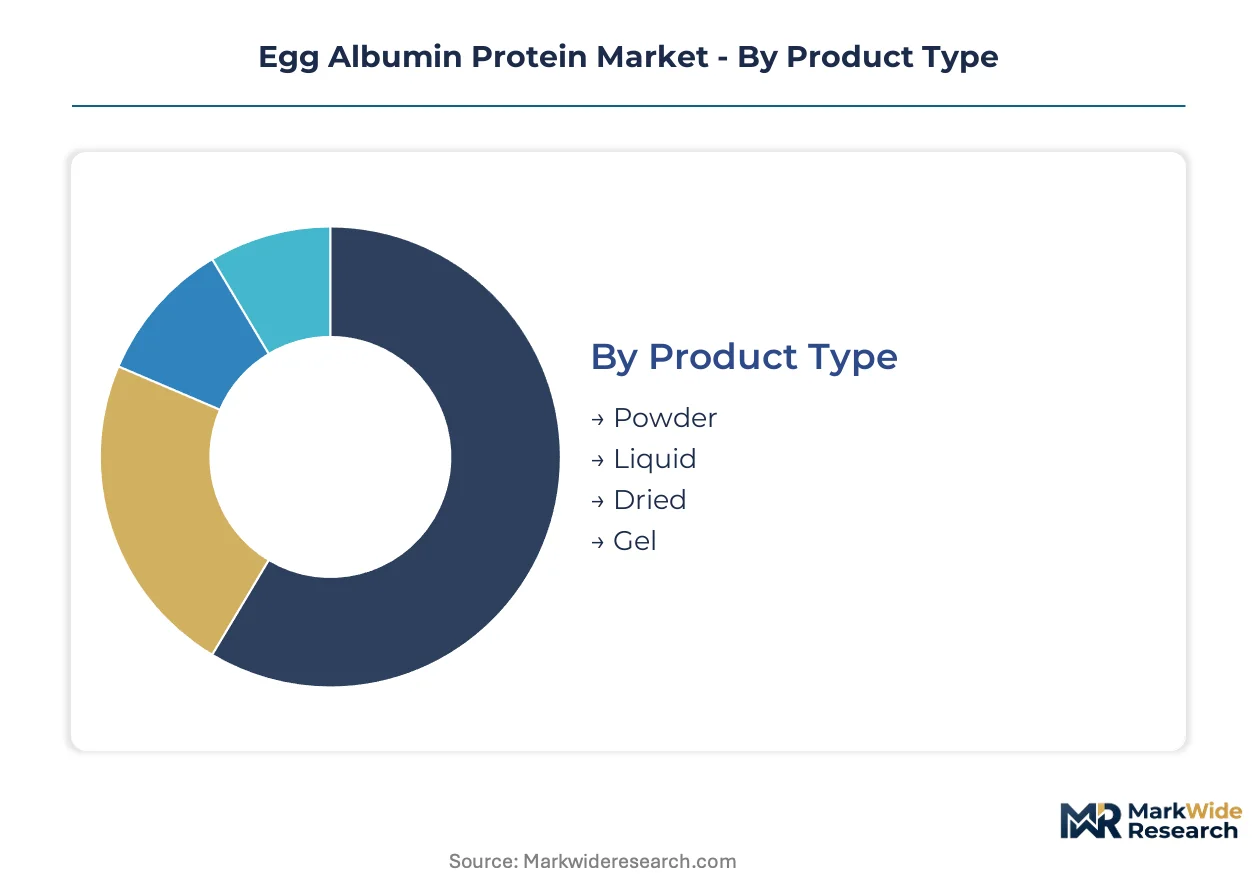
Egg albumin protein segmentation reveals how functional requirements and supply-chain constraints fragment procurement strategies across food manufacturing. Product form and application specificity dictate margin capture, while end-user scale determines whether suppliers compete on technical service or logistics reliability.
Product Type:
Powder formulations occupy the premium customization tier with extended stability and reduced cold-chain dependency, while liquid albumin serves high-volume industrial buyers seeking standardization at scale.
- Powder:Lyophilized and spray-dried variants concentrate ovalbumin at 80-90% protein content with shelf lives exceeding 24 months. German and Dutch nutraceutical contract manufacturers source heavily here for protein fortification applications where transport infrastructure is limited.
- Liquid:Unprocessed or pasteurized egg white maintains native protein structure for optimal foaming performance. North American industrial bakeries in Chicago and Toronto metropolitan areas consume the largest volumes for continuous-process sponge cake and meringue production.
- Dried:Lower-cost drum-dried alternatives sacrifice some functional performance for price-sensitive formulations. Southeast Asian confectionery exporters utilize this grade for regional distribution.
- Gel:Thermally treated pre-gelled albumin enables binding in comminuted meat systems without additional processing steps. Brazilian processed meat manufacturers have adopted this format for cost-efficient reformulation.
Most installed capacity flows through Liquid. Expansion is steepest in Powder.
Application:
Application segmentation tracks how protein fortification priorities are redistributing demand from traditional bakery matrices toward functional nutrition endpoints.
- Baking:Aerated cake systems, meringues, and macarons depend on albumin's foam stability and heat-set gelation at 62-65°C. French and Italian artisan bakery clusters specify high-whisking-tolerance grades for premium patisserie output.
- Health Supplements:Protein powders, ready-to-drink beverages, and functional bars incorporate albumin for complete amino acid profiles and clean-label positioning. US sports nutrition brands and Japanese senior nutrition formulators are the primary demand anchors.
- Confectionery:Nougat, marshmallow, and aerated chocolate applications exploit albumin's whipping properties. Belgian and Swiss chocolate manufacturers maintain specifications for European confectionery export markets.
- Meat Products:Binding and moisture retention in surimi, meatballs, and restructured meats leverage albumin's gelation under thermal processing. Spanish and Portuguese cured meat processors utilize this functionality for yield optimization.
Volume concentrates in Baking. Value expansion is accelerating in Health Supplements.
End User:
End-user categories separate commodity-scale procurement from specification-intensive pharmaceutical and nutraceutical sourcing.
- Food Industry:Industrial bakeries, sauce manufacturers, and prepared food processors purchase bulk liquid and standard-grade powder through annual contracts. Midwest US and Rhine-Ruhr manufacturing corridors represent the densest demand clusters.
- Beverage Industry:Ready-to-drink protein beverages and alcoholic cocktail foams require low-flavor-impact, high-solubility grades. Brazilian and Mexican beverage innovators are testing albumin against whey alternatives.
- Nutraceuticals:Pharmaceutical-grade albumin for cell-culture media and clinical nutrition demands EMA-validated supply chains with batch-level documentation. Singapore and Boston biologics manufacturing hubs are scaling purchases.
- Catering Services:Foodservice distributors supply pasteurized liquid in institutional formats for hotel and restaurant kitchen operations. Dubai and Riyadh hospitality sectors drive Middle Eastern demand.
Contract value is largest in Food Industry. Specification complexity peaks in Nutraceuticals.
Packaging Type:
Packaging segmentation reflects the tension between industrial-scale efficiency and portion-control convenience across distribution channels.
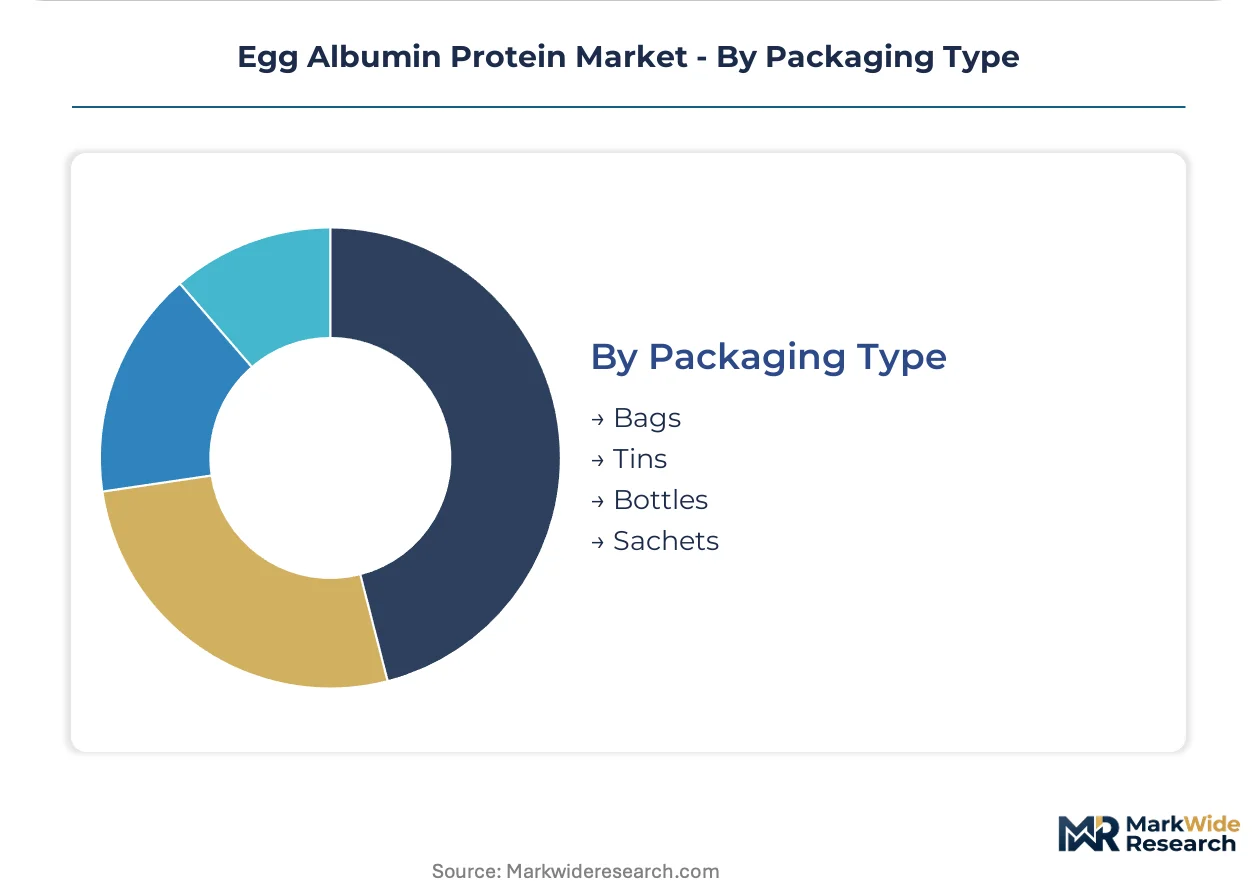
- Bags:Multi-wall paper or polyethylene sacks deliver 20-25kg powder quantities to manufacturing facilities. European and North American industrial users specify UN-certified transport packaging for cross-border sourcing.
- Tins:Metal canisters protect hygroscopic powders in humid climates and support retail positioning. Japanese and South Korean consumer-facing protein brands favor this format.
- Bottles:PET and glass containers distribute liquid albumin for foodservice and small-scale manufacturing. Brazilian and Argentine retail channels stock 500ml-1L formats.
- Sachets:Single-serve 10-30g packets enable precise portioning for artisan bakers and clinical nutrition. Indian and Indonesian institutional catering procurement is shifting toward this format.
Throughput concentrates in Bags. Format innovation is most active in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing technologists and food formulation chemists cluster around the Rhine-Ruhr corridor and Chicago metropolitan area, anchoring technical service capabilities for industrial albumin applications.
Germany
Bakery and nutraceutical manufacturers drive powder albumin procurement for protein fortification and clean-label reformulation. REACH substance registration deadlines tighten documentation requirements for imported egg-derived proteins. The Lower Saxony egg-processing belt concentrates spray-drying capacity serving domestic and Benelux contract manufacturers.
United States
Industrial bakeries in Chicago and Toronto metropolitan areas consume liquid albumin volumes for continuous-process sponge cake production. FDA GRAS notification pathways and USDA egg-product inspection standards govern market access and elevate testing burdens. Midwest manufacturing corridors host the densest demand clusters for bulk liquid and standard-grade powder procurement.
Japan
Senior nutrition formulators and consumer-facing protein brands pull lyophilized albumin for shelf-stable functional foods. METI standards and PMDA pharmaceutical-grade specifications shape quality benchmarks for cell-culture and clinical nutrition applications. Kanto region processing facilities leverage proprietary drying technology for regional distribution.
Netherlands
Dutch processors supply verified sustainable supply chains advantaged by EU Green Deal feed-sourcing mandates tightening emissions rules. ECHA compliance documentation requirements reward REACH-registered domestic sources with preferred-supplier status. Gelderland and Overijssel processing clusters export premium fraction concentrates to German nutraceutical contract manufacturers.
Brazil
Processed meat manufacturers and beverage innovators test albumin against whey alternatives for binding and protein fortification. ANVISA food-grade specifications and agricultural ministry traceability protocols govern import and domestic production standards. São Paulo state industrial zones drive regional demand for cost-efficient pre-gelled albumin formats.
Egg Albumin Protein Market Competitive Landscape
The competitive structure tilts toward integrated processors with captive egg supply and pharmaceutical-grade certification infrastructure. Tiered differentiation separates premium nutraceutical suppliers from industrial-scale liquid albumin operators. Three archetypes dominate: backward-integrated agribusiness conglomerates with proprietary farming operations, specialized fractionation houses with membrane filtration capabilities, and diversified chemical-pharmaceutical groups leveraging existing purification assets. Capacity expansion in powder drying and strategic partnerships for cell-culture media distribution represent the dominant competitive moves.
Within the pharmaceutical-grade tier, Merck KGaA exemplifies the diversified chemical-pharmaceutical archetype through its existing purification infrastructure. Kewpie Corporation represents backward-integrated Japanese processors with proprietary lyophilization technology. Rembrandt Foods occupies a position among industrial-scale North American operators focused on liquid albumin output.
| Leading Market Players |
|---|
| Merck KGaA |
| Kewpie Corporation |
| Rembrandt Foods |
| Rose Acre Farms |
| Taiyo Kagaku Co. Ltd |
| HiMedia Laboratories Pvt. Ltd |
| IGRECA |
| Now Health Group |
| Sanovo Technology Group |
| Others |
Supply & Pricing Matrix
Feed cost volatility in corn and soybean markets propagates through egg albumin pricing tiers, compressing margins at the industrial liquid grade while pharmaceutical-grade powder commands premium spreads anchored to EMA certification overhead and cold-chain logistics.
Pricing Analysis
The bundled-vs-unbundled service split separates commodity liquid albumin from premium powder grades. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels tracks certification intensity and documentation burden. Price differentiation hinges on EMA validation status and volume scale commitments. Pricing pressure stems from cultivated protein alternatives attracting sustainability-focused nutraceutical buyers. Industrial bakeries exhibit highest price sensitivity; cell-culture media purchasers show lowest.
Supply Chain Analysis
Regional distribution centers in Lower Saxony and Gelderland anchor hub-and-spoke patterns serving Rhine-Ruhr manufacturing corridors. Supply concentrates in Germany, the Netherlands, and the United States. Raw material flows draw from corn and soybean feedstock markets plus specialized egg farming operations. Single-source vulnerability to avian influenza outbreaks in Dutch-German clusters poses structural risk. Distribution runs through direct-to-manufacturer digital procurement platforms and traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in egg albumin protein rests on lyophilization technology maturation reducing cold-chain dependency and enabling premium powder penetration into emerging markets.
For Market Incumbents: Anchor market position through backward integration into verified sustainable egg farming under EU Green Deal feed-sourcing mandates. Invest in membrane filtration capabilities to defend against regional fractionation competitors in Southern Europe. Prioritize REACH-registered supply chain documentation to maintain preferred-supplier status with German nutraceutical contract manufacturers facing ECHA compliance deadlines.
For New Entrants and Emerging Players: Capture white-space opportunity in cell-culture media distribution serving Singapore and Boston biologics manufacturing hubs. Target Southeast Asian confectionery exporters with cost-efficient drum-dried albumin formats. Enter through direct-to-manufacturer digital procurement platforms bypassing traditional ingredient distributors.
For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical-grade certification timelines stretch 18-24 months and smaller processors lack IT infrastructure for batch-level traceability. Long-term viability favors diversified chemical-pharmaceutical groups with existing purification assets or backward-integrated processors with proprietary drying technology. Watch cultivated protein precision fermentation cost curves as inflection signal for conventional albumin displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | EMA validation protocols unlock preferred-supplier contracts with multinational biologics manufacturers. |
| Lyophilization Capacity Expansion | Proprietary drying technology extends shelf life and reduces cold-chain dependency for emerging market distribution. |
| Backward Integration into Sustainable Egg Farming | EU Green Deal feed-sourcing mandates reward verified supply chains with procurement advantages. |
| Membrane Filtration Technology Adoption | Regional processors in Spain and Italy compress Dutch dominance in premium fraction supply. |
| Direct-to-Manufacturer Digital Platform Launch | Online procurement captures margin and shortens lead times for mid-sized food formulators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged egg processing plant managers, nutraceutical contract manufacturing procurement leads, bakery formulation chemists, and pharmaceutical-grade albumin quality directors. Secondary validation drew from EFSA and EMA regulatory filings, USDA egg-product inspection standards, EU Green Deal policy documentation, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Comparable-period anchoring linked projection assumptions to historical production and consumption patterns across the analysis window. Segmentation modeling tracked product form, application specificity, end-user scale, and regional regulatory cluster. CAGRs derived from slope-log analysis of normalized growth trajectories. Forecast inputs incorporated feed cost volatility indices and lyophilization technology adoption curves.
Avian influenza outbreaks, REACH documentation deadline shifts, and cultivated protein cost breakthroughs are the dominant revision risks. Forecasts reflect documented assumptions on technology maturation and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Protein Ingredients Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Global Dietary Fibers Market
Ingredients
Bean Flour Market
Ingredients
Europe Fats and Oil Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Mineral Premix Market
Ingredients
Encapsulated Salt Market
Ingredients
Meat Starter Culture Market
Ingredients
Industrial Starch Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Fresh Yeast Market
Ingredients
Marine Ingredients Market
Ingredients
Bakery Ingredients Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Fruit Concentrate Market