
 Arachidonic Acid Market | 2026-2036
Arachidonic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Arachidonic Acid Market Intelligence
The European Union's updated directive on infant formula composition is consolidating the supply base for high-purity arachidonic acid, rewriting the cost-of-entry calculus for suppliers. This regulatory shift favors large-scale producers with extensive quality control systems and documented production traceability. DSM-Firmenich AG leverages its significant R&D investment in nutritional lipids to meet these stringent European standards. CABIO Bioengineering specializes in fermentation-derived ARA, capturing significant volume in the expanding Asia-Pacific infant nutrition sector.
Arachidonic acid is an omega-6 polyunsaturated fatty acid, a critical component of cell membranes vital for infant neural development and immune function. It is commercially derived from the fungus Mortierella alpina via fermentation, ensuring a consistent, contaminant-free source. The nutraceuticals segment, specifically infant formula, constitutes the largest source of demand, driving most of the market's volume. Product forms like oil and powder dominate production as they offer superior stability and ease of integration into final formulations.
Global quality standards are governed by frameworks from the US Food and Drug Administration (FDA), the European Food Safety Authority (EFSA), and China's National Health Commission through its GB standards. These regulations dictate purity specifications, permissible sources, and mandatory inclusion levels in sensitive products like infant formula, creating high barriers to entry. Future competitive advantage will depend on securing scalable, fermentation-based production capacity to meet globally harmonized, yet regionally specific, formulation requirements for key end-users.
Market Dynamics
The arachidonic acid market is fundamentally shaped by a regulatory tightening that elevates the importance of production traceability and purity. This shift, led by bodies like the European Food Safety Authority, creates significant barriers to entry and favors suppliers with sophisticated, large-scale fermentation capabilities.
Growth Catalysts
- Mandatory Fortification:Updated directives from the European Food Safety Authority (EFSA) mandating ARA inclusion in infant and follow-on formula create a stable, non-discretionary demand base across all EU member states.
- Premiumization in Asia:China's expanding premium infant nutrition segment provides a significant volume pull, as parents show a strong preference for formulas containing scientifically-backed ingredients for cognitive development.
- Fermentation Technology:The commercial maturity of producing ARA from the fungus Mortierella alpina ensures a consistent, scalable, and contaminant-free supply, which is critical for sensitive end-uses like infant formula.
Market Restraints
- High Capital Investment:The construction and certification of cGMP-compliant fermentation facilities require substantial upfront capital, limiting the pool of potential new entrants capable of producing high-purity ARA at scale.
- Substrate Cost Volatility:Production costs are sensitive to fluctuations in the price of glucose and other nutrient media used in the fermentation process, which can compress margins for producers.
- Complex Downstream Processing:Extracting and purifying ARA oil or converting it into a stable powder without degradation is technically challenging, adding complexity and cost to the manufacturing value chain.
Strategic Opportunities
- Adult & Clinical Nutrition:Development of ARA-fortified products for adult cognitive health, sports nutrition, and medical foods for patients with inflammatory conditions represents a significant new application area beyond infant formula.
- Geographic Expansion:Growing middle-class populations in Southeast Asia and Latin America with increasing health awareness present new growth frontiers for suppliers of fortified nutritional products.
- Synergistic Formulations:Combining ARA with other bio-active lipids like DHA, EPA, or novel prebiotics in advanced formulations offers a pathway to create higher-value, differentiated nutritional products.
Industry Challenges
- Regulatory Compliance Burden:Navigating and maintaining compliance with the distinct and evolving purity specifications of the FDA, EFSA, and China's GB standards requires continuous investment in testing and documentation.
- Sterility in Production:Maintaining aseptic conditions throughout the large-scale fermentation process for Mortierella alpina is an operational challenge, as any contamination can ruin entire batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arachidonic Acid Market |
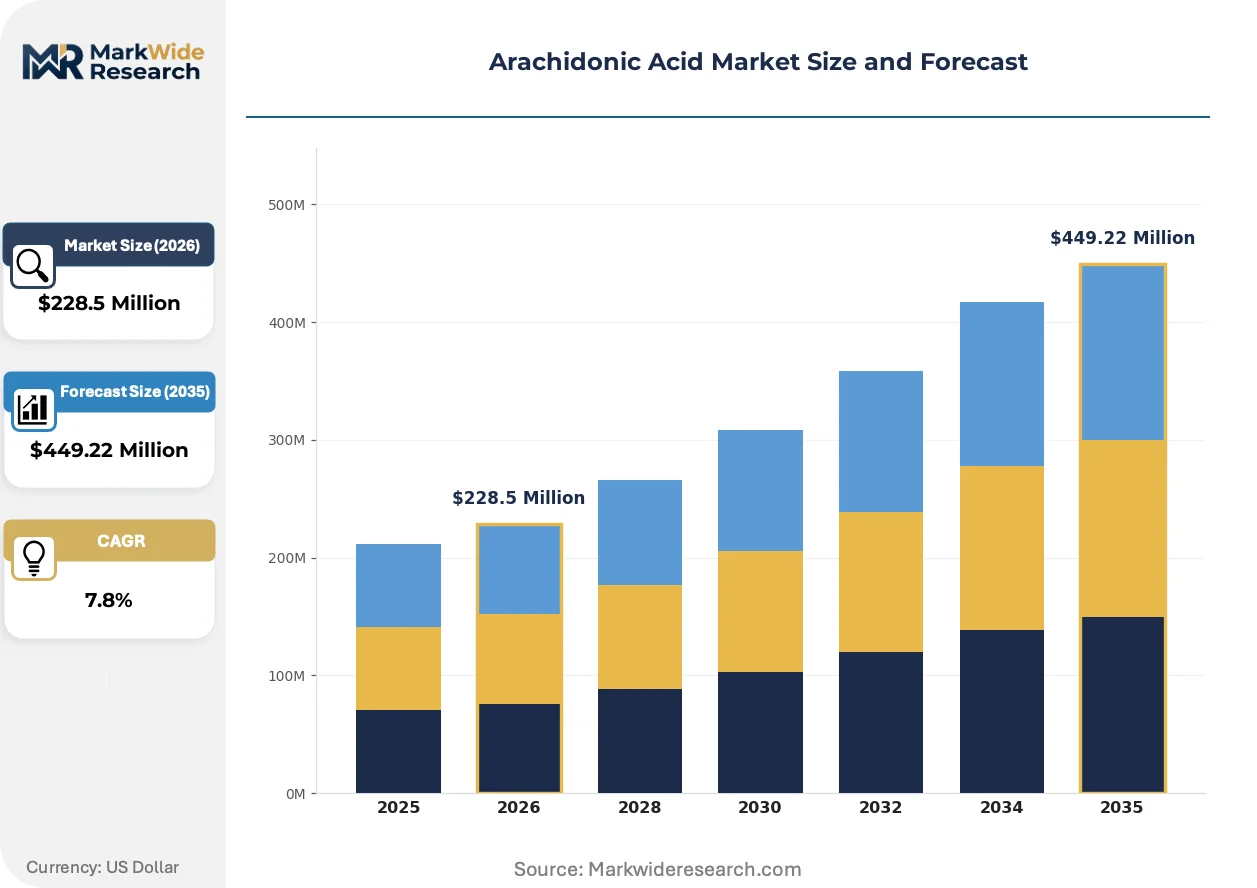
| Market Size in 2026 | $228.5 Million |
| Market Size in 2035 | $449.22 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil, Capsules, Emulsion Application: Nutraceuticals, Pharmaceuticals, Cosmetics, Animal Feed End User: Healthcare Providers, Food Manufacturers, Cosmetic Companies, Research Institutions Source: Animal, Plant, Synthesized, Others |
| Companies Covered | BASF SE, Cargill, Incorporated, DSM-Firmenich AG, Cayman Chemical, CABIO Bioengineering, Merck KGaA, Suntory Holdings Limited, Guangdong Runke Bioengineering, Avanti Polar Lipids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arachidonic Acid Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of advanced bioprocessing techniques with increasingly stringent global food safety regulations. This intersection is elevating the role of scientific validation and traceable supply chains as primary competitive differentiators, especially within the infant nutrition sector.
Strain Improvement and Precision Fermentation
Precision fermentation techniques are optimizing the yield and purity of arachidonic acid from proprietary strains of Mortierella alpina. Infant formula and specialty nutraceutical manufacturers are the primary adopters of these higher-grade ARA oils and powders. Advanced bioprocessing is integrating directly into quality management systems, allowing for end-to-end traceability that satisfies stringent regulatory demands for source verification.
Harmonization of Global Standards
Regulatory frameworks from the European Food Safety Authority (EFSA) and China's National Health Commission are increasingly aligning on minimum and maximum levels for ARA in infant formula. This harmonization creates a more uniform global market, benefiting large producers who can certify a single product for multiple regions. The infant formula segment is most impacted, with brands reformulating products to comply with a globalized set of compositional standards.
Certification-Driven Procurement
A notable shift in purchasing behavior involves buyers prioritizing suppliers who can provide comprehensive certification for non-GMO, allergen-free, and organic-compliant ARA. This disrupts older procurement models focused primarily on cost, displacing suppliers unable to furnish extensive traceability and quality assurance documentation. The trend is most visible in the European and Chinese premium infant formula markets, where consumer confidence is a critical brand asset.
Arachidonic Acid Market Segmentation
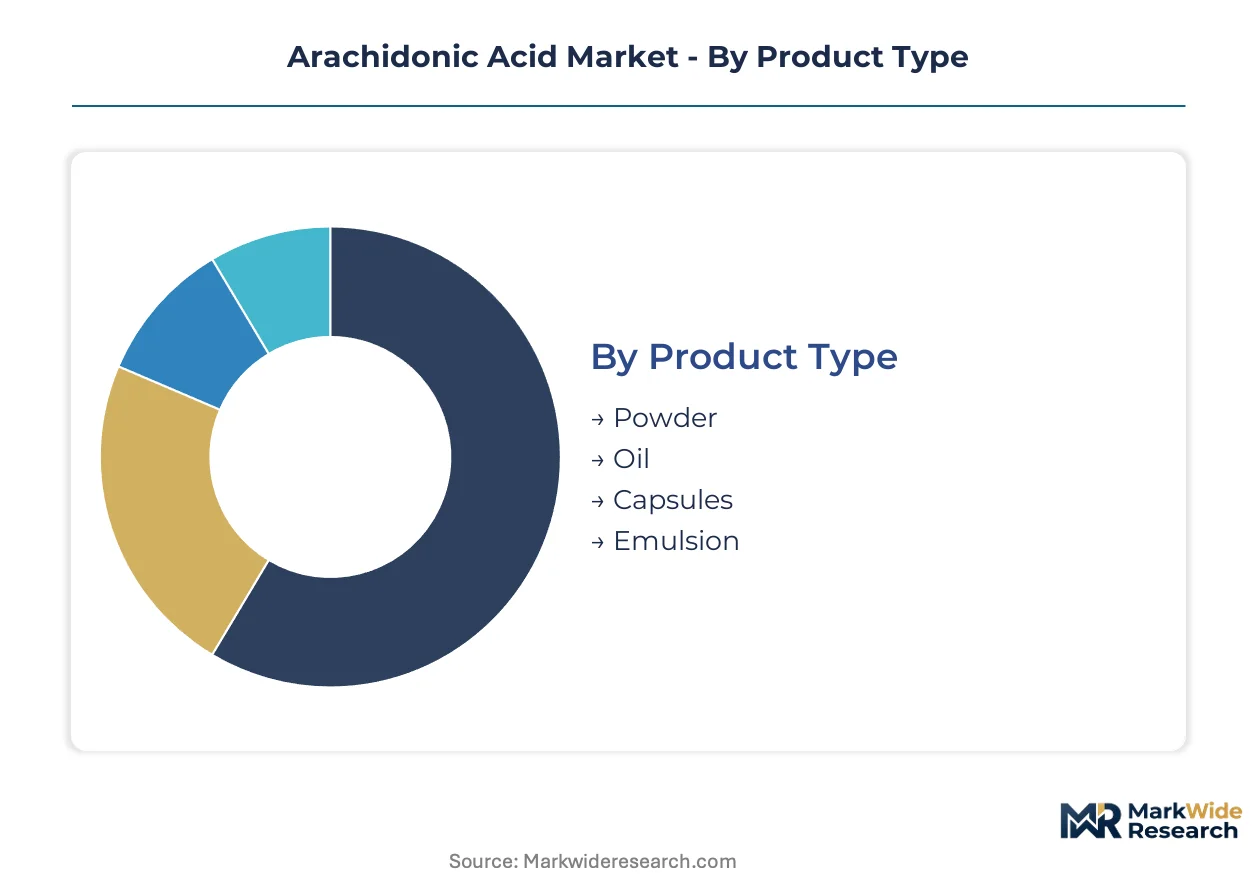
The arachidonic acid market structure reflects diverse product forms, applications, and end-user requirements, each influencing production scale and purity standards. Understanding these distinct segments clarifies the capital allocation priorities for manufacturers and the procurement strategies for major buyers. Regulatory mandates for infant formula drive specific segment growth.
Product Type:
The capital intensity for arachidonic acid production varies significantly across product types, with high-purity forms demanding substantial investment in specialized processing equipment. Manufacturers must invest in advanced drying and encapsulation technologies to ensure product stability and shelf-life, particularly for sensitive applications.
- Oil:This liquid form of arachidonic acid is directly extracted from microbial fermentation, offering high bioavailability and concentration for nutritional formulations. Demand concentrates in infant formula manufacturing, where its direct integration into liquid or powdered mixes is critical for cognitive development.
- Powder:Arachidonic acid powder is produced through microencapsulation or spray drying of the oil, enhancing stability, ease of handling, and precise dosing. The premium infant nutrition segment in China and Europe drives significant volume for these stable, high-purity powdered ingredients.
- Capsules:Encapsulated arachidonic acid provides a convenient dosage form for nutraceuticals targeting adult cognitive health and sports nutrition.
- Emulsion:Arachidonic acid emulsions offer improved dispersion and absorption in liquid dietary supplements and medical food applications.
Most installed capacity flows through Oil. Expansion is steepest in Powder.
Application:
The application landscape for arachidonic acid is primarily driven by volume requirements within the nutritional sector, with specialized uses expanding into high-value pharmaceutical formulations. Each application segment dictates specific purity levels and regulatory compliance frameworks for ingredient suppliers.
- Nutraceuticals:This segment represents the largest application for arachidonic acid, predominantly driven by its mandatory inclusion in infant formula for neural and visual development. Global regulatory bodies like the EFSA and China's NHC establish precise inclusion levels for these products.
- Pharmaceuticals:Arachidonic acid finds use in specialized medical foods and therapeutic formulations targeting inflammatory conditions or neurological disorders, requiring ultra-high purity and stringent quality control. Research into its role in neuroprotection and immune modulation propels this high-value segment.
- Cosmetics:Arachidonic acid is incorporated into skincare products for its anti-inflammatory and skin barrier repair properties.
- Animal Feed:Supplementation with arachidonic acid in animal feed aims to improve growth, reproductive performance, and immune function in livestock and aquaculture.
Nutraceuticals dominate volume, while Pharmaceuticals offer significant value per unit.
End User:
End-user segments exhibit distinct procurement behaviors and quality requirements for arachidonic acid, influencing supplier relationships and product specifications. Food manufacturers prioritize consistent supply and regulatory compliance, while healthcare providers demand pharmaceutical-grade purity for clinical applications.
- Food Manufacturers:This segment, primarily infant formula producers, constitutes the largest end-user group, requiring high-volume, consistent supply of fermentation-derived arachidonic acid. Their procurement is highly sensitive to global food safety standards and traceability documentation.
- Healthcare Providers:Hospitals and clinics utilize arachidonic acid in medical nutrition therapies and specialized dietary supplements for patients with specific clinical needs. They demand rigorously tested, high-purity ingredients for patient safety and efficacy.
- Cosmetic Companies:These companies purchase arachidonic acid for integration into dermatological and personal care product lines.
- Research Institutions:Academic and private research organizations acquire arachidonic acid for studies on metabolic pathways, inflammation, and neurological functions.
Food Manufacturers represent the largest procurement base, with Healthcare Providers showing consistent, specialized demand.
Source:
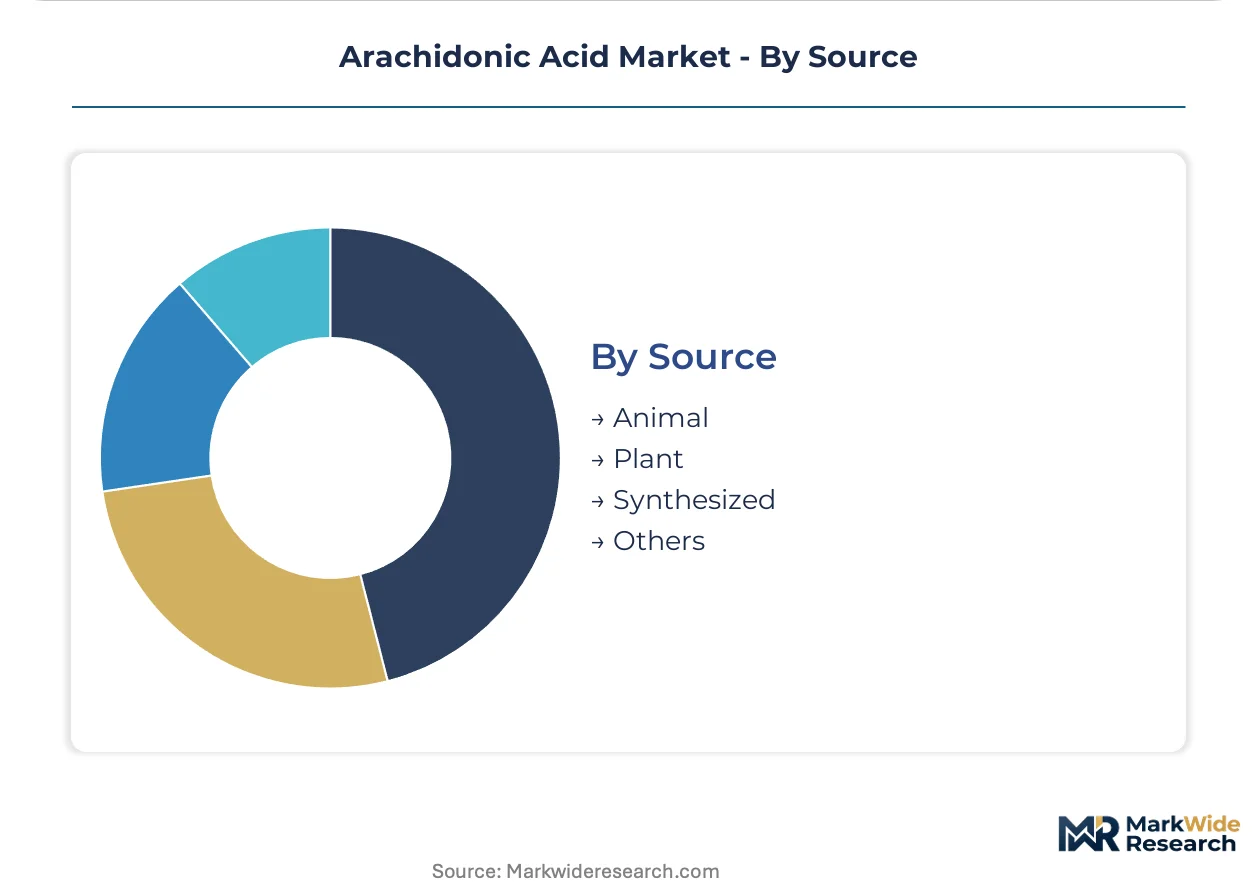
The arachidonic acid market's supply concentration is increasingly shifting towards technologically mature and scalable production methods, particularly microbial fermentation. Regulatory preferences for consistent, contaminant-free sources significantly influence the viability and market share of different raw material origins.
- Plant:This category primarily refers to arachidonic acid produced via the fermentation of microorganisms like Mortierella alpina, offering a consistent, high-purity, and vegan-friendly source. Global regulations for infant formula increasingly favor these controlled, fermentation-derived ingredients over animal sources due to purity and safety.
- Synthesized:Chemical synthesis methods provide highly purified arachidonic acid for specific research or pharmaceutical applications where precise isomer control and ultra-high purity are paramount. This method offers complete control over the final product's chemical structure.
- Animal:Historically, some arachidonic acid was derived from animal fats, but concerns over contaminants and ethical sourcing have reduced its market presence.
- Others:This segment includes emerging or less common biotechnological approaches for arachidonic acid production, still in developmental or niche application phases.
Plant-based sources hold the dominant market share, with Synthesized methods gaining traction for niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled scientific workforce anchors the global arachidonic acid market, particularly in regions with advanced bioprocessing capabilities. These concentrations of expertise drive innovation in fermentation technology and lipid extraction. Regulatory harmonization efforts across major economies further standardize product requirements and procurement.
China
Demand for premium infant nutrition significantly drives arachidonic acid consumption in China, as parents seek advanced formulations. The National Health Commission's GB standards dictate mandatory inclusion levels for infant formula, ensuring product quality and safety. Production and processing hubs in the Yangtze River Delta region concentrate advanced fermentation facilities, supporting domestic and export markets.
Germany
European Food Safety Authority (EFSA) directives on essential fatty acids underpin stable demand within Germany, particularly for infant and follow-on formulas. These regulations ensure high purity standards and comprehensive traceability for nutritional lipids across member states. Specialized bioprocessing clusters in Bavaria focus on advanced fermentation and ingredient refinement, catering to stringent EU requirements.
United States
The United States market sees strong demand from the nutraceuticals segment, including infant formula and adult cognitive health products for an aging population. US Food and Drug Administration (FDA) guidelines govern the safety and efficacy of arachidonic acid ingredients, influencing product development. Research and development centers in California drive innovation for novel lipid formulations and delivery systems.
Japan
Japanese consumers prioritize high-quality nutraceuticals, boosting demand for advanced arachidonic acid formulations with proven health benefits. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict quality and safety standards for functional foods and dietary supplements. Biotech firms in the Tokyo metropolitan area develop specialized lipid products for health applications, targeting both domestic and international markets.
Arachidonic Acid Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the arachidonic acid market, creating a dynamic competitive environment. This landscape exhibits a tiered structure, favoring large-scale producers capable of meeting stringent regulatory demands and high-volume requirements. Strategic archetypes include global ingredient suppliers leveraging extensive R&D, regional fermentation experts optimizing local supply chains, and niche high-purity providers. Dominant competitive moves involve significant capacity expansion to secure market share and strategic partnerships for technology transfer and geographic reach.
Within the global ingredient supplier archetype, DSM-Firmenich AG, a European entity, represents a major player leveraging extensive R&D investments in nutritional lipids. CABIO Bioengineering, a Chinese firm, occupies a prominent position among the specialized fermentation experts, capturing significant volume in the expanding Asia-Pacific infant nutrition sector. BASF SE, another European chemical and ingredient conglomerate, exemplifies the diversified players with broad portfolio offerings across various industries. These companies anchor various segments, from high-purity infant formula ingredients to broader nutraceutical applications, demonstrating varied strategic approaches.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| DSM-Firmenich AG |
| Cayman Chemical |
| CABIO Bioengineering |
| Merck KGaA |
| Suntory Holdings Limited |
| Guangdong Runke Bioengineering |
| Avanti Polar Lipids |
| Others |
Cost & Logistics Intelligence
Glucose substrate costs, a primary input for fermentation, directly influence the upstream production economics of arachidonic acid, cascading through to the final ingredient pricing for end-users. This cost sensitivity impacts margin structures across the global supply chain, particularly for high-volume applications.
Pricing Analysis
The certified-versus-commodity split defines arachidonic acid pricing, with premium tiers commanding significantly higher prices due to stringent quality and traceability requirements. Contract-based long-term offtake agreements dominate for infant formula manufacturers, ensuring stable supply and pricing. Price differentiation stems from purity grade, specific regulatory certifications (e.g., EFSA, China's GB standards), and volume scale. Pricing pressure stems from substrate cost volatility, particularly for standard-grade products. Infant formula manufacturers exhibit the lowest price sensitivity for high-purity, certified ARA, while animal feed and cosmetics segments are more price-sensitive.
Supply Chain Analysis
Specialized logistics and cold chain requirements for arachidonic acid oil and powder contribute significantly to overall delivered cost, especially for intercontinental shipments. Supply production concentrates heavily in China and Germany, leveraging advanced fermentation capabilities. Raw material dependencies center on glucose and specific nutrient media. A primary supply chain risk involves maintaining aseptic conditions during large-scale fermentation, as contamination can lead to batch losses and supply disruptions. Distribution runs primarily through direct sales to major food manufacturers and specialized ingredient distributors serving smaller nutraceutical and pharmaceutical clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arachidonic acid market presents a compelling margin-expansion story, driven by the premiumization of infant nutrition and the potential for high-value applications beyond formula. Strategic investments in bioprocessing efficiency serve as a key cost-down driver.
For Market Incumbents: Deepen R&D investments into advanced bioprocessing techniques to further optimize fermentation yields and purity, reducing per-unit production costs. Expand large-scale cGMP-compliant capacity in strategic regions like Southeast Asia to mitigate logistics costs and serve growing local demand. This proactive capacity build-out defends against emerging entrants with localized production advantages. Reinforce global regulatory expertise to maintain compliance across diverse markets, a critical lever against competitive threats.
For New Entrants and Emerging Players: Capture white-space opportunities in adult cognitive health and medical food formulations, which have less established supply chains than infant formula. Target underpenetrated markets in Latin America and Southeast Asia, focusing on local partnerships for distribution and market entry. A specific go-to-market angle involves developing synergistic formulations combining ARA with other functional lipids or prebiotics to create differentiated, higher-value nutritional products.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory barriers create high entry costs for specialized ingredients, favoring established players with documented traceability. The long-term viability of high-purity ARA remains strong, anchored by mandatory inclusion in infant formula and expanding applications in clinical nutrition. Acquisition targets should include specialized fermentation technology providers or niche formulators with proprietary encapsulation methods. A signal to watch is the expansion of mandatory ARA inclusion into new infant formula categories or clinical guidelines in major economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in APAC | Secures market share in the fastest-growing infant nutrition segment across Asia-Pacific. |
| Precision Fermentation R&D | Optimizes yield and purity, directly lowering production costs for high-grade ARA. |
| Long-term Supply Agreements | Provides pricing stability and supply assurance for major infant formula manufacturers. |
| Joint Venture for Clinical Nutrition | Accelerates market entry into high-value medical food applications for ARA. |
| Certification for Novel Applications | Unlocks new market segments by meeting specific regulatory requirements beyond infant formula. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to ensure a comprehensive market assessment. Primary interviews engaged R&D directors, procurement managers at infant formula companies, regulatory specialists, and product development leads. Secondary sources included publications from the European Food Safety Authority, US Food and Drug Administration, China's National Health Commission, company annual reports, and trade association data, enabling both bottom-up and top-down triangulation.
The forecast framework employed a segment-weighting approach, modeling market dynamics across product type (oil, powder), application (nutraceuticals, pharmaceuticals), end-user (food manufacturers, healthcare providers), and source (plant, synthesized). Compound annual growth rates were derived from historical data, projected regulatory mandates, and anticipated shifts in consumer preferences over the projection horizon. Key forecast inputs included raw material price trends, infant birth rates, and new product development pipelines.
Underlying measurement precision varies by segment; the infant formula market carries tighter precision than emerging adult nutrition applications. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Barley Malt Extract Market
Ingredients
Compressed Yeast Market
Ingredients
Functional Flours Market
Ingredients
Clean Label Starch Market
Ingredients
High Protein Flour Market
Ingredients
Rooster Comb Extract Market
Ingredients
Marine Peptides Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Chickpea Fiber Market
Ingredients
Fruit Powder Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
US Vegetable Oil Market
Ingredients
Revivable Yeast Market