
 Sweet Almond Oil Market | 2026-2036
Sweet Almond Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Almond Oil Market Analysis
California's almond processing expansion is reshaping raw material availability for cold-pressed oil extraction. Blue Diamond Growers leverages vertical integration from orchard to oil to sustain supply consistency across cosmetic and food-grade channels. Plimon dominates European organic certification, while ESI S.p.A. specializes in pharmaceutical-grade refinement standards for dermal applications.
Sweet almond oil is a fixed oil expressed from Prunus dulcis kernels, containing approximately 70% oleic acid and 20% linoleic acid with a light yellow color and low comedogenic rating of 2. Cold-pressed unrefined grades retain tocopherols and phytosterols for cosmetic formulations, whereas refined variants serve high-heat food processing. Organic cold-pressed product types command premium positioning in cosmetics as clean-label formulators reject solvent-extracted alternatives. Pharmaceutical and nutraceutical applications represent the fastest-expanding demand pool, driven by clinical interest in almond oil's emollient and anti-inflammatory properties. Bulk container packaging dominates ingredient supply to manufacturers, while bottle formats capture retail margin in specialty stores and online channels.
USDA organic certification and FDA food-contact substance notifications govern US market access, while EU REACH and EFSA novel food assessments shape European import requirements. California's State Water Resources Control Board irrigation regulations directly impact kernel quality and oil yield consistency for processors. Stakeholders must monitor evolving organic integrity standards and water allocation policies that determine feedstock reliability across the value chain.
Market Dynamics
EU REACH compliance is forcing cosmetic formulators to abandon solvent-extracted feedstocks in favor of cold-pressed, traceable alternatives, compressing procurement timelines and elevating organic certification premiums across European supply chains.
Growth Catalysts
- Clean-label cosmetics mandate:Formulators in Germany's natural beauty cluster now require organic-certified almond oil to meet retailer sustainability scorecards, pulling volume toward cold-pressed grades.
- REACH traceability expansion:The EU's tightened ingredient documentation rules are disqualifying non-verifiable supply sources, advantaging vertically integrated California processors with orchard-to-bottle chain of custody.
- Pharmaceutical emollient demand:Clinical interest in almond oil's anti-inflammatory properties for dermal applications is accelerating pharmaceutical-grade refinement capacity expansion.
Market Restraints
- California water allocation volatility:The State Water Resources Control Board's irrigation restrictions directly threaten kernel yield consistency, creating input cost instability for oil extractors.
- Organic certification bottleneck:USDA and EU organic integrity audits now require 36-month transition periods for new orchard conversions, constraining certified feedstock expansion.
- Synthetic emollient substitution:Petrochemical-derived alternatives at lower price points continue capturing mass-market cosmetic formulations, pressuring almond oil's volume position in economy tiers.
Strategic Opportunities
- Underpenetrated Asian nutraceutical channels:Japan's PMDA and South Korea's MFDS are streamlining novel food approvals for functional oils, opening pharmaceutical-grade export pathways.
- Direct-to-formulator digital platforms:Bulk ingredient marketplaces are disintermediating traditional distributors, allowing specialty oil processors to capture margin from mid-size cosmetic manufacturers.
- Water-efficient orchard technology:Subsurface drip irrigation and deficit irrigation protocols are enabling yield stability under California's tightening environmental regulations.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous USDA organic, EU organic, and COSMOS approvals require dedicated compliance teams, stretching mid-size processor administrative capacity.
- Cold-press capacity scaling costs:Mechanical pressing equipment for pharmaceutical-grade output demands stainless steel construction and temperature-controlled environments, elevating capital intensity for quality tier expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Almond Oil Market |
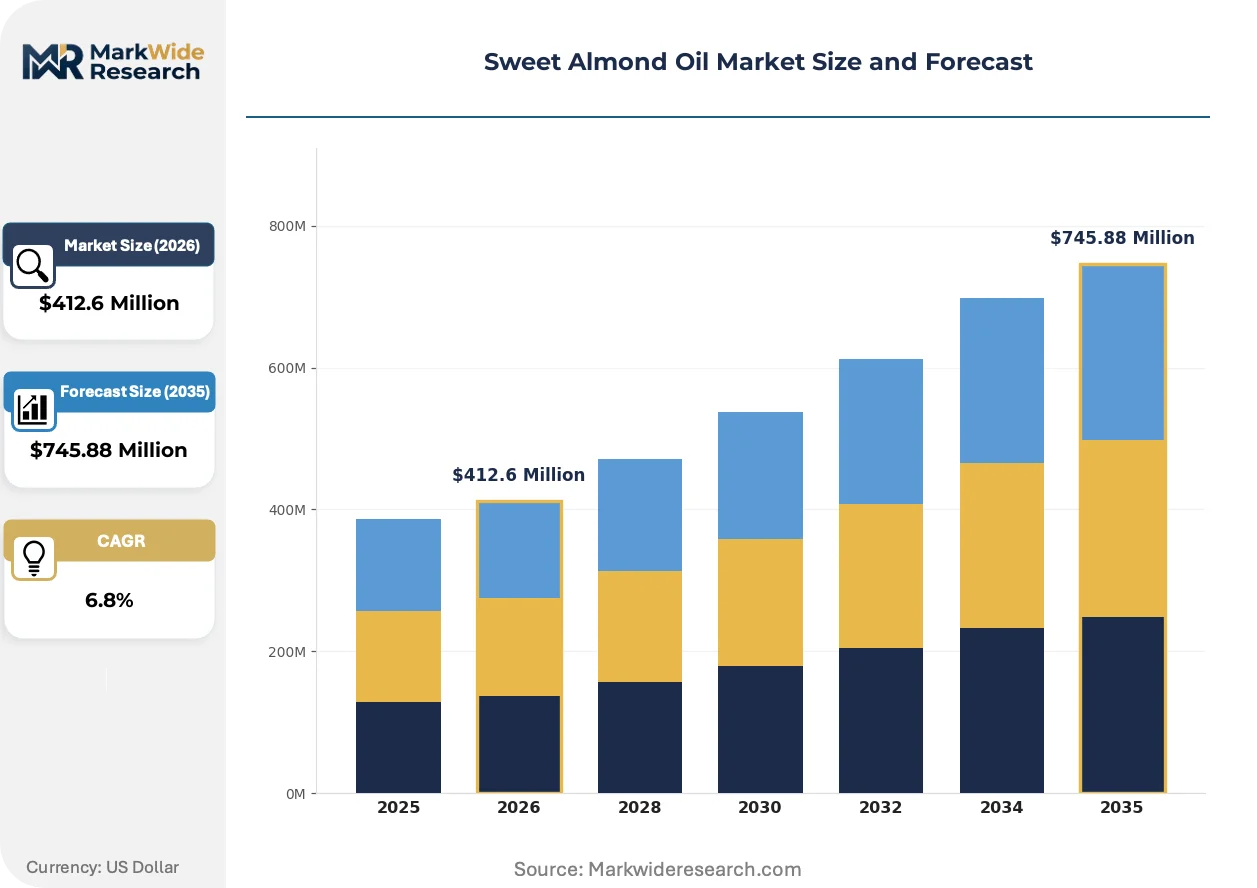
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Unrefined, Organic, Cold-Pressed Application: Cosmetics, Food Industry, Pharmaceuticals, Nutraceuticals Packaging Type: Bottles, Jars, Bulk Containers, Sachets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | La Tourangelle, Plimon, Blue Diamond Growers, Jedwards International, Liberty Vegetable Oil Company, Now Health Group, ESI S.p.A., Proteco Oils, Provital Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Almond Oil Market Emerging Trajectories
Supercritical CO2 extraction protocols are advancing alongside blockchain-enabled provenance tracking, compressing the gap between artisanal quality claims and industrial-scale verification.
Supercritical CO2 extraction technology operates at low temperatures with zero solvent residue, preserving heat-sensitive bioactive compounds for pharmaceutical formulations. Cosmetic manufacturers in France and Germany are piloting this method for high-value skincare lines. The process is rendering obsolete traditional cold-press limitations on batch consistency and oxidative stability.
REACH Article 33 disclosure requirements now mandate full supply chain transparency for cosmetic ingredients above 0.1% concentration. This regulatory pressure is fragmenting procurement relationships as formulators demand documented orchard origins. Small-scale Spanish and Italian processors without traceability infrastructure are losing shelf access to California's vertically integrated suppliers.
Clean beauty certification is displacing conventional ingredient sourcing as the primary buyer decision criterion. Specialty retailers and direct-to-consumer brands now require COSMOS or NSF/ANSI 305 verification before listing. This behavioral pivot concentrates demand in Germany, France, and the Netherlands where retailer sustainability commitments are legally binding.
Sweet Almond Oil Market Segmentation
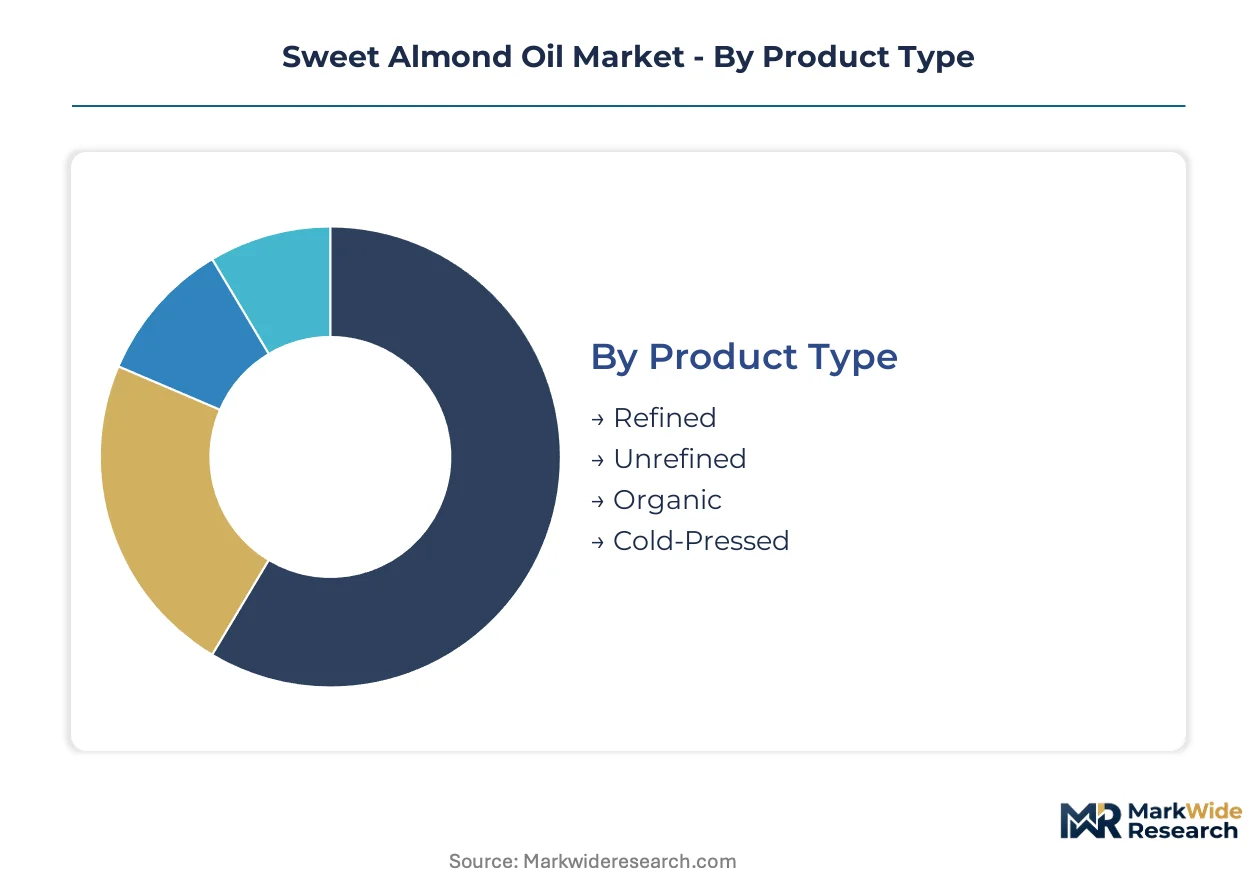
Sweet almond oil segmentation reflects divergent supply chain requirements across cosmetic, food, and pharmaceutical channels. Each product grade demands distinct certification protocols, extraction methods, and packaging configurations that determine margin capture and customer access.
Product Type:
After-sales service intensity varies sharply across extraction grades, with organic and pharmaceutical-tier products requiring certificate-of-analysis documentation and batch traceability support that refined food-grade volumes do not demand.
- Refined:Heat-processed and filtered to remove impurities, achieving neutral flavor profiles and extended shelf stability. Food manufacturers in Germany's baking sector prioritize this grade for high-temperature processing applications where unrefined variants would degrade.
- Unrefined:Retains natural tocopherols and characteristic aroma through minimal processing, commanding preference among artisanal cosmetic formulators in France seeking sensorial differentiation for premium skincare lines.
- Organic:USDA or EU-certified cultivation with 36-month transition audits and prohibited synthetic inputs.
- Cold-Pressed:Mechanical extraction below 40°C preserves heat-sensitive phytosterols for dermal anti-inflammatory applications.
By volume, refined grades lead. By growth pace, organic cold-pressed variants are climbing the fastest.
Application:
Cost tier stratification separates pharmaceutical-grade refinement investments from commodity food processing, with mid-tier cosmetic applications capturing the widest margin spread between raw material and finished formulation.
- Cosmetics:Emollient and carrier oil functions dominate skincare, haircare, and massage product formulations. Germany's natural beauty cluster drives specification tightening toward COSMOS-certified feedstock with documented orchard provenance.
- Food Industry:Salad dressings, baking, and confectionery applications consume volume at lower per-unit value. California processors supply this channel through established distributor relationships with minimal certification overhead.
- Pharmaceuticals:Dermal preparations and excipient applications require GMP-compliant refinement with endotoxin testing and sterile filtration protocols.
- Nutraceuticals:Softgel encapsulation and functional food fortification demand oxidative stability specifications exceeding standard food grades.
Cosmetics generates the highest unit margins. Pharmaceuticals shows the steepest expansion trajectory.
Packaging Type:
Volume scale determines packaging economics, with bulk containers serving manufacturing clients at 1000-liter minimums while retail formats capture 3-4x markup through specialty channel distribution.
- Bottles:Amber glass and UV-protected PET formats dominate direct-to-consumer cosmetic sales. French apothecary retailers specify pharmaceutical-grade glass with tamper-evident closures for premium positioning.
- Jars:Wide-mouth configurations serve body butter and balm formulations requiring scoop access. German natural cosmetics brands favor recycled glass with minimalist labeling to align with sustainability scorecards.
- Bulk Containers:Stainless steel totes and food-grade polyethylene drums supply manufacturing scale.
- Sachets:Single-use hotel amenity and sample formats represent minimal volume but high brand exposure value.
Bulk containers dominate tonnage. Bottles deliver the fastest value growth.
Distribution Channel:
Customer type fragmentation separates price-sensitive food service procurement from specification-driven cosmetic manufacturing, with channel selection determining certification burden and payment terms.
- Online Retail:Direct-to-consumer platforms enable small-batch cosmetic brands to bypass distributor markups. Amazon and specialized clean beauty marketplaces in the Netherlands require organic certification documentation before listing approval.
- Supermarkets:Mass-market food and personal care placement demands promotional investment and slotting fees. German discounters Aldi and Lidl drive private-label almond oil volume at compressed margins.
- Specialty Stores:Pharmacies, organic food shops, and apothecaries command premium shelf positioning.
- Wholesalers:Ingredient distributors serve mid-size cosmetic manufacturers with blended product portfolios and technical support services.
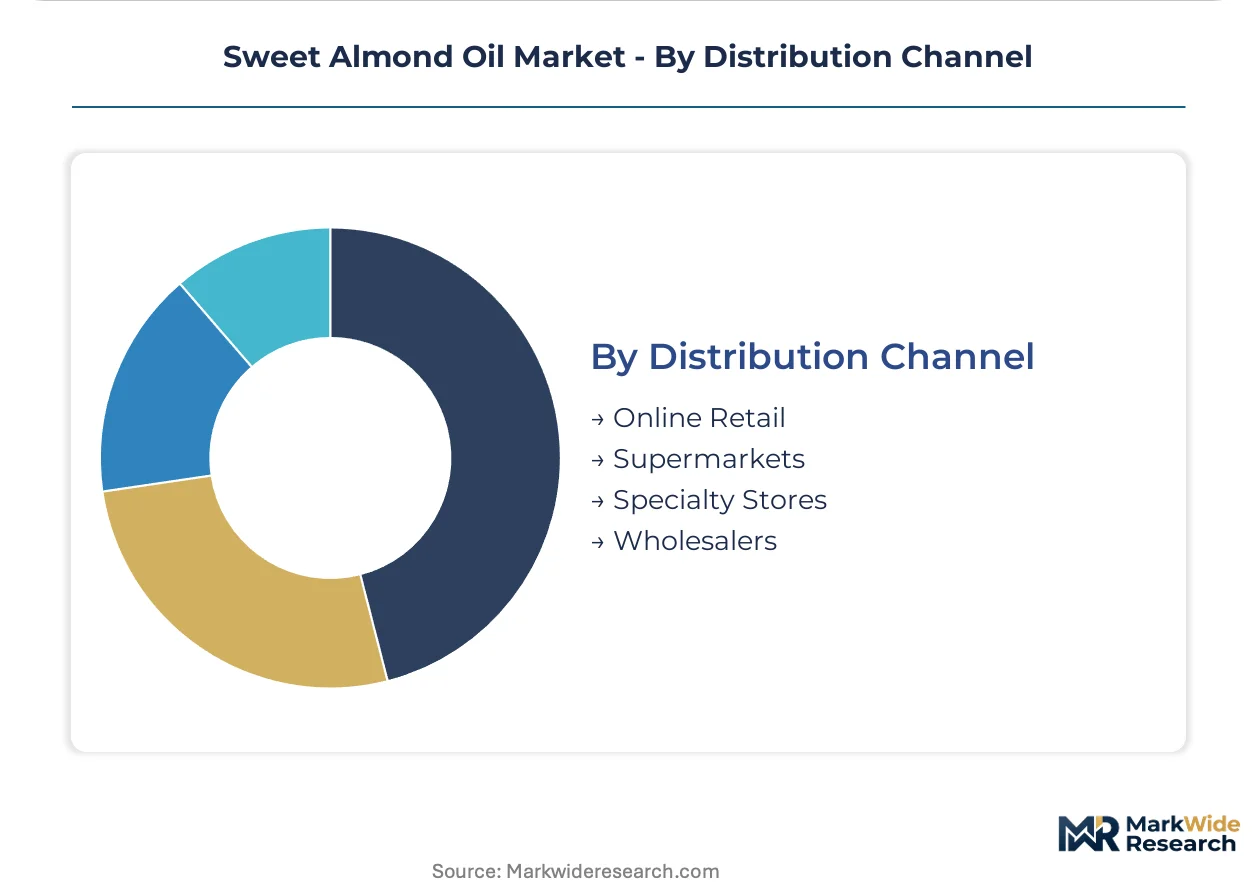
Wholesalers move the greatest volume. Online retail channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic certification anchors California's supply dominance, while ECHA REACH compliance reshapes European procurement patterns across cosmetic and pharmaceutical channels.
United States
California's Central Valley supplies the majority of cold-pressed cosmetic-grade volumes, with Blue Diamond Growers maintaining orchard-to-oil traceability. The State Water Resources Control Board's irrigation allocations directly constrain kernel yield consistency for processors. Sacramento-based extraction facilities now prioritize pharmaceutical-grade refinement capacity to serve domestic nutraceutical encapsulators.
Germany
Cosmetic formulators in Hamburg and Munich drive specification tightening toward COSMOS-certified feedstock with documented provenance. Germany's national chemical regulator enforces REACH Article 33 disclosure thresholds above 0.1% concentration. The natural beauty cluster around Berlin demands organic cold-pressed grades exclusively, compressing procurement timelines for non-verifiable Mediterranean suppliers.
France
Provence-based artisanal cosmetics manufacturers source unrefined grades for sensorial differentiation in premium skincare. ANSM and CNIL oversight extends to cosmetic ingredient traceability beyond baseline EU requirements. Parisian apothecary retailers specify pharmaceutical-grade glass packaging with tamper-evident closures for direct-to-consumer positioning.
Italy
Pharmaceutical-grade refinement for dermal applications concentrates in Emilia-Romagna's processing corridor. ESI S.p.A. anchors regional capacity for GMP-compliant output with endotoxin testing protocols. Bologna's cosmetic chemistry cluster sources predominantly from Spanish and Californian orchards due to limited domestic almond cultivation.
Japan
PMDA streamlining of novel food approvals opens pharmaceutical-grade export pathways for functional oil applications. Tokyo-based nutraceutical encapsulators seek oxidative stability specifications exceeding standard food grades. Osaka's cosmetic formulators pilot supercritical CO2 extraction for high-value skincare lines requiring zero solvent residue.
Sweet Almond Oil Market Vendor Landscape
Vertically integrated processors and specialty refinement specialists split the market between volume efficiency and certification depth. California-based orchard operators capture supply consistency premiums through backward integration into kernel production. European certification-focused processors command margin through COSMOS and pharmaceutical-grade compliance. Competitive moves center on traceability infrastructure investment and cold-press capacity scaling for quality-tier expansion.
Within the vertically integrated tier, Blue Diamond Growers exemplifies orchard-to-oil control spanning cosmetic and food-grade channels. Among European specialists, Plimon anchors organic certification depth while ESI S.p.A. occupies the pharmaceutical-grade refinement segment. These three companies represent the dominant strategic archetypes: captive supply control, certification authority, and GMP-compliant processing capacity.
| Leading Market Players |
|---|
| La Tourangelle |
| Plimon |
| Blue Diamond Growers |
| Jedwards International |
| Liberty Vegetable Oil Company |
| Now Health Group |
| ESI S.p.A. |
| Proteco Oils |
| Provital Group |
| Others |
Supply Flow & Price Mechanics
Los Angeles-Long Beach port congestion surcharges are compressing margins for European cosmetic formulators sourcing Californian cold-pressed grades, amplifying price spreads between Pacific and Atlantic delivery points while accelerating procurement consolidation around vertically integrated suppliers with captive California orchard access.
Pricing Analysis
Trans-Atlantic freight differentials now exceed $0.40 per liter between Hamburg and Marseille delivery points for organic-certified cold-pressed volumes. Three-tier pricing structure across premium pharmaceutical, standard cosmetic, and economy food-grade levels stratifies by certification depth and extraction temperature protocols. Pricing pressure stems from synthetic emollient substitution in mass-market personal care, with petrochemical alternatives capturing economy-tier volume. Mass-market food manufacturers exhibit highest price sensitivity, while German natural beauty formulators absorb premiums for documented COSMOS provenance.
Supply Chain Analysis
EU REACH Article 33 disclosure requirements function as de facto export controls on non-verifiable Mediterranean suppliers, fragmenting procurement relationships across the value chain. Kernel supply concentrates in California, Spain, and Italy, with Californian processors commanding traceability premiums. Extraction capacity draws from mechanical cold-press equipment, stainless steel refinement infrastructure, and pharmaceutical-grade filtration systems. Single-source vulnerability concentrates around California's Central Valley irrigation allocations, where State Water Resources Control Board restrictions threaten yield consistency. Distribution runs through bulk stainless steel totes for manufacturing scale, with amber glass bottling for apothecary retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweet almond oil demand cycles correlate with clean beauty certification adoption waves, positioning the market for recovery as EU retailer sustainability commitments harden into binding procurement specifications.
For Market Incumbents: Insulate core margin pools by deepening backward integration into water-efficient orchard assets and accelerating COSMOS certification coverage before EU organic integrity audits tighten. Synthetic emollient substitution in economy personal care tiers threatens volume displacement; counter by locking long-term offtake agreements with German natural beauty cluster formulators. For New Entrants and Emerging Players: Establish a beachhead in Japan's PMDA-streamlined nutraceutical encapsulation segment, where oxidative stability specifications exceed standard food grades and Californian incumbents lack dedicated pharmaceutical-grade refinement relationships. Target South Korean MFDS novel food approval pathways for functional oil positioning, leveraging supercritical CO2 extraction as technical differentiation against mechanical cold-press limitations. For Investors and Strategic Acquirers: Specialty refinement specialists with GMP-compliant capacity and existing EMA notification pathways represent the most defensible acquisition archetype for pharmaceutical-grade exposure. Long-term viability hinges on water rights security under California's tightening environmental regulations. Watch PMDA and MFDS approval velocity as inflection indicators for Asian nutraceutical demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Water-Efficient Orchards | Captures yield stability premiums under State Water Resources Control Board allocation constraints. |
| COSMOS Certification Expansion | Locks shelf access with German retailers bound by legally binding sustainability scorecards. |
| Pharmaceutical-Grade Refinement Capacity Addition | Serves PMDA and MFDS novel food approval pathways for functional oil encapsulators. |
| Direct-to-Formulator Digital Platform Launch | Disintermediates traditional distributors for mid-size cosmetic manufacturers seeking traceability documentation. |
| Supercritical CO2 Extraction Technology Deployment | Preserves heat-sensitive bioactives for high-value French and German skincare formulations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cosmetic formulators, pharmaceutical excipient procurement managers, cold-press extraction facility operators, and organic certification auditors. Secondary validation drew from ECHA REACH disclosure databases, USDA organic integrity audit records, FDA food-contact substance notifications, and California State Water Resources Control Board allocation filings. Bottom-up volume modeling triangulated against top-down trade flow analysis across the analysis window.
Calibration anchored volume and value outputs to observed procurement patterns across extraction grade tiers, application segments, and packaging configurations. Segmentation dimensions spanned refined versus unrefined versus organic cold-pressed product types, cosmetic versus food versus pharmaceutical versus nutraceutical end-uses, and bulk container versus bottle versus jar packaging formats. CAGRs derived from regression against kernel yield projections, certification adoption curves, and regulatory enforcement intensity trajectories. Water allocation volatility and synthetic substitution elasticities served as key forecast sensitivity inputs.
Sensitivities concentrate around California irrigation restriction severity, EU organic integrity audit frequency, and Asian nutraceutical approval velocity. Forecasts reflect documented assumptions on certification transition timelines and REACH disclosure threshold enforcement. Material shifts in State Water Resources Control Board allocation policies or PMDA/MFDS novel food approval timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sunflower Meal Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Cottonseed Oil Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Shortening Powder Market
Ingredients
Konjac Flour Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Europe Gelatin Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Non Meat Ingredients Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Commercial Amino Acids Market