
 South America Clean Ingredients Market | 2026-2036
South America Clean Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
South America Clean Ingredients Market Analytics
Stevia and monk fruit extracts is broadening the addressable market for sugar reduction across South American beverage portfolios. Kerry Inc leverages its regional formulation centers to anchor technical service relationships with mid-sized Brazilian juice processors. Chr. Hansen Holding A/S specializes in microbial-derived preservation systems that extend shelf life without synthetic chemical declarations. Givaudan dominates natural flavor compounding for the premium snack segment in Argentina and Chile.
Clean ingredients encompass plant-derived, minimally processed inputs that exclude artificial colors, synthetic preservatives, and genetically modified organisms, typically meeting organic or non-GMO certification thresholds and functioning as direct replacements in standard manufacturing lines. These inputs serve primarily to maintain sensory performance while satisfying label transparency demands from health-conscious consumers and retail procurement gatekeepers. Plant-based proteins and natural sweeteners command the deepest margin pools as volume buyers consolidate supply agreements around single-source botanical extraction. Clean preservatives are gaining fastest in ambient-stable sauces and dressings where ANVISA scrutiny of benzoate levels has intensified manufacturer reformulation timelines. Organic flavors remain comparatively mature in baking applications, though beverage innovators are pulling higher-complexity profiles into carbonated and functional drink formulations.
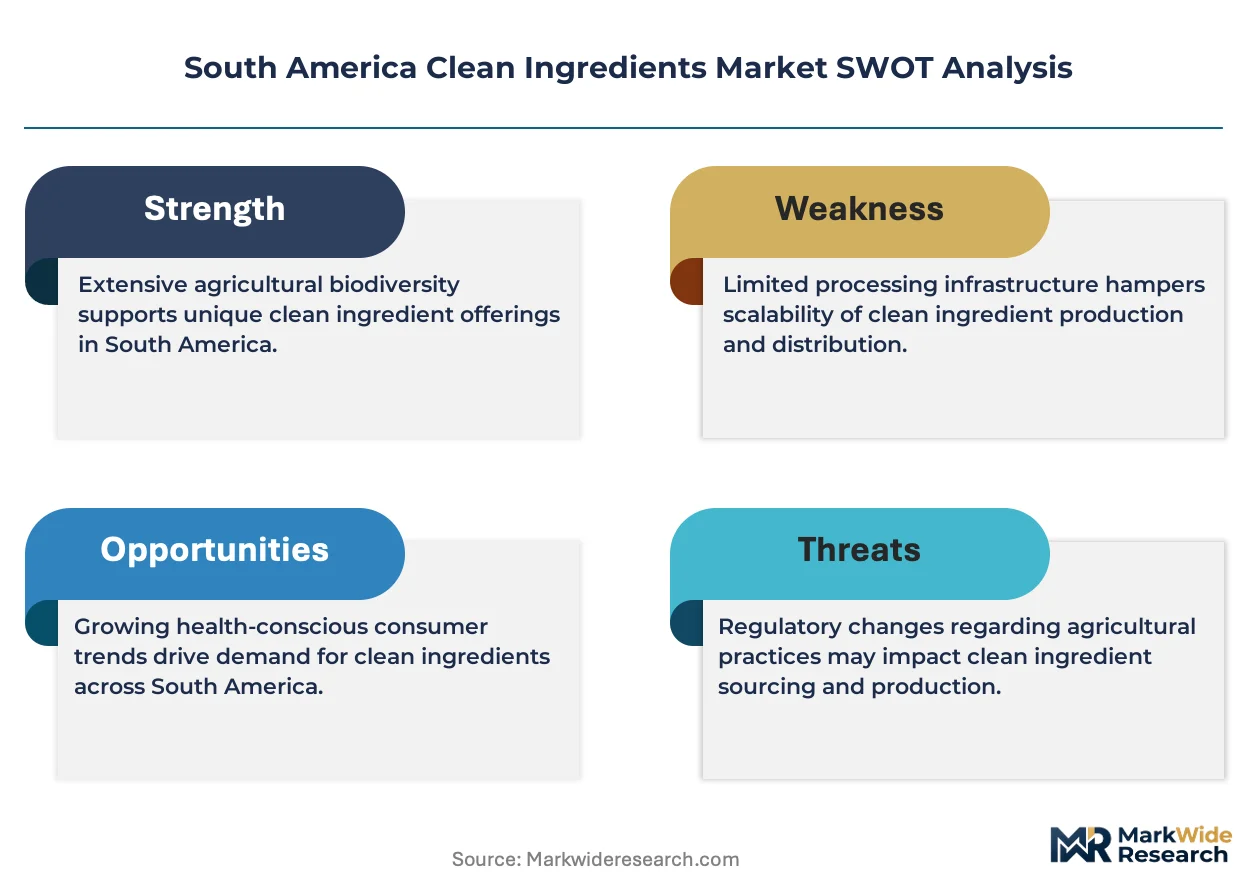
ANVISA's evolving additive disclosure rules and MERCOSUR harmonization protocols on food labeling are forcing reformulation investments across Brazilian and Argentine manufacturing bases. Brazil's national organic certification program under MAPA and Chile's strict GMO-free import standards create layered compliance thresholds that filter market access for international suppliers. Argentina's food code updates under INAL are tightening permissible preservative concentrations in processed sauces and condiments. Stakeholders must monitor regulatory divergence between national frameworks and sub-regional trade bloc standards to avoid stranded inventory in cross-border distribution channels.
Market Dynamics
ANVISA's additive disclosure tightening is compressing reformulation timelines across Brazilian processed food corridors, forcing manufacturers to accelerate clean label transitions or face retail delisting from health-conscious procurement gatekeepers.
Growth Catalysts
- ANVISA labeling mandates:Brazil's regulator now requires front-of-pack warning symbols on synthetic additives, pushing beverage formulators toward stevia and monk fruit extraction protocols.
- Chilean import standards:Strict GMO-free certification requirements for inbound ingredients are filtering supplier pools toward verified organic botanical sources.
- Clean preservation systems:Microbial-derived shelf-life extension technologies are displacing benzoate-dependent formulations in ambient-stable sauces and dressings.
Market Restraints
- Organic input cost volatility:Weather-dependent stevia leaf and monk fruit harvests in Paraguay and Colombia create raw material price instability for extractors.
- Extraction technology concentration:Supercritical CO2 processing capacity clusters in São Paulo and Buenos Aires, creating bottleneck risk for regional natural flavor production.
- Technical performance gaps:Plant-based proteins from regional legume sources exhibit inferior emulsification versus soy isolates, limiting clean-label meat analog adoption.
Strategic Opportunities
- Argentine sauce reformulation:INAL's tightening preserviture concentration limits create first-mover advantage for clean preservative suppliers in Buenos Aires manufacturing corridors.
- Functional beverage innovation:Carbonated drink portfolios in São Paulo are pulling higher-complexity organic flavor profiles previously reserved for premium snacking applications.
- MERCOSUR harmonization:Sub-regional trade bloc alignment on food labeling standards reduces compliance fragmentation for cross-border ingredient distribution.
Industry Challenges
- Formulation talent scarcity:Mid-sized Brazilian juice processors lack in-house clean-label reformulation expertise, creating dependency on external technical service relationships.
- Certification timeline compression:MAPA's organic certification backlog extends supplier qualification cycles, straining manufacturer procurement calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Clean Ingredients Market |
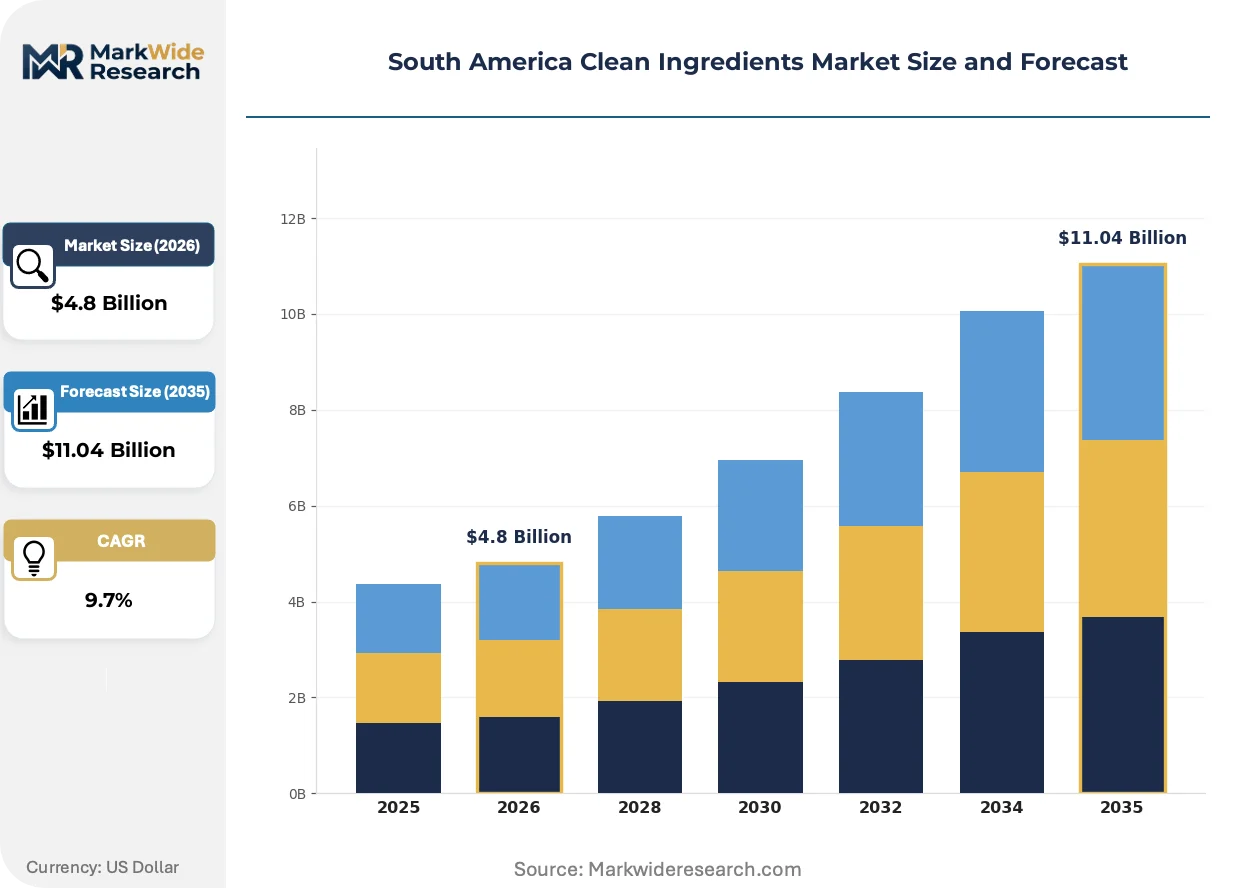
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sweeteners, Plant-Based Proteins, Organic Flavors, Clean Preservatives End User: Food & Beverage, Personal Care, Nutraceuticals, Household Products Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale Application: Baking, Beverages, Sauces, Snacks |
| Companies Covered | Chr. Hansen Holding A/S, Sensient Technologies Corporation, Dohler Group, DDW Inc, Kerry Inc, Givaudan, Firmenich SA, Archer Daniels Midland Company, Corbion NV, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Clean Ingredients Market Evolving Landscape
Clean ingredient adoption across South America is pivoting from premium positioning to mass-market technical performance requirements, with sensory parity becoming the non-negotiable threshold for reformulation decisions.
Supercritical CO2 extraction is consolidating as the dominant processing technology for high-purity stevia glycosides and monk fruit mogrosides. Brazilian beverage formulators in São Paulo's processed food corridor are adopting these systems at accelerating cadence. The technology is consolidating supply relationships around single-source botanical extraction agreements that lock in volume commitments and margin pools.
ANVISA's evolving additive disclosure framework is forcing simultaneous reformulation across multiple product categories. Brazilian manufacturers face compressed timelines to eliminate synthetic colorants and preservatives or trigger mandatory warning labels. The ambient-stable sauces and dressings segment is responding most aggressively, with benzoate-dependent formulations facing explicit retail procurement exclusion.
Buyer concentration among Brazilian retail chains is reshaping supplier qualification requirements. Mid-sized juice processors now face consolidated technical service demands from São Paulo-based supermarket headquarters. Argentina's smaller manufacturing base exhibits more fragmented procurement, though Buenos Aires retail consolidation is beginning to replicate the Brazilian pattern.
South America Clean Ingredients Market Segmentation
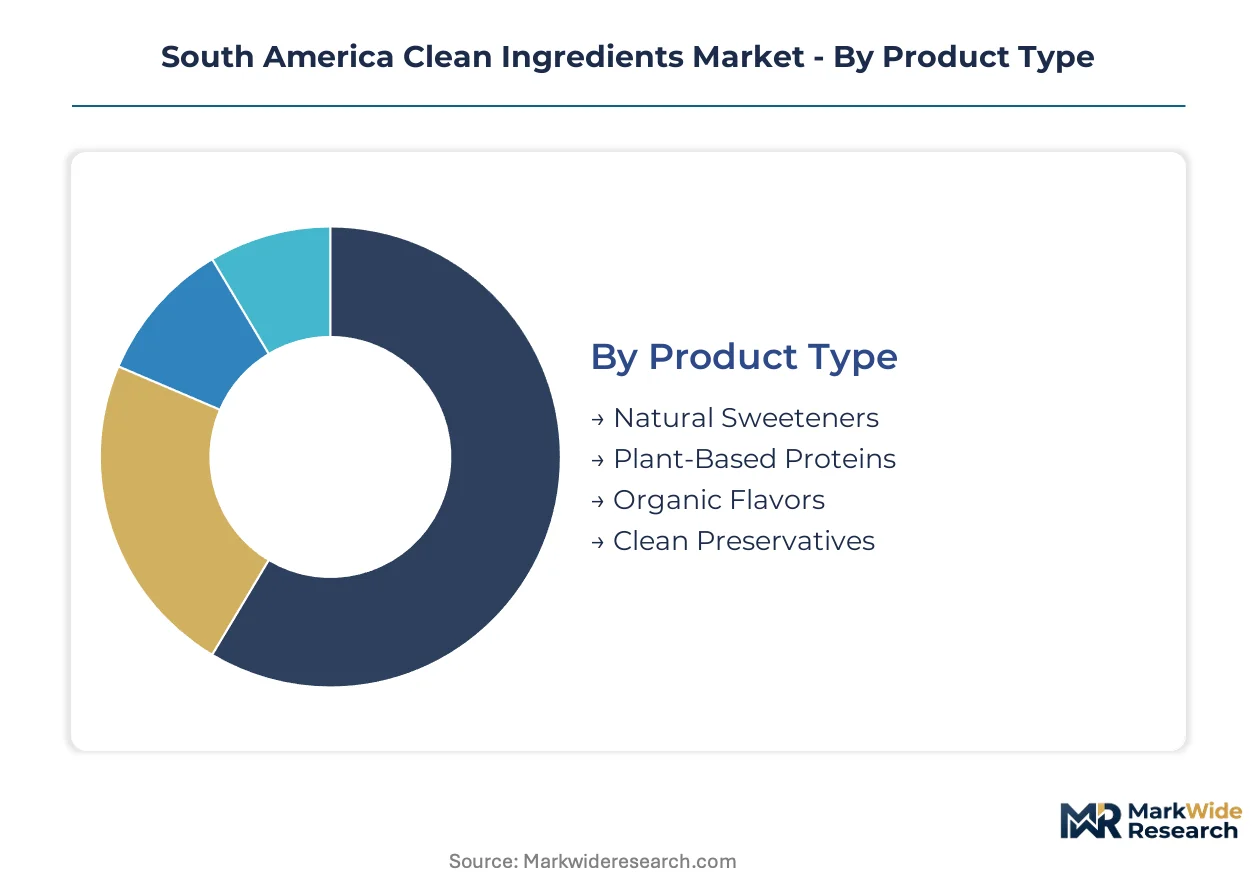
Clean ingredient procurement patterns diverge sharply across buyer types in South America. Manufacturers prioritize functional performance thresholds, while retail gatekeepers enforce certification visibility. Understanding these segmentation fractures reveals where margin pools concentrate and where reformulation investments deliver compliance advantage.
Product Type:
Cost tier separates commodity buyers from premium formulators seeking single-source botanical extraction agreements.
- Natural Sweeteners:Stevia glycosides and monk fruit mogrosides extracted via supercritical CO2 systems dominate sugar reduction protocols. São Paulo beverage corridors absorb the majority of volume as ANVISA warning label mandates compress reformulation timelines for carbonated and functional drink portfolios.
- Clean Preservatives:Microbial-derived shelf-life extension systems displace benzoate-dependent formulations in ambient-stable applications. Argentine sauce manufacturers under INAL's tightening concentration limits represent the most aggressive adoption front, with Buenos Aires processing corridors leading procurement acceleration.
- Plant-Based Proteins:Regional legume isolates from Brazilian soybean and Argentine pea extraction facilities serve meat analog and bakery fortification applications.
- Organic Flavors:High-complexity profiles previously reserved for premium snacking now penetrate beverage innovation pipelines.
Volume sits with natural sweeteners; growth tilts toward clean preservatives.
End User:
Application maturity determines whether buyers accept technical performance trade-offs or demand sensory parity.
- Food & Beverage:Processed food corridors in Brazil and Argentina drive the deepest procurement consolidation. ANVISA disclosure rules and INAL preserviture limits force simultaneous multi-category reformulation, concentrating technical service relationships around Kerry Inc's regional formulation centers and Chr. Hansen's microbial preservation expertise.
- Personal Care:Clean label surfactants and botanical actives face formulation talent scarcity across mid-sized Brazilian processors.
- Nutraceuticals:Organic certification backlogs under MAPA strain supplier qualification cycles for dietary supplement manufacturers.
- Household Products:Natural surfactant and solvent alternatives remain comparatively nascent, constrained by cost-performance gaps versus petrochemical baselines.
Revenue concentrates in food and beverage; nutraceuticals expand most quickly as certification pipelines clear.
Distribution Channel:
Customer scale and procurement sophistication dictate channel selection across the value chain.
- Supermarkets:Brazilian retail chain consolidation reshapes supplier qualification requirements, with São Paulo headquarters imposing consolidated technical service demands on mid-sized juice processors.
- Wholesale:Bulk ingredient distribution dominates plant-based protein and natural sweetener volume flows to large-scale manufacturers.
- Specialty Stores:Premium organic flavors and certified clean preservatives serve artisanal producers and regional brands.
- Online Retail:Direct-to-manufacturer platforms gain traction among smaller Argentine processors seeking fragmented procurement flexibility.
Wholesale captures current volume; online retail gains share fastest as procurement digitization accelerates.
Application:
Reformulation urgency varies by regulatory exposure and retail procurement pressure.
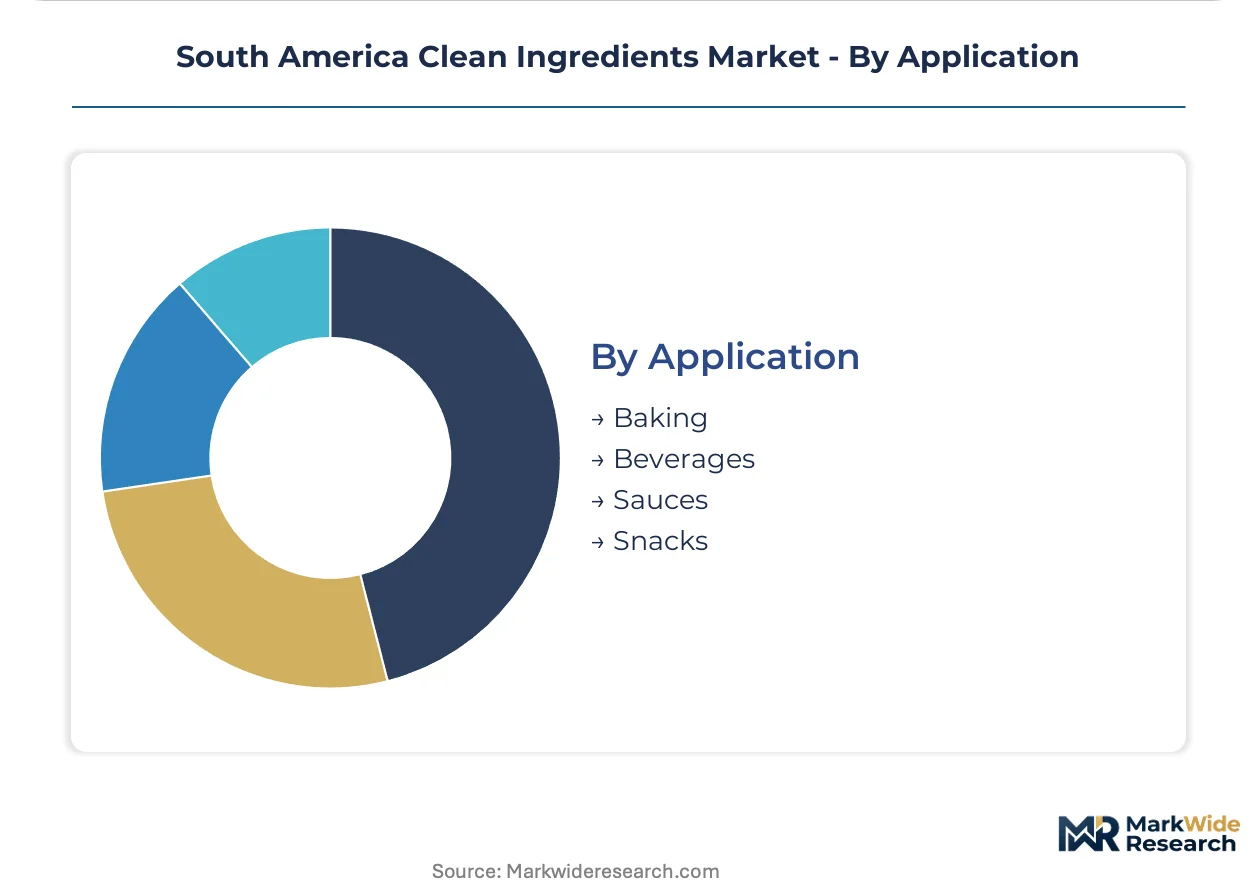
- Beverages:Carbonated and functional drink portfolios in São Paulo pull higher-complexity organic flavor profiles and stevia-monk fruit extraction protocols. ANVISA's front-of-pack warning symbols on synthetic additives create immediate displacement pressure.
- Sauces:Ambient-stable dressings face the most aggressive clean preservation adoption as benzoate-dependent formulations trigger explicit retail exclusion under tightening scrutiny.
- Snacks:Premium positioning in Argentina and Chile sustains Givaudan's natural flavor compounding dominance.
- Baking:Organic flavors remain comparatively mature, with slower reformulation cycles than beverage or sauce categories.
Volume clusters in beverages; sauces follow the steepest expansion trajectory as preserviture limits tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration clusters in São Paulo's processed food corridor, where ANVISA disclosure mandates drive procurement urgency. Argentine sauce manufacturers under INAL's tightening limits represent the secondary growth pole.
Brazil
São Paulo anchors clean ingredient procurement across carbonated beverages and ambient-stable sauces. ANVISA's front-of-pack warning symbols on synthetic additives compress reformulation timelines for mid-sized juice processors. The city's supercritical CO2 extraction facilities consolidate supply relationships around single-source botanical agreements.
Argentina
Buenos Aires manufacturing corridors absorb microbial-derived preservation systems as INAL tightens benzoate concentration limits in processed condiments. The national food code updates force simultaneous multi-category reformulation across sauce and dressing portfolios. Regional extraction capacity remains concentrated in Greater Buenos Aires.
Chile
Santiago-based premium snack producers sustain demand for high-complexity organic flavor profiles. Strict GMO-free import standards filter supplier pools toward verified organic botanical sources. The country's certification requirements exceed MERCOSUR baseline protocols.
Colombia
Bogotá's beverage innovation pipelines pull stevia and monk fruit extraction protocols for sugar reduction portfolios. The country's organic certification alignment with MAPA standards eases cross-border supply integration. Andean extraction facilities serve regional natural sweetener demand.
Paraguay
Stevia leaf cultivation clusters in eastern agricultural zones supply raw material to Brazilian and Argentine processors. Weather-dependent harvests create price volatility that propagates through regional extractors. The country's botanical output feeds São Paulo's supercritical CO2 processing capacity.
South America Clean Ingredients Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation service providers capturing disproportionate value in technical performance categories. The supplier base organizes around three archetypes: microbial preservation specialists, natural flavor compounders, and integrated botanical extractors. Consolidation pressure concentrates in extraction technology ownership and regional formulation center networks. Competitive moves cluster on strategic partnerships with mid-sized processors and capacity expansion in supercritical CO2 systems.
Among European-origin specialists, Chr. Hansen Holding A/S and Givaudan occupy anchor positions within their respective archetypes. Kerry Inc represents the integrated technical service model. These three exemplify how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Sensient Technologies Corporation |
| Dohler Group |
| DDW Inc |
| Kerry Inc |
| Givaudan |
| Firmenich SA |
| Archer Daniels Midland Company |
| Corbion NV |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction specialists concentrated in São Paulo and Buenos Aires drive labor-cost differentials that widen pricing-tier spreads between commodity botanical inputs and certified clean-label grades.
Pricing Analysis
Volume sits with commodity-grade stevia leaf and regional legume isolates, while margins concentrate in certified organic extracts and microbial-derived preservation systems. Three-tier pricing structure across premium, standard, and economy levels reflects MAPA organic certification status and extraction purity grades. Cost compression in standard-tier natural sweeteners is intensifying because weather-dependent harvests in Paraguay and Colombia propagate price volatility. Mid-sized Brazilian juice processors exhibit the highest price sensitivity, whereas premium snack manufacturers in Chile accept meaningful premiums for verified GMO-free botanical sources.
Supply Chain Analysis
Single-source vulnerability sits with supercritical CO2 processing capacity clustered in São Paulo and Greater Buenos Aires, creating bottleneck exposure for regional natural flavor production. Raw material supply draws from Paraguayan stevia cultivation zones, Colombian monk fruit harvests, and Brazilian soybean extraction facilities. Weather-induced commodity price volatility represents the dominant structural risk propagating through regional extractors. Distribution runs through wholesale bulk channels serving large-scale manufacturers, with direct-to-procurement online platforms gaining fastest among smaller Argentine processors seeking fragmented supply flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ANVISA's evolving additive disclosure framework erects a barrier-to-entry moat that rewards pre-qualified suppliers with accelerated procurement timelines.
For Market Incumbents: Acquire supercritical CO2 extraction capacity in São Paulo's processing corridor to lock in single-source botanical agreements before capacity constraints harden. Secure MAPA organic certification pipelines early to exploit the backlog straining competitor qualification cycles. Threat substitution from synthetic additive producers facing retail delisting creates acquisition opportunities for distressed clean-label assets. For New Entrants and Emerging Players: INAL's tightening preserviture limits in Argentina open a window for microbial-derived shelf-life extension specialists to establish first-mover positioning in Buenos Aires manufacturing corridors. Target ambient-stable sauce reformulation as the most penetrable application segment, where benzoate-dependent formulations face explicit retail procurement exclusion. Anchor go-to-market strategy through technical service partnerships with mid-sized processors lacking in-house clean-label formulation expertise. For Investors and Strategic Acquirers: Re-rating potential sits with integrated technical service providers given ANVISA disclosure mandates compressing manufacturer reformulation timelines toward outsourced expertise. Long-term viability favors archetypes combining regional formulation centers with captive extraction capacity. Watch INAL's implementation timeline for preserviture concentration limits as the signal indicating Argentine demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | São Paulo extraction facilities consolidate supply relationships around single-source botanical agreements. |
| MAPA Organic Certification Investment | Certified suppliers exploit procurement backlogs straining competitor qualification timelines. |
| Microbial Preservation R&D Partnership | Chr. Hansen-style expertise displaces benzoate-dependent formulations in Argentine sauce corridors. |
| Regional Formulation Center Network | Kerry Inc model anchors technical service relationships with mid-sized Brazilian juice processors. |
| MERCOSUR Harmonization Compliance | Cross-border certification alignment reduces stranded inventory risk in distribution channels. |
Research Methodology
Trade databases, regulatory filing repositories, and agricultural commodity exchange records formed the secondary backbone, supplemented by primary interviews with clean ingredient procurement managers at Brazilian beverage manufacturers, Argentine sauce formulators, Chilean retail category buyers, and supercritical CO2 extraction facility operators. Bottom-up volume estimates from individual processing facilities triangulated against top-down demand projections from end-use consumption patterns.
Historical trendline analysis of stevia leaf and monk fruit harvest volumes informed growth trajectory assumptions across the analysis window. Segmentation modeling incorporated product type tier, end-use application maturity, certification grade, and regional regulatory cluster dimensions. CAGRs derived from curve-fitting approaches applied to validated consumption data points, with ANVISA implementation timelines and INAL code revision schedules serving as industry-specific demand inflection inputs.
Caveats apply where ANVISA enforcement intensity or INAL preserviture limit calibration could materially shift the outlook for reformulation investment cycles. Forecasts reflect documented assumptions about MERCOSUR harmonization progress and MAPA certification pipeline clearance rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cultured Non-Fat Dairy Ingredients Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
South America Lipid Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Oak Extract Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
Baking Ingredients Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Honey Powder Market
Ingredients
Quark Powder Market
Ingredients
Bread Flour Market
Ingredients
2'-Fucosyllactose (2'-FL) Market