
 Dried Fruit Ingredients Market | 2026-2036
Dried Fruit Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Fruit Ingredients Market Analysis
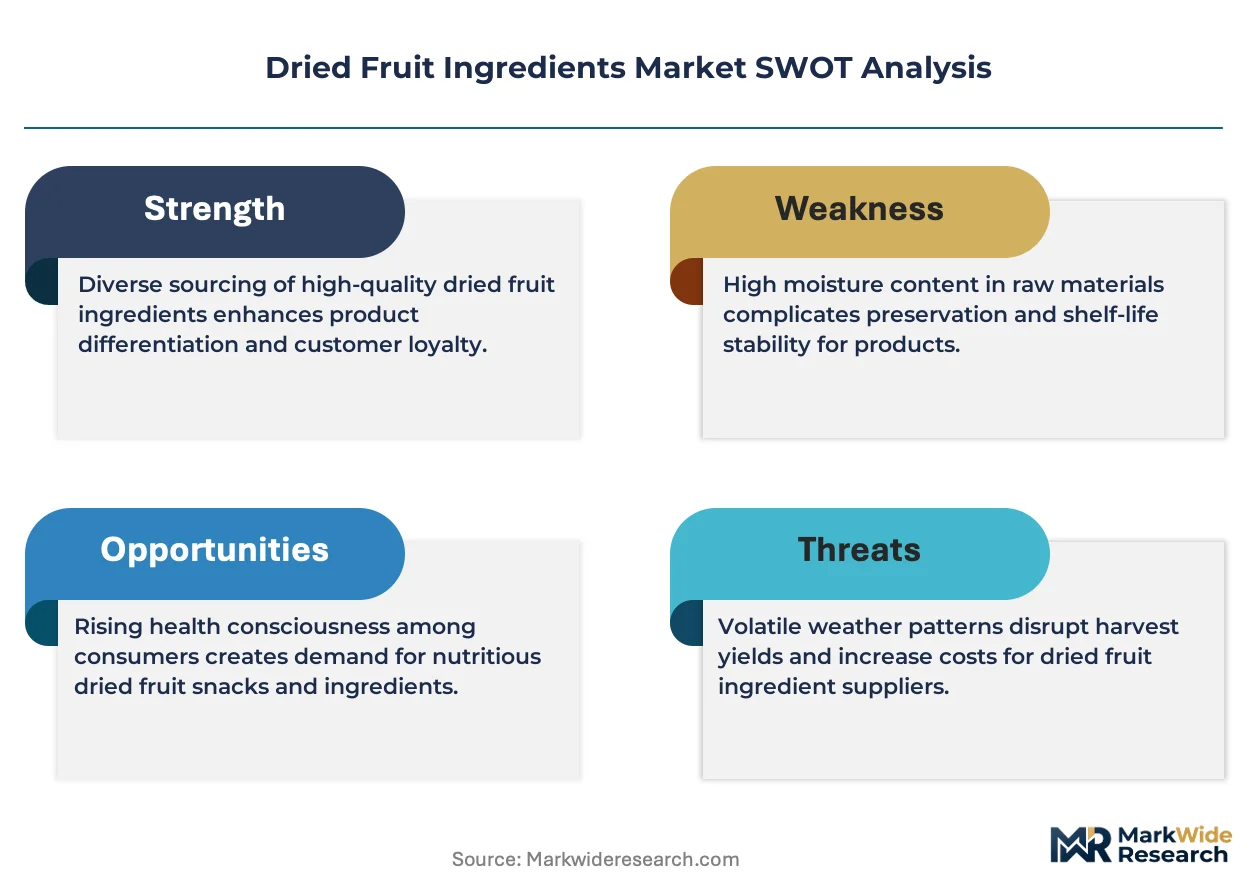
Single-serve pouch configurations is shifting buyer preference across the dried fruit ingredients supply chain, replacing bulk institutional formats in foodservice and retail channels. Sun-Maid Growers of California leverages its cooperative structure to sustain year-round supply consistency for raisin ingredients. Döhler GmbH anchors its position through integrated extraction and formulation capabilities that extend into beverage applications. Mariani Packing Company differentiates through controlled-atmosphere storage technology that preserves moisture specifications for industrial bakery contracts.
Dried fruit ingredients comprise dehydrated or partially rehydrated whole fruits, fruit pieces, powders, and concentrated pastes with moisture content typically ranging from 10% to 25% depending on application requirements; these materials function as natural sweeteners, texturizers, flavor carriers, and shelf-life extendants across processed food manufacturing. Dried raisins and dried figs occupy the largest volume positions within the product type structure, while dried apples capture expanding share in snack bar and cereal applications where lower water activity supports extended ambient distribution. Within the application dimension, bakery remains the most mature demand pool with established supplier relationships, whereas confectionery represents the fastest-growing segment as manufacturers reformulate around sugar reduction targets using date and prune pastes for binding and sweetness.
FDA enforcement of the Food Safety Modernization Act preventive controls for human food governs domestic manufacturing, while EFSA maximum residue levels and EU Mycotoxin Regulation 1881/2006 constrain import eligibility for Mediterranean-origin dried figs and apricots into European markets; compliance with these frameworks determines market access and shapes supplier investment in sorting, testing, and traceability infrastructure. Stakeholders must monitor evolving contaminant thresholds and origin certification requirements as procurement decisions increasingly hinge on documented supply chain integrity rather than price alone.
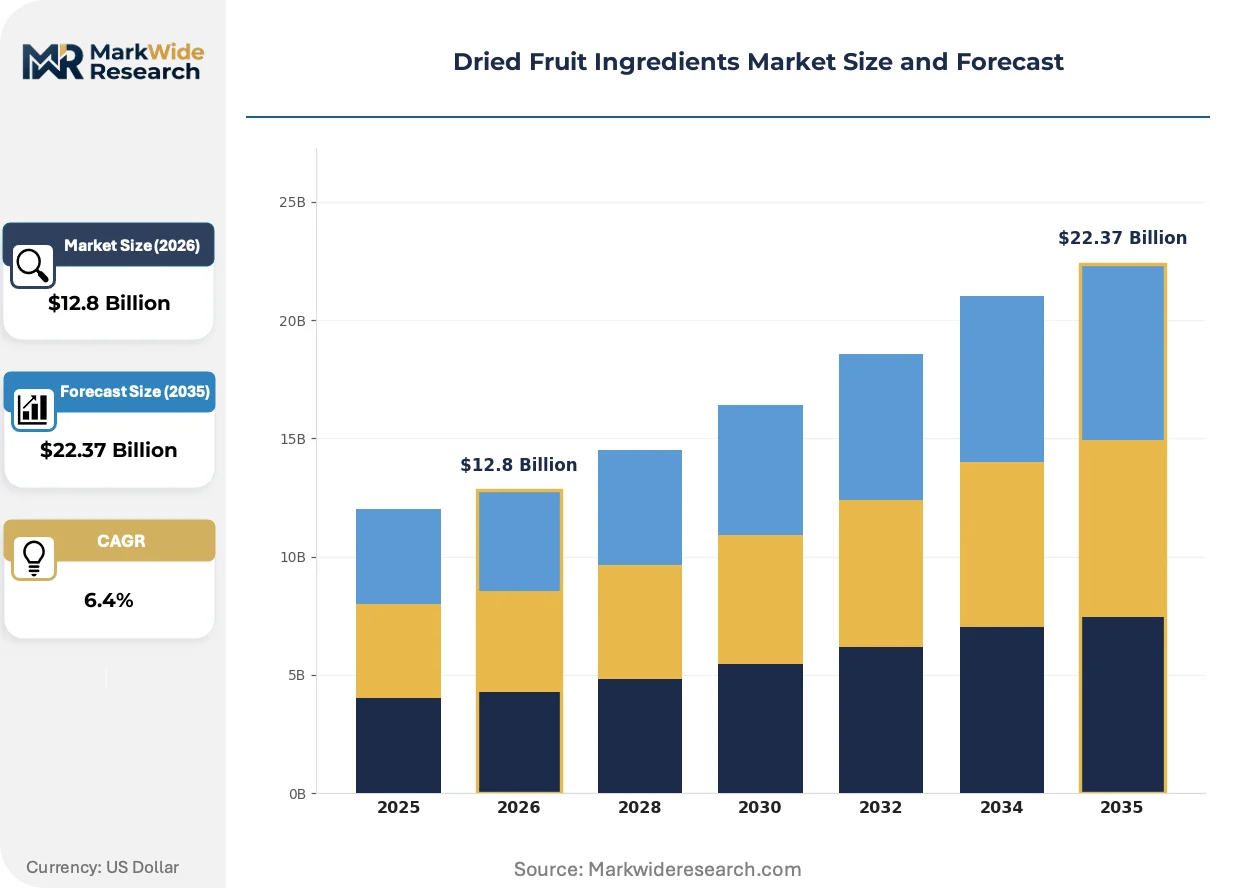
Market Dynamics
Single-serve pouch configurations are compressing procurement volumes for bulk institutional formats across foodservice and retail channels, forcing suppliers to reconfigure production lines and inventory management systems toward smaller batch sizes with higher frequency.
Growth Catalysts
- EFSA Contaminant Thresholds:Tightened aflatoxin limits for dried figs and apricots under updated EU guidance are accelerating investment in sorting and testing infrastructure among Mediterranean processors seeking continued market access.
- Confectionery Reformulation:Date and prune pastes are displacing artificial binders and high-fructose syrups as manufacturers target sugar reduction mandates without sacrificing texture or shelf stability.
- Turkish Processing Concentration:Demand clustering around Turkey as a sourcing and processing hub for Mediterranean dried fruits is drawing capital toward controlled-atmosphere storage and integrated export logistics.
Market Restraints
- Input Cost Volatility:Fresh fruit procurement costs fluctuate with seasonal weather patterns and irrigation water availability in California's Central Valley and Turkey's Aegean region.
- Supply Concentration Risk:Raisin ingredient volumes depend heavily on Sun-Maid Growers of California's cooperative structure, creating single-source vulnerability for industrial bakery contracts.
- Regulatory Friction:FDA enforcement of Food Safety Modernization Act preventive controls imposes compliance burdens on smaller domestic processors lacking dedicated quality assurance infrastructure.
Strategic Opportunities
- Beverage Applications:Integrated extraction capabilities are opening formulation partnerships with juice and functional drink manufacturers seeking natural sweetness and flavor carriers.
- Clean-Label Snack Bars:Dried apple pieces are capturing expanding share in cereal and bar applications where lower water activity supports extended ambient distribution without synthetic preservatives.
- India PLI Scheme:India's production-linked incentive scheme for food processing infrastructure offers capital subsidy pathways for exporters establishing sorting and packaging operations.
Industry Challenges
- Traceability Infrastructure:Documented supply chain integrity requirements under EU Mycotoxin Regulation 1881/2006 demand investment in blockchain or equivalent lot-tracking systems that smaller traders cannot finance.
- Moisture Specification Control:Industrial bakery contracts require precise 10-25% moisture content ranges that degrade during ocean freight unless shippers maintain refrigerated container protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Fruit Ingredients Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Apricots, Dried Figs, Dried Raisins, Dried Apples Application: Beverages, Snacks, Bakery, Confectionery End User: Food Manufacturers, Retailers, Wholesalers, Catering Services Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Sun-Maid Growers of California, Ocean Spray Cranberries, Inc., Dole plc, Döhler GmbH, Mariani Packing Company, ADM, Sunbeam Foods, AL FOAH, Traina Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Fruit Ingredients Market Emerging Trajectories
Processing technology and packaging format evolution are compressing traditional supply chain hierarchies while regulatory scrutiny of contaminants and clean-label procurement standards reshape competitive requirements.
Controlled-atmosphere storage technology is absorbing capital allocation from conventional warehouse refrigeration as Mariani Packing Company and similar industrial suppliers seek to preserve moisture specifications across extended holding periods for bakery contract fulfillment. Large-scale manufacturers are adopting these systems at accelerated pace to secure year-round supply consistency. This technology is absorbing market share from commodity traders lacking equivalent preservation infrastructure.
EU Mycotoxin Regulation 1881/2006 maximum residue levels are constraining import eligibility for Mediterranean-origin dried figs and apricots into European markets. Processors must now maintain laboratory testing protocols and origin certification documentation that smaller exporters cannot sustain. Dried fig suppliers in Turkey and Greece are responding by consolidating around integrated processors with captive laboratory capacity.
Buyer concentration among clean-label snack bar and cereal manufacturers is compressing supplier margins while elevating technical service requirements. Foodservice distributors that previously stocked bulk institutional formats are replacing these with single-serve pouch configurations for retail and hospitality channels. This pattern is most visible in North American and Western European markets where convenience-oriented consumption dominates breakfast and on-the-go snacking occasions.
Dried Fruit Ingredients Market Segmentation
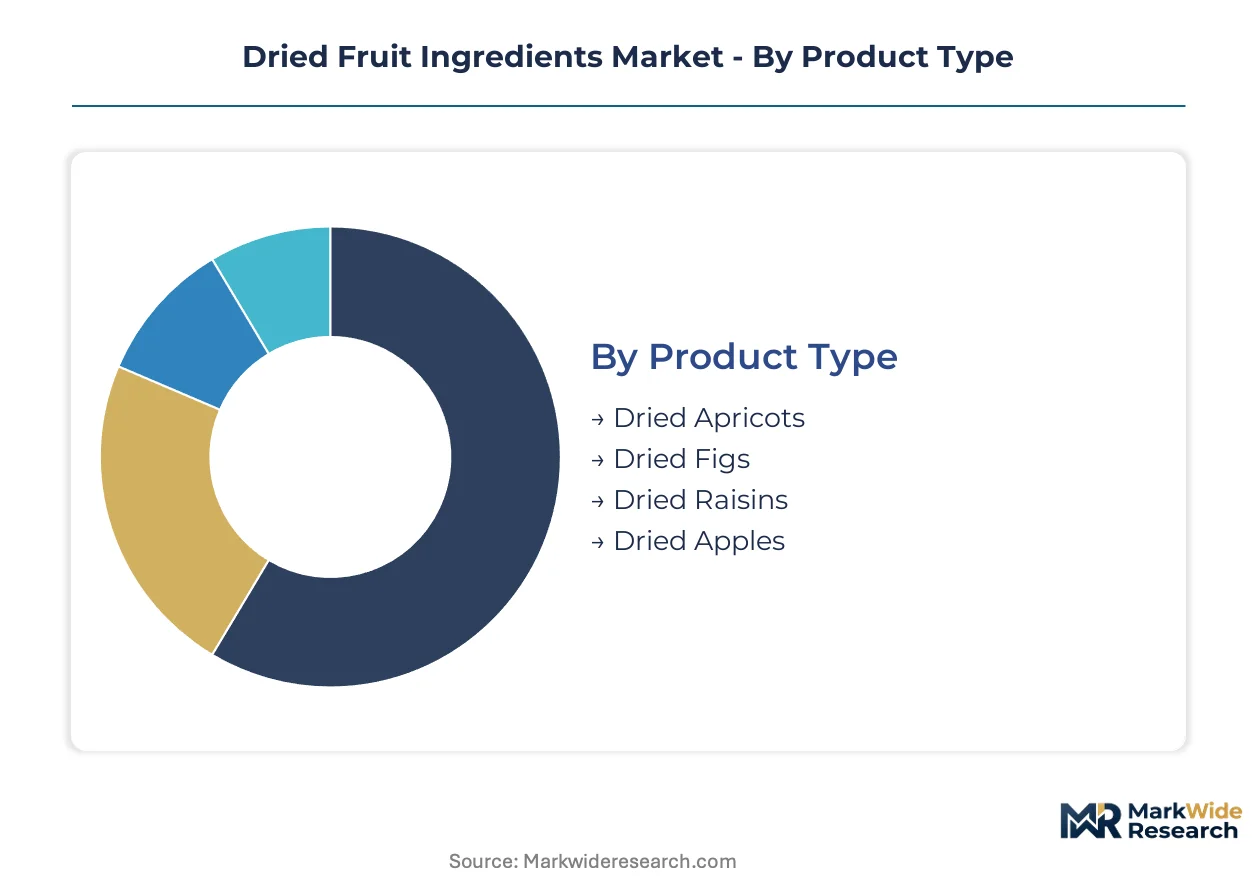
Segmentation in dried fruit ingredients reveals divergent technical requirements between standalone snack applications and embedded industrial formulations. Procurement patterns split between commodity volume contracts for bakery integration and premium specifications for clean-label retail positioning.
Product Type:
Integration depth varies sharply: raisins and figs dominate embedded systems where moisture control and binding functionality matter, while apricots and apples serve more standalone or visible-inclusion applications.
- Dried Raisins:These dehydrated grape products maintain 15-20% moisture specifications critical for industrial bakery dough absorption. California's Central Valley cooperative structure supplies year-round volume to bread and cereal manufacturers facing binding and sweetness requirements without artificial additives.
- Dried Figs:Mediterranean-origin figs carry elevated aflatoxin scrutiny under EFSA thresholds, forcing Turkish processors to invest in optical sorting and laboratory testing infrastructure. Confectionery manufacturers in Europe embed fig pastes as natural binders replacing synthetic alternatives in energy bar formulations.
- Dried Apricots:Turkish and Greek processors supply these to health-focused retail channels where sulfur-free and organic certifications command premium positioning.
- Dried Apples:Lower water activity specifications suit ambient-distribution snack bars; Pacific Northwest sourcing clusters serve North American clean-label contract manufacturers.
Dried raisins lead volumes today; dried apples are gaining share fastest.
Application:
Cost tier segmentation separates commodity-scale bakery procurement from premium confectionery reformulation projects with technical service overlays.
- Bakery:Mature demand pool with established supplier relationships and rigid moisture specification contracts. Industrial bread and pastry manufacturers specify 10-15% moisture ranges for dough compatibility.
- Confectionery:Fastest-climbing application as date and prune pastes displace high-fructose syrups under sugar reduction mandates. European manufacturers drive formulation partnerships requiring integrated extraction capabilities.
- Snacks:Clean-label bar and trail-mix applications favor visible fruit pieces over powders; single-serve pouch configurations now dominate procurement formats.
- Beverages:Natural sweetness carriers and flavor extracts for functional drinks; Döhler GmbH anchors integrated supply through captive extraction infrastructure.
Bakery retains volume leadership; confectionery shows steepest expansion trajectory.
End User:
Customer type determines specification intensity: food manufacturers demand certificate-of-analysis documentation while retailers prioritize packaging format flexibility.
- Food Manufacturers:Industrial-scale buyers with captive quality assurance teams auditing supplier laboratories for mycotoxin compliance. Bakery and confectionery procurement teams specify origin certification and lot traceability.
- Retailers:Private-label developers sourcing single-serve and bulk formats for shelf placement; margin pressure compresses supplier pricing while elevating packaging customization requirements.
- Wholesalers:Intermediate distributors consolidating Mediterranean-origin volumes for redistribution to smaller foodservice operators lacking direct import capability.
- Catering Services:Institutional foodservice buyers shifting from bulk institutional formats to pre-portioned pouches for hospitality and healthcare channels.
Food manufacturers dominate procurement volumes; retailers are expanding specification fastest.
Distribution Channel:
Supply concentration maps to channel control: integrated processors bypass intermediaries for direct food manufacturer contracts while fragmented retail channels sustain multiple distributor tiers.
- Supermarkets:Volume outlet for consumer-packaged dried fruits; shelf-space negotiations favor established brands with year-round supply consistency.
- Online Retail:Direct-to-consumer growth channel for specialty and organic certifications; subscription models for single-serve formats.
- Health Food Stores:Premium positioning for sulfur-free, organic, and raw-labeled products; smaller batch requirements suit regional processors.
- Specialty Shops:Mediterranean and Middle Eastern ethnic retail channels maintaining demand for traditional fig and apricot varieties.
Supermarkets retain volume concentration; online retail is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley pioneered industrial-scale raisin production during the early twentieth century, establishing cooperative processing structures that still supply North American bakery manufacturers. Mediterranean drying traditions in Turkey and Greece later scaled into export-oriented operations serving European confectionery reformulation.
United States
California's Central Valley cooperative structure sustains year-round raisin supply to industrial bread and cereal manufacturers. FDA enforcement of Food Safety Modernization Act preventive controls shapes domestic processor compliance investments. Fresno County processing clusters anchor binding-ingredient supply for clean-label bakery contracts.
Turkey
Aegean region fig and apricot processors face tightened EFSA aflatoxin thresholds under updated EU guidance. The country's national food safety regulator aligns export certification with EU Mycotoxin Regulation 1881/2006. Aydın Province drying facilities draw capital toward optical sorting and controlled-atmosphere storage infrastructure.
Germany
Integrated extraction specialists serve beverage manufacturers seeking natural sweetness carriers for functional drink formulations. EFSA contaminant limits constrain Mediterranean-origin dried fruit import eligibility. Hamburg port logistics clusters handle mycotoxin-tested fig and apricot volumes for redistribution across European confectionery operations.
India
Domestic processors target clean-label snack bar export opportunities amid expanding global demand for sulfur-free dried apple pieces. The Production-Linked Incentive scheme for food processing infrastructure offers capital subsidy pathways. Maharashtra sorting and packaging operations scale to meet ambient-distribution cereal manufacturer specifications.
China
Domestic consumption of dried fruit inclusions climbs within bakery and confectionery manufacturing for domestic retail and export markets. SAMR food safety standards govern processing facility licensing and contaminant testing protocols. Xinjiang autonomous region drying operations concentrate on raisin and apricot volumes for Asian distribution networks.
Dried Fruit Ingredients Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity and technical service depth. Cooperative structures and integrated extraction specialists occupy distinct tiers, with family-owned processors and multinational ingredient houses competing through divergent supply chain architectures. Three archetypes dominate: cooperative aggregators with captive grower networks, integrated processors with laboratory testing infrastructure, and extraction specialists extending into beverage applications. Competitive moves concentrate on backward integration into controlled-atmosphere storage and geographic expansion toward Turkish processing clusters.
Within the cooperative-aggregator tier, Sun-Maid Growers of California exemplifies year-round supply consistency through its grower-owned structure. Among integrated processors with testing infrastructure, Mariani Packing Company occupies a position representing preservation-technology investment for industrial bakery contracts. On the extraction-specialist vector, Döhler GmbH anchors formulation partnerships extending into beverage applications through captive processing capabilities.
| Leading Market Players |
|---|
| Sun-Maid Growers of California |
| Ocean Spray Cranberries, Inc. |
| Dole plc |
| Döhler GmbH |
| Mariani Packing Company |
| ADM |
| Sunbeam Foods |
| AL FOAH |
| Traina Foods |
| Others |
Supply Flow & Price Mechanics
Optical sorting technician pools in Turkey's Aegean region anchor labor-cost differentials that widen pricing-tier spreads between commodity traders and integrated processors with captive laboratory capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic sulfur-free apricots from conventionally dried figs and bulk raisin commodities. Price differentiation rests on EFSA compliance documentation and controlled-atmosphere storage investment. Cost compression in the economy tier is intensifying because Mediterranean processors absorb optical sorting capital costs to retain EU market access. Retail private-label developers exhibit highest price sensitivity; industrial bakery manufacturers with year-round volume contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with California's Central Valley cooperative structure for raisin ingredients. Geographic supply concentration clusters in Turkey, the United States, and Greece. Raw material dependencies draw from fresh grape harvests, Mediterranean fig crops, and Pacific Northwest apple orchards. Supply chain risk centers on EFSA aflatoxin threshold enforcement that disqualifies non-compliant Mediterranean shipments. Distribution runs through integrated processors with direct food manufacturer contracts bypassing commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Mycotoxin Regulation 1881/2006 enforcement accelerates demand for documented supply chain integrity over price-based procurement.
For Market Incumbents: Deepen backward integration into controlled-atmosphere storage infrastructure to defend against Turkish processors capturing bakery contract share. Expand optical sorting capacity in Aydın Province to preempt EFSA compliance failures that would disqualify export eligibility. For New Entrants and Emerging Players: EU Mycotoxin Regulation 1881/2006 in Europe opens a window for Indian processors with PLI-subsidized sorting infrastructure to capture clean-label snack bar demand. Target sulfur-free dried apple supply to North American cereal manufacturers seeking Pacific Northwest alternatives. For Investors and Strategic Acquirers: Beverage ingredient houses are the most active acquirer in this space seeking integrated extraction capabilities. Five-to-ten year viability favors processors with captive laboratory infrastructure over commodity traders. Watch EFSA threshold revision announcements as inflection indicators for compliance investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Atmosphere Storage | Mariani Packing Company leverages preservation technology to secure industrial bakery contracts with precise moisture specifications. |
| Optical Sorting Infrastructure Deployment | Turkish processors in Aydın Province meet tightened EFSA aflatoxin limits for dried fig export eligibility into European markets. |
| Integrated Extraction Capability Expansion | Döhler GmbH anchors beverage formulation partnerships through captive processing infrastructure for natural sweetness carriers. |
| Clean-Label Certification Investment | Sulfur-free and organic credentials command premium positioning in health-focused retail channels across North America. |
| Geographic Processing Cluster Expansion | India's PLI scheme subsidizes Maharashtra sorting operations targeting ambient-distribution cereal manufacturer specifications. |
Methodological Framework
Direct dialogue with dried fruit processing plant managers, industrial bakery procurement leads, confectionery formulation scientists, and EU regulatory compliance officers grounded this analysis. Secondary validation drew from FDA FSMA guidance documents, EFSA contaminant threshold updates, EU Mycotoxin Regulation 1881/2006, and Turkish export certification records. Bottom-up volume modeling triangulated against top-down market sizing across product type and application dimensions.
Segmentation outputs reflect discrete modeling of moisture specification tiers, clean-label certification grades, and regional regulatory clusters across the analysis window. CAGRs were derived from trend extrapolation of procurement volume shifts and reformulation partnership formations. Forecast inputs incorporated EFSA enforcement intensity assumptions and PLI scheme uptake rates in Indian processing infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA threshold tightening or California drought-induced raisin supply disruption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Specialty Starch Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Cottonseed Oil Market
Ingredients
Shortening Powder Market
Ingredients
US Choline Bitartrate Market
Ingredients
North America Protein Ingredients Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Europe Corn Glucose Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Sunflower Lecithin Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Casein Hydrolysate Market
Ingredients
South America Malt Ingredient Market
Ingredients
Lupin Flour Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Non Meat Ingredients Market