
 Corn Oil Cake Market | 2026-2036
Corn Oil Cake Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Oil Cake Market Analytics
Multi-source procurement from integrated crush facilities is expanding across North American feed supply chains. Archer Daniels Midland leverages its river-terminal network to lock in origination economics for oil cake exports. Cargill sustains margin capture through backward integration into corn wet milling and downstream feed formulation. Bunge Limited competes on Gulf Coast export capacity, positioning bulk shipments for Southeast Asian aquafeed buyers.
Corn oil cake is the protein-rich residue remaining after corn germ oil extraction, typically containing 18-25% crude protein and 3-5% residual oil depending on the expeller or solvent extraction method employed. The material serves primarily as a livestock protein supplement and, in food-grade refining, as a source of zein and other corn-derived ingredients. Feed Grade output dominates volume flows, anchoring the economics of commercial crush operations, while Food Grade commands tighter specification premiums from manufacturers of corn protein isolates. Biodiesel Production as an application is gaining structural weight as renewable diesel capacity absorbs more corn oil, enlarging the cake coproduct stream.
The US EPA renewable fuel mandates and FDA feed-ingredient safety protocols jointly determine which coproduct streams qualify for food-chain or fuel-credit pathways. Brazil's ANVISA and Ministry of Agriculture regulations on feed contaminants shape import acceptance criteria for South American buyers. Stakeholders must track how biofuel policy revisions redirect corn oil volumes between edible and industrial uses, altering cake availability and pricing for protein buyers.
Market Dynamics
Renewable diesel capacity expansion is redirecting corn oil streams toward fuel-credit pathways, enlarging the protein coproduct stream available to feed formulators while compressing margins for traditional edible-oil processors.
Growth Catalysts
- US EPA Renewable Fuel Standards:Mandates redirect corn processing capacity toward biofuel coproducts, expanding feed-grade oil cake availability for protein buyers.
- Brazilian dairy sector consolidation:Large-scale operators in Minas Gerais and São Paulo states are standardizing corn oil cake in ration formulations to replace costlier soybean meal.
- Integrated crush facility economics:River-terminal processors capture margin through simultaneous oil extraction and cake pelletization, lowering unit costs for export buyers.
Market Restraints
- Input cost volatility:Corn germ supply fluctuates with ethanol plant operating rates, creating cake volume uncertainty for contract buyers.
- Supply concentration risk:Argentina's Pampas grain belt hosts disproportionate crush capacity; drought or export-tax policy shifts there transmit immediately to global cake pricing.
- Substitution threat:Distillers dried grains with solubles (DDGS) from ethanol plants compete directly as a lower-protein, higher-fiber alternative in ruminant rations.
Strategic Opportunities
- Southeast Asian aquafeed penetration:Vietnamese and Indonesian shrimp producers are testing corn oil cake as a partial fishmeal replacement in grow-out diets.
- Food-grade zein extraction:Advanced membrane filtration enables higher-value corn protein isolate production from solvent-extracted cake streams.
- EU Green Deal protein autonomy:Import substitution incentives for non-GMO feed ingredients create entry pathways for certified-origin South American suppliers.
Industry Challenges
- Myotoxin certification complexity:FDA and ANVISA maximum residue limits for aflatoxin and fumonisin require batch testing protocols that extend delivery timelines.
- Legacy equipment retrofit costs:Expeller-press facilities face capital outlays to install solvent extraction capacity needed for food-grade specification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Oil Cake Market |
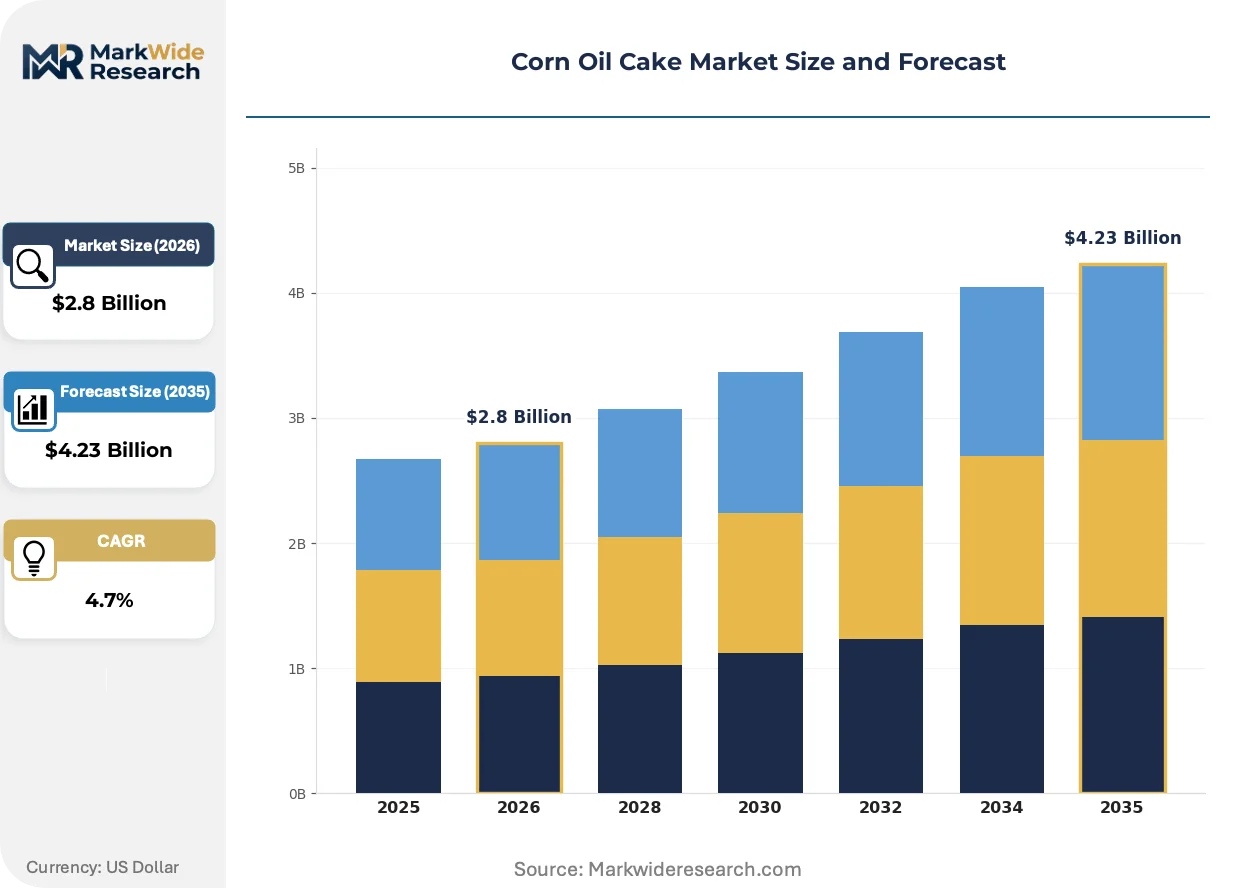
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Grade, Food Grade, Industrial Grade, Cosmetic Grade Application: Animal Feed, Food Processing, Biodiesel Production, Fertilizer End User: Dairy Farms, Poultry Farms, Food Manufacturers, Biofuel Producers Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Louis Dreyfus Company, Wilmar International Limited, Archer Daniels Midland Company, Ingredion Incorporated, Grain Processing Corporation, Cargill, COFCO, Richardson International, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Oil Cake Market Evolving Landscape
Processing technology convergence and procurement model evolution are compressing traditional supply chain tiers, enabling direct origination contracts between crush facilities and large-scale feed operators.
Membrane filtration systems for zein recovery are consolidating the food-grade segment around solvent-extraction processors with capital to install downstream protein isolation equipment. Specialty ingredient manufacturers in the US Corn Belt and Netherlands are contracting directly with these facilities, bypassing commodity traders. This technology is consolidating margin capture in the hands of integrated operators while marginalizing standalone expeller-press competitors.
REACH registration requirements for novel feed additives in the European Union are tightening import documentation for corn-derived protein concentrates. Batch-specific contaminant testing and chain-of-custody certification now accompany commercial shipments to Dutch and German compounders. The specialty feed premix segment is absorbing these compliance costs through formula premiums, while commodity bulk buyers face exclusion from premium supply chains.
Direct origination contracting is displacing spot-market procurement among North American dairy cooperatives and integrated poultry operators. These buyers are locking in multi-quarter cake volumes through prepayment structures with river-terminal crush facilities, securing supply against germ-oil competition from renewable diesel producers. The upper Midwest dairy corridor exhibits the most advanced adoption of this procurement model.
Corn Oil Cake Market Segmentation
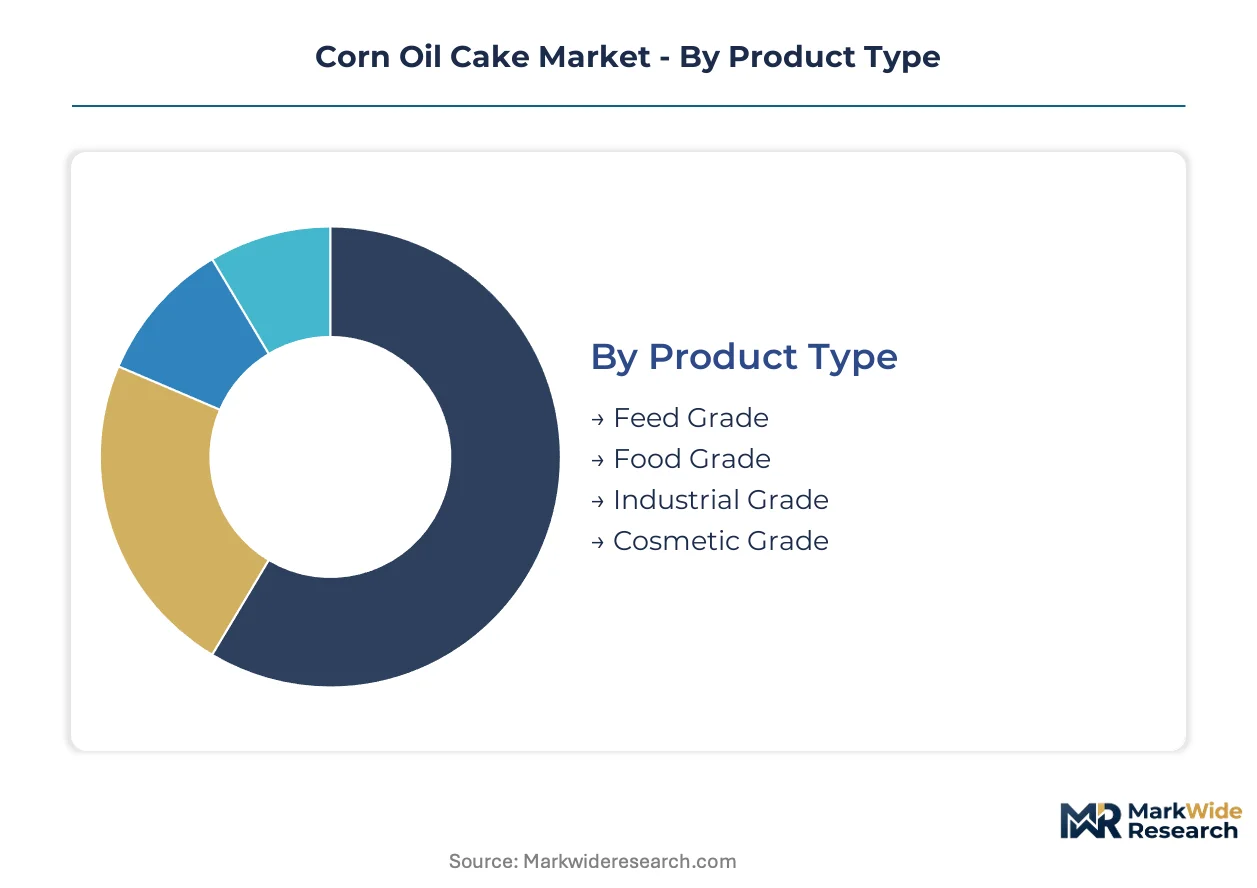
Corn oil cake segmentation reflects divergent regulatory pathways and margin structures across the value chain. Certification requirements from FDA, ANVISA, and EPA determine which processing streams qualify for food-chain, feed-chain, or fuel-credit applications.
Product Type:
FDA and ANVISA certification burdens vary sharply across grades, with food-grade and cosmetic-grade segments facing mycotoxin testing protocols that feed-grade processors bypass.
- Feed Grade:Contains 18-25% crude protein and 3-5% residual oil depending on extraction method. Dairy farms in Brazil's Minas Gerais state are standardizing this grade to replace costlier soybean meal, while EPA renewable fuel standards enlarge coproduct availability.
- Food Grade:Solvent-extracted material meeting FDA specifications for zein and protein isolate recovery. Specialty ingredient manufacturers in the US Corn Belt and Netherlands contract directly with crush facilities, bypassing commodity traders.
- Industrial Grade:Intermediate specification for non-food chemical applications with relaxed contaminant thresholds.
- Cosmetic Grade:Refined streams for personal care formulations requiring batch-specific chain-of-custody documentation.
Leading the category by volume: Feed Grade. Expanding most quickly: Food Grade.
Application:
Application segments split along protein recovery economics versus fuel-credit arbitrage, with biodiesel coproduct flows now competing against traditional feed formulations.
- Animal Feed:Dominates volume flows as the anchor application for commercial crush operations. River-terminal processors in Argentina's Pampas grain belt supply both domestic ranchers and export buyers through integrated pelletization.
- Biodiesel Production:Renewable diesel capacity expansion redirects corn oil streams toward fuel-credit pathways, enlarging the protein coproduct stream available to feed formulators while compressing margins for edible-oil processors.
- Food Processing:Zein extraction and corn protein isolate production serve manufacturers of specialty ingredients.
- Fertilizer:Residual cake streams enter organic soil amendment markets with lower specification barriers.
Commanding highest volume: Animal Feed. Gaining share fastest: Biodiesel Production.
End User:
End-user concentration tracks livestock sector consolidation and biofuel policy implementation across major producing regions.
- Dairy Farms:Large-scale operators in Brazil's São Paulo state are locking in multi-quarter volumes through prepayment structures with crush facilities.
- Poultry Farms:Integrated operators in the US upper Midwest exhibit advanced adoption of direct origination contracting.
- Food Manufacturers:Specialty compounders in the Netherlands and Germany absorb REACH compliance costs through formula premiums.
- Biofuel Producers:Renewable diesel facilities compete for corn germ supply against traditional edible-oil processors.
Steepest volume concentration: Dairy Farms. Fastest procurement-model evolution: Poultry Farms.
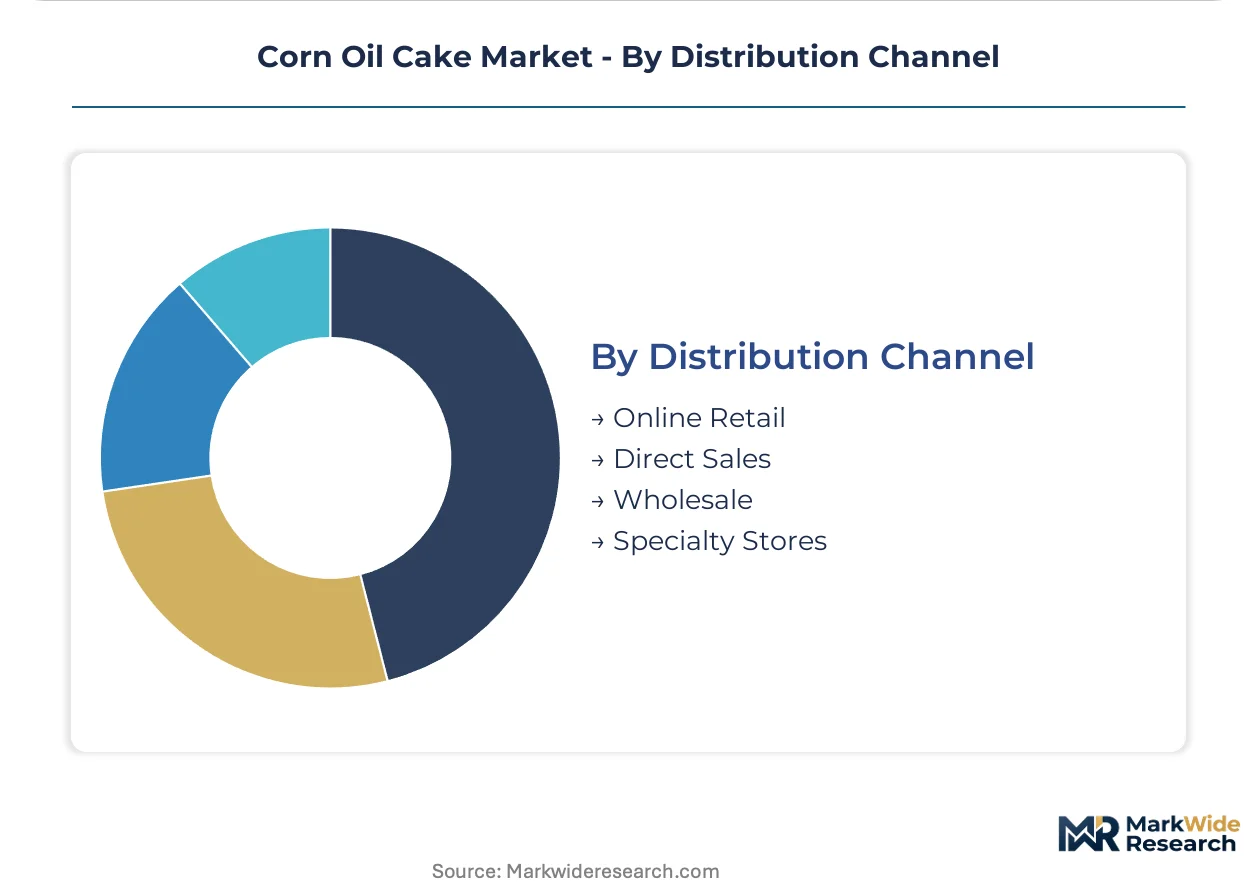
Distribution Channel:
Channel structure reflects compression of traditional supply chain tiers as large-scale buyers bypass intermediaries.
- Direct Sales:Multi-quarter prepayment contracts between crush facilities and North American dairy cooperatives displace spot-market procurement.
- Wholesale:Bulk shipments through Gulf Coast export terminals serve Southeast Asian aquafeed buyers.
- Online Retail:Emerging channel for specialty-grade small-lot purchases with documentation requirements.
- Specialty Stores:Niche outlet for certified-origin non-GMO supply chains targeting EU Green Deal protein autonomy incentives.
Capturing dominant share: Direct Sales. Most rapid structural shift: Wholesale export logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's Pampas grain belt anchors global corn oil cake supply, with integrated crush facilities processing domestic germ supply and export-bound coproduct streams. Regional dynamics diverge sharply between biofuel policy environments and livestock sector consolidation patterns.
United States
EPA renewable fuel standards redirect corn processing capacity toward biodiesel coproducts, expanding feed-grade oil cake availability for domestic protein buyers. FDA feed-ingredient safety protocols determine which streams qualify for food-chain versus fuel-credit pathways. River-terminal processors in Illinois and Iowa capture origination economics through simultaneous oil extraction and cake pelletization.
Brazil
Large-scale dairy operators in Minas Gerais and São Paulo states standardize corn oil cake in ration formulations to replace costlier soybean meal. ANVISA and the Ministry of Agriculture impose strict feed contaminant limits that shape import acceptance criteria for regional buyers. Integrated crush facilities in the Center-West grain belt supply both domestic ranchers and export markets.
Argentina
Export-tax policy shifts and drought risk in the Pampas region transmit immediately to global cake pricing through concentrated crush capacity. The national agricultural regulator oversees mycotoxin certification requirements for shipments bound for European and Asian markets. Rosario and Buenos Aires province host the dominant share of solvent-extraction infrastructure serving international buyers.
China
Dual carbon goals and renewable energy targets redirect corn oil streams toward biofuel applications, enlarging protein coproduct volumes for domestic feed compounders. SAMR and GB standards govern feed safety and processing specifications for industrial-scale operations. Shandong Peninsula processors balance edible-oil demand against fuel-credit arbitrage opportunities.
Netherlands
EU Green Deal protein autonomy incentives create entry pathways for certified-origin South American suppliers meeting non-GMO feed specifications. REACH registration requirements tighten import documentation for corn-derived protein concentrates bound for Dutch compounders. Rotterdam and Amsterdam terminals serve as distribution hubs for specialty-grade shipments to German and Belgian feed manufacturers.
Corn Oil Cake Market Competitive Landscape
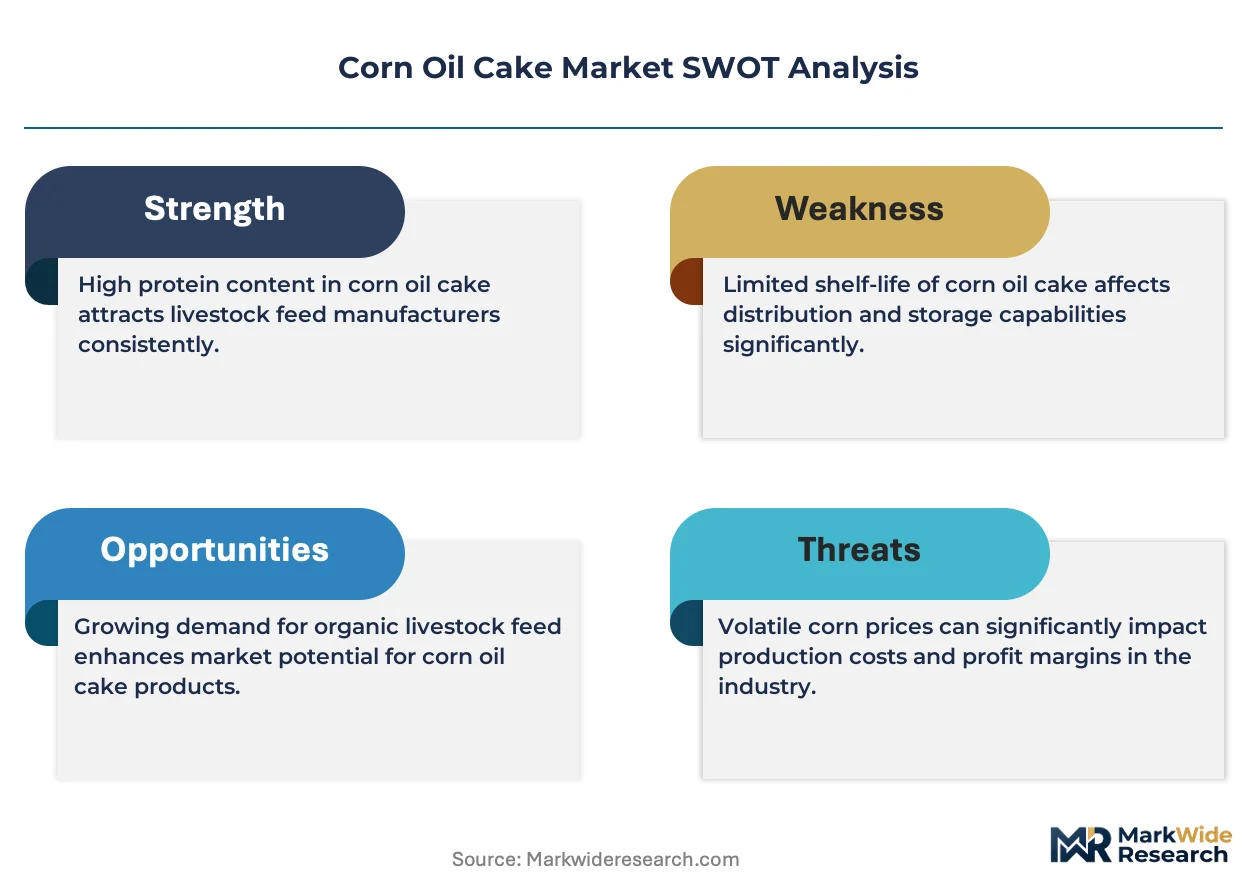
Global majors compete with regional champions across origination networks and crush facility economics. The vendor base clusters around three tiers: integrated agribusiness conglomerates with river-terminal assets, national oilseed processors with captive germ supply, and specialty ingredient manufacturers with downstream protein isolation capabilities. Dominant competitive moves include backward integration into corn wet milling and direct origination contracting that displaces traditional commodity trading tiers.
Within the integrated agribusiness tier, Archer Daniels Midland Company and Cargill exemplify the capital-intensive model of simultaneous oil extraction, cake pelletization, and export logistics control. Bunge Limited occupies a position anchored in Gulf Coast terminal capacity and bulk shipment expertise for Southeast Asian aquafeed buyers. Wilmar International Limited represents the Asia-Pacific regional champion archetype with origination leverage in palm and oilseed processing that extends to corn coproduct streams.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| Wilmar International Limited |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Grain Processing Corporation |
| Cargill |
| COFCO |
| Richardson International |
| Bunge Limited |
| Others |
Value Network & Pricing Analysis
Large-scale dairy cooperatives in Brazil's Minas Gerais state anchor pricing power through multi-quarter prepayment contracts, locking in feed-grade volumes directly with Center-West crush facilities and compressing spot-market liquidity for smaller buyers.
Pricing Analysis
Certification-bundled pricing separates food-grade zein-extracted streams from unbundled feed-grade bulk sales. Three-tier pricing structure across premium solvent-extracted, standard expeller-pressed, and economy-grade residual tiers reflects FDA and ANVISA mycotoxin testing burdens. Pricing pressure stems from renewable diesel facilities bidding up corn germ supply against edible-oil processors. Smallholder ranchers exhibit highest price sensitivity, while Netherlands specialty compounders absorb REACH compliance premiums.
Supply Chain Analysis
Direct-to-feedmill channels handle North American dairy cooperative demand, while wholesale export terminals serve Vietnamese and Indonesian aquafeed buyers. Argentina, Brazil, and the United States concentrate solvent-extraction infrastructure. Supply draws from corn germ coproduct streams tethered to ethanol plant operating rates and renewable diesel capacity. Single-source vulnerability runs through Argentina's Pampas grain belt, where drought or export-tax shifts transmit immediately to global cake availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corn oil cake supply is consolidating around integrated crush operators with captive origination networks, as capital requirements for solvent-extraction retrofit and mycotoxin certification infrastructure force standalone expeller-press facilities toward exit.
For Market Incumbents: Anticipate margin compression from renewable diesel germ-oil competition by deepening backward integration into corn wet milling and securing river-terminal pelletization capacity. Lock in multi-quarter prepayment structures with upper Midwest poultry integrators before DDGS substitution intensifies. Prioritize ANVISA batch-testing protocol investments to defend Brazilian dairy supply relationships against Argentine export rivals. For New Entrants and Emerging Players: Specialty feed premix distributors in the Netherlands and Germany offer the most penetrable channel entry, as REACH documentation requirements exclude commodity bulk traders from premium supply chains. Target EU Green Deal protein autonomy incentives with certified-origin non-GMO supply from South American partner crush facilities. Lead with chain-of-custody certification services rather than volume commodity plays. For Investors and Strategic Acquirers: The window for entry favors solvent-extraction assets with downstream membrane filtration capability for zein recovery. Mid-cap processors in Argentina's Rosario corridor with underutilized food-grade capacity represent prime consolidation targets. Watch EPA renewable fuel mandate revisions as the critical signal for germ-oil arbitrage direction and coproduct cake availability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet Milling | Captures origination economics and secures germ supply against renewable diesel competition. |
| Solvent Extraction Capacity Retrofit | Enables FDA food-grade compliance and zein recovery premiums from membrane filtration systems. |
| Direct Origination Contracting | Displaces commodity traders by locking multi-quarter volumes with prepayment structures. |
| REACH Registration Investment | Opens EU specialty feed premix channels that exclude uncertified bulk competitors. |
| River-Terminal Export Logistics Expansion | Positions bulk pelletized shipments for Southeast Asian aquafeed buyers through Gulf Coast capacity. |
Research Methodology
USDA crop production reports, EPA renewable fuel standard filings, and ANVISA feed safety registrations formed the secondary backbone, cross-referenced with primary interviews involving crush facility operations managers, Brazilian dairy nutritionists, Dutch compounder procurement leads, and Argentine export terminal logistics coordinators. Bottom-up volume estimates from individual processing facility throughput combined with top-down corn germ supply modeling to triangulate market sizing.
Bottom-up segmentation modeling tracked product grade, extraction method, and end-use application across the projection horizon. The analytical framework incorporated corn oil arbitrage between edible and fuel-credit pathways, livestock sector consolidation patterns, and regulatory certification tiering. CAGRs derived from facility capacity expansion pipelines and policy-driven coproduct flow redirection. Forecast inputs included EPA mandate revision scenarios and EU protein autonomy incentive uptake curves.
Several conditions sit outside the modeled scope, including extreme weather events disrupting Argentina's Pampas crush concentration, abrupt biofuel policy reversals redirecting germ-oil streams, and trade barrier escalations affecting Southeast Asian aquafeed import channels. Forecasts reflect assumptions about renewable diesel capacity commissioning timelines and mycotoxin testing protocol harmonization across FDA and ANVISA jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oak Chips White Extract Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Omega-3 Encapsulation Market
Ingredients
Farnesene Market
Ingredients
Global Egg White Peptide Market
Ingredients
Polydextrose Ingredients Market
Ingredients
Sodium Caseinate Market
Ingredients
Millet Protein Market
Ingredients
Eucalyptus Oil Market
Ingredients
Europe Gelatin Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Global Yeast Market
Ingredients
Kairomones Market
Ingredients
Bleached Flour Market
Ingredients
Cosmetic Ingredients Market