
 Shortening Fats Market | 2026-2036
Shortening Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Shortening Fats Market Analysis
Foodservice distribution is fragmenting as regional bakery cooperatives and industrial commissaries bypass traditional ingredient wholesalers. Cargill Incorporated leverages its North American oilseed crushing network to secure captive supply of refined vegetable oils for shortening production. Wilmar International Limited dominates Southeast Asian palm oil origination, anchoring cost positions across solid fat formulations. Fuji Oil Asia Pte. Ltd. specializes in tailored shortening blends for Japanese and Korean confectionery manufacturers.
Shortening fats are semi-solid or solid lipid preparations, typically manufactured through hydrogenation, interesterification, or fractionation of vegetable or animal oils, designed to impart plasticity, aeration, and shelf stability to baked goods and fried products. The ingredient source dimension shows vegetable-derived shortenings leading volume as bakery chains reject partially hydrogenated oils under trans-fat regulations, while solid fats command premium positioning in laminated dough applications where precise melting profiles determine product quality. Liquid fats and shortening blends are gaining fastest in artisanal and clean-label segments where processors seek pourable alternatives with reduced saturated fat content.
The FDA enforces updated restrictions on partially hydrogenated oils under its food additive regulations, compelling reformulation across US-manufactured shortenings, while the EU's REACH framework and F-Gas Regulation constrain solvent-based processing aids used in European fat modification plants. BIS standards in India and EFSA novel food assessments for emerging lipid technologies add compliance layers for cross-border suppliers. Stakeholders must monitor regulatory divergence between trans-fat limits and carbon accounting rules to align R&D pipelines with divergent regional approval pathways.
Market Dynamics
The trans-fat labeling tightening across Southeast Asian markets is forcing industrial bakers to abandon partially hydrogenated oils, triggering wholesale reformulation of shortening fat portfolios and reshaping supplier relationships.
Growth Catalysts
- Indonesia's expanding bakery cooperative network:Regional procurement consortia are consolidating orders for palm-based shortening blends, creating volume anchors that attract specialized fat processors.
- FDA's updated PHO restrictions:US food additive regulations now prohibit residual partially hydrogenated oils, compelling exporters to certify reformulated shortenings for cross-border trade.
- Interesterification technology maturation:Enzymatic fat modification processes enable precise control over solid fat content without hydrogenation, meeting clean-label demands from artisanal bread producers.
Market Restraints
- Palm oil price volatility:Crude palm oil futures on Bursa Malaysia Derivatives exchange swing with El Niño patterns, compressing margins for shortening manufacturers locked into annual supply contracts.
- Malaysian-Indonesian supply concentration:Over 85% of global palm oil origination sits with Southeast Asian plantation conglomerates, creating origination risk for buyers seeking supply diversification.
- Technical limitation in laminated dough applications:Liquid shortening alternatives lack the plasticity range required for croissant and puff pastry lamination, preserving demand for solid fats with higher saturated fat profiles.
Strategic Opportunities
- India's industrial bakery commissary expansion:Quick-service restaurant chains and cloud kitchen aggregators are building centralized production facilities in Mumbai and Bangalore, creating demand for bulk shortening with extended fry stability.
- EU F-Gas Regulation phase-down:Solvent-based fractionation plants face refrigerant constraints, creating openings for supercritical CO2 processing equipment suppliers to retrofit European fat modification facilities.
- Fractionation-interesterification convergence:Combining palm mid-fraction isolation with enzymatic rearrangement enables tailored melting curves for confectionery coatings, opening premium positioning in Japanese chocolate manufacturing.
Industry Challenges
- Lipid chemistry specialization shortage:Industrial fat technologists with expertise in crystallization kinetics and polymorphism control are scarce, delaying R&D timelines for multinational shortening developers.
- Dual certification burden:Exporters must simultaneously satisfy India's BIS standards for trans-fat labeling and EU REACH documentation for processing aids, extending product registration cycles.
- Legacy hydrogenation asset stranding:Plants with sunk capital in catalytic hydrogenation infrastructure face write-down pressure as interesterification capacity expands, complicating capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shortening Fats Market |
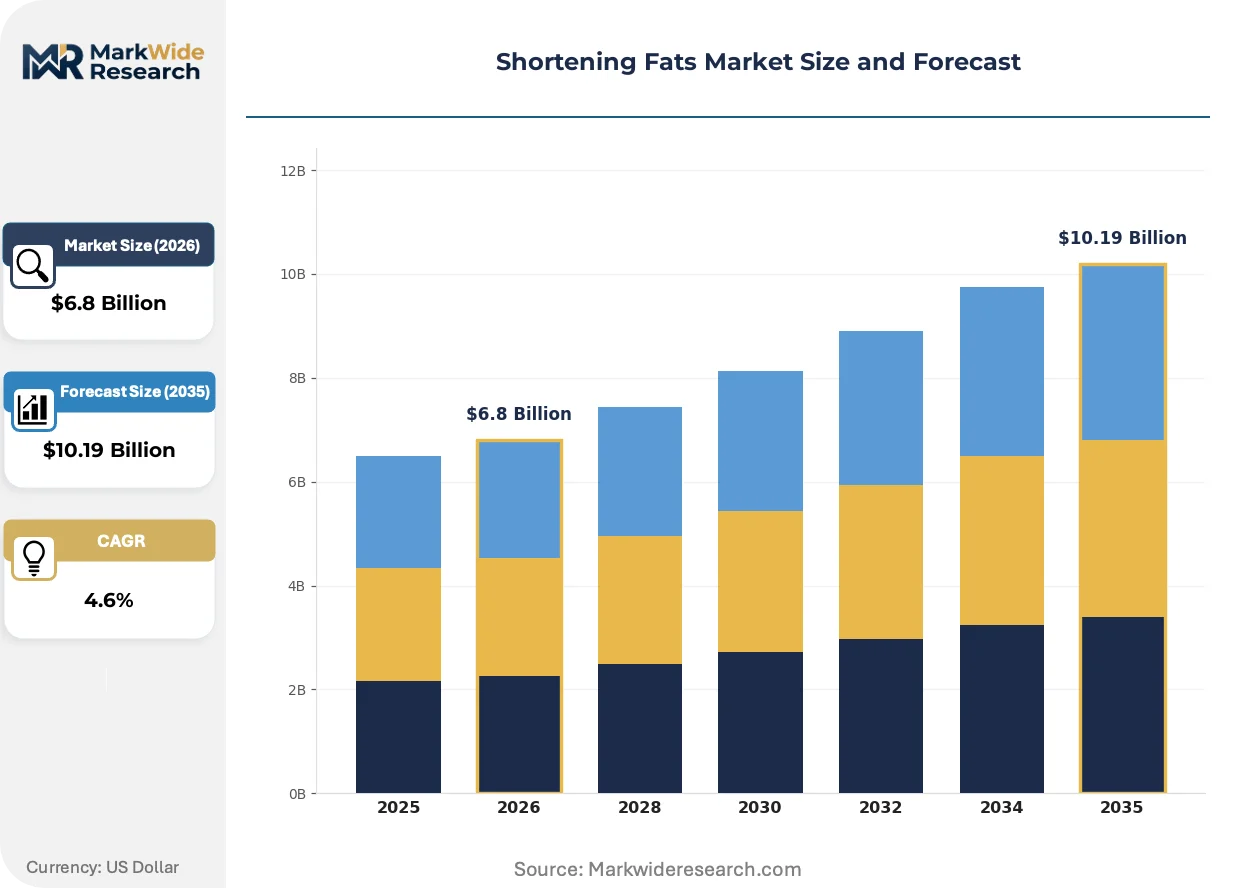
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Fats, Liquid Fats, Aerosol, Shortening Blends End Use: Baking, Confectionery, Snacks, Culinary Packaging Type: Bulk Packaging, Retail Packaging, Jar, Pouch Ingredient Source: Vegetable, Animal, Synthetic, Others |
| Companies Covered | AAK AB, Fuji Oil Asia Pte. Ltd., Cargill Incorporated, Unilever, COFCO Group Co. Ltd., Bunge Global SA, Archer Daniels Midland Company, Conagra Foodservice, Inc., Wilmar International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shortening Fats Market Emerging Trajectories
Digital formulation platforms and enzymatic processing advances are compressing development cycles for shortening fats, while regulatory divergence between trans-fat limits and carbon accounting rules forces parallel R&D tracks.
Enzymatic interesterification is virtualizing the shortening development process. This biocatalytic approach rearranges fatty acid positions on glycerol backbones without creating trans isomers. Industrial bakeries in Thailand and Vietnam are adopting enzyme-modified palm fractions at accelerating rates. The technology is virtualizing traditional pilot-scale testing by enabling computational prediction of solid fat content curves from molecular structure inputs.
REACH compliance documentation requirements are expanding scope for European fat modification plants. ECHA's updated substance registration obligations now capture novel emulsifier carriers used in shortening blends. German and Dutch processors face extended dossier preparation timelines. Specialty shortening exporters to the EU are consolidating formulation platforms to minimize registration burden.
Foodservice procurement consolidation is concentrating buyer power in Southeast Asian markets. Regional bakery cooperatives in the Philippines and Indonesia now negotiate directly with Malaysian palm oil refiners, bypassing traditional ingredient distributors. This channel compression is most visible in Jakarta and Manila, where industrial commissaries for quick-service chains source shortening in 20-tonne minimum orders.
Shortening Fats Market Segmentation
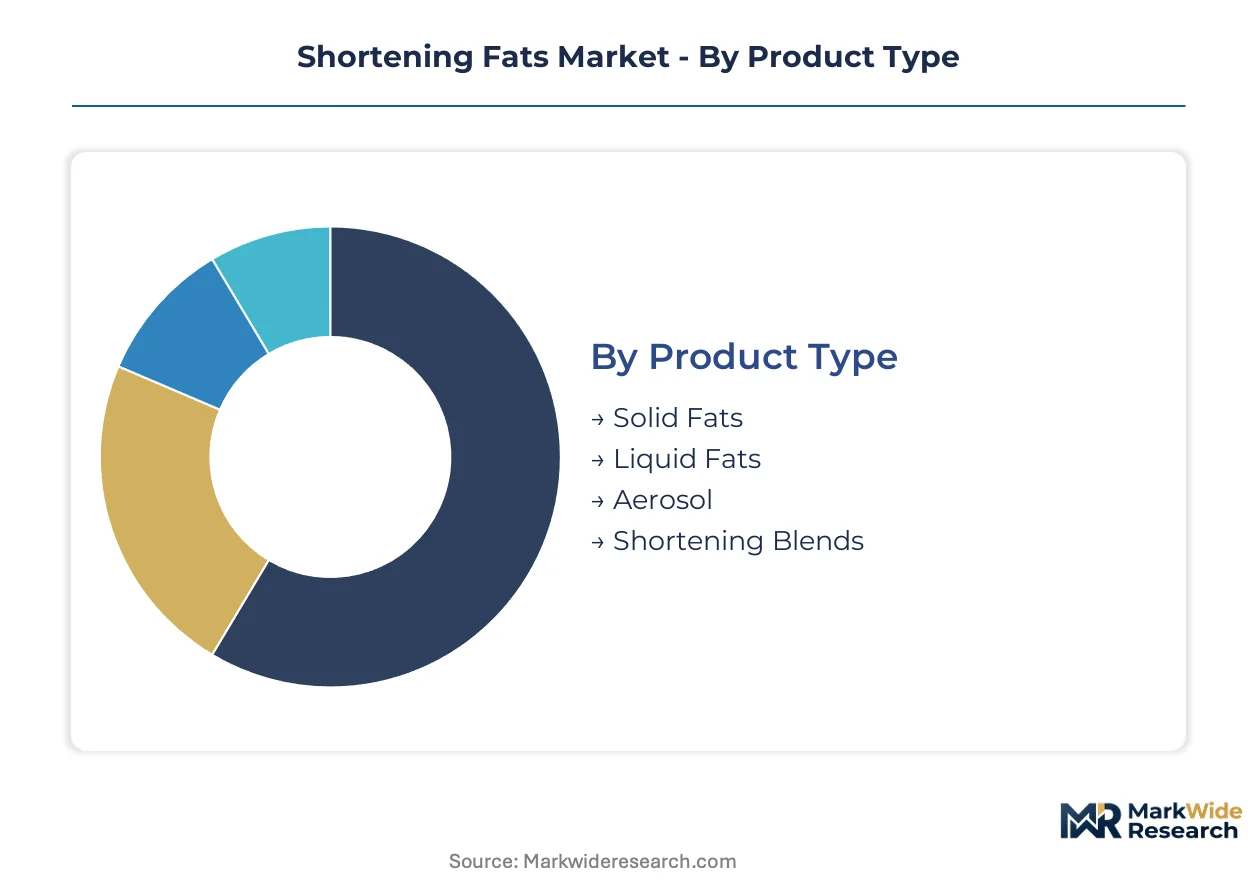
Shortening fat formulations diverge sharply across temperature stability requirements and processing constraints. Each segment carries distinct regulatory exposure and supply chain dependencies that reshape procurement strategies for industrial bakers.
Product Type:
The use-case spectrum spans from high-plasticity laminating fats to pourable alternatives for clean-label positioning.
- Solid Fats:Hydrogenated or fractionated vegetable oils with controlled polymorphism deliver precise melting profiles for croissant lamination and puff pastry layering. Southeast Asian bakery chains in Jakarta and Manila prioritize these for consistent dough handling despite trans-fat reformulation pressures.
- Liquid Fats:Non-hydrogenated vegetable oils with modified crystallization behavior pour at ambient temperatures. Artisanal bread producers in Vietnam and Thailand are adopting these for reduced saturated fat claims, though fry stability limitations constrain quick-service applications.
- Aerosol:Propellant-dispensed shortening sprays target home baking and small-scale foodservice operations with portion control convenience.
- Shortening Blends:Interesterified palm fractions combined with liquid oils balance plasticity and pourability for multi-use industrial kitchens.
The dominant share belongs to Solid Fats, while Liquid Fats is closing the gap fastest.
End Use:
Cost tier differentiation separates commodity volume plays from premium formulation services.
- Baking:Industrial bread, cake, and pastry production consumes the largest volume of shortening fats, with laminated dough applications requiring precise solid fat content curves that only fractionated palm mid-fractions currently satisfy.
- Confectionery:Chocolate coatings and praline fillings demand tailored melting behavior with sharp contraction properties. Japanese and Korean manufacturers specify enzymatically interesterified shortenings for snap and gloss control.
- Snacks:Extended fry stability requirements drive demand for high-oleic base stocks in potato chip and extruded snack production across Indonesian and Malaysian processing plants.
- Culinary:Restaurant and foodservice pan-frying applications favor all-purpose shortenings with neutral flavor profiles and high smoke points.
Baking commands the volume base, though Confectionery generates the steepest margin expansion.
Packaging Type:
Customer type fragmentation splits procurement between centralized industrial commissaries and fragmented retail channels.
- Bulk Packaging:Tanker and drum deliveries serve industrial bakery commissaries in Mumbai and Bangalore with 20-tonne minimum orders, bypassing traditional distributors.
- Retail Packaging:Consumer-facing cartons and tubs target home bakers through supermarket chains, with labeling compliance varying by destination market.
- Jar:Premium positioning for specialty shortenings with added emulsifiers or flavor compounds.
- Pouch:Flexible packaging for foodservice portion packs and institutional catering operations.
Bulk Packaging anchors industrial procurement, while Pouch formats are expanding most quickly in cloud kitchen supply chains.
Ingredient Source:
Supply concentration risk concentrates origination decisions for multinational shortening developers.
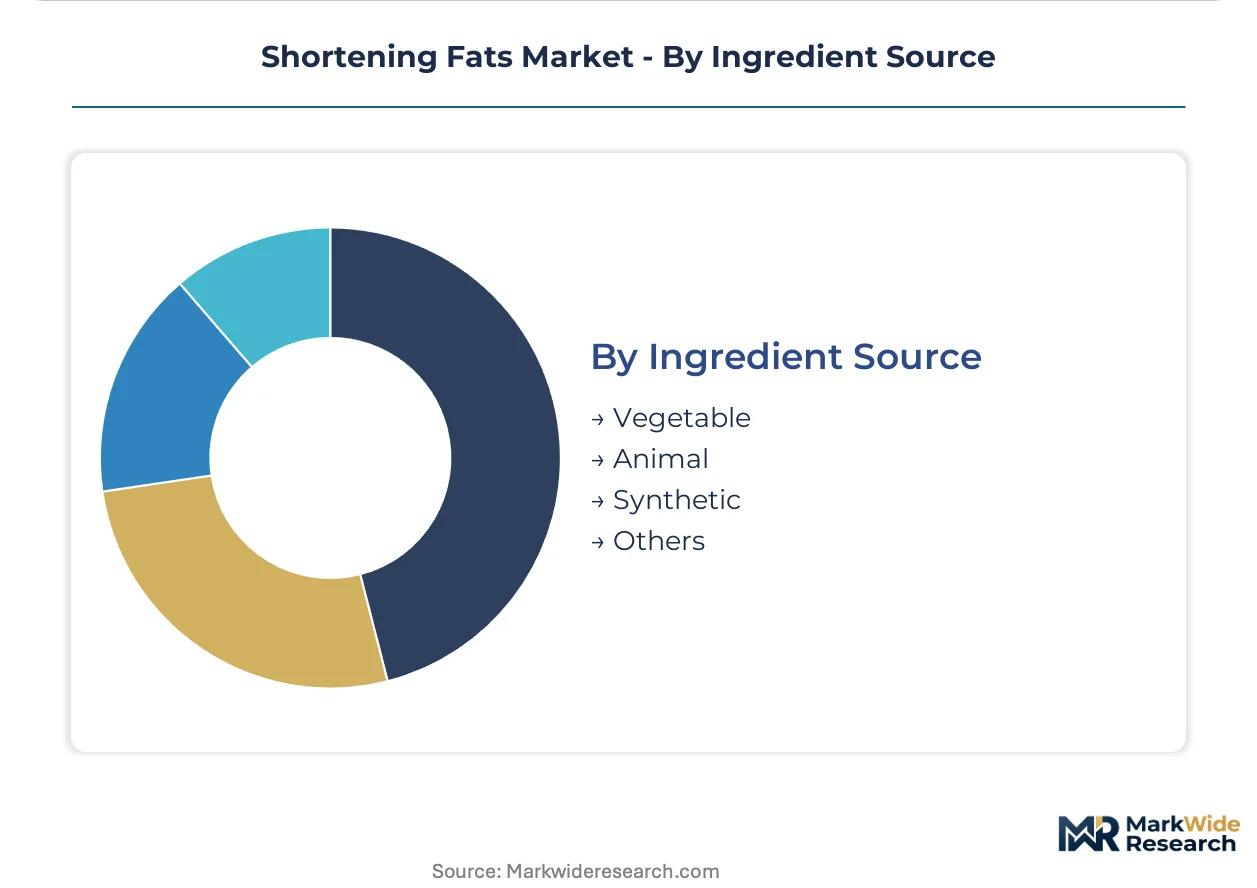
- Vegetable:Palm, soybean, and sunflower oil derivatives dominate volume as bakery chains reject partially hydrogenated alternatives. Malaysian and Indonesian plantation conglomerates control over 85% of global palm oil origination, embedding geographic concentration risk.
- Animal:Tallow and lard-based shortenings retain niche demand for traditional pie crust applications and specific religious dietary certifications.
- Synthetic:Structurally modified lipids and novel fat mimetics face extended EFSA novel food assessment timelines in Europe.
- Others:Emerging microbial and algae-derived lipid technologies occupy pre-commercial development phases.
Vegetable sources hold absolute volume dominance, with Synthetic alternatives facing the steepest regulatory climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palm oil origination in Indonesia and Malaysia commands pricing leverage over European confectionery buyers, while US bakery chains absorb reformulation costs under tighter FDA enforcement. This asymmetry reshapes procurement geography for shortening fat suppliers.
United States
Industrial bakery commissaries in Chicago and Dallas are accelerating interesterified shortening adoption ahead of FDA compliance deadlines. The agency's updated PHO restrictions now prohibit residual partially hydrogenated oils in cross-border shipments. Cargill's North American oilseed crushing network anchors captive supply for domestic shortening production.
Indonesia
Bakery cooperatives in Jakarta and Surabaya are consolidating 20-tonne procurement orders for palm-based shortening blends. BIS-equivalent trans-fat labeling standards are tightening through the national standards body. Wilmar International's plantation-to-refinery infrastructure dominates origination across Sumatran processing clusters.
Malaysia
Fractionation plants in Port Klang and Pasir Gudang face margin compression from crude palm oil volatility on Bursa Malaysia Derivatives. The country's sustainable palm oil certification programs are expanding documentation requirements for export-bound shortenings. Peninsular Malaysian refiners supply enzymatically modified fats to Japanese confectionery manufacturers.
India
Quick-service restaurant chains and cloud kitchen aggregators are building centralized production facilities in Mumbai and Bangalore. FSSAI trans-fat limits and BIS labeling standards are compelling reformulation of traditional vanaspati shortenings. Industrial commissaries in Maharashtra and Karnataka now source bulk vegetable-derived solid fats with extended fry stability.
Germany
Specialty fat processors in Hamburg and Frankfurt am Main face extended REACH dossier timelines for novel emulsifier carriers. ECHA's updated substance registration obligations are constraining formulation flexibility for shortening blends. German confectionery manufacturers specify enzymatically interesterified palm fractions for chocolate coating applications.
Shortening Fats Market Vendor Landscape
Integrated plantation-refinery conglomerates and specialized lipid technology firms split the market into distinct capability tiers. The vendor base concentrates around Southeast Asian palm oil origination and North American oilseed processing. Two strategic archetypes dominate: captive supply chain operators controlling upstream feedstock, and formulation specialists delivering tailored melting profiles. Competitive moves center on enzymatic processing capacity expansion and direct procurement relationships with industrial bakery cooperatives.
Among integrated supply chain operators, Wilmar International Limited and Cargill Incorporated exemplify the captive origination model, securing cost positions through plantation and crushing infrastructure. Fuji Oil Asia Pte. Ltd. occupies a position within the formulation-specialist tier, serving confectionery manufacturers with customized shortening blends. These three companies represent the competitive spectrum from upstream control to downstream application engineering.
| Leading Market Players |
|---|
| AAK AB |
| Fuji Oil Asia Pte. Ltd. |
| Cargill Incorporated |
| Unilever |
| COFCO Group Co. Ltd. |
| Bunge Global SA |
| Archer Daniels Midland Company |
| Conagra Foodservice, Inc. |
| Wilmar International Limited |
| Others |
Supply Flow & Price Mechanics
The Strait of Malacca shipping corridor carries over 80% of global palm oil seaborne trade, and its freight rate volatility feeds directly into both Malaysian refinery cost positions and the premium spreads that European confectionery buyers pay for enzymatically modified shortening fractions.
Pricing Analysis
The customization-premium spread separates standard palm mid-fraction deliveries from configured-to-order enzymatic interesterification runs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard-grade shortenings is intensifying because Indonesian bakery cooperatives consolidate procurement into 20-tonne minimum orders. Quick-service restaurant chains in India exhibit highest price sensitivity, while Japanese confectionery manufacturers accept premium positioning for tailored melting curve specifications.
Supply Chain Analysis
Upstream feedstock origination draws from Indonesian and Malaysian plantation conglomerates controlling over 85% of global palm oil supply. Crude palm oil futures on Bursa Malaysia Derivatives, refined vegetable oil inputs from North American oilseed crushing, and enzymatic processing catalysts constitute critical dependencies. Single-source vulnerability concentrates in Sumatran processing clusters exposed to El Niño-driven harvest volatility. Distribution runs through direct procurement relationships between regional bakery cooperatives and refinery operators, bypassing traditional ingredient wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortening fats sit in early-cycle expansion as trans-fat labeling mandates across Southeast Asia force wholesale reformulation of industrial bakery portfolios, accelerating adoption of enzymatic interesterification technology.
For Market Incumbents: Insulate margin positions by securing captive palm oil origination through backward integration into Indonesian plantation assets or long-term offtake agreements with Malaysian refinery clusters. Expand enzymatic processing capacity in Peninsular Malaysia to serve Japanese confectionery demand for tailored melting profiles. The threat of liquid shortening alternatives in artisanal segments demands crystallization kinetics R&D investment to preserve laminated dough application dominance.
For New Entrants and Emerging Players: India's industrial bakery commissary buildout in Mumbai and Bangalore offers the most penetrable white-space, with cloud kitchen aggregators sourcing bulk shortening for extended fry stability. Target enzymatic interesterification service provision to mid-tier regional bakery cooperatives lacking in-house lipid chemistry expertise. A technical sales model embedding formulation scientists with industrial commissary procurement teams accelerates trial-to-contract conversion.
For Investors and Strategic Acquirers: FDA's updated PHO restrictions reshape the acquisition landscape by stranding legacy hydrogenation assets and privileging enzymatic processing capability. The 5-10 year viability window favors targets with established Southeast Asian palm oil origination relationships and clean-label certification portfolios. Monitor BIS and FSSAI trans-fat enforcement timelines in India as inflection indicators for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Enables trans-fat-free reformulation for FDA and EU REACH compliance without hydrogenation. |
| Backward Integration into Plantation Assets | Secures cost position against Bursa Malaysia Derivatives volatility for Indonesian refinery operations. |
| Direct Procurement Relationship Development | Bypasses traditional distributors to capture Jakarta and Manila bakery cooperative volume consolidation. |
| Clean-Label Certification Investment | Opens premium positioning in Japanese and Korean confectionery coating applications. |
| Supercritical CO2 Processing Retrofit | Addresses EU F-Gas Regulation constraints on solvent-based fractionation plants in German and Dutch facilities. |
Methodological Framework
A standing panel of lipid technology directors, industrial bakery procurement managers, palm oil refinery operations heads, and enzymatic processing equipment specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from Bursa Malaysia Derivatives trading data, FDA food additive regulation filings, ECHA REACH substance registration databases, and FSSAI trans-fat labeling standards. Bottom-up volume modeling from individual refinery capacity and top-down demand triangulation from end-use consumption patterns converged on segment-level outputs.
Scenario-bracketing framed analytical approach across the analysis window, with base, upside, and downside cases reflecting regulatory enforcement timing and palm oil price trajectory assumptions. Segmentation dimensions modeled included product type (solid fats, liquid fats, shortening blends), ingredient source (vegetable, animal, synthetic), end-use application (baking, confectionery, snacks), and regional regulatory cluster (FDA-governed, EU REACH-governed, BIS/FSSAI-governed). CAGRs derived from fitted growth curves anchored to documented capacity expansion announcements and procurement contract visibility. Industry-specific forecast inputs incorporated enzymatic interesterification adoption rates and cloud kitchen commissary buildout pipelines.
Practitioners should monitor El Niño pattern developments, EU F-Gas Regulation phase-down enforcement, and Indian trans-fat labeling implementation timelines for early signals requiring forecast revision. Cross-checking against Bursa Malaysia Derivatives crude palm oil futures curves and regional bakery cooperative procurement auction results is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pet Food Premix Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Seaweed Derivatives Market
Ingredients
Liquid Feed Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Smoked Yeast Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Agar Market
Ingredients
Non-GMO Soya Market
Ingredients
Beetroot Powder Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Chickpea Protein Market