
 Middle East Feed Palatability Enhancers Market | 2026-2036
Middle East Feed Palatability Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Feed Palatability Enhancers Market Foresight
Asset-light toll manufacturing and third-party flavor compounding arrangements is narrowing the capital barrier for regional entrants to challenge established suppliers. Cargill Inc. leverages its integrated grain-to-feed infrastructure across Saudi Arabia and the UAE to secure captive offtake for its palatability portfolios. Kerry Group Plc sustains formulation leadership through dedicated savory science facilities serving Middle Eastern taste profiles. DSM-Firmenich anchors its position with precision-delivery yeast extract technologies optimized for arid-zone livestock stress conditions.
Feed palatability enhancers comprise sensory-active compounds—synthetic and natural flavors, high-intensity sweeteners, organic acids, and olfactory stimulants—typically dosed at 0.01% to 0.5% of feed weight to mask anti-nutritional bitterness and trigger cephalic phase digestive responses. These additives function by stimulating chemoreceptors in the oral and nasal cavities of monogastric and ruminant species, thereby increasing voluntary feed intake and reducing sorting behavior in pelleted rations. Poultry feed commands the dominant volume share, as broiler operations across the Gulf prioritize intake consistency in high-temperature environments where heat stress depresses appetite. Flavors extract premium pricing relative to sweeteners, since thermostable meat and fish hydrolysates require more complex encapsulation to survive extrusion temperatures exceeding 85°C. Direct sales channels dominate transaction value, with multinational suppliers embedding technical service teams inside the largest feed mill operations to co-develop customized masking systems.
Saudi Food and Drug Authority registration requirements and UAE Ministry of Climate Change and Environment feed safety protocols are converging toward mandatory traceability documentation for imported flavor precursors. The GCC Standardization Organization's harmonized additive maximum residue limits are reducing regulatory fragmentation, though national-level halal certification requirements for porcine-derived ingredient exclusions still create compliance complexity for global suppliers. Stakeholders must monitor how Egypt's expanding poultry export ambitions and associated feed quality standards reshape procurement specifications across the broader Middle Eastern trade corridor.
Market Dynamics
SFDA's tightening feed additive registration requirements is compressing supplier timelines and forcing documented safety dossiers for all imported flavor precursors entering Saudi Arabia, reshaping competitive access across the Gulf.
Growth Catalysts
- SFDA Registration Mandate:Saudi Arabia's mandatory traceability documentation for imported flavor precursors is filtering out informal suppliers and consolidating procurement toward qualified multinationals with dedicated regulatory affairs teams.
- Heat-Stress Formulation Demand:Broiler operations across the UAE and Kuwait are adopting thermostable meat hydrolysates to maintain voluntary feed intake in ambient temperatures exceeding 45°C during summer months.
- Central Region Integration:Vertically integrated poultry producers in Saudi Arabia's Riyadh corridor are expanding compound feed mill capacity, creating captive offtake for customized masking systems.
Market Restraints
- Encapsulation Cost Structure:Thermostable meat and fish hydrolysates require complex microencapsulation to survive extrusion temperatures above 85°C, elevating unit economics relative to standard sweeteners.
- Halal Certification Friction:National-level porcine-derived ingredient exclusion requirements across GCC states create compliance complexity for global suppliers with centralized manufacturing footprints.
- Input Concentration Risk:High-intensity sweetener precursors remain concentrated among specialized chemical manufacturers in Western Europe, exposing regional formulators to currency and freight volatility.
Strategic Opportunities
- Egypt Export Corridor:Egypt's expanding poultry export ambitions and associated feed quality standards are reshaping procurement specifications across the broader Middle Eastern trade corridor, opening formulation partnerships with Alexandria-based feed mills.
- Toll Manufacturing Channels:Asset-light third-party flavor compounding arrangements are narrowing capital barriers for regional entrants to challenge established suppliers without full manufacturing infrastructure.
- Precision-Delivery Convergence:Yeast extract technologies combined with arid-zone livestock stress optimization are enabling differentiated positioning for suppliers serving Kuwait and Qatar's intensive dairy operations.
Industry Challenges
- Savory Science Talent Scarcity:Dedicated formulation expertise for Middle Eastern taste profiles remains concentrated within a limited pool of technical service teams embedded at multinational suppliers.
- Registration Timeline Compression:SFDA's evolving documentation requirements are extending product approval cycles, delaying market entry for novel natural flavor candidates.
- Legacy System Integration:Direct sales channels with co-development protocols require technical personnel placement inside feed mill operations, straining field service bandwidth across dispersed Gulf geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Feed Palatability Enhancers Market |
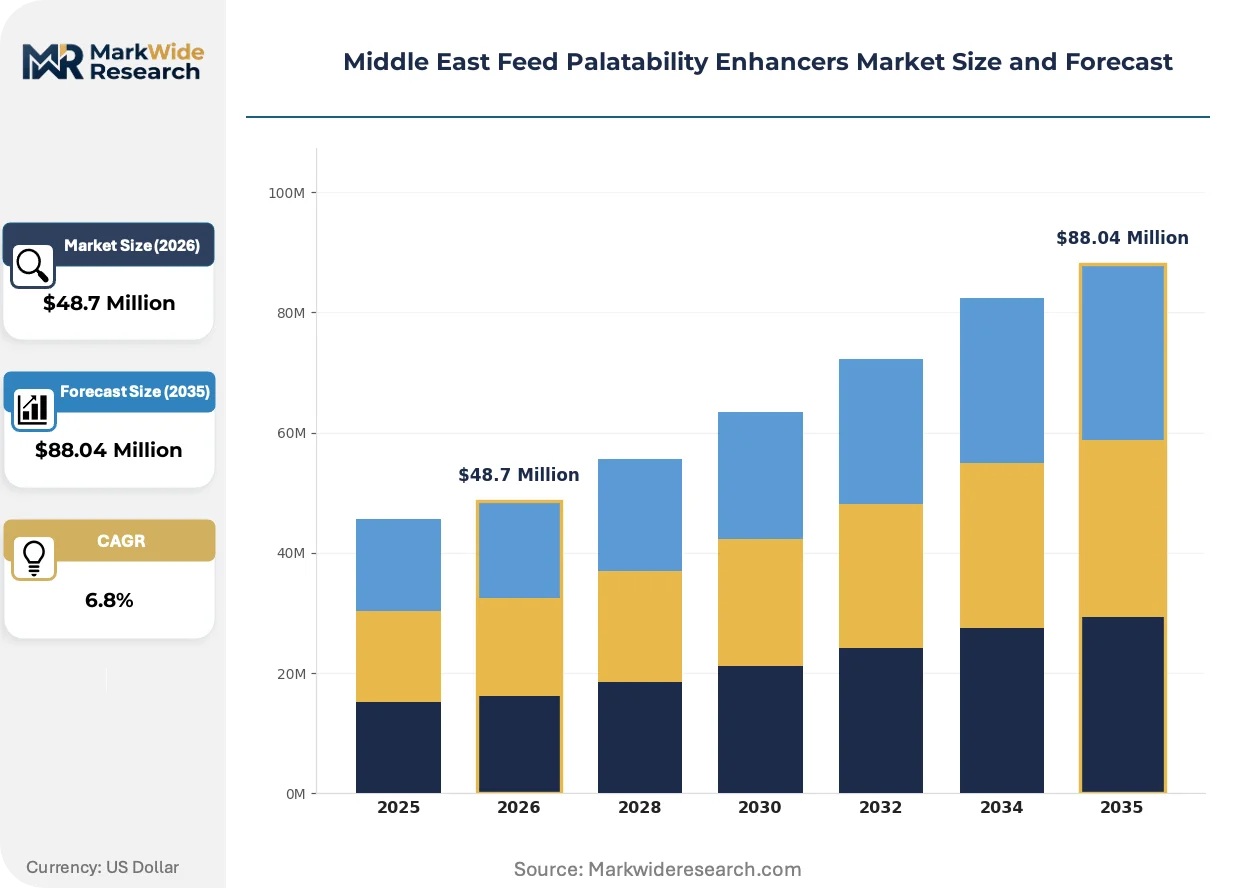
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Poultry Feed, Ruminant Feed, Aquafeed, Swine Feed Ingredient: Flavors, Sweeteners, Acids, Olfactives Application: Livestock Nutrition, Pet Foods, Aquaculture, Feed Mill Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | DuPont, Cargill Inc., Kerry Group Plc, Associated British Foods PLC, Kemin Industries Inc., DSM-Firmenich, Symrise AG, Alltech, Diana Group, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Feed Palatability Enhancers Market Shifts & Advancements
Digital formulation platforms and precision-delivery systems are compressing development cycles for region-specific palatability solutions, while regulatory harmonization across GCC states is standardizing compliance architectures.
Microencapsulated thermostable flavor systems are virtualizing traditional compounding workflows by enabling real-time adjustment of release profiles during extrusion. Poultry integrators in Saudi Arabia's Central Region are adopting these systems at accelerated pace to reduce batch rejection rates. This virtualization is compressing the technical service interval between formulation iteration and field validation, collapsing what previously required weeks into days.
SFDA's convergence with UAE Ministry of Climate Change and Environment feed safety protocols is mandating blockchain-traceable documentation for all imported flavor precursors. Industrial consequence includes elevated compliance costs for smaller regional traders lacking integrated quality management systems. Poultry feed mills across Dubai and Sharjah are most affected, responding by consolidating supplier panels toward integrated multinationals with pre-validated dossiers.
Buyer concentration among vertically integrated poultry producers is compressing switching cycles for palatability suppliers. Technical service co-development agreements are displacing transactional spot purchasing in Riyadh and Abu Dhabi feed mill procurement. This pattern is most visible in Saudi Arabia's Central Region, where the largest compound feed operations now embed supplier personnel full-time within quality control laboratories.
Middle East Feed Palatability Enhancers Market Segmentation
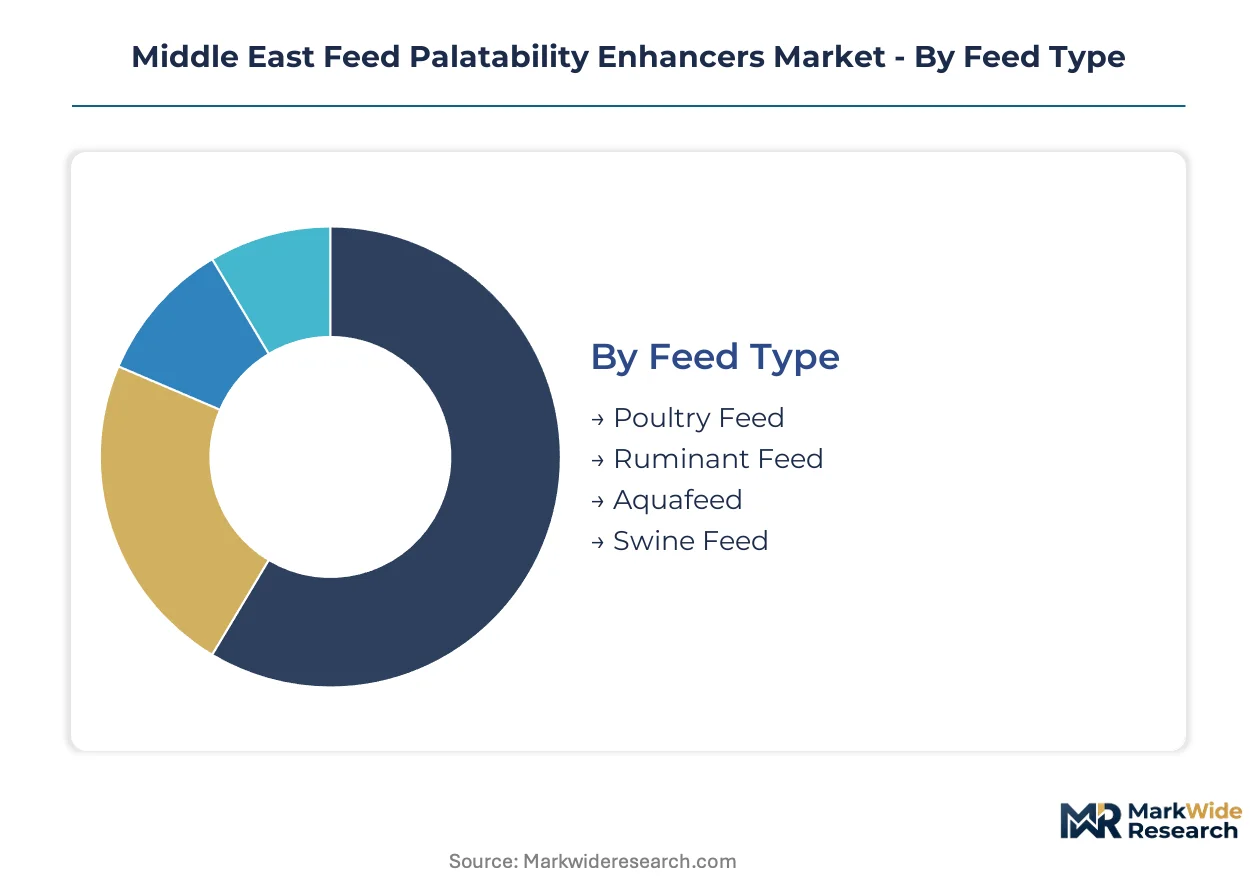
Feed palatability enhancers serve divergent species physiology and processing conditions across the Middle East, demanding formulation precision that varies by feed type, ingredient chemistry, and channel access. Segmentation reveals where technical service investments concentrate and where commoditization pressures emerge.
Feed Type:
Mature applications in intensive poultry operations contrast with emerging demand patterns in aquaculture and specialty livestock sectors.
- Poultry Feed:Thermostable meat hydrolysates and encapsulated yeast extracts dominate formulations for high-density broiler houses across Saudi Arabia's Central Region and UAE operations. SFDA-registered masking systems command premium placement due to mandatory traceability documentation for imported precursors.
- Ruminant Feed:Molasses-based sweeteners and volatile fatty acid precursors address intake depression in heat-stressed dairy herds, particularly in Kuwait and Qatar's intensive operations where ambient summer temperatures exceed 45°C.
- Aquafeed:Marine protein hydrolysates and nucleotide-rich yeast derivatives target high-value marine and freshwater species in Egypt's expanding aquaculture zones near Alexandria.
- Swine Feed:Limited regional applicability due to halal certification constraints across GCC states; minimal formal market presence outside non-Muslim minority farming operations.
Poultry Feed handles the majority of throughput; Aquafeed is gaining share fastest on Egypt's export corridor expansion.
Ingredient:
Cost tier differentiation separates precision-formulated sensory actives from commodity sweetener alternatives.
- Flavors:Complex microencapsulation of thermostable meat and fish hydrolysates enables survival through extrusion temperatures above 85°C, commanding substantial premiums over standard alternatives. Demand concentrates in vertically integrated Saudi poultry operations requiring batch consistency.
- Sweeteners:High-intensity sucralose and neotame formulations serve ruminant and pet food applications where heat stability requirements are less stringent. Procurement faces input concentration risk from Western European chemical manufacturers.
- Acids:Organic acid blends including citric, fumaric, and propionic acid variants provide dual-function palatability enhancement and antimicrobial preservation, particularly valued in humid coastal feed milling environments.
- Olfactives:Synthetic and natural olfactory stimulants trigger cephalic phase digestive responses in monogastric species, deployed at low inclusion rates of 0.01% to 0.1% in premium pet food formulations.
Flavors capture the highest margin tier; Sweeteners represent the volume anchor across commodity feed applications.
Application:
Customer type fragmentation separates integrated livestock operations from fragmented pet food and aquaculture buyers.
- Livestock Nutrition:Direct technical service embedding within Saudi and UAE feed mill quality control laboratories enables customized masking system co-development for broiler integrators.
- Pet Foods:Premium positioning in UAE and Qatar urban markets drives demand for specialized savory profiles, though volume remains constrained by smaller addressable market size.
- Aquaculture:Egypt's government-backed aquaculture expansion and associated feed quality standards are reshaping procurement specifications for marine protein-derived palatability systems.
- Feed Mill:Toll manufacturing arrangements and third-party flavor compounding serve mid-sized independent mills lacking in-house formulation expertise, particularly in Jordan and Lebanon.
Livestock Nutrition absorbs the dominant technical service investment; Aquaculture exhibits the steepest expansion trajectory on Egyptian production targets.
Distribution Channel:
Supply concentration in direct sales channels contrasts with emerging digital procurement among smaller regional formulators.
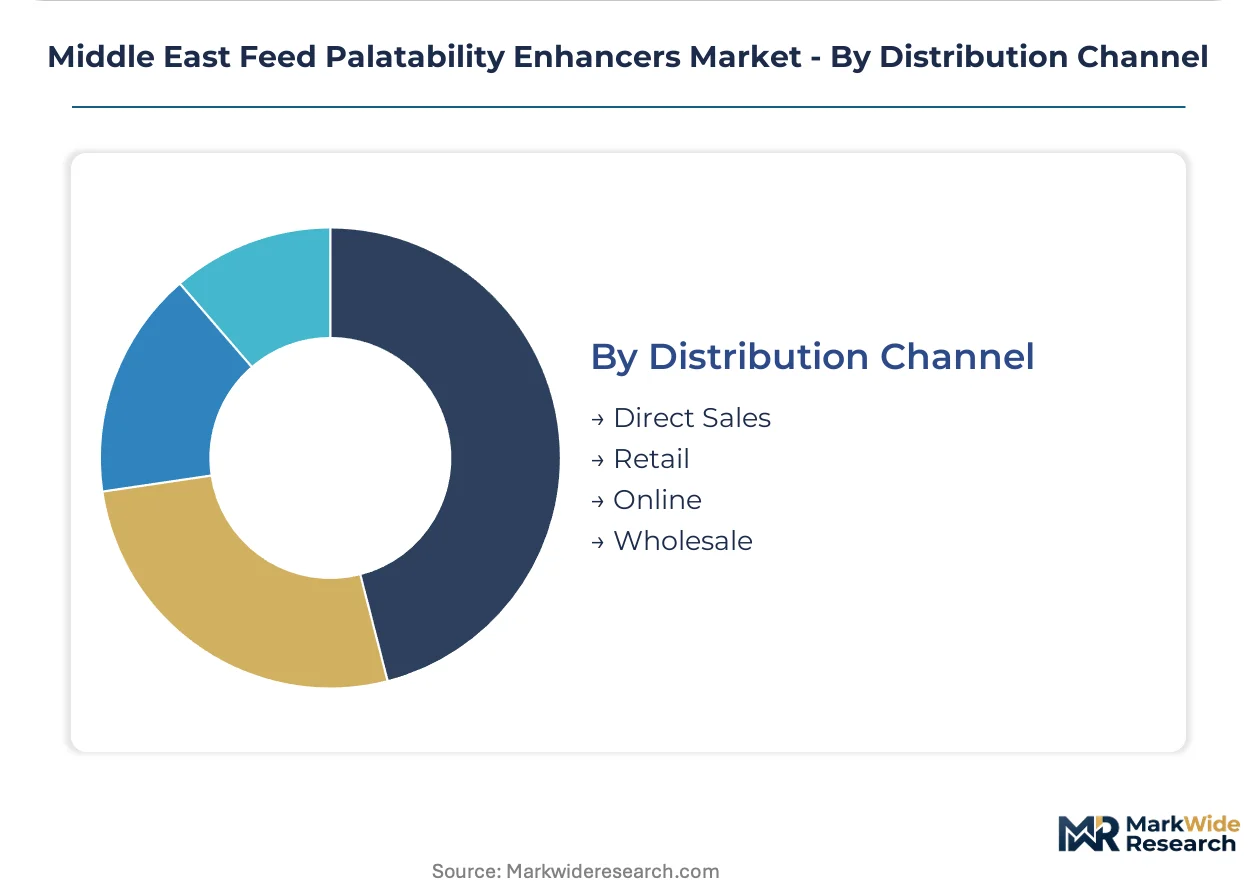
- Direct Sales:Multinational suppliers embed technical personnel full-time within the largest Saudi and UAE compound feed operations, displacing transactional spot purchasing with co-development protocols.
- Retail:Limited relevance for bulk feed additive procurement; marginal presence in smallholder poultry and livestock supplement markets.
- Online:Emerging channel for standardized sweetener and acid products among regional toll manufacturers seeking rapid price benchmarking and sample procurement.
- Wholesale:Traditional trader networks persist for unregistered or legacy flavor precursors, though SFDA documentation requirements are compressing informal supplier participation.
Direct Sales manages relationship-intensive high-value transactions; Online is climbing fastest on toll manufacturing channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi Arabia's Central Region while UAE buyers leverage technical service co-development to extract formulation concessions. This asymmetry shapes procurement patterns across the Gulf. Egypt's export corridor ambitions are redrawing supply relationships along the Mediterranean trade axis.
Saudi Arabia
Vertically integrated poultry producers in Riyadh and the Central Region operate the largest compound feed mills in the Gulf, driving concentrated demand for SFDA-registered masking systems. The Saudi Food and Drug Authority's mandatory traceability documentation for imported flavor precursors filters out informal suppliers. Almarai and other integrators embed supplier personnel full-time within quality control laboratories to accelerate formulation iteration.
United Arab Emirates
Broiler operations across Dubai and Sharjah adopt thermostable meat hydrolysates to maintain voluntary feed intake during summer months when ambient temperatures exceed 45°C. The UAE Ministry of Climate Change and Environment's feed safety protocols are converging with Saudi standards toward blockchain-traceable documentation. Industrial clusters in Dubai Industrial City and Jebel Ali Free Zone host multinational technical service teams serving Gulf-wide accounts.
Egypt
Government-backed aquaculture expansion near Alexandria is reshaping procurement specifications for marine protein-derived palatability systems. The country's expanding poultry export ambitions are elevating feed quality standards across the broader Middle Eastern trade corridor. Feed mills in the Nile Delta are consolidating supplier panels toward integrated multinationals with pre-validated dossiers.
Kuwait
Intensive dairy operations in the Jahra and Wafra agricultural zones deploy molasses-based sweeteners and volatile fatty acid precursors to address intake depression in heat-stressed herds. National halal certification requirements for porcine-derived ingredient exclusions create compliance complexity for global suppliers. Local feed compounders are exploring toll manufacturing arrangements to narrow capital barriers for regional flavor compounding.
Qatar
Premium pet food positioning in Doha's urban markets drives demand for specialized savory profiles, though volume remains constrained by smaller addressable market size. The country's national food security strategy prioritizes domestic livestock production, expanding compound feed capacity in Umm Salal and Al Khor. Precision-delivery yeast extract technologies optimized for arid-zone stress conditions are gaining placement in dairy nutrition programs.
Middle East Feed Palatability Enhancers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying encapsulated precursors and sensory actives. Market structure consolidates around multinational suppliers with dedicated regulatory affairs teams capable of navigating SFDA documentation requirements. Three archetypes dominate: integrated grain-to-feed conglomerates with captive offtake infrastructure, savory science specialists with regional formulation facilities, and precision-delivery technology providers. Competitive moves concentrate on technical service embedding within feed mill operations and strategic partnerships with toll manufacturers.
Within the integrated infrastructure tier, Cargill Inc. leverages grain origination and feed milling assets across Saudi Arabia and the UAE to secure captive placement for palatability portfolios. Kerry Group Plc occupies a position exemplifying savory science leadership through dedicated facilities serving Middle Eastern taste profiles. DSM-Firmenich anchors the precision-delivery archetype with yeast extract technologies optimized for arid-zone livestock stress conditions. These three represent the dominant competitive vectors shaping procurement consolidation toward qualified multinationals.
| Leading Market Players |
|---|
| DuPont |
| Cargill Inc. |
| Kerry Group Plc |
| Associated British Foods PLC |
| Kemin Industries Inc. |
| DSM-Firmenich |
| Symrise AG |
| Alltech |
| Diana Group |
| Others |
Supply & Pricing Matrix
Overcapacity in Western European high-intensity sweetener precursor manufacturing is compressing margin structures for Middle Eastern formulators while simultaneously elevating bargaining power among Saudi and UAE poultry integrators demanding documented SFDA safety dossiers. This utilization asymmetry forces regional compounders to absorb encapsulation cost premiums or cede share to integrated multinationals with captive manufacturing footprints.
Pricing Analysis
The customization-premium spread between configured-to-order masking systems and standard sweetener formulations runs wide across the Gulf, with contract-based long-term offtake dominating procurement for vertically integrated Saudi poultry operations while spot purchasing persists for commodity acids. Price differentiation hinges on SFDA registration tier and technical service embedding depth, with heat-stabilized meat hydrolysates commanding substantial premiums over neotame alternatives. Pricing pressure stems from Egyptian feed mills consolidating supplier panels toward pre-validated multinationals. Contract poultry integrators exhibit lowest price sensitivity; independent toll manufacturers face acute margin compression.
Supply Chain Analysis
Contract-manufacturing concentration for thermostable flavor encapsulation rests with specialized European chemical processors and regional toll compounding facilities in Jordan and Lebanon. Geographic supply concentration centers on Germany, Switzerland, and the Netherlands for high-intensity sweetener precursors, with Saudi Arabia and the UAE hosting downstream formulation and technical service operations. Raw material dependencies include marine protein hydrolysates, yeast extract derivatives, and synthetic olfactory actives. Single-source vulnerability from Western European precursor manufacturers exposes regional formulators to freight and currency volatility. Distribution runs through direct technical service channels embedded within compound feed mill quality control laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East feed palatability enhancers market sits at a platform-economics inflection where SFDA-mandated blockchain traceability documentation is collapsing supplier interoperability and favoring integrated data ecosystems over fragmented trader networks.
For Market Incumbents: Build regulatory affairs moats by embedding dedicated dossier management teams inside Riyadh and Dubai to compress approval timelines for novel natural flavor candidates. Deepen backward integration into yeast extract fermentation capacity to secure arid-zone stress optimization IP. Defend against Egyptian toll manufacturing challengers by locking long-term co-development protocols with Central Region poultry integrators. For New Entrants and Emerging Players: Egypt's Nile Delta feed mill consolidation presents the most penetrable white-space for marine protein-derived palatability systems serving government-backed aquaculture expansion. Target toll manufacturing arrangements with Alexandria-based compounders lacking in-house savory science expertise. Pursue asset-light flavor compounding partnerships to bypass capital-intensive encapsulation infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across third-party flavor compounding as microencapsulation virtualization reduces fixed asset requirements. Long-term viability favors platform integrators with pre-validated SFDA dossiers over component specialists exposed to input concentration risk. Monitor Egyptian poultry export quota announcements as the critical signal for regional procurement specification shifts. Acquisition targets should demonstrate embedded technical service relationships with vertically integrated Saudi producers.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Dossier Investment | Pre-validated safety documentation accelerates market access for novel natural flavors in Saudi Arabia. |
| Toll Manufacturing Partnership | Asset-light compounding arrangements narrow capital barriers for Egyptian and Jordanian regional entrants. |
| Precision-Delivery Yeast Extract Scale-Up | Arid-zone livestock stress optimization captures placement in Kuwait and Qatar intensive dairy operations. |
| Blockchain Traceability Integration | Converging UAE and Saudi feed safety protocols mandate documented precursor provenance for import clearance. |
| Technical Service Laboratory Embedding | Full-time personnel placement inside Riyadh feed mill quality control accelerates formulation iteration cycles. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with feed mill procurement directors, regulatory affairs managers at multinational suppliers, poultry integrator nutritionists, and toll manufacturing operators; alongside secondary validation from SFDA registration databases, UAE Ministry of Climate Change and Environment feed safety protocols, GCC Standardization Organization additive maximum residue limit harmonization documents, and customs trade records for flavor precursor imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs considered feed type segmentation by species application, ingredient chemistry tiers from commodity sweeteners to precision-encapsulated flavors, distribution channel concentration between direct sales and emerging digital procurement, and regional regulatory cluster divergence across Saudi Arabia, UAE, Egypt, Kuwait, and Qatar. CAGRs were derived from elasticity-adjusted volume projections incorporating heat-stress formulation demand intensity and vertically integrated poultry capacity expansion trajectories. Industry-specific inputs included broiler operation density metrics and ambient temperature severity indices for summer feed intake depression modeling.
Practitioners should monitor SFDA documentation requirement evolution, Egyptian poultry export quota policy shifts, and Western European precursor manufacturer capacity utilization for early signals of competitive access compression or procurement specification disruption. Quarterly review of registration approval timelines, toll manufacturing capacity announcements, and blockchain traceability technology adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soy Protein Ingredients Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Desiccated Coconut Market
Ingredients
Global Distillers Grains Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Sesame Oil Market
Ingredients
Modified Flour Market
Ingredients
Omega 6 Market
Ingredients
Corn Oil Cake Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Functional Flours Market
Ingredients
Dill Seed Oil Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Mung Bean Starch Market