
 Bakery Ingredients Market | 2026-2036
Bakery Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Ingredients Market Intelligence
Recipe-as-a-service and digital formulation platforms are decoupling technical expertise from physical ingredient sales, allowing bakeries to access customized blends without maintaining in-house R&D labs. Kerry Group PLC leverages its taste and nutrition science portfolio to anchor premium positioning in enzyme and emulsifier systems across European and North American accounts. Cargill Corporation competes through backward integration into oilseed processing, securing captive supply of specialty shortenings and lecithin variants. Associated British Foods PLC dominates the bread improver segment through its AB Mauri division, controlling distribution into both artisan and industrial bakery channels.
Bakery ingredients encompass functional components—flours, leavening agents, emulsifiers, enzymes, and shortenings—that modify dough rheology, control moisture retention, and extend shelf stability in finished baked goods. Wheat flour specifications typically range from 9% to 14% protein content depending on intended application, with bread flours requiring higher gluten formation capacity than cake flours designed for tender crumb structures. Flours and shortenings represent mature, high-volume segments where margin compression is common, while emulsifiers command premium pricing due to clean-label reformulation complexity and regulatory substitution costs. The industrial end-user channel concentrates procurement volume among large-scale bread and cookie manufacturers, whereas food service and artisan bakery segments drive faster growth in specialty and organic ingredient grades.
The FDA governs GRAS self-affirmation for novel enzymes and emulsifiers entering the US market, while the EMA and EFSA jointly shape permissible additive categories across European member states through reauthorization cycles and purity specification updates. BIS certification requirements in India mandate fortification standards for wheat flour, directly influencing premix formulation decisions by multinational suppliers operating in that market. Stakeholders must monitor diverging regulatory timelines for enzyme approvals and emerging restrictions on synthetic preservatives, as these will determine which ingredient portfolios retain market access and which require accelerated reformulation investment.
Market Dynamics
Clean-label reformulation mandates across the EU F-Gas Regulation and REACH are forcing ingredient suppliers to rebuild emulsifier and shortening portfolios around enzyme-based and palm-free alternatives, compressing legacy synthetic additive demand.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon-based propellants in aerosol baking sprays is redirecting R&D investment toward compressed gas and pump-dispensed emulsifier systems for industrial bakeries.
- Artisan bakery channel expansion:Premium food service accounts in Germany and France are specifying organic specialty flours and clean-label improvers, creating pull-through demand for certified ingredient grades.
- Enzyme engineering advances:Novel lipase and amylase variants developed through precision fermentation are enabling clean-label dough conditioning without azodicarbonamide or DATEM replacements.
Market Restraints
- Palm oil supply concentration:Indonesian and Malaysian plantation output volatility directly impacts shortenings pricing and reformulation timelines for European manufacturers seeking palm-free claims.
- REACH reauthorization cycles:Extended ECHA evaluation timelines for existing food-contact substances create regulatory lag, freezing formulation decisions and extending product development cycles by 18-24 months.
- Wheat protein variability:Climate-induced harvest quality fluctuations in Black Sea and North American growing regions destabilize flour specification consistency for industrial bread manufacturers.
Strategic Opportunities
- India BIS fortification mandates:Mandatory iron, folic acid, and vitamin B12 premix requirements in wheat flour create captive demand for micronutrient suppliers establishing local blending operations.
- Recipe-as-a-service platforms:Digital formulation tools are decoupling technical expertise from physical ingredient sales, allowing mid-size bakeries to access customized blends without in-house R&D infrastructure.
- Enzyme-emulsifier hybrid systems:Convergence of precision fermentation with lipid modification chemistry is opening clean-label texture solutions that replace synthetic mono- and diglycerides in cake and pastry applications.
Industry Challenges
- Clean-label certification timelines:Organic and non-GMO verification processes for enzyme production substrates extend time-to-market by 12-18 months versus conventional synthetic alternatives.
- Flour protein analytics capability gap:Industrial bakeries lack in-house near-infrared spectroscopy expertise to validate incoming wheat flour specifications, creating quality control dependencies on supplier certificates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Ingredients Market |
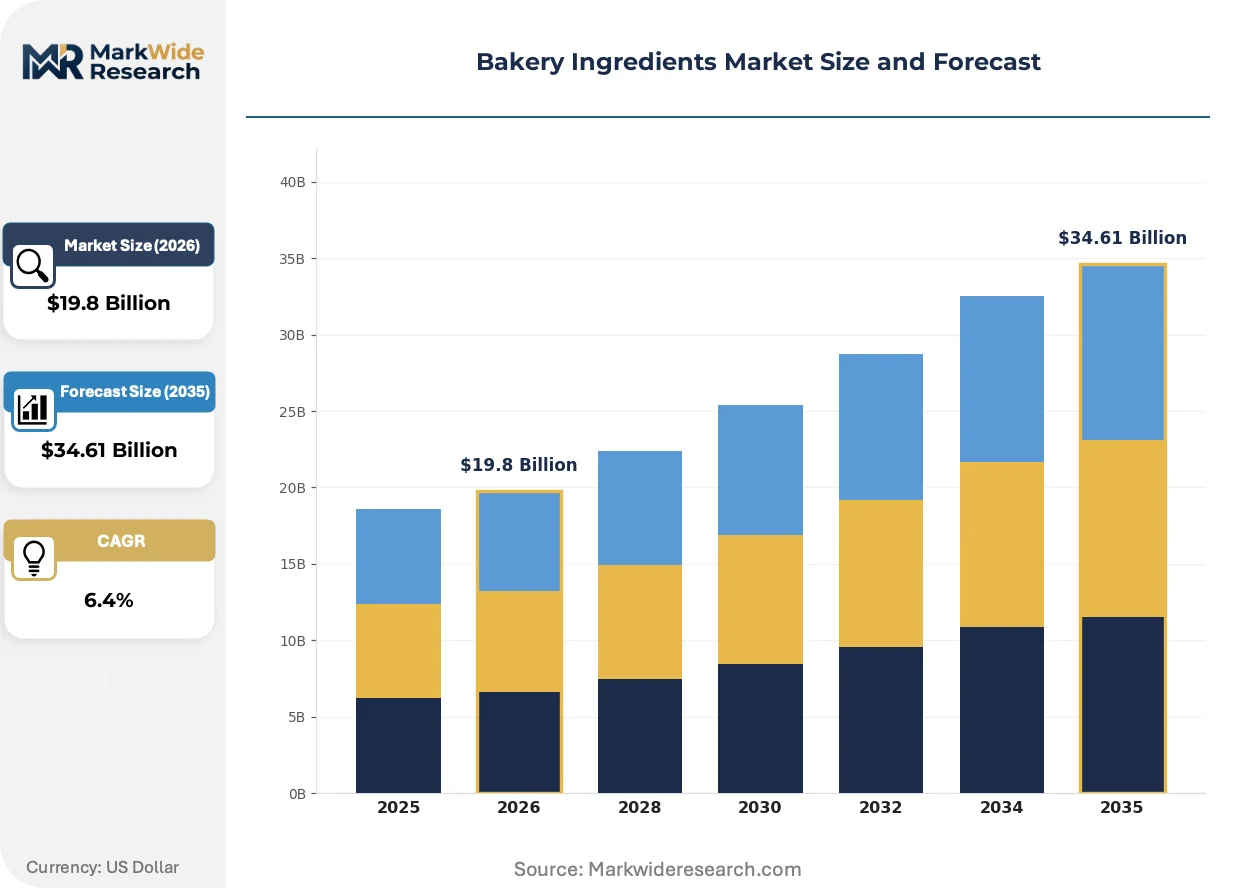
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flours, Sugars, Emulsifiers, Shortenings Application: Breads, Cakes, Pastries, Cookies End User: Bakeries, Food Service, Retail, Industrial Packaging Type: Bags, Boxes, Bulk Containers, Sachets |
| Companies Covered | Archer Daniels Midland Company, Cargill Corporation, Kerry Group PLC, Associated British Foods PLC, DuPont de Nemours, Inc., Koninklijke DSM N.V., Dawn Food Products, Inc., Ingredion Incorporated, Bakels Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Ingredients Market Strategic Shifts & Innovations
Digital formulation platforms and precision fermentation are converging to disaggregate technical service from ingredient manufacturing, while regulatory pressure on synthetic additives accelerates enzyme and plant-based lipid substitution.
Precision fermentation-derived enzymes are integrating into industrial bread improver systems as direct replacements for azodicarbonamide and calcium peroxide. North American and European industrial bakeries are adopting these bio-based conditioners at scale for clean-label product lines. This substitution is integrating technical expertise into supplier service models, compressing margins on commodity improver sales while expanding high-value formulation consulting revenue.
REACH authorization requirements for food-contact substances are tightening purity specifications for emulsifiers and processing aids across European member states. ECHA's expanded substance evaluation list is forcing reformulation of DATEM and SSL variants in frozen dough applications. German and French industrial bakeries are responding by accelerating enzyme-based alternatives through accelerated stability testing protocols.
Food service distributors are unbundling ingredient procurement from technical formulation support, allowing independent bakeries to access customized premixes through digital platforms without minimum order constraints. This channel fragmentation is most visible in the UK and Netherlands, where regional bakery cooperatives are consolidating purchasing through specialized ingredient e-procurement portals that bypass traditional broker networks.
Bakery Ingredients Market Segmentation
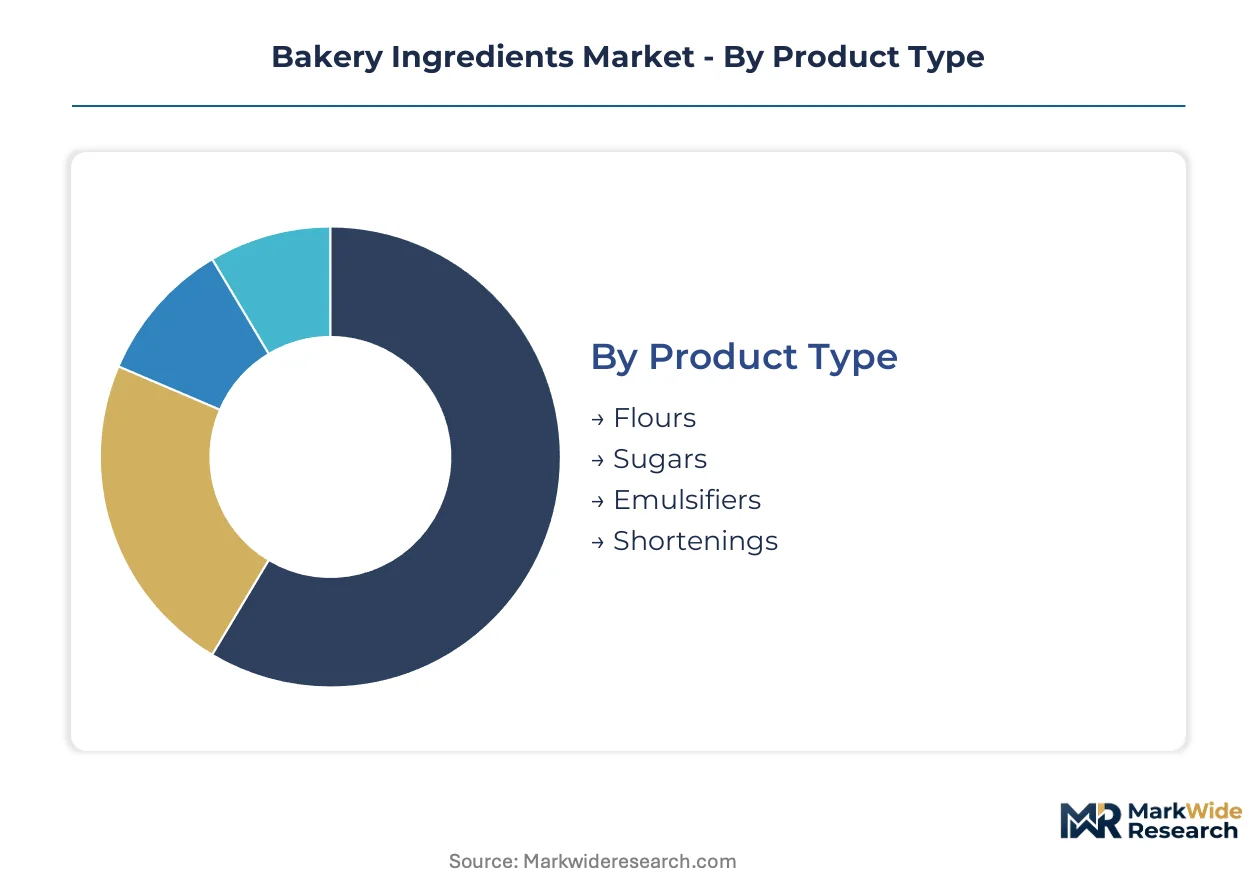
Bakery ingredients segment along functional, application, and channel dimensions that determine formulation complexity and procurement scale. Understanding these divisions clarifies where commodity volume concentrates versus where specialty premiums command pricing power.
Product Type:
Ingredient systems vary in their integration depth — some function as standalone inputs requiring minimal modification, others demand precise blending with complementary components.
- Flours:Wheat flour specifications span 9% to 14% protein content, with bread flours requiring higher gluten formation capacity than cake formulations. German industrial bakeries are upgrading to certified specialty grades as artisan channel specifications cascade upward. Volume placements concentrate in flours; the faster expansion belongs to emulsifiers.
- Emulsifiers:Clean-label reformulation complexity and regulatory substitution costs sustain premium pricing for DATEM and SSL replacements. EU F-Gas Regulation and REACH compliance are accelerating enzyme-based alternatives in French and German frozen dough applications. Clean-label certification timelines extend time-to-market by 12-18 months versus synthetic alternatives.
- Sugars:Granulated, brown, and specialty sugar syrups provide fermentation substrate and Maillard browning control across bread and pastry categories.
- Shortenings:Palm oil supply concentration in Indonesian and Malaysian plantations creates pricing volatility for European manufacturers pursuing palm-free claims.
Procurement scale favors bulk flour contracts; reformulation investment flows toward emulsifier and shortening substitution.
Application:
Finished product categories impose distinct rheological demands that shape ingredient specification priorities and supplier technical service intensity.
- Breads:Industrial loaf production consumes the highest flour volumes and drives demand for dough conditioners, improvers, and shelf-life extenders. Clean-label enzyme systems are displacing azodicarbonamide and calcium peroxide in North American and European industrial lines. Production scale here anchors commodity ingredient demand.
- Cakes:Tender crumb structure requirements favor lower-protein flours and specialized emulsifier systems for aeration and moisture retention. REACH authorization tightening for food-contact substances is forcing DATEM reformulation in German and French frozen cake applications.
- Pastries:Laminated dough applications require precise fat-flour interaction control through specialized shortenings and lipid-modified emulsifiers.
- Cookies:Spread control and snap texture depend on precise sugar crystallization and fat melting point management in creaming and wire-cut processes.
Industrial bread manufacturing anchors volume; artisan pastry and cake segments generate faster specialty ingredient growth.
End User:
Channel structure determines minimum order scale, technical service requirements, and certification complexity for ingredient suppliers.
- Bakeries:Artisan and craft segments in Germany and France are specifying organic specialty flours and clean-label improvers, creating pull-through demand for certified grades. Digital formulation platforms now allow mid-size bakeries to access customized premixes without in-house R&D infrastructure.
- Industrial:Large-scale bread and cookie manufacturers concentrate procurement volume and demand consistent flour specifications that climate-induced harvest variability in Black Sea and North American regions increasingly disrupts.
- Food Service:Premium accounts drive faster growth in specialty and organic ingredient grades through distributor unbundling of procurement from technical support.
- Retail:Packaged consumer ingredient sales through grocery channels emphasize convenience formats and smaller pack sizes.
Industrial channels dominate tonnage; food service and artisan bakery segments expand most quickly in value terms.
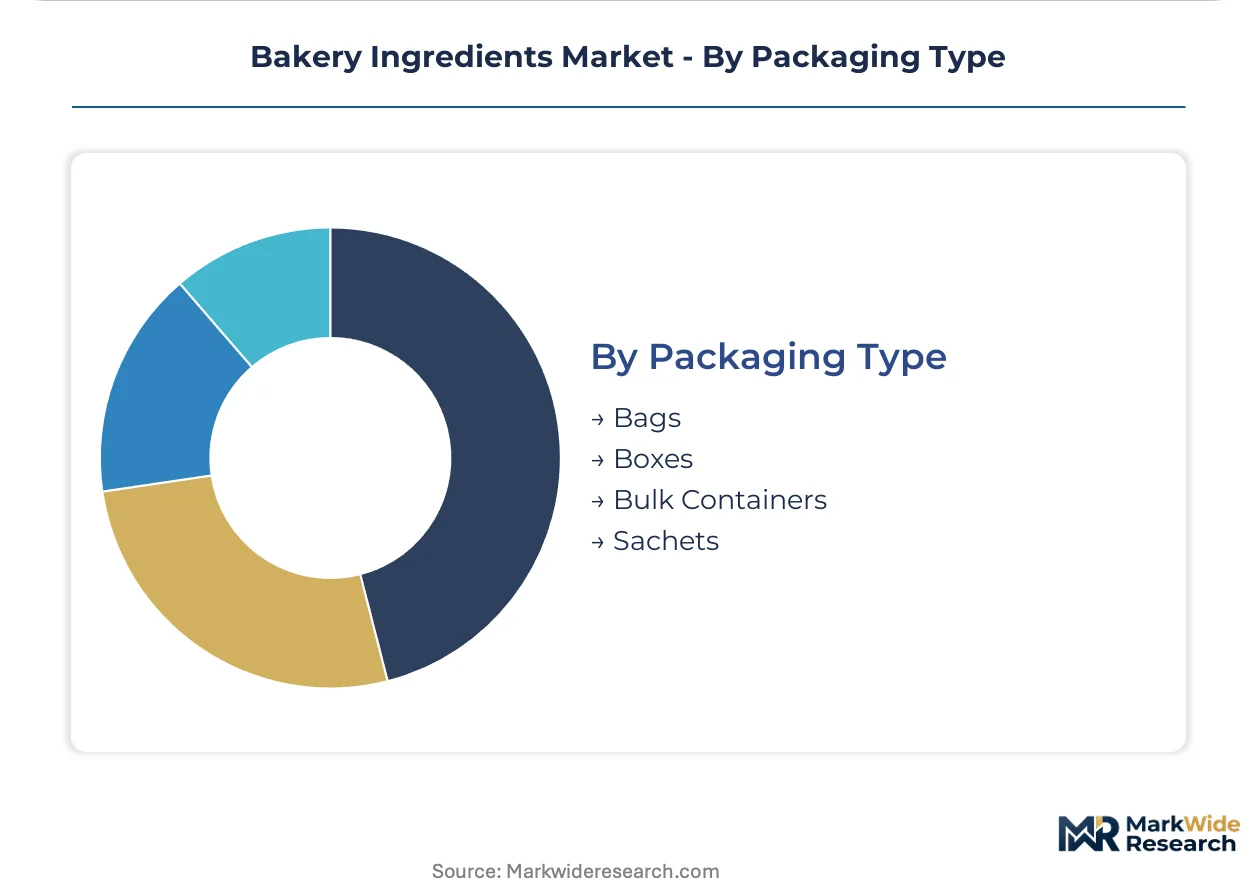
Packaging Type:
Packaging configuration aligns with end-user operational scale, shelf-life requirements, and handling automation levels.
- Bulk Containers:Tote bins and silo deliveries serve industrial bakeries with automated handling systems and high throughput requirements.
- Bags:Multi-wall paper and woven polypropylene formats balance protection with handling convenience for mid-scale bakery operations.
- Boxes:Corrugated cases organize smaller bags or pouches for food service distributors and retail channel logistics.
- Sachets:Single-use portions support recipe-as-a-service platforms and small-batch artisan operations with precise dosing and minimal waste.
Bulk containers capture industrial volume; sachet formats climb fastest alongside digital formulation platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of specialty emulsifiers and enzyme systems concentrates in European and North American chemical clusters, while consumption growth tilts toward Asian markets where fortification mandates and industrial bakery expansion accelerate ingredient procurement.
Germany
Industrial bakeries in North Rhine-Westphalia and craft segments in Bavaria are upgrading to certified organic flours and clean-label improvers simultaneously. The EU F-Gas Regulation and REACH compliance through ECHA are forcing reformulation toward palm-free shortenings and enzyme-based dough conditioners. Cologne and Munich anchor formulation R&D clusters where suppliers integrate digital recipe platforms with physical ingredient distribution.
United States
Large-scale bread manufacturers in the Midwest and premium food service accounts on the coasts are diverging in procurement patterns. FDA GRAS self-affirmation processes govern novel enzyme introductions, creating regulatory lag versus European approval timelines. Chicago and Minneapolis-St. Paul concentrate industrial bakery volume, while California and New York metro areas drive specialty and organic grade demand through artisan channel expansion.
India
BIS fortification mandates for wheat flour are creating captive demand for micronutrient premixes as industrial bakeries scale production. FSSAI standards and state-level food safety enforcement are tightening ingredient traceability requirements. Maharashtra and Gujarat host blending operations where multinational suppliers localize production to serve both domestic consumption and export markets into South Asia and the Middle East.
France
Artisan bakery cooperatives in Île-de-France and industrial frozen dough producers in Hauts-de-France are pulling specialty ingredient specifications in divergent directions. EFSA reauthorization cycles for food-contact substances are compressing formulation timelines for DATEM and SSL replacements. Lyon and Paris anchor clean-label innovation clusters where enzyme-emulsifier hybrid systems undergo accelerated stability testing.
Brazil
Industrial cookie and bread manufacturers in São Paulo state are expanding procurement of specialty shortenings amid palm oil price volatility. ANVISA registration requirements for novel food additives extend time-to-market for enzyme-based improvers versus synthetic alternatives. Campinas and the São Paulo metro area concentrate formulation expertise where suppliers blend imported specialty inputs with locally processed commodities.
Bakery Ingredients Market Key Industry Players
Top-tier vendors anchor the enzyme and emulsifier technology tier, while mid-scale regional blenders compete on formulation service intensity and local certification speed. The market structures around three player archetypes: integrated agribusiness conglomerates with captive oilseed processing, specialized enzyme and fermentation science firms, and regional premix blenders with deep bakery channel relationships. M&A activity concentrates on precision fermentation capabilities and geographic expansion into fortification-mandated markets. Portfolio diversification toward digital formulation services is separating technical consulting revenue from commodity ingredient margins.
Among the integrated agribusiness conglomerates, Cargill Corporation and Archer Daniels Midland Company exemplify the backward integration archetype, controlling upstream oilseed processing that supplies captive shortenings and lecithin variants. Kerry Group PLC represents the specialized nutrition science tier, anchoring premium positioning in taste and enzyme systems through European and North American account penetration. Associated British Foods PLC occupies a position spanning both industrial and artisan channels through its AB Mauri division, illustrating the dual-channel distribution archetype.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Corporation |
| Kerry Group PLC |
| Associated British Foods PLC |
| DuPont de Nemours, Inc. |
| Koninklijke DSM N.V. |
| Dawn Food Products, Inc. |
| Ingredion Incorporated |
| Bakels Group |
| Others |
Cost & Logistics Intelligence
Palm oil futures volatility on the Bursa Malaysia Derivatives Exchange cascades through bakery ingredient supply chains into three distinct pricing tiers: palm-free premium formulations, standard shortenings, and economy-grade commodity blends. This commodity benchmark transmission compresses margins for European manufacturers while rewarding suppliers with backward-integrated oilseed processing or enzyme-based substitution portfolios.
Pricing Analysis
Margin tightening in standard-grade emulsifiers reflects REACH-driven reformulation costs and extended ECHA reauthorization timelines. Three-tier pricing structure across premium, standard, and economy levels separates clean-label certified enzyme systems from conventional DATEM variants and commodity improvers. Price differentiation hinges on organic certification grade and volume scale. Industrial bread manufacturers exhibit highest price sensitivity; artisan bakery and food service accounts absorb premiums for clean-label positioning.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Malaysian palm oil plantations that supply 85% of global bakery shortening feedstocks. Raw material dependencies extend to Black Sea and North American wheat regions for high-protein bread flours, and to Chinese and Indian enzyme fermentation capacity for precision-fermented dough conditioners. Tariff exposure on palm oil imports into the EU creates supply chain risk. Distribution runs through industrial bakery direct contracts, regional food service distributors, and digital formulation platform aggregators serving artisan segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived enzymes are displacing azodicarbonamide and calcium peroxide in industrial bread applications, compressing legacy synthetic additive margins while expanding service-based revenue for technical formulation providers.
For Market Incumbents: To counter margin compression in commodity emulsifiers, accelerate captive supply integration into oilseed processing and enzyme fermentation capacity. Prioritize certification investment for organic and non-GMO substrate verification to defend premium positioning in German and French artisan channels. For New Entrants and Emerging Players: Mid-size bakery cooperatives in the UK and Netherlands represent underserved buyer archetypes seeking digital formulation platforms without minimum order constraints. Penetrate through specialized e-procurement portals that unbundle technical service from physical ingredient sales, targeting recipe-as-a-service subscription models. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation specialists with EFSA-approved enzyme portfolios in France and Germany. Long-term viability over the next decade rests on clean-label substitution momentum; monitor ECHA substance evaluation list expansions as inflection signals for accelerated DATEM and SSL replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill's captive supply of specialty shortenings insulates margin from palm oil futures volatility. |
| Precision Fermentation Capacity Expansion | Kerry Group's enzyme engineering advances enable clean-label dough conditioning without azodicarbonamide. |
| Digital Formulation Platform Launch | Recipe-as-a-service tools decouple technical expertise from physical ingredient sales for mid-size bakeries. |
| Organic Certification Investment | AB Mauri's certified ingredient grades capture premium positioning in German artisan channel expansion. |
| Regional Blending Operation Establishment | Local micronutrient premix facilities in Maharashtra serve India's BIS fortification mandates. |
Research Approach
Trade databases, ECHA regulatory filings, and customs export records formed the secondary backbone, cross-referenced with primary interviews involving bakery R&D directors, industrial procurement managers, food service distributor category leads, and enzyme fermentation technical officers. Bottom-up volume estimates from flour mill and emulsifier production data were reconciled with top-down demand aggregation across bread, cake, pastry, and cookie applications.
Historical trendline analysis tracked wheat protein content variability, palm oil price cycles, and enzyme approval timelines across the modeling period. Segmentation dimensions included functional ingredient type, finished application category, end-user channel structure, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth trajectories, incorporating climate-induced harvest quality fluctuations and fortification mandate implementation schedules as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA reauthorization delays, Black Sea wheat supply disruptions, and Indonesian palm oil export policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Edible Animal Fat Market
Ingredients
Modified Maize Starch Market
Ingredients
Carob Powder Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Canada Soy Protein Market
Ingredients
Agave Inulin Market
Ingredients
Food Minerals Market
Ingredients
Camelina Oil Market
Ingredients
Africa Fats and Oil Market
Ingredients
Vegetable Extract Market
Ingredients
Hops Market
Ingredients
Meat Extract Market
Ingredients
Food Grade Cassia Gum Powder Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Rose Extract Market
Ingredients
Global Tomato Powder Market