
 MENA Architectural Services Market | 2026-2036
MENA Architectural Services Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Architectural Services Market Insights
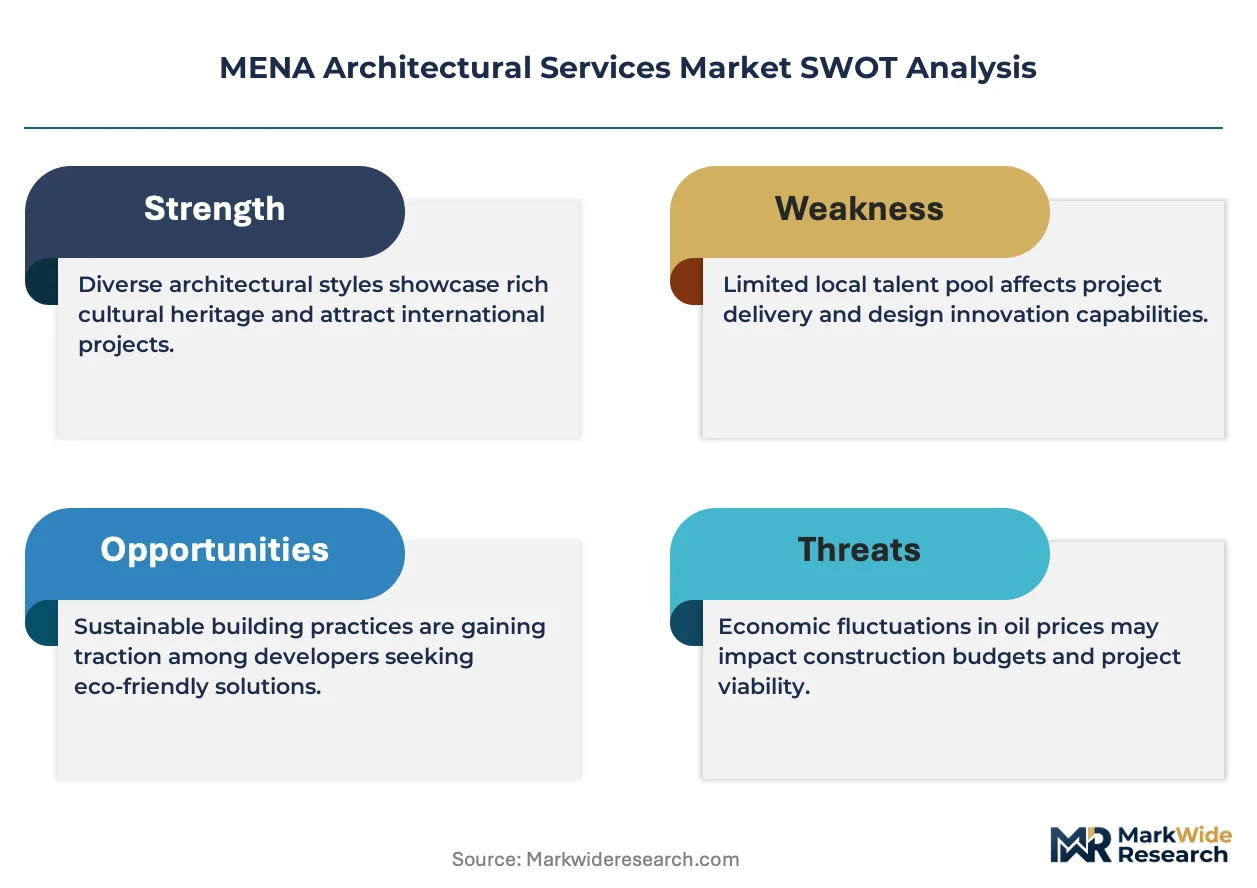
The gap between premium signature architecture and commoditized design documentation is realigning fee structures across the MENA region. AECOM Technology Corporation leverages its integrated engineering portfolio to capture complex mixed-use developments in Dubai and Riyadh. KEO International Consultants anchors its position through deep relationships with Kuwaiti and Qatari government clients. AtkinsRéalis Limited differentiates via digital delivery platforms that compress design-to-construction timelines on transport infrastructure.
Architectural services encompass the creative and technical planning of buildings and urban environments, integrating structural engineering coordination, environmental systems design, and spatial functionality to produce construction-ready documentation. These services translate client requirements into built form through iterative schematic design, design development, and construction administration phases. Design Services commands the largest fee pool across the MENA region, though Design-Build delivery models are expanding fastest as developers seek single-point accountability. Hospitality Projects generate premium margins due to brand-specific design standards and repeat client relationships with international hotel operators.
Saudi Arabia's Saudi Building Code and the UAE's Al Sa'fat green building framework are elevating technical competency requirements for market access, particularly in energy modeling and passive design. Egypt's new urban communities authority and Morocco's building energy codes are extending similar regulatory pressure westward across North Africa. Stakeholders must monitor how procurement digitization and local content requirements reshape competitive positioning in upcoming giga-project tenders.
Market Dynamics
The Saudi Building Code and UAE's Al Sa'fat regulations are compressing design-to-permit timelines across the MENA region. Developers now demand integrated energy modeling and passive design documentation as standard deliverables, not premium add-ons.
Growth Catalysts
- Giga-project pipelines:Saudi Vision 2030 developments in Riyadh and Jeddah are generating sustained fee volume for master planning and schematic design services. NEOM and Qiddiya alone account for substantial design documentation requirements.
- Al Sa'fat compliance mandates:Dubai's green building regulations now require energy performance modeling for all new commercial developments above 2,000 square meters. This creates mandatory technical scope expansion for local practices.
- Design-Build procurement:Single-point accountability contracts are displacing traditional design-bid-build sequences across GCC transport and mixed-use developments. Contractors now absorb architectural risk.
Market Restraints
- Specialized talent scarcity:Energy modeling and BIM coordination skills concentrate in Beirut and Cairo, creating recruitment friction for Riyadh and Dubai practices. Salary arbitrage is compressing margin structures.
- Steel and aluminum input volatility:Façade system specifications face cost uncertainty from regional smelter capacity constraints. Project feasibility studies require frequent repricing.
- Payment cycle elongation:Government clients in Kuwait and Qatar extend design fee disbursement to 90-120 day terms. Working capital intensity favors larger integrated firms.
Strategic Opportunities
- Egypt's new urban communities:The administrative capital and fourth-generation cities west of Cairo lack established local design capacity. International practices can anchor early relationships before domestic competition matures.
- Digital twin convergence:BIM-to-FM handover requirements on Saudi giga-projects are creating demand for asset information modeling specialists. Practices with computational design capability capture premium scope.
- Morocco building energy codes:Casablanca and Rabat are extending technical mandates similar to GCC frameworks. Early regulatory alignment positions firms for North African expansion.
Industry Challenges
- BIM coordination complexity:Multi-disciplinary model federation requires investment in clash detection software and dedicated digital delivery teams. Mid-sized practices face capability gaps.
- Saudi Building Code certification timelines:Third-party energy compliance review adds 6-8 weeks to permit submission cycles. Project schedules compress design development phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Architectural Services Market |
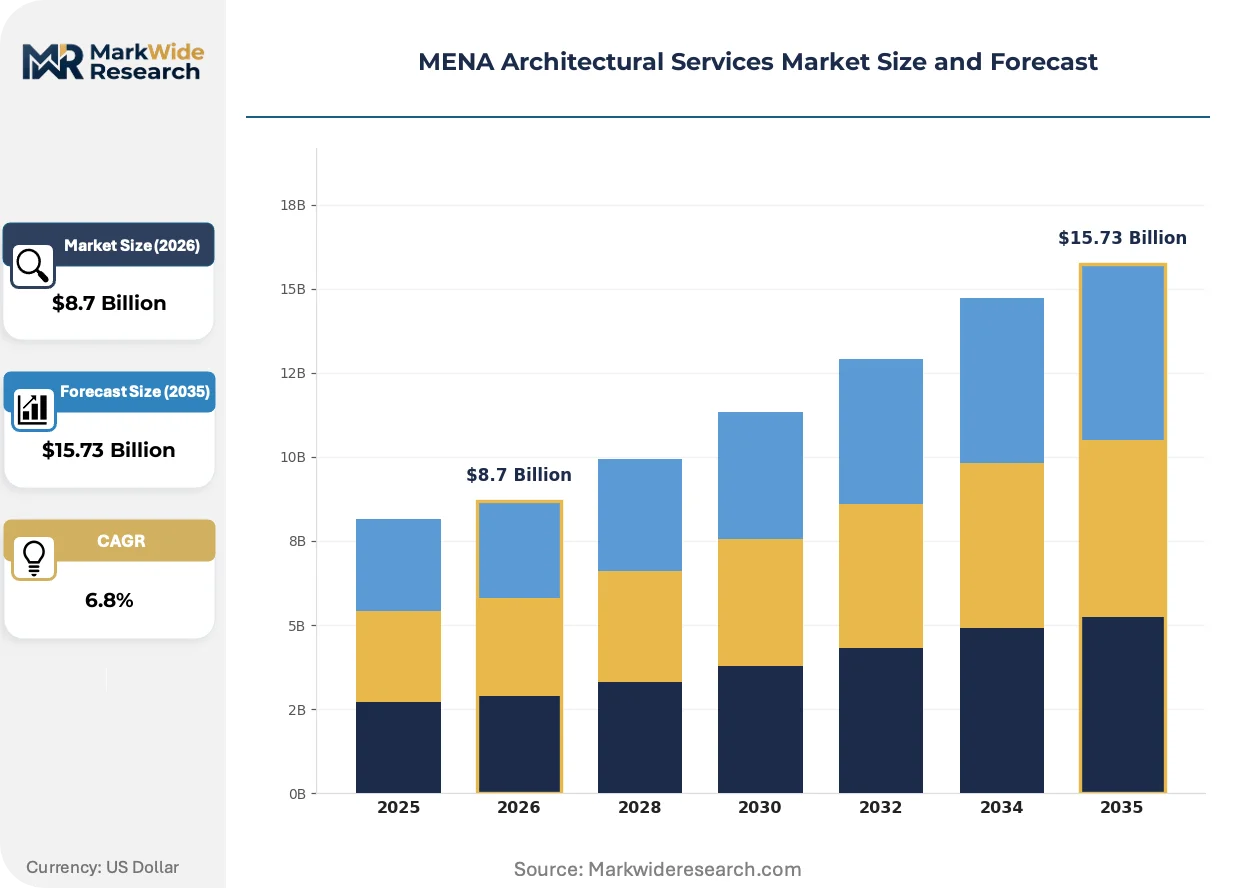
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Services, Consulting, Urban Planning, Landscape Architecture Project Type: Residential Buildings, Commercial Spaces, Hospitality Projects, Institutional Structures End User: Government Organizations, Private Developers, Non-Profit Entities, Educational Institutions Delivery Model: Design-Bid-Build, Design-Build, Build-Operate-Transfer, Construction Management |
| Companies Covered | AECOM Technology Corporation, KEO International Consultants, AtkinsRéalis Limited, DSA Architects Intl, HKS Inc, Omrania and Associates, Foster + Partners Limited, RMJM Inc, Lacasa Architects & Engineering Consultants, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Architectural Services Market Trends and Innovations
Computational design tools and generative algorithms are displacing manual schematic iteration across premium MENA developments. Regulatory digitization is compressing compliance verification timelines.
Parametric design software is expanding into massing optimization and daylighting analysis on Saudi giga-projects. King Abdullah Financial District developers now mandate algorithmic optioneering for tower envelopes. This capability is expanding into fee structures that reward performance outcomes rather than drawing production.
Al Sa'fat and the Saudi Building Code are mandating post-occupancy energy verification for commercial developments above specified thresholds. Dubai Municipality now requires as-built thermal imaging and air leakage testing documentation. Hospitality and healthcare segments are responding with integrated commissioning scope in original design contracts.
Developer procurement teams are unbundling design services from construction management on complex mixed-use assets. Single-source design-build contracts face scrutiny from institutional investors seeking clearer cost accountability. This pattern is most visible in Riyadh's Diriyah Gate and Jeddah Central developments, where separate design and construction contracts are re-emerging.
MENA Architectural Services Market Segmentation
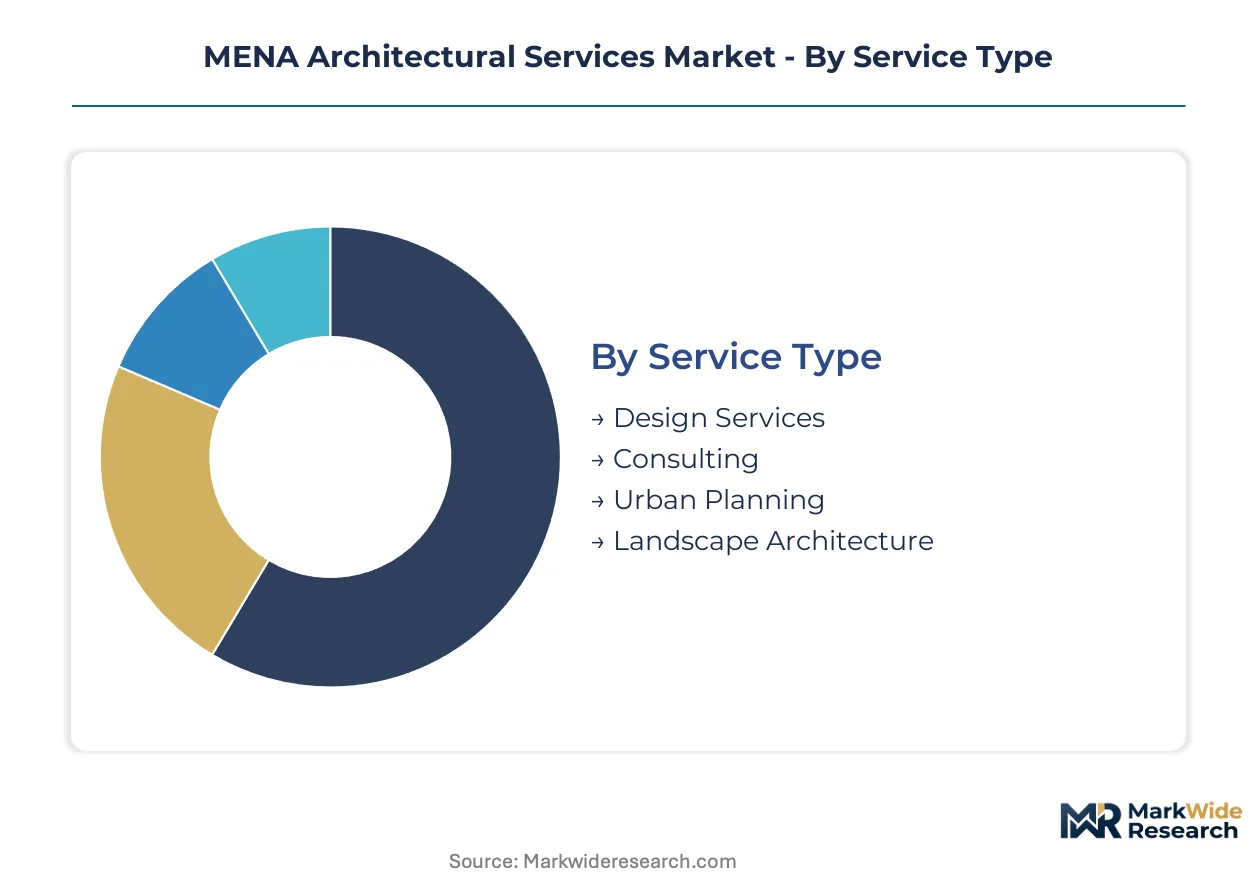
Fee structures and technical competency requirements vary sharply across service categories in the MENA architectural services market. Procurement digitization and regulatory mandates are compressing traditional segment boundaries, particularly where energy modeling and BIM coordination intersect with delivery models.
Service Type:
Technical sophistication and documentation depth define competitive positioning across service categories.
- Design Services:Schematic design through construction documentation forms the core fee pool, with Saudi giga-projects demanding algorithmic massing studies and daylighting optimization as standard deliverables. Riyadh and Jeddah developers now require energy performance modeling for permit submission under the Saudi Building Code.
- Consulting:Technical advisory on regulatory compliance and sustainability certification commands premium rates as Al Sa'fat mandates expand across Dubai commercial developments above 2,000 square meters.
- Urban Planning:Master planning for new urban communities in Egypt and fourth-generation cities west of Cairo generates sustained engagement for international practices establishing early relationships.
- Landscape Architecture:Integrated hardscape and softscape design supports hospitality and mixed-use developments seeking biophilic credentials and outdoor amenity differentiation.
Mature deployment sits with Design Services. Newer deployment is concentrated in Consulting.
Project Type:
Margin structures and client retention patterns diverge significantly by asset class complexity.
- Hospitality Projects:Brand-specific design standards and repeat relationships with international hotel operators generate premium margins and multi-phase engagement continuity across Riyadh and Dubai developments.
- Commercial Spaces:Office and retail assets face compressed design-to-permit timelines as Dubai Municipality mandates as-built thermal imaging and air leakage testing documentation for compliance verification.
- Residential Buildings:High-volume housing developments in Saudi Arabia's giga-projects prioritize standardization and speed over bespoke architectural expression.
- Institutional Structures:Healthcare and education facilities require specialized technical coordination for MEP integration and regulatory compliance across Kuwait and Qatar government procurement cycles.
Revenue concentration favors Hospitality Projects. Volume expansion is climbing fastest in Commercial Spaces.
End User:
Procurement sophistication and payment terms shape practice selection criteria across client categories.
- Government Organizations:Extended fee disbursement cycles of 90-120 days in Kuwait and Qatar favor larger integrated firms with working capital depth.
- Private Developers:Institutional investors in Riyadh's Diriyah Gate and Jeddah Central developments are unbundling design from construction management, re-emphasizing separate contract accountability.
- Non-Profit Entities:Cultural and heritage projects often prioritize design excellence over speed, sustaining boutique practice participation.
- Educational Institutions:Campus master planning and research facility design require long-term relationship cultivation with established technical credentials.
Contract volume concentrates with Government Organizations. Procurement innovation is expanding most quickly among Private Developers.
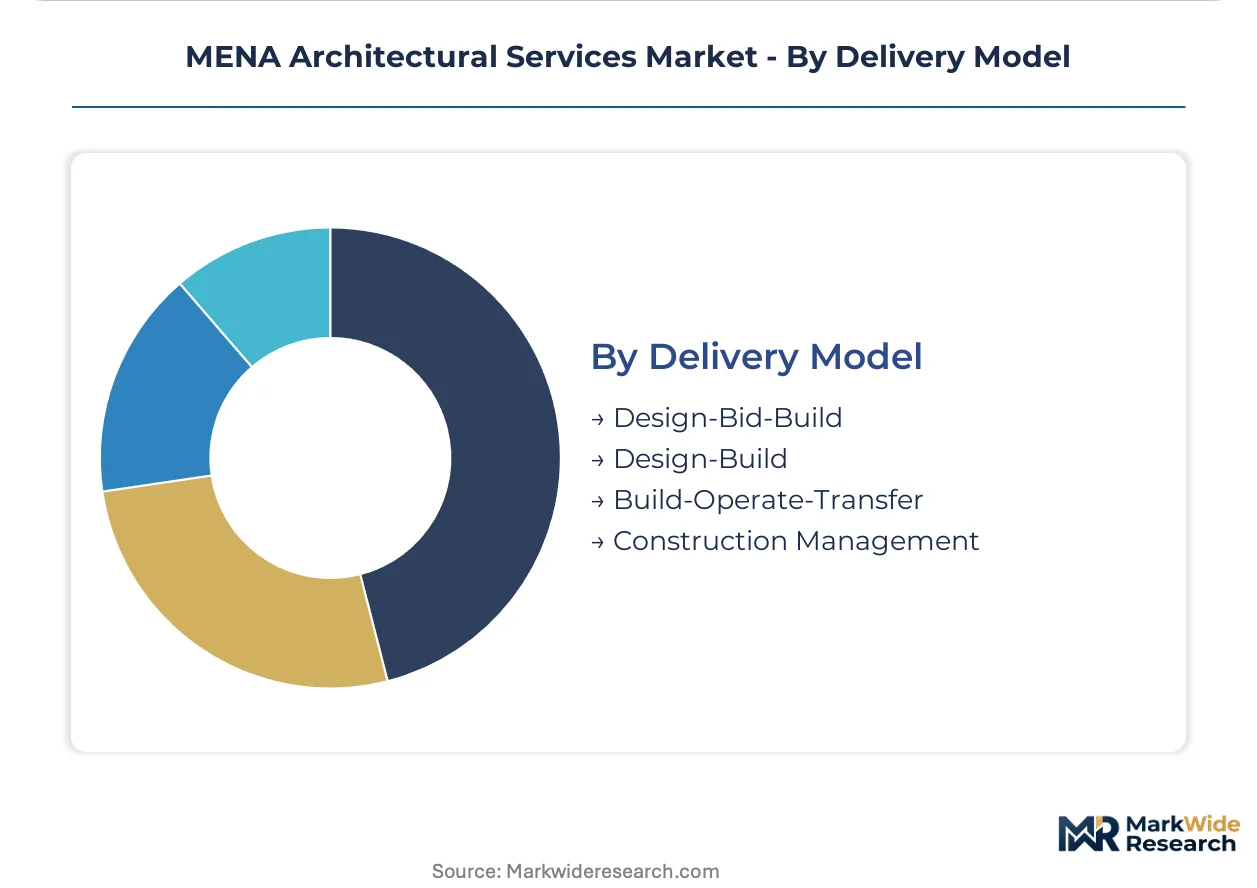
Delivery Model:
Risk allocation and single-point accountability are reconfiguring traditional procurement sequences across the GCC.
- Design-Build:Single-source contracts are displacing traditional sequences across transport and mixed-use developments, with contractors now absorbing architectural risk and compressing design-to-construction timelines.
- Design-Bid-Build:Separate design and construction contracts are re-emerging in complex mixed-use assets where institutional investors seek clearer cost accountability and transparent fee structures.
- Construction Management:Agency-style delivery with owner-contractor direct relationships requires sophisticated owner representation capabilities that mid-sized practices struggle to resource.
- Build-Operate-Transfer:Long-term concession structures for infrastructure and hospitality assets demand financial modeling expertise beyond traditional architectural scope.
Established deployment favors Design-Bid-Build. Market share is shifting fastest toward Design-Build.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh and Jeddah dominate fee generation as Saudi Vision 2030 giga-projects absorb design capacity across the GCC. The Saudi Building Code and UAE's Al Sa'fat regulations are elevating technical requirements from Cairo to Casablanca.
Saudi Arabia
NEOM and Qiddiya developments generate sustained master planning demand in Riyadh and Jeddah. The Saudi Building Code mandates energy performance modeling for all commercial permits above 2,000 square meters. King Abdullah Financial District developers now require algorithmic massing studies as standard deliverables.
United Arab Emirates
Dubai's hospitality and mixed-use pipeline sustains premium-margin design work despite completion rate normalization. Al Sa'fat regulations from Dubai Municipality require as-built thermal imaging and air leakage testing for commercial assets. DIFC and Business Bay clusters concentrate repeat client relationships with international hotel operators.
Egypt
The administrative capital and fourth-generation cities west of Cairo lack established local design capacity. The new urban communities authority extends technical mandates similar to GCC frameworks. International practices anchor early relationships before domestic competition matures in these greenfield developments.
Qatar
Government procurement cycles for healthcare and education facilities sustain institutional project pipelines in Doha. Extended fee disbursement terms of 90-120 days favor larger integrated firms with working capital depth. Lusail City and Education City clusters concentrate specialized MEP coordination requirements.
Morocco
Casablanca and Rabat extend building energy codes comparable to GCC regulatory pressure. Early regulatory alignment positions firms for North African expansion from established Middle East operations. Tangier-Med industrial zone and Casablanca Finance City generate commercial and logistics facility design demand.
MENA Architectural Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical competency and delivery model sophistication. The vendor base separates into three tiers: integrated engineering-architecture conglomerates with GCC government relationships, mid-sized specialists in hospitality or healthcare verticals, and documentation-focused practices competing on speed. Two dominant competitive moves are reshaping positioning: procurement digitization requiring BIM-to-FM capability investment, and local content requirements in Saudi giga-project tenders forcing joint venture structures.
Within the integrated conglomerate tier, AECOM Technology Corporation and AtkinsRéalis Limited occupy positions defined by engineering-architecture bundling and digital delivery platforms. KEO International Consultants exemplifies the government-relationship archetype through deep Kuwaiti and Qatari client anchoring. These three represent distinct strategic vectors—technical integration, digital compression, and institutional relationship depth—that other competitors must match or circumvent.
| Leading Market Players |
|---|
| AECOM Technology Corporation |
| KEO International Consultants |
| AtkinsRéalis Limited |
| DSA Architects Intl |
| HKS Inc |
| Omrania and Associates |
| Foster + Partners Limited |
| RMJM Inc |
| Lacasa Architects & Engineering Consultants |
| Others |
Pricing and Supply Chain Analysis
Signature-to-commodity divergence across the MENA architectural services market manifests in fee structures that reward algorithmic massing capability while compressing documentation-only margins, with procurement digitization and Saudi Building Code compliance requirements simultaneously elevating technical investment thresholds and supplier consolidation pressures.
Pricing Analysis
Outcome-linked fee structures now dominate premium engagements, with King Abdullah Financial District developers mandating algorithmic optioneering for tower envelopes and tying compensation to daylighting performance metrics. Price differentiation rests on BIM-to-FM handover capability and energy modeling certification tier under Saudi Building Code and Al Sa'fat frameworks. Cost compression in schematic documentation runs through Cairo and Beirut talent arbitrage. Government clients in Kuwait and Qatar exhibit lowest price sensitivity due to extended 90-120 day disbursement cycles; mid-sized practices face acute margin pressure from working capital intensity.
Supply Chain Analysis
Saudi local content requirements are reshaping sourcing patterns for steel and aluminum façade systems, forcing joint venture structures with domestic fabricators. Material supply concentrates in UAE, Saudi Arabia, and Egypt for processed metals; specialized glazing draws from Italy and Germany. Raw material dependencies span aluminum billet, low-iron glass, and high-performance coating chemistries. Single-source vulnerability sits with regional smelter capacity constraints. Distribution runs through contractor-led procurement on design-build contracts and developer direct relationships on unbundled engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MENA architectural services market is consolidating around technical competency barriers, with Saudi Building Code certification timelines and BIM coordination complexity forcing documentation-focused practices toward acquisition or exit.
For Market Incumbents: To counter talent arbitrage from Cairo and Beirut compressing margin structures, anchor position through captive energy modeling capability investment and algorithmic design tool deployment. Prioritize Saudi giga-project joint venture structures that satisfy local content mandates while retaining technical control. Deepen relationships with institutional investors in Riyadh's Diriyah Gate and Jeddah Central developments who are unbundling design from construction management. For New Entrants and Emerging Players: The premium-to-commodity price-point gap in hospitality and healthcare verticals offers white-space entry before incumbent lock-in solidifies. Target Egypt's administrative capital and fourth-generation cities west of Cairo where established local design capacity remains absent. Pursue digital twin and asset information modeling specialization as the go-to-market angle, positioning for BIM-to-FM handover requirements on Saudi giga-projects. For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized specialists possessing hospitality or healthcare vertical depth and nascent computational design capability given regulatory digitization compressing compliance timelines. Long-term viability favors practices with GCC government relationship anchoring and working capital depth to absorb extended disbursement cycles. Monitor Saudi giga-project tender local content requirement enforcement as the signal for joint venture structure proliferation.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Design Capability Investment | King Abdullah Financial District developers now mandate parametric massing studies as standard deliverables. |
| BIM-to-FM Platform Development | Saudi giga-projects require asset information modeling specialists for digital twin handover compliance. |
| Local Content Joint Venture Formation | Saudi tender requirements force foreign practices into domestic partnership structures for market access. |
| Energy Modeling Certification Acquisition | Al Sa'fat and Saudi Building Code mandates elevate technical credentialing to mandatory scope. |
| Hospitality Vertical Specialization | Brand-specific design standards with international hotel operators generate premium-margin repeat engagements. |
Research Methodology
Independent corroboration across primary interviews with design firm principals, government procurement officers, and developer project directors, combined with secondary validation from Dubai Municipality regulatory filings, Saudi Building Code documentation, and GCC construction project databases, underwrites the qualitative findings. Bottom-up fee pool estimates triangulate against top-down market sizing from regional AEC industry reports and professional services trade data.
Comparable historical reference periods anchor the projection horizon, with growth trajectories modeled across service type, project type, end user, and delivery model segmentation dimensions. CAGRs derive from trend extrapolation adjusted for regulatory mandate implementation timelines and giga-project pipeline visibility. Forecast inputs incorporate procurement digitization adoption curves and local content requirement enforcement intensity.
Inputs from developer procurement teams and design firm financial officers were available through the study window; gaps in private practice margin disclosure introduce uncertainty bands around competitive intensity assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Industrial Maintenance Products Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Construction Project Management Services Market
Construction Services
Work Order Management Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
NDT and Inspection Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Condenser Cleaners Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Global Pipeline Maintenance Services Market