
 Europe Maintenance, Repair, and Operations (MRO) Market | 2026-2036
Europe Maintenance, Repair, and Operations (MRO) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Maintenance, Repair, and Operations (MRO) Market Insights
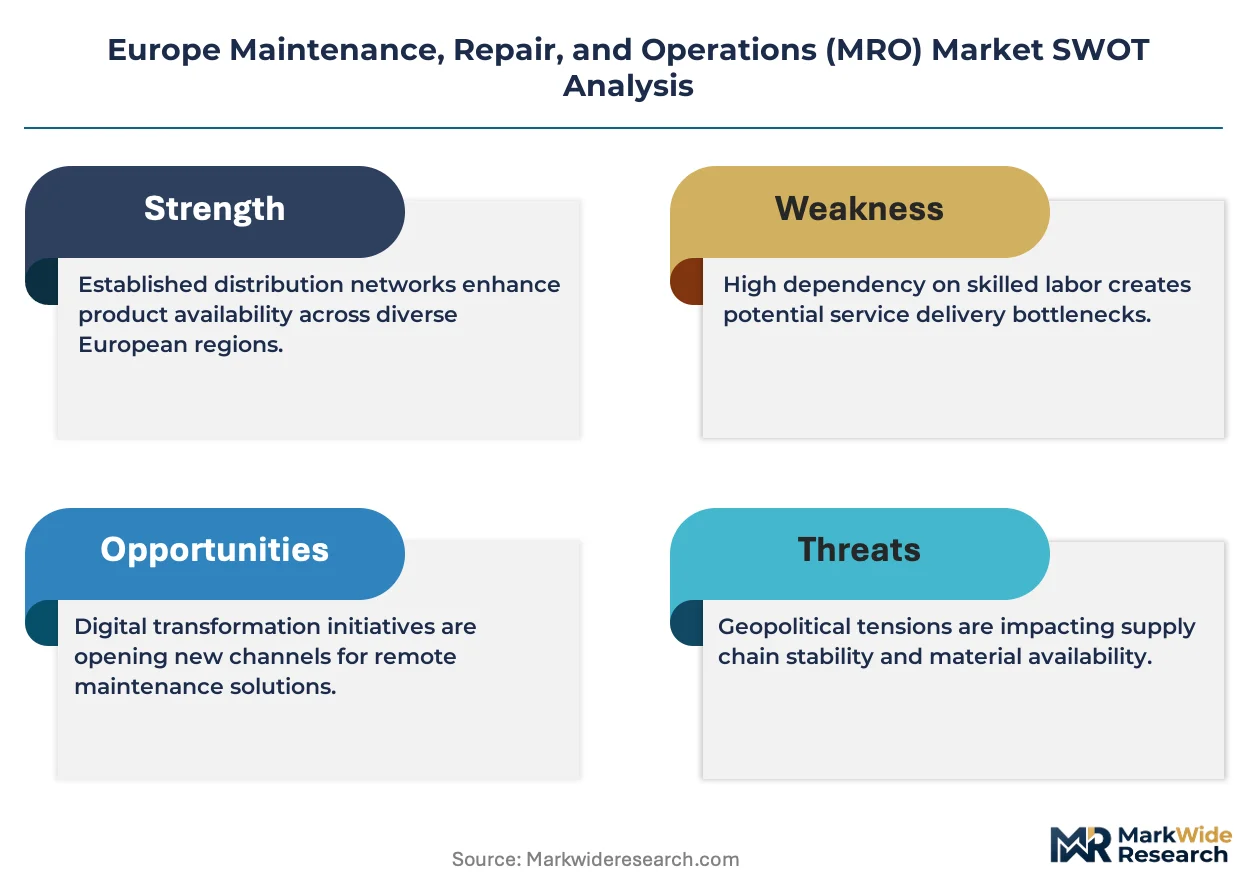
Multi-source procurement is broadening across European industrial procurement departments as buyers reduce dependency on single distributors. Wurth Group GmbH leverages its captive manufacturing network to control quality across fasteners and chemicals. Sonepar SA anchors its position through extensive branch density across France and Southern Europe. Rexel SA competes on digital platform integration, linking inventory to customer ERP systems in real time.
Maintenance, Repair, and Operations encompasses the technical supply, servicing, and upkeep of production assets through scheduled interventions, spare part replacement, and consumable replenishment to sustain operational uptime. MRO procurement typically involves thousands of SKUs spanning fasteners, lubricants, bearings, and pneumatic components, with inventory turns and stockout risk as critical performance parameters. The spare parts category within Product Type dominates working capital allocation, while consumables generate the highest transaction frequency and channel loyalty. Inspection services under Service Type command premium pricing due to certified technician requirements and liability exposure in aerospace and energy applications.
REACH and RoHS frameworks restrict chemical compositions in MRO consumables, compelling distributors to validate supplier compliance documentation across their catalogs. The EU Green Deal and national carbon accounting rules under CSRD push industrial buyers toward condition-based maintenance to minimize energy waste from equipment degradation. Stakeholders must weigh whether to build predictive analytics capabilities in-house or embed them through distributor partnerships as regulatory compliance tightens.
Market Dynamics
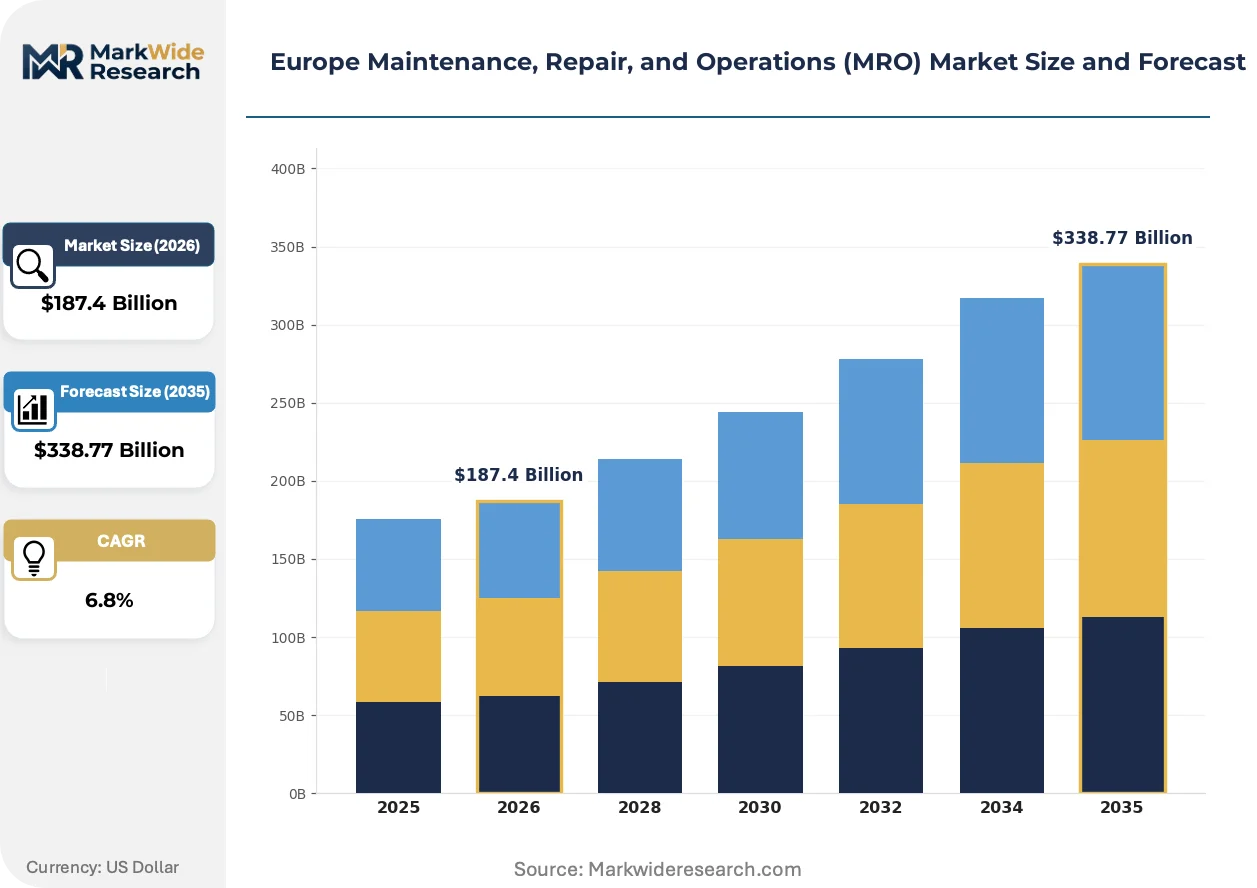
Industrial decarbonization mandates under the EU Green Deal are forcing European manufacturing facilities to retrofit legacy equipment with predictive maintenance systems, compressing traditional reactive service models and redistributing MRO procurement budgets toward condition-monitoring technologies.
Growth Catalysts
- CSRD carbon accounting rules:Mandatory Scope 1 and 2 emissions disclosure for large EU enterprises accelerates investment in energy-efficient bearing and lubricant replacements to cut equipment degradation waste.
- Aerospace corridor concentration:Toulouse and Bordeaux maintenance clusters generate concentrated demand for certified inspection services and specialized fasteners in France's civil aviation supply chain.
- IoT sensor deployment:Vibration and thermal monitoring hardware is automating failure prediction across German automotive OEM outsourced maintenance contracts.
Market Restraints
- Specialized alloy supply concentration:Aerospace-grade titanium fastener stock depends on a narrow supplier base in Southern Europe, exposing buyers to allocation risk during raw material shocks.
- REACH compliance documentation burden:Chemical distributors must validate full substance composition across thousands of MRO SKUs, extending catalog onboarding timelines and freezing niche product availability.
- Skilled technician scarcity:Certified thermography and ultrasonic inspection capacity lags demand growth in Poland and Czech industrial zones, capping service expansion.
Strategic Opportunities
- Portuguese and Greek industrial zones:Underpenetrated secondary manufacturing regions lack dense distributor branch networks, creating whitespace for digital-first inventory platforms with local fulfillment partnerships.
- AI-driven spare parts forecasting:Machine learning convergence with ERP integration enables distributors to offer guaranteed availability contracts, shifting procurement from transactional to subscription models.
- F-Gas Regulation retrofit wave:Industrial refrigeration and HVAC asset replacement mandates open captive service contract opportunities for compliant refrigerant and compressor suppliers.
Industry Challenges
- Legacy ERP integration complexity:Real-time inventory API connections between distributor platforms and buyer systems require costly middleware development, slowing digital procurement adoption among mid-cap manufacturers.
- Multi-site certification synchronization:Aerospace and energy MRO providers must maintain parallel AS9100 and ISO 45001 audits across scattered European facilities, fragmenting quality management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Maintenance, Repair, and Operations (MRO) Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Maintenance, Repair, Overhaul Industry Vertical: Aerospace, Automotive, Construction, Manufacturing Product Type: Tools, Spare Parts, Consumables, Equipment Delivery Model: On-site, Remote, Mobile, Fixed |
| Companies Covered | Wurth Group GmbH, Sonepar SA, Rexel SA, WESCO International Inc., Eriks NV, RS Group plc, Descours and Cabaud, Rubix, Ferguson PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Maintenance, Repair, and Operations (MRO) Market Trends and Innovations
Digital thread technologies are compressing the gap between asset performance data and procurement execution, enabling European industrial buyers to shift from calendar-based maintenance toward condition-triggered spare part replenishment cycles.
Edge computing architectures embedded in production equipment are automating anomaly detection at the source, eliminating latency to cloud analytics. German automotive plants and French aerospace subcontractors are deploying these systems fastest, with pilot programs expanding to full-line coverage within eighteen-month windows. The technology is automating manual inspection rounds and compressing mean-time-to-repair metrics by triggering pre-positioned spare part shipments before failure occurs.
REACH authorization sunset clauses are phasing out chromate conversion coatings and certain solvent-based cleaners from approved MRO chemical lists. Industrial buyers in metalworking and surface treatment must qualify replacement formulations under compressed regulatory timelines, with ECHA scrutiny intensifying for imported maintenance consumables. The restriction most impacts small-batch custom fabricators in Northern Italy and Benelux regions with legacy process equipment.
Consolidated procurement desks are displacing plant-level purchasing autonomy across European manufacturing groups. Centralized category managers now negotiate framework agreements covering fasteners, bearings, and PPE across multiple country operations, compressing distributor margin through volume concentration. The shift is most visible in German Mittelstand conglomerates and Nordic industrial holding companies with cross-border production footprints.
Europe Maintenance, Repair, and Operations (MRO) Market Segmentation
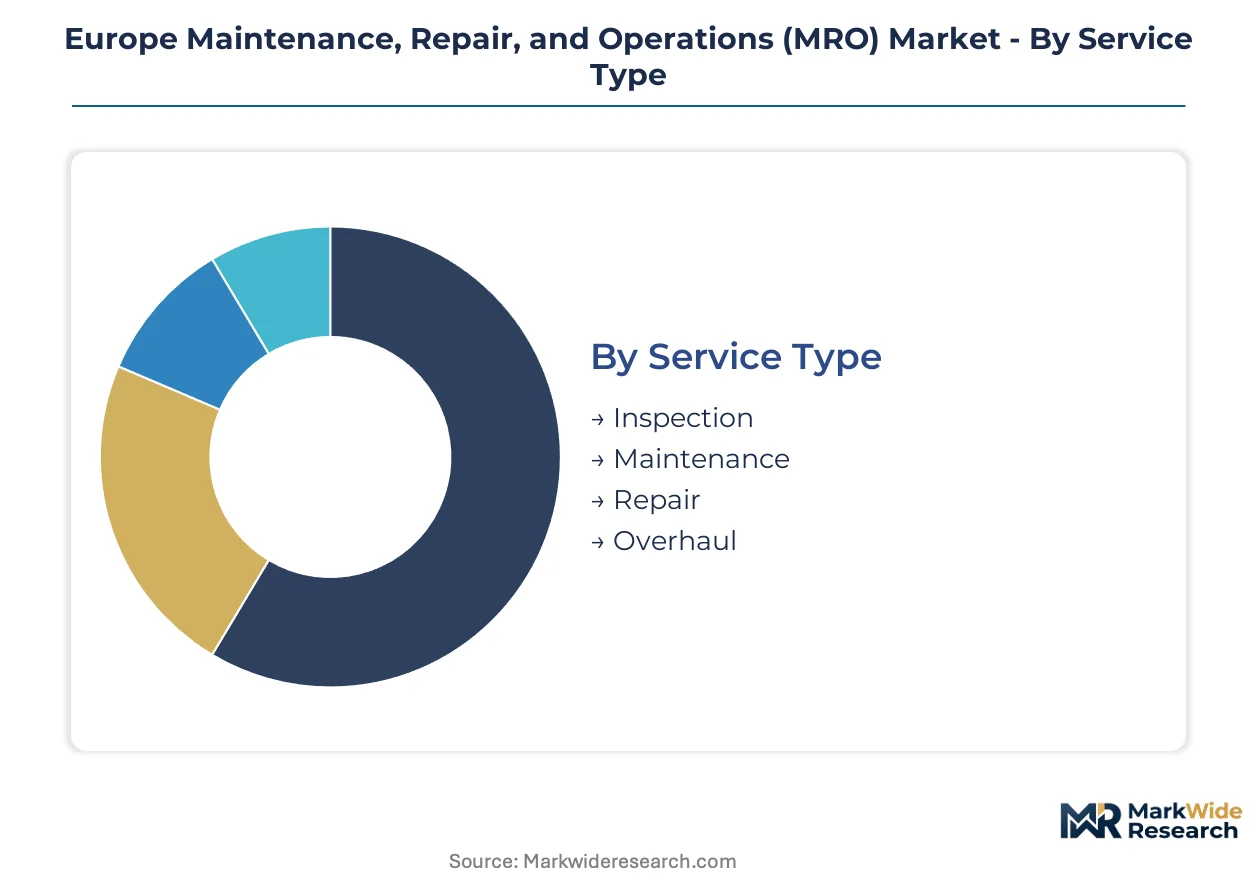
European MRO procurement splits across four critical dimensions that determine vendor selection criteria and contract structures. Buyers weight technical certification requirements differently across aerospace, automotive, and heavy manufacturing verticals. Delivery model choices increasingly hinge on inventory velocity needs versus total cost of service ownership.
Service Type:
Buyers prioritize liability coverage and technician certification grade when allocating service budgets across intervention categories.
- Inspection:Thermography, ultrasonic testing, and borescope examinations require AS9100 or ISO 45001 certified personnel. Demand concentrates in Toulouse and Bordeaux aerospace clusters where airworthiness mandates drive recurring non-destructive testing contracts. CSRD carbon accounting rules accelerate thermography adoption for detecting energy waste from compressed air leaks and thermal bridging in German automotive plants.
- Maintenance:Scheduled preventive interventions encompass lubrication, alignment, and filter replacement programs. Polish and Czech industrial zones face technician scarcity that caps service expansion despite rising manufacturing output. IoT sensor deployment across German OEM outsourced contracts automates maintenance triggering and compresses traditional calendar-based scheduling.
- Repair:Corrective interventions restore failed assets to operational status through component replacement or refurbishment. Metalworking facilities in Northern Italy and Benelux navigate REACH authorization sunset clauses when qualifying replacement chemical formulations for surface treatment repair processes.
- Overhaul:Comprehensive asset rebuilding extends equipment lifecycle through systematic component replacement and recalibration. French aerospace subcontractors leverage edge computing pilot programs to predict overhaul timing before catastrophic failure occurs.
Volume sits with Maintenance; growth tilts toward Inspection.
Industry Vertical:
End-use concentration shapes regional distributor branch density and specialized inventory investment.
- Aerospace:Airframe and engine maintenance demands certified fasteners, specialized alloys, and traceable documentation chains. Toulouse and Bordeaux maintenance clusters generate concentrated procurement of titanium fasteners and chromate-free conversion coatings under REACH pressure.
- Automotive:Powertrain and assembly line uptime requirements drive high-frequency consumable replenishment and predictive bearing replacement. German OEMs expand outsourced MRO procurement to cut fixed costs while deploying vibration monitoring hardware across production networks.
- Construction:Heavy equipment fleets require mobile service capabilities and ruggedized component logistics. Portuguese and Greek industrial zones present whitespace for digital-first inventory platforms with local fulfillment partnerships.
- Manufacturing:Diverse production assets span CNC machinery, material handling systems, and process control equipment. Consolidated procurement desks across German Mittelstand conglomerates displace plant-level purchasing autonomy through centralized category management.
Aerospace commands premium pricing; manufacturing delivers transaction scale.
Product Type:
Working capital allocation and inventory turn velocity diverge sharply across physical goods categories.
- Spare Parts:Bearings, seals, gears, and precision components tie up substantial balance sheet resources through safety stock requirements. German automotive plants pre-position critical spares based on edge-computed failure predictions, compressing mean-time-to-repair metrics.
- Consumables:Lubricants, adhesives, abrasives, and cleaning chemicals generate highest transaction frequency and channel loyalty. REACH compliance documentation burdens extend catalog onboarding timelines for chemical distributors serving metalworking fabricators.
- Tools:Hand tools, power tools, and precision measurement instruments require calibration tracking and lifecycle management systems. Nordic industrial holding companies with cross-border footprints centralize tool procurement through framework agreements.
- Equipment:Capital asset replacements including compressors, pumps, and HVAC systems trigger F-Gas Regulation retrofit opportunities. Industrial refrigeration mandates open captive service contracts for compliant refrigerant and compressor suppliers.
Spare Parts dominate capital allocation; Consumables drive purchase frequency.
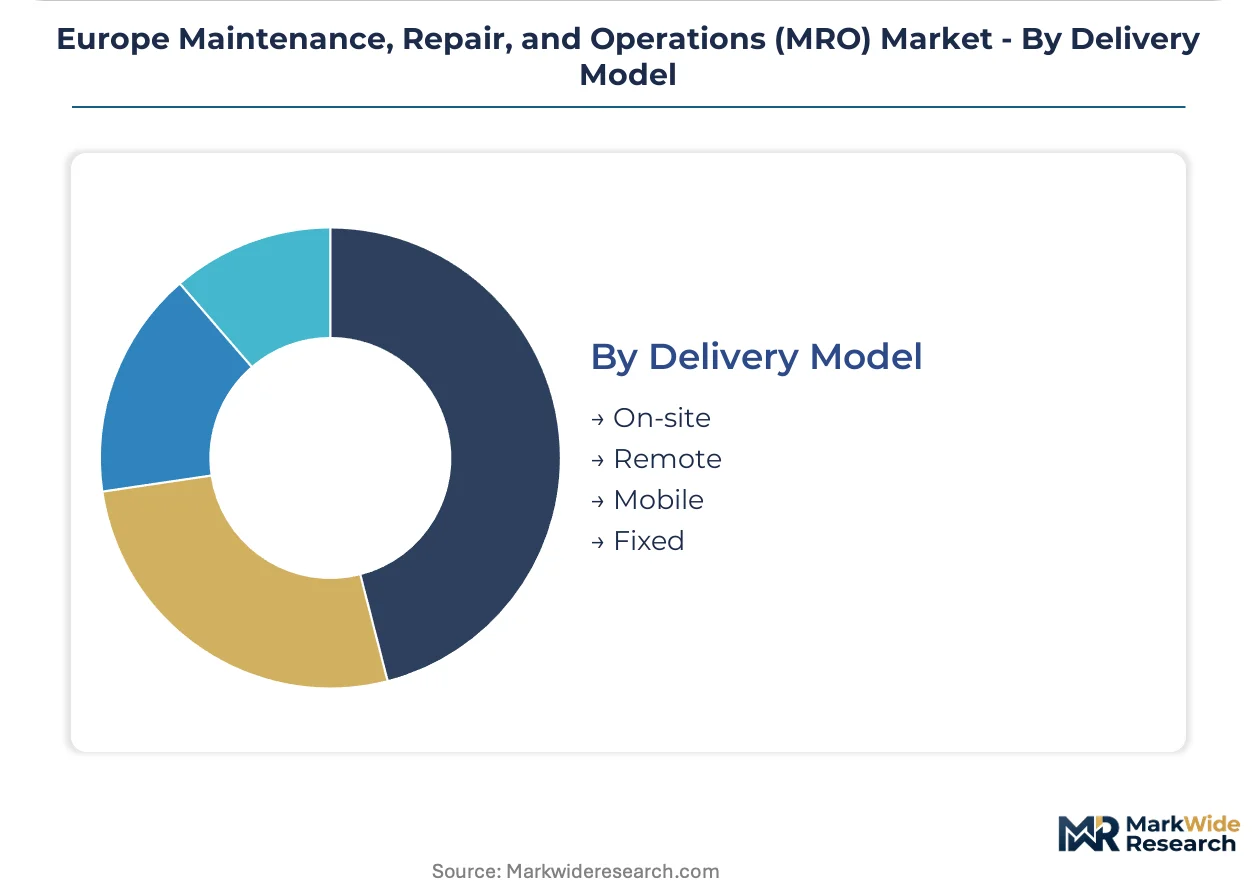
Delivery Model:
Proximity requirements and response time guarantees determine logistics infrastructure investment.
- On-site:Embedded technician teams and consigned inventory programs eliminate procurement friction for critical production lines. French aerospace subcontractors deploy full-line edge computing coverage within compressed implementation windows.
- Remote:Digital diagnostics and augmented reality guidance reduce travel requirements for standard troubleshooting. Real-time inventory API connections between distributor platforms and buyer ERP systems enable remote availability confirmation.
- Mobile:Rapid-response service vehicles carry diagnostic equipment and high-velocity SKUs to dispersed industrial facilities. Sonepar SA anchors Southern European coverage through extensive branch density supporting mobile fulfillment.
- Fixed:Centralized service depots and regional distribution centers optimize inventory pooling across customer portfolios. Rexel SA competes through digital platform integration linking fixed-location inventory to customer systems.
Fixed infrastructure handles inventory depth; mobile capabilities capture emergency response premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium fastener stock from Southern European suppliers anchors aerospace-grade MRO procurement across the continent. REACH compliance documentation burdens and CSRD carbon accounting rules reshape national distributor strategies. Industrial clusters concentrate demand in specific corridors.
Germany
Automotive OEM outsourced maintenance contracts and IoT sensor deployment drive predictive bearing replacement programs. KBA vehicle safety standards intersect with CSRD Scope 1 and 2 disclosure mandates for manufacturing equipment efficiency. Stuttgart and Wolfsburg production networks compress mean-time-to-repair through edge-computed failure predictions.
France
Toulouse and Bordeaux aerospace corridors generate concentrated procurement of certified fasteners and non-destructive testing services. ECHA scrutiny intensifies for chromate-free conversion coating formulations under REACH authorization timelines. The Île-de-France manufacturing belt consolidates procurement desks across Mittelstand-style conglomerates.
United Kingdom
North Sea energy asset maintenance and offshore wind expansion sustain demand for corrosion-resistant fasteners and inspection capacity. HSE workplace safety regulations overlay EU-originated REACH compliance requirements for chemical distributors. Midlands manufacturing zones face technician scarcity in thermography and ultrasonic testing certification.
Italy
Metalworking fabricators in Northern Italy navigate REACH sunset clauses for solvent-based cleaners and surface treatment chemicals. ANSM industrial chemical oversight converges with EU Green Deal decarbonization targets for equipment retrofit. Lombardy and Piedmont machinery districts centralize tool procurement through Nordic-style holding company frameworks.
Poland
Manufacturing output expansion in the Silesian and Łódź industrial zones outpaces certified inspection technician availability. National carbon accounting preparations align with impending CSRD adoption timelines for large enterprises. German automotive supply chain spillover sustains bearing and pneumatic component demand growth.
Europe Maintenance, Repair, and Operations (MRO) Market Competitive Landscape
Multi-source procurement expansion dominates the current landscape as buyers reduce single-distributor dependency. The vendor base organizes into three tiers: integrated manufacturers with captive production networks, branch-dense national distributors, and digital-first inventory platforms. Strategic archetypes include quality-controlled manufacturing specialists, ERP-integrated logistics providers, and regional coverage aggregators. Competitive moves center on geographic whitespace penetration and predictive analytics capability embedding.
Within the integrated manufacturing tier, Wurth Group GmbH exemplifies captive network control over fasteners and chemicals. Sonepar SA and Rexel SA anchor the branch-density and digital-platform vectors respectively, with the former emphasizing Southern European physical presence and the latter competing through real-time ERP connectivity. These three entities represent distinct strategic positions without implying specific market share figures or operational details.
| Leading Market Players |
|---|
| Wurth Group GmbH |
| Sonepar SA |
| Rexel SA |
| WESCO International Inc. |
| Eriks NV |
| RS Group plc |
| Descours and Cabaud |
| Rubix |
| Ferguson PLC |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between AS9100-aerospace and standard-industrial MRO tiers manifests in bundled service pricing for inspection capacity and fragmented sourcing for commodity fasteners. REACH compliance documentation burdens and titanium fastener supply concentration reshape procurement economics across both premium and volume segments.
Pricing Analysis
Warranty and service-bundling splits predictive maintenance subscriptions from transactional spare part procurement. Three-tier pricing structure across premium, standard, and economy levels reflects technician certification grade, inventory velocity guarantees, and geographic delivery radius. Pricing pressure stems from consolidated procurement desks compressing distributor margins through multi-site framework agreements. Mid-cap manufacturers exhibit highest price sensitivity due to legacy ERP integration costs, while aerospace subcontractors absorb premiums for traceable documentation chains.
Supply Chain Analysis
Single-source vulnerability sits with Southern European titanium fastener suppliers serving Toulouse and Bordeaux aerospace clusters. Production draws from Germany, France, and Poland for precision components, with specialty alloy feedstock anchored in Southern Europe. REACH authorization sunset clauses for chromate conversion coatings constitute the dominant regulatory supply risk. Distribution runs through branch-dense national networks with digital platform integration for ERP-linked inventory visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity across Polish and Czech industrial zones props service pricing for inspection and maintenance capacity. Supply constraints in aerospace-grade fastener stock amplify procurement risk for buyers lacking multi-source qualification.
For Market Incumbents: Anchor market position through captive manufacturing control over REACH-compliant chemical formulations and predictive analytics capability embedding in customer ERP systems. Defend against digital-first inventory platforms by expanding Southern European branch density for emergency response coverage. Prioritize AS9100 and ISO 45001 certification synchronization across scattered facilities to maintain aerospace service contracts. For New Entrants and Emerging Players: Launch via digital-first inventory platforms partnered with local fulfillment networks in Portuguese and Greek industrial zones where distributor branch density remains underdeveloped. Target construction equipment fleets and mobile service capabilities as the most penetrable whitespace. Pursue AI-driven spare parts forecasting as the primary go-to-market differentiator for guaranteed availability contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated manufacturers seeking geographic expansion or predictive analytics capability. Long-term viability favors distributors with embedded ERP integration and compliance documentation automation. Watch CSRD carbon accounting adoption timelines as the signal for condition-based maintenance investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Capability Embedding | Machine learning integration with customer ERP systems shifts procurement from transactional to subscription models. |
| REACH-Compliant Chemical Portfolio Expansion | Replacement formulation qualification for chromate-free coatings captures metalworking fabricator demand. |
| Southern European Branch Network Density | Physical presence in Portuguese and Greek zones addresses whitespace for emergency response coverage. |
| Technician Certification Pipeline Investment | AS9100 and thermography capacity expansion captures aerospace and energy inspection premiums. |
| Multi-Source Fastener Qualification | Titanium fastener supplier diversification mitigates allocation risk during raw material shocks. |
Research Methodology
Independent corroboration across maintenance directors at German automotive OEMs, procurement leads at French aerospace subcontractors, and distribution channel partners in Southern Europe underwrites the qualitative findings. Secondary validation draws from ECHA substance restriction databases, EU Green Deal implementation trackers, and customs trade data for titanium fastener flows. Bottom-up demand modeling across industry verticals converges with top-down macroeconomic triangulation.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions span service type, product category, delivery model, and industry vertical with regional regulatory cluster overlays. CAGR derivation incorporates IoT sensor deployment curves, CSRD adoption timelines, and REACH authorization phase-out schedules as industry-specific forecast inputs.
Raw material allocation shocks, REACH enforcement intensity, and technician certification capacity are the dominant revision risks. Forecasts reflect assumptions regarding regulatory compliance timelines and industrial decarbonization investment pacing. Deviation in CSRD disclosure mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Composite Autoclave Repair Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Train Contractor Market
Construction Services
Hardbanding Services Market
Construction Services
Excavating Contractor Market
Construction Services
Die Casting Services Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Gutter Cleaning Services Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
North America Testing and Commissioning Market