
 Global Construction Scaffolding Rental Market | 2026-2036
Global Construction Scaffolding Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Scaffolding Rental Market Analysis
Maintenance-inclusive rental contracts is pivoting how scaffolding suppliers monetize equipment access, shifting revenue from pure asset hire to lifecycle service bundles. United Rentals leverages its North American branch density to anchor national coverage for multi-site contractors. Altrad Group sustains European market presence through specialized industrial access solutions. Sunbelt Rentals competes aggressively on fleet availability and same-day deployment capabilities.
Construction scaffolding rental encompasses the temporary provision of elevated work platforms, guardrails, and load-bearing frames manufactured from steel, aluminum, or composite materials to enable safe personnel access at height during building, repair, or demolition activities. Equipment specifications typically address load ratings, bay dimensions, and coupling mechanisms that determine assembly speed and structural stability under variable site conditions. System scaffolding commands premium rental rates due to faster erection times and reduced labor dependency on complex geometries. Frame scaffolding occupies the volume base across residential and light commercial projects where standardized configurations dominate. Modular scaffolding is gaining traction in infrastructure development segments requiring rapid reconfiguration across irregular facades and bridge superstructures.
OSHA standards in the United States, the EU Work at Height Directive, and India's BIS safety codes collectively mandate regular inspection protocols, certified installation supervision, and documented load testing that elevate compliance costs for rental operators while simultaneously filtering informal competitors from formal project supply chains. China's GB standards and Japan's METI industrial safety guidelines add further specification layers for multinational contractors operating across Asia-Pacific jurisdictions. Stakeholders must monitor evolving carbon-accounting requirements for steel-intensive equipment fleets as European CSRD disclosure rules extend supply chain emissions tracking into construction services procurement.
Market Dynamics
Maintenance-inclusive rental contracts are displacing pure equipment hire across the scaffolding sector, forcing suppliers to bundle lifecycle services and certified installation supervision into recurring revenue streams rather than transactional asset turnover.
Growth Catalysts
- India's Smart Cities Mission:Government-backed urban megaprojects in Mumbai, Delhi, and Bangalore are generating sustained equipment rental volumes for multi-year infrastructure builds.
- EU Work at Height Directive:Mandatory documented load testing and certified installation supervision are filtering informal competitors from formal European project supply chains.
- Modular system scaffolding:Rapid reconfiguration capabilities for irregular bridge superstructures and industrial facades are compressing erection timelines on complex geometries.
Market Restraints
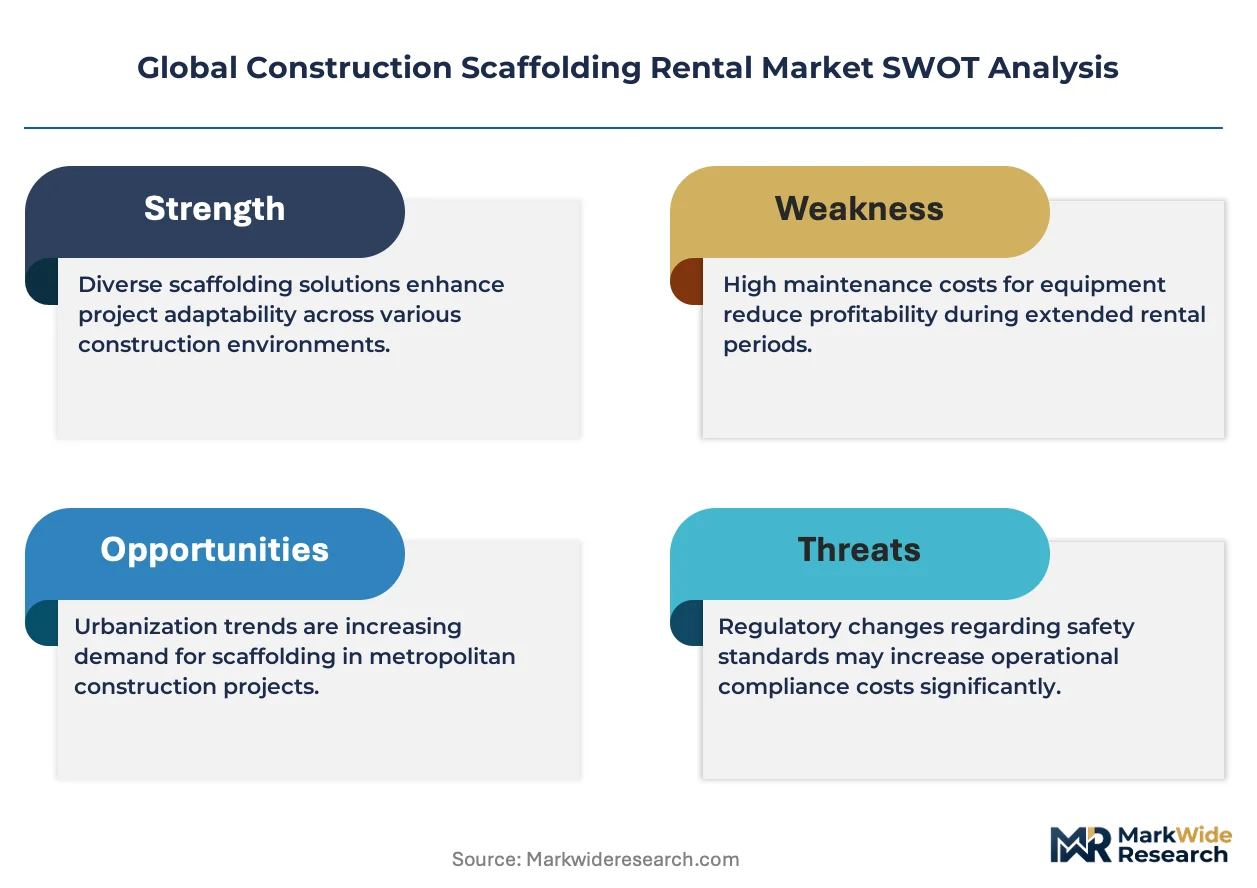
- Steel price volatility:Input cost swings for high-grade structural steel directly compress rental margin structures across fleet-intensive operators.
- Chinese manufacturing concentration:Overreliance on Yangtze River Delta producers for aluminum and composite components creates geopolitical supply exposure.
- OSHA inspection frequency mandates:Weekly documented safety protocols elevate compliance labor costs for US rental operators serving multi-site contractors.
Strategic Opportunities
- Indonesia's Nusantara capital relocation:The greenfield administrative city buildout represents underpenetrated demand for system scaffolding on government-backed timelines.
- Saudi Vision 2030 gigaprojects:NEOM and Red Sea tourism developments are creating concentrated demand for rapid-deployment rental fleets with maintenance bundling.
- EU CSRD carbon disclosure:Steel-intensive equipment fleets face new supply chain emissions tracking requirements that favor rental models over ownership for scope accounting.
Industry Challenges
- Certified erection supervisor scarcity:OSHA and BIS-mandated installation oversight credentials face pipeline gaps relative to project ramp rates in Texas and Maharashtra.
- Fleet digitization capex:RFID tracking and predictive maintenance sensor deployment demands upfront hardware investment with multi-year payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Scaffolding Rental Market |
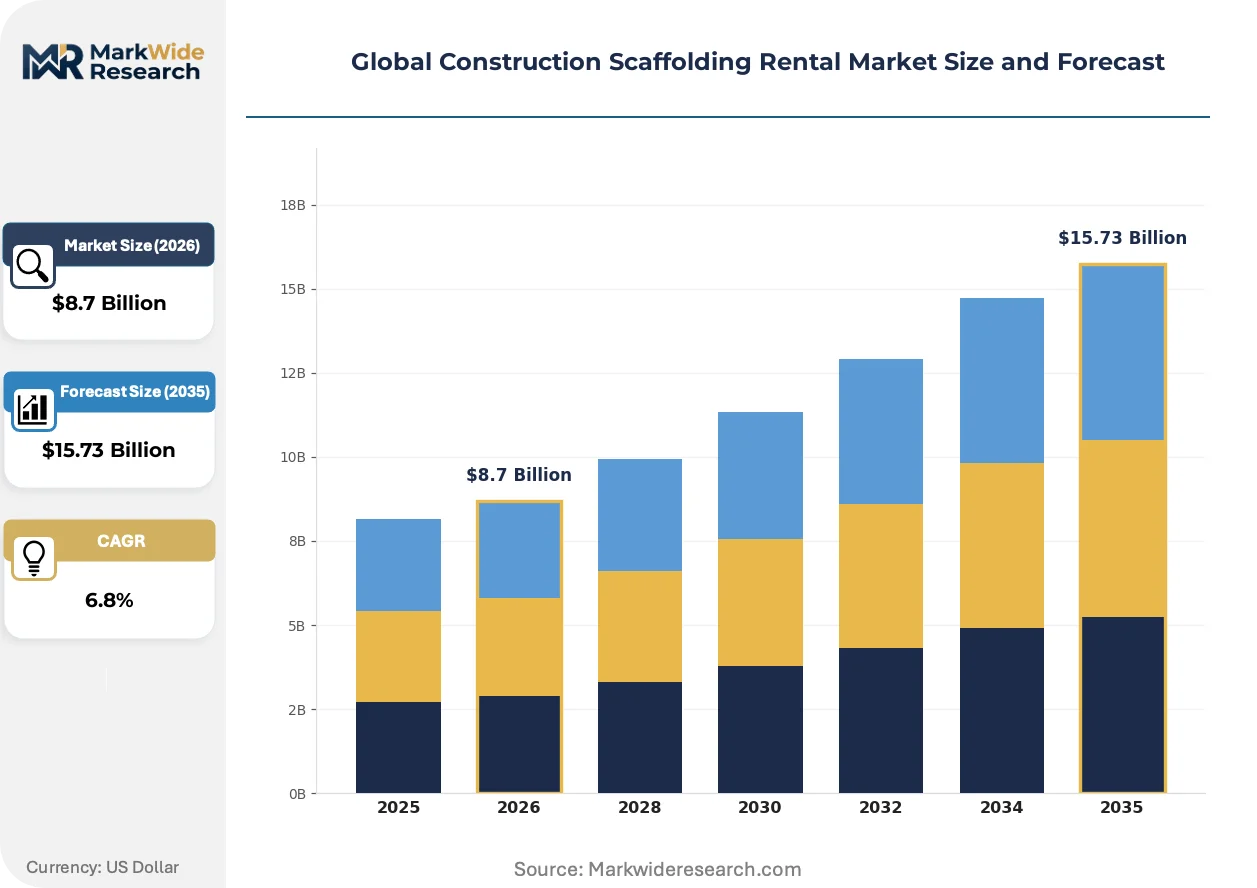
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame Scaffolding, Swing Stage, Modular Scaffolding, System Scaffolding End User: Residential Construction, Industrial Construction, Commercial Construction, Infrastructure Development Service Type: Rental Services, Installation Services, Inspection Services, Maintenance Services Deployment Type: On-Site, Off-Site, Temporary, Permanent |
| Companies Covered | United Rentals, Altrad Group, Sunbelt Rentals, PERI Group, Ashtead Group Plc, Condor S.p.A., BrandSafway, ULMA Construction, Apollo Scaffold Services Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Scaffolding Rental Market Emerging Trajectories
Equipment intelligence and regulatory carbon accounting are converging to reshape how scaffolding fleets are deployed, monitored, and monetized across project lifecycles.
Lightweight carbon-fiber composite platforms are integrating load-bearing frames with embedded strain sensors for real-time structural monitoring. Offshore wind turbine maintenance contractors in the North Sea are adopting these systems for rapid helicopter-transportable deployment. The technology is integrating predictive analytics that compress unplanned downtime intervals and extend certified-use cycles between inspections.
REACH substance restrictions on chromate surface treatments are accelerating powder-coating substitution across European steel scaffolding manufacturing. The regulation is forcing rental operators to retire legacy hot-dip galvanized inventories ahead of depreciation schedules. German industrial access specialists are responding with certified coating-transition programs that maintain fleet availability during specification upgrades.
Project owners are consolidating vendor relationships around single-source national rental contracts with embedded maintenance and dismantling services. Multi-site contractors in the US Gulf Coast petrochemical corridor are displacing fragmented local supplier networks with integrated fleet management agreements. This concentration is most visible in Texas and Louisiana, where turnaround maintenance schedules demand guaranteed equipment availability with 24-hour deployment commitments.
Global Construction Scaffolding Rental Market Segmentation
Equipment lifecycle economics and regulatory compliance burdens are fragmenting demand across four distinct segmentation dimensions. Rental operators must align fleet composition and service bundling to specific project archetypes rather than deploying uniform solutions.
Product Type:
Replacement cycles for legacy frame inventories are compressing as OSHA and EU Work at Height Directive mandates accelerate obsolescence of non-compliant configurations.
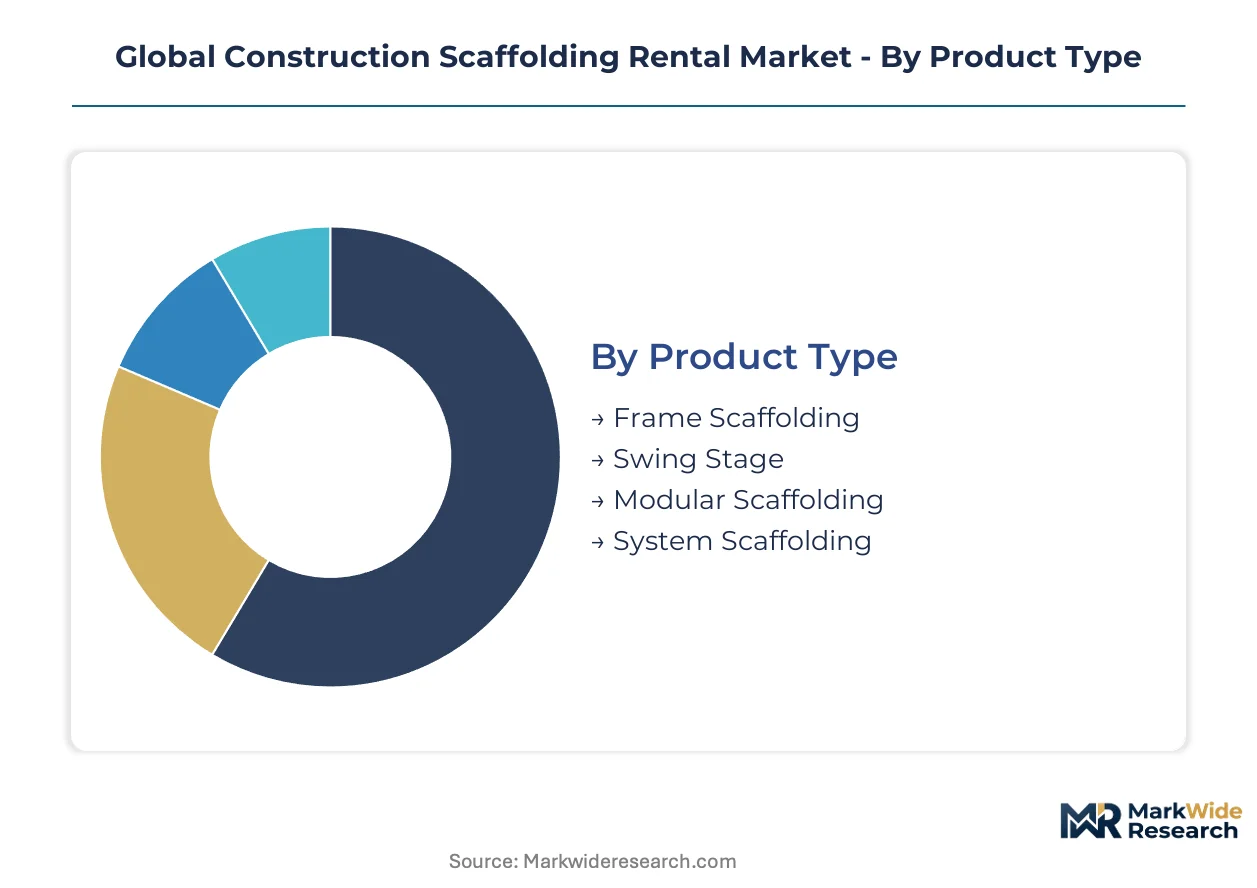
- System Scaffolding:Pre-engineered modular components with integrated locking mechanisms enable rapid assembly without loose fittings. Demand concentrates in German industrial maintenance and Saudi Vision 2030 gigaprojects where certified erection speed determines contract awards.
- Frame Scaffolding:Standardized welded tubular frames with cross-bracing dominate residential and light commercial volumes. US multi-site contractors in Texas and Florida rely on this segment for repetitive low-rise structures where configuration simplicity outweighs erection speed.
- Modular Scaffolding:Interchangeable vertical and horizontal members adapt to irregular geometries without custom fabrication.
- Swing Stage:Suspended platforms for facade access and window replacement on high-rise structures.
Volume placements concentrate in Frame Scaffolding; the faster expansion belongs to System Scaffolding.
End User:
Procurement authority consolidation across end-user categories is elevating contract scale and service bundling requirements.
- Infrastructure Development:Bridge superstructures, tunnel portals, and elevated transit systems demand load-rated systems with documented inspection trails. India's Smart Cities Mission in Mumbai and Delhi generates sustained multi-year rental volumes with mandatory BIS compliance.
- Commercial Construction:Office towers and retail complexes prioritize rapid deployment and aesthetic compatibility with curtain wall installation schedules.
- Industrial Construction:Petrochemical turnarounds and power plant outages require explosion-rated aluminum configurations with 24-hour availability commitments.
- Residential Construction:Single-family and low-rise multifamily projects operate on compressed timelines with price-sensitive procurement.
Contract value concentrates in Infrastructure Development; margin expansion is steepest in Industrial Construction.
Service Type:
Revenue model migration from transactional asset hire to recurring service subscriptions is reshaping competitive positioning across service categories.
- Rental Services:Pure equipment provision without installation or maintenance support. This segment retains price-sensitive residential and small commercial contractors in fragmented US regional markets.
- Installation Services:Certified erection supervision with documented load testing and OSHA-compliant assembly protocols. Gulf Coast petrochemical operators mandate this bundling for turnaround schedules.
- Maintenance Services:Predictive upkeep and component replacement under fixed-fee arrangements.
- Inspection Services:Third-party documented safety audits with regulatory filing support.
Revenue retention is strongest in Installation Services; customer acquisition costs are lowest in Rental Services.
Deployment Type:
Site logistics constraints and project duration profiles are determining deployment configuration selection.
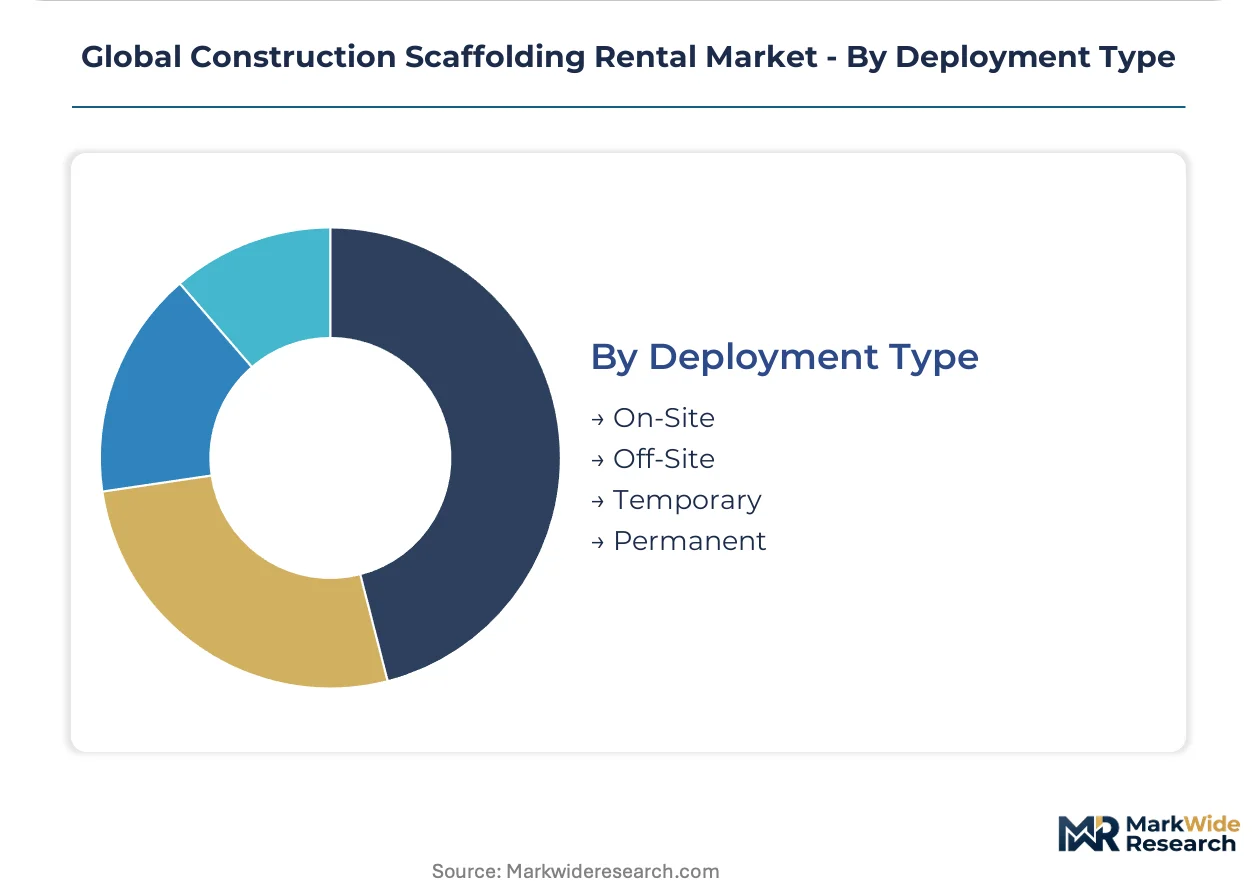
- On-Site:Equipment assembled and maintained at the construction location throughout project duration. This configuration dominates Indian urban megaprojects where material handling infrastructure limits prefabrication options.
- Temporary:Short-duration deployment for specific construction phases with rapid dismantling requirements.
- Off-Site:Modular assembly in controlled yards with transport to final location.
- Permanent:Fixed installations for ongoing maintenance access on industrial facilities.
Project count concentrates in Temporary; contract duration is longest in On-Site.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scaffolding rental consumption concentrates in economies with active infrastructure pipelines, while manufacturing supply clusters in steel-producing regions with established fabrication networks. The geographic mismatch between production assets and project demand creates cross-border equipment flows and regional specialization in fleet services.
United States
Gulf Coast petrochemical turnarounds and Texas infrastructure megaprojects sustain multi-year rental demand with 24-hour deployment requirements. OSHA mandates weekly documented safety inspections and certified erection supervision that elevate compliance costs for rental operators. Houston anchors the largest equipment concentration, where national rental contracts consolidate fragmented local supplier networks.
Germany
Industrial maintenance schedules and REACH-mandated coating transitions drive system scaffolding replacement cycles ahead of depreciation timelines. ECHA substance restrictions on chromate surface treatments force powder-coating substitution across legacy steel inventories. The Ruhr industrial corridor hosts specialized access solution providers serving chemical plant turnaround contracts.
India
Smart Cities Mission projects in Mumbai, Delhi, and Bangalore generate sustained multi-year rental volumes for urban infrastructure builds. BIS safety codes mandate documented load testing and certified installation supervision that filter informal competitors from formal procurement channels. Maharashtra's construction clusters concentrate equipment demand for bridge superstructures and elevated transit systems.
Saudi Arabia
Vision 2030 gigaprojects including NEOM and Red Sea tourism developments create concentrated demand for rapid-deployment rental fleets. SFDA-aligned industrial safety guidelines and government-backed timelines require maintenance-bundled contracts with guaranteed availability. The Eastern Province petrochemical corridor sustains explosion-rated aluminum scaffolding demand for facility maintenance.
China
Yangtze River Delta producers supply aluminum and composite components to regional fabrication networks serving domestic infrastructure builds. GB standards and MIIT industrial safety guidelines add specification layers for equipment deployed on multinational contractor projects. Sichuan-Chongqing infrastructure development absorbs modular scaffolding for irregular bridge geometries and tunnel portals.
Global Construction Scaffolding Rental Market Vendor Landscape
Top-tier vendors anchor national-scale fleet operations, while regional specialists occupy niche industrial access segments. The vendor base stratifies across three tiers: integrated rental-service bundlers, equipment-only lessors, and project-specific access contractors. Strategic archetypes include maintenance-inclusive contract providers, rapid-deployment specialists, and industrial turnaround access experts. Competitive moves concentrate on fleet digitization investments and geographic coverage expansion through branch network density.
Among North American rental operators, United Rentals exemplifies the integrated service bundler archetype through its national branch density. Altrad Group occupies a position representing European industrial access specialization. Sunbelt Rentals anchors the rapid-deployment competitive vector with same-day fleet availability capabilities.
| Leading Market Players |
|---|
| United Rentals |
| Altrad Group |
| Sunbelt Rentals |
| PERI Group |
| Ashtead Group Plc |
| Condor S.p.A. |
| BrandSafway |
| ULMA Construction |
| Apollo Scaffold Services Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between OSHA-compliant system scaffolding and informal frame inventories manifests in rental rate spreads exceeding three-to-one, with premium tiers commanding bundled installation supervision while commodity segments compete on fleet turnover velocity alone. This bifurcation concentrates margin capture among integrated operators capable of underwriting compliance documentation costs across multi-site contractor portfolios.
Pricing Analysis
Margin tightening in frame scaffolding reflects steel price volatility and compressed utilization cycles under accelerated replacement mandates. Three-tier pricing structure across premium system, standard modular, and economy frame levels differentiates primarily on certified erection speed and documented inspection trails. Cost-down pressure on residential-tier rentals intensifies as informal suppliers absorb compliance-exempt project volumes in fragmented regional markets. Infrastructure contractors exhibit lowest price sensitivity given penalty exposure on government-backed timelines.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta fabrication hubs and Ruhr industrial corridor coating facilities are extending component lead times for aluminum and powder-coated steel inventories. Manufacturing gravity centers on China, Germany, and India for structural steel and composite member production. Raw material dependencies span high-grade structural steel, aluminum extrusions, and chromate-free surface treatments. Single-source vulnerability concentrates in Yangtze River Delta aluminum component suppliers. Distribution runs through national rental branch networks with regional fleet pooling for rapid deployment commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where OSHA, EU Work at Height Directive, and BIS safety code documentation requirements create barrier-to-entry moats favoring capitalized incumbents with certified supervisor pipelines and inspection infrastructure.
For Market Incumbents: Cement market position by accelerating fleet digitization investments in RFID tracking and predictive maintenance sensors ahead of compliance disclosure mandates. Defend against emerging modular system specialists by deepening backward integration into powder-coating capabilities and certified erection training academies. Prioritize branch density expansion in Texas and Maharashtra where supervisor scarcity filters regional competitors from turnaround maintenance contracts. For New Entrants and Emerging Players: Equipment leasing partnerships with national contractors offer the most penetrable entry vector for bypassing capital-intensive fleet ownership barriers. Target Indonesia's Nusantara capital relocation and Saudi Vision 2030 gigaprojects where maintenance-bundled contract structures favor agile rental operators over legacy asset-heavy incumbents. Deploy helicopter-transportable carbon-fiber composite platforms as differentiated rapid-deployment offerings for offshore wind maintenance contractors. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap regional specialists possessing dense branch networks in high-compliance jurisdictions given EU CSRD carbon disclosure extension into construction services procurement. Long-term viability favors operators with integrated installation-maintenance bundling capabilities and digitized fleet visibility. Monitor certified erection supervisor pipeline gaps in Texas and Maharashtra as inflection indicators for contract fulfillment risk and regional pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Digitization Investment | RFID tracking and predictive maintenance sensors compress unplanned downtime intervals for OSHA-compliant operators. |
| Certified Erection Training Academy | Supervisor pipeline development addresses scarcity gaps in Texas and Maharashtra construction clusters. |
| Maintenance-Inclusive Contract Bundling | Recurring revenue migration displaces transactional asset hire across Gulf Coast petrochemical turnarounds. |
| Powder-Coating Capability Integration | REACH-compliant surface treatment substitution future-proofs European steel inventories against ECHA restrictions. |
| Carbon-Fiber Composite Platform Introduction | Lightweight helicopter-transportable systems penetrate offshore wind maintenance segments in North Sea markets. |
Methodological Framework
Trade association filings, customs and steel import records, and regulatory safety code databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with scaffolding rental fleet managers, certified erection supervisors, petrochemical turnaround procurement leads, and infrastructure project safety officers provided operational validation of utilization rates and compliance cost structures. Bottom-up equipment fleet counts triangulated against top-down construction spending allocations across the analysis window.
Historical rental rate trendlines and fleet turnover velocity patterns anchored projection modeling across equipment type, end-use sector, service bundling tier, and deployment configuration dimensions. CAGRs derived from segment-level demand elasticity coefficients applied to infrastructure pipeline visibility and regulatory compliance phase-in schedules. Industry-specific forecast inputs incorporated steel price volatility indices and certified supervisor pipeline graduation rates.
Several conditions sit outside the modeled scope, including geopolitical disruption to Yangtze River Delta manufacturing, unanticipated regulatory acceleration in carbon accounting disclosure, and informal market share capture in price-sensitive residential segments. Forecasts reflect documented assumptions on compliance cost pass-through rates and fleet digitization adoption curves. Material deviation in steel input costs, supervisor certification pipeline output, or government infrastructure commitment timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
Dust Suppression Control Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Construction TIC Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Global Industrial Services Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
Industrial Maintenance Products Market
Construction Services
Excavating Contractor Market
Construction Services
Condenser Cleaners Market
Construction Services
Remote Construction Market
Construction Services
NDT and Inspection Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Train Contractor Market