
 Industrial Maintenance Products Market | 2026-2036
Industrial Maintenance Products Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Maintenance Products Market Analysis
Polyurea is hardening its position as the preferred elastomer in high-performance protective coatings, displacing traditional epoxies in corrosive industrial environments. PPG Industries leverages captive resin production to control formulation costs across marine and infrastructure accounts. Hempel anchors its competitiveness through specialized anti-corrosion systems for offshore energy assets. Sherwin-Williams dominates North American distribution through integrated store networks serving maintenance contractors.
Industrial maintenance products encompass lubricants, adhesives, sealants, cleaning agents, tools, equipment, spare parts, and consumables formulated to preserve or restore operational integrity of machinery, structures, and facilities. These formulations typically incorporate base oils, synthetic polymers, corrosion inhibitors, and surfactants engineered to withstand temperature extremes, chemical exposure, and mechanical wear in continuous-use environments. Lubricants and cleaning agents command the largest revenue pools due to recurring replenishment cycles across manufacturing and automotive applications, while adhesives and sealants generate superior margins in specialized repair services. Consumables represent the fastest-expanding component category as predictive maintenance programs shorten replacement intervals for wear-prone parts.
EPA regulations on volatile organic compound emissions and REACH restrictions on hazardous substance classifications are elevating compliance costs for solvent-based formulations while accelerating reformulation toward waterborne and bio-based alternatives. OSHA workplace exposure limits and ISO 14001 environmental management standards further shape procurement specifications for industrial facilities. Stakeholders must monitor evolving chemical hazard designations and carbon-border adjustment mechanisms to anticipate shifts in product qualification requirements and supply chain sourcing.
Market Dynamics
The EPA's volatile organic compound emission limits and REACH substance restrictions are compressing formulation margins while accelerating the displacement of solvent-based systems with waterborne and bio-based alternatives across industrial maintenance supply chains.
Growth Catalysts
- REACH substance restrictions:Chemical manufacturers in Germany's automotive sector are expanding procurement of bio-based lubricants to maintain EU market access. This compliance-driven substitution creates premium positioning for reformulated products.
- Predictive maintenance programs:Manufacturing facilities in Stuttgart and Wolfsburg industrial clusters are shortening replacement intervals for wear-prone consumables. The shift from calendar-based to condition-based service cycles expands recurring revenue pools.
- Offshore energy infrastructure:Specialized anti-corrosion coating demand is concentrating around North Sea and Gulf of Mexico assets requiring extended service life in salt-spray environments. Asset operators specify polyurea elastomers for their superior chemical resistance.
Market Restraints
- Base oil price volatility:Synthetic polymer and corrosion inhibitor feedstock costs fluctuate with crude oil derivatives and specialty chemical supply constraints. Formulators cannot fully pass input spikes to long-term maintenance contracts.
- Concentrated resin supply:Captive production of polyurea precursors limits independent coating manufacturers' access to critical raw materials. PPG Industries and similar integrated players control formulation cost structures.
- Epoxy substitution ceiling:Traditional epoxy coatings retain cost advantages in non-corrosive indoor environments where temperature extremes and chemical exposure are absent. Price-sensitive facilities delay premium elastomer adoption.
Strategic Opportunities
- India's manufacturing corridors:BIS certification requirements and PLI scheme incentives for domestic production are opening procurement channels for compliant maintenance product suppliers. Automotive and textile machinery clusters in Gujarat and Tamil Nadu represent underpenetrated demand.
- Carbon-border adjustment mechanisms:The EU's CBAM is creating competitive advantage for low-carbon-footprint lubricant and cleaning agent producers. Bio-based formulation capabilities will determine qualification for European industrial procurement.
- Digital inventory integration:Integrated distributor networks are deploying vendor-managed inventory systems with automated replenishment triggers. Sherwin-Williams' store infrastructure provides a template for channel modernization.
Industry Challenges
- Formulation chemist scarcity:Expertise in waterborne system stability and bio-based additive compatibility is concentrated among aging specialists. Training pipelines have not kept pace with reformulation demands from EPA and OSHA compliance timelines.
- ISO 14001 certification complexity:Environmental management system audits require documented supply chain carbon accounting that many mid-tier suppliers cannot yet provide. Procurement specifications from certified facilities are excluding non-compliant vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Maintenance Products Market |
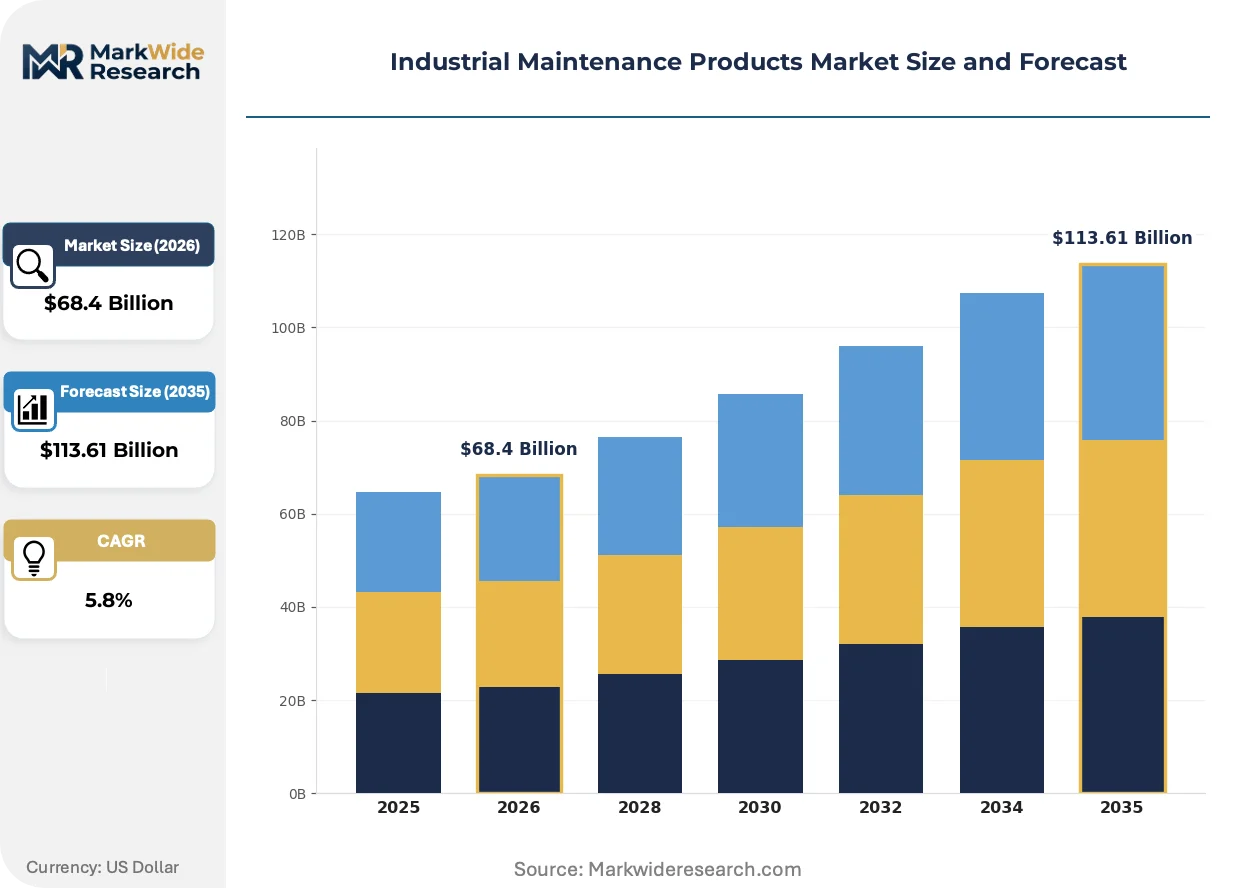
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lubricants, Adhesives, Sealants, Cleaning Agents Component: Tools, Equipment, Spare Parts, Consumables Application: Manufacturing, Construction, Warehousing, Automotive Service Type: Repair Services, Maintenance Contracts, Installation, Consulting |
| Companies Covered | Jotun, Hempel, PPG Industries, Illinois Tool Works, 3M Company, Sherwin-Williams, Axalta Coating Systems, Grainger, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Maintenance Products Market Emerging Trajectories
Electrification of industrial equipment and tightening chemical hazard classifications are compressing traditional product lifecycles while opening white space for predictive-enabled consumables and low-emission formulations.
Polyurea elastomer spray systems are electrifying protective coating application across marine infrastructure and chemical processing facilities. Shipyards in Hamburg and Rotterdam are adopting plural-component spray equipment to reduce cure times from days to hours. The technology is electrifying maintenance scheduling by enabling in-service application that minimizes asset downtime.
REACH Annex XIV authorization requirements and EPA Significant New Use Rules are reclassifying solvent-based cleaners as restricted substances across European and North American manufacturing. Industrial laundries and parts-cleaning operations face reformulation deadlines that favor aqueous and semi-aqueous alternatives. Metalworking facilities in Germany's automotive supply chain are retrofitting vapor degreasing equipment to accommodate modified alcohol chemistry.
Maintenance contractors are consolidating purchasing through integrated distributor networks that bundle technical specification support with just-in-time logistics. Independent job shops serving North American manufacturing are migrating from spot-buying at retail counters to managed procurement programs with volume commitments. The channel shift is most visible in automotive supplier parks where OEM-aligned service contracts require certified product traceability and consolidated invoicing.
Industrial Maintenance Products Market Segmentation
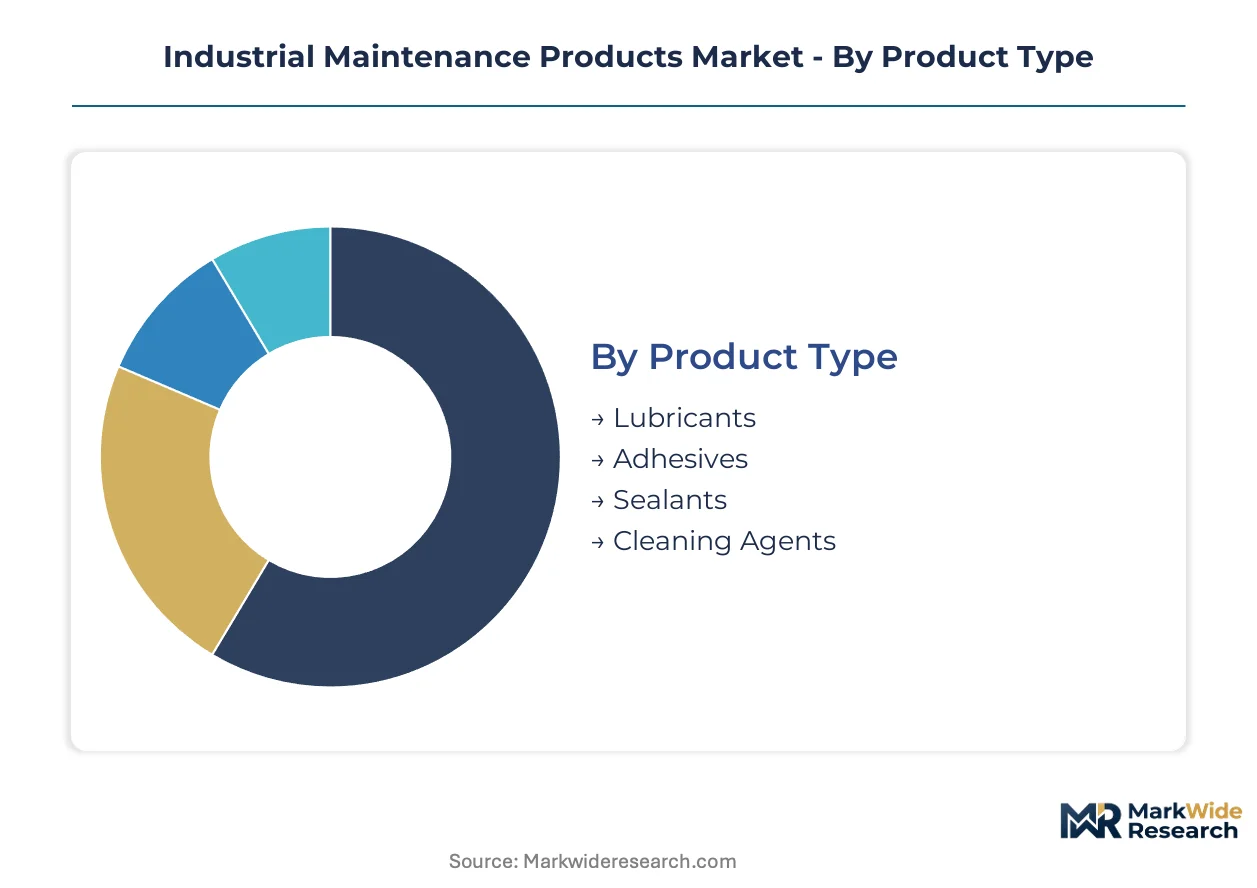
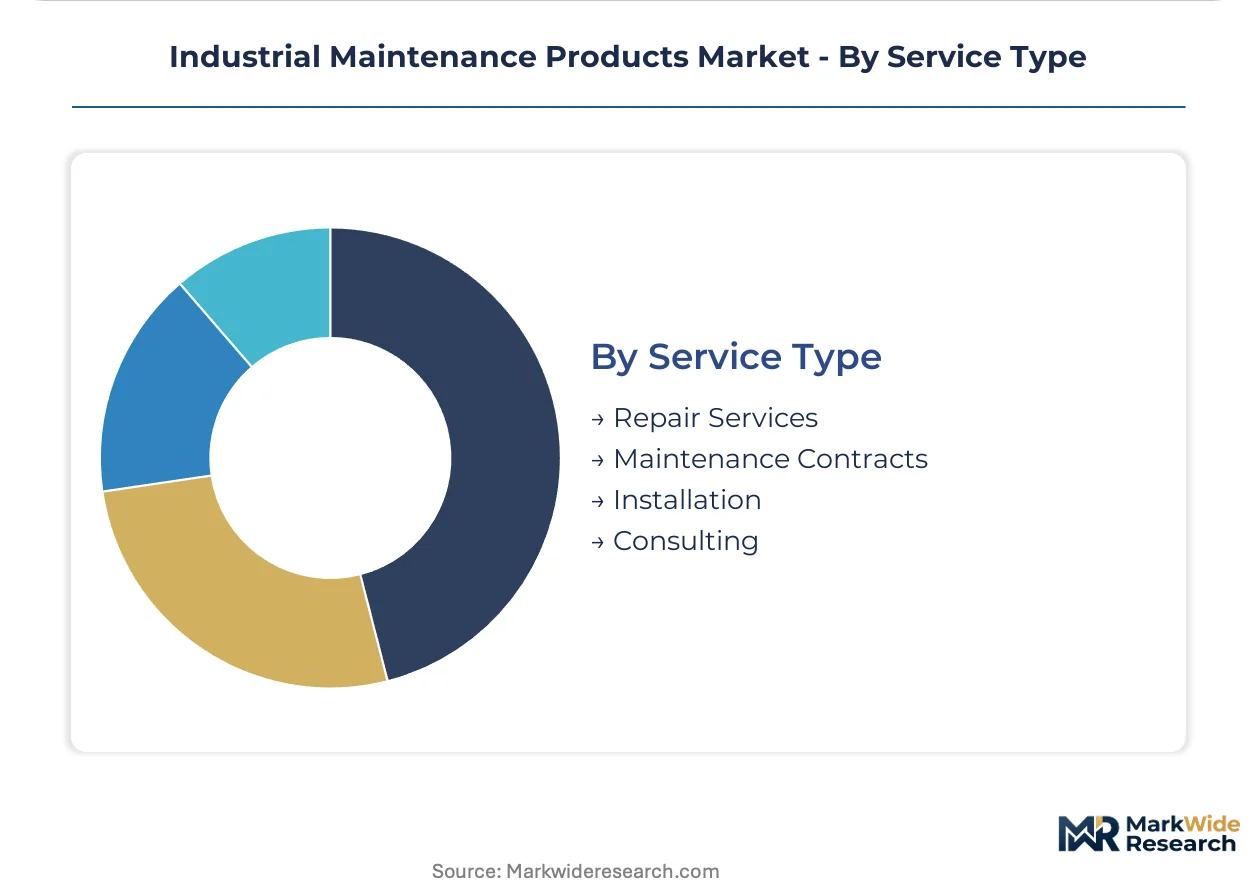
Industrial maintenance products fragment across four dimensions that shape capital deployment and margin capture. Equipment-intensive segments demand upfront manufacturing investment, while service-oriented categories generate recurring revenue through labor leverage. Understanding these structural differences illuminates where procurement budgets concentrate and where reformulation pressures bite hardest.
Product Type:
Lubricants and adhesives require the heaviest capital commitment in formulation R&D and blending infrastructure, while cleaning agents run lighter on fixed assets but face steeper regulatory compliance costs.
- Lubricants:Base oil blending with synthetic polymer additives delivers viscosity stability across temperature extremes. Stuttgart automotive suppliers specify bio-based formulations to satisfy REACH substance restrictions, compressing margins for conventional mineral oil producers.
- Adhesives:Structural bonding systems incorporate epoxy, polyurethane, or cyanoacrylate chemistries tailored to substrate compatibility. Offshore energy contractors in the North Sea specify marine-grade formulations for salt-spray resistance, driving premium pricing.
- Sealants:Elastomeric compounds fill gaps between dissimilar materials under thermal cycling stress.
- Cleaning Agents:Aqueous and semi-aqueous surfactant blends displace solvent-based vapor degreasers under EPA volatile organic compound limits.
Most installed capacity flows through Lubricants. Expansion is steepest in Cleaning Agents.
Component:
Equipment and spare parts tie up working capital in inventory and distribution networks, whereas consumables turn inventory faster and tools occupy a middle ground on asset intensity.
- Equipment:Plural-component spray systems, automated lubrication dispensers, and diagnostic instruments represent the highest ticket items. Hamburg shipyards invest in polyurea spray rigs to cut coating cure times from days to hours, justifying capital outlay through reduced dry-dock scheduling.
- Consumables:Filters, wiping materials, and single-use application supplies generate recurring replenishment revenue. Predictive maintenance programs in Wolfsburg manufacturing clusters shorten replacement intervals, expanding volume throughput.
- Tools:Hand tools, power tools, and precision measurement instruments carry moderate capital requirements with extended replacement cycles.
- Spare Parts:OEM-specified replacement components demand authorized distribution relationships and technical documentation support.
Revenue concentrates in Equipment. Volume expansion runs fastest in Consumables.
Application:
Automotive and manufacturing applications concentrate procurement volume, while construction and warehousing spread demand across fragmented contractor bases with divergent specification standards.
- Manufacturing:Continuous-process facilities require 24/7 lubrication and cleaning protocols to minimize unplanned downtime. German automotive supply chain plants specify ISO 14001-certified products to satisfy environmental management audit requirements.
- Automotive:OEM-aligned service contracts demand certified product traceability and consolidated invoicing through managed procurement programs. Tier-1 suppliers in supplier parks drive standardization across maintenance chemical specifications.
- Construction:Project-based demand fluctuates with infrastructure investment cycles and seasonal activity patterns.
- Warehousing:Material handling equipment maintenance dominates, with conveyor systems and automated storage retrieval mechanisms driving lubricant and spare part consumption.
Procurement volume pools heaviest in Manufacturing. Specification tightening accelerates fastest in Automotive.
Service Type:
Maintenance contracts and repair services scale through labor deployment and technical expertise, while installation and consulting carry lower capital barriers but demand specialized engineering credentials.
- Maintenance Contracts:Multi-year agreements bundle scheduled service, consumable replenishment, and emergency response. North American manufacturing job shops migrate from spot-buying to volume-commitment programs with vendor-managed inventory integration.
- Repair Services:Unplanned breakdown response commands premium labor rates and expedited parts logistics. Metalworking facilities retrofit vapor degreasing equipment to accommodate modified alcohol chemistry under reformulation deadlines.
- Installation:New equipment commissioning and facility startup support requires coordination with OEM technical teams.
- Consulting:Predictive maintenance program design and environmental compliance advisory services leverage specialized expertise in waterborne system stability and bio-based additive compatibility.
Contract value concentrates in Maintenance Contracts. Margin expansion is sharpest in Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive supplier parks concentrate premium-grade lubricant demand as German OEMs enforce REACH-compliant procurement specifications across tier-1 networks. Industrial clusters in Wolfsburg, Hamburg, and the Ruhr Valley anchor continental consumption of protective coatings and predictive maintenance consumables.
Germany
Automotive OEMs in Stuttgart and Wolfsburg mandate bio-based lubricant specifications to satisfy REACH substance restrictions. ECHA authorization timelines compress reformulation windows for solvent-based cleaners. The Ruhr Valley's steel and chemical processing complexes drive specialized anti-corrosion coating procurement for continuous-process environments.
United States
EPA volatile organic compound limits accelerate waterborne coating adoption across Gulf Coast petrochemical facilities. OSHA workplace exposure standards reshape parts-cleaning protocols in Midwest automotive plants. Houston's offshore energy service base concentrates polyurea elastomer demand for salt-spray protection of platform assets.
China
MIIT industrial upgrading directives prioritize predictive maintenance system deployment in Yangtze River Delta manufacturing corridors. NMPA-equivalent chemical registration requirements elevate compliance costs for imported formulation components. Shanghai's port infrastructure drives marine coating consumption for vessel repair and maintenance cycles.
India
BIS certification requirements and PLI scheme incentives open procurement channels for compliant lubricant suppliers in Gujarat automotive clusters. CDSCO-aligned chemical safety protocols reshape industrial cleaning agent specifications. Tamil Nadu's textile machinery corridors generate concentrated demand for wear-part consumables under shortened replacement intervals.
Japan
METI carbon neutrality roadmaps accelerate bio-based formulation adoption in Nagoya automotive manufacturing zones. JIS standards enforcement elevates quality thresholds for imported maintenance chemicals. Osaka's machinery and electronics clusters specify precision lubrication systems for automated production lines.
Industrial Maintenance Products Market Vendor Landscape
Global majors compete with regional champions across formulation technology and distribution reach, creating a tiered structure where integrated resin producers hold cost advantages over independent blenders. The vendor base separates into captive resin manufacturers, specialized coating formulators, and broad-line distributors with technical service capabilities. Two dominant competitive moves reshape positioning: backward integration into polyurea precursor production and vendor-managed inventory partnerships with automotive OEMs.
Among integrated coating specialists, PPG Industries and Hempel occupy positions that exemplify the captive supply archetype, while Sherwin-Williams anchors the distributor-integrated tier with store-network infrastructure. These three companies represent distinct strategic postures—resin-backed formulation control, offshore energy specialization, and channel density—rather than overlapping competitive vectors.
| Leading Market Players |
|---|
| Jotun |
| Hempel |
| PPG Industries |
| Illinois Tool Works |
| 3M Company |
| Sherwin-Williams |
| Axalta Coating Systems |
| Grainger |
| AkzoNobel |
| Others |
Supply Flow & Price Mechanics
Captive polyurea precursor production anchors both supply security and pricing power for integrated coating manufacturers serving marine and offshore energy accounts. PPG Industries and Hempel leverage in-house resin capabilities to buffer formulation costs against synthetic polymer feedstock volatility, while independent blenders absorb margin compression from base oil price swings without equivalent hedging mechanisms.
Pricing Analysis
Base oil and synthetic polymer feedstock pass-through mechanics determine margin retention across lubricant and coating tiers. Contract-based long-term offtake agreements dominate procurement between Stuttgart automotive OEMs and bio-based lubricant suppliers, with price differentiation resting on REACH compliance certification and ISO 14001 environmental management tier. Cost compression in mineral oil formulations is intensifying because EPA volatile organic compound limits accelerate waterborne system adoption. Tier-1 automotive suppliers exhibit lowest price sensitivity due to specification lock-in, while independent metalworking job shops in fragmented construction markets resist premium elastomer pricing.
Supply Chain Analysis
Formulation chemist scarcity in Germany, the United States, and China constrains batch consistency for waterborne and bio-based system production. Supply chains draw from crude oil derivatives, specialty corrosion inhibitors, and surfactant feedstocks that fluctuate with energy market volatility. Single-source vulnerability concentrates around polyurea precursor manufacturers with captive resin capabilities. Distribution runs through integrated store networks and vendor-managed inventory systems serving automotive supplier parks and offshore energy service bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive maintenance program adoption that shortens consumable replacement cycles and elevates premium-grade specification demand.
For Market Incumbents: Lock in bio-based formulation capabilities before REACH Annex XIV authorization timelines compress reformulation windows. Secure captive polyurea precursor supply through backward integration or exclusive offtake agreements to defend against resin access restrictions. Deepen vendor-managed inventory partnerships with Stuttgart and Wolfsburg automotive clusters to embed switching costs.
For New Entrants and Emerging Players: The premium-to-economy tier price gap in industrial cleaning agents creates entry space for aqueous and semi-aqueous alternatives undercutting solvent-based legacy products. Target India's Gujarat and Tamil Nadu manufacturing corridors where BIS certification requirements and PLI scheme incentives favor compliant domestic suppliers. Lead with technical specification support bundled into channel partnerships rather than spot-price competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 14001 certification complexity excludes mid-tier suppliers from automotive OEM procurement specifications. Long-term viability favors targets with documented bio-based formulation pipelines and established automotive supplier park relationships. Monitor ECHA authorization timeline acceleration as the inflection signal for reformulation-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive polyurea resin production shields PPG Industries from feedstock volatility in marine coating formulations. |
| Green Manufacturing Transition | Bio-based lubricant capabilities determine EU market access under tightening REACH substance restrictions. |
| Long-term Supply Agreement | Vendor-managed inventory contracts with Stuttgart automotive clusters embed recurring revenue and specification lock-in. |
| Joint Venture | Localized production partnerships in Gujarat satisfy BIS certification requirements and PLI scheme incentives. |
| Capacity Expansion | Polyurea spray system manufacturing scale-up serves Hamburg and Rotterdam shipyard electrification of coating application. |
Methodological Framework
Bottom-up automotive and manufacturing maintenance demand modeling reconciled against top-down chemical formulation supply tracking forms the analytical core of this study. Primary interviews with plant maintenance directors, OEM procurement leads, coating application contractors, and aftermarket service heads informed demand-side assumptions. Secondary validation drew from EPA emission filings, ECHA substance restriction databases, SEC 10-K disclosures from integrated coating manufacturers, and customs trade data on base oil and synthetic polymer imports. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped lubricant, adhesive, sealant, and cleaning agent consumption against installed manufacturing equipment base and predictive maintenance program penetration rates across the projection horizon. Segmentation dimensions modeled include product type grade tier, end-use industry concentration, component replacement cycle velocity, and regional regulatory cluster stringency. CAGRs were derived from slope analysis of historical procurement patterns projected through compliance-driven substitution curves and condition-based maintenance adoption trajectories. Offshore energy asset counts and automotive production forecasts supplied industry-specific demand drivers.
Caveats apply where ECHA authorization timeline acceleration, carbon-border adjustment mechanism implementation, or base oil price volatility spikes could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and predictive maintenance program adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Dust Suppression Control Market
Construction Services
Remote Construction Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Grease Trap Service Market
Construction Services
MENA Architectural Services Market
Construction Services
Construction Project Management Services Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
NDT and Inspection Market
Construction Services
Construction TIC Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
Excavating Contractor Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Train Contractor Market
Construction Services
Global Industrial Services Market