
 China Fire Sprinklers Market | 2026-2036
China Fire Sprinklers Market Size, Share, and Industry Trends Forecast 2026-2036
China Fire Sprinklers Market Intelligence
Modular sprinkler packages that combine detection, suppression, and monitoring hardware into single procurement bundles is broadening buyer choice across China's construction sector. Jinyuan Technology Development leverages its manufacturing scale to dominate wet pipe system production for residential towers. Fujian Sanhui Fire Equipment differentiates through specialized deluge configurations for petrochemical facilities. Quanzhou Xiangrui Fire Technology anchors the southern China market with extensive distribution through Fujian province.
Fire sprinklers are thermosensitive automatic water discharge devices comprising a fusible alloy element, deflector, and threaded connection body rated for specific activation temperatures and flow coefficients (K-factor), manufactured through brass forging, precision machining, and hydrostatic testing to deliver controlled water distribution for fire containment. Wet pipe systems occupy the largest installed base due to lower maintenance requirements in China's temperate coastal zones, while smart technology segments are expanding fastest as MIIT promotes IoT integration in building safety infrastructure. Pre-action configurations command premium positioning in data center and cold storage applications where accidental discharge carries catastrophic cost.
China's Ministry of Emergency Management enforces GB 50016 and GB 50084 design codes that mandate sprinkler coverage in high-rise commercial and industrial buildings, directly shaping product certification requirements and installation demand. BIS-equivalent fire product conformity assessment procedures, administered through provincial fire departments, control market access by requiring type approval and factory inspection for all marketed sprinkler heads. Stakeholders must monitor alignment between local GB standard revisions and municipal green building incentives to anticipate specification shifts in upcoming construction procurement cycles.
Market Dynamics
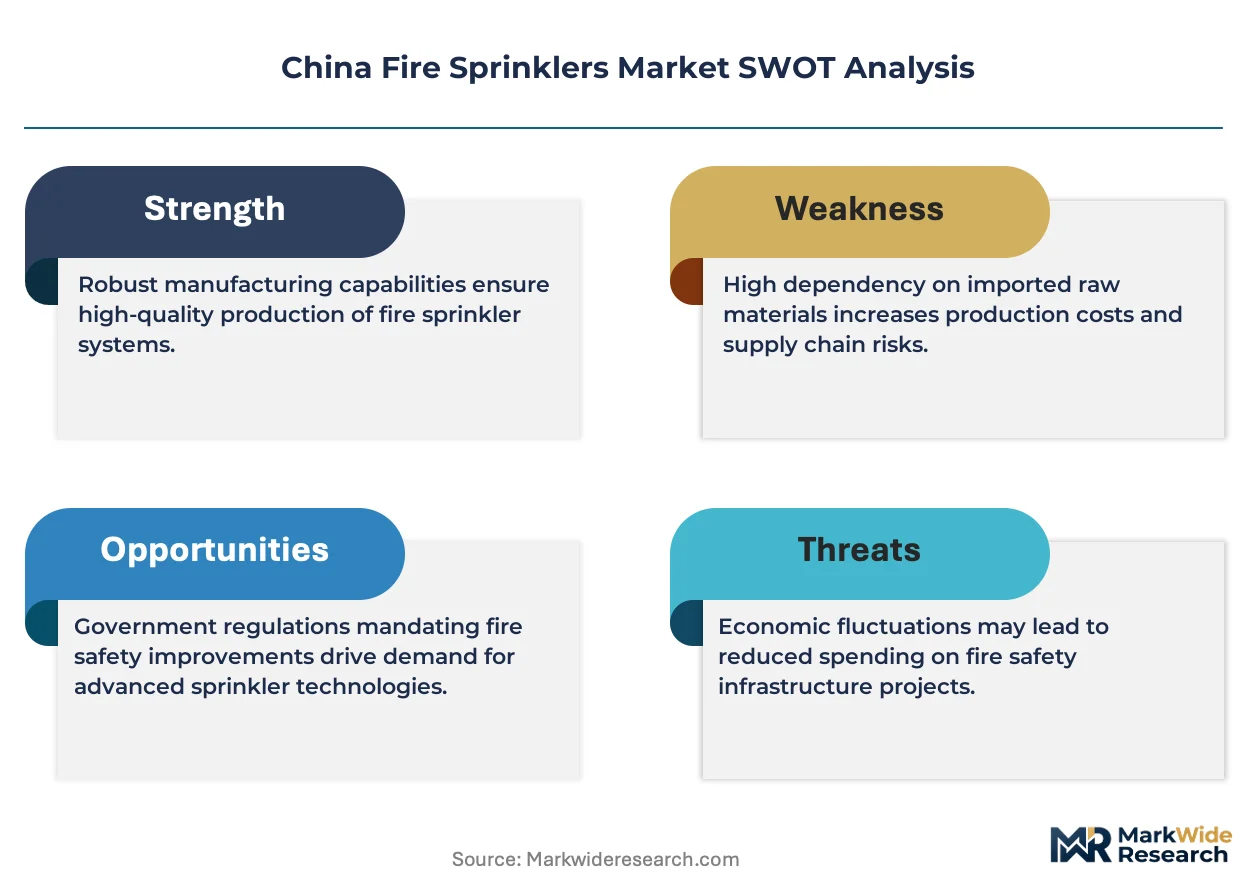
China's fire sprinkler market is being restructured by GB standard revisions from the Ministry of Emergency Management, which are compressing compliance timelines and forcing wholesale system upgrades in existing commercial stock.
Growth Catalysts
- GB 50084 enforcement tightening:The Ministry of Emergency Management's accelerated inspection schedules for high-rise commercial buildings are compelling retrofits of legacy dry pipe systems across Shanghai and Shenzhen office towers.
- Data center construction boom:Pre-action sprinkler configurations are gaining mandatory specification in hyperscale cloud facilities across Hebei and Inner Mongolia, where water damage risk to server infrastructure drives premium hardware selection.
- Petrochemical corridor expansion:Deluge system demand concentrates in Ningbo and Dalian refining complexes, where foam-water sprinkler integration addresses hydrocarbon fire suppression requirements under GB 50151.
Market Restraints
- Brass alloy price volatility:Sprinkler head manufacturing faces margin compression from fluctuating copper and zinc input costs, with forged brass body production concentrated in Zhejiang foundries exposed to metal commodity swings.
- Certification bottlenecks:Provincial fire department type approval procedures create 8-14 month market access delays for imported sprinkler technologies, protecting domestic wet pipe incumbents from European and North American competition.
- Competing suppression technologies:Aerosol and clean agent systems are displacing water-based sprinklers in electrical substations and museum archives where residual water damage exceeds fire loss risk.
Strategic Opportunities
- Central China logistics hubs:Cold storage facilities in Wuhan and Zhengzhou remain underpenetrated by pre-action systems, creating specification openings as pharmaceutical and fresh food distribution networks expand.
- MIIT IoT integration mandates:Addressable sprinkler networks with real-time flow monitoring are capturing new construction specifications, with building management system convergence creating bundled procurement opportunities.
- Green building certification alignment:Municipal incentives in Beijing and Guangzhou for LEED-equivalent construction are elevating smart sprinkler systems with water usage optimization into preferred supplier lists.
Industry Challenges
- Skilled installation technician shortage:Precision threading and hydrostatic testing protocols for K-factor-rated heads require certified technicians, with training pipeline gaps in third and fourth-tier cities delaying project completion.
- Legacy system integration complexity:Addressable retrofit installations in 1990s-era commercial towers face conduit routing conflicts with existing electrical and HVAC infrastructure, inflating labor costs and timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Fire Sprinklers Market |
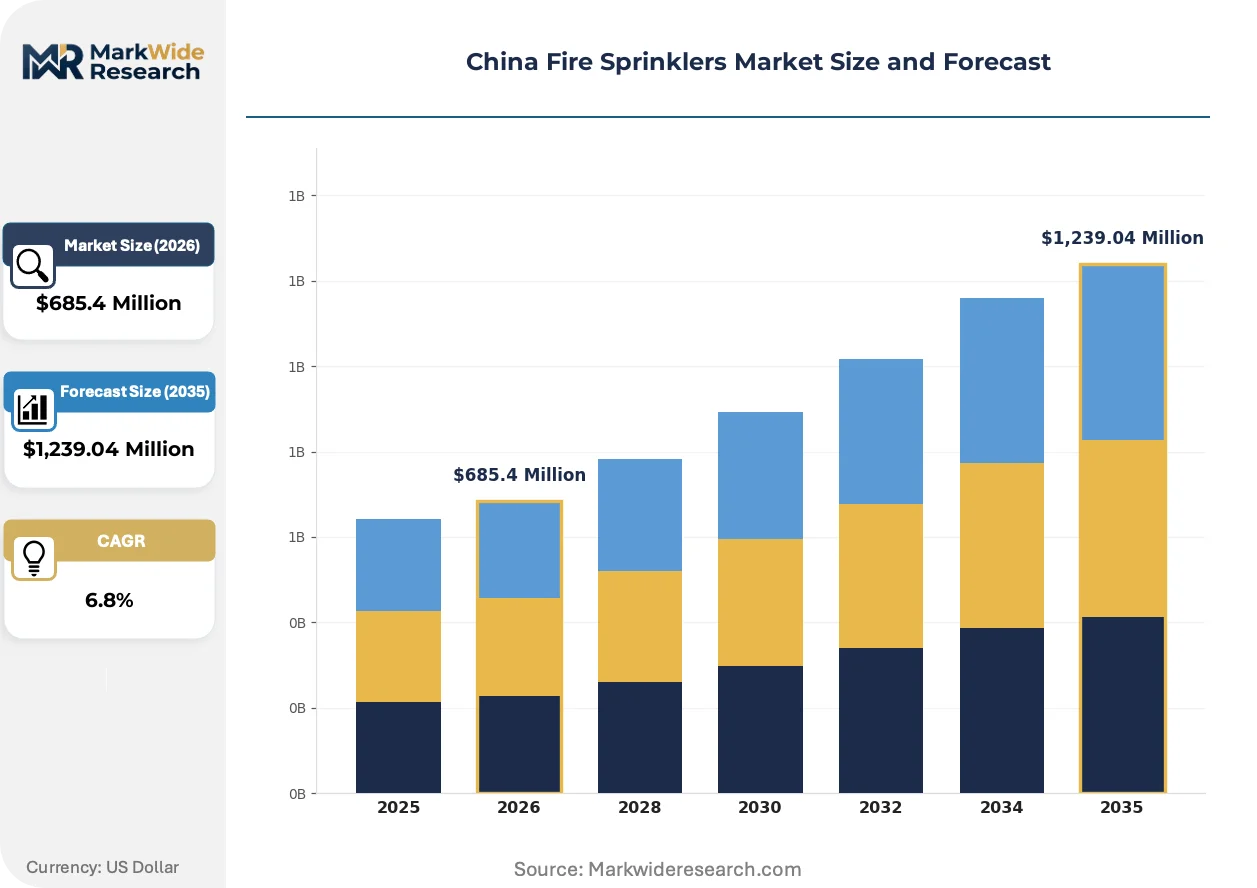
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Pipe, Dry Pipe, Pre-action, Deluge Technology: Conventional, Addressable, Hybrid, Smart End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Retrofit, Upgrades, Maintenance |
| Companies Covered | Jinyuan Technology Development, Quanzhou Xiangrui Fire Technology, JUAND Fire Protection, Fujian Sanhui Fire Equipment, Taizhou Green Rain Valves, Quanzhou Sanxing Fire-Fighting Equipment, Quanzhou Baichuan Firefighting Equipment, Shanxi Goodwill Industrial, Ca-Fire Protection, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Fire Sprinklers Market Strategic Shifts & Innovations
Smart building infrastructure convergence is redefining fire suppression procurement, with detection-alarm-sprinkler integration moving from optional upgrade to baseline specification in premium construction segments.
LoRaWAN-enabled sprinkler monitoring is integrating pressure transducers and flow sensors into addressable loop architectures, permitting centralized fault detection and predictive maintenance scheduling. Property management groups in Shenzhen and Hangzhou are specifying these configurations for 50,000+ square meter mixed-use developments. The technology is integrating facility operations software with emergency response dispatch, compressing alarm-to-activation verification windows from minutes to seconds.
GB standard harmonization with ISO 6182 is forcing domestic manufacturers to redesign deflector geometries and orifice dimensions for international certification compatibility. Jiangsu and Zhejiang producers are retooling machining lines to dual-standard tolerances, with export-bound production requiring separate quality control tracks. Cold storage and data center segments are absorbing the compliance costs fastest, passing premiums through to end-users with limited price sensitivity.
Equipment-as-service contracting is displacing capital purchase models for large industrial installations, with sprinkler system providers retaining ownership and charging per-square-meter protection fees. Petrochemical operators in Ningbo are adopting this structure to transfer obsolescence risk and secure guaranteed response-time commitments. The arrangement concentrates most visibly in facilities with 10-year operational horizons where technology refresh cycles outpace depreciation schedules.
China Fire Sprinklers Market Segmentation
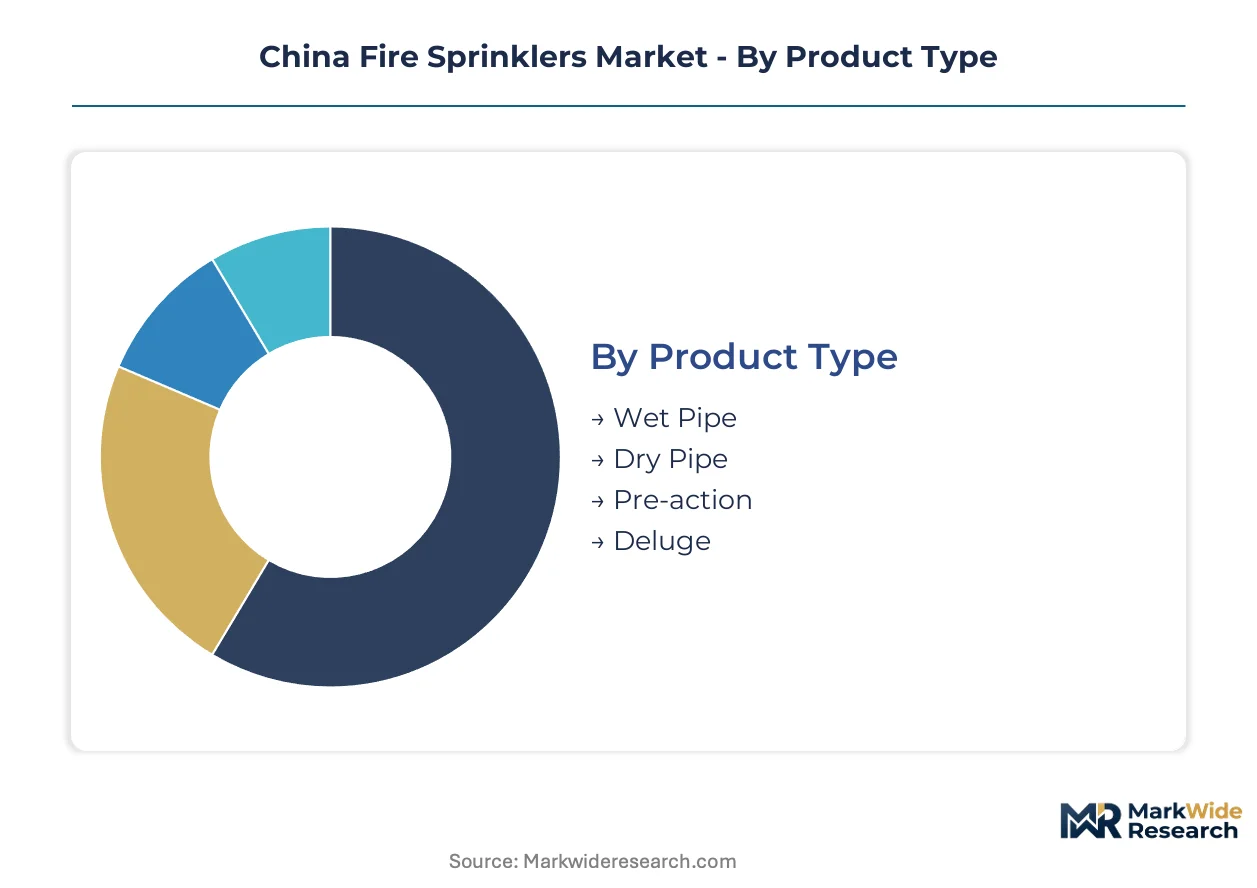
China's fire sprinkler market segments along four critical dimensions that determine procurement patterns, technical specifications, and margin structures. Product type and technology choices drive capital allocation decisions, while end-user verticals and installation modes shape geographic demand distribution across Jiangsu, Zhejiang, and Guangdong provinces.
Product Type:
Capital requirements vary sharply across system architectures, with deluge and pre-action configurations demanding 3-4x the upfront investment of standard wet pipe installations due to specialized valve assemblies and detection integration.
- Wet Pipe:Pressurized water-filled piping with fusible-element heads rated for specific K-factors and activation temperatures. Demand concentrates in Shanghai and Shenzhen residential towers where GB 50084 compliance timelines compress installation schedules and maintenance simplicity outweighs freeze-risk concerns in coastal temperate zones.
- Pre-action:Dual-interlock systems requiring both detection signal and sprinkler activation before water discharge, engineered for water-sensitive environments. Data centers in Hebei and Inner Mongolia mandate these configurations where server infrastructure damage costs dwarf fire suppression expenditures.
- Dry Pipe:Air-pressurized piping for freeze-risk applications with delayed water delivery. Cold storage facilities in northern China deploy these systems despite longer activation latency.
- Deluge:Open-nozzle systems with rapid flooding capability for high-hazard industrial environments. Petrochemical complexes in Ningbo and Dalian specify foam-water deluge integration under GB 50151 hydrocarbon fire protocols.
Most installed capacity flows through wet pipe systems. Expansion is steepest in pre-action configurations.
Technology:
Procurement sophistication divides buyers across detection integration tiers, with premium segments demanding real-time monitoring capabilities that conventional mechanical systems cannot deliver.
- Conventional:Standalone thermosensitive heads without electrical supervision, manufactured through brass forging and precision machining to GB standard tolerances. Legacy commercial towers across Guangdong province retain these systems where retrofit conduit routing faces HVAC and electrical infrastructure conflicts.
- Smart:IoT-enabled networks with pressure transducers, flow sensors, and building management system convergence. Shenzhen and Hangzhou property groups specify these for 50,000+ square meter mixed-use developments where predictive maintenance and alarm-to-activation compression justify hardware premiums.
- Addressable:LoRaWAN-enabled loop architectures permitting individual head identification and centralized fault detection. MIIT integration mandates accelerate specification in new green building certifications.
- Hybrid:Dual-mode systems combining conventional mechanical reliability with selective electronic monitoring. Mid-market industrial facilities in Jiangsu province adopt these for balanced cost-performance positioning.
Conventional technology retains the largest operational base. Smart systems are climbing the fastest as municipal green building incentives in Beijing and Guangzhou elevate water-optimization capabilities.
End User:
Specification authority and budget cycles differ radically across verticals, with industrial procurement driven by safety engineering teams and commercial decisions filtered through property management cost frameworks.
- Industrial:Petrochemical refining, pharmaceutical manufacturing, and logistics warehousing with specialized hazard classifications. Ningbo and Dalian refining complexes drive deluge system specifications under GB 50151 foam-water integration requirements.
- Commercial:High-rise office towers, retail complexes, and hospitality assets where GB 50084 enforcement timelines compel system upgrades. Shanghai and Shenzhen account for disproportionate retrofit demand as Ministry of Emergency Management inspection schedules accelerate.
- Residential:Multi-unit towers and mixed-use developments where wet pipe simplicity and maintenance access dominate procurement. Jinyuan Technology Development anchors supply through manufacturing scale advantages.
- Institutional:Healthcare, education, and government facilities with extended operational horizons and public procurement protocols. Equipment-as-service contracting gains traction here for obsolescence risk transfer.
Industrial verticals absorb the highest per-square-meter protection spending. Commercial stock is gaining share fastest as compliance deadlines force wholesale upgrades.
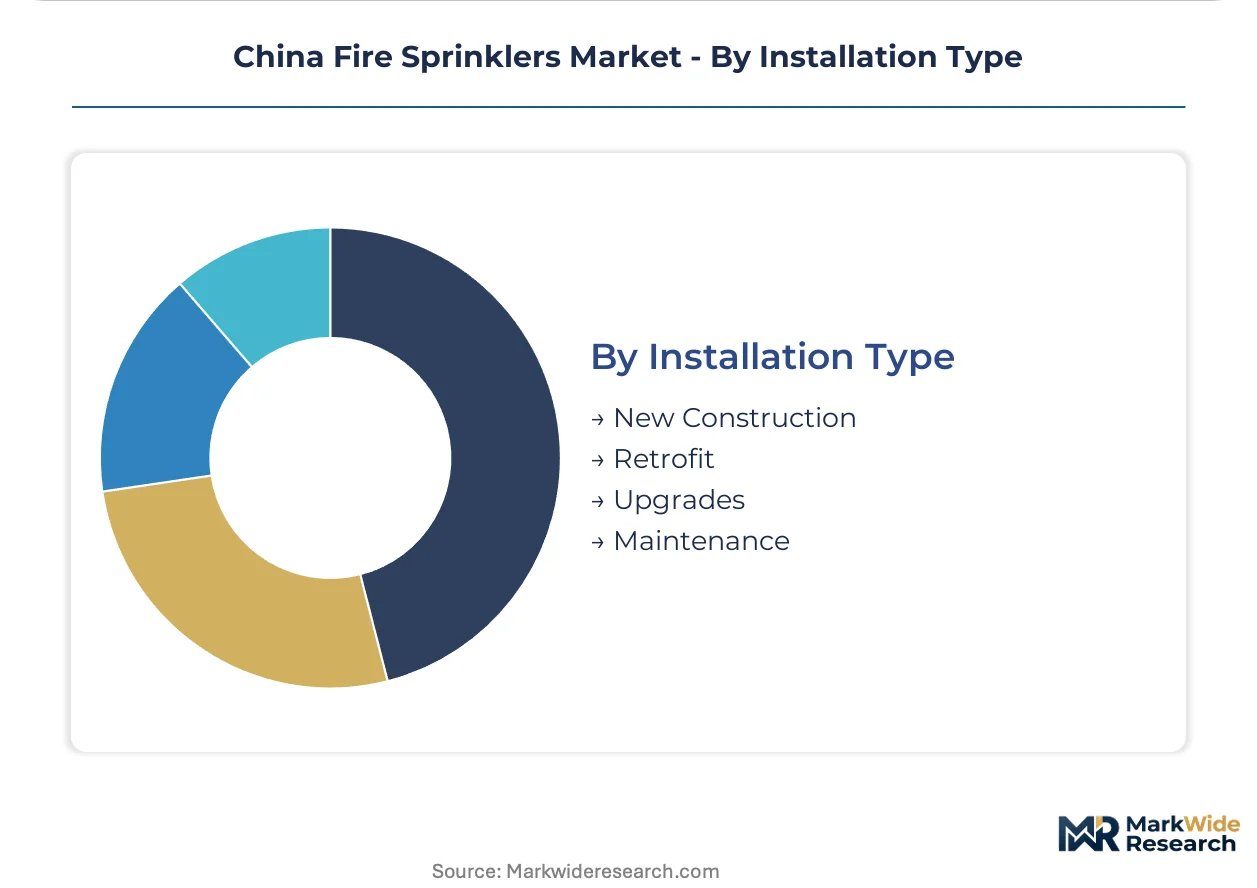
Installation Type:
Project economics bifurcate between greenfield specifications with integrated design flexibility and brownfield constraints where legacy infrastructure dictates technical compromise.
- New Construction:Integrated sprinkler-architectural design with optimal head placement and conduit routing. Addressable and smart system penetration peaks here as MIIT IoT mandates align with construction timelines.
- Retrofit:System replacement in existing structures with infrastructure conflict resolution. 1990s-era Shanghai and Shenzhen towers face inflated labor costs from electrical and HVAC routing constraints.
- Upgrades:Partial system enhancement addressing code compliance gaps without full replacement. GB standard revision cycles drive cyclical demand spikes.
- Maintenance:Recurring inspection, testing, and component replacement services. Skilled technician shortages in third and fourth-tier cities create service delivery bottlenecks.
New construction commands specification authority for technology selection. Retrofit activity is expanding most quickly as accelerated inspection schedules compress compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fire sprinkler industry traces its manufacturing lineage to Zhejiang and Fujian provinces, where brass forging and precision machining clusters emerged in the 1990s to serve domestic construction booms. These coastal manufacturing bases now supply both domestic installation demand and export markets.
Yangtze River Delta
Shanghai and Jiangsu province drive wet pipe system demand through high-rise commercial retrofits. GB 50084 enforcement timelines from the Ministry of Emergency Management compress project schedules. Suzhou and Nantong manufacturing corridors supply forged brass heads to construction sites across the region.
Pearl River Delta
Shenzhen and Guangzhou property groups specify addressable sprinkler networks for 50,000+ square meter mixed-use developments. MIIT IoT integration mandates accelerate smart system procurement. Dongguan fabrication clusters produce K-factor-rated heads for southern China's temperate coastal zones.
Beijing-Tianjin-Hebei
Data center construction in Hebei province mandates pre-action configurations for hyperscale cloud facilities. Municipal green building incentives in Beijing elevate water-optimization capabilities into preferred specifications. Tianjin port logistics support component import for specialized valve assemblies.
Sichuan-Chongqing
Cold storage expansion for pharmaceutical distribution drives dry pipe system specifications in Chengdu and Chongqing. Western China infrastructure investment lags coastal adoption curves. Local technician training pipelines face gaps that delay project completion timelines.
Shandong Peninsula
Petrochemical refining complexes in Qingdao and Yantai specify foam-water deluge integration under GB 50151 hydrocarbon fire protocols. Industrial safety engineering teams command specification authority for high-hazard installations. Weihai and Yantai foundries supply specialized nozzle configurations.
China Fire Sprinklers Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration tiers, with addressable and smart system specialists capturing hardware premiums while conventional wet pipe fabricators compete on manufacturing scale. The vendor base organizes around three strategic archetypes: integrated technology providers bundling detection and suppression, specialized deluge system engineers for petrochemical applications, and scale-driven wet pipe producers for residential towers. Dominant competitive moves include geographic expansion through provincial distribution networks and portfolio diversification into maintenance services.
Among Zhejiang and Fujian-based manufacturers, Jinyuan Technology Development, Fujian Sanhui Fire Equipment, and Quanzhou Xiangrui Fire Technology occupy distinct positioning archetypes. Jinyuan exemplifies the scale-driven tier serving high-volume residential construction. Fujian Sanhui represents specialized engineering capabilities for industrial hazard classifications. Quanzhou Xiangrui anchors southern China distribution density through Fujian province coverage. These companies collectively illustrate how regional manufacturing concentration produces differentiated competitive positioning without national consolidation.
| Leading Market Players |
|---|
| Jinyuan Technology Development |
| Quanzhou Xiangrui Fire Technology |
| JUAND Fire Protection |
| Fujian Sanhui Fire Equipment |
| Taizhou Green Rain Valves |
| Quanzhou Sanxing Fire-Fighting Equipment |
| Quanzhou Baichuan Firefighting Equipment |
| Shanxi Goodwill Industrial |
| Ca-Fire Protection |
| Others |
Cost & Logistics Intelligence
Copper and zinc LME benchmark volatility cascades through Zhejiang foundry operations into three distinct hardware pricing tiers, with forged brass body costs determining whether sprinkler heads land in premium addressable configurations or economy-grade wet pipe bundles for residential towers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement across China's construction sector. Certification grade under GB 50084 and GB 50151 standards differentiates tiers, with MIIT-compliant IoT-enabled systems commanding hardware premiums while conventional wet pipe heads compete on manufacturing scale. Cost compression in the economy tier is intensifying because brass alloy input volatility squeezes margins at Zhejiang forging operations. Residential developers in third and fourth-tier cities exhibit highest price sensitivity, while data center operators in Hebei and Inner Mongolia absorb premiums for pre-action configurations without negotiation.
Supply Chain Analysis
Skilled machining technician shortages in Wenzhou and Ningbo constrain output expansion at precision forging operations. Supply concentrates in Zhejiang and Fujian provinces, with brass ingot processing and K-factor head machining forming contiguous manufacturing clusters. Raw material dependencies center on copper-zinc alloy feedstock, electronic components for addressable systems, and specialized valve assemblies for pre-action configurations. Single-source vulnerability runs through provincial fire department type approval bottlenecks that delay imported technology market access. Distribution runs through construction contractor procurement channels and equipment-as-service providers for industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's fire sprinkler market functions as a geographic-arbitrage play where coastal manufacturing clusters in Zhejiang and Fujian exploit 15-20% cost advantages over inland assembly operations while GB standard harmonization with ISO 6182 creates export certification premiums for dual-standard producers.
For Market Incumbents: Anchor manufacturing scale advantages in wet pipe residential supply through captive brass forging capacity in Zhejiang. Defend against aerosol and clean agent displacement in electrical substation applications by accelerating smart system certification under MIIT IoT mandates. Vertical integration into addressable detection hardware preserves margin capture as building management system convergence elevates bundled procurement specifications. For New Entrants and Emerging Players: A 40-50% price-point gap between premium addressable systems and economy wet pipe configurations creates entry space for hybrid technology specialists. Cold storage facilities in Wuhan and Zhengzhou represent the most penetrable segment, with pre-action system underpenetration offering specification openings as pharmaceutical distribution networks expand. Target equipment-as-service contracting for petrochemical operators seeking obsolescence risk transfer. For Investors and Strategic Acquirers: Asymmetric upside sits with addressable technology specialists possessing dual GB-ISO certification capability and established provincial fire department relationships. Long-term viability across the 5-10 year window hinges on positioning ahead of MIIT mandate acceleration and green building incentive expansion. The signal to watch is GB 50084 revision timing that could compress retrofit compliance windows and concentrate demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Forging | Captive Zhejiang foundry capacity insulates margin compression from copper-zinc LME volatility. |
| Dual GB-ISO Certification Investment | Retooled machining lines unlock export premiums as Jiangsu producers face harmonization deadlines. |
| Equipment-as-Service Contracting | Petrochemical operators in Ningbo transfer obsolescence risk through per-square-meter protection fees. |
| IoT Sensor Integration Partnerships | LoRaWAN-enabled flow monitoring aligns with MIIT mandates for 50,000+ square meter developments. |
| Central China Distribution Expansion | Wuhan and Zhengzhou cold storage penetration addresses pharmaceutical logistics underpenetration. |
Research Approach
Bottom-up construction sector modeling reconciled against top-down manufacturing output tracking forms the analytical core of this study. Primary interviews with fire protection system engineers, Ministry of Emergency Management compliance officers, property management procurement directors, and Zhejiang foundry operations managers combined with secondary validation from GB standard revision drafts, provincial fire department type approval records, customs brass alloy import data, and MIIT IoT infrastructure policy circulars. Triangulation across these sources anchors volume and value estimates.
Historical installation trendline analysis across wet pipe, pre-action, dry pipe, and deluge system architectures informs projection framework construction. Segmentation dimensions modeled include product type, technology tier, end-user vertical, and installation mode across the analysis window. CAGRs derive from fitted growth curves applied to construction permit data and industrial facility commissioning records. Forecast inputs incorporate GB 50084 enforcement acceleration scenarios and data center construction pipeline tracking in Hebei and Inner Mongolia.
Caveats apply where brass alloy commodity spikes, GB standard revision delays, or technician training pipeline gaps could materially shift the outlook. Forecasts reflect assumptions about MIIT mandate implementation pace and provincial fire department approval efficiency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Casting Equipment Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Collating Machinery Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Grout Bags Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Asia-Pacific Road Marking Machine Market