
 Global Industrial Services Market | 2026-2036
Global Industrial Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Services Market Outlook
German engineering service providers is repositioning toward digital-first maintenance contracts as industrial clients phase out reactive repair models. Schneider Electric SE leverages its IoT-enabled asset management platforms to capture recurring revenue streams from energy-intensive facilities. ABB Ltd. anchors its competitive stance through robotics-integrated field service capabilities that reduce plant downtime for automotive manufacturers. Siemens AG differentiates via its vertical software stack that connects edge diagnostics to cloud-based lifecycle analytics.
Global Industrial Services encompass the technical and operational support activities that sustain capital equipment performance, including scheduled maintenance protocols, emergency repair interventions, system installation and commissioning, and engineering consulting engagements that optimize asset utilization rates across production environments. These services employ condition-monitoring sensors, remote diagnostics platforms, and automated spare-part logistics to maintain equipment availability above operational thresholds. Maintenance and Repair services command the largest share of current revenue as aging installed bases across manufacturing and utilities require systematic overhaul cycles. IoT and Automation technologies represent the fastest-expanding technology dimension as real-time vibration analysis and autonomous inspection systems displace manual monitoring routines. Aerospace and Automotive end users generate premium-margin demand due to stringent uptime requirements and traceability standards that necessitate certified technician networks.
OSHA mandates in the United States and REACH compliance obligations across Europe are elevating contractor certification requirements and documentation standards for hazardous environment interventions. The EU AI Act introduces conformity assessment burdens for automated diagnostic systems deployed in safety-critical industrial settings. Stakeholders must evaluate how regulatory fragmentation between EPA emissions protocols and emerging CSRD sustainability disclosure rules will reshape service pricing structures and geographic deployment priorities.
Market Dynamics
Industrial facility operators are abandoning break-fix maintenance models in favor of predictive service architectures powered by edge-connected sensor networks, compressing contract renewal cycles and elevating data analytics capabilities above mechanical repair skills in vendor selection criteria.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:The F-Gas Regulation is accelerating refrigerant system retrofits across process manufacturing, generating sustained service contract demand for leak detection and thermal optimization protocols.
- India PLI scheme factory modernization:Production-linked incentive disbursements are funding brownfield automation upgrades that require commissioning support and multi-year maintenance commitments from domestic and foreign service providers.
- Predictive analytics platforms:Vibration monitoring and thermal imaging algorithms are converting emergency repair revenue into recurring subscription models with higher customer lifetime value.
Market Restraints
- Certified technician scarcity:Specialized training requirements for hazardous environment interventions under OSHA and REACH protocols are extending workforce recruitment timelines and inflating labor cost structures.
- Spare parts supply concentration:Precision component sourcing remains concentrated in German and Japanese industrial clusters, exposing service operations to geopolitical disruption and extended lead times.
- EU AI Act conformity assessment:Automated diagnostic systems deployed in safety-critical settings face mandatory third-party certification that delays product launch cycles and elevates compliance expenditure.
Strategic Opportunities
- India domestic manufacturing expansion:Greenfield electronics and pharmaceutical plants under PLI incentives require full-lifecycle service partnerships spanning installation through decommissioning.
- Digital twin convergence with IoT:Physics-based simulation models integrated with live sensor feeds are enabling virtual commissioning services that reduce physical prototype iterations.
- Outcome-based performance contracts:Guaranteed uptime agreements are displacing time-and-materials billing in automotive and aerospace verticals, locking in multi-year revenue visibility.
Industry Challenges
- Cyber-physical security integration:Connected maintenance platforms must satisfy IEC 62443 industrial cybersecurity standards while preserving real-time diagnostic latency requirements.
- Legacy system interoperability:Brownfield facilities operate heterogeneous equipment generations that resist standardized API integration, forcing costly custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Services Market |
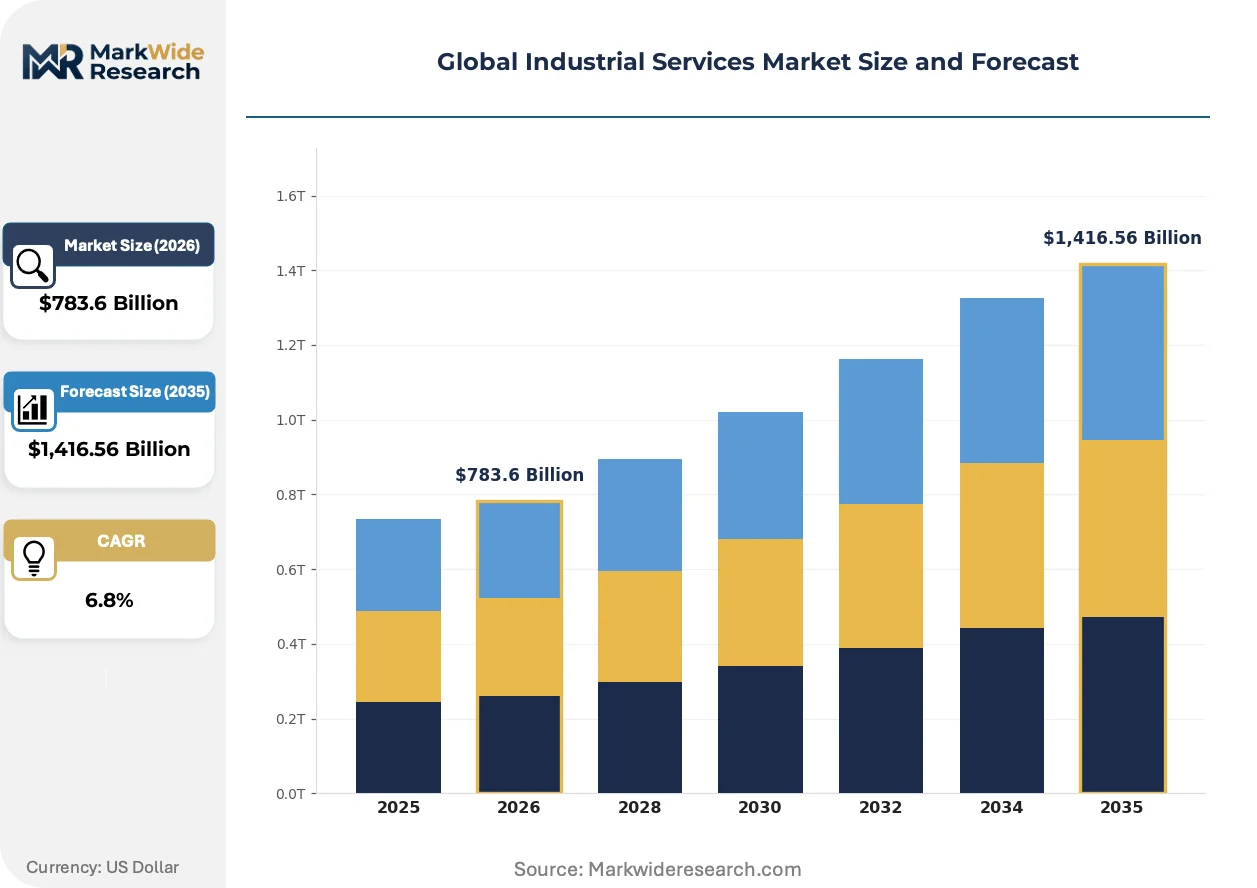
| Market Size in 2026 | $783.6 Billion |
| Market Size in 2035 | $1,416.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Installation, Consulting Technology: IoT, Robotics, AI, Automation End User: Aerospace, Manufacturing, Automotive, Utilities Distribution Channel: Direct Sales, Online Platforms, Distributors, Resellers |
| Companies Covered | Schneider Electric SE, ABB Ltd., Mitsubishi Electric Corporation, Baker Hughes Company, Schlumberger Limited, Siemens AG, Honeywell International Inc., Halliburton Company, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Services Market Strategic Shifts
Service delivery models are converging around autonomous inspection systems and cloud-native analytics platforms that compress diagnostic cycles from days to minutes while shifting revenue recognition from episodic interventions to continuous monitoring subscriptions.
Autonomous mobile robots equipped with ultrasonic thickness gauges and infrared cameras are expanding into refinery and chemical processing facilities where confined space entry restrictions previously mandated human inspection teams. Petrochemical operators in the US Gulf Coast are deploying these systems at scale following EPA emissions enforcement actions. The technology is expanding into adjacent verticals including pulp processing and cement manufacturing where dust-laden environments accelerate equipment degradation.
The EU AI Act's risk-based classification framework is mandating conformity assessments for machine-learning diagnostic tools deployed in safety-critical industrial contexts. Equipment manufacturers must now document training data provenance and algorithmic transparency before deploying automated fault detection in chemical processing or nuclear auxiliary systems. German engineering service providers are restructuring quality management systems to accommodate notified body oversight of AI-enabled maintenance recommendations.
Asset-intensive manufacturers are consolidating vendor relationships around integrated service platforms that bundle spare parts logistics, remote diagnostics, and field technician dispatch through single contractual frameworks. Automotive OEMs in Stuttgart and Wolfsburg are piloting these arrangements with preferred providers, displacing fragmented multi-vendor maintenance structures. The consolidation is most visible in German automotive clusters where just-in-sequence production tolerances eliminate redundancy in equipment availability planning.
Global Industrial Services Market Segmentation
Service procurement patterns diverge sharply across industrial verticals. Certification requirements, technology maturity, and contract structures reshape how vendors structure their offerings and how buyers evaluate total cost of ownership.
Service Type:
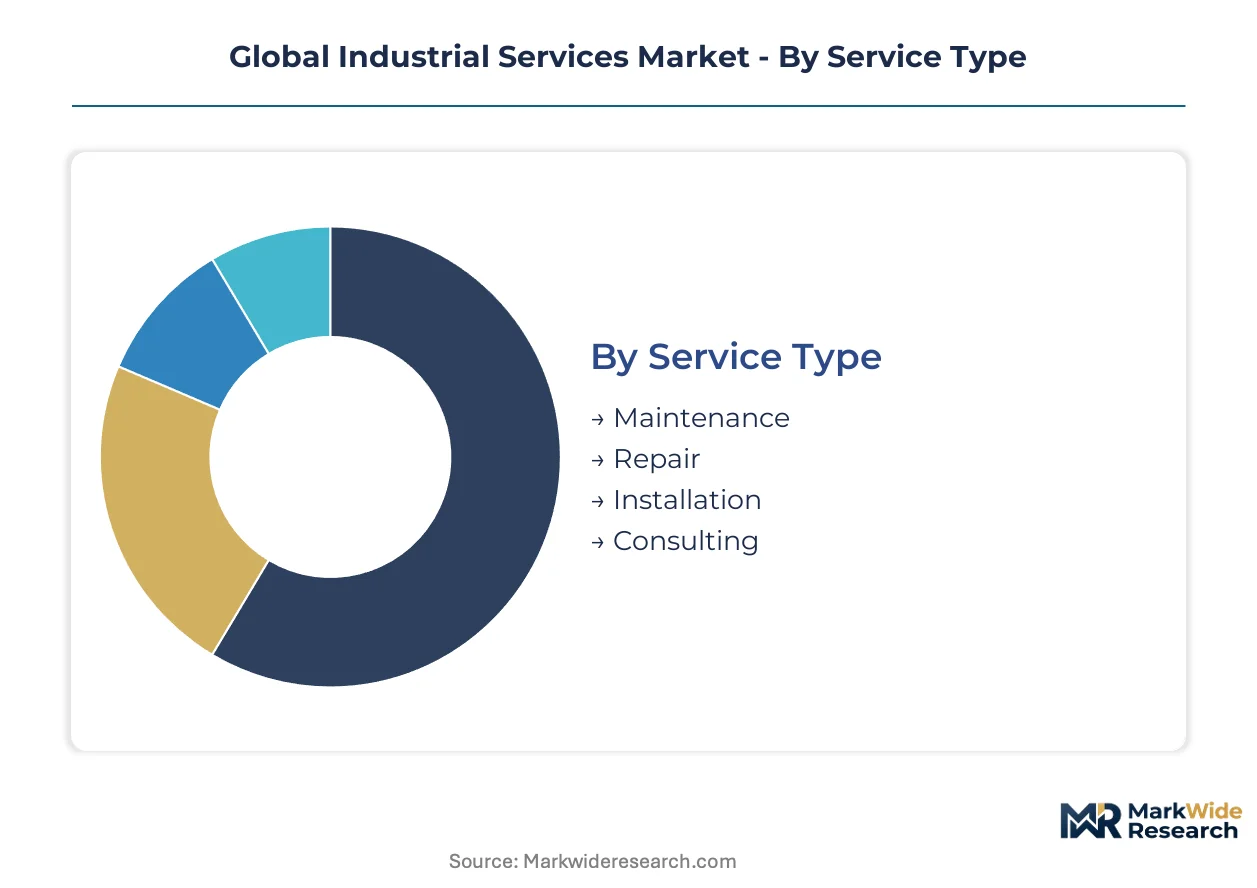
OSHA and REACH protocols impose tiered technician certification burdens that vary by intervention complexity. Emergency repair mandates hazardous environment credentials. Predictive maintenance contracts require data analytics competencies.
- Maintenance:Scheduled preventive protocols sustain equipment availability above operational thresholds. German automotive clusters in Stuttgart and Wolfsburg concentrate demand as just-in-sequence production tolerances eliminate redundancy.
- Repair:Emergency interventions restore failed assets to operational status. US Gulf Coast petrochemical operators generate premium-margin demand following EPA emissions enforcement actions that mandate rapid turnaround.
- Installation:Greenfield commissioning and brownfield upgrade deployment.
- Consulting:Engineering optimization engagements that improve asset utilization rates.
Maintenance sits at the top of the volume ranking, with Repair climbing the fastest as aging installed bases require systematic overhaul cycles.
Technology:
Capital deployment intensity separates these segments. Hardware-heavy robotics and automation platforms demand upfront infrastructure investment. Software-centric AI and IoT layers convert toward recurring subscription economics.
- IoT:Edge-connected sensor networks transmit vibration, thermal, and acoustic data to cloud analytics platforms. Indian electronics manufacturers under PLI scheme incentives deploy these systems at scale for factory modernization.
- Robotics:Autonomous mobile platforms equipped with ultrasonic and infrared inspection capabilities. US refinery operators deploy these systems where confined space entry restrictions previously mandated human teams.
- AI:Machine-learning diagnostic tools face EU AI Act conformity assessments for safety-critical deployments.
- Automation:Programmable control systems that integrate with legacy brownfield equipment through custom gateway development.
IoT commands the largest revenue share, with AI gaining share fastest as automated fault detection displaces manual monitoring routines.
End User:
Traceability standards and uptime requirements dictate service provider selection criteria. Aerospace and automotive verticals impose certified technician networks. Utilities prioritize asset lifecycle economics over speed.
- Aerospace:MRO services satisfy stringent airworthiness documentation and parts traceability mandates. FAA certification requirements structure vendor qualification timelines and technician training protocols.
- Automotive:Just-in-sequence manufacturing tolerances demand guaranteed uptime agreements. German OEMs in Wolfsburg pilot integrated service platforms that bundle logistics, diagnostics, and dispatch.
- Manufacturing:Process industries and discrete production facilities with heterogeneous equipment generations.
- Utilities:Power generation and grid infrastructure with extended asset depreciation horizons.
Automotive generates the steepest pricing premiums, with Aerospace expanding most quickly as fleet renewal cycles accelerate MRO demand.
Distribution Channel:
Contract scale and customization depth determine channel selection. Direct relationships dominate complex multi-year performance agreements. Intermediaries capture transactional spare parts and break-fix demand.
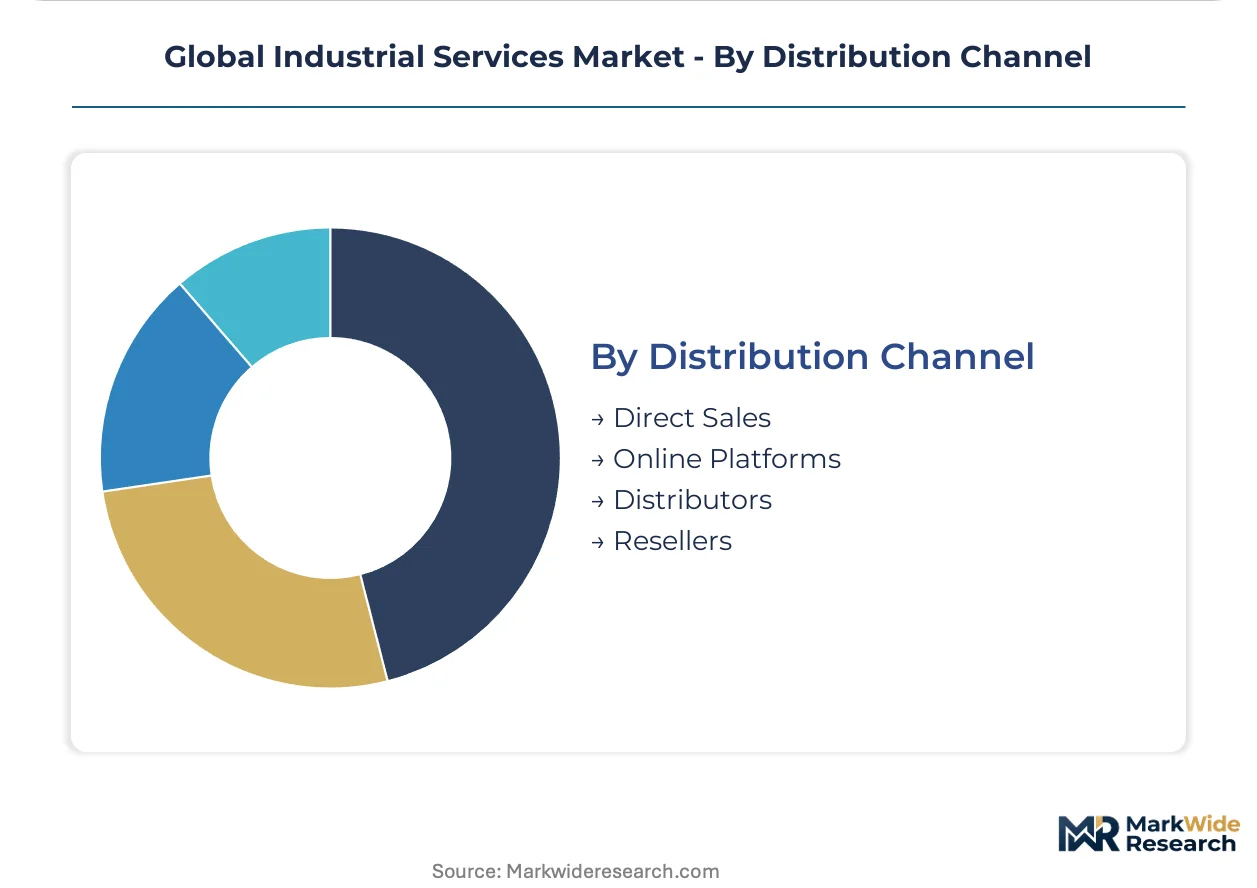
- Direct Sales:Enterprise account teams negotiate outcome-based performance contracts with automotive and aerospace OEMs. These arrangements lock in multi-year revenue visibility and displace fragmented multi-vendor structures.
- Distributors:Regional inventory positioning for emergency spare parts fulfillment. German and Japanese industrial clusters concentrate precision component sourcing, exposing operations to geopolitical disruption.
- Online Platforms:Self-service procurement for standardized maintenance consumables and diagnostic subscriptions.
- Resellers:Value-added integration services for mid-market facilities lacking in-house engineering capabilities.
Direct Sales anchors the highest contract values, with Online Platforms climbing fastest as remote diagnostics convert toward continuous monitoring subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting industrial service procurement toward jurisdictions with harmonized compliance frameworks. Germany's REACH protocols and India's PLI incentives create divergent cost-of-compliance environments that reshape vendor deployment priorities.
United States
OSHA mandates elevate contractor certification requirements for hazardous environment interventions. EPA emissions enforcement actions across the US Gulf Coast generate premium-margin repair demand from petrochemical operators. Houston-area refineries deploy autonomous inspection systems at scale following regulatory pressure.
Germany
EU Green Deal energy-efficiency mandates accelerate refrigerant system retrofits across process manufacturing. F-Gas Regulation compliance generates sustained service contract demand for leak detection protocols. Stuttgart and Wolfsburg automotive clusters pilot integrated service platforms that bundle logistics and dispatch.
India
PLI scheme disbursements fund brownfield automation upgrades requiring commissioning support. Domestic electronics and pharmaceutical plants demand full-lifecycle service partnerships spanning installation through decommissioning. Maharashtra and Gujarat factory modernization concentrates demand for predictive maintenance contracts.
China
Dual carbon goals tighten energy-efficiency mandates for industrial equipment retrofits. MIIT standards accelerate factory digitization programs that require IoT-enabled asset management integration. Yangtze River Delta manufacturing bases expand predictive service architectures for aging installed bases.
Japan
METI industrial policy prioritizes robotics-integrated field service capabilities for automotive manufacturers. JIS standards structure technician certification requirements for precision equipment maintenance. Nagoya-area automotive suppliers consolidate vendor relationships around guaranteed uptime agreements.
Global Industrial Services Market Competitive Environment
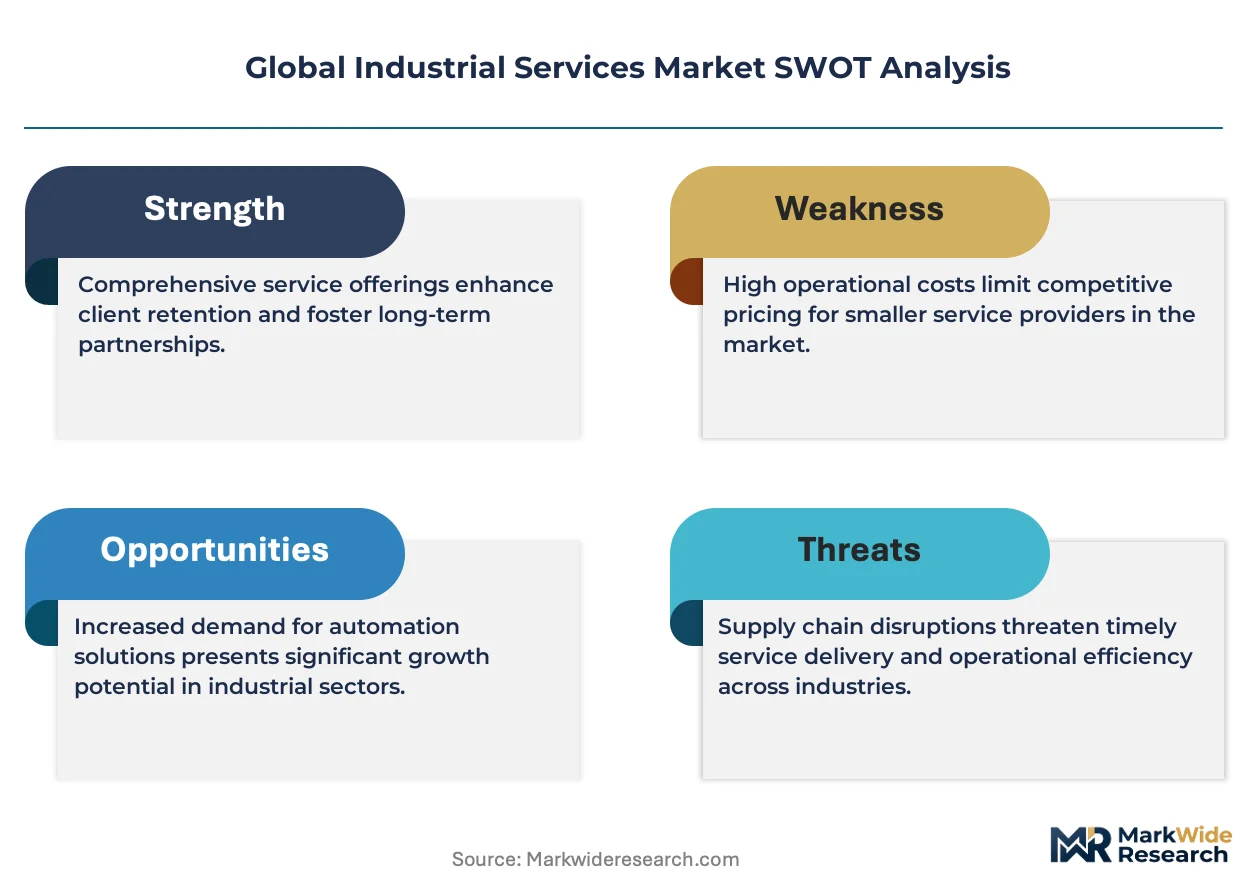
Established producers occupy the standard tier; emerging entrants pursue digital-native service architectures. The vendor base separates into three maturity tiers: legacy engineering conglomerates with captive hardware portfolios, software-centric analytics specialists, and regional maintenance contractors. Two dominant competitive moves structure rivalry: strategic partnerships binding equipment manufacturers to service platforms, and backward integration into precision component sourcing.
Within the diversified industrial conglomerate tier, Schneider Electric SE, ABB Ltd., and Siemens AG exemplify archetypes that anchor competitive positioning through vertical software integration. These entities represent the premium-service vector where outcome-based performance contracts displace time-and-materials billing. Their geographic footprints span multiple regulatory jurisdictions, positioning them to capture recurring revenue from energy-intensive facilities undergoing EU Green Deal compliance retrofits.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd. |
| Mitsubishi Electric Corporation |
| Baker Hughes Company |
| Schlumberger Limited |
| Siemens AG |
| Honeywell International Inc. |
| Halliburton Company |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Certified technician labor costs cascade through service pricing tiers, with OSHA and REACH compliance burdens inflating premium-grade intervention rates while commoditized maintenance contracts absorb margin compression from Indian and Chinese labor arbitrage. Energy-intensive facilities in Germany and the US Gulf Coast face divergent input cost structures as F-Gas retrofit mandates and EPA enforcement actions reshape contractor qualification economics.
Pricing Analysis
Distributor margins compress emergency repair pricing as regional inventory positioning adds 15-25% markup layers before end-user settlement. Three-tier pricing structure across premium, standard, and economy levels separates certified hazardous-environment interventions from routine preventive maintenance and break-fix commodity work. Pricing pressure stems from Indian PLI scheme factory modernization, where domestic service providers undercut foreign incumbents on commissioning contracts. Automotive OEMs in Stuttgart and Wolfsburg exhibit lowest price sensitivity due to just-in-sequence production tolerances that eliminate equipment availability redundancy.
Supply Chain Analysis
Dual-sourcing requirements for precision components mandate multi-supplier qualification across German, Japanese, and South Korean industrial clusters, extending procurement timelines for vibration sensors and thermal imaging hardware. Spare parts logistics draw from concentrated manufacturing bases in Stuttgart, Nagoya, and Seoul, exposing service operations to geopolitical disruption and extended lead times. Single-source vulnerability concentrates in specialized robotics-integrated field service equipment. Distribution runs through direct enterprise account teams for multi-year performance contracts, with regional distributors capturing transactional emergency parts demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Industrial Services Market functions as a stable compounder, with recurring revenue from predictive maintenance subscriptions generating predictable cash flows as manufacturing facilities abandon break-fix models.
For Market Incumbents: Anchor competitive positioning through backward integration into precision component sourcing, reducing exposure to German and Japanese supply concentration. Expand captive technician training academies to address OSHA and REACH certification scarcity that extends recruitment timelines. Defend margin structure by converting time-and-materials contracts to outcome-based performance agreements with guaranteed uptime provisions. For New Entrants and Emerging Players: Begin with digital-native predictive analytics platforms targeting mid-market manufacturing facilities in Maharashtra and Gujarat under PLI scheme incentives. White-space opportunity concentrates in brownfield automation upgrades requiring custom gateway development for legacy system interoperability. Pursue channel partnerships with established distributors to bypass direct sales force buildout costs. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional maintenance contractors lack IoT platform capabilities to compete for integrated service contracts. Long-term viability favors vendors with vertical software stacks connecting edge diagnostics to cloud analytics. Target acquisition profile: mid-cap specialists with certified technician networks in aerospace and automotive verticals. Monitor EU AI Act conformity assessment timelines as inflection indicator for automated diagnostic system deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Reduces lead time exposure from German and Japanese supply concentration for critical spare parts. |
| Predictive Analytics Platform Development | Converts emergency repair revenue to recurring subscriptions with higher customer lifetime value. |
| Certified Technician Training Academy Expansion | Addresses OSHA and REACH compliance burdens that constrain workforce scaling in hazardous environments. |
| Outcome-Based Performance Contract Rollout | Locks in multi-year revenue visibility with automotive OEMs in Stuttgart and Wolfsburg clusters. |
| Digital Twin Integration with IoT Sensors | Enables virtual commissioning services that reduce physical prototype iterations for brownfield upgrades. |
Study Parameters
Coverage spans Germany, the United States, India, China, and Japan, with primary inputs from each market through structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Secondary validation draws from SEC 10-K filings, EU regulatory submissions under REACH and F-Gas frameworks, Indian PLI scheme disbursement records, and customs trade data for precision component flows. Bottom-up and top-down triangulation reconciles facility-level service contract values with aggregate vendor revenue disclosures.
Granularity-level modeling distinguishes service type, technology layer, end-user vertical, and distribution channel dimensions across the projection horizon. Segment-specific CAGRs derive from installed base aging curves, regulatory compliance deadline clustering, and technology substitution rates for IoT-enabled asset management. Forecast inputs incorporate EU AI Act conformity assessment timelines, PLI scheme incentive disbursement schedules, and EPA enforcement action intensity indices.
Several conditions sit outside the modeled scope, including abrupt geopolitical disruption to German-Japanese component trade corridors and unanticipated cybersecurity breaches of IEC 62443-certified maintenance platforms. Forecasts reflect assumptions around steady regulatory enforcement continuity and stable technician training pipeline throughput. Deviation in EU AI Act implementation velocity or Indian PLI scheme funding allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Composite Autoclave Repair Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
Industrial Maintenance Products Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
Train Contractor Market
Construction Services
Dust Suppression Control Market
Construction Services
Remote Construction Market
Construction Services
Hardbanding Services Market
Construction Services
Die Casting Services Market
Construction Services
MENA Architectural Services Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Grease Trap Service Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Excavating Contractor Market