
 Composite Autoclave Repair Market | 2026-2036
Composite Autoclave Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Autoclave Repair Market Insights
The gap between certified aerospace-grade autoclave repair and general industrial refurbishment is broadening as thermal imaging and ultrasonic testing certifications diverge. Lufthansa Technik AG leverages its Hamburg base to dominate European wide-body composite MRO. HAECO anchors Asia-Pacific capacity through Hong Kong Aircraft Engineering Company Limited facilities. Hexcel specializes in prepreg-compatible repair systems that sustain OEM warranty compliance.
Composite autoclave repair encompasses restoration of pressure vessels that cure fiber-reinforced polymer components using controlled heat up to 400°C and pressure exceeding 6 bar, restoring vacuum integrity and thermal uniformity for aerospace, marine, and wind energy manufacturing. Structural reinforcement leads repair type demand as carbon-fiber primary structures age in service, while digital radiography represents the fastest-expanding technology segment as defect detection standards tighten. Predictive maintenance emerges as the highest-margin service model, converting emergency repair contracts into recurring revenue streams.
FAA airworthiness directives and EASA Part 145 maintenance organization approvals shape North American and European market access, mandating traceable repair documentation and technician certification. MEE environmental compliance in China and EPA emissions standards in the United States constrain autoclave operating permits, redirecting investment toward closed-loop thermal systems. Stakeholders must weigh regulatory certification costs against captive in-house repair capabilities as OEM warranty terms tighten.
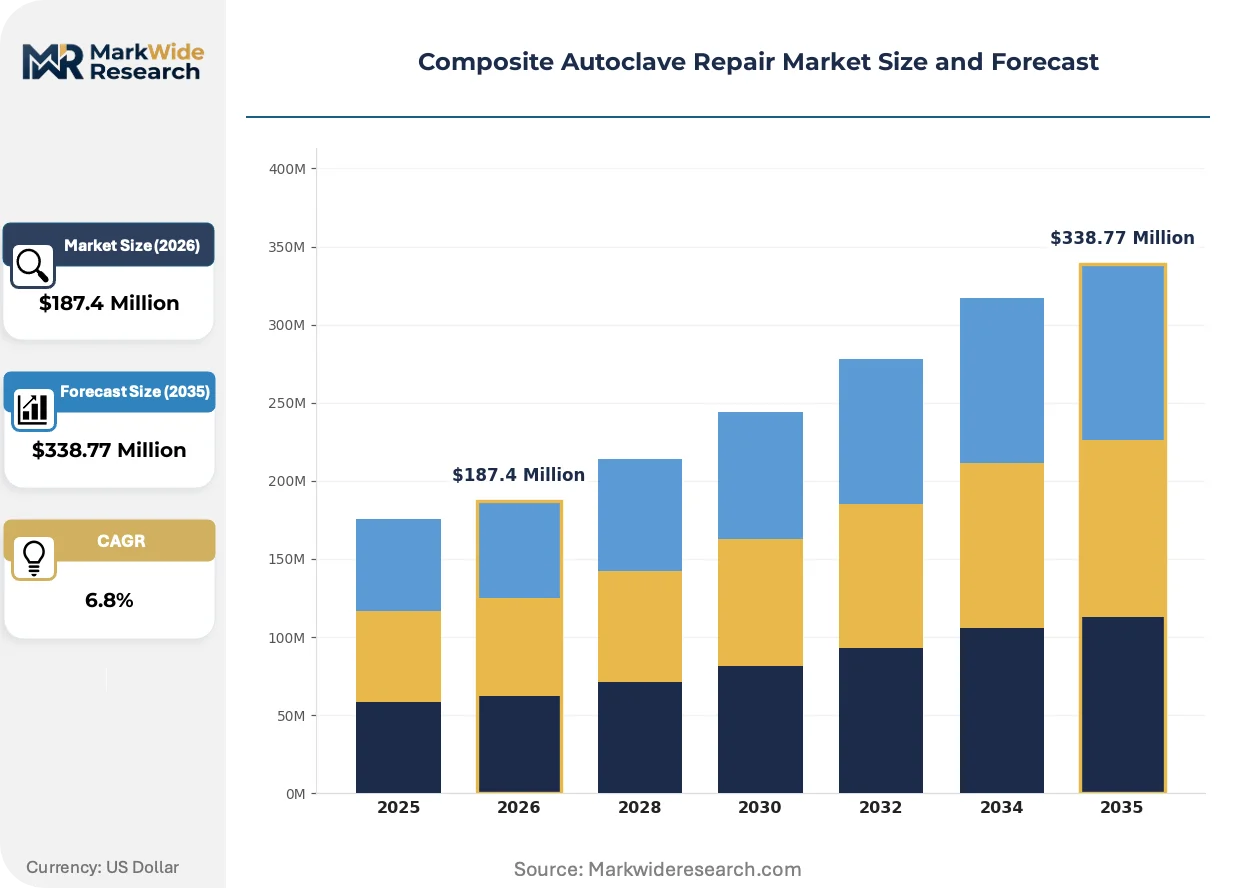
Market Dynamics
FAA airworthiness directives mandating traceable composite repair documentation are forcing MRO providers to upgrade thermal imaging and ultrasonic testing capabilities, creating a bifurcation between certified aerospace-grade operations and general industrial refurbishment.
Growth Catalysts
- EASA Part 145 mandates:European maintenance organization approvals require documented technician certification and vacuum integrity testing, elevating demand for qualified autoclave repair services across France, Germany, and the Netherlands.
- Wind energy blade manufacturing:Offshore turbine manufacturers in Denmark and Spain require pressure vessel restoration to maintain 400°C thermal uniformity for carbon-fiber spar cap production.
- Carbon-fiber primary structure aging:Commercial aviation fleets accumulate flight cycles that degrade autoclave-cured wing box and fuselage components, generating structural reinforcement repair volume.
Market Restraints
- Specialized alloy input volatility:Inconel and Haynes alloy prices for pressure vessel shell replacement fluctuate with nickel market conditions, compressing repair margin predictability.
- German MRO supply concentration:Lufthansa Technik AG and Air France KLM E&M anchor premium European capacity, limiting price competition and extending lead times for non-contracted operators.
- EPA emissions permitting:United States environmental standards constrain autoclave operating permits for open-loop thermal systems, requiring capital-intensive closed-loop retrofits.
Strategic Opportunities
- India defense aerospace:Hindustan Aeronautics Limited and private sector MRO entrants seek certified autoclave repair partners as indigenous fighter and transport programs expand composite airframe production.
- Digital radiography convergence:Integration of computed tomography with automated defect recognition compresses inspection cycles and enables predictive maintenance service models.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates traceable repair documentation, creating premium pricing for carbon-footprint-audited autoclave restoration services.
Industry Challenges
- ASNT Level III technician scarcity:Ultrasonic and radiographic testing certification programs produce insufficient qualified personnel to meet aerospace MRO demand expansion.
- OEM warranty compliance complexity:Prepreg-compatible repair systems must sustain Hexcel and Toray warranty terms, requiring proprietary material handling protocols that extend technician training duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Autoclave Repair Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Repair Type: Structural Reinforcement, Sealant Replacement, Electronic Calibration, Pressure Vessel Inspection, Leak Detection Technology: Thermal Imaging, Ultrasonic Testing, Eddy Current, Vibration Analysis, Digital Radiography End User: Aerospace Manufacturers, Marine Fabricators, Wind Turbine Operators, Defense Contractors, Space Exploration Agencies Service Model: On-site Maintenance, Remote Diagnostics, Scheduled Overhaul, Emergency Repair, Predictive Maintenance |
| Companies Covered | Lufthansa Technik AG, Air France KLM E&M, HAECO, Hong Kong Aircraft Engineering Company Limited, Heatcon Composite Systems, Hexcel, Gurit, 3M Company, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Autoclave Repair Market Trends and Innovations
Repair documentation digitization and automated defect detection are compressing inspection timelines while elevating certification barriers, reshaping competitive positioning toward technology-integrated service providers.
Phased array ultrasonic testing is consolidating as the dominant non-destructive evaluation method for vacuum integrity verification in pressure vessel restoration. Aerospace MRO providers in the United States and Germany are adopting this technology to satisfy FAA and EASA defect detection standards. The shift is consolidating market share toward repair shops with capitalized inspection equipment, marginalizing generalist industrial refurbishment operations.
EU F-Gas Regulation phase-down schedules are pressuring autoclave operators to retrofit thermal systems with lower-global-warming-potential heat transfer fluids. Industrial consequence includes accelerated capital replacement cycles for aging pressure vessels and requalification of repair procedures under revised safety protocols. Wind energy manufacturing clusters in Denmark and Spain are most affected, redirecting investment toward closed-loop thermal system designs.
Service contract unbundling is fragmenting traditional bundled maintenance agreements into discrete inspection, repair, and certification components. Tier-one aerospace suppliers in France and Germany now procure predictive maintenance subscriptions separately from emergency repair services, compressing margins on reactive work. The shift is most visible in wide-body MRO operations at Hamburg and Toulouse maintenance clusters.
Composite Autoclave Repair Market Segmentation
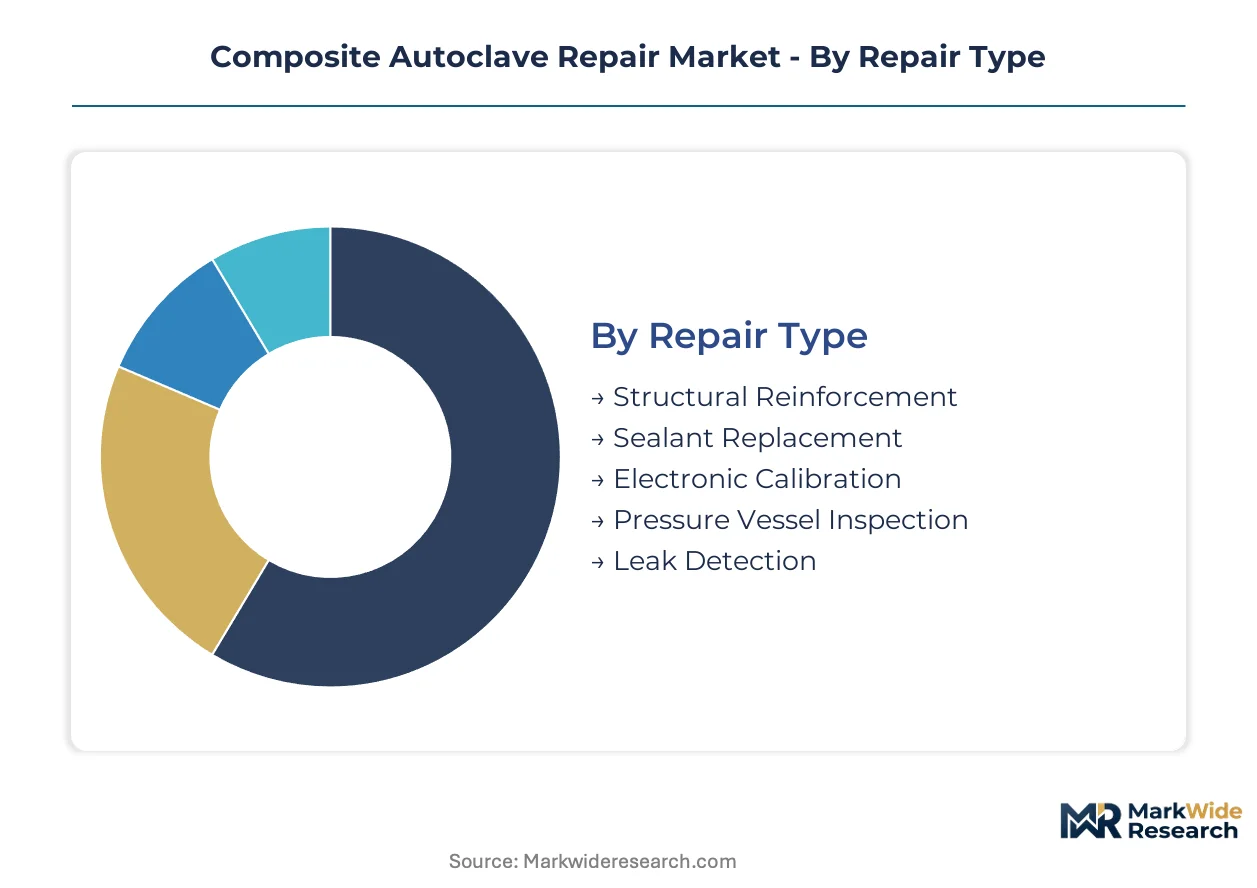
Autoclave repair demand fragments across distinct operational requirements, with certification standards and thermal system complexity determining which service providers capture premium contracts versus commodity work.
Repair Type:
Cost tiers separate warranty-compliant aerospace restoration from general industrial refurbishment.
- Structural Reinforcement:Carbon-fiber primary structure restoration demands vacuum integrity restoration and thermal uniformity verification to 400°C specifications. Aerospace manufacturers in the United States and Germany drive volume as aging commercial fleets accumulate flight cycle degradation on wing box and fuselage components.
- Sealant Replacement:Pressure boundary restoration replaces degraded elastomeric seals and gaskets to restore 6-bar operating pressure containment. Wind turbine operators in Denmark and Spain generate recurring demand as offshore blade manufacturing cycles accelerate vessel utilization rates.
- Electronic Calibration:PID controller and thermocouple array recalibration restores temperature uniformity within ±2°C tolerance bands.
- Pressure Vessel Inspection:Shell thickness measurement and weld integrity assessment per ASME Boiler and Pressure Vessel Code Section VIII requirements.
- Leak Detection:Vacuum decay testing and helium mass spectrometry identify micro-leakage paths in composite bonding surfaces.
Volume sits with Structural Reinforcement; growth tilts toward Sealant Replacement.
Technology:
Capital intensity and technician certification requirements stratify providers into aerospace-qualified specialists versus generalist operators.
- Digital Radiography:Computed tomography with automated defect recognition compresses inspection cycles from hours to minutes while generating traceable documentation for FAA and EASA compliance. MRO providers in Hamburg and Toulouse maintenance clusters adopt this technology fastest to satisfy tightening airworthiness directive standards.
- Ultrasonic Testing:Phased array systems map delamination and void distribution in composite pressure vessel walls without surface preparation. Aerospace manufacturers across France, Germany, and the United States mandate this method for warranty-sustaining repair documentation.
- Thermal Imaging:Infrared thermography identifies insulation degradation and hot spots in heating element arrays.
- Eddy Current:Surface and near-surface crack detection in metallic pressure vessel components and heating coil assemblies.
- Vibration Analysis:Fan, blower, and circulation motor condition monitoring through spectral frequency signature analysis.
Ultrasonic Testing commands the largest installed base; Digital Radiography is climbing the fastest.
End User:
Regulatory exposure and composite fabrication sophistication determine service pricing and contract duration.
- Aerospace Manufacturers:OEM and Tier-1 suppliers require EASA Part 145 and FAA-certified repair documentation with full material traceability. Boeing and Airbus supply chains in the United States, France, and Germany sustain premium pricing for qualified autoclave restoration services.
- Wind Turbine Operators:Offshore blade manufacturers demand 400°C thermal uniformity restoration for carbon-fiber spar cap production. Vestas and Siemens Gamesa facilities in Denmark and Spain redirect investment toward closed-loop thermal system retrofits under EU F-Gas Regulation pressure.
- Marine Fabricators:Yacht and naval vessel composite hull manufacturers require pressure vessel restoration for prepreg curing operations.
- Defense Contractors:Military airframe and missile casing production mandates ITAR-compliant repair documentation and technician security clearance.
- Space Exploration Agencies:Satellite and launch vehicle composite structure fabrication requires ultra-high-vacuum autoclave restoration for outgassing-sensitive applications.
Aerospace Manufacturers dominate current spend; Wind Turbine Operators show the steepest expansion trajectory.
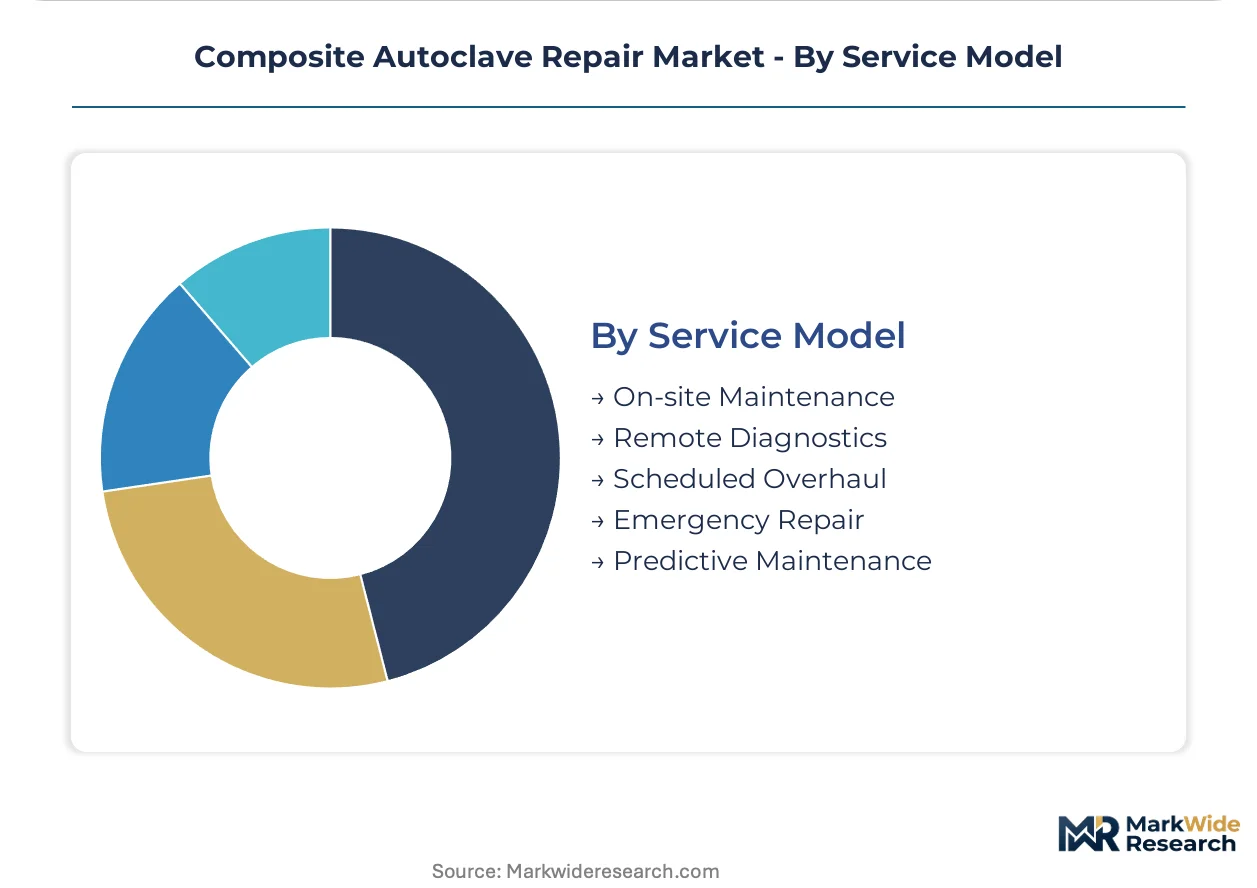
Service Model:
Contract structure preference shifts from bundled agreements toward discrete, unbundled procurement components.
- Predictive Maintenance:IoT sensor integration and machine learning algorithms convert emergency repair contracts into recurring revenue subscriptions. Lufthansa Technik AG and Air France KLM E&M in Germany and France now procure these services separately from reactive repair work.
- Emergency Repair:Unscheduled pressure vessel restoration demands 24-hour response commitments and expedited technician dispatch. Aerospace MRO clusters in Hamburg and Toulouse sustain premium pricing for guaranteed availability contracts.
- On-site Maintenance:Technician deployment to customer facilities for repair execution without equipment transport.
- Remote Diagnostics:Telemetry-enabled troubleshooting and repair guidance through secure data connection to autoclave control systems.
- Scheduled Overhaul:Planned pressure vessel refurbishment during production line maintenance windows.
Emergency Repair generates the highest per-incident revenue; Predictive Maintenance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European composite autoclave repair demand through Lufthansa Technik AG's wide-body MRO dominance, while Toulouse and Toulouse-Blagnac aerospace clusters sustain parallel capacity for Airbus supply chain compliance.
United States
Boeing's Everett and Charleston manufacturing footprints drive structural reinforcement repair volume for aging carbon-fiber wing boxes. FAA airworthiness directives mandate traceable thermal imaging documentation, elevating certification barriers for MRO providers. Seattle-Tacoma and Wichita aerospace corridors concentrate qualified repair capacity serving Tier-1 prepreg suppliers.
Germany
Lufthansa Technik AG's Hamburg base dominates European wide-body composite MRO, generating premium pricing for EASA Part 145-certified autoclave restoration. EU F-Gas Regulation phase-down schedules pressure thermal system retrofits. Munich and Augsburg manufacturing clusters sustain parallel demand from automotive carbon-fiber component producers.
China
COMAC's Shanghai and Xi'an assembly lines expand indigenous composite airframe production, redirecting MEE environmental compliance investment toward closed-loop thermal systems. MEE emissions standards constrain operating permits for legacy open-loop autoclaves. Tianjin and Chengdu aerospace zones anchor emerging repair capacity for defense and commercial programs.
France
Air France KLM E&M's Paris-CDG and Toulouse maintenance bases sustain premium MRO capacity for Airbus A350 and A320neo composite structures. EASA Part 145 approvals require documented vacuum integrity testing. Saint-Nazaire wind energy manufacturing clusters generate secondary demand for 400°C thermal uniformity restoration.
India
Hindustan Aeronautics Limited's Bengaluru and Nashik facilities expand indigenous fighter and transport composite programs, seeking certified autoclave repair partnerships. CDSCO and DGFT regulations shape import substitution for aerospace materials. Hyderabad defense aerospace corridor emerges as a secondary demand node for ITAR-compliant restoration services.
Composite Autoclave Repair Market Competitive Landscape
Capital-heavy MRO operators compete with asset-light inspection technology providers across diverging certification tiers. The market structures around three strategic archetypes: integrated aerospace MRO conglomerates with captive autoclave fleets; specialized composite repair shops with EASA Part 145 and FAA dual certification; and industrial equipment service providers serving wind energy and marine fabricators without aerospace-grade documentation. Dominant competitive moves include predictive maintenance subscription unbundling and phased array ultrasonic testing equipment capitalization to marginalize generalist competitors.
Among European-integrated MRO conglomerates, Lufthansa Technik AG and Air France KLM E&M exemplify the premium-tier archetype through Hamburg and Paris-CDG base dominance. HAECO occupies a position within Asia-Pacific capacity anchoring through Hong Kong Aircraft Engineering Company Limited facilities. Hexcel represents the materials-integrated specialist tier, with prepreg-compatible repair system positioning sustaining OEM warranty compliance relationships. These three company structures illustrate the geographic and certification-based stratification shaping contract access.
| Leading Market Players |
|---|
| Lufthansa Technik AG |
| Air France KLM E&M |
| HAECO |
| Hong Kong Aircraft Engineering Company Limited |
| Heatcon Composite Systems |
| Hexcel |
| Gurit |
| 3M Company |
| Henkel AG & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
Phased array ultrasonic testing adoption is simultaneously elevating capital requirements for repair providers and concentrating supply among EASA Part 145-certified operators in Germany and France. This technology shift compresses margins for uncertified generalists while embedding cost premiums into aerospace-grade service contracts.
Pricing Analysis
Outcome-based pricing tied to autoclave uptime guarantees anchors premium contracts for aerospace manufacturers, separating EASA Part 145-certified providers from commodity refurbishment shops. Price differentiation hinges on technician certification tier and digital radiography documentation capabilities. Cost compression in standard industrial repair is intensifying because wind energy operators in Denmark and Spain are consolidating procurement volumes. Tier-1 aerospace MROs in Hamburg and Toulouse exhibit the lowest price sensitivity; independent marine fabricators face the highest.
Supply Chain Analysis
India's PLI scheme for aerospace components is reshaping sourcing patterns for pressure vessel alloys and specialized gasket materials. Inconel and Haynes alloy supply concentrates in the United States, Germany, and Japan. Repair operations draw from nickel market futures and elastomer compound distributors. Single-source vulnerability sits with ASNT Level III-certified technician pools. Distribution runs through OEM-authorized service networks and independent MRO channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASNT Level III technician scarcity props pricing power for certified repair providers across the projection horizon. Capacity bottlenecks in Hamburg and Toulouse maintenance clusters sustain premium contract terms.
For Market Incumbents: Acquire phased array ultrasonic testing equipment fleets to marginalize generalist competitors lacking capital for defect detection automation. Expand technician certification pipelines in partnership with FAA-approved training centers to preempt emerging MRO entrants from India and China. EASA Part 145 approval maintenance represents the critical defensive moat. For New Entrants and Emerging Players: Wind turbine operators in Spain and Denmark present the most penetrable buyer archetype for unbundled predictive maintenance subscriptions. Defense aerospace corridors in India offer secondary white-space for ITAR-compliant repair partnerships. Lead with remote diagnostics capability to bypass capital-intensive equipment ownership requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated aerospace MRO conglomerates seeking EASA Part 145 capacity expansion. Long-term viability favors dual-certified providers with proprietary digital radiography documentation systems. Watch for F-Gas Regulation enforcement acceleration in EU member states as inflection signal for thermal system retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Converts emergency repair revenue into recurring streams for Lufthansa Technik AG and Air France KLM E&M contract portfolios. |
| Phased Array Ultrasonic Testing Capitalization | Creates inspection capability barriers that marginalize uncertified competitors in Hamburg and Toulouse aerospace clusters. |
| India Defense Aerospace Partnership | Positions repair providers for Hindustan Aeronautics Limited indigenous fighter program composite airframe demand. |
| Closed-Loop Thermal System Retrofit | Satisfies EU F-Gas Regulation phase-down schedules for Vestas and Siemens Gamesa wind turbine manufacturing facilities. |
| ASNT Level III Technician Pipeline Investment | Addresses certification scarcity constraining expansion of FAA and EASA-compliant repair capacity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with MRO operations directors, autoclave maintenance engineers, aerospace procurement managers, and EASA Part 145 compliance officers validated segment assumptions. FAA airworthiness directive databases, EASA safety publication archives, and ASME Boiler and Pressure Vessel Code documentation provided regulatory trajectory inputs. Bottom-up repair volume estimates triangulated against top-down aerospace fleet projection models.
Segment-level granularity modeled repair type, technology adoption tier, end-user industry, and service model contract structure across the projection horizon. CAGRs derived from technician supply constraints, fleet aging curves, and regulatory compliance cost trajectories. Forecast inputs incorporated carbon-fiber primary structure flight cycle accumulation rates and EU F-Gas Regulation enforcement timelines.
Revisions become necessary when FAA or EASA mandates accelerate inspection protocol changes, or when nickel alloy price volatility disrupts pressure vessel shell replacement economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Hardbanding Services Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Dust Suppression Control Market
Construction Services
Train Contractor Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
Construction Project Management Services Market
Construction Services
Gutter Cleaning Services Market
Construction Services
3D Concrete Printing Services Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Construction TIC Market
Construction Services
MENA Architectural Services Market
Construction Services
NDT and Inspection Market
Construction Services
Condenser Cleaners Market