
 Grease Trap Service Market | 2026-2036
Grease Trap Service Market Size, Share, and Industry Trends Forecast 2026-2036
Grease Trap Service Market Insights
Aftermarket service revenue is rewriting profit distribution across the grease management value chain. Liquid Environmental Solutions leverages integrated collection and processing infrastructure to sustain margin density in high-frequency cleaning routes. DAR PRO anchors national coverage through backward integration into rendering operations, while Mahoney Environmental competes via specialized hospitality-sector contracts.
Grease trap service encompasses the scheduled removal, transport, and compliant disposal of fats, oils, and greases from underground or above-ground interceptors, typically requiring vacuum truck extraction and documented chain-of-custody tracking to wastewater treatment facilities or rendering plants. The primary purpose is preventing sewer line blockages and protecting municipal collection systems from corrosive buildup and overflows. Maintenance contracts among restaurants dominate revenue stability due to recurring jurisdictional inspection mandates, while automatic grease removal units command premium service rates because of their mechanical complexity and sensor-based monitoring requirements. Direct sales channels capture institutional facility relationships through multi-year bundled agreements.
EPA pretreatment standards and state-level plumbing codes shape interceptor sizing and cleaning frequency mandates across the United States. Local sewer authorities enforce compliance through penalty structures that convert non-adherent foodservice operators into contracted service customers. Stakeholders must monitor municipal infrastructure privatization trends and evolving biofuel feedstock specifications that redirect recovered grease value streams.
Market Dynamics
Municipal pretreatment ordinances are tightening inspection frequencies and penalty structures, converting non-compliant foodservice operators into contracted maintenance customers and consolidating route density for service providers with established compliance documentation capabilities.
Growth Catalysts
- EPA Pretreatment Standards:Federal discharge limits are mandating documented chain-of-custody tracking for fats, oils, and greases, forcing independent restaurants into scheduled service agreements with certified haulers.
- Quick-Service Restaurant Expansion:National chains are standardizing multi-unit maintenance programs that prioritize vendors with integrated collection and processing infrastructure over fragmented local operators.
- Coastal Discharge Regulations:Southeastern US municipalities are imposing stricter interceptor sizing requirements on aging commercial kitchen infrastructure, accelerating replacement cycles for undersized underground units.
Market Restraints
- Vacuum Truck Fleet Concentration:Specialized extraction equipment manufacturing concentrates among a limited supplier base, creating procurement bottlenecks for regional service expansion.
- Rendering Plant Capacity:Backward integration into grease processing requires proximity to rendering facilities, restricting viable service territories to corridors with established feedstock demand from biofuel producers.
- Interceptor Sizing Variability:Inconsistent state-level plumbing codes create compliance complexity for multi-jurisdictional operators, increasing training and certification overhead.
Strategic Opportunities
- Automatic Grease Removal Units:Mechanical interceptors with sensor-based monitoring command premium service rates and create recurring revenue streams through proprietary maintenance protocols.
- Institutional Facility Bundling:Universities, hospitals, and correctional facilities are consolidating grease management into multi-year facility services contracts, favoring vendors with national coverage.
- Biofuel Feedstock Specifications:Evolving renewable diesel standards are redirecting recovered grease value streams toward higher-margin rendering contracts with integrated energy producers.
Industry Challenges
- Hazmat Certification Pipeline:Vacuum truck operators require commercial driver's licenses plus hazardous materials endorsements, constraining workforce scalability in high-growth metropolitan corridors.
- Legacy Interceptor Integration:Retrofitting sensor monitoring onto decades-old concrete interceptors demands customized installation protocols that complicate standardization efforts.
- Documentation System Fragmentation:Municipal sewer authorities operate incompatible digital compliance platforms, forcing service providers to maintain multiple reporting interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grease Trap Service Market |
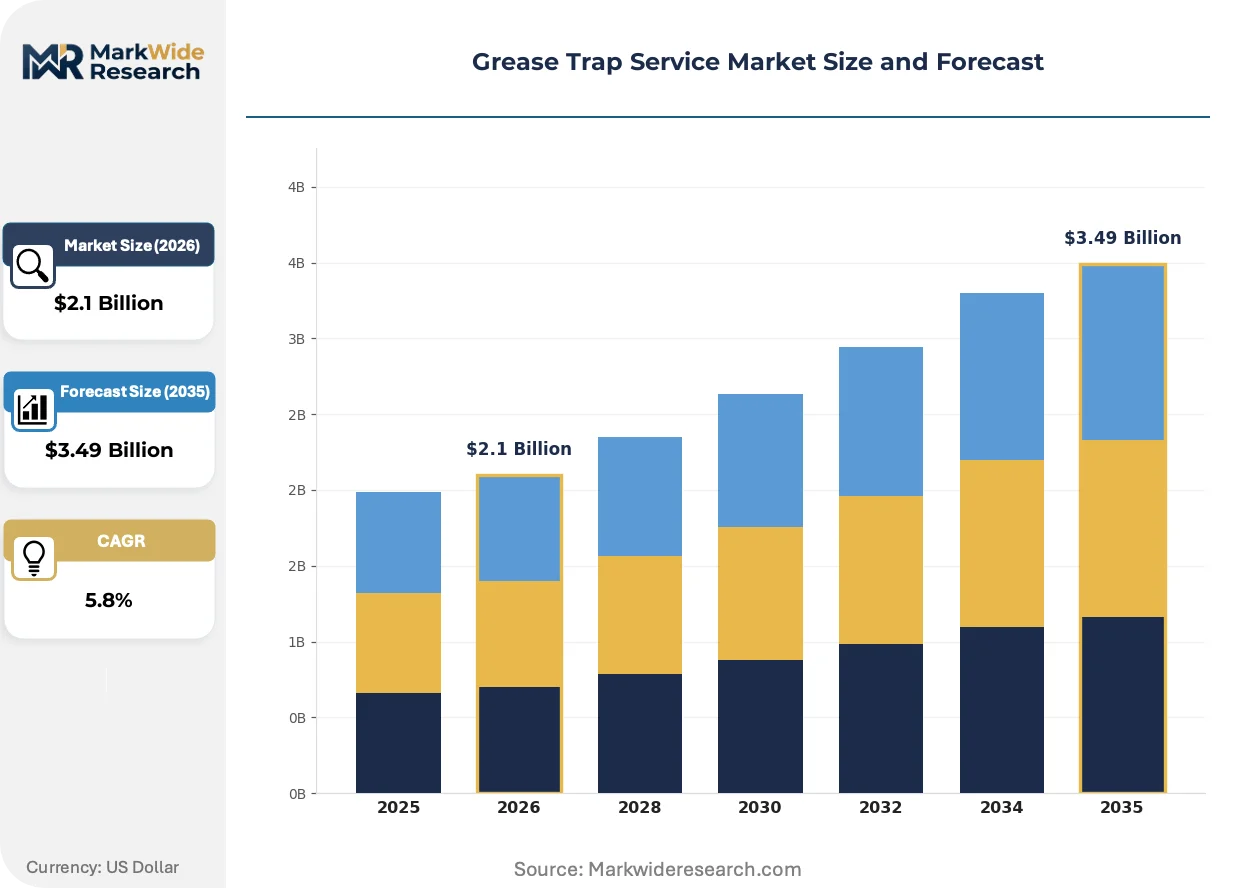
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Maintenance, Cleaning, Inspection, Repair Customer Type: Restaurants, Hotels, Food Processing Units, Commercial Kitchens, Institutional Facilities Trap Type: Passive Grease Traps, Automatic Grease Removal Units, Interceptor Tanks, Passive Hydromechanical Units Distribution Channel: Direct Sales, Dealer Network, Online Platforms, Facility Management Companies |
| Companies Covered | Liquid Environmental Solutions, DAR PRO, Mahoney Environmental, Ace Grease, Valley Proteins, Sanimax, Roto-Rooter, JJ Richards, Grease Guardian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grease Trap Service Market Trends and Innovations
Digital monitoring systems and automated extraction technologies are compressing service intervals while elevating compliance documentation standards. These shifts favor capital-intensive operators capable of integrating hardware deployment with recurring maintenance revenue.
Sensor-equipped grease interceptors are migrating from passive storage vessels to active monitoring platforms. Quick-service restaurant chains with drive-thru saturation are deploying these units at accelerated pace to preempt municipal inspection failures. The technology is migrating from high-volume coastal markets toward inland metropolitan corridors where enforcement staffing has expanded.
The EPA's renewed emphasis on documented chain-of-custody tracking is extending liability downstream to service providers. Haulers must now maintain GPS-tagged extraction records and treatment facility receipts to defend against discharge violation attribution. Full-service operators with captive rendering relationships are capturing institutional contracts that independent haulers cannot underwrite.
Multi-unit restaurant operators are consolidating vendor relationships through centralized procurement functions that prioritize compliance guarantees over unit pricing. Regional service providers are responding by acquiring smaller haulers to satisfy geographic coverage requirements in RFP processes. This concentration is most visible in Sun Belt metropolitan areas where development codes mandate grease interceptors for all new commercial kitchen construction.
Grease Trap Service Market Segmentation
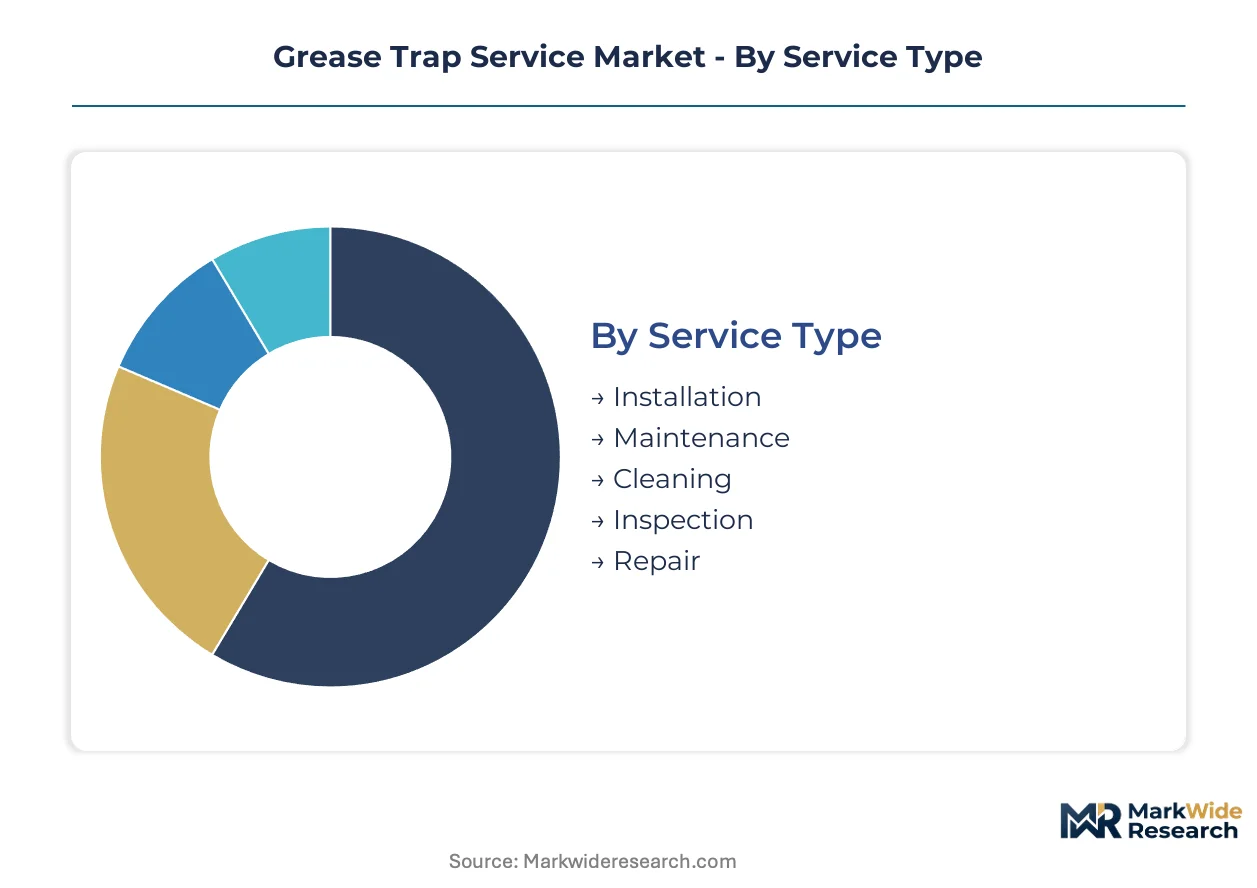
Grease trap service segmentation reveals divergent margin profiles across operational modes. After-sales service intensity varies dramatically between reactive repair calls and predictive maintenance contracts, reshaping how providers allocate fleet and technician resources across customer portfolios.
Service Type:
Scheduled maintenance programs generate recurring revenue streams that stabilize cash flow against volatile emergency dispatch cycles.
- Installation:New interceptor deployment requires coordination with municipal permitting offices and plumbing contractors. Demand clusters in Sun Belt metropolitan corridors where commercial kitchen construction codes mandate underground grease separation infrastructure.
- Maintenance:Recurring service agreements dominate revenue stability through jurisdictional inspection mandates that convert non-compliant operators into contracted customers. Quick-service restaurant chains are consolidating these programs under centralized procurement functions.
- Cleaning:Vacuum truck extraction of accumulated fats, oils, and greases demands documented chain-of-custody tracking to treatment facilities.
- Inspection:Compliance verification services are tightening frequency requirements under EPA pretreatment standards.
- Repair:Emergency interceptor rehabilitation addresses concrete degradation and mechanical failure in aging infrastructure.
By volume, Cleaning leads. By growth pace, Maintenance is ahead.
Customer Type:
Contract value scales with facility complexity and regulatory exposure rather than simple kitchen size.
- Restaurants:Quick-service chains standardize multi-unit maintenance programs prioritizing vendors with integrated collection infrastructure. Independent operators enter scheduled service agreements following municipal penalty enforcement.
- Hotels:Full-service hospitality properties bundle grease management into broader facility services contracts requiring national coverage capabilities.
- Food Processing Units:Industrial-scale fat and oil discharge volumes necessitate specialized extraction equipment and rendering plant relationships.
- Commercial Kitchens:Shared-use food preparation facilities face compounded compliance obligations from multiple tenant operations.
- Institutional Facilities:Universities, hospitals, and correctional institutions consolidate grease management into multi-year agreements favoring compliance guarantees over unit pricing.
By contract count, Restaurants dominate. By contract value, Institutional Facilities command premium positioning.
Trap Type:
Mechanical complexity determines service rate premiums and technician certification requirements.
- Passive Grease Traps:Concrete or fiberglass gravity separators represent the installed base majority in aging commercial infrastructure. Southeastern US municipalities are accelerating replacement cycles for undersized units under stricter interceptor sizing requirements.
- Automatic Grease Removal Units:Sensor-equipped mechanical interceptors command premium service rates through proprietary maintenance protocols and remote monitoring capabilities. Drive-thru saturated quick-service chains deploy these at accelerated pace to preempt inspection failures.
- Interceptor Tanks:Large-volume underground storage vessels serve high-throughput food processing and institutional applications.
- Passive Hydromechanical Units:Compact above-ground separators address space-constrained urban kitchen retrofits.
By installed base, Passive Grease Traps prevail. By expansion trajectory, Automatic Grease Removal Units are climbing fastest.
Distribution Channel:
Channel selection reflects customer scale and compliance documentation sophistication.
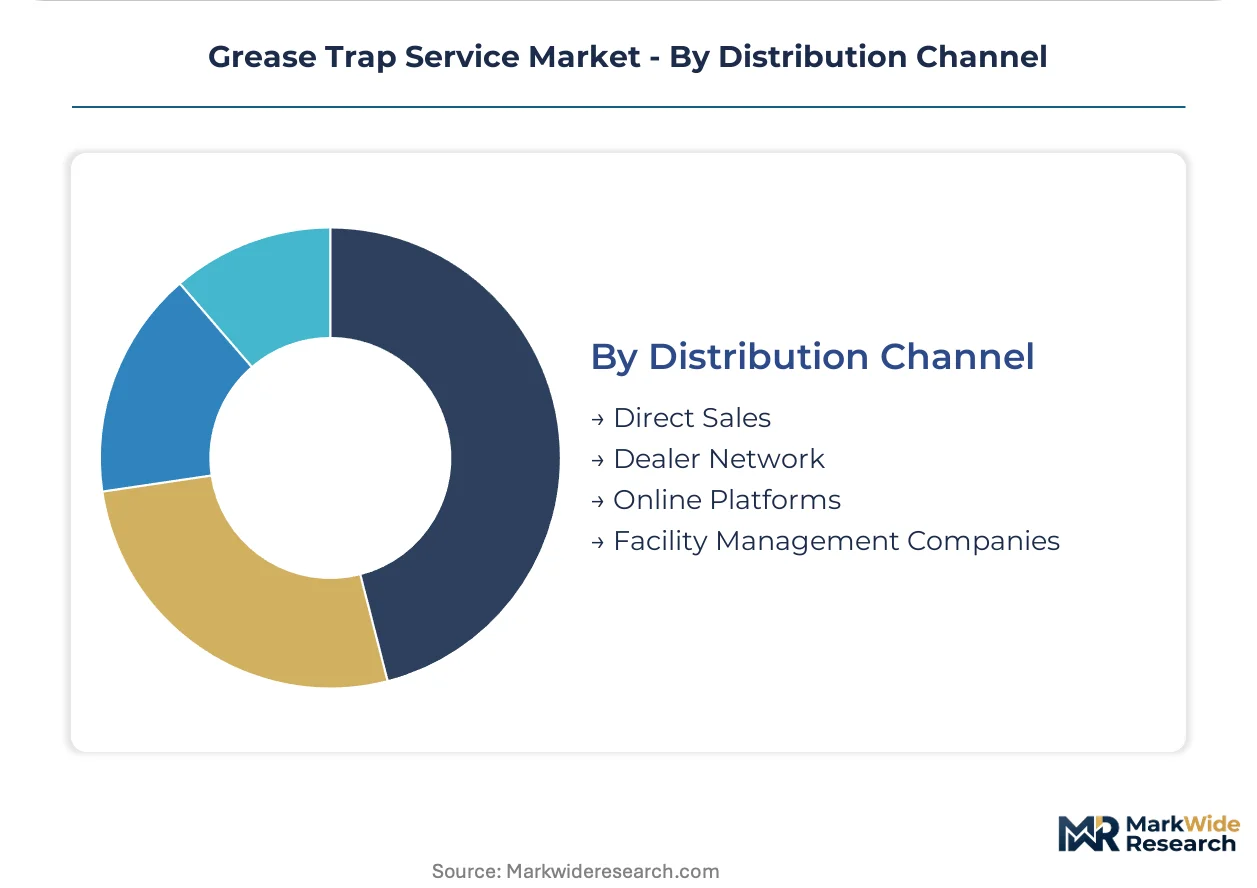
- Direct Sales:National account teams capture multi-year bundled agreements with institutional and chain restaurant relationships. These contracts prioritize vendors with captive rendering capabilities and GPS-tagged extraction documentation systems.
- Dealer Network:Regional haulers serve independent restaurants through localized route density and municipal inspection relationships.
- Online Platforms:Digital scheduling interfaces are emerging for standardized maintenance bookings among smaller operators.
- Facility Management Companies:Integrated building services providers subcontract grease management as a component of comprehensive maintenance contracts.
By revenue concentration, Direct Sales captures the largest share. By accessibility expansion, Online Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between coastal municipalities with stringent discharge enforcement and inland markets where reactive maintenance still prevails. The southeastern United States concentrates scheduled service adoption due to aging interceptor infrastructure and coastal proximity, while southwestern states emphasize new construction compliance.
United States
Quick-service restaurant chains and institutional facilities drive contracted maintenance volume across metropolitan corridors. EPA pretreatment standards mandate documented chain-of-custody tracking, converting independent operators into scheduled service agreements. Sun Belt cities including Atlanta, Houston, and Phoenix exhibit accelerated interceptor replacement cycles under tightened sizing requirements.
Canada
Municipal sewer authorities in Ontario and British Columbia enforce inspection frequencies that mirror US coastal standards. Environment and Climate Change Canada guidelines shape provincial discharge limits, while Toronto and Vancouver concentrate service provider route density through multi-unit restaurant procurement consolidation.
Germany
Industrial food processing facilities and commercial kitchen clusters generate specialized extraction demand. REACH regulations and federal water management standards impose documentation requirements on fats, oils, and grease disposal. The Rhine-Ruhr and Bavarian manufacturing corridors anchor service provider infrastructure for high-volume institutional contracts.
United Kingdom
Water company enforcement of private sewer regulations drives reactive-to-scheduled service conversion among independent restaurants. Environment Agency discharge permits mandate interceptor maintenance records. Greater London and Manchester concentrate automatic grease removal unit deployment due to space-constrained urban kitchen retrofits.
Australia
Coastal municipalities in New South Wales and Queensland impose interceptor sizing requirements on commercial kitchen construction. State environmental protection authorities enforce penalty structures that convert non-compliant operators. Sydney and Melbourne metropolitan areas exhibit bundled facility services procurement among hospitality and healthcare sectors.
Grease Trap Service Market Competitive Landscape
Capability concentration sits with integrated collection-and-processing operators; scale advantage sits with national route-density networks. The market structure tiers between full-service providers with captive rendering relationships and regional haulers dependent on third-party disposal. Two strategic archetypes dominate: vertically integrated infrastructure operators and specialized hospitality-sector contractors. Competitive moves concentrate on geographic coverage expansion through hauler acquisitions and multi-year institutional contract bundling.
Within the integrated infrastructure tier, Liquid Environmental Solutions and DAR PRO exemplify operators combining collection route density with backward integration into rendering operations. Mahoney Environmental occupies a position among specialized contractors targeting hospitality-sector relationships through proprietary service protocols. These three anchors illustrate the capability-scale tradeoff shaping vendor selection in centralized procurement processes.
| Leading Market Players |
|---|
| Liquid Environmental Solutions |
| DAR PRO |
| Mahoney Environmental |
| Ace Grease |
| Valley Proteins |
| Sanimax |
| Roto-Rooter |
| JJ Richards |
| Grease Guardian |
| Others |
Pricing and Supply Chain Analysis
Vacuum truck manufacturing concentrates among a limited supplier base in the United States and Germany, anchoring margin capture downstream with fleet operators who lock in multi-year maintenance contracts. This upstream equipment scarcity translates directly into pricing power for incumbent service providers with established route density, while regional haulers face procurement bottlenecks that compress their ability to compete on unit rates.
Pricing Analysis
Long-term offtake agreements dominate the contract structure, with quick-service restaurant chains standardizing multi-unit maintenance programs that prioritize compliance guarantees over spot pricing. Price differentiation rests on certification tier and after-sales service bundling, as EPA-mandated chain-of-custody documentation commands premium rates. Cost compression in the independent restaurant tier is intensifying because municipal penalty enforcement converts non-compliant operators into price-sensitive contracted customers. Institutional facilities exhibit least price sensitivity due to bundled facility services procurement, while independent operators represent the most price-sensitive segment.
Supply Chain Analysis
Upstream feedstock flows from commercial kitchen interceptors across the United States, Canada, and Germany concentrate recoverable grease volumes near metropolitan corridors with rendering infrastructure. The supply chain draws from vacuum truck fleets, specialized extraction equipment, and hazardous materials certification pipelines as critical inputs. Single-source vulnerability sits with rendering plant capacity, restricting viable service territories to corridors with established biofuel feedstock demand. Distribution runs through direct sales channels for institutional accounts and dealer networks for independent restaurant coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-based automatic grease removal units are disrupting traditional passive interceptor maintenance, with EPA pretreatment standards accelerating this technological inflection across municipal enforcement jurisdictions.
For Market Incumbents: Harden compliance documentation capabilities to defend against liability extension under chain-of-custody mandates. Deepen backward integration into rendering operations to capture biofuel feedstock premiums, while consolidating regional hauler acquisitions to satisfy national coverage requirements in quick-service restaurant RFP processes.
For New Entrants and Emerging Players: Pursue automatic grease removal unit deployment as the most penetrable white-space target, particularly in Sun Belt metropolitan areas where drive-thru saturation accelerates sensor-equipped interceptor adoption. Target inland metropolitan corridors where enforcement staffing expansion creates first-mover advantages in scheduled maintenance conversion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional haulers lacking captive rendering relationships, presenting rollup opportunities for integration into full-service platforms. Long-term viability favors operators with combined route density and upstream processing control. Monitor municipal infrastructure privatization trends as the critical inflection signal for contract consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Rendering Capacity Expansion | Captures biofuel feedstock premiums from renewable diesel producers in established corridors. |
| Sensor Platform Integration | Compresses service intervals while elevating EPA-compliant documentation standards for chains. |
| Regional Hauler Acquisition | Satisfies geographic coverage mandates in quick-service restaurant centralized procurement. |
| Hazmat Certification Pipeline Investment | Alleviates workforce constraints constraining fleet scalability in high-growth metropolitan areas. |
| Institutional Facility Bundling | Secures multi-year agreements with universities and hospitals prioritizing compliance guarantees. |
Research Methodology
Cross-validation between primary fieldwork and secondary regulatory filings anchors the qualitative findings in documented enforcement patterns. Interviews with vacuum truck fleet operators, municipal sewer authority inspectors, rendering plant procurement managers, and quick-service restaurant facility directors combined with EPA pretreatment standard records, state plumbing code databases, and municipal ordinance filings. Bottom-up route density analysis and top-down market sizing triangulate volume estimates across the projection horizon.
Calibration against historical interceptor replacement cycles and enforcement staffing expansion patterns shapes the analytical framework. Segmentation dimensions span service type, customer archetype, interceptor technology tier, and distribution channel complexity. CAGRs derive from modeled adoption curves for automatic grease removal units and scheduled maintenance penetration rates among independent operators. Biofuel feedstock specification evolution and municipal privatization timelines serve as industry-specific forecast inputs.
Sensitivities concentrate around rendering plant capacity expansion delays and municipal enforcement budget fluctuations. Forecasts reflect assumptions on technology substitution velocity and regulatory harmonization across state plumbing codes. Cross-checking against wastewater authority inspection volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Remote Construction Market
Construction Services
Excavating Contractor Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Construction TIC Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Industrial Maintenance Products Market