
 Europe Telecom Transformers Market | 2026-2036
Europe Telecom Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Telecom Transformers Market Analytics
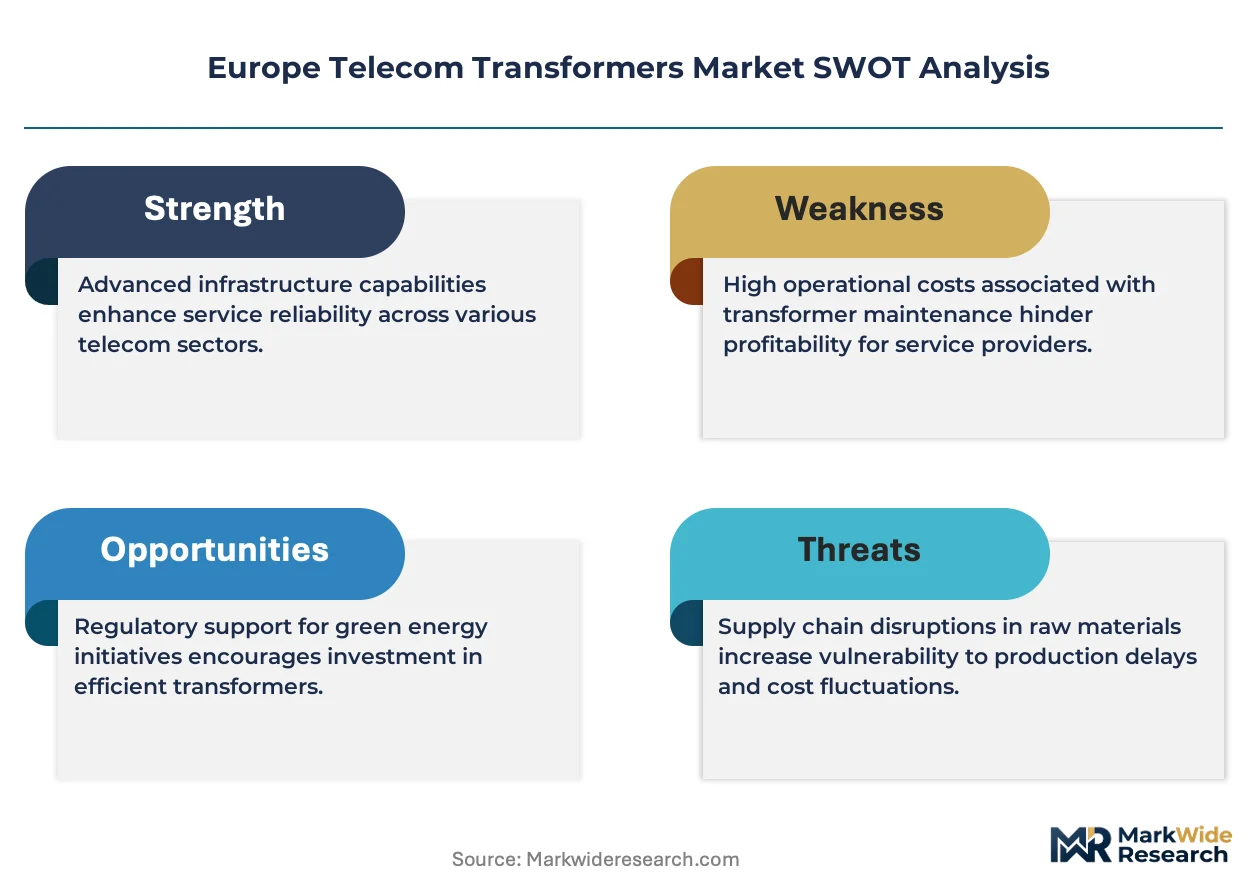
Network virtualization and open RAN architectures is reconfiguring power requirements at cell sites and central offices across Europe. Siemens Energy leverages its manufacturing footprint in Germany to anchor supply for high-efficiency step-down units. Hitachi Energy sustains competitive pressure through specialized isolation transformer designs for data center interconnection. Schneider Electric dominates distribution channels for compact outdoor installations in France and Spain.
Europe telecom transformers are electromagnetic devices engineered to transfer electrical energy between circuits at specific voltage ratios, typically operating at frequencies from 50 to 60 Hz with insulation classes rated for 1 kV to 36 kV distribution environments. These units condition power for base stations, switching centers, and fiber-optic repeaters where voltage stability directly determines network uptime. Step-down transformers lead product type demand as operators retrofit legacy sites for lower-voltage digital equipment. Smart technology installations represent the fastest-expanding segment as remote monitoring capabilities reduce field maintenance costs. Data centers as an end user category command premium pricing due to redundant power specifications and continuous uptime requirements.
The EU F-Gas Regulation and Ecodesign Directive shape transformer material selection and efficiency benchmarks across member states. CE marking requirements under the Low Voltage Directive govern market access for indoor and modular installations. Germany's KBA and France's national energy regulator enforce supplementary efficiency audits on utility-scale deployments. Stakeholders must monitor evolving EU taxonomy criteria for sustainable infrastructure investments.
Market Dynamics
5G network densification across Germany and France is forcing power infrastructure upgrades at cell sites, while the EU Green Deal's energy efficiency mandates accelerate transformer replacement cycles. This dual pressure from digitalization and decarbonization is restructuring procurement priorities for European telecom operators.
Growth Catalysts
- EU Green Deal mandates:Energy efficiency benchmarks under the Ecodesign Directive compel operators to retire legacy oil-filled units. Member states enforce accelerated depreciation schedules for inefficient assets.
- 5G small cell deployment:Germany's industrial zones and France's urban corridors require compact step-down transformers at 10x legacy density. Power conditioning needs multiply with radio unit virtualization.
- Data center interconnection:Hyperscale facilities in the Netherlands and Ireland demand redundant isolation transformers for fiber landing stations. Uptime specifications drive premium specification adoption.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Input material costs fluctuate with energy-intensive smelting operations. Transformer OEMs struggle to pass through price swings under long-term utility contracts.
- Specialized winding labor concentration:Skilled technician pools concentrate in Germany's industrial heartland. Eastern European markets face capacity constraints for precision coil manufacturing.
- F-Gas Regulation compliance costs:Natural ester and synthetic fluid alternatives require redesigned cooling systems. Material qualification timelines extend product development cycles.
Strategic Opportunities
- Poland and Romania grid modernization:EU cohesion funds finance rural broadband expansion. These markets lack incumbent transformer suppliers, creating first-mover positioning for efficient unit providers.
- Smart transformer retrofit kits:Remote monitoring modules attach to installed base assets. Operators in Spain and Italy reduce truck rolls through predictive thermal analytics.
- Open RAN power architecture standardization:Disaggregated radio units create standardized voltage requirements. Modular transformer platforms serve multiple vendor ecosystems.
Industry Challenges
- CE marking timeline compression:The Low Voltage Directive's conformity assessment procedures create bottlenecks. Notified body capacity constraints delay market entry for innovative designs.
- Legacy site integration complexity:Victorian-era exchange buildings in London and Paris impose physical envelope restrictions. Compact retrofit units sacrifice efficiency for dimensional compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Telecom Transformers Market |
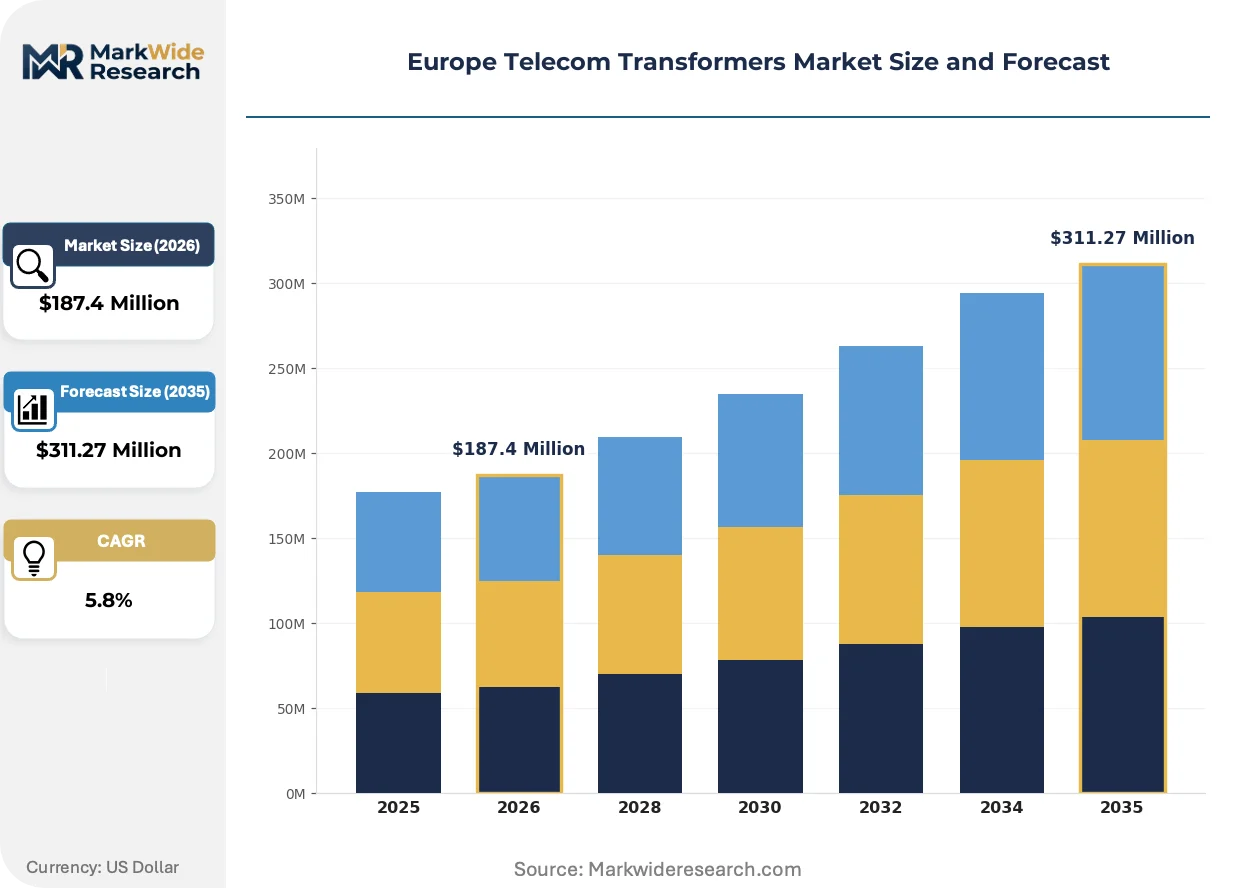
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-up Transformer, Step-down Transformer, Isolation Transformer, Auto Transformer End User: Telecom Operators, Data Centers, Utility Providers, Network Equipment Manufacturers Installation: Indoor, Outdoor, Modular, Compact Technology: Conventional, Digital, Smart, Hybrid |
| Companies Covered | Siemens Energy, Hitachi Energy, Schneider Electric, GE Vernova, SGB-SMIT Group, Eaton, Ormazabal, Kyte Powertech, Cahors, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Telecom Transformers Market Evolving Landscape
Digitalization of power infrastructure is collapsing traditional boundaries between electrical hardware and network management systems. Three distinct vectors are redefining product specifications and supplier relationships across European telecom networks.
Amorphous metal core technology is rendering obsolete conventional silicon steel laminations in distribution-class units. Operators in Scandinavia and the Netherlands now specify these cores for urban substations where no-load losses determine lifecycle economics. The technology is rendering obsolete decade-old efficiency benchmarks, compressing payback periods for premium transformer investments.
The EU F-Gas Regulation's phase-down schedules are accelerating bio-based dielectric fluid adoption. Natural ester formulations from rapeseed and soybean feedstocks now dominate outdoor installation specifications. French and German regulators enforce additional leakage monitoring requirements, pushing manufacturers toward sealed tank designs with extended maintenance intervals.
Telecom operators are consolidating vendor relationships around integrated power and cooling packages. Traditional electrical distributors lose relevance as direct procurement from OEMs with service capabilities expands. This pattern concentrates in markets with mature fiber infrastructure like Denmark and Switzerland, where total cost of ownership frameworks override upfront capital comparisons.
Europe Telecom Transformers Market Segmentation
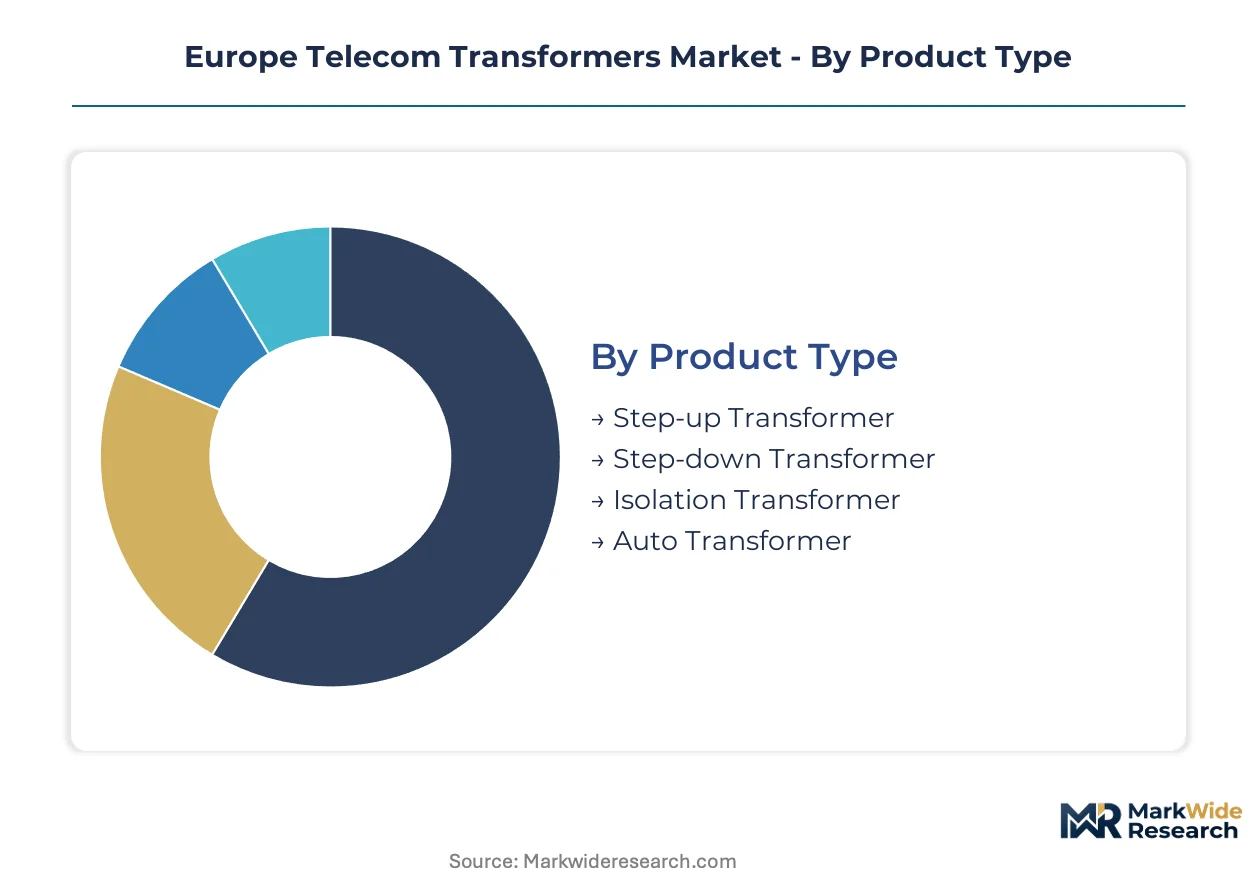
Segmentation of the Europe Telecom Transformers Market reveals distinct procurement patterns across voltage classes and deployment environments. Service intensity varies sharply by installation type and end-user criticality, shaping supplier contract structures and maintenance revenue pools.
Product Type:
After-sales service intensity escalates with unit complexity and deployment criticality, creating divergent margin profiles across transformer architectures.
- Step-down Transformer:These units reduce medium-voltage distribution feeds to equipment-grade levels for base stations and central offices. Germany's industrial zones and France's urban corridors drive concentration as 5G densification multiplies site counts. Operators prioritize compact designs that fit legacy enclosures.
- Isolation Transformer:Galvanic separation protects sensitive digital equipment from ground loops and harmonic distortion. Data centers in Ireland and the Netherlands specify redundant configurations for fiber landing stations. Uptime requirements justify premium pricing and dedicated service contracts.
- Step-up Transformer:Deployed where generation assets feed directly into telecom infrastructure. Rural broadband expansion in Poland and Romania creates scattered demand for grid-interconnection units.
- Auto Transformer:Single-winding designs offer weight and cost advantages for voltage ratios under 3:1. Limited adoption reflects EU efficiency mandates favoring dual-winding alternatives.
Step-down transformer configurations hold the largest share; momentum sits with isolation transformer specifications for hyperscale data center interconnection.
End User:
Cost tier stratification separates mission-critical deployments from price-sensitive volume procurement, with contract terms reflecting uptime liability exposure.
- Telecom Operators:Deutsche Telekom, Orange, and Vodafone anchor procurement volumes across Germany, France, and Spain. Network densification schedules drive recurring upgrade cycles with standardized specifications.
- Data Centers:Hyperscale facilities demand N+1 redundancy with thermal monitoring integration. Dublin and Amsterdam clusters concentrate specifications for 36 kV-class isolation units with extended warranties.
- Utility Providers:Grid-edge transformer sharing agreements reduce capital duplication. CE marking under the Low Voltage Directive governs co-location installations.
- Network Equipment Manufacturers:Ericsson and Nokia integrate power conditioning into turnkey radio unit packages. Procurement shifts toward modular transformer platforms compatible with open RAN architectures.
Telecom operators dominate volume; data center specifications are expanding most quickly on a value-per-unit basis.
Installation:
Physical envelope constraints in historic European infrastructure create premium niches for dimensionally optimized designs.
- Outdoor:Weatherproof enclosures with natural ester cooling dominate rural and suburban deployments. France's F-Gas Regulation enforcement accelerates bio-based fluid adoption.
- Indoor:Fire-resistant dry-type units serve Victorian-era exchange buildings in London and Paris. KBA efficiency audits in Germany add compliance layers to utility-scale indoor specifications.
- Modular:Pre-fabricated skid-mounted systems compress deployment timelines for rapid 5G rollout programs.
- Compact:Reduced footprint designs sacrifice some efficiency for dimensional compliance in constrained urban sites.
Outdoor installations retain the largest installed base; compact configurations gain share fastest in dense urban corridors.
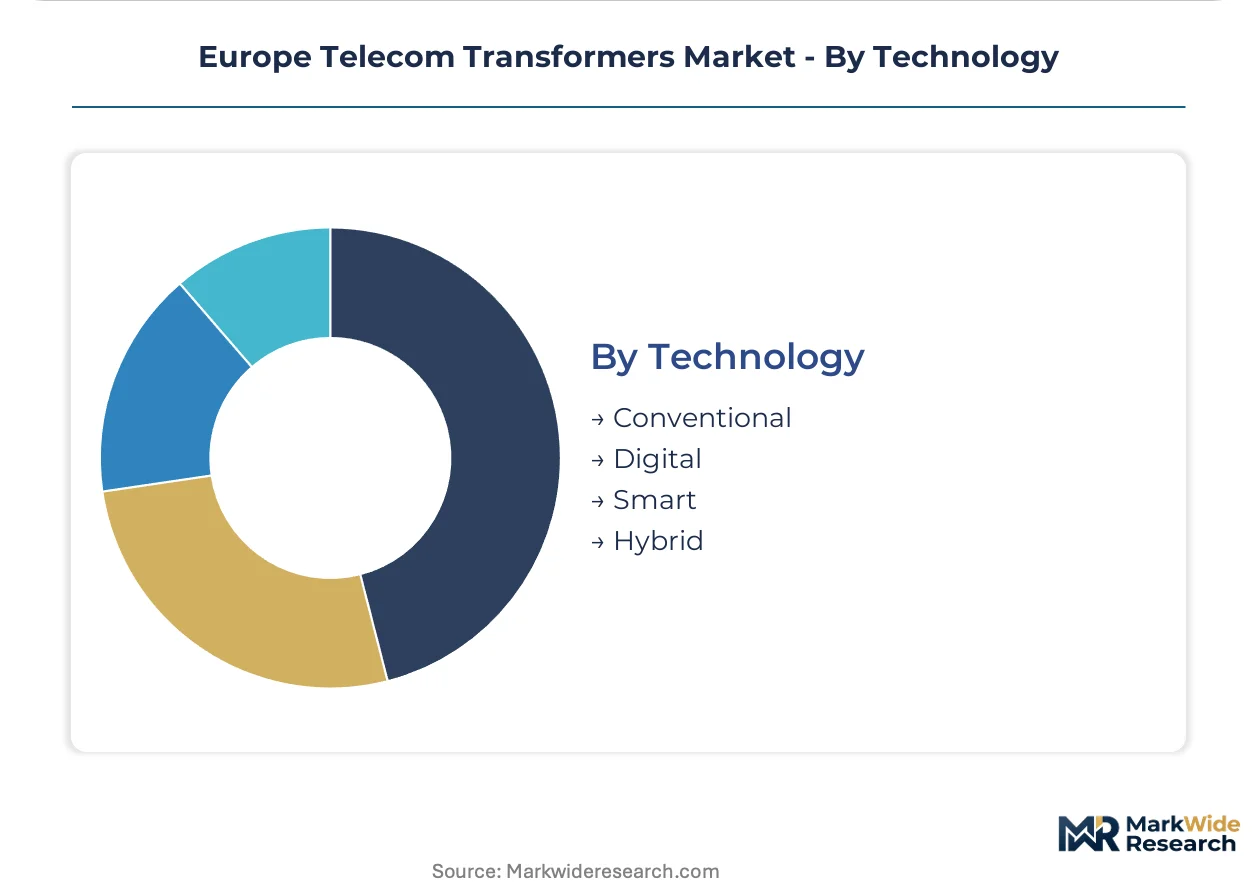
Technology:
Technology tiering separates legacy asset bases from digital transformation investments, with retrofit economics determining adoption velocity.
- Smart:Embedded sensors enable predictive thermal analytics and remote diagnostics. Operators in Spain and Italy reduce truck rolls through condition-based maintenance protocols.
- Digital:Solid-state power conversion challenges conventional magnetic designs in select low-power applications. Voltage regulation precision supports virtualized radio architectures.
- Conventional:Silicon steel laminations and mineral oil insulation retain cost advantages in price-sensitive Eastern European markets.
- Hybrid:Combinations of magnetic and electronic conditioning address specialized harmonic environments.
Conventional technology maintains the largest installed base; smart transformer platforms climb the fastest as retrofit modules attach to legacy assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators in Western Europe anchor procurement volumes, while Eastern European markets attract first-mover positioning for efficient unit providers. Data center clusters in Ireland and the Netherlands concentrate premium specifications for isolation transformers. EU cohesion funds now finance rural broadband expansion across Poland and Romania.
Germany
Deutsche Telekom and Vodafone drive 5G densification across industrial zones and urban corridors. The KBA enforces supplementary efficiency audits on utility-scale deployments, accelerating retirement of oil-filled legacy units. Bavaria's manufacturing heartland hosts precision coil production facilities serving domestic and export demand.
France
Orange anchors volume procurement for network densification schedules in Paris and regional urban centers. The national energy regulator enforces efficiency benchmarks beyond EU minimums, favoring sealed tank designs with natural ester cooling. Île-de-France concentrates demand for compact retrofit units in constrained Victorian-era exchange buildings.
Netherlands
Hyperscale data centers in Amsterdam and surrounding regions command premium pricing for redundant isolation transformers with thermal monitoring integration. CE marking under the Low Voltage Directive governs co-location installations with utility providers. The Randstad cluster leads adoption of amorphous metal core technology for urban substations.
Ireland
Dublin's fiber landing stations and hyperscale facilities specify 36 kV-class isolation units with extended warranties and N+1 redundancy. The EU Green Deal's energy efficiency mandates accelerate transformer replacement cycles alongside data center expansion. Rural broadband programs create scattered demand for grid-interconnection step-up units.
Poland
EU cohesion funds finance rural broadband expansion where incumbent transformer suppliers remain absent. The Ecodesign Directive compels operators to specify efficient units despite price-sensitive procurement traditions. Warsaw and Kraków industrial zones attract first-mover positioning for compact outdoor installations.
Europe Telecom Transformers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages separate volume leaders from niche positioning. Siemens Energy leverages its German manufacturing footprint to anchor supply for high-efficiency step-down units, while Hitachi Energy sustains pressure through specialized isolation designs. The market exhibits three strategic archetypes: integrated power-cooling package providers, precision coil manufacturing specialists, and distribution-channel dominators for compact outdoor installations. Competitive moves concentrate on portfolio diversification into smart monitoring modules and geographic expansion into Eastern European markets lacking incumbent suppliers.
Among Germany-based industrial conglomerates, Siemens Energy and SGB-SMIT Group exemplify the integrated manufacturing archetype with captive production of electromagnetic components. Schneider Electric, a France-based multinational, occupies a position as the distribution-channel anchor for compact outdoor installations across Iberian and French markets. Hitachi Energy represents the specialized engineering tier with emphasis on isolation transformer architectures for data center interconnection.
| Leading Market Players |
|---|
| Siemens Energy |
| Hitachi Energy |
| Schneider Electric |
| GE Vernova |
| SGB-SMIT Group |
| Eaton |
| Ormazabal |
| Kyte Powertech |
| Cahors |
| Others |
Value Network & Pricing Analysis
Germany's precision coil manufacturing concentration in Bavaria and the Rhineland anchors margin capture for high-efficiency step-down units, while price pressure from volatile copper and grain-oriented electrical steel feeds back into sourcing strategies across European OEMs. Transformer OEMs face compressed pricing power when long-term utility contracts prevent full pass-through of energy-intensive smelting cost swings.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate procurement between Deutsche Telekom, Orange, and tier-one suppliers. Pricing stratifies across premium amorphous core specifications for Scandinavian urban substations, standard silicon steel designs for volume 5G deployments, and economy-grade conventional units for Eastern European rural broadband. Cost compression in the economy tier is intensifying because Polish and Romanian operators prioritize upfront capital constraints over lifecycle efficiency. Data center operators in Ireland and the Netherlands exhibit the lowest price sensitivity, accepting N+1 redundancy premiums for isolation transformer specifications.
Supply Chain Analysis
Tariff exposure between China and the European Union threatens silicon steel lamination and copper winding supply continuity for non-vertically integrated OEMs. Manufacturing concentrates in Germany, France, and Italy for electromagnetic core production, while China and Russia supply refined copper and grain-oriented electrical steel feedstock. Supply chain risk centers on single-source dependency for amorphous metal ribbon, with Hitachi Metals and Metglas controlling global production capacity. Distribution runs through direct OEM relationships with major telecom operators, bypassing traditional electrical distributors as integrated power-cooling packages gain preference.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Telecom Transformers Market represents a high-growth disruption as 5G densification and EU Green Deal mandates force simultaneous infrastructure replacement cycles. The regulatory inflection at the Ecodesign Directive's efficiency benchmarks creates procurement urgency that favors prepared suppliers.
For Market Incumbents: Build switching-cost moats through embedded smart monitoring modules that attach to installed base assets. Siemens Energy and Schneider Electric should deepen backward integration into precision coil manufacturing to offset skilled technician scarcity in Germany's industrial heartland. Threat from open RAN standardization demands modular transformer platform investments compatible with disaggregated radio architectures. Certification investment in CE marking pre-approval accelerates market entry timelines for innovative sealed tank designs. For New Entrants and Emerging Players: Build out smart transformer retrofit kit offerings targeting Spain and Italy's condition-based maintenance transition. Poland and Romania's EU cohesion fund-financed rural broadband expansion presents the most penetrable geography, with absent incumbent suppliers and price-sensitive procurement traditions. A go-to-market angle through utility grid-edge sharing agreements reduces capital duplication barriers and leverages co-location installation expertise. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial conglomerates seeking portfolio rationalization away from non-core electromagnetic component manufacturing. Long-term viability over a five-to-ten year horizon hinges on exposure to data center interconnection growth and smart technology retrofit economics. Acquisition targets should demonstrate amorphous metal core qualification or natural ester fluid cooling system development. The signal to watch is F-Gas Regulation enforcement intensity accelerating bio-based dielectric adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Metal Core Qualification | Scandinavian operators specify these cores for urban substations where no-load loss economics dominate procurement. |
| Natural Ester Cooling System Development | French and German regulators enforce leakage monitoring requirements that favor sealed tank designs with extended intervals. |
| Smart Monitoring Module Integration | Telecom operators in Spain and Italy reduce truck rolls through predictive thermal analytics on retrofitted legacy assets. |
| Eastern European Manufacturing Footprint | Poland and Romania lack incumbent transformer suppliers, creating first-mover positioning for efficient unit providers. |
| Open RAN Platform Compatibility | Disaggregated radio architectures from Ericsson and Nokia create standardized voltage requirements for modular transformer designs. |
Research Methodology
The analysis maps step-down, isolation, step-up, and auto transformer sub-sectors, each validated through network planning executives at Deutsche Telekom and Orange, procurement officers at hyperscale data center operators, and regulatory affairs specialists at Siemens Energy and Hitachi Energy. Primary interviews with plant engineers, aftermarket service heads, and distribution channel partners combined with secondary validation from EU Ecodesign Directive filings, CE marking databases, and national energy regulator efficiency audit records. Bottom-up unit shipment estimates triangulated against top-down transformer replacement cycle modeling across the analysis window.
Fixed assumptions held copper and grain-oriented electrical steel price volatility within historical bands, while 5G densification schedules and EU Green Deal enforcement intensity were varied across scenarios. Segmentation dimensions modeled include product type, end user criticality tier, installation environment constraints, and technology sophistication level. CAGRs were derived from installed base retirement schedules and new build penetration rates, with industry-specific inputs incorporating KBA efficiency audit timelines and F-Gas Regulation phase-down schedules.
Stress conditions across raw material cost spikes, CE marking approval delays, and skilled winding labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
United States Dry-Type Transformer Market
Transformers
Air Cooled Transformer Market
Transformers
India Power Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
United States Large Power Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Traction Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Phase-Shifting Transformer Market
Transformers
Amorphous Core Transformers Market
Transformers
Neon Transformer Market
Transformers
Transformer Steel Market
Transformers
Distribution Transformer Market
Transformers
North America Smart Transformers Market
Transformers
Green Power Transformers Market