
 Three Phase Transformer Market | 2026-2036
Three Phase Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Three Phase Transformer Market Analytics
Modular substation bundling with pre-installed three phase transformers is hardening as the default procurement format for utility buyers. TBEA Co., Ltd. leverages captive silicon steel capacity to anchor cost positions in ultra-high-voltage tiers. Siemens Energy differentiates through digital monitoring integration, while Hitachi Energy competes on reactor-transformer hybrid designs for offshore wind collection.
A three phase transformer is an electromagnetic device comprising three sets of primary and secondary windings arranged on a common magnetic core, typically constructed from grain-oriented silicon steel laminations to minimize eddy current losses and achieve efficiency ratings exceeding 98% at full load; its fundamental purpose is to transmit bulk electrical power across distribution and transmission networks by stepping voltage up for long-distance transport or down for end-use consumption. Step-up configurations dominate margin pools in the renewable energy application segment, where developers require 34.5 kV to 345 kV class units for solar and wind farm interconnection. Isolation transformers sustain premium pricing in industrial settings demanding harmonic mitigation and equipment protection, while outdoor installations occupy the largest volume share due to utility preference for pad-mounted and pole-top configurations in substation expansion projects.
IEC 60076 governs international loss evaluation and temperature rise limits, while EPA regulations under the SF6 Emission Reduction Partnership constrain gas-insulated transformer designs in the US market. China's GB standards and India's CEA technical specifications for grid connectivity further fragment certification requirements for manufacturers serving multiple territories. Stakeholders must monitor evolving efficiency mandates and raw material supply concentration in transformer-grade silicon steel to calibrate capacity and sourcing strategies.
Market Dynamics
Utility procurement departments are consolidating vendor relationships around modular substation integrators who bundle three phase transformers with switchgear and protection systems, compressing the supplier base and elevating scale requirements for core material sourcing.
Growth Catalysts
- IEC 60076 efficiency tier mandates:European grid operators are accelerating replacement cycles for pre-2015 transformer fleets to meet loss-reduction thresholds, creating pull-through demand for amorphous core designs.
- India's western grid corridors:Rajasthan and Gujarat solar parks are procuring 220 kV class step-up units in multi-hundred megawatt blocks, concentrating order flow among manufacturers with 765 kV manufacturing licenses.
- Amorphous metal ribbon cores:Distribution transformer specifications in Japan and South Korea are specifying Metglas alloys for no-load loss reduction below 100 watts, rewarding suppliers with in-house ribbon annealing capability.
Market Restraints
- Grain-oriented silicon steel concentration:Nippon Steel and POSCO control over 70 percent of ultra-low-loss domain-refined sheet supply, exposing transformer OEMs to alloy surcharge volatility and allocation risk.
- SF6 insulation phase-down:EPA regulations constraining gas-insulated transformer designs are forcing dry-type and ester-fluid alternatives that carry 15-25 percent cost premiums and larger physical footprints.
- Copper winding substitution ceiling:Aluminum magnet wire penetration stalls above 66 kV voltage classes due to thermal cycling fatigue and joint reliability concerns in high-load-factor applications.
Strategic Opportunities
- Offshore wind collection platforms:66 kV inter-array voltage levels are creating demand for compact, salt-spray-rated three phase transformers with integrated shunt reactors, a product category where European suppliers currently lack scaled capacity.
- China's coastal manufacturing provinces:Jiangsu and Zhengjiang industrial parks are localizing 500 kV+ ultra-high-voltage transformer production under provincial dual carbon targets, opening joint-venture pathways for foreign core technology licensors.
- Digital twin integration:IoT sensor packages embedded in winding hot-spot monitoring are enabling predictive maintenance contracts that extend OEM revenue streams beyond equipment sale into 15-year service agreements.
Industry Challenges
- High-voltage winding technician scarcity:The specialized craft of interleaved disc winding for 345 kV+ classes is concentrated among aging workforces in Germany and Japan, constraining capacity expansion regardless of capital availability.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of IEEE C57, IEC 60076, and China's GB/T 17468 approvals for a single platform can extend product launch cycles by 18-24 months.
- Legacy oil-filled unit retrofit complexity:Substations with PCB-contaminated legacy transformers face decommissioning bottlenecks that delay site availability for new three phase installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three Phase Transformer Market |
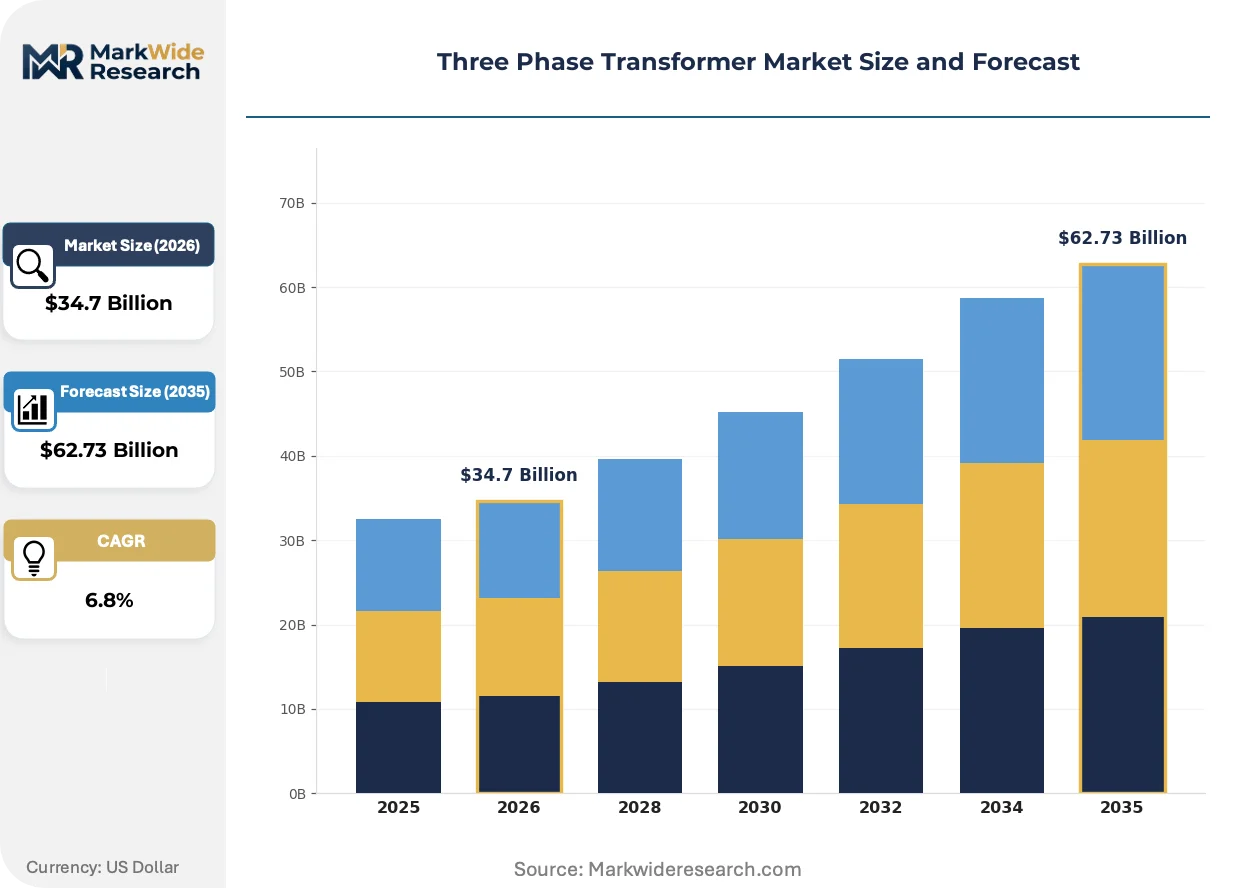
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Up, Step-Down, Isolation, Auto Application: Industrial, Commercial, Power Generation, Renewable Energy Installation: Indoor, Outdoor, Mounted, Portable End User: Utilities, Manufacturing, Construction, Telecommunications |
| Companies Covered | CHINT Electric Co., Ltd., AISITE Transformer Co., Ltd., TBEA Co., Ltd., Hitachi Energy, Siemens Energy, China XD Group, CEEG, Eaton, Taikai Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three Phase Transformer Market Evolving Landscape
Transformer design is bifurcating between ultra-efficient distribution units for dense urban load centers and ruggedized high-voltage platforms for renewable collection, with digital monitoring becoming a non-negotiable specification rather than an optional add-on.
Amorphous metal core technology is overtaking conventional grain-oriented silicon steel in distribution transformer specifications below 10 MVA. Japanese utilities led adoption during the 2011 efficiency push, and Indian state distribution companies are now mandating no-load loss levels achievable only through Metglas ribbon construction. The structural consequence is a supply squeeze on amorphous metal feedstock that favors transformer manufacturers with backward integration into ribbon casting or long-term offtake agreements with Hitachi Metals.
Europe's F-Gas Regulation is tightening permissible global warming potential ratings for insulating gases, accelerating development of fluoronitrile and clean-air alternatives to SF6 in gas-insulated transformer designs. German transmission system operators are piloting 145 kV units with C4-FN mixtures, while French RTE specifications now exclude pure SF6 for new substation installations. The segment most affected is urban underground substations where footprint constraints previously mandated gas insulation, now driving demand for compact dry-type and ester-filled alternatives.
Utility engineering departments are unbundling transformer procurement from turnkey substation contracts, establishing direct relationships with OEMs for specification compliance and lifecycle accountability. This disintermediation is compressing margins for traditional EPC intermediaries while elevating technical sales engagement requirements for manufacturers. The shift is most visible in Australia's National Electricity Market, where transmission network service providers now issue separate transformer and switchgear tenders for greenfield solar connection projects.
Three Phase Transformer Market Segmentation
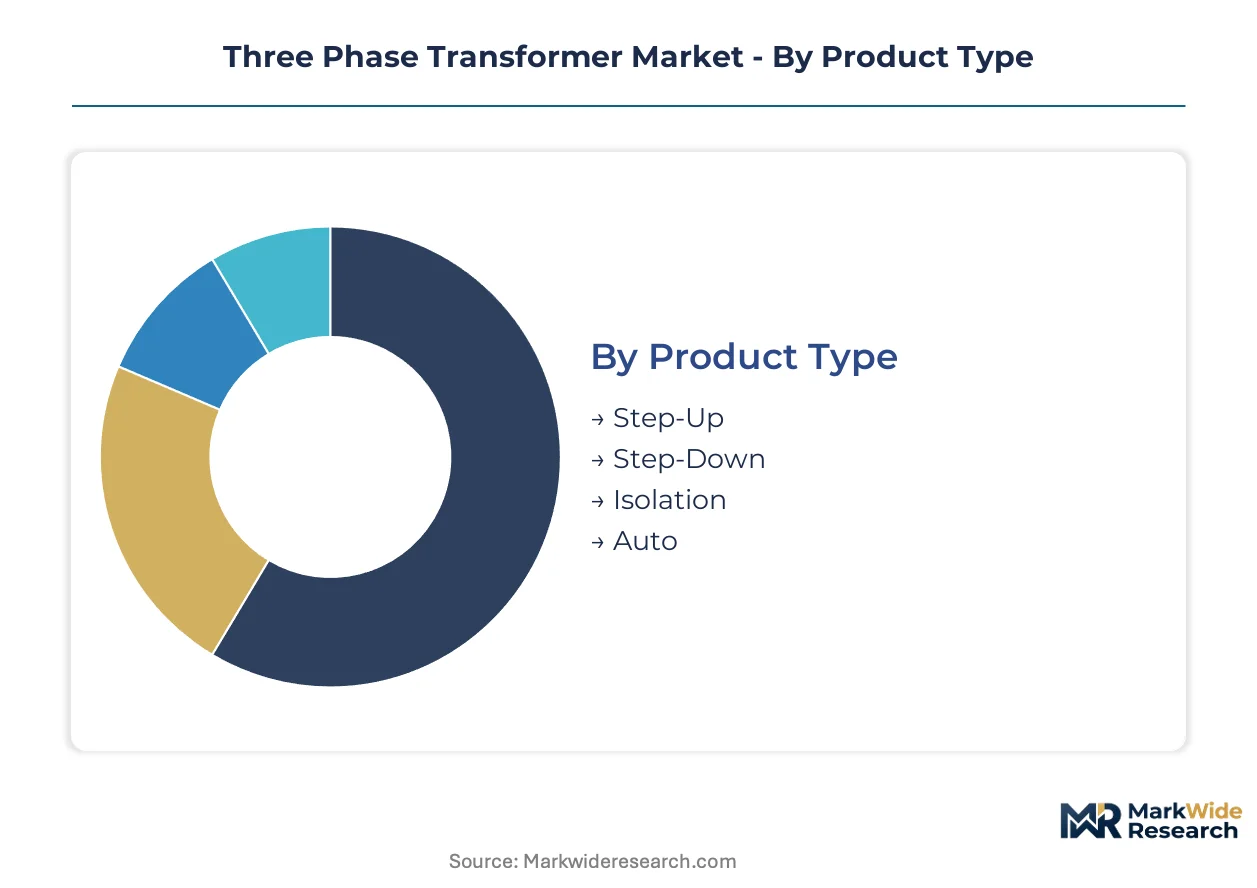
Three phase transformer procurement patterns diverge sharply across voltage classes and end-use contexts, with utility-scale renewable projects demanding standardized high-voltage platforms while industrial buyers seek customized harmonic-mitigation specifications. Understanding these segment boundaries clarifies where manufacturers must anchor modular designs versus engineer-to-order capabilities.
Product Type:
Standardization dominates at distribution voltage levels while ultra-high-voltage tiers require bespoke engineering for loss optimization and thermal management.
- Step-Up:Configurations elevate generator output from 34.5 kV to 345 kV for long-distance transmission, with Rajasthan and Gujarat solar parks procuring 220 kV class units in concentrated blocks. Renewable interconnection mandates are hardening demand for amorphous core designs that meet IEC 60076 efficiency tiers.
- Step-Down:Units reduce transmission voltage to distribution levels across urban substations and industrial parks. China's coastal manufacturing provinces are localizing 500 kV+ production under provincial dual carbon targets, compressing import dependency for grid infrastructure.
- Isolation:Separates primary and secondary circuits completely to block harmonic propagation and protect sensitive equipment. Premium positioning in data center and semiconductor fabrication applications.
- Auto:Shares winding sections between primary and secondary sides, reducing copper mass and physical footprint for cost-constrained utility budgets. Prevalent in voltage ratio applications below 3:1.
Leading the category by volume: Step-Down. Expanding most quickly: Step-Up.
Application:
Margin profiles invert between mature industrial replacement cycles and capital-intensive renewable greenfield development.
- Power Generation:Centralized thermal and nuclear plants require 765 kV class step-up units with decades-long service intervals. Aging technician workforces in Germany and Japan constrain capacity expansion regardless of capital availability.
- Renewable Energy:Offshore wind collection platforms at 66 kV inter-array voltage levels demand compact, salt-spray-rated designs with integrated shunt reactors. European suppliers currently lack scaled capacity for this emerging specification.
- Industrial:Steel, cement, and chemical processing facilities specify isolation transformers for harmonic mitigation and equipment protection. Procurement concentrates around modular substation bundling with switchgear.
- Commercial:Office complexes and retail distribution centers favor pad-mounted step-down units for secondary distribution. Digital monitoring integration is becoming a non-negotiable specification.
Commanding the highest margins: Renewable Energy. Largest installed base: Industrial.
Installation:
Footprint constraints and environmental exposure dictate material selection between oil-immersed, dry-type, and ester-fluid insulation systems.
- Outdoor:Pad-mounted and pole-top configurations occupy the largest volume share due to utility preference in substation expansion projects. EPA SF6 phase-down rules are forcing dry-type and ester-fluid alternatives that carry cost premiums and larger physical footprints.
- Indoor:Underground urban substations previously mandated gas insulation for compactness; Europe's F-Gas Regulation now drives demand for compact dry-type and ester-filled alternatives with fluoronitrile mixtures.
- Mounted:Pole-top and platform-mounted units serve rural distribution networks with standardized kVA ratings. Procurement runs through consolidated vendor relationships with modular substation integrators.
- Portable:Mobile substation trailers for emergency restoration and construction power represent a niche segment with premium rental pricing structures.
Dominating procurement volume: Outdoor. Facing steepest technical disruption: Indoor.
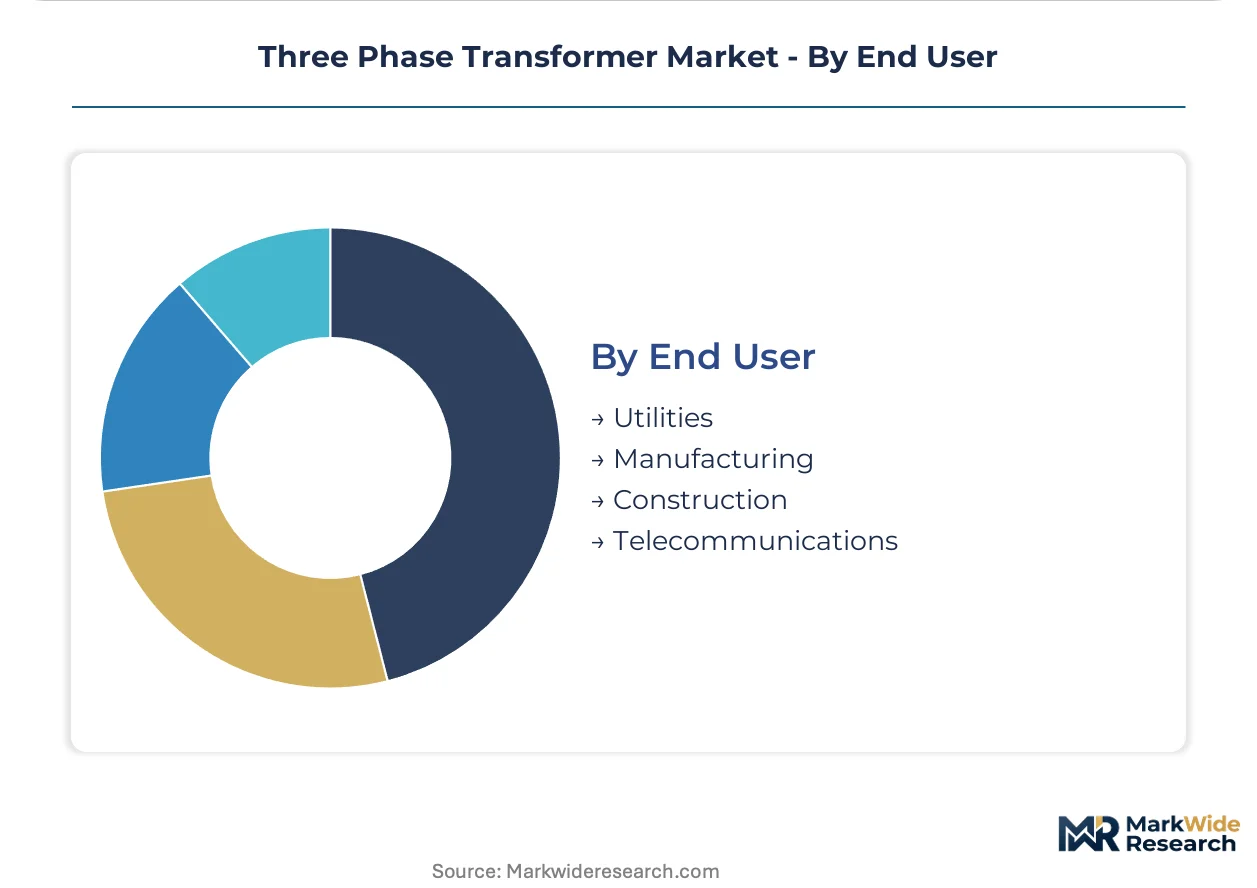
End User:
Customer scale determines whether procurement flows through EPC intermediaries or direct OEM relationships with lifecycle accountability clauses.
- Utilities:Transmission network service providers in Australia's National Electricity Market now issue separate transformer and switchgear tenders, disintermediating traditional EPC contractors. Direct OEM relationships elevate technical sales engagement requirements.
- Manufacturing:Automotive and electronics producers specify harmonic-mitigating isolation transformers for clean power delivery. Multi-jurisdiction certification timelines for simultaneous IEEE C57, IEC 60076, and GB/T 17468 approvals can extend product launch cycles.
- Construction:Temporary power infrastructure for megaprojects favors rental and lease structures over capital purchase. Demand fluctuates with infrastructure investment cycles.
- Telecommunications:Data center operators require ultra-efficient distribution units with IoT sensor packages for predictive maintenance contracts extending OEM revenue into 15-year service agreements.
Generating the largest order values: Utilities. Driving fastest specification evolution: Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of transformer-grade silicon steel and ultra-high-voltage units, while India and the United States consume substantial volumes for grid expansion and renewable interconnection. This production-consumption divide shapes procurement strategies across major markets.
China
Jiangsu and Zhejiang industrial parks localize 500 kV+ transformer production under provincial dual carbon targets. GB standards and MIIT efficiency mandates accelerate replacement of pre-2020 distribution fleets. Coastal manufacturing clusters now supply domestic renewable projects and export markets simultaneously.
India
Rajasthan and Gujarat solar parks procure 220 kV class step-up units in multi-hundred megawatt blocks. CEA technical specifications for grid connectivity require manufacturers to hold 765 kV manufacturing licenses. Western grid corridors concentrate order flow among domestic and joint-venture producers.
United States
Texas and California utility-scale solar farms expand procurement of 34.5 kV to 345 kV step-up configurations. EPA SF6 Emission Reduction Partnership regulations constrain gas-insulated designs, elevating dry-type and ester-fluid alternatives. FERC interconnection queues drive substation expansion timelines.
Germany
Transmission system operators pilot 145 kV fluoronitrile transformer units under EU F-Gas Regulation phase-down schedules. Bavaria and North Rhine-Westphalia host aging technician workforces specialized in 345 kV+ interleaved disc winding. E.ON and TenneT procurement favors modular substation bundling.
Japan
Tokyo Electric Power and regional utilities mandate amorphous core distribution transformers with no-load losses below 100 watts. METI efficiency tiers reward suppliers with in-house Metglas ribbon annealing capability. Chubu and Kansai industrial zones concentrate transformer-grade silicon steel processing.
Three Phase Transformer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across voltage tiers and application segments. The market structure concentrates around scale-driven OEMs with captive core material sourcing and technology licensors with digital monitoring capabilities. Three archetypes dominate: integrated steel-to-transformer producers, digital-native equipment suppliers, and regional specialists with utility relationships. Capacity expansion and strategic partnerships constitute the primary competitive moves, with joint ventures proliferating in China's coastal provinces.
Among China-based manufacturers, TBEA Co., Ltd. and China XD Group exemplify integrated production archetypes with upstream control over silicon steel supply. Siemens Energy and Hitachi Energy occupy positions on the technology-differentiation vector, representing digital monitoring and reactor-transformer hybrid specializations respectively. CEEG and Taikai Group anchor the regional specialist tier with concentrated utility relationships in domestic markets.
| Leading Market Players |
|---|
| CHINT Electric Co., Ltd. |
| AISITE Transformer Co., Ltd. |
| TBEA Co., Ltd. |
| Hitachi Energy |
| Siemens Energy |
| China XD Group |
| CEEG |
| Eaton |
| Taikai Group |
| Others |
Value Network & Pricing Analysis
Utility procurement consolidation around modular substation bundling is compressing supplier margins and forcing transformer OEMs to absorb alloy surcharge volatility from concentrated silicon steel sources.
Pricing Analysis
Cost compression in distribution transformer tiers reflects amorphous metal core substitution mandates from Japanese and Indian utilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 60076 efficiency certification grade and captive silicon steel sourcing. Pricing pressure intensifies in step-up configurations as renewable developers consolidate 220 kV class orders into multi-hundred megawatt blocks. Industrial isolation transformer buyers exhibit lowest price sensitivity due to harmonic mitigation specifications, while commercial pad-mounted procurement shows highest elasticity.
Supply Chain Analysis
Multi-jurisdiction certification gating extends product launch cycles and elevates working capital requirements for transformer manufacturers serving cross-border markets. Supply concentrates in China, Japan, and South Korea for grain-oriented silicon steel and ultra-high-voltage manufacturing licenses. Raw material dependencies center on transformer-grade silicon steel laminations, Metglas amorphous metal ribbon, and copper magnet wire. Single-source vulnerability persists in domain-refined steel sheet from Nippon Steel and POSCO. Distribution runs through direct OEM relationships with transmission network service providers and modular substation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized high-voltage winding technician scarcity constrains capacity expansion regardless of capital availability, propping pricing power for incumbent manufacturers with aging craft workforces.
For Market Incumbents: Anchor cost positions through backward integration into silicon steel processing or long-term offtake agreements with Hitachi Metals for Metglas ribbon. Defend against emerging digital-native equipment suppliers by embedding IoT sensor packages for predictive maintenance contracts. Prioritize certification investment in simultaneous IEEE C57, IEC 60076, and GB/T 17468 approvals to compress launch cycles. For New Entrants and Emerging Players: Modular substation integrators represent the most accessible channel pathway for market entry. Target offshore wind collection platforms at 66 kV inter-array voltage levels where European suppliers currently lack scaled capacity. Pursue joint-venture structures in China's Jiangsu and Zhejiang industrial parks under provincial dual carbon targets. For Investors and Strategic Acquirers: The window for entry favors manufacturers with in-house ribbon annealing capability and 765 kV manufacturing licenses. Long-term viability hinges on exposure to India's western grid corridors and renewable interconnection mandates. Watch for inflection signals in EPA SF6 phase-down enforcement accelerating dry-type and ester-fluid alternative adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Steel | TBEA Co., Ltd. leverages captive capacity to anchor ultra-high-voltage tier cost positions. |
| Digital Monitoring Platform Integration | Siemens Energy differentiates through IoT sensor packages enabling 15-year predictive maintenance contracts. |
| Amorphous Core Manufacturing Scale-Up | Japanese and Indian utility mandates for no-load loss reduction below 100 watts reward Metglas ribbon suppliers. |
| Joint Venture Localization in China | Foreign core technology licensors access 500 kV+ production under Jiangsu and Zhejiang dual carbon targets. |
| Fluoronitrile Insulation Development | German transmission operators pilot C4-FN mixtures under EU F-Gas Regulation phase-down schedules. |
Research Methodology
Regulatory filings from EPA, IEC, and CEA, transformer OEM technical specifications, and utility procurement databases formed the secondary backbone. Primary interviews with utility planning officers, EPC contractors, grid operators, transformer manufacturing executives, and silicon steel procurement leads validated demand assumptions. Bottom-up unit economics and top-down market sizing were triangulated against customs trade data and FERC interconnection queue records.
Bottom-up modeling of voltage class, application segment, and installation type deployments across the analysis window generated volume and value outputs. CAGRs were derived from regression analysis of historical procurement patterns and regulatory mandate timelines. Forecast inputs incorporated IEC 60076 efficiency tier adoption curves, India's CEA licensing requirements, and EPA SF6 phase-down enforcement trajectories.
Caveats apply where raw material supply disruption or multi-jurisdiction certification delays could materially shift the outlook. Forecasts reflect assumptions around technician workforce availability and alloy surcharge stability. A model refresh is warranted upon material change in grain-oriented silicon steel allocation policies or amorphous metal feedstock expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Smart Transformers Market
Transformers
Industrial Control Transformers Market
Transformers
Middle-East Smart Transformer Market
Transformers
South America Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Step Up/Down Transformers Market
Transformers
Latin America Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Middle East and Africa Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
Middle East Distribution Transformer Market
Transformers
Gas Insulated Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
North America Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market