
 Liquid Filled Transformer Market | 2026-2036
Liquid Filled Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Filled Transformer Market Foresight
IEEE C57 transformer testing and qualification is unwinding the competitive landscape, raising barriers for new entrants while favoring incumbents with certified testing laboratories. Hitachi Energy leverages its global manufacturing footprint to sustain cost competitiveness across high-voltage segments. Schneider Electric anchors its position through integrated digital monitoring platforms paired with liquid-filled hardware. ABB competes aggressively in offshore wind interconnection projects requiring specialized step-up designs.
A liquid filled transformer is an electromagnetic apparatus that uses mineral oil or synthetic ester as both coolant and dielectric medium, typically operating at voltages from 4.16 kV to 765 kV with temperature rises controlled through natural or forced oil circulation. Its primary purpose is to transfer electrical energy between circuits via electromagnetic induction while managing thermal loads that air-cooled units cannot dissipate efficiently. Distribution transformers occupy the largest volume tier due to ubiquitous grid deployment, though power transformers command disproportionate margin pools from utility-scale projects. Step-up configurations for renewable energy integration represent the fastest-expanding application segment as wind and solar farms require voltage elevation for transmission.
EPA efficiency regulations under the Energy Conservation Program mandate minimum performance standards for liquid-filled distribution transformers sold in the United States, directly influencing core steel grades and winding designs. IEEE C57 standards govern testing protocols and thermal performance ratings, while IEC 60076 provides the parallel framework for markets outside North America. NHTSA and DOT indirectly shape demand through electric vehicle charging infrastructure buildouts that strain existing distribution capacity. Stakeholders must monitor evolving efficiency tier thresholds and copper-aluminum substitution economics as procurement specifications tighten.
Market Dynamics
Grid modernization mandates and EPA efficiency tier escalations are compressing product lifecycles while forcing simultaneous capital deployment across manufacturing and testing infrastructure.
Growth Catalysts
- EPA Energy Conservation Program Tier 2 mandates:The tightened efficiency thresholds for distribution transformers sold in the United States are accelerating replacement cycles for utilities holding aging mineral-oil units.
- Offshore wind interconnection buildouts:Renewable developers in China and Germany require specialized step-up designs for floating and fixed-bottom arrays, creating dedicated procurement channels.
- Natural ester dielectric fluids:Biodegradable coolant chemistry is penetrating data center and urban substation applications where fire safety and environmental containment override first-cost considerations.
Market Restraints
- Grain-oriented electrical steel concentration:Cold-rolled core material supply clusters in China and Japan, exposing transformer OEMs to alloy pricing volatility and export quota disruptions.
- IEEE C57.12.00 testing bottlenecks:Certified laboratory capacity constraints in North America extend qualification timelines for new entrants by 8-14 months.
- Dry-type transformer substitution:Cast-resin units are capturing indoor commercial and industrial segments below 10 MVA where fire codes restrict liquid-filled installations.
Strategic Opportunities
- India rural electrification gaps:The country's national power utility targets universal household connectivity by decade-end, requiring millions of distribution units for 11 kV feeder extensions.
- Digital twin integration:Thermal modeling software paired with dissolved gas analysis sensors enables predictive maintenance contracts that extend OEM revenue streams beyond hardware shipment.
- EU F-Gas Regulation phase-down:Synthetic ester fluids with lower global warming potential qualify for accelerated depreciation under member-state green tax incentives.
Industry Challenges
- Winding technician scarcity:Precision copper and aluminum coil fabrication requires multi-year apprenticeships that vocational programs in the United States and Germany have not scaled to replacement rates.
- Legacy SCADA integration friction:New intelligent electronic devices from transformer manufacturers must communicate with decades-old utility control protocols, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Filled Transformer Market |
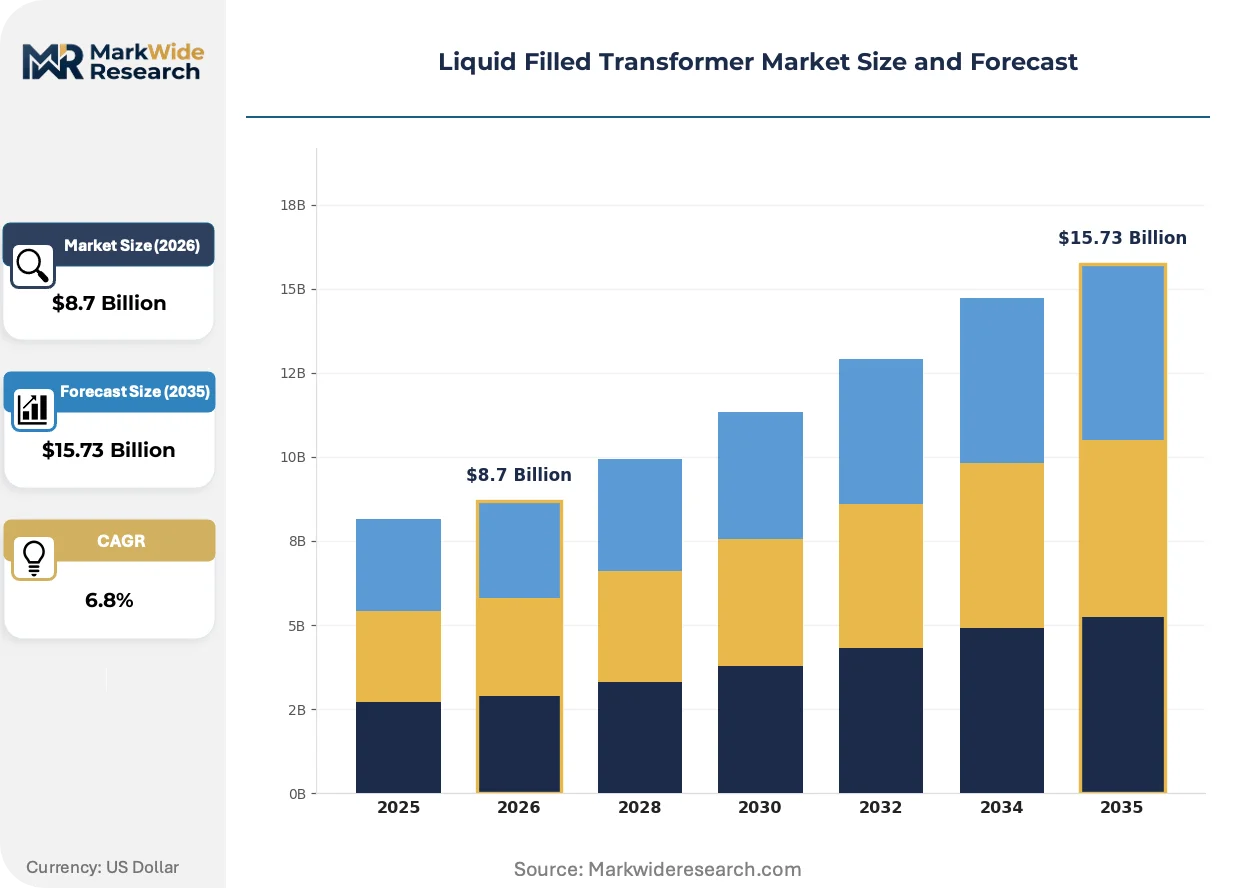
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Up Transformer, Step-Down Transformer, Distribution Transformer, Power Transformer End User: Utilities, Industrial Manufacturing, Renewable Energy, Commercial Facilities Installation Type: Indoor, Outdoor, Underground, Above Ground Cooling Method: Oil-Immersed, Water-Cooled, Air-Cooled, Fans |
| Companies Covered | Schneider Electric, Hammond Power Solutions, Hitachi Energy, JSHP Transformer, MGM Transformer Company, ABB, Siemens Energy AG, Prolec GE, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Filled Transformer Market Shifts & Advancements
Active materials substitution and embedded sensing architectures are redefining competitive differentiation beyond nameplate efficiency metrics toward total lifecycle cost optimization.
Natural and synthetic ester dielectric fluids are displacing conventional mineral oil in fire-sensitive installations. Data center operators and urban underground utilities are specifying these alternatives for their elevated flash points and reduced environmental liability. The shift is compressing margins for legacy oil-formulation suppliers while creating captive supply advantages for vertically integrated chemical processors.
REACH restrictions on persistent organic pollutants are forcing reformulation of antioxidant packages used in transformer oils. European compounders must validate new additive chemistries through accelerated aging protocols before 2026 registration deadlines. Distribution transformer OEMs serving EU member states are dual-qualifying fluid systems to avoid supply disruption during the transition window.
Performance-based service agreements are displacing traditional equipment procurement in utility accounts. Major grid operators in California and Texas now contract for guaranteed availability and thermal loading capacity rather than capital asset ownership. This restructures vendor economics toward uptime penalties and remote monitoring subscriptions, favoring manufacturers with integrated digital platforms over pure hardware suppliers.
Liquid Filled Transformer Market Segmentation
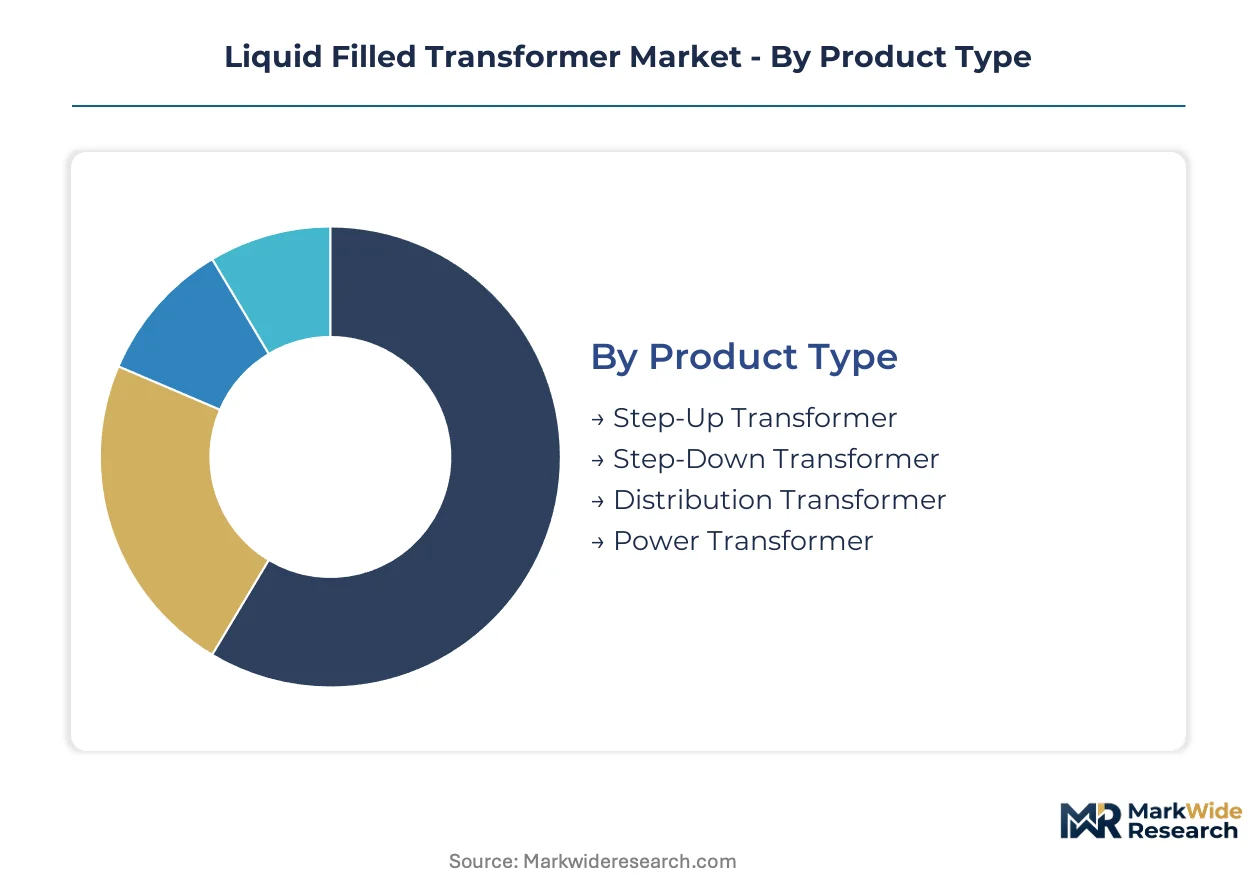
Liquid filled transformer procurement specifications diverge sharply across voltage classes and end-use applications, with regulatory efficiency tiers and fire safety codes dictating acceptable configurations. Understanding these segment boundaries clarifies where margin pools concentrate and which technical qualifications create vendor stickiness.
Product Type:
EPA Energy Conservation Program mandates and IEEE C57 testing protocols create tiered entry barriers that reshape competitive dynamics across voltage ratings and thermal performance classes.
- Distribution Transformer:Units rated below 34.5 kV dominate unit volume across utility procurement programs. Rural electrification drives in India and grid hardening initiatives in the United States absorb millions of these units annually, with efficiency tier escalations forcing core steel upgrades.
- Power Transformer:High-voltage designs above 69 kV command specialized manufacturing infrastructure and extended qualification timelines. Offshore wind interconnection projects in Germany and China require bespoke step-up configurations with forced oil circulation systems.
- Step-Up Transformer:Renewable energy integration applications demand voltage elevation for transmission economics. Solar farms in Texas and wind arrays in the North Sea specify these units for collector system aggregation.
- Step-Down Transformer:Industrial substations and urban distribution networks deploy these for voltage reduction. Data center campuses in Northern Virginia and manufacturing parks in Gujarat represent concentrated demand pockets.
Distribution transformers handle the majority of throughput; power transformers are the fastest mover on share.
End User:
Capital deployment cycles and procurement sophistication vary dramatically across customer categories, with utility-scale buyers demanding performance guarantees that reshape vendor economics.
- Utilities:Grid operators in California, Texas, and Maharashtra drive standardization through multi-year framework agreements. These accounts specify dissolved gas analysis sensors and remote monitoring integration as baseline requirements.
- Renewable Energy:Wind and solar developers require specialized step-up designs for collector systems. Floating offshore arrays in the North Sea and utility-scale solar in Rajasthan create dedicated procurement channels with accelerated delivery timelines.
- Industrial Manufacturing:Steel mills, chemical plants, and semiconductor fabs specify ruggedized designs for harmonic-rich environments. Fire safety codes in European petrochemical clusters increasingly mandate natural ester dielectric fluids.
- Commercial Facilities:Shopping complexes, hospitals, and university campuses deploy liquid-filled units where load density exceeds dry-type thermal limits. Urban underground installations in Tokyo and London face strict containment regulations.
Utilities anchor procurement volume; renewable energy developers are climbing the fastest on share.
Installation Type:
Physical deployment constraints and environmental exposure dictate cooling architecture and enclosure specifications, with fire codes and flood risk reshaping site selection.
- Outdoor:Open-air substations across the United States, China, and India represent the default configuration for utility-scale deployment. Weatherproof enclosures and corrosion-resistant coatings extend service life in coastal and high-humidity environments.
- Underground:Urban density in Tokyo, Singapore, and Manhattan drives vault and tunnel installations where fire containment and oil spill prevention override first-cost considerations. Synthetic ester fluids penetrate this segment for reduced environmental liability.
- Indoor:Industrial facilities and commercial buildings specify these where space constraints or aesthetic requirements apply. Fire suppression systems and oil containment curbs add capital cost but satisfy building code mandates.
- Above Ground:Elevated platforms and skid-mounted configurations serve temporary power and remote extraction sites. Mining operations in Western Australia and oil sands in Alberta favor these for rapid relocation.
Outdoor installations carry the bulk of deployed capacity; underground configurations are expanding most quickly.
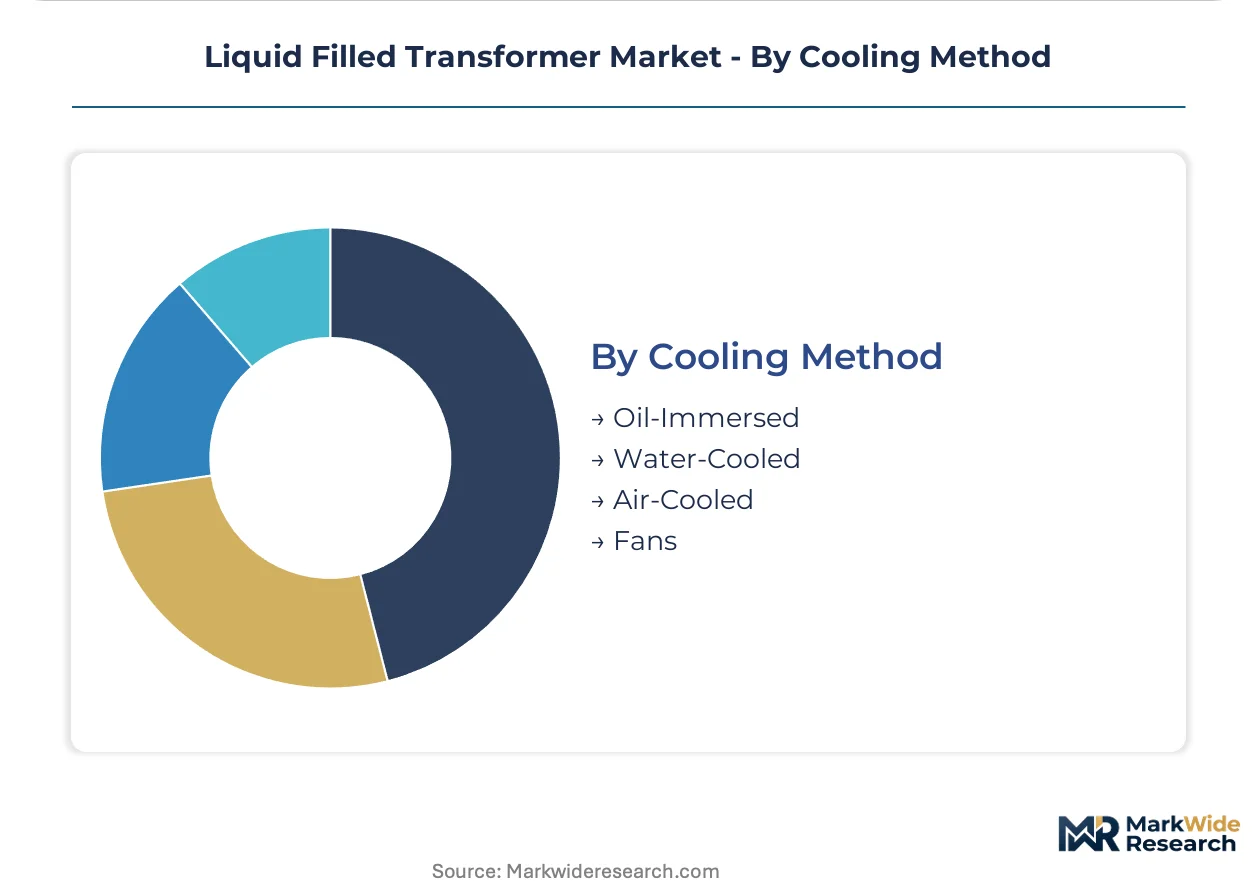
Cooling Method:
Thermal management architecture directly determines load capability and maintenance intervals, with active cooling systems enabling higher power density in constrained footprints.
- Oil-Immersed:Mineral oil or ester fluid baths with natural circulation dominate distribution ratings through 10 MVA. This approach leverages mature manufacturing processes and established IEEE C57 thermal rise protocols.
- Fans:Forced air augmentation on radiators enables 25-50% load increases without footprint expansion. Data center substations in Ashburn and Frankfurt specify these for peak shaving capability.
- Water-Cooled:Heat exchanger systems serve high-power-density applications where ambient air cannot dissipate thermal loads. Offshore platforms and submarine interconnections in the North Sea deploy these configurations.
- Air-Cooled:Hybrid designs combine oil insulation with air heat rejection for specific indoor applications. These occupy niche positions where fire codes restrict liquid volume but thermal loads exceed dry-type ratings.
Oil-immersed systems handle the majority of installed base; fan-assisted cooling is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Energy Conservation Program mandates and rural electrification targets are reshaping procurement patterns across major transformer-consuming economies. Grid hardening investments and renewable integration requirements concentrate demand in specific national markets where regulatory timelines and infrastructure age create synchronized replacement cycles.
United States
Utility-scale grid modernization drives transformer procurement across Texas, California, and the Midwest. EPA Tier 2 efficiency mandates accelerate replacement of aging mineral-oil units installed during the 1960s-1980s buildout. Houston and Dallas-Fort Worth clusters host concentrated manufacturing capacity serving domestic utility accounts.
China
Offshore wind interconnection projects in the Yangtze River Delta and Bohai Bay require specialized step-up designs for floating arrays. MIIT grid investment targets and dual carbon goals prioritize high-efficiency units for renewable collector systems. Shanghai and Jiangsu province anchor manufacturing for export-oriented OEMs.
Germany
North Sea offshore wind buildouts and industrial electrification strain existing transformer capacity. EU F-Gas Regulation phase-down accelerates synthetic ester adoption for fire-sensitive urban installations. Hamburg and Bremen harbor zones concentrate specialized fabrication for submarine interconnection projects.
India
Rural electrification gaps and distribution network expansion absorb millions of units annually under national connectivity targets. CEA technical standards and state utility procurement programs standardize 11 kV feeder specifications. Gujarat and Maharashtra industrial corridors drive demand for heavy-duty power transformer configurations.
Japan
Grid resilience investments following recent seismic events prioritize earthquake-resistant designs and dissolved gas monitoring systems. METI efficiency roadmaps and urban underground substation requirements favor synthetic ester fluids in Tokyo and Osaka metro areas. Chubu and Kansai regions concentrate domestic manufacturing for replacement cycles.
Liquid Filled Transformer Market Competitive Landscape
Player mix skews toward diversified electrical equipment conglomerates with integrated digital platforms and specialized high-voltage engineering houses. Market structure shows moderate consolidation at the premium tier for power transformers above 69 kV, with fragmented competition in distribution ratings below 34.5 kV. Two dominant archetypes emerge: vertically integrated energy technology groups with global manufacturing footprints, and regional specialists capturing utility framework agreements through proximity and service responsiveness. Competitive moves center on strategic partnerships for offshore wind interconnection projects and portfolio diversification into predictive maintenance software.
Among diversified electrical equipment groups, Schneider Electric, Hitachi Energy, and ABB exemplify the integrated-platform archetype combining liquid-filled hardware with digital monitoring capabilities. These entities occupy positions where utility-scale procurement specifications increasingly mandate dissolved gas analysis sensors and remote diagnostics integration. Regional specialists such as Hammond Power Solutions and JSHP Transformer sit within tiered competitive layers serving distribution transformer volume through manufacturing proximity to North American and Asian utility accounts respectively. Siemens Energy AG and General Electric Company represent the heavy-power segment where offshore wind and grid interconnection projects require bespoke engineering qualifications.
| Leading Market Players |
|---|
| Schneider Electric |
| Hammond Power Solutions |
| Hitachi Energy |
| JSHP Transformer |
| MGM Transformer Company |
| ABB |
| Siemens Energy AG |
| Prolec GE |
| General Electric Company |
| Others |
Supply & Pricing Matrix
Copper-to-aluminum winding substitution is compressing material cost structures while simultaneously redrawing procurement geography toward suppliers with flexible coil fabrication capabilities. This input shift allows OEMs to offset grain-oriented electrical steel volatility but introduces new qualification hurdles under IEEE C57 thermal rise protocols.
Pricing Analysis
Certification level under IEEE C57.12.00 and IEC 60076 creates the primary spread between premium and standard tiers, with laboratory-validated units commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects core steel grade, fluid chemistry, and bundled digital monitoring capabilities. Pricing pressure stems from EPA Tier 2 efficiency mandates forcing core material upgrades without proportional tariff recovery mechanisms. Municipal utilities exhibit highest price sensitivity due to rate-case constraints, while offshore wind developers prioritize availability over unit cost.
Supply Chain Analysis
Inventory buffers for grain-oriented electrical steel have thinned to precarious levels, with transformer OEMs holding 60-90 day coverage versus historical 120-180 day positions. Manufacturing concentrates in China, Japan, and Germany for cold-rolled core material, while coil winding and final assembly distributes across the United States, India, and Poland. Supply chains draw from copper cathode, aluminum rod, and specialty ester fluid feedstocks. Single-source vulnerability concentrates in Nippon Steel and Baosteel for domain-refined electrical steel. Distribution runs through direct utility framework agreements and EPC contractor channels for project-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA efficiency tier escalations and renewable interconnection mandates are accelerating replacement cycles beyond historical patterns, creating a high-growth disruption where capability scarcity in certified testing infrastructure separates winners from laggards.
For Market Incumbents: Shield margin pools by securing captive testing laboratory capacity before IEEE C57.12.00 qualification bottlenecks worsen, and deepen backward integration into grain-oriented electrical steel through offtake agreements with Japanese and Chinese mills. Dry-type transformer substitution in commercial buildings below 10 MVA represents the core threat to legacy volume; vertical control over core steel grades offers the primary defensive lever. For New Entrants and Emerging Players: Lead with digital twin integration and predictive maintenance software rather than hardware commoditization, targeting municipal utilities in Texas and California where performance-based service agreements displace capital procurement. Rural electrification gaps in India offer the most penetrable geography; partner with state distribution companies for 11 kV feeder specifications rather than competing for utility-scale power transformer qualifications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists holding utility framework agreements but lacking digital platform integration. Five-to-ten year viability hinges on EPA efficiency tier enforcement durability and renewable buildout continuity. Watch for IEEE C57 testing laboratory acquisition activity as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Supply | Captive offtake agreements with Baosteel insulate Hitachi Energy and ABB from export quota volatility. |
| Digital Twin Platform Development | Schneider Electric's EcoStruxure integration extends revenue streams beyond hardware into predictive maintenance subscriptions. |
| Natural Ester Fluid Qualification | EU F-Gas Regulation phase-down accelerates synthetic ester adoption for urban underground installations in Germany. |
| IEEE C57 Testing Laboratory Acquisition | Certified capacity constraints in North America extend qualification timelines, favoring incumbents with in-house validation. |
| Offshore Wind Interconnection Partnership | Specialized step-up designs for floating arrays in the North Sea and Yangtze River Delta create dedicated procurement channels. |
Research Methodology
The analysis maps distribution transformer, power transformer, and step-up configurations, each validated through utility procurement officers, transformer OEM product managers, EPC contractor project directors, and grid operator planning engineers. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, FERC interconnection queues, EPA Energy Conservation Program dockets, and IEEE standards documentation. Bottom-up unit deployment estimates triangulated against top-down grid investment forecasts.
Consistency checks against EIA transformer shipment data and IEA grid modernization expenditure benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled voltage class, cooling architecture, dielectric fluid chemistry, and end-use application segmentation. CAGRs derived from replacement cycle analysis, efficiency mandate compliance timelines, and renewable capacity addition trajectories. Forecast inputs incorporated grain-oriented electrical steel pricing indices and copper-aluminum substitution elasticities.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement, continued offshore wind buildout, or stable electrical steel supply would require recalibration. Forecasts reflect documented assumptions regarding efficiency tier adoption rates and IEEE qualification capacity expansion. Specific risks include tariff disruption on core steel imports, dry-type substitution acceleration, and winding technician scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Smart Transformers Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
Uninhibited Transformer Oil Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Smart Transformer Market
Transformers
Global Transformer Market
Transformers
Global Large Power Transformers Market
Transformers
South America Transformer Market
Transformers
North America Smart Transformers Market
Transformers
United Arab Emirates Transformer Market
Transformers
Transformer Core Market
Transformers
Latin America Transformer Market
Transformers
India Transformer Market
Transformers
HVDC Converter Transformers Market
Transformers
Asia-Pacific Transformer Market
Transformers
Middle East and Africa Transformer Market