
 Third Generation Energy Sources Market | 2026-2036
Third Generation Energy Sources Market Size, Share, and Industry Trends Forecast 2026-2036
Third Generation Energy Sources Market Analytics
ISO 50001 energy management certification is rotating the competitive landscape toward firms demonstrating verified operational efficiency. NextEra Energy leverages its utility-scale development pipeline across multiple continents to sustain project origination velocity. Brookfield Renewable Partners anchors its position through captive infrastructure ownership and long-term power purchase agreements. Fluence Energy differentiates with integrated hardware-software platforms for grid-connected storage systems.
Third generation energy sources encompass advanced renewable and clean conversion technologies that bypass conventional combustion cycles, including solid-oxide fuel cells operating at 800-1000°C and closed-loop geothermal binary plants using organic Rankine cycles with working fluids selected for low-boiling-point optimization. These systems deliver dispatchable baseload power, industrial process heat, or grid stabilization services where intermittent first- and second-generation renewables require firming capacity. Photovoltaics dominates installed capacity across utility and distributed applications, while fuel cells capture premium value in data center and maritime propulsion segments requiring continuous reliable output. Hydrokinetic technology occupies early commercialization phases with concentrated demonstration activity in tidal channel environments.
FERC Order 2023 reshapes interconnection queue management across the United States, compressing study timelines and accelerating project energization dates for hybrid solar-plus-storage facilities. The EPA's greenhouse gas standards for existing power plants create compliance pathways favoring biomass co-firing and geothermal retrofits at retiring coal stations. Stakeholders must monitor evolving state-level renewable portfolio standard modifications and utility integrated resource plan proceedings to anticipate procurement timing and offtake structure evolution.
Market Dynamics
FERC Order 2023 compresses interconnection study timelines for hybrid solar-plus-storage facilities, compressing project energization schedules and reordering competitive positioning toward developers with pre-certified equipment packages and established utility relationships.
Growth Catalysts
- ISO 50001 Certification Mandates:Industrial offtakers in Germany and Japan now require supplier energy management certification, rotating procurement toward verified efficient operators.
- Utility-Scale Solar Thermal Procurement:Southwestern United States developers leverage streamlined FERC interconnection rules to accelerate permitting for dispatchable renewable capacity.
- Grid-Scale Storage Co-Location:Australian developers pair photovoltaics with battery systems to displace legacy peaker plants and capture ancillary services revenue.
Market Restraints
- High-Temperature Material Costs:Solid-oxide fuel cells require yttria-stabilized zirconia and specialized interconnects, exposing manufacturers to rare earth price volatility concentrated in Chinese processing facilities.
- Binary Working Fluid Supply Concentration:Closed-loop geothermal plants depend on isobutane and pentane blends from limited petrochemical suppliers, creating feedstock vulnerability.
- EPA Compliance Pathway Uncertainty:Greenhouse gas standards for existing power plants create permitting friction for biomass co-firing retrofits at retiring coal stations.
Strategic Opportunities
- Data Center Continuous Power:Solid-oxide fuel cells capture premium value in hyperscale computing facilities requiring uninterrupted baseload output with lower carbon intensity than diesel backup.
- Maritime Propulsion Electrification:Fuel cell systems penetrate cargo vessel and ferry segments as the International Maritime Organization's carbon intensity regulations tighten.
- Tidal Channel Demonstration Scaling:Hydrokinetic technology advances from pilot to commercial phase in Scotland's Pentland Firth and Canada's Bay of Fundy.
Industry Challenges
- Specialized Technician Scarcity:Solid-oxide fuel cell installation and maintenance requires expertise in high-temperature electrochemistry and ceramic engineering that exceeds conventional HVAC technician training.
- Hybrid System Integration Complexity:Solar-plus-storage developers must synchronize DC-AC conversion, inverter controls, and battery management systems across multiple OEM platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Third Generation Energy Sources Market |
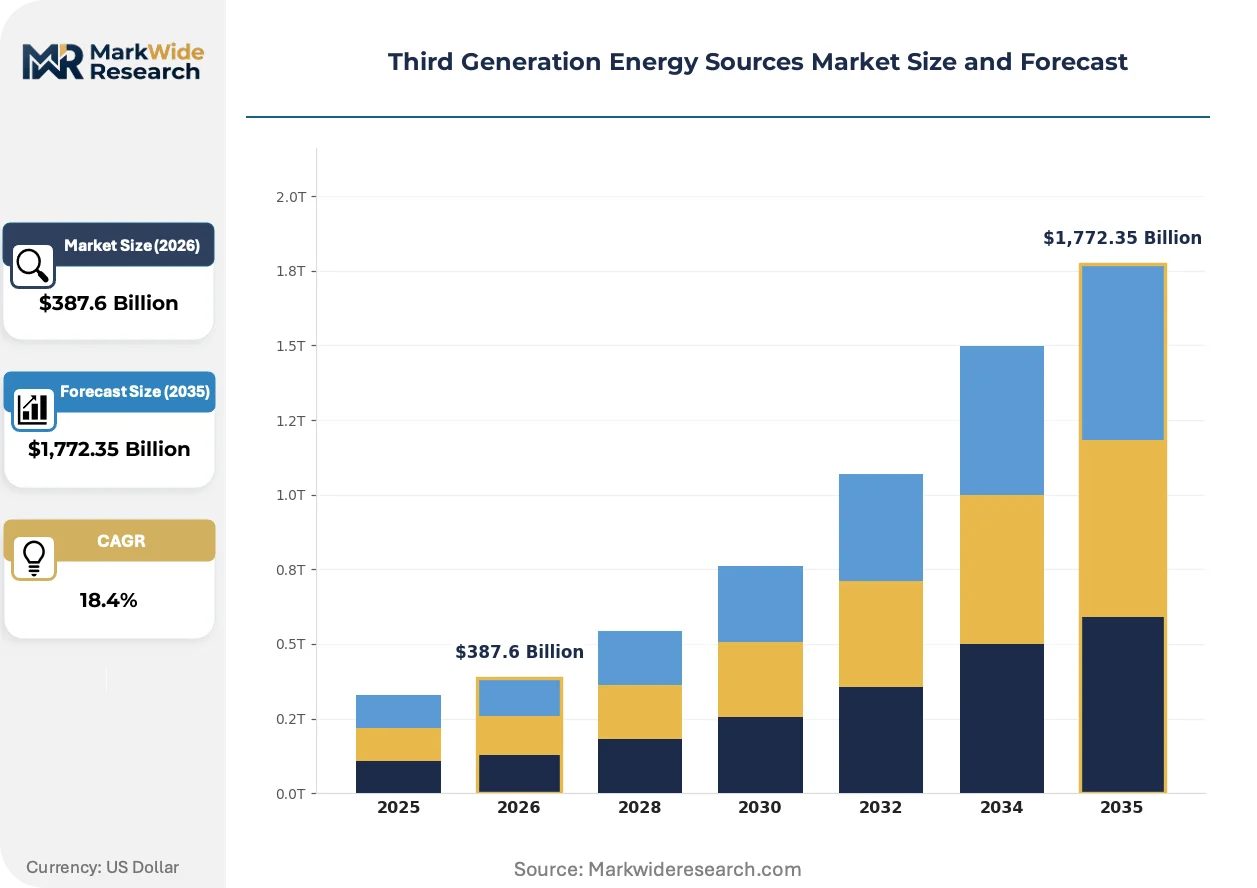
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,772.35 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solar Thermal, Geothermal, Ocean Thermal, Biomass Technology: Photovoltaics, Fuel Cells, Hydrokinetic, Terrestrial Heat Application: Power Generation, Heating, Desalination, Waste Treatment End User: Industrial, Residential, Commercial, Utility Providers |
| Companies Covered | Sungrow Power Supply, FuelCell Energy, NextEra Energy, Enlight Renewable Energy, Energy Vault Holdings, Brookfield Renewable Partners, Canadian Solar, Fluence Energy, First Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Third Generation Energy Sources Market Evolving Landscape
Technology convergence between electrochemical storage and thermal generation is compressing traditional equipment procurement categories, while regulatory pressure on carbon intensity accelerates displacement of conventional firming capacity.
Solid-oxide fuel cells operating at 800-1000°C are displacing diesel generators in mission-critical backup applications. Data center operators in Northern Virginia and Frankfurt now specify fuel cell systems for primary backup, drawn by continuous runtime and eliminated refueling logistics. This displacement compresses the addressable market for reciprocating engine manufacturers while expanding demand for hydrogen infrastructure.
The EPA's greenhouse gas standards for existing power plants create compliance pathways favoring geothermal retrofits at retiring coal stations. Developers in Wyoming and North Dakota pursue closed-loop binary systems using existing transmission infrastructure. Affected utilities respond by accelerating integrated resource plan proceedings to evaluate baseload replacement options.
Industrial offtakers now unbundle energy procurement from equipment ownership, contracting instead for heat-as-a-service or dispatchable capacity under long-term agreements. Chemical processors in Texas and refineries in Rotterdam lead this shift, transferring operational risk to specialized developers. This pattern is most visible in energy-intensive manufacturing clusters seeking to decarbonize without capital deployment.
Third Generation Energy Sources Market Segmentation
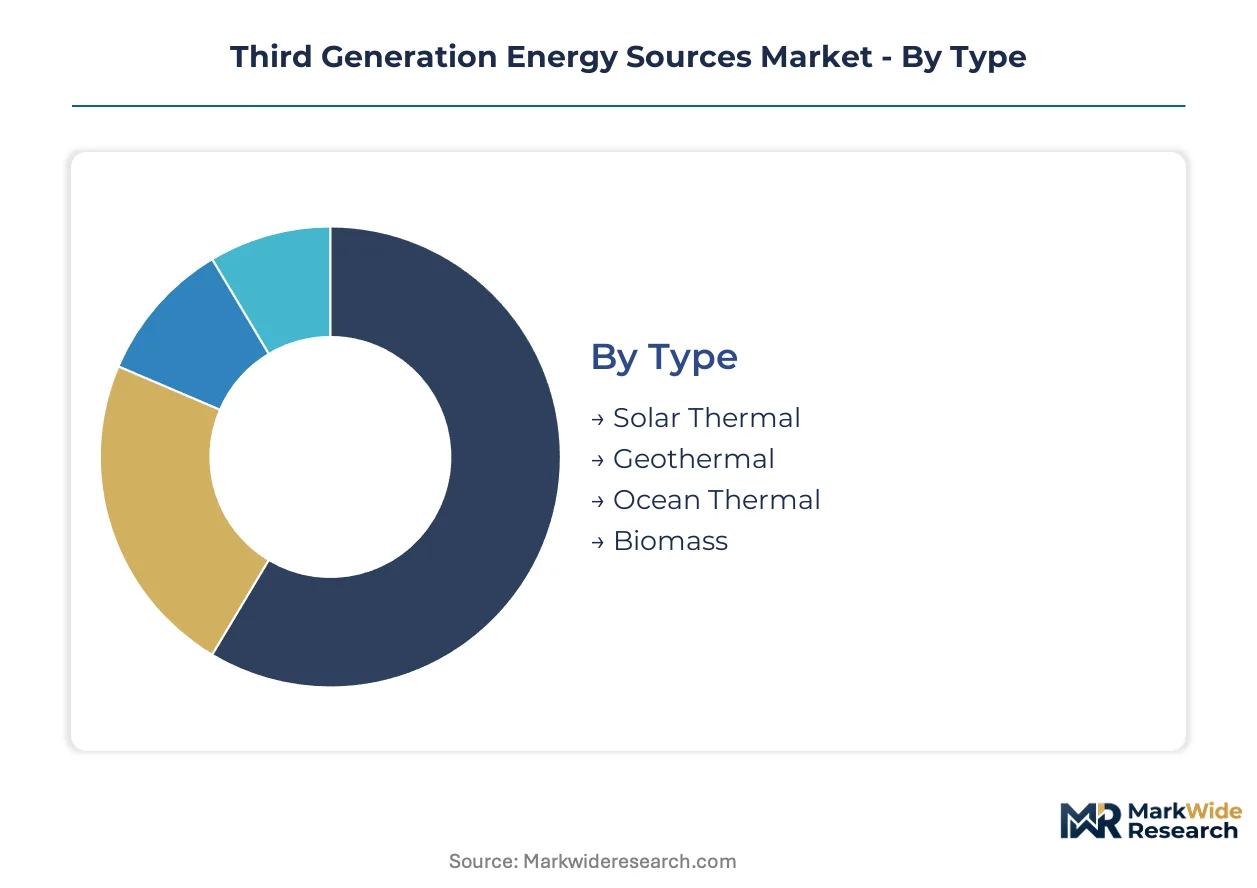
Technology heterogeneity across third generation energy sources creates distinct procurement channels and investment profiles. Each segment category routes through different customer decision-making structures and regulatory compliance pathways.
Type:
Channel configuration varies sharply by source maturity and project scale, with established technologies flowing through utility procurement desks while emerging categories require developer-direct engagement.
- Solar Thermal:Concentrating solar power systems with molten salt storage deliver dispatchable electricity through parabolic trough or power tower configurations. Procurement concentrates in southwestern United States utility integrated resource plans, where FERC Order 2023 streamlines interconnection timelines for hybrid configurations.
- Geothermal:Binary cycle plants using organic Rankine engines extract heat from moderate-temperature reservoirs without steam flashing. Expansion concentrates in Wyoming and North Dakota retrofit projects at retiring coal stations, leveraging existing transmission corridors and EPA compliance pathways.
- Ocean Thermal:Rankine cycle systems exploit temperature gradients between surface and deep seawater for baseload power generation. Demonstration activity clusters in Hawaii and tropical island territories seeking energy independence.
- Biomass:Anaerobic digestion and thermal gasification systems convert organic feedstocks to biogas or syngas for combined heat and power. Deployment faces permitting friction under EPA greenhouse gas standards for existing power plants.
Solar thermal dominates installed base. Geothermal is where expansion concentrates.
Technology:
Cost tier stratification separates mass-deployed silicon-based systems from premium electrochemical and kinetic technologies requiring specialized balance-of-plant engineering.
- Photovoltaics:Crystalline silicon and thin-film modules convert sunlight directly to electricity through semiconductor junctions. Utility-scale deployment in Australia pairs with co-located battery storage to displace legacy peaker plants and capture ancillary services revenue streams.
- Fuel Cells:Solid-oxide systems operating at 800-1000°C achieve high electrical efficiency through electrochemical oxidation without combustion. Data center operators in Northern Virginia and Frankfurt specify these for primary backup, eliminating diesel refueling logistics while meeting continuous runtime requirements.
- Hydrokinetic:Tidal and river current turbines extract kinetic energy without dam infrastructure or head differential. Commercialization advances in Scotland's Pentland Firth and Canada's Bay of Fundy demonstration zones.
- Terrestrial Heat:Ground-source heat pumps and direct-use systems leverage shallow geothermal gradients for building thermal loads. Residential and commercial deployment depends on drilling cost economics and subsurface characterization accuracy.
Photovoltaics commands volume leadership. Fuel cells capture premium pricing tiers.
Application:
Customer type determines contracting structure, with industrial offtakers favoring heat-as-a-service models while utilities pursue capital ownership of generation assets.
- Power Generation:Grid-connected electricity supply for utility portfolios or behind-the-meter industrial consumption. Texas chemical processors and Rotterdam refineries contract for dispatchable capacity under long-term agreements, transferring operational risk to specialized developers.
- Heating:Industrial process heat and district thermal networks replacing fossil combustion. German and Japanese industrial offtakers now mandate ISO 50001 energy management certification from suppliers, rotating procurement toward verified efficient operators.
- Desalination:Thermal or membrane processes powered by renewable heat or electricity for freshwater production. Island and coastal municipalities in water-stressed regions evaluate solar thermal coupling.
- Waste Treatment:Anaerobic digestion and thermal processing of organic residuals with energy recovery. Municipal and agricultural waste streams provide feedstock for biogas upgrading and power generation.
Power generation anchors revenue concentration. Heating applications are climbing the fastest as industrial decarbonization mandates tighten.
End User:
Volume distribution skews toward utility-scale procurement, though margin profiles favor specialized industrial applications with high reliability premiums.
- Industrial:Energy-intensive manufacturing, chemical processing, and refining operations requiring continuous thermal and electrical supply. These facilities unbundle equipment ownership in favor of contracted heat or capacity services.
- Residential:Distributed rooftop photovoltaics and ground-source heat pumps for single-family and multi-family buildings. Deployment scales with net metering policy stability and financing accessibility.
- Commercial:Office, retail, and institutional facilities with predictable load profiles suitable for on-site generation and demand management. Building-integrated photovoltaics and fuel cell backup systems penetrate this segment.
- Utility Providers:Centralized procurement of grid-scale capacity for portfolio diversification and regulatory compliance. Integrated resource plan proceedings in multiple jurisdictions evaluate baseload replacement options favoring geothermal and solar thermal with storage.
Utility providers drive procurement volume. Industrial end users generate premium margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers and industrial offtakers concentrate procurement across five national markets where regulatory frameworks and resource endowments align. Each jurisdiction presents distinct interconnection protocols, certification mandates, and site-specific deployment patterns.
United States
Utility-scale solar thermal procurement accelerates across Arizona and Nevada as FERC Order 2023 compresses interconnection study timelines for hybrid configurations. EPA greenhouse gas standards for existing power plants create compliance pathways favoring geothermal retrofits at retiring coal stations in Wyoming. Developers in the Southwest leverage streamlined permitting to advance dispatchable renewable capacity additions.
Australia
Grid-scale energy storage co-located with photovoltaics displaces legacy peaker plants in New South Wales and Queensland. The country's renewable energy target mechanisms and state-level integrated resource plans drive procurement timing. Developers capture ancillary services revenue streams through battery systems paired with utility-scale solar installations.
Germany
Industrial offtakers mandate ISO 50001 energy management certification from suppliers, rotating procurement toward verified efficient operators. The EU Green Deal implementation and national industrial decarbonization roadmaps tighten process heat requirements. Chemical processors in the Rhine-Ruhr cluster contract for heat-as-a-service rather than equipment ownership.
Japan
METI's hydrogen and fuel cell commercialization roadmap accelerates solid-oxide system deployment for industrial baseload applications. Manufacturing clusters in Osaka and Nagoya evaluate continuous power systems for semiconductor fabrication facilities. The country's feed-in tariff evolution shifts toward self-consumption and direct power purchase agreements.
China
Dual carbon goals and provincial renewable portfolio standards concentrate photovoltaics manufacturing in Jiangsu and Anhui. State-owned utilities pursue integrated solar-plus-storage projects under centralized procurement frameworks. The Yangtze River Delta hosts concentrated demonstration activity for next-generation electrochemical storage integration.
Third Generation Energy Sources Market Competitive Landscape
Player mix skews toward integrated utility developers and specialized storage technology firms with established equipment certification pathways. Market structure exhibits moderate consolidation around firms possessing captive project pipelines and long-term power purchase agreement origination capabilities. Three archetypes dominate: utility-scale developers with multi-continent pipelines, infrastructure owners with captive renewable assets, and integrated hardware-software platform specialists. Competitive dynamics center on pre-certified equipment package deployment and strategic partnerships for hybrid system integration.
Among North American integrated developers, NextEra Energy and Brookfield Renewable Partners exemplify the utility-scale pipeline archetype with established interconnection queue management capabilities. Fluence Energy occupies a position within the integrated platform tier, representing specialists in grid-connected storage system deployment. These three entities anchor competitive positioning across the project origination-to-energization value chain.
| Leading Market Players |
|---|
| Sungrow Power Supply |
| FuelCell Energy |
| NextEra Energy |
| Enlight Renewable Energy |
| Energy Vault Holdings |
| Brookfield Renewable Partners |
| Canadian Solar |
| Fluence Energy |
| First Solar |
| Others |
Value Network & Pricing Analysis
Utility-scale project origination at multi-gigawatt scale compresses balance-of-system costs through equipment package standardization, concentrating pricing power among developers with FERC pre-certified interconnection queues and established engineering-procurement-construction relationships.
Pricing Analysis
Cost-plus contracts with rare earth and lithium carbonate indexation dominate solid-oxide fuel cell and battery storage procurement. Price differentiation separates ISO 50001-certified operators from uncertified competitors and tracks project scale tiers from distributed commercial to utility-scale. Cost compression in photovoltaics modules intensifies as Chinese manufacturing capacity expands. Industrial offtakers in Germany and Japan show lowest price sensitivity due to carbon compliance mandates, while residential solar buyers exhibit highest elasticity.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes yttria-stabilized zirconia shipments from Chinese processing facilities to solid-oxide fuel cell manufacturers. Manufacturing concentrates in China for photovoltaics and battery cells, South Korea for fuel cell stacks, and Germany for inverter power electronics. Raw material dependencies include polysilicon, lithium hydroxide, and isobutane working fluids for binary geothermal plants. Tariff exposure on Chinese solar equipment creates procurement friction. Distribution runs through utility integrated resource plan proceedings and direct developer-offtaker power purchase agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third generation energy sources sit in early-cycle expansion as FERC Order 2023 and analogous regulatory streamlining across Australia and Germany accelerate project energization timelines beyond historical baselines.
For Market Incumbents: Consolidate interconnection queue positioning through pre-certified equipment packages and captive relationships with utility planning officers. Acquire specialized solid-oxide fuel cell maintenance capabilities to address technician scarcity threatening project uptime. Prioritize backward integration into rare earth processing to offset Chinese supply concentration.
For New Entrants and Emerging Players: Heat-as-a-service contracting gaps in Texas chemical processing and Rotterdam refining clusters offer white-space entry where incumbents under-serve. Target industrial decarbonization mandates in Germany's Rhine-Ruhr region as the most penetrable geography. Pursue direct power purchase agreement origination with data center operators seeking continuous baseload alternatives to diesel backup.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated hardware-software platform specialists with captive grid-connected storage deployment capabilities. Long-term viability hinges on hybrid system integration expertise spanning solar-plus-storage configurations. Monitor EPA compliance pathway clarity for existing power plants as the critical inflection signal for geothermal retrofit investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Origination | Long-term offtake contracts with utility integrated resource plans secure revenue visibility across FERC-jurisdictional projects. |
| Technology Licensing | Solid-oxide fuel cell stack designs licensed to maritime propulsion builders capture IMO carbon intensity compliance demand. |
| Backward Integration into Rare Earth Processing | In-house yttria-stabilized zirconia production insulates solid-oxide fuel cell manufacturing from Chinese supply volatility. |
| ISO 50001 Certification Program | Verified energy management credentials unlock German and Japanese industrial procurement mandates requiring supplier certification. |
| Joint Venture | Co-development partnerships with Australian grid operators accelerate solar-plus-storage deployment displacing legacy peaker plants. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, independent power producer project developers, EPC contractors, and grid operators and refined through secondary validation across EIA generation databases, IEA renewable energy reports, FERC interconnection filings, and project development tracking systems. Bottom-up capacity addition modeling triangulated against top-down market sizing across technology segments.
Variance decomposition across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type shaped analytical outputs over the projection horizon. CAGRs derived from equipment cost curve trajectories and policy-driven procurement acceleration patterns. Forecast inputs incorporated FERC Order 2023 implementation timelines and state-level renewable portfolio standard evolution.
Underlying assumptions cover continued rare earth processing concentration in China, with deviation risk concentrated in EPA greenhouse gas standard litigation outcomes and ISO 50001 certification adoption rates among industrial offtakers. Revision becomes warranted when FERC interconnection queue processing speed crosses thresholds materially above or below modeled baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Stirling Engine Market
Power Generation
Hydrogenerators Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Distributed Power Generation Market
Power Generation
Global Power Generation Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
India Thermal Power Plant Market
Power Generation
Industrial Solar Generator Market
Power Generation
Cogeneration System Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Residential Solar Generator Market
Power Generation
Subsea Power Grid System Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Tunisia Power Market
Power Generation
Vietnam Power Generation EPC Market