
 North America Disinfectants and Cleaning Agents Market | 2026-2036
North America Disinfectants and Cleaning Agents Market Size, Share, and Industry Trends Forecast 2026-2036
North America Disinfectants and Cleaning Agents Market Analysis
EPA Safer Choice certification and state-level green procurement mandates in California and New York is consolidating demand toward low-toxicity, biodegradable chemistries. Procter & Gamble leverages its retail distribution scale to dominate shelf presence across mass-market channels. Ecolab anchors its position through institutional service contracts that bundle chemicals with dispensing equipment and compliance training. Clorox Company differentiates via brand equity in healthcare-adjacent segments where efficacy claims carry liability weight.
Disinfectants and cleaning agents encompass formulated chemical solutions designed to eliminate pathogenic microorganisms or remove contaminants from surfaces, typically specifying EPA registration for efficacy claims against defined microbial classes and requiring precise active ingredient concentrations to achieve log-reduction targets. Their primary commercial purpose spans infection control in healthcare environments, food safety in processing facilities, and hygiene maintenance across institutional and residential settings. Surface cleaners and spray disinfectants capture mature volume pools where private-label competition compresses margins, while hydrogen peroxide-based formulations represent the fastest-expanding chemistry segment as end users pivot from quaternary ammonium compounds amid respiratory toxicity concerns. The food service application channel exhibits concentrated demand growth driven by FDA Food Code compliance requirements and post-pandemic operational hygiene audits.
EPA registration under FIFRA governs efficacy labeling and antimicrobial claims, while OSHA Bloodborne Pathogens Standard mandates disinfectant availability in occupational exposure settings, and state-level California Cleaning Product Right to Know Act imposes ingredient disclosure requirements that reshape formulation transparency. These regulatory layers elevate compliance costs for new market entrants while rewarding incumbents with established toxicology dossiers and state-level registration portfolios. Stakeholders must monitor emerging per- and polyfluoroalkyl substance restrictions that could force reformulation of surfactant packages across multiple product lines.
Market Dynamics
State-level green procurement mandates in California and New York are consolidating demand toward low-toxicity, biodegradable chemistries, forcing reformulation across legacy surfactant packages while elevating compliance costs for new entrants.
Growth Catalysts
- EPA Safer Choice certification:Federal procurement preference for certified products drives institutional buyers toward verified low-toxicity formulations. Hospital systems now embed this standard into vendor qualification protocols.
- Food service channel expansion:FDA Food Code compliance audits intensify post-pandemic, requiring documented sanitation protocols in commercial kitchens. Chain restaurants upgrade chemical dispensing infrastructure to pass operational hygiene inspections.
- Healthcare facility construction:New hospital builds and renovation cycles in the United States incorporate infection prevention infrastructure from design phase. This embeds long-term chemical service contracts into capital projects.
Market Restraints
- Active ingredient supply concentration:Quaternary ammonium compound precursors concentrate among specialty chemical producers in the US Gulf Coast. Any disruption to ethylene oxide derivatives tightens formulation availability.
- Per- and polyfluoroalkyl substance restrictions:Emerging state-level bans on PFAS in surfactant packages force reformulation of multiple product lines. Toxicology dossier rebuilding extends registration timelines by 18-24 months.
- Respiratory toxicity liability:Occupational exposure claims related to quaternary ammonium compounds drive insurance cost escalation. School districts and municipal purchasers now exclude these chemistries from bid specifications.
Strategic Opportunities
- Canadian provincial procurement alignment:Health Canada and PMRA harmonization with US EPA standards creates cross-border contract consolidation. Ontario and British Columbia health authorities seek vendors with dual-registration portfolios.
- Electrostatic sprayer convergence:Application equipment integration with hydrogen peroxide chemistries enables touchless disinfection protocols. Long-term care facilities adopt this pairing to reduce labor-intensive surface wiping.
- Mexican food processing modernization:FDA-equivalent COFEPRIS standards upgrade drives chemical sanitation investment in meat and produce packing. US-based suppliers with bilingual compliance documentation capture cross-border share.
Industry Challenges
- EPA FIFRA registration timeline compression:Emerging pathogen claims require expedited efficacy testing against SARS-CoV-2 variants and Candida auris. Laboratory capacity constraints delay product launch windows.
- Dispensing equipment interoperability:Proprietary dilution control systems from incumbent chemical suppliers lock out competing formulations. Third-party chemistries face retrofit cost barriers in institutional accounts.
- Workforce chemical handling certification:OSHA Hazard Communication Standard training requirements expand with each formulation class addition. Custodial staffing turnover forces repeated compliance investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Disinfectants and Cleaning Agents Market |
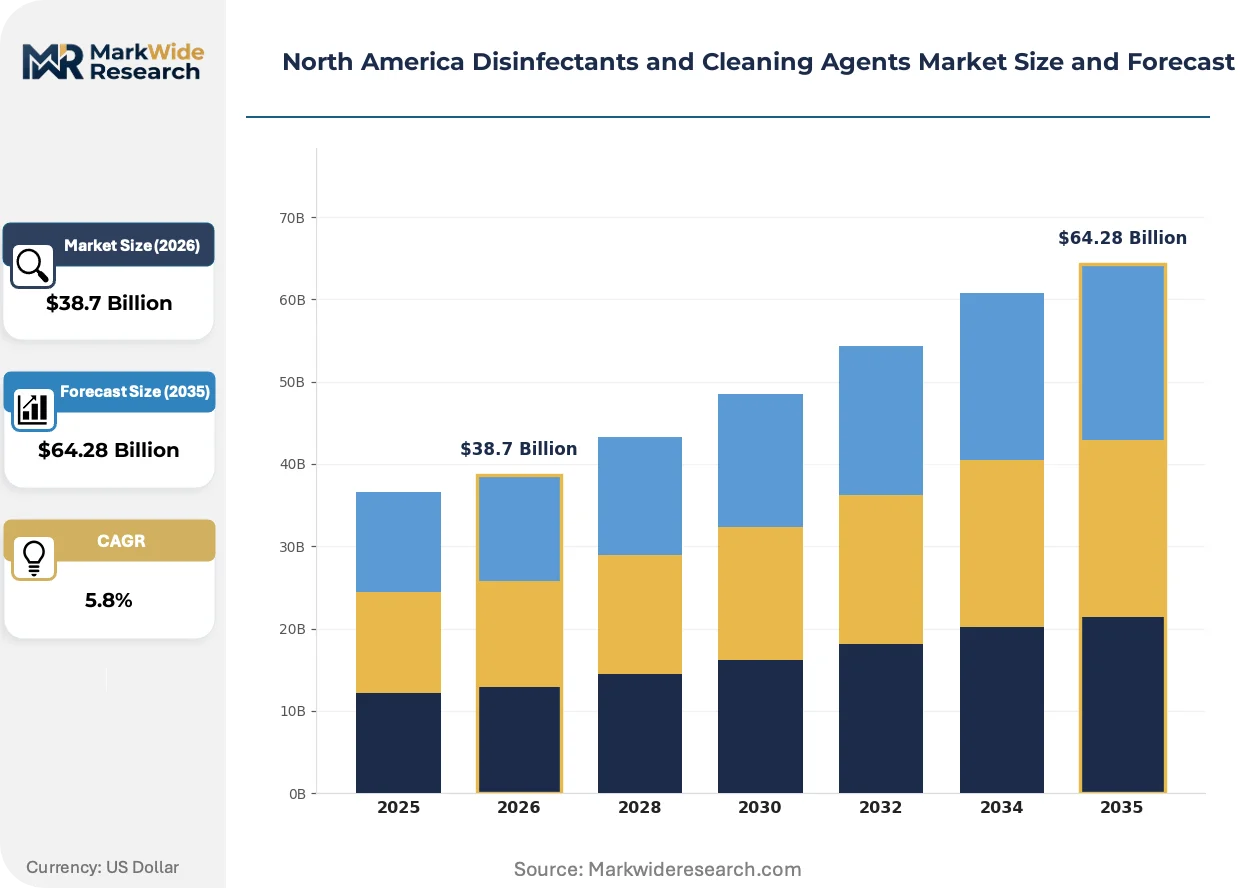
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Disinfecting Wipes, Spray Disinfectants, Hand Sanitizers Application: Household, Healthcare, Industrial, Food Service Formulation: Aqueous, Alcohol-Based, Hydrogen Peroxide-Based, Sodium Hypochlorite-Based End User: Residential, Hospitals, Educational Institutions, Commercial Facilities |
| Companies Covered | Procter & Gamble, Clorox Company, Reckitt Benckiser, SC Johnson, Ecolab, Church & Dwight, 3M, Diversey Holdings, Kimberly-Clark, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Disinfectants and Cleaning Agents Market Emerging Trajectories
Formulation chemistry is pivoting toward peroxide-based systems as end users reject legacy quaternary ammonium compounds. Equipment integration and regulatory disclosure mandates are accelerating product-service bundling.
Accelerated hydrogen peroxide technology is unifying disinfection and cleaning steps into single-application protocols. Hospital environmental services departments adopt these chemistries to reduce room-turnover labor. This convergence compresses SKU proliferation while raising performance liability stakes for efficacy claims.
California Cleaning Product Right to Know Act enforcement is forcing ingredient disclosure granularity that exceeds federal FIFRA labeling. Formulators must reconcile confidential business information protections with public database submission requirements. Private-label manufacturers serving California distribution channels face the steepest compliance adaptation costs.
Facility managers now bundle chemical supply with dispensing equipment service contracts rather than purchasing chemicals transactionally. This displaces traditional distribution relationships with multi-year performance agreements. The shift is most visible in US hospital systems consolidating vendor panels to reduce procurement administrative burden.
North America Disinfectants and Cleaning Agents Market Segmentation
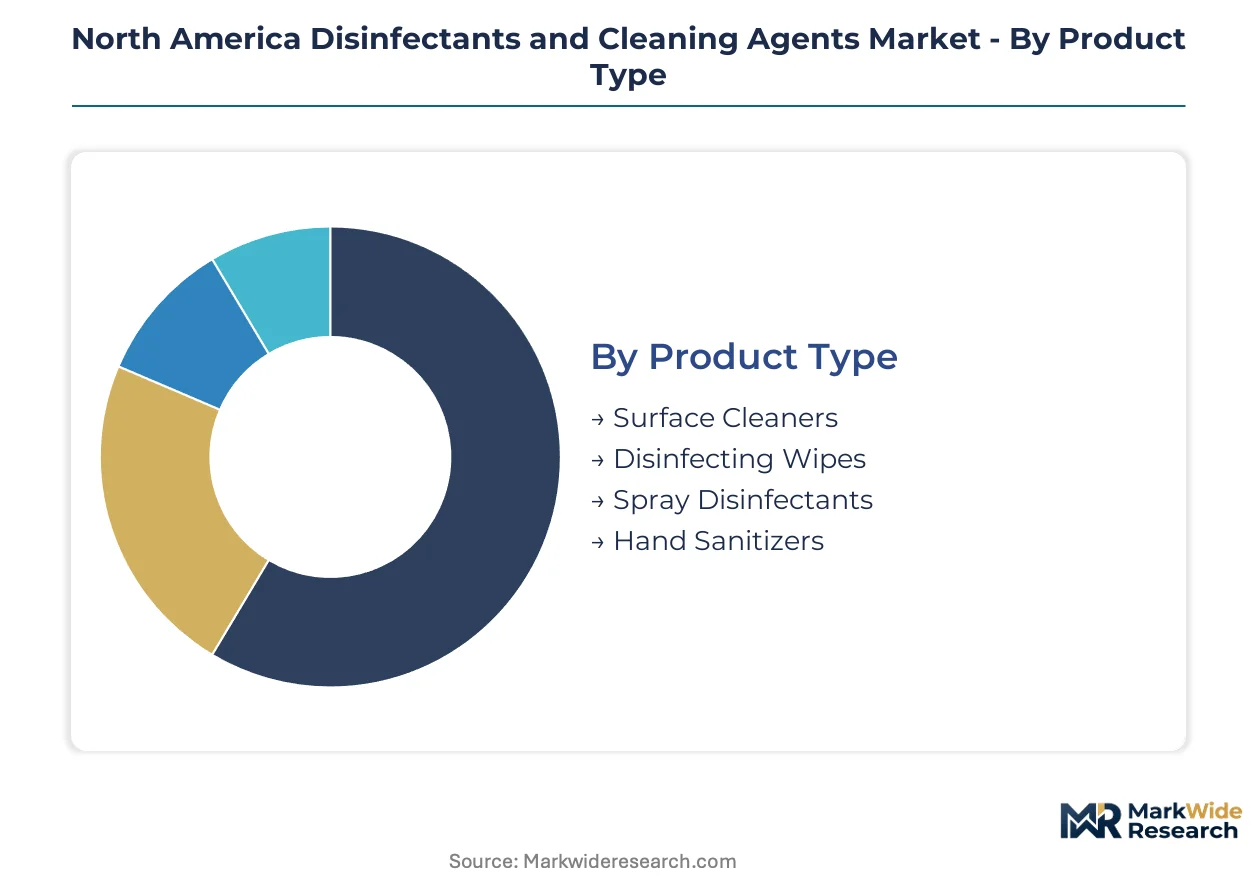
Segmentation in this market reveals how regulatory certification burdens and application-specific efficacy requirements fragment demand across distinct purchasing channels. Product positioning must align with EPA registration classes, OSHA exposure protocols, and state-level disclosure mandates that vary sharply by end-use environment.
Product Type:
EPA registration tiers and FIFRA labeling requirements create divergent compliance burdens across these categories, with healthcare-facing products demanding the most extensive toxicology dossiers.
- Surface Cleaners:Formulated solutions removing soil and organic matter without antimicrobial claims, avoiding EPA pesticide registration. Demand concentrates in commercial facilities across California and New York where green procurement mandates favor Safer Choice-certified formulations over conventional surfactant packages.
- Disinfecting Wipes:Saturated substrates carrying EPA-registered active ingredients at precise concentrations for log-reduction claims. Hospital systems in Texas and Florida embed these into infection prevention bundles, driving volume through group purchasing organization contracts that lock in multi-year supply agreements.
- Spray Disinfectants:Pressurized or trigger-dispersed formulations for broad-area application.
- Hand Sanitizers:Alcohol-based or benzalkonium chloride formulations for personal hygiene compliance.
Leading the category by volume: Surface Cleaners. Growing fastest: Disinfecting Wipes.
Application:
Customer procurement sophistication varies dramatically across these channels, from transactional retail purchasing to multi-year institutional service contracts with embedded compliance training.
- Healthcare:Acute care hospitals, outpatient clinics, and long-term care facilities requiring EPA-registered hospital-grade disinfectants against defined pathogen classes. Demand clusters in United States metropolitan hospital construction corridors where infection prevention infrastructure is specified at the design phase, embedding chemical service contracts into capital projects.
- Food Service:Commercial kitchens, chain restaurants, and food processing facilities governed by FDA Food Code sanitation protocols. Post-pandemic operational hygiene audits intensify chemical dispensing infrastructure upgrades, particularly in quick-service restaurant chains seeking documented compliance for franchise inspections.
- Household:Residential cleaning and disinfection for consumer retail channels.
- Industrial:Manufacturing facilities, warehouses, and logistics operations requiring heavy-duty cleaning protocols.
Highest margin concentration: Healthcare. Steepest expansion trajectory: Food Service.
Formulation:
Active ingredient selection determines regulatory pathway, occupational exposure liability, and compatibility with emerging application equipment.
- Hydrogen Peroxide-Based:Accelerated peroxide systems unifying cleaning and disinfection into single-application protocols with favorable respiratory toxicity profiles. Hospital environmental services departments in Illinois and Ohio adopt these chemistries to reduce room-turnover labor while avoiding quaternary ammonium compound liability exclusions in bid specifications.
- Alcohol-Based:Ethanol or isopropanol formulations rapid-acting against enveloped viruses with minimal residue. Hand hygiene compliance drives volume in educational institutions across Pennsylvania and Michigan where custodial staffing turnover forces repeated OSHA Hazard Communication Standard training investment.
- Aqueous:Water-based surfactant systems for general cleaning without antimicrobial claims.
- Sodium Hypochlorite-Based:Bleach-derived formulations for sporicidal efficacy in outbreak response scenarios.
Fastest chemistry pivot: Hydrogen Peroxide-Based. Largest installed base: Aqueous.
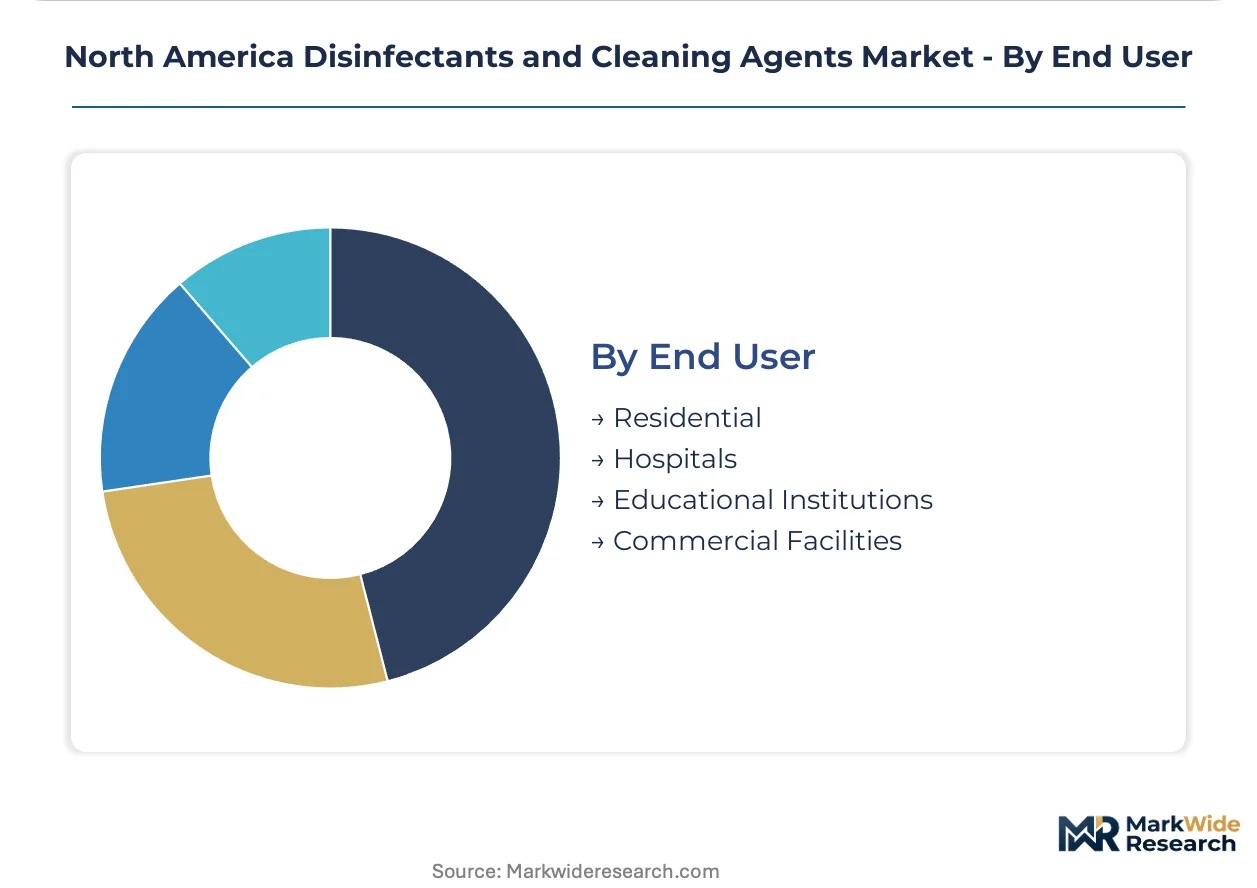
End User:
Purchasing authority and specification control vary from centralized procurement offices to decentralized facility management with divergent technical evaluation capacity.
- Hospitals:Integrated delivery networks and standalone acute care facilities with dedicated infection prevention committees. United States health systems in North Carolina and Arizona consolidate vendor panels to reduce procurement administrative burden, favoring suppliers bundling chemicals with dispensing equipment and compliance training.
- Commercial Facilities:Office buildings, hospitality properties, and retail establishments managed through facilities services contracts. Property management companies in Washington and Massachusetts increasingly specify electrostatic sprayer compatibility to enable touchless disinfection protocols and reduce labor-intensive surface wiping.
- Residential:Individual consumers purchasing through retail mass-market channels.
- Educational Institutions:K-12 districts and universities with custodial workforce training mandates.
Deepest contract integration: Hospitals. Most price-sensitive segment: Residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital construction corridors in Houston, Dallas, and Phoenix anchor chemical service contract demand across the southern United States. These metropolitan clusters concentrate infection prevention infrastructure investment and multi-year vendor consolidation.
United States
Healthcare facility construction in North Carolina and Arizona embeds long-term chemical service contracts into capital projects from the design phase. EPA Safer Choice certification now governs federal procurement preference, driving institutional buyers toward verified low-toxicity formulations. Hospital systems in Illinois and Ohio adopt accelerated hydrogen peroxide systems to reduce room-turnover labor while avoiding quaternary ammonium compound liability exclusions.
Canada
Health Canada and PMRA harmonization with US EPA standards enables cross-border contract consolidation for suppliers with dual-registration portfolios. Ontario and British Columbia health authorities actively seek vendors capable of serving both markets with unified compliance documentation. Toronto and Vancouver hospital procurement offices now specify bilingual safety data sheets as mandatory bid requirements.
Mexico
COFEPRIS standards upgrading toward FDA equivalence drives chemical sanitation investment in meat and produce packing facilities across Nuevo León and Jalisco. US-based suppliers with Spanish-language compliance documentation capture cross-border market share in these northern industrial states. Mexico City Metro food service chains accelerate dispensing infrastructure upgrades to pass post-pandemic operational hygiene audits.
California
The California Cleaning Product Right to Know Act imposes ingredient disclosure requirements that exceed federal FIFRA labeling granularity. Formulators must reconcile confidential business information protections with public database submission requirements. Los Angeles and San Francisco commercial facility managers specify Safer Choice-certified surface cleaners exclusively, displacing conventional surfactant packages from municipal procurement.
New York
State-level green procurement mandates consolidate demand toward low-toxicity, biodegradable chemistries across state agencies and public institutions. New York Metro hospital systems embed EPA Safer Choice standards into vendor qualification protocols. Buffalo and Rochester educational institutions exclude quaternary ammonium compounds from bid specifications following respiratory toxicity liability concerns.
North America Disinfectants and Cleaning Agents Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers and service bundling depth. Institutional contract vendors capture superior returns by embedding dispensing equipment and compliance training into multi-year agreements. Three archetypes dominate: retail mass-market suppliers leveraging shelf presence, institutional service contractors bundling chemicals with equipment, and specialty healthcare-focused formulators emphasizing efficacy liability protection. Dominant competitive moves include strategic partnerships for electrostatic sprayer compatibility and portfolio diversification into peroxide-based formulations.
Among US-based institutional contractors, Ecolab anchors the service-bundling archetype through its position in hospital environmental services. Procter & Gamble occupies the mass-market retail tier, while Clorox Company exemplifies the healthcare-adjacent specialist model where brand equity carries liability weight. These three entities represent distinct margin capture strategies across the market's vertical segments.
| Leading Market Players |
|---|
| Procter & Gamble |
| Clorox Company |
| Reckitt Benckiser |
| SC Johnson |
| Ecolab |
| Church & Dwight |
| 3M |
| Diversey Holdings |
| Kimberly-Clark |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap formulators in the US Gulf Coast anchor surfactant supply concentration, translating ethylene oxide derivative access into pricing discipline against private-label competitors lacking backward integration into active ingredient precursors.
Pricing Analysis
Outcome-based pricing tied to infection prevention audit pass rates anchors hospital system contracts, separating EPA-registered hospital-grade formulations from commodity surface cleaners. Certification tier and service bundling depth drive price differentiation, with Safer Choice-certified products commanding premiums in California and New York municipal procurement. Cost compression in quaternary ammonium compound segments is intensifying because school districts exclude these chemistries from bid specifications. Residential retail channels exhibit the highest price sensitivity, while integrated delivery networks show the least due to embedded compliance training requirements.
Supply Chain Analysis
Quaternary ammonium compound precursors rest on specialty chemical producers concentrated in the United States Gulf Coast, China, and Germany. Active ingredient dependencies include ethylene oxide derivatives, hydrogen peroxide feedstocks, and peracetic acid stabilizers. Single-source vulnerability in EPA-registered toxicology dossiers extends reformulation timelines when PFAS restrictions force surfactant package redesigns. Distribution runs through institutional service contractors bundling chemicals with dispensing equipment, displacing traditional wholesale relationships in hospital and food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accelerated hydrogen peroxide systems are displacing legacy quaternary ammonium compounds across healthcare and education procurement, compressing reformulation investment windows for suppliers anchored in chemistries facing respiratory toxicity liability exclusions.
For Market Incumbents: Extend EPA registration portfolios into peroxide-based formulations before state-level quaternary ammonium compound exclusions harden in bid specifications. Deepen backward integration into hydrogen peroxide feedstock supply through long-term offtake agreements with US Gulf Coast producers. Lock in multi-year service contracts with Ontario and British Columbia health authorities as Health Canada-PMRA harmonization creates cross-border consolidation opportunities.
For New Entrants and Emerging Players: Enter via electrostatic sprayer compatibility certification as a differentiated application equipment angle, targeting long-term care facilities in Illinois and Ohio seeking touchless disinfection protocols. Capture share in Mexican meat and produce packing facilities across Nuevo León and Jalisco by delivering bilingual COFEPRIS compliance documentation that US-based incumbents lack. Lead with documented room-turnover labor reduction claims to bypass entrenched chemical service relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor dual-registered specialists with Health Canada-PMRA and US EPA portfolios as cross-border contract consolidation accelerates. Long-term viability hinges on peroxide-based formulation capabilities and electrostatic application equipment integration. Watch SARS-CoV-2 variant and Candida auris efficacy claim expansion as inflection indicators for laboratory testing capacity constraints and expedited registration premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Peroxide-Based Formulation Pivot | Repositions suppliers away from quaternary ammonium compound liability exclusions in school district procurement. |
| Electrostatic Sprayer Compatibility Certification | Enables touchless disinfection protocol adoption in long-term care facilities seeking labor reduction. |
| Dual-Registration Portfolio Buildout | Captures Health Canada-PMRA and US EPA harmonization benefits in Ontario and British Columbia hospital systems. |
| Bilingual Compliance Documentation Investment | Opens COFEPRIS-aligned Mexican food processing modernization contracts in Nuevo León and Jalisco. |
| Safer Choice Certification Acceleration | Secures federal procurement preference and California-New York municipal contract eligibility. |
Methodological Framework
Document review covered EPA FIFRA registration databases, OSHA enforcement records, and state-level procurement mandate filings, complemented by interviews with hospital infection prevention directors, environmental services managers at integrated delivery networks, food safety officers at quick-service restaurant chains, chemical distribution channel partners, and EPA Safer Choice program administrators. Secondary validation drew from customs trade data, ACC industry reports, SEC 10-K chemical segment disclosures, and Health Canada PMRA registration tracking. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry and end-use application dimensions.
Segment-level value outputs derived from pricing stratification across certification tiers and service bundling depth, with hydrogen peroxide-based chemistry expansion rates and quaternary ammonium compound displacement trajectories informing the analytical framework across the projection horizon. Modeled dimensions included product type by EPA registration class, application channel by compliance protocol intensity, formulation chemistry by respiratory toxicity profile, and end user by procurement centralization level. CAGRs were derived from regression analysis of historical construction spending, regulatory mandate implementation timelines, and channel shift velocities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS surfactant restrictions or ethylene oxide supply disruptions. Projections reflect assumptions on Health Canada-PMRA harmonization pace, state-level green procurement mandate expansion, and hospital construction cycle continuity. A small set of triggers—emerging pathogen efficacy claim requirements, electrostatic equipment interoperability standards, and Mexican COFEPRIS upgrade velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
India Air Treatment Products Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
Antibacterial Products Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Sulfuryl Fluoride Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market