
 Global Fumigation Products Market | 2026-2036
Global Fumigation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fumigation Products Market Foresight
Modular pellet-and-sachet bundling is expanding as the dominant packaging configuration, letting pest control operators scale treatments from single shipping containers to full warehouse floors without switching chemistries. Solvay leverages its integrated phosphine supply chain to dominate European grain-storage contracts. FMC Corporation anchors North American structural pest control through captive production of sulfuryl fluoride precursors. Detia Degesch GmbH specializes in precision-dose aluminum phosphide formulations for quarantine-compliant agricultural exports.
Fumigation products are biocidal formulations—typically aluminum or magnesium phosphide solids, sulfuryl fluoride gas, or chloropicrin liquids—delivered at controlled concentrations measured in grams per cubic meter to eliminate arthropod, nematode, or microbial infestations in enclosed spaces. Their primary purpose is to secure commodity integrity across post-harvest supply chains and cross-border trade flows. Phosphine gas retains the largest volume share in grain protection, though methyl bromide phase-out under the Montreal Protocol is displacing volume toward sulfuryl fluoride in quarantine compliance applications. Pest control operators represent the fastest-growing end-user channel as outsourced sanitation contracts replace in-house treatment teams at food processing plants.
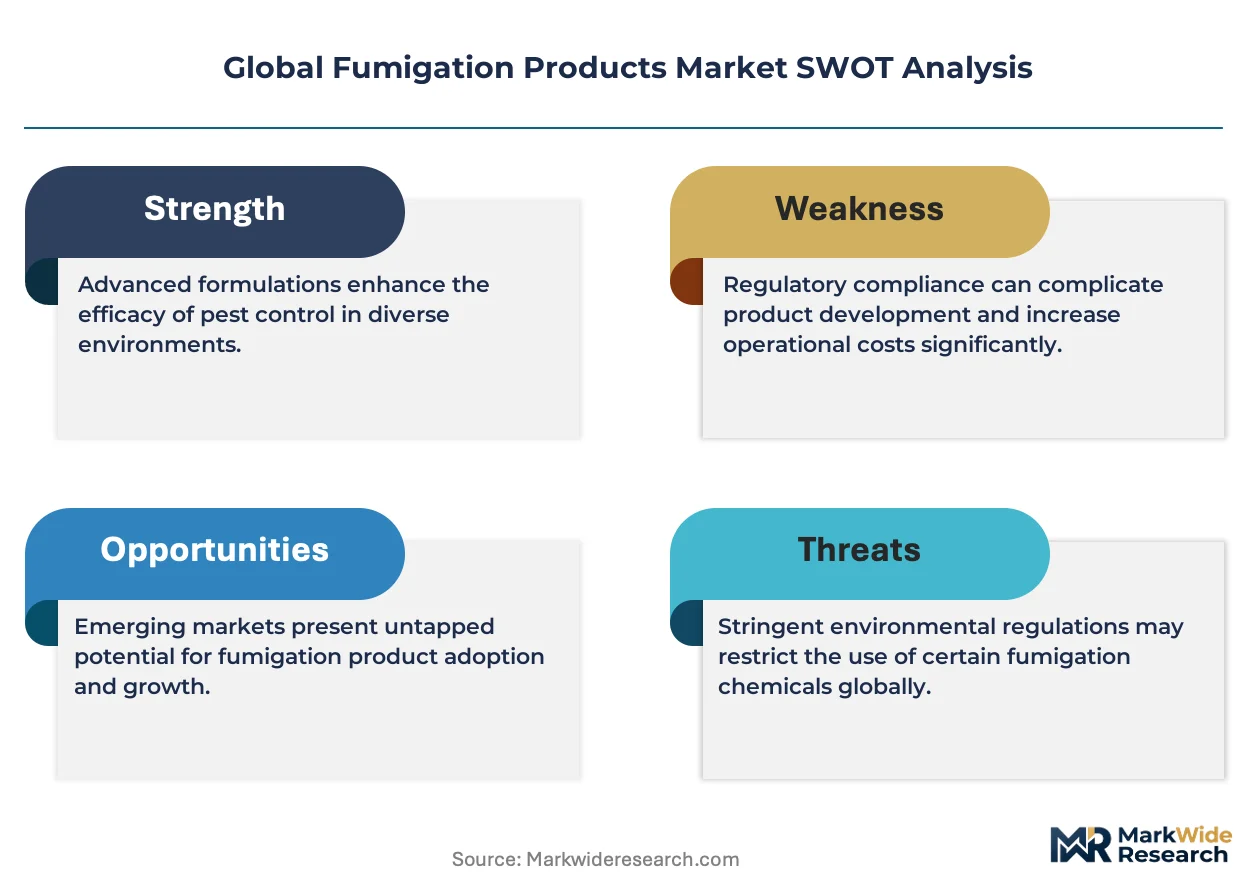
The EPA governs restricted-use classifications and applicator certification for phosphine and sulfuryl fluoride in the United States, while ECHA's REACH framework governs active substance approval and residue limit harmonization across EU member states. India's CEA enforces phosphine tablet purity standards under the Insecticides Act, directly conditioning import eligibility for warehousing equipment. Stakeholders must monitor regulatory divergence between F-Gas phase-down schedules in Europe and emerging residue tolerance harmonization in ASEAN trade corridors.
Market Dynamics
Phosphine-resistant insect strains are forcing warehouse operators across Southeast Asia to escalate dosage precision and rotate chemistries, compressing margins for commodity treatment providers while accelerating substitution toward sulfuryl fluoride in premium export corridors.
Growth Catalysts
- Montreal Protocol phase-out schedules:Methyl bromide restrictions under ozone-depleting substance frameworks are redirecting quarantine compliance volume toward sulfuryl fluoride alternatives in cross-border agricultural trade.
- India's export-mandated residue standards:CEA-enforced phosphine tablet purity requirements under the Insecticides Act are tightening compliance thresholds for rice and wheat shipments, expanding certified treatment service demand.
- Modular pellet-sachet packaging:Scalable dosing configurations allow pest control operators to deploy identical chemistries across single containers and full warehouse floors without equipment swaps.
Market Restraints
- Aluminum phosphide supply concentration:Captive production of phosphine precursors concentrates among integrated chemical conglomerates, exposing buyers to allocation risk during feedstock disruptions.
- F-Gas Regulation phase-down friction:EU-mandated hydrofluorocarbon restrictions are compressing sulfuryl fluoride availability windows for container fumigation, forcing chemistry switches mid-contract.
- High-purity gas handling infrastructure:Sulfuryl fluoride deployment requires specialized pressurized application equipment, elevating capital barriers for smaller pest control operators.
Strategic Opportunities
- ASEAN residue tolerance harmonization:Emerging mutual recognition agreements between Thailand, Vietnam, and Indonesia are creating unified treatment certification pathways for regional grain traders.
- IoT-enabled concentration monitoring:Wireless gas sensors integrated with phosphine release systems are enabling real-time dosage verification for quarantine-inspected shipments.
- Food processing plant outsourcing:Third-party sanitation contracts are displacing in-house treatment teams, expanding addressable market for certified applicator networks.
Industry Challenges
- Certified applicator pipeline constraints:EPA-mandated restricted-use licensing requirements for phosphine and sulfuryl fluoride are lengthening workforce onboarding timelines across North American operations.
- Cross-regulatory compliance complexity:Divergent residue limit frameworks between ECHA's REACH harmonization and India's CEA enforcement are forcing multi-jurisdictional exporters to maintain parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fumigation Products Market |
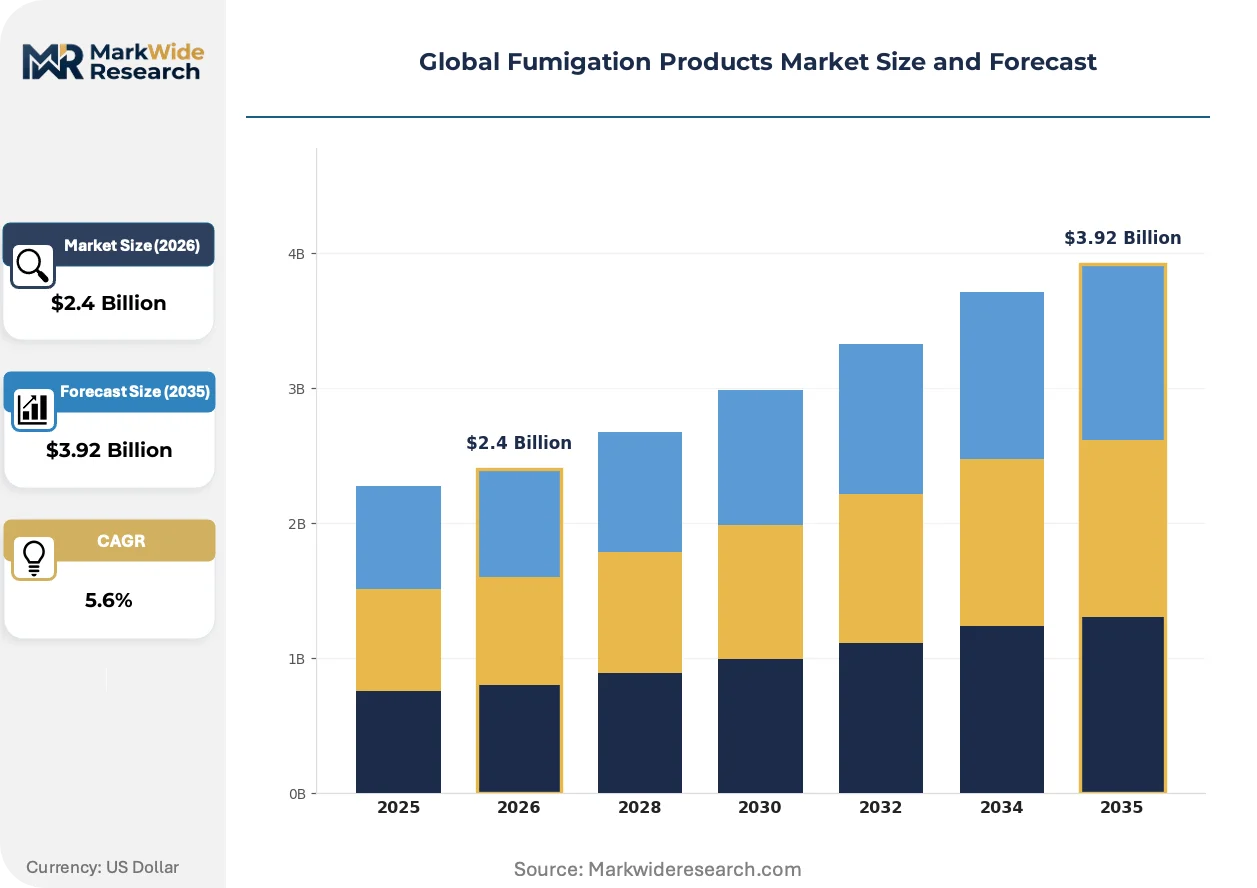
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphine Gas, Sulfuryl Fluoride, Methyl Bromide, Chloropicrin, Carbon Tetrachloride, Others Application: Grain Protection, Storage Facilities, Shipping Containers, Soil Treatment, Structural Pest Control, Quarantine Compliance End User: Food Processing Plants, Warehousing Facilities, Agricultural Farms, Shipping Companies, Government Agencies, Pest Control Operators Packaging Type: Pressurized Cylinders, Bulk Containers, Sachets, Liquid Bottles, Pellet Packs, Cartridge Bags |
| Companies Covered | Solvay, Draslovka Services Group, AMVAC Chemical Corporation, FMC Corporation, UPL Limited, Detia Degesch GmbH, LANXESS AG, Nufarm Limited, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fumigation Products Market Shifts & Advancements
Electrochemical phosphine generation from solid precursors is reshaping dosing precision, while regulatory chemistry rotations and procurement centralization are compressing traditional service models. Three developments are restructuring competitive requirements.
Electrochemical on-site phosphine generators are electrifying warehouse treatment protocols by eliminating cylinder logistics and enabling gram-level concentration control. Large grain cooperatives in Australia and Argentina are deploying these systems for export-certification compliance. The technology is electrifying competitive positioning by shifting value capture from chemical supply toward equipment-plus-service contracts.
The EU's F-Gas Regulation is accelerating sulfuryl fluoride substitution in container fumigation by restricting hydrofluorocarbon availability quotas. Maritime logistics providers are renegotiating multi-year chemistry supply agreements to secure alternative gas allocations. Container lines operating Rotterdam-to-Singapore corridors face the most acute reformulation timelines.
Centralized procurement by multinational grain traders is consolidating vendor relationships around integrated service providers capable of cross-border compliance documentation. Regional pest control cooperatives are losing share to certified applicator networks with multi-jurisdictional licensing. This concentration is most visible in India's agricultural belt, where government-mandated export standards are favoring larger operators with in-house laboratory verification.
Global Fumigation Products Market Segmentation
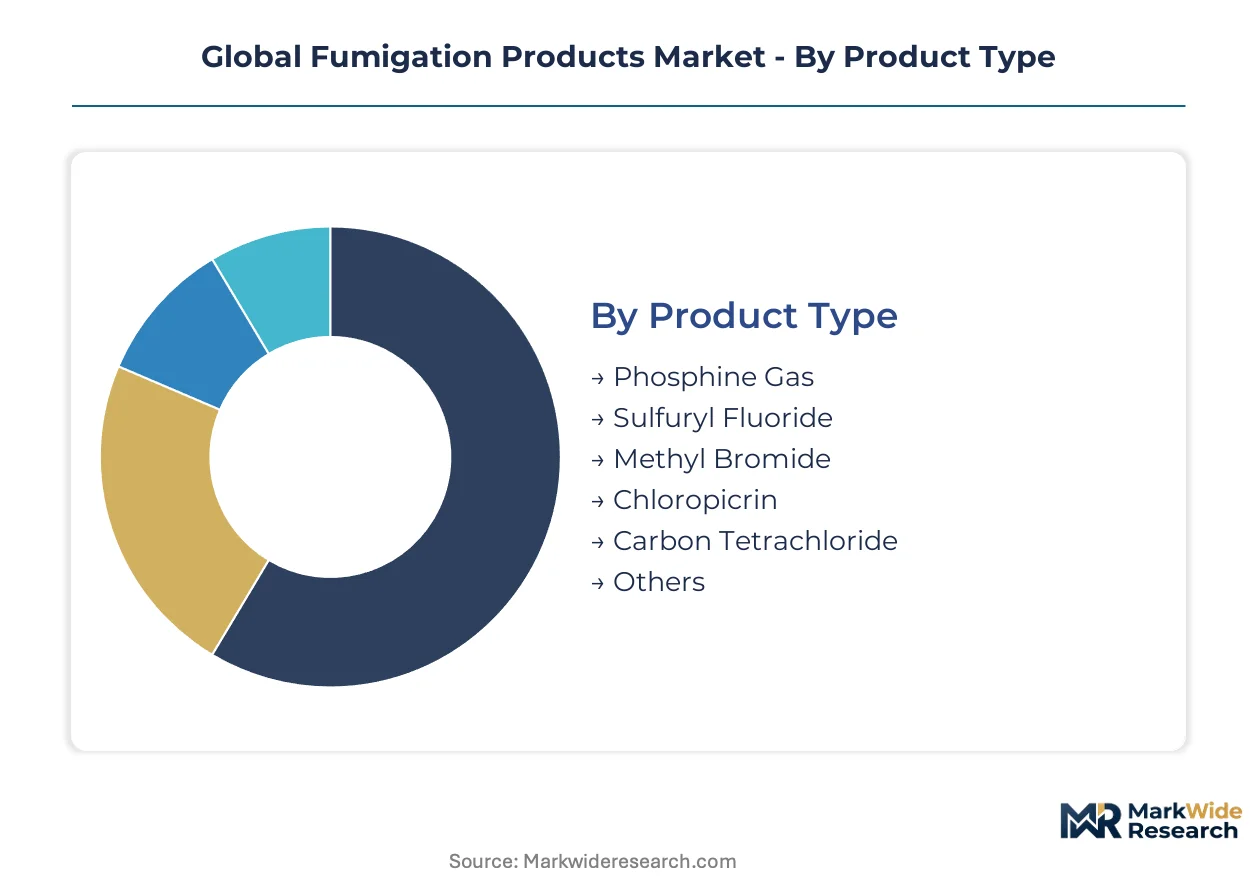
Segmentation in fumigation products determines chemistry selection, regulatory compliance pathways, and capital intensity requirements across divergent treatment scenarios. Buyers prioritize residue tolerance thresholds, applicator certification compatibility, and scalability from single-container to warehouse-scale deployment.
Product Type:
Buyers select chemistries based on target pest spectrum, commodity sensitivity, and regulatory phase-out timelines affecting availability windows.
- Phosphine Gas:Generated from aluminum or magnesium phosphide solids, this chemistry penetrates bulk grain masses through slow-release reactions with atmospheric moisture. Demand concentrates in India's agricultural belt, where CEA-enforced tablet purity standards under the Insecticides Act mandate certified formulations for rice and wheat export eligibility.
- Sulfuryl Fluoride:A colorless, odorless gas deployed at precise concentrations for structural and container fumigation, sulfuryl fluoride leaves no surface residue post-aeration. Volume is accelerating in EU container corridors as the F-Gas Regulation compresses hydrofluorocarbon quotas and forces chemistry substitution away from methyl bromide alternatives.
- Methyl Bromide:Ozone-depleting properties subject this chemistry to Montreal Protocol phase-down schedules, restricting use to critical quarantine exemptions only.
- Chloropicrin:A liquid warning agent often combined with other fumigants, chloropicrin serves soil treatment applications requiring nematode suppression.
- Carbon Tetrachloride:Legacy formulations retain niche usage in specific industrial sterilization protocols with restricted applicator licensing.
- Others:Emerging biofumigants and phosphine synergists address resistant insect strains through novel mode-of-action combinations.
Volume sits with phosphine gas; growth tilts toward sulfuryl fluoride.
Application:
Application scope dictates equipment capital requirements, treatment duration protocols, and documentation standards for cross-border certification.
- Grain Protection:Post-harvest storage treatments protect cereal commodities from Sitophilus and Tribolium infestations during extended holding periods. Australia's grain cooperatives deploy electrochemical phosphine generators for export-certification compliance, eliminating cylinder logistics while enabling gram-level concentration precision.
- Storage Facilities:Warehouse-scale fumigation requires sealed-structure integrity and aeration infrastructure for worker safety post-treatment. Southeast Asian operators face margin compression as phosphine-resistant strains force dosage escalation and chemistry rotation.
- Shipping Containers:Maritime logistics providers renegotiate multi-year supply agreements as EU F-Gas restrictions accelerate sulfuryl fluoride adoption in Rotterdam-to-Singapore corridors.
- Soil Treatment:Pre-planting fumigation suppresses nematode and fungal pathogens in high-value horticultural production systems.
- Structural Pest Control:Building envelope treatments target drywood termites and stored-product pests in residential and commercial properties.
- Quarantine Compliance:Phytosanitary certification requirements drive treatment documentation for cross-border agricultural trade flows.
Grain protection commands the largest treatment volume; container fumigation exhibits the steepest expansion trajectory as trade corridor regulations tighten.
End User:
End-user category determines procurement centralization, in-house versus outsourced treatment capabilities, and regulatory liability exposure.
- Food Processing Plants:Third-party sanitation contracts are displacing in-house treatment teams, expanding addressable market for certified applicator networks with multi-jurisdictional licensing.
- Warehousing Facilities:Grain storage operators across Southeast Asia expand phosphine-based protocols while managing resistant strain pressures through precision dosing.
- Agricultural Farms:On-farm treatment capacity remains limited by applicator certification barriers and capital constraints for pressurized gas handling infrastructure.
- Shipping Companies:Container lines face acute reformulation timelines as F-Gas phase-downs restrict sulfuryl fluoride availability windows mid-contract.
- Government Agencies:National plant protection organizations enforce quarantine compliance standards and treatment certification reciprocity agreements.
- Pest Control Operators:EPA-mandated restricted-use licensing requirements for phosphine and sulfuryl fluoride lengthen workforce onboarding timelines across North American operations.
Warehousing facilities generate the highest treatment frequency; pest control operators are climbing the fastest as outsourcing displaces internal sanitation teams.
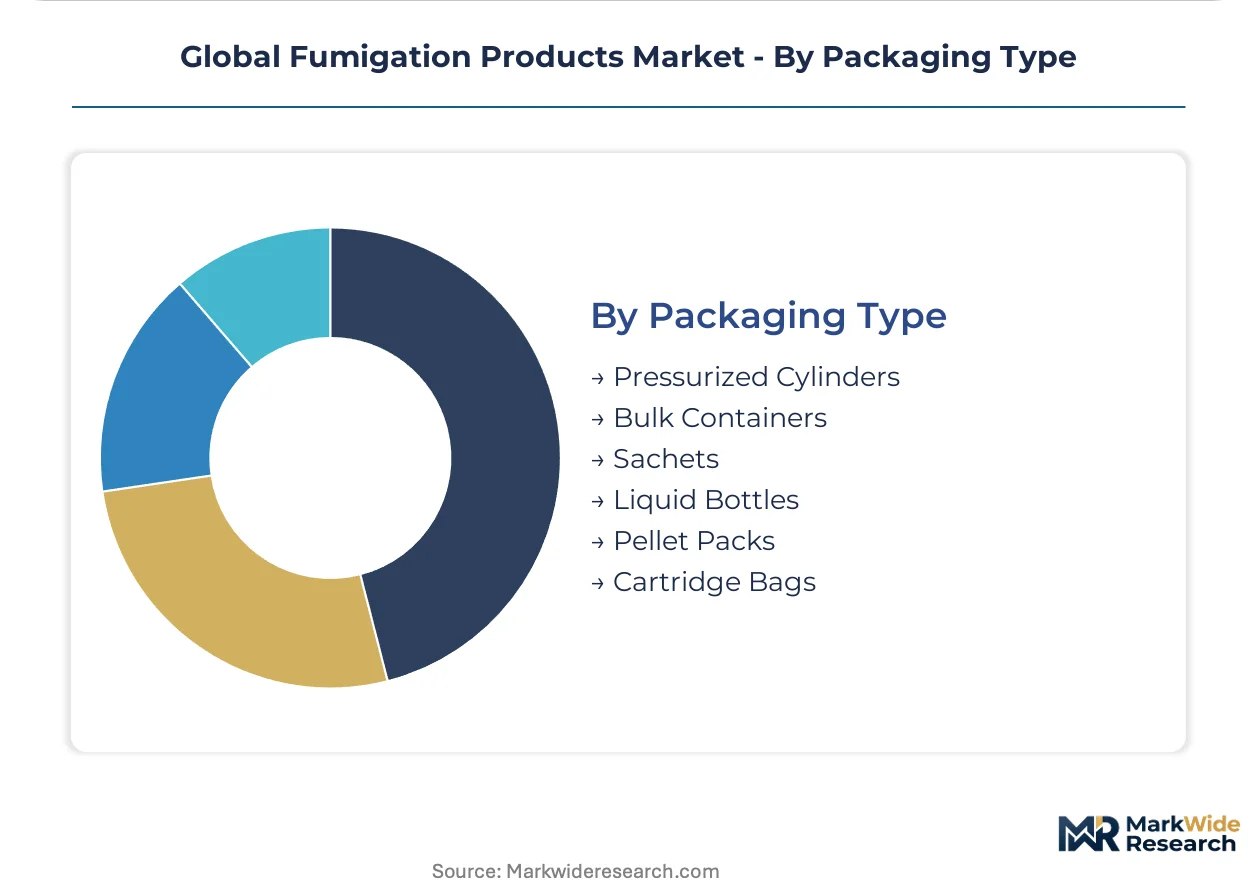
Packaging Type:
Packaging configuration determines dosing scalability, field handling safety, and compatibility with automated release systems.
- Pressurized Cylinders:Sulfuryl fluoride deployment requires specialized pressurized application equipment, elevating capital barriers for smaller operators.
- Bulk Containers:Large-scale phosphine precursor storage serves centralized treatment facilities with high-throughput grain handling capacity.
- Sachets:Modular pellet-and-sachet bundling enables pest control operators to scale treatments from single containers to full warehouse floors without switching chemistries.
- Liquid Bottles:Chloropicrin and warning agent formulations utilize standard chemical handling protocols with lower infrastructure requirements.
- Pellet Packs:Aluminum phosphide pellets deliver controlled phosphine release through moisture-activated reactions in enclosed storage environments.
- Cartridge Bags:Pre-measured cartridge configurations simplify applicator dosing precision for quarantine-inspected shipments.
Sachet configurations are gaining share fastest through modular scalability; bulk containers retain volume concentration in large cooperative storage systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's agricultural belt concentrates treatment demand through government-mandated export standards, while Rotterdam and Singapore anchor maritime logistics corridors facing acute chemistry reformulation timelines.
United States
Structural pest control contracts drive sulfuryl fluoride consumption across residential and commercial building envelopes. The EPA's restricted-use applicator certification requirements lengthen workforce onboarding timelines for phosphine deployment. California's Central Valley grain cooperatives face compliance pressure from state-level residue monitoring protocols.
Germany
Container fumigation operators along the Hamburg-Rotterdam corridor accelerate sulfuryl fluoride substitution as the EU F-Gas Regulation compresses hydrofluorocarbon availability quotas. ECHA's REACH framework governs active substance approval harmonization across member states. The Port of Hamburg serves as the primary logistics hub for chemistry reallocation negotiations.
India
Government-mandated phosphine tablet purity standards under the Insecticides Act tighten residue compliance thresholds for rice and wheat export eligibility. The CEA enforces warehousing equipment import conditioning through certified treatment service requirements. Punjab and Haryana's grain storage cooperatives expand precision-dose aluminum phosphide protocols.
Australia
Large grain cooperatives deploy electrochemical phosphine generators for export-certification compliance, eliminating cylinder logistics while enabling gram-level concentration control. The country's national plant protection organization enforces quarantine treatment documentation reciprocity with ASEAN trade partners. Queensland and New South Wales storage facilities lead generator adoption rates.
Singapore
Maritime logistics providers renegotiate multi-year chemistry supply agreements as F-Gas phase-downs restrict sulfuryl fluoride availability windows mid-contract. The port authority coordinates regional residue tolerance harmonization between Thailand, Vietnam, and Indonesia. Container lines operating Rotterdam-to-Singapore corridors face the most acute reformulation deadlines.
Global Fumigation Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across chemistry supply and equipment-plus-service contract models. Market structure tilts toward consolidation as centralized procurement by multinational grain traders favors integrated providers with cross-border compliance documentation capabilities. Three archetypes dominate: integrated chemical conglomerates with captive phosphine precursor production, precision-dose formulation specialists serving quarantine-compliant agricultural exports, and equipment-plus-service integrators deploying electrochemical generation systems. Competitive moves concentrate on backward integration into phosphine precursor supply and multi-jurisdictional licensing expansion for certified applicator networks.
Among European integrated chemical conglomerates, Solvay anchors grain-storage contract concentration through supply chain control, while LANXESS AG occupies a position within the specialty chemicals tier. FMC Corporation represents North American structural pest control anchoring through precursor production capabilities. Detia Degesch GmbH exemplifies the precision-dose formulation specialist archetype serving agricultural export corridors.
| Leading Market Players |
|---|
| Solvay |
| Draslovka Services Group |
| AMVAC Chemical Corporation |
| FMC Corporation |
| UPL Limited |
| Detia Degesch GmbH |
| LANXESS AG |
| Nufarm Limited |
| Arkema |
| Others |
Supply & Pricing Matrix
Electrochemical phosphine generation systems are compressing cylinder logistics costs while concentrating value capture among equipment-plus-service integrators with captive precursor supply. This production-method transition simultaneously reduces per-treatment variable costs and elevates capital barriers for smaller pest control operators.
Pricing Analysis
Premium pricing for short lead-time phosphine tablet deliveries commands substantial markups over spot inventory purchases from regional distributors. Three-tier pricing structure across certified-purity, standard-grade, and unbranded tablet tiers reflects CEA-enforced purity standards under India's Insecticides Act. Cost compression in standard-grade phosphine is intensifying because Southeast Asian warehouse operators face margin pressure from resistant-strain dosage escalation. Smallholder grain cooperatives exhibit highest price sensitivity; multinational grain traders with centralized procurement show lowest sensitivity due to volume-scale leverage.
Supply Chain Analysis
Single-source vulnerability sits with Chinese aluminum phosphide precursor production, which feeds formulation plants in Germany, India, and the United States. The supply chain draws from yellow phosphorus feedstock, specialized metal phosphide reactors, and pressurized gas handling equipment. Tariff exposure on Chinese inorganic chemical exports threatens cost stability for European and North American formulators. Distribution runs through certified applicator networks with EPA or ECHA-recognized licensing, bypassing traditional agricultural chemical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where India's CEA-enforced tablet purity standards create a regulatory moat favoring operators with in-house laboratory verification capabilities.
For Market Incumbents: Deploy backward integration into phosphine precursor production to secure allocation priority during feedstock disruptions. Expand multi-jurisdictional licensing coverage across ASEAN trade corridors before residue tolerance harmonization consolidates vendor relationships. Defensive moves must counter sulfuryl fluoride substitution pressure from EU F-Gas phase-downs and electrochemical generator displacement of traditional tablet applications. For New Entrants and Emerging Players: Pest control operator networks represent the most penetrable channel archetype, particularly in North American food processing plant outsourcing contracts. White-space targets include IoT-enabled concentration monitoring services and electrochemical generator leasing models for mid-size grain cooperatives. A go-to-market angle anchored to real-time quarantine documentation compliance bypasses incumbent chemical supply relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking captive phosphine supply and certified applicator network density. Long-term viability favors precision-dose formulation specialists with quarantine-compliant agricultural export positioning. The signal to watch is electrochemical generator adoption rates among Australian and Argentine grain cooperatives as inflection indicator for equipment-plus-service contract model displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive aluminum phosphide production secures allocation priority during Chinese feedstock disruptions. |
| Multi-Jurisdictional Licensing Expansion | CEA, EPA, and ECHA certifications enable unified service contracts across India, US, and EU grain export corridors. |
| Electrochemical Generator Deployment | On-site phosphine generation eliminates cylinder logistics while shifting revenue to equipment-plus-service contracts. |
| IoT-Enabled Concentration Monitoring | Wireless gas sensors integrated with release systems enable real-time dosage verification for quarantine inspections. |
| ASEAN Certification Reciprocity Partnerships | Mutual recognition agreements between Thailand, Vietnam, and Indonesia create unified treatment pathways. |
Research Methodology
Independent corroboration across plant protection officers at grain cooperatives, procurement leads at maritime logistics providers, and regulatory affairs specialists at phosphine formulators underwrites the qualitative findings. Primary interviews with EPA-certified applicators, ECHA registration consultants, and CEA enforcement officials combined with secondary validation from customs trade data, Insecticides Act compliance records, and Montreal Protocol phase-out schedules. Bottom-up treatment volume estimates triangulated against top-down chemical precursor consumption figures.
Historical reference periods spanning pre- and post-methyl bromide phase-out milestones anchored the forecast window to chemistry substitution trajectories. The analytical framework models product type, application scope, end-user category, and packaging configuration dimensions across the projection horizon. CAGRs derived from segment-level growth rate synthesis incorporating regulatory phase-down schedules, resistant-strain prevalence patterns, and electrochemical generator adoption curves.
Caveats apply where Montreal Protocol exemption renewals, F-Gas quota reallocations, or phosphine-resistant strain mutations could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and chemistry substitution timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Surface Disinfectant Chemicals Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Aerosol Disinfectants Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Pyrethroids Market