
 Global Potassium Sorbate Market | 2026-2036
Global Potassium Sorbate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Potassium Sorbate Market Outlook
Market Context with Strategic Players
Chinese sorbate production capacity is consolidating around Shandong province's chemical manufacturing belt. Shandong Kunda Biotechnology Co., Ltd. leverages integrated fermentation-to-crystallization operations to control input costs across the potassium sorbate value chain. Merck sustains premium positioning through pharmaceutical-grade certification that commands higher unit economics in regulated end markets. Celanese Corporation anchors North American supply security with distribution infrastructure serving beverage and baked goods manufacturers.
Technical Definition and Structural Segments
Potassium sorbate is the potassium salt of sorbic acid, a white crystalline powder with the molecular formula C6H7KO2 that inhibits mold, yeast, and fungal growth in acidic environments up to pH 6.5. Food industry applications dominate volume consumption, with powder and granule formats leading because of dosing precision in commercial bakery and beverage operations. Cosmetics and personal care preservation represents the fastest-expanding end-user segment as formulators replace parabens with GRAS-listed alternatives. Direct sales and wholesale channels capture the majority of bulk transactions, while online distribution is gaining traction among mid-size specialty food producers seeking smaller lot sizes.
Regulatory Framework and Forward Outlook
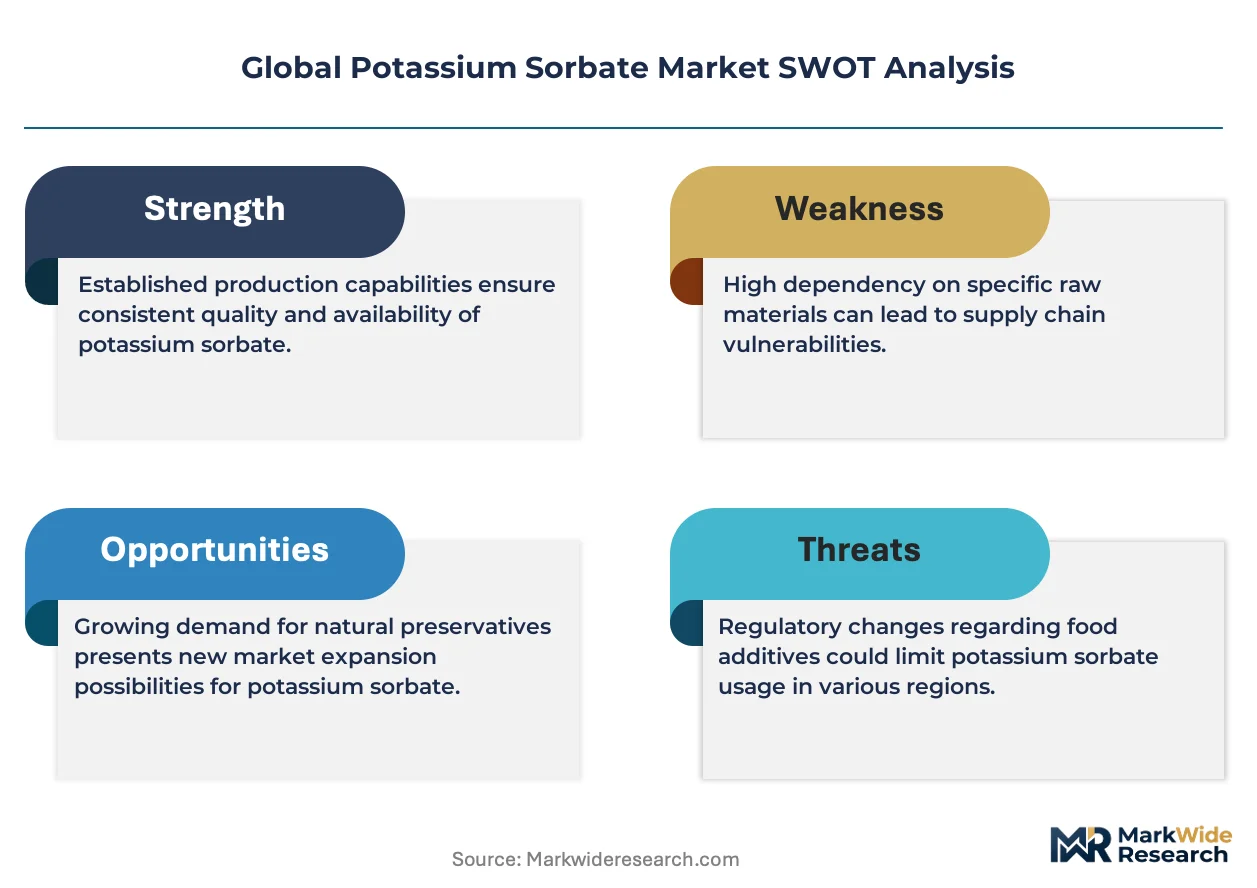
FDA food additive regulations, EFSA purity standards under REACH, and China's GB national food safety standards collectively define compliance thresholds for potassium sorbate manufacturers seeking multi-jurisdiction market access. These frameworks elevate capital requirements for new entrants while rewarding incumbent producers with established analytical and documentation capabilities. Stakeholders must monitor regulatory divergence between jurisdictions as maximum permitted levels and labeling requirements evolve independently across the United States, European Union, and China.
Market Dynamics
Clean-label reformulation pressures across packaged food and personal care sectors are compressing demand for legacy synthetic preservatives while elevating potassium sorbate as the preferred GRAS-listed alternative. This substitution dynamic concentrates purchasing power among large-scale food manufacturers seeking single-source preservative solutions.
Growth Catalysts
- Beverage Industry Volume Pull:Carbonated and still beverage producers in the United States are expanding potassium sorbate procurement to replace benzoate-based preservation systems in acidic formulations below pH 4.5.
- REACH Purity Escalation:ECHA enforcement of updated impurity thresholds for food contact substances is disqualifying smaller Chinese exporters and consolidating import share among certified producers.
- Fermentation Yield Improvements:Continuous bioprocessing advances in sorbic acid precursor production are reducing unit raw material requirements for potassium salt conversion.
Market Restraints
- Crude Oil Derivative Volatility:Acetic acid and ketene feedstock costs for synthetic sorbic acid production fluctuate with petrochemical pricing, compressing margin stability for non-integrated manufacturers.
- Shandong Supply Concentration:Over 60 percent of global crystallization capacity sits within 200 kilometers of Weifang, creating single-point vulnerability to regional environmental enforcement actions or logistics disruptions.
- pH Application Ceiling:Potassium sorbate antimicrobial efficacy degrades above pH 6.5, excluding the preservative from neutral and alkaline food categories where alternatives dominate.
Strategic Opportunities
- Indian Processed Food Expansion:FSSAI modernization of food additive standards is opening formal-channel access for potassium sorbate in dairy alternatives and ready-to-eat meals previously reliant on unregulated preservation.
- Cosmetics Paraben Replacement:EU Commission restrictions on propylparaben and butylparaben in leave-on products are redirecting formulator R&D toward sorbate-based preservation systems for emulsion skincare.
- Direct-to-Manufacturer Digital Platforms:Specialty chemical marketplaces are collapsing traditional distributor markups for mid-size bakery and confectionery producers seeking sub-ton lot sizes with certificate-of-analysis documentation.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Multi-jurisdiction compliance requires in-house HPLC and mass spectrometry capabilities that compete for scarce technicians against pharmaceutical and biotechnology employers.
- Dual Certification Timeline Compression:Simultaneous FDA food additive notification and EFSA novel food assessment processes extend market entry timelines by 18-24 months for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Potassium Sorbate Market |
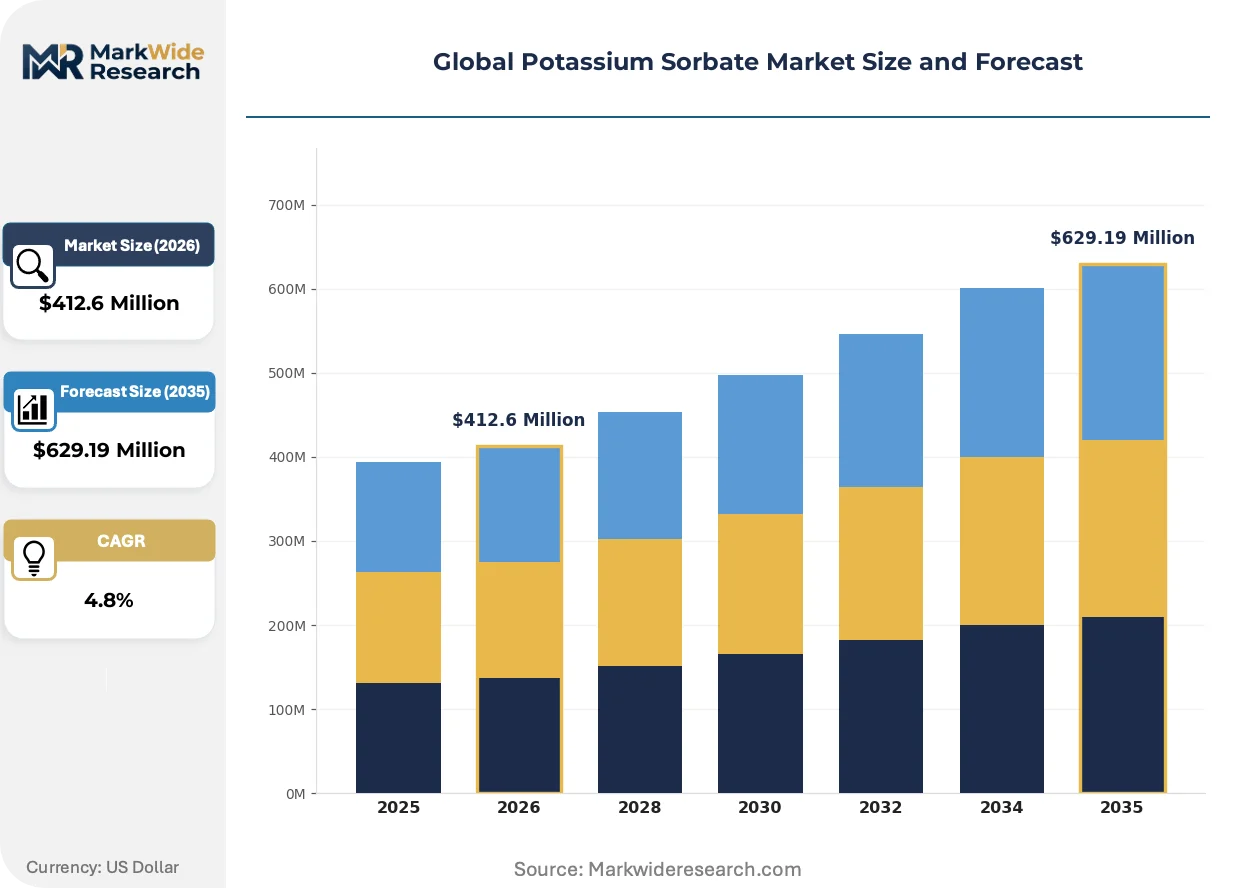
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Crystals End User: Food Industry, Cosmetics, Pharmaceuticals, Agriculture Application: Baking, Beverages, Personal Care, Preservation Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Titan Biotech, Shandong Kunda Biotechnology Co., Ltd., Merck, Celanese Corporation, Hunan Huari Pharmaceutical Co., Ltd., Cargill, TCI, Tate & Lyle, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Potassium Sorbate Market Strategic Shifts
Bioprocess engineering and regulatory harmonization efforts are converging to reshape how potassium sorbate is manufactured, certified, and distributed across fragmented end-use markets. These developments favor scale and documentation capability over commodity positioning.
Continuous fermentation technology for sorbic acid precursor synthesis is consolidating production economics around integrated manufacturing campuses. Mid-size European preservative blenders are adopting this feedstock to secure supply continuity independent of Chinese crystallization bottlenecks. The technology is consolidating margin structures toward producers with captive fermentation capacity.
EFSA's 2023 re-evaluation of sorbic acid and potassium sorbate acceptable daily intake levels triggered reformulation audits across EU-based sauce and condiment manufacturers. The industrial consequence is accelerated demand for high-purity grades with documented impurity profiles below 0.1 percent. German and Dutch food safety agencies are now requiring batch-level third-party testing for imports from non-EU origins.
Specialty food producers are consolidating preservative purchasing through cooperative procurement alliances that aggregate volume for direct manufacturer negotiation. These alliances displace traditional chemical distributors in the 5-50 metric ton annual consumption segment. The shift is most visible in California and Pacific Northwest craft beverage clusters seeking supply chain transparency for clean-label marketing claims.
Global Potassium Sorbate Market Segmentation
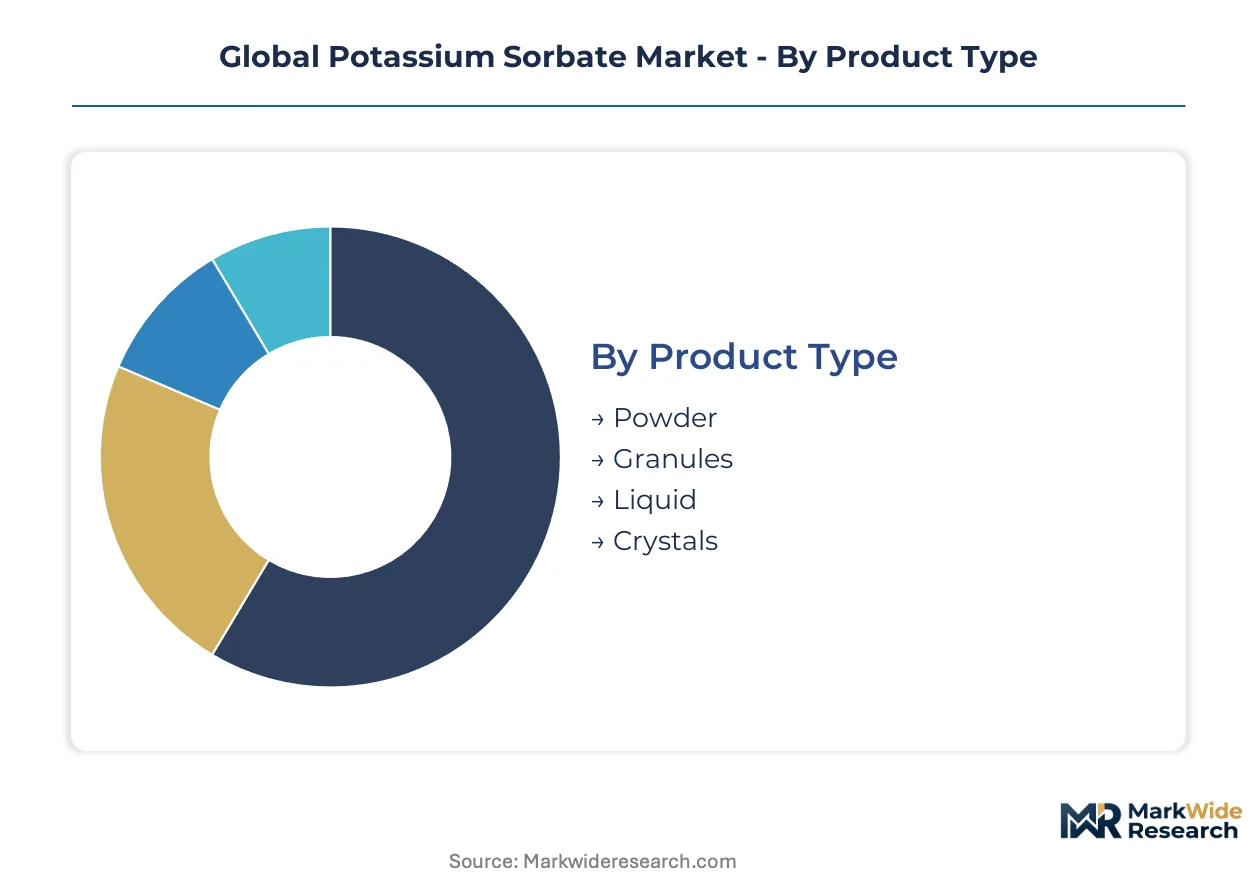
Potassium sorbate demand fragments across physical formats, end-use industries, and procurement channels that each impose distinct purity, packaging, and documentation requirements. Manufacturers configure production lines around these segment boundaries to capture volume efficiency without sacrificing grade-specific certification.
Product Type:
Physical format selection determines integration depth—powder and granules serve standalone dosing systems, while liquid solutions embed directly into automated batch processing.
- Powder:Fine crystalline particles with high surface area enable rapid dissolution in acidic aqueous systems. Commercial bakeries across the United States specify powder for precise gram-scale addition to dough conditioners and icings, with FDA food additive compliance documentation required per lot.
- Granules:Larger particle size reduces dusting during bulk handling and improves flow characteristics in pneumatic conveying systems. European beverage concentrate producers in Germany and the Netherlands prefer granules for automated dosing equipment, driven by REACH-mandated impurity thresholds below 0.1 percent.
- Liquid:Pre-dissolved potassium sorbate solutions eliminate hydration steps in continuous processing lines. Cosmetics formulators in France utilize liquid formats for emulsion stability testing.
- Crystals:High-purity crystalline grades command pharmaceutical and food-grade premiums. Japanese pharmaceutical manufacturers source crystals for API preservation.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
End User:
Customer type segmentation reveals divergent margin structures—commodity food manufacturers squeeze unit economics while cosmetics and pharmaceutical buyers absorb certification premiums.
- Food Industry:Acidic packaged goods manufacturers represent the dominant consumption base, spanning carbonated beverages, sauces, baked goods, and dairy alternatives. Clean-label reformulation across California and Pacific Northwest craft food clusters is elevating sorbate demand as benzoate replacement.
- Cosmetics:Skincare and haircare formulators are displacing paraben preservation systems with GRAS-listed alternatives. EU Commission restrictions on propylparaben in leave-on products are redirecting R&D investment toward sorbate-based emulsion stability.
- Pharmaceuticals:Oral liquid and topical formulations require compendial-grade potassium sorbate with USP or EP certification. Indian generic drug manufacturers are expanding procurement as CDSCO tightens excipient quality standards.
- Agriculture:Animal feed and crop protection applications utilize technical-grade material with lower purity tolerances. Brazilian feed additive producers represent emerging demand as ANVISA aligns veterinary preservative rules with international norms.
Food Industry commands absolute tonnage; Cosmetics is climbing the fastest.
Application:
Application segmentation tracks where antimicrobial efficacy intersects with pH constraints—each use case imposes distinct formulation compatibility requirements.
- Baking:Mold inhibition in bread, cakes, and pastries exploits potassium sorbate effectiveness in pH ranges typical of chemically leavened goods. North American industrial bakeries integrate sorbate into dough conditioners and icings at concentrations optimized for shelf-life extension without flavor impact.
- Beverages:Carbonated and still drinks below pH 4.5 represent the largest single application volume. United States beverage manufacturers are completing benzoate-to-sorbate transitions to support clean-label positioning.
- Personal Care:Emulsion-based skincare and haircare products require preservation systems effective in water-in-oil and oil-in-water matrices. German cosmetics manufacturers are reformulating around sorbate-paraben blends pending full paraben phase-out.
- Preservation:General industrial preservation spans sauces, condiments, and prepared meals. Chinese sauce producers are upgrading to food-grade sorbate as GB national standards tighten heavy metal limits.
Beverages anchor volume share; Personal Care shows steepest expansion trajectory.
Distribution Channel:
Channel structure reflects lot-size fragmentation—bulk procurement concentrates through direct relationships while smaller manufacturers access certified material through digital platforms.
- Online:Specialty chemical marketplaces and manufacturer-direct portals serve mid-size producers seeking sub-ton quantities with certificate-of-analysis documentation. California craft beverage cooperatives aggregate demand through shared digital procurement platforms.
- Retail:Packaged potassium sorbate for small-scale food producers and home-based cosmetics formulators moves through chemical supply distributors. French specialty ingredient retailers stock food-grade sorbate alongside pH testing equipment.
- Wholesale:Regional chemical distributors hold inventory for just-in-time delivery to medium-volume manufacturers. Midwest United States bakery supply wholesalers maintain sorbate stocks for multi-state delivery networks.
- Direct Sales:Large-volume food and beverage manufacturers negotiate annual contracts with crystallization producers, bypassing distributor markups. Shandong-based producers serve export markets through direct relationships with European and North American compounders.
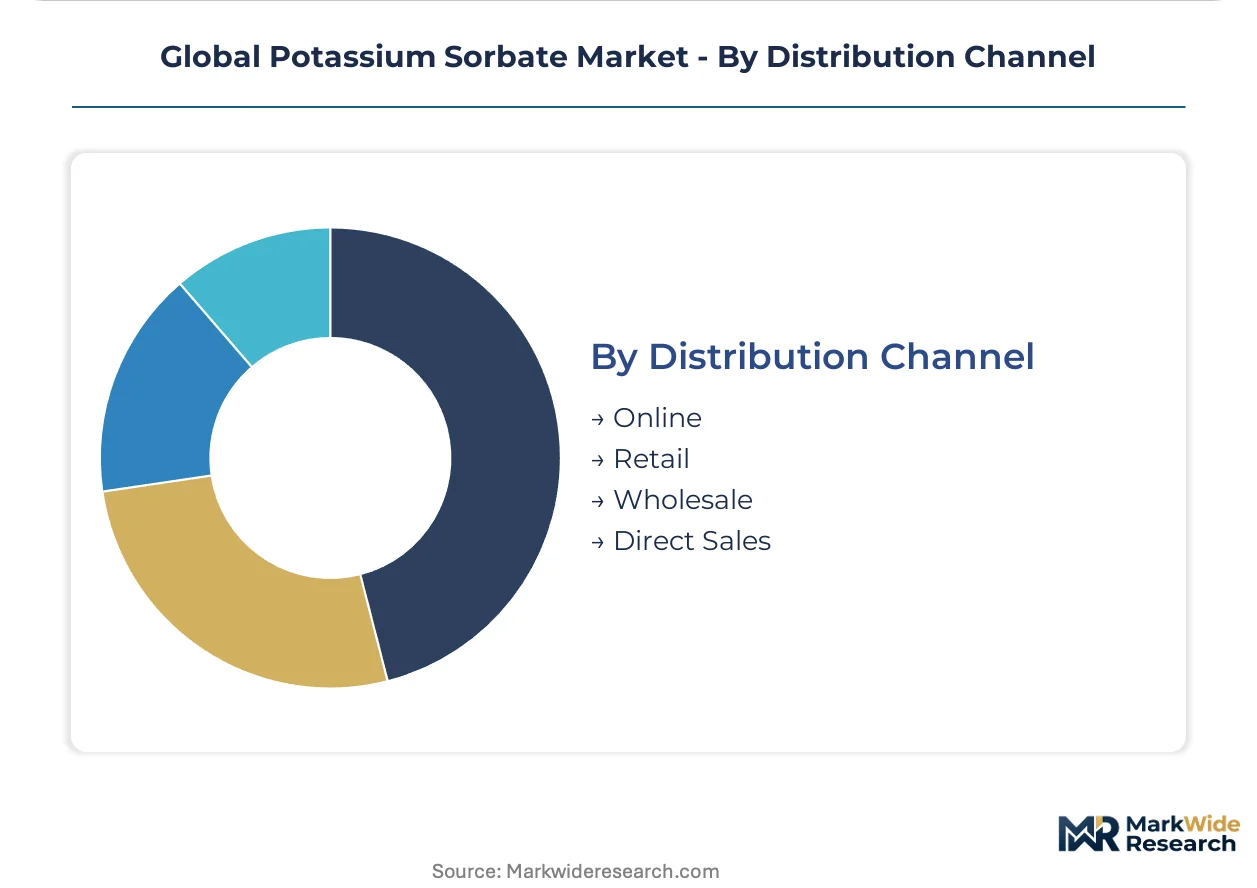
Direct Sales captures bulk tonnage; Online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's chemical manufacturing belt anchors global crystallization capacity for potassium sorbate, with over 60 percent of worldwide production concentrated within 200 kilometers of Weifang. This geographic concentration shapes trade flows and regulatory compliance strategies across import-dependent markets.
United States
Carbonated and still beverage manufacturers in California and the Pacific Northwest are completing benzoate-to-sorbate transitions to support clean-label positioning. FDA food additive regulations govern maximum permitted levels and labeling requirements for acidic formulations below pH 4.5. Midwest industrial bakeries in Illinois and Ohio integrate powder-grade material into dough conditioners for mold inhibition.
China
Domestic sauce producers in Shandong and Jiangsu provinces are upgrading to food-grade sorbate as GB national standards tighten heavy metal limits. SAMR enforcement of updated food safety standards is consolidating production licenses among certified crystallization operators. The Weifang chemical cluster houses integrated fermentation-to-crystallization campuses serving export markets.
Germany
Beverage concentrate producers in Bavaria and North Rhine-Westphalia prefer granule formats for automated dosing equipment. EFSA purity standards under REACH mandate impurity thresholds below 0.1 percent for food contact substances. German cosmetics manufacturers in Hamburg are reformulating around sorbate-paraben blends pending full paraben phase-out.
India
Generic drug manufacturers in Maharashtra and Gujarat are expanding procurement of compendial-grade material as CDSCO tightens excipient quality standards. FSSAI modernization of food additive standards is opening formal-channel access for dairy alternatives and ready-to-eat meals. Mumbai-based pharmaceutical formulators require USP-certified grades for oral liquid preservation.
Brazil
Animal feed additive producers in São Paulo and Minas Gerais represent emerging demand as ANVISA aligns veterinary preservative rules with international norms. Technical-grade material serves crop protection applications with lower purity tolerances. The Campinas agrochemical cluster is integrating sorbate-based preservation into formulated products.
Global Potassium Sorbate Market Competitive Environment
Global majors compete with regional champions across certification tiers and geographic reach. The vendor base stratifies around three structural tiers: integrated fermentation operators with captive crystallization capacity, pharmaceutical-grade specialists commanding certification premiums, and regional compounders serving formulation-blend demand. Strategic moves concentrate on backward integration into sorbic acid precursor production and direct-to-manufacturer digital platform development.
Within the integrated manufacturing tier, Shandong Kunda Biotechnology Co., Ltd. exemplifies Chinese producers leveraging fermentation-to-crystallization control. Merck occupies a position among pharmaceutical-grade specialists, while Celanese Corporation anchors North American supply security through distribution infrastructure. Hunan Huari Pharmaceutical Co., Ltd. represents regional champions serving domestic and export pharmaceutical markets.
| Leading Market Players |
|---|
| Titan Biotech |
| Shandong Kunda Biotechnology Co., Ltd. |
| Merck |
| Celanese Corporation |
| Hunan Huari Pharmaceutical Co., Ltd. |
| Cargill |
| TCI |
| Tate & Lyle |
| Archer Daniels Midland |
| Others |
Value Chain & Pricing Dynamics
Acetic acid and ketene feedstock costs trace from petrochemical complexes through synthetic sorbic acid production into crystallization economics, compressing margin structures for non-integrated manufacturers while rewarding Shandong-based operators with captive fermentation capacity.
Pricing Analysis
Certificate-of-analysis documentation and REACH compliance warranties are bundled into premium-grade contracts while technical-grade material ships unbundled for feedstock applications. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels separates compendial-certified crystals from standard powder and bulk agricultural material. Pricing pressure stems from crude oil derivative volatility feeding synthetic production routes. Large-scale beverage manufacturers exhibit lowest price sensitivity due to formulation lock-in costs, while mid-size bakery cooperatives negotiate aggressively on sub-ton lot sizes.
Supply Chain Analysis
REACH certification and FDA food additive notification requirements gate access to regulated end markets, filtering export capacity toward documented producers. Manufacturing concentrates in China, Germany, and India for crystallization and compounding operations. Sorbic acid precursor, potassium hydroxide, and crystallization energy inputs anchor production economics. Single-source vulnerability runs through the Weifang chemical cluster's environmental enforcement exposure. Distribution runs through direct manufacturer relationships for bulk tonnage and specialty chemical marketplaces for fragmented lot sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into sorbic acid fermentation capacity has become the decisive competitive lever as crystallization margins compress and precursor supply security determines market access.
For Market Incumbents: Acquire fermentation-to-crystallization campuses in Shandong province to consolidate cost control across the potassium sorbate value chain. Expand compendial-grade certification capabilities to capture pharmaceutical excipient premiums as CDSCO and EFSA tighten purity enforcement. Defend against emerging Indian and Brazilian compounders by locking long-term offtake agreements with North American beverage manufacturers completing benzoate replacement programs. For New Entrants and Emerging Players: Direct-to-manufacturer digital platforms offer the lowest-friction entry path for mid-size specialty food producers seeking sub-ton quantities with batch-level documentation. Target cosmetics formulators in France and Germany displaced by EU paraben restrictions, where sorbate-based preservation R&D budgets are expanding fastest. Build cooperative procurement alliances with Pacific Northwest craft beverage clusters to aggregate volume for manufacturer-direct negotiation. For Investors and Strategic Acquirers: EFSA re-evaluation triggering batch-level third-party testing requirements for non-EU imports is the leading indicator that certification-capable assets will command scarcity premiums. Position for five-to-ten year holding periods around integrated operators with REACH and FDA dual-notification capabilities. Monitor SAMR enforcement actions in Weifang as the critical inflection signal for supply disruption and margin expansion opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive sorbic acid production insulates margin structures from petrochemical feedstock volatility. |
| Dual Certification Investment | Simultaneous FDA notification and EFSA assessment capabilities unlock multi-jurisdiction market access. |
| Direct-to-Manufacturer Digital Platform Development | Specialty chemical marketplaces collapse distributor markups for mid-size lot procurement. |
| High-Purity Grade Capacity Expansion | Impurity thresholds below 0.1 percent capture pharmaceutical and premium food-grade premiums. |
| Cooperative Procurement Alliance Formation | Aggregated demand from craft beverage clusters enables manufacturer-direct contract negotiation. |
Study Parameters
Multi-period observation of crystallization capacity utilization, REACH enforcement patterns, and beverage industry reformulation timelines anchored the trend analysis, supplemented by interviews with plant managers at Shandong fermentation facilities, procurement leads at North American beverage compounders, distribution channel partners in European wholesale networks, and technical R&D directors at cosmetics formulators. Secondary validation drew from customs and trade data, EFSA safety assessments, FDA food additive petitions, and SEC filings from listed chemical producers. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and end-use segments.
Segment-weighting approaches distributed value and volume across powder, granule, liquid, and crystal formats; food, cosmetics, pharmaceutical, and agriculture end users; and direct, wholesale, online, and retail channels. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules throughout the forecast period. Industry-specific inputs included pH application constraints, clean-label substitution elasticities, and regulatory compliance timeline assumptions.
The model holds under stable petrochemical feedstock pricing and continued REACH enforcement intensity; deviation in crude oil volatility or environmental enforcement actions in Shandong would shift crystallization economics and trade flow patterns. A model refresh is warranted upon material change in EFSA acceptable daily intake thresholds or FDA food additive reclassification proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
India Air Treatment Products Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
Disinfectant Fogging and Misting Chemicals for Large Facilities Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Preservative Blends Market