
 India Hydrogen Peroxide Market | 2026-2036
India Hydrogen Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
India Hydrogen Peroxide Market Insights
Chemical engineering talent is rotating toward process safety and automation specializations as Indian hydrogen peroxide producers scale anthraquinone auto-oxidation capacity. National Peroxide Limited leverages its legacy manufacturing footprint in Kalyan to sustain bulk supply relationships with domestic pulp mills. Gujarat Alkalies and Chemical Limited anchors its position through backward integration into caustic soda and captive power, while Meghmani Finechem Limited differentiates via specialized grades for textile bleaching.
Hydrogen peroxide is a colorless liquid oxidizer with molecular formula H₂O₂, typically manufactured through the anthraquinone process yielding concentrations from 35% to 70% for industrial use; its strong oxidizing properties drive applications in bleaching, sterilization, and chemical synthesis. Aqueous solutions dominate volume throughput due to safer handling profiles and compatibility with existing dosing infrastructure across paper and textile plants. Electronics cleaning represents the fastest-growing application segment as semiconductor fabrication investments in India multiply, while industrial grade products occupy the mature, price-sensitive core of the market.
BIS standards govern hydrogen peroxide purity and packaging specifications, filtering subscale producers from institutional procurement channels, while CDSCO oversight applies to food-grade and pharmaceutical variants entering processing and antiseptic applications. The EPA-aligned water treatment mandates in several states expand municipal demand for hydrogen peroxide-based advanced oxidation processes. Stakeholders must monitor how state-level environmental compliance deadlines and semiconductor cluster approvals in Gujarat, Tamil Nadu, and Karnataka reshape grade-mix requirements and regional supply contracts.
Market Dynamics
Anthraquinone auto-oxidation capacity expansion in Gujarat and Maharashtra is compressing regional supply gaps while tightening BIS certification thresholds for new market entrants.
Growth Catalysts
- Electronics cleaning demand:Semiconductor fabrication investments in Tamil Nadu and Karnataka are pulling high-purity hydrogen peroxide grades into advanced oxidation processes for wafer cleaning.
- BIS standardization:Mandatory purity specifications for industrial chemicals are filtering subscale producers and consolidating procurement toward certified suppliers.
- Pulp mill modernization:Domestic paper manufacturers are replacing chlorine-based bleaching with hydrogen peroxide to meet EPA-aligned state water treatment mandates.
Market Restraints
- Anthracene derivative volatility:Feedstock cost swings for the anthraquinone process compress margin predictability for non-integrated producers.
- Gujarat supply concentration:Overreliance on Dahej and Vadodara chemical clusters creates single-point vulnerability for national distribution networks.
- Chlorine dioxide substitution:Pulp mills in cost-sensitive segments retain legacy bleaching agents where hydrogen peroxide premiums exceed budget thresholds.
Strategic Opportunities
- North-east India penetration:Assam and Manipur lack local hydrogen peroxide production, creating white space for bulk supply contracts with emerging textile clusters.
- Food-grade certification:FSSAI compliance for aseptic packaging applications opens antiseptic and beverage sterilization segments currently served by imports.
- Captive hydrogen integration:Electrolyzer deployment at chlor-alkali complexes enables on-site peroxide synthesis, decoupling producers from merchant hydrogen markets.
Industry Challenges
- Process safety engineering scarcity:Auto-oxidation plant operators face recruitment gaps for hazard analysis specialists certified under OSHA-aligned Indian factory regulations.
- BIS certification timelines:Laboratory testing backlogs for new grade approvals delay market entry by 8-14 months for specialty formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hydrogen Peroxide Market |
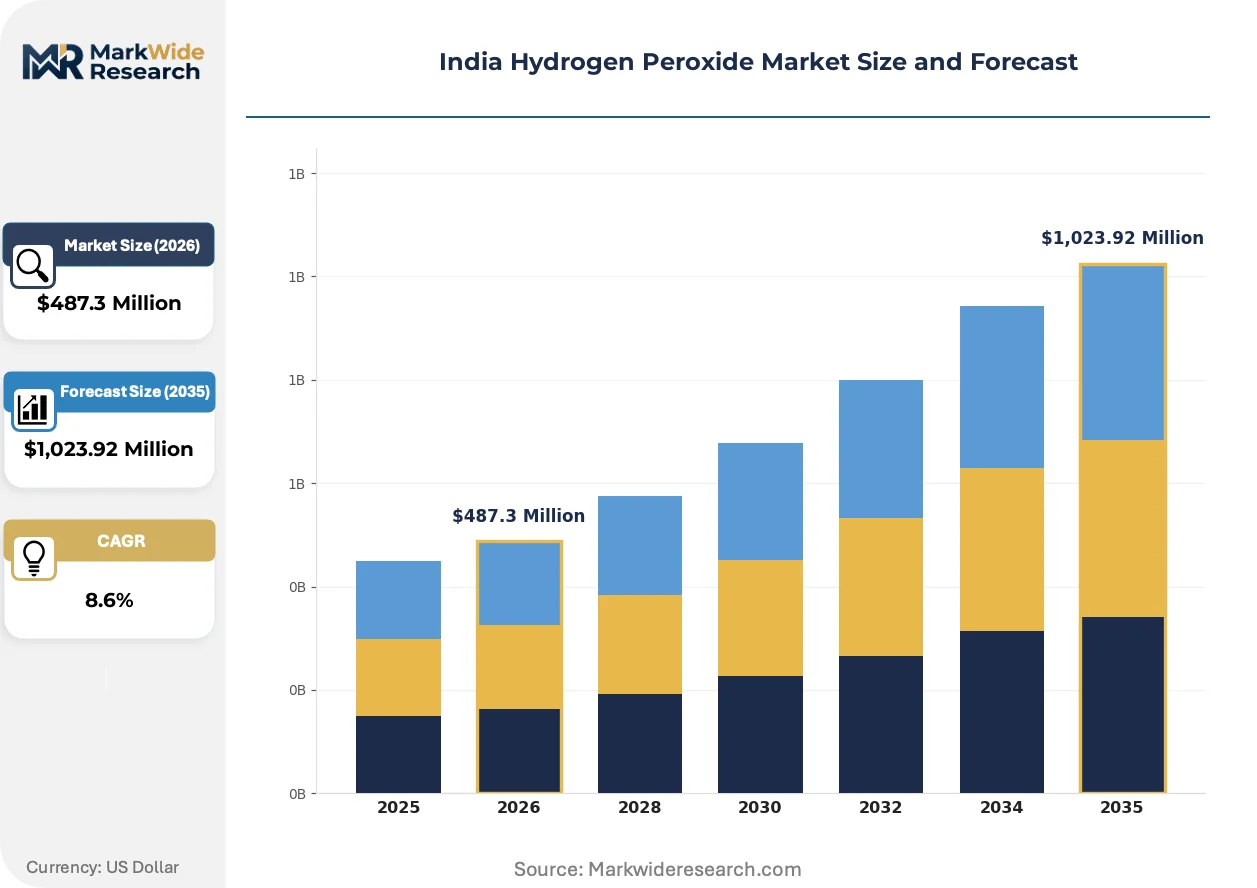
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilized Hydrogen Peroxide, Aqueous Solutions, Anhydrous Hydrogen Peroxide, Industrial Grade Application: Textile Bleaching, Paper Pulping, Water Treatment, Electronics Cleaning End User: Pulp and Paper Industry, Textile Sector, Food Processing, Chemical Manufacturing Packaging Type: Drums, IBC Containers, Bags, Bulk Containers |
| Companies Covered | Aditya Birla Chemicals, Gujarat Alkalies and Chemical Limited, Indian Peroxide Limited, Meghmani Finechem Limited, National Peroxide Limited, DCM Shriram, National Oxygen Limited, Arkema India, OCI Chemical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hydrogen Peroxide Market Trends and Innovations
Process intensification and regulatory tightening are reshaping how hydrogen peroxide manufacturers configure production assets and grade portfolios across Indian chemical corridors.
Membrane electrolysis for on-site hydrogen generation is decomposing the traditional merchant hydrogen supply chain that has constrained anthraquinone plant economics. Chlor-alkali producers in Gujarat are piloting solid oxide electrolyzer integration to capture stranded renewable power, compressing feedstock costs for captive peroxide synthesis. This technology shift is decomposing the historical dependence on compressed gas logistics and enabling distributed production nodes closer to pulp and electronics clusters.
BIS certification requirements for industrial chemicals are tightening purity thresholds and packaging specifications, forcing reformulation investments across the supplier base. The standards body now mandates accelerated stability testing for export-grade concentrations, raising compliance costs for smaller blenders. Pulp mills in Maharashtra are responding by consolidating procurement toward integrated producers with in-house analytical capabilities.
Long-term offtake agreements are displacing spot purchasing as semiconductor fabs in Karnataka and Tamil Nadu secure supply continuity for high-purity grades. Electronics manufacturers now require 24-month volume commitments with price collars, transferring inventory risk upstream to chemical producers. This contracting shift is most visible in the Bengaluru-Tirupati corridor, where wafer fabrication investments are outpacing local chemical infrastructure.
India Hydrogen Peroxide Market Segmentation
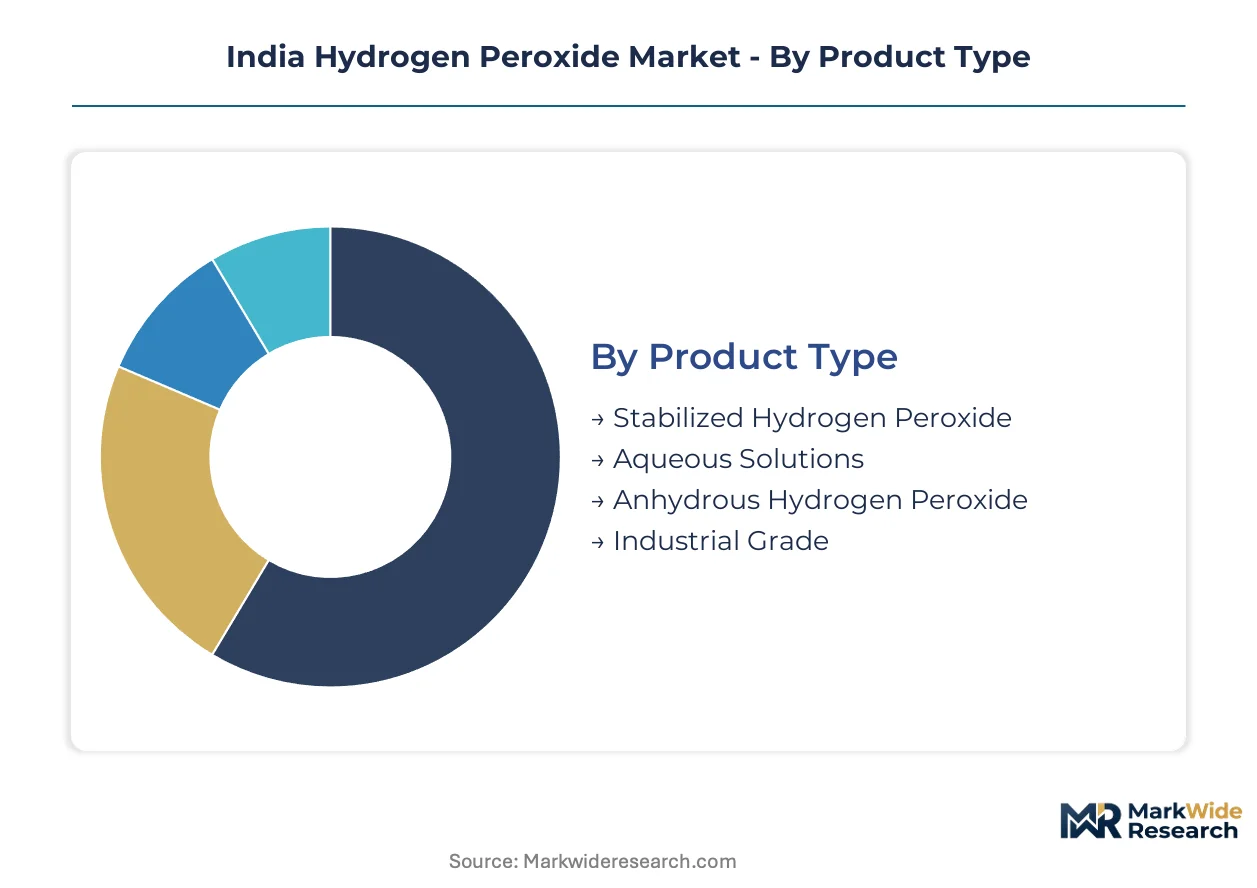
India's hydrogen peroxide market fragments across product purity, application intensity, and logistics configuration. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape supplier positioning.
Product Type:
Domestic consumption clusters around aqueous formulations for safety compliance, while export-oriented production emphasizes stabilized and industrial grades for bulk chemical processing.
- Aqueous Solutions:Water-diluted formulations at 35-50% concentration dominate textile and paper mill dosing systems. Maharashtra and Gujarat pulp clusters absorb the bulk of domestic volume under BIS purity mandates.
- Industrial Grade:Standardized 50-70% concentrations serve bulk chemical synthesis and effluent treatment. Dahej chemical corridor producers leverage this grade for inter-state supply contracts with chlorine-alkali integrated buyers.
- Stabilized Hydrogen Peroxide:Additive-inhibited variants extend shelf life for export shipments to Middle East and Southeast Asian processors.
- Anhydrous Hydrogen Peroxide:Concentrated >90% solutions serve specialty aerospace and defense propulsion applications with stringent handling protocols.
Aqueous solutions hold the largest share; momentum sits with industrial grade as chlor-alkali complexes expand captive synthesis.
Application:
Cost-tier stratification separates mature bleaching applications from emerging precision cleaning segments with divergent certification requirements.
- Paper Pulping:Chlorine replacement drives demand across Vapi and Tarapur paper complexes. EPA-aligned state mandates in Maharashtra accelerate mill conversion timelines.
- Electronics Cleaning:Semiconductor wafer oxidation and photoresist stripping pull ultra-high-purity grades into Bengaluru-Tirupati fabrication corridors. CDSCO traceability requirements apply for pharmaceutical-adjacent tool cleaning.
- Textile Bleaching:Surat and Tiruppur processing hubs consume standard grades for cotton and synthetic fiber whitening under ZDHC chemical compliance frameworks.
- Water Treatment:Municipal advanced oxidation process installations in Gujarat and Tamil Nadu deploy hydrogen peroxide for pharmaceutical residue breakdown.
Paper pulping anchors volume; electronics cleaning climbs the fastest as semiconductor investments multiply.
End User:
Customer-type concentration varies by procurement sophistication, with integrated chemical manufacturers capturing supply chain efficiencies unavailable to fragmented textile processors.
- Pulp and Paper Industry:Integrated mills in Vapi and Aurangabad negotiate long-term offtake with quarterly price collars. BIS certification filters spot-market suppliers from institutional procurement.
- Chemical Manufacturing:Chlor-alkali and peroxide derivative producers backward-integrate into captive hydrogen supply, compressing merchant market dependence.
- Textile Sector:Surat dyeing clusters and Tiruppur garment processors purchase drum-packaged volumes through distributor networks with 30-day credit terms.
- Food Processing:Aseptic packaging sterilization applications require FSSAI-compliant food-grade certification currently met through limited domestic supply.
Pulp and paper commands the largest share; food processing presents the steepest expansion trajectory as import substitution accelerates.
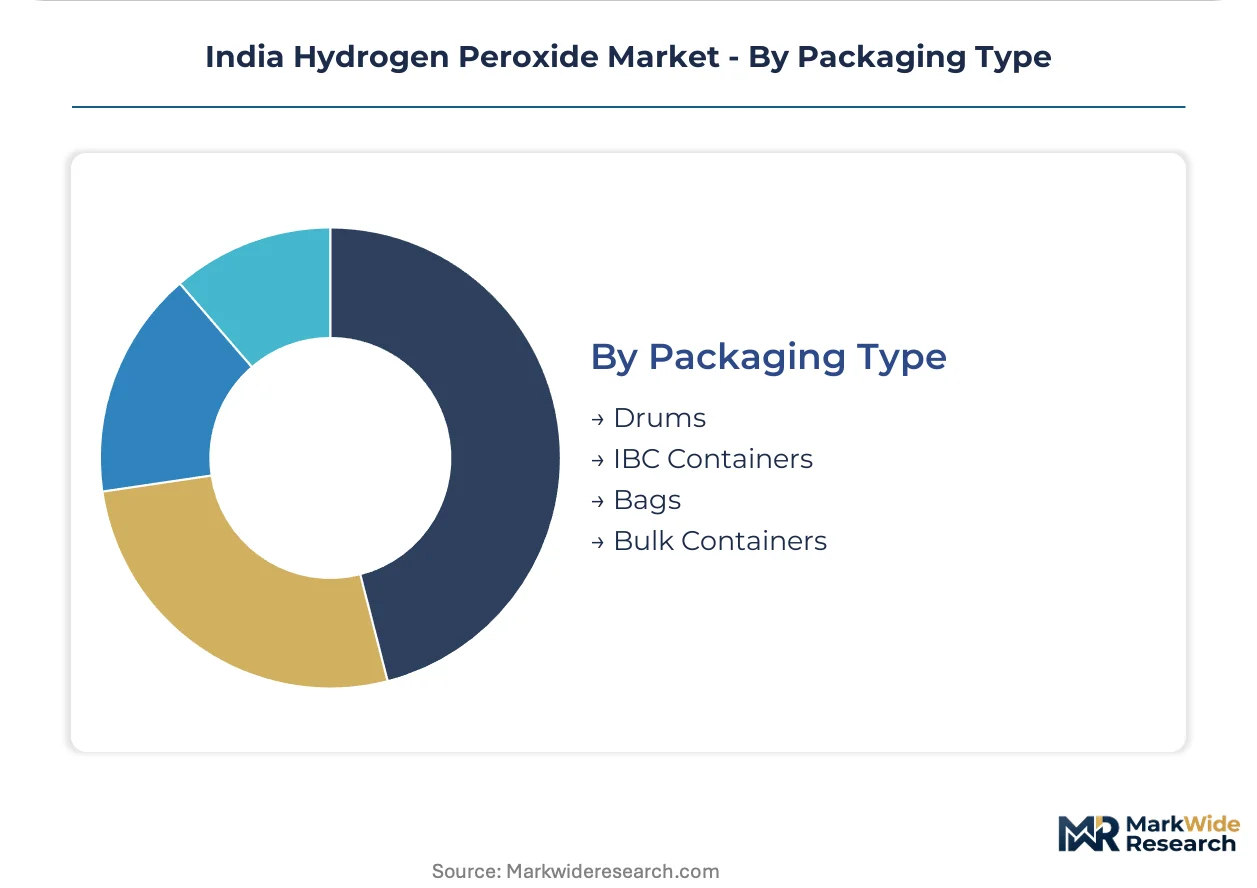
Packaging Type:
Logistics configuration directly determines reachable market radius, with bulk infrastructure constraining supplier access to coastal chemical corridors.
- Drums:200-liter steel and HDPE containers serve textile processors and small paper mills with limited storage capacity. Tiruppur and Surat distributors maintain drum-filling operations.
- IBC Containers:Intermediate bulk totes at 1000-liter scale balance handling efficiency with site constraints at mid-size pulp mills.
- Bulk Containers:Tanker truck and railcar deliveries serve Dahej and Vadodara chemical complexes with dedicated unloading infrastructure.
- Bags:Powdered percarbonate and persulfate derivatives in moisture-barrier packaging serve rural detergent compounders.
Drums dominate unit volume; bulk containers concentrate value capture at integrated chemical hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements anchor production concentration in western India, where chemical manufacturing clusters and port infrastructure enable feedstock access and export logistics. State-level environmental mandates and semiconductor investments are redrawing regional demand maps.
Maharashtra
Pulp mill modernization in Vapi and Tarapur drives chlorine-replacement demand for hydrogen peroxide bleaching. EPA-aligned state water treatment mandates accelerate mill conversion timelines. Mumbai-Pune chemical corridor hosts National Peroxide Limited's legacy manufacturing footprint serving domestic pulp mills.
Gujarat
Dahej and Vadodara chemical clusters concentrate anthraquinone auto-oxidation capacity expansion. Captive power and backward integration into caustic soda anchor Gujarat Alkalies and Chemical Limited's supply position. BIS certification thresholds filter smaller blenders from institutional procurement channels.
Karnataka
Semiconductor wafer fabrication investments in the Bengaluru-Tirupati corridor pull ultra-high-purity hydrogen peroxide grades for electronics cleaning. CDSCO traceability requirements apply for pharmaceutical-adjacent tool cleaning applications. Long-term offtake agreements with 24-month volume commitments displace spot purchasing.
Tamil Nadu
Electronics manufacturing clusters generate demand for advanced oxidation processes in wafer cleaning and photoresist stripping. State-level environmental compliance deadlines reshape grade-mix requirements for municipal water treatment installations. Tiruppur garment processors consume drum-packaged volumes for textile bleaching under ZDHC frameworks.
Assam and North-east India
Emerging textile clusters in Assam and Manipur lack local hydrogen peroxide production, creating white space for bulk supply contracts. FSSAI-compliant food-grade certification opens aseptic packaging applications currently served by imports. Distributor networks with 30-day credit terms serve drum-filling operations for regional processors.
India Hydrogen Peroxide Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into caustic soda and captive power distinguishing the upper tier from merchant-dependent competitors. BIS certification requirements filter subscale producers from institutional procurement channels. Two strategic archetypes dominate: integrated chlor-alkali producers with captive hydrogen supply, and specialized peroxide manufacturers focused on grade differentiation. Competitive moves concentrate on capacity expansion in Gujarat and Maharashtra, and long-term offtake agreements with semiconductor fabs.
Among India-based integrated producers, Gujarat Alkalies and Chemical Limited and National Peroxide Limited exemplify the backward-integrated archetype, while Meghmani Finechem Limited occupies a position within the specialist tier. These three entities represent distinct competitive positioning strategies visible across the supplier base: captive feedstock control, legacy manufacturing footprint leverage, and specialized grade development for textile applications.
| Leading Market Players |
|---|
| Aditya Birla Chemicals |
| Gujarat Alkalies and Chemical Limited |
| Indian Peroxide Limited |
| Meghmani Finechem Limited |
| National Peroxide Limited |
| DCM Shriram |
| National Oxygen Limited |
| Arkema India |
| OCI Chemical |
| Others |
Pricing and Supply Chain Analysis
Anthraquinone auto-oxidation scale economies in Gujarat and Maharashtra compress unit costs for integrated producers while establishing price floors that merchant-dependent competitors struggle to match. BIS certification overhead and captive hydrogen supply advantages concentrate margin capture among backward-integrated chlor-alkali operators, fragmenting the supplier base into certified institutional vendors and price-competitive spot-market blenders.
Pricing Analysis
Dahej-Vadodara chemical corridors command a 12-18% premium over eastern and northeastern delivery points due to bulk infrastructure and logistics density. Contract-based long-term offtake agreements dominate semiconductor and pulp mill procurement, with price differentiation resting on BIS certification tier and volume scale. Cost compression in standard industrial grades is intensifying because chlorine dioxide substitution retains cost-sensitive paper segments. Small textile processors in Tiruppur and Surat exhibit highest price sensitivity; semiconductor fabs in Karnataka demonstrate lowest sensitivity due to purity-critical process requirements.
Supply Chain Analysis
Inventory cycles at Dahej chemical hubs run 45-60 days for merchant hydrogen feedstock, compressing working capital efficiency for non-integrated producers. Supply concentrates in India, with anthracene derivative inputs drawn from China and select European specialty chemical suppliers. Single-source vulnerability permeates the merchant hydrogen supply chain, where compressed gas logistics create distribution chokepoints. Distribution runs through bulk tanker networks serving integrated chemical complexes, with drum-filling operations at regional distributor nodes reaching fragmented textile and small paper mill customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronics cleaning demand fragmentation creates niche positioning opportunities for specialty grade producers outside the integrated chlor-alkali core. Semiconductor fabrication investments in Karnataka and Tamil Nadu pull procurement sophistication upward, rewarding suppliers with CDSCO traceability and accelerated stability testing capabilities.
For Market Incumbents: Fortify BIS certification barriers by investing in-house analytical laboratories capable of export-grade accelerated stability testing. Expand captive hydrogen supply through solid oxide electrolyzer deployment at existing chlor-alkali complexes, decoupling from merchant hydrogen volatility that threatens margin predictability. Deepen long-term offtake agreements with Bengaluru-Tirupati semiconductor fabs to lock in 24-month volume commitments before specialty chemical infrastructure catches regional demand.
For New Entrants and Emerging Players: Lead with FSSAI-compliant food-grade certification targeting aseptic packaging sterilization applications currently import-dependent. North-east India textile clusters in Assam and Manipur represent the most penetrable geography, lacking local production and served by high-logistics-cost western supply. Pursue distributor partnerships offering 30-day credit terms rather than direct mill sales to bypass capital-intensive bulk infrastructure requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated chlor-alkali producers with captive hydrogen and established BIS-certified grade portfolios serving institutional pulp and semiconductor accounts. Over the projection horizon, acquisition targets should display electrolyzer deployment readiness and analytical certification capabilities rather than pure capacity scale. Monitor state-level semiconductor cluster approval timelines in Gujarat, Tamil Nadu, and Karnataka as inflection indicators for high-purity grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Hydrogen | Solid oxide electrolyzer deployment at Dahej chlor-alkali complexes decouples producers from merchant hydrogen price volatility. |
| BIS Certification Investment | In-house analytical laboratories accelerate export-grade stability testing, filtering subscale competitors from institutional procurement channels. |
| Long-term Supply Agreement | 24-month volume commitments with Karnataka semiconductor fabs transfer inventory risk upstream and secure high-purity grade offtake. |
| Food-grade Certification Pathway | FSSAI compliance for aseptic packaging applications opens import substitution opportunities in beverage sterilization segments. |
| North-east Distribution Expansion | Drum-filling operations in Assam reduce logistics premiums for emerging textile clusters lacking local production infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at anthraquinone auto-oxidation facilities, procurement leads at Vapi and Tarapur pulp mills, distribution channel partners in Surat and Tiruppur textile corridors, and technical R&D directors at chlor-alkali integrated producers, then refined against secondary validation from BIS certification records, CDSCO pharmaceutical-grade filings, customs trade data for anthracene derivative imports, and SEC disclosures from listed chemical manufacturers. Bottom-up capacity utilization estimates across Gujarat and Maharashtra production hubs were triangulated with top-down demand modeling from end-use consumption patterns.
Variance decomposition across the analysis window isolates grade-mix shifts, regional demand migration, and regulatory compliance cost inflation as distinct forecast drivers. Segmentation dimensions modeled include product purity tier, application intensity across paper pulping and electronics cleaning, packaging logistics configuration, and regional production hub concentration. CAGRs were derived through iterative convergence of supply-side capacity expansion schedules and demand-side offtake commitment visibility, with semiconductor fab investment pipelines and EPA-aligned state water treatment mandates serving as industry-specific demand calibration inputs.
Forecasts assume regulatory continuity in BIS industrial chemical standards and CDSCO pharmaceutical-grade oversight; material policy shifts in purity thresholds or packaging specifications would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Clinical Grade Disinfectant Market
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Sodium Nitrite Market
Disinfectants and Preservatives
Sterilants Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
Global Mold Inhibitors Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Disinfecting Wipes Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Hypochlorite Bleaches Market
Disinfectants and Preservatives
Hypochlorous Acid Market