
 India Air Treatment Products Market | 2026-2036
India Air Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
India Air Treatment Products Market Foresight
The capital-intensity divergence between compressor-manufacturing incumbents and assembly-reliant entrants is bifurcating competitive dynamics in India's air treatment sector. Daikin Industries Ltd leverages captive compressor production to sustain margin resilience against import volatility. Eureka Forbes Ltd anchors its position through deep rural distribution networks that dominate tier-2 and tier-3 city penetration. Havells India Ltd differentiates via in-house motor and control-system manufacturing that reduces supplier dependency.
Air treatment products encompass electromechanical systems designed to modify ambient air parameters through filtration, humidity control, temperature regulation, or ionization, typically operating across CADR ratings from 100 to 1,000 cubic meters per hour depending on application scale. These systems serve residential, commercial, and industrial environments where particulate matter, VOCs, or thermal loads compromise occupant health, process integrity, or equipment performance. Air purifiers incorporating HEPA technology lead volume shipments as urban AQI deterioration drives replacement cycles in northern Indian cities. The commercial end-user segment represents the fastest-expanding margin pool, with hospitals, data centers, and pharmaceutical cleanrooms specifying activated-carbon and UV-C multi-stage configurations. Online distribution channels are capturing disproportionate growth in residential sales, though direct-sales relationships still control project-based industrial contracts.
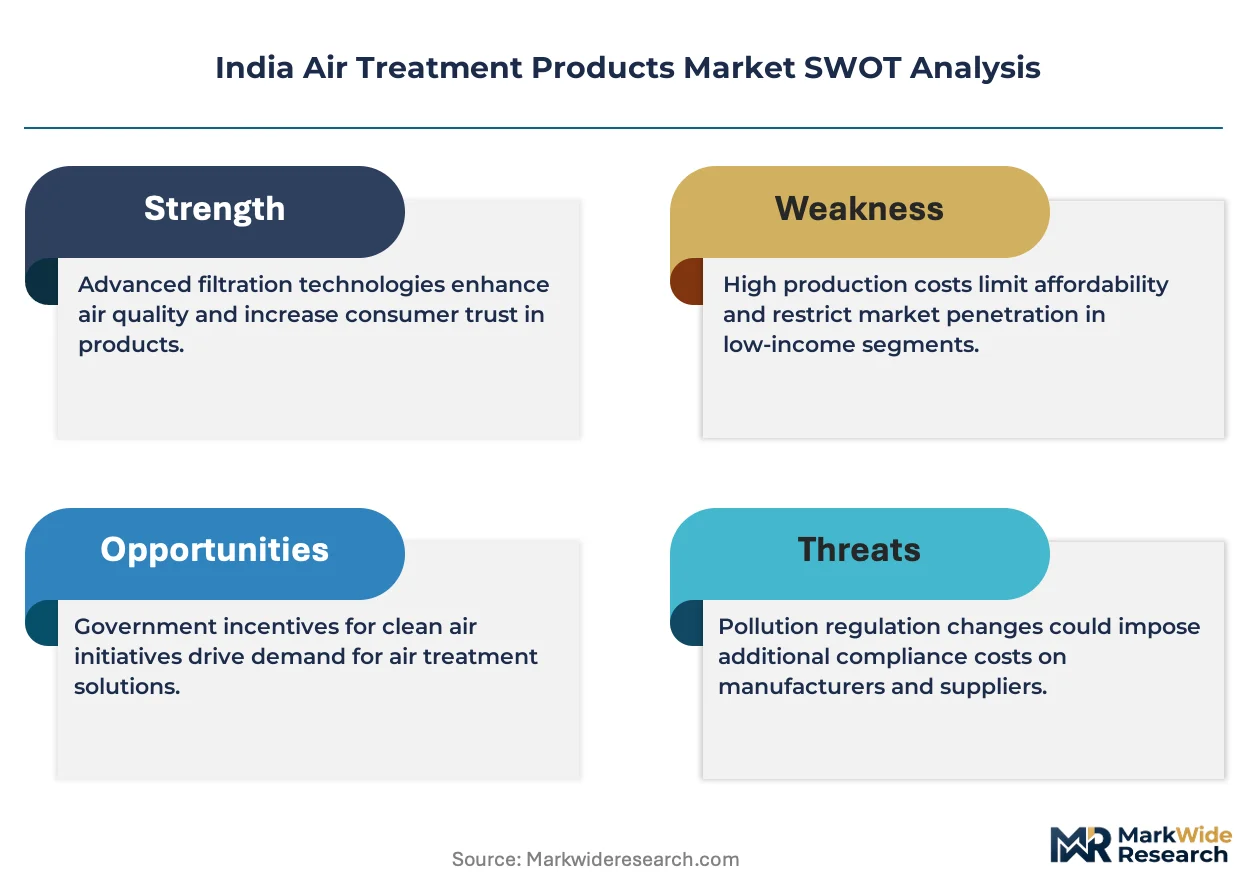
BIS mandates under the Compulsory Registration Scheme govern electronic air treatment equipment safety and energy performance, while CEA efficiency norms shape industrial cooling system specifications for large-scale deployments. The PLI scheme for white goods manufacturing is redirecting capital toward domestic component ecosystems, altering supplier geography for compressors and heat exchangers. Stakeholders must monitor how BIS testing protocol revisions and state-level building energy codes will reshape product certification timelines and channel inventory requirements.
Market Dynamics
PLI scheme disbursements are redirecting component sourcing from ASEAN suppliers toward Gujarat and Tamil Nadu manufacturing clusters, compressing lead times for compressors and heat exchangers while forcing assembly-dependent brands to absorb margin erosion or accelerate backward integration.
Growth Catalysts
- BIS Compulsory Registration Scheme:Certification mandates for electronic air purifiers are eliminating unorganized competitors and consolidating shelf space for compliant manufacturers in modern trade channels.
- Metropolitan AQI deterioration:Delhi NCR and Mumbai particulate levels are shortening replacement cycles for HEPA filtration systems in residential installations.
- Data center expansion:Hyperscale facilities in Hyderabad and Chennai are specifying activated-carbon and UV-C multi-stage configurations for particulate and microbial control.
Market Restraints
- Copper and rare-earth magnet volatility:Compressor motor inputs face price swings that erode margins for assembly-reliant entrants lacking captive component production.
- Import concentration in refrigeration-grade steel:Korean and Japanese suppliers control specialty alloy supply for heat exchanger coils, exposing domestic fabricators to forex and tariff risk.
- Filter media technical limitations:Domestic non-woven synthetic production cannot yet match Korean and German suppliers on HEPA efficiency-to-pressure-drop ratios.
Strategic Opportunities
- Tier-2 and tier-3 city penetration:Underpenetrated markets in Madhya Pradesh and Rajasthan present first-mover advantages for brands with rural distribution infrastructure.
- CEA efficiency norm alignment:Industrial cooling system specifications for large-scale deployments create specification advantages for domestic manufacturers meeting Bureau of Energy Efficiency standards.
- Online channel convergence:E-commerce platforms are capturing disproportionate residential growth, enabling direct-to-consumer brands to bypass traditional dealer networks.
Industry Challenges
- BIS testing protocol revisions:Evolving certification timelines create inventory uncertainty for channel partners managing multiple product generations.
- Skill scarcity in refrigeration system integration:Qualified technicians for industrial chiller and dehumidifier installation remain concentrated in Maharashtra and Karnataka, constraining national deployment speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Air Treatment Products Market |
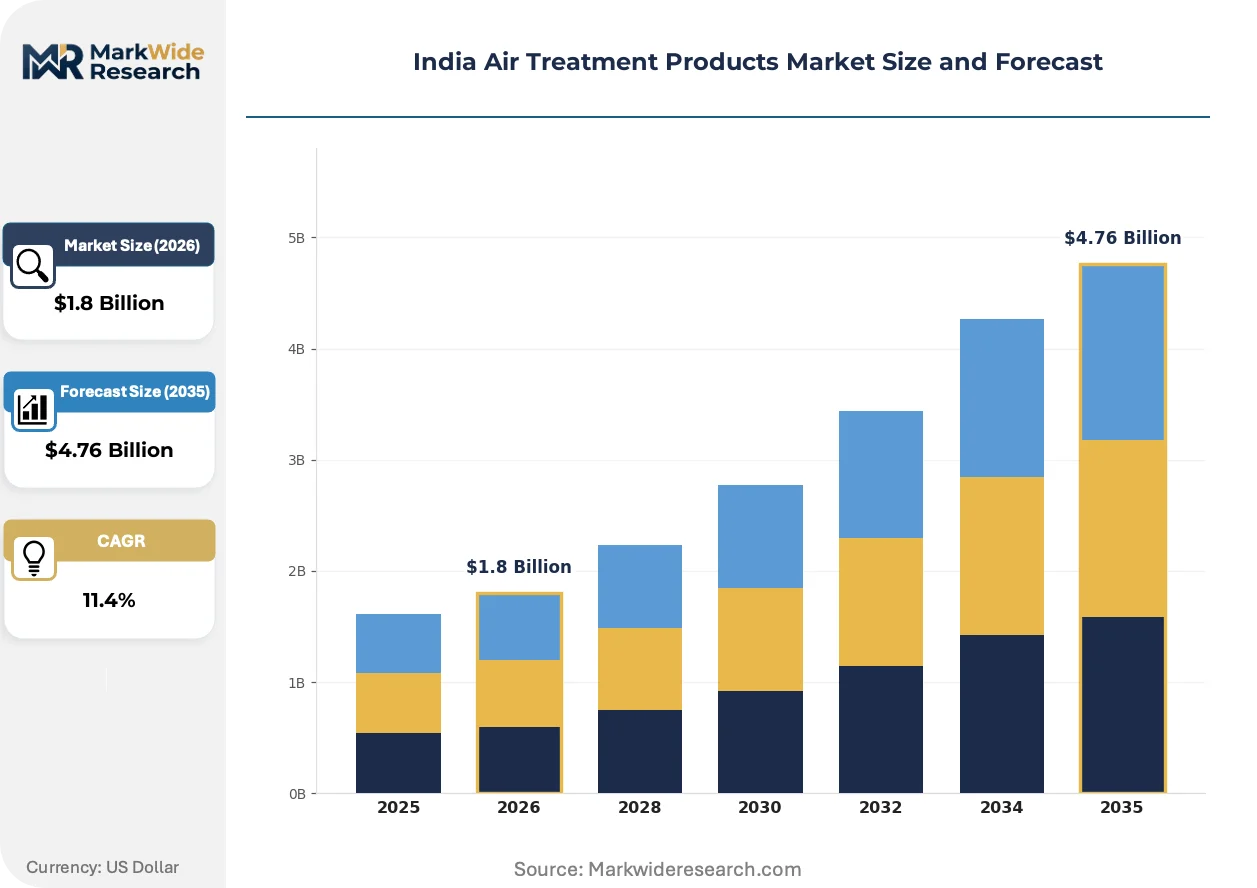
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Purifiers, Humidifiers, Dehumidifiers, Air Conditioners Technology: HEPA, Activated Carbon, UV-C, Ionizer End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Daikin Industries Ltd, Honeywell International Inc, Koninklijke Philips NV, Dyson Ltd, Panasonic Corporation, Xiaomi Corporation, Eureka Forbes Ltd, Havells India Ltd, Blue Star Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Air Treatment Products Market Shifts & Advancements
Electrochemical sensor integration and IoT-enabled predictive maintenance are redefining product value propositions, while regulatory pressure on embodied carbon is reshaping supplier qualification criteria across the value chain.
Photocatalytic oxidation technology is bifurcating the residential air purifier segment. Systems incorporating titanium dioxide-coated substrates and UV-A activation are penetrating premium installations in Delhi NCR and Mumbai. This capability split is compressing demand for basic HEPA-only units while enabling margin expansion for multi-stage configurations that combine particulate, VOC, and microbial control.
Bureau of Indian Standards mandates under the Compulsory Registration Scheme are tightening energy performance and safety testing protocols for electronic air treatment equipment. Manufacturers must now submit to extended laboratory validation cycles before market entry. The commercial segment faces the steepest compliance burden, with hospitals and pharmaceutical cleanrooms demanding documentation traceability that exceeds residential certification requirements.
After-sales service unbundling is disrupting traditional dealer economics in the residential channel. Direct-to-consumer brands are offering filter subscription programs and remote diagnostics through mobile applications, displacing the margin that authorized service networks previously captured on replacement cycles. This behavioral shift is most visible in Bangalore and Pune, where tech-savvy buyers prioritize convenience over established brand relationships.
India Air Treatment Products Market Segmentation
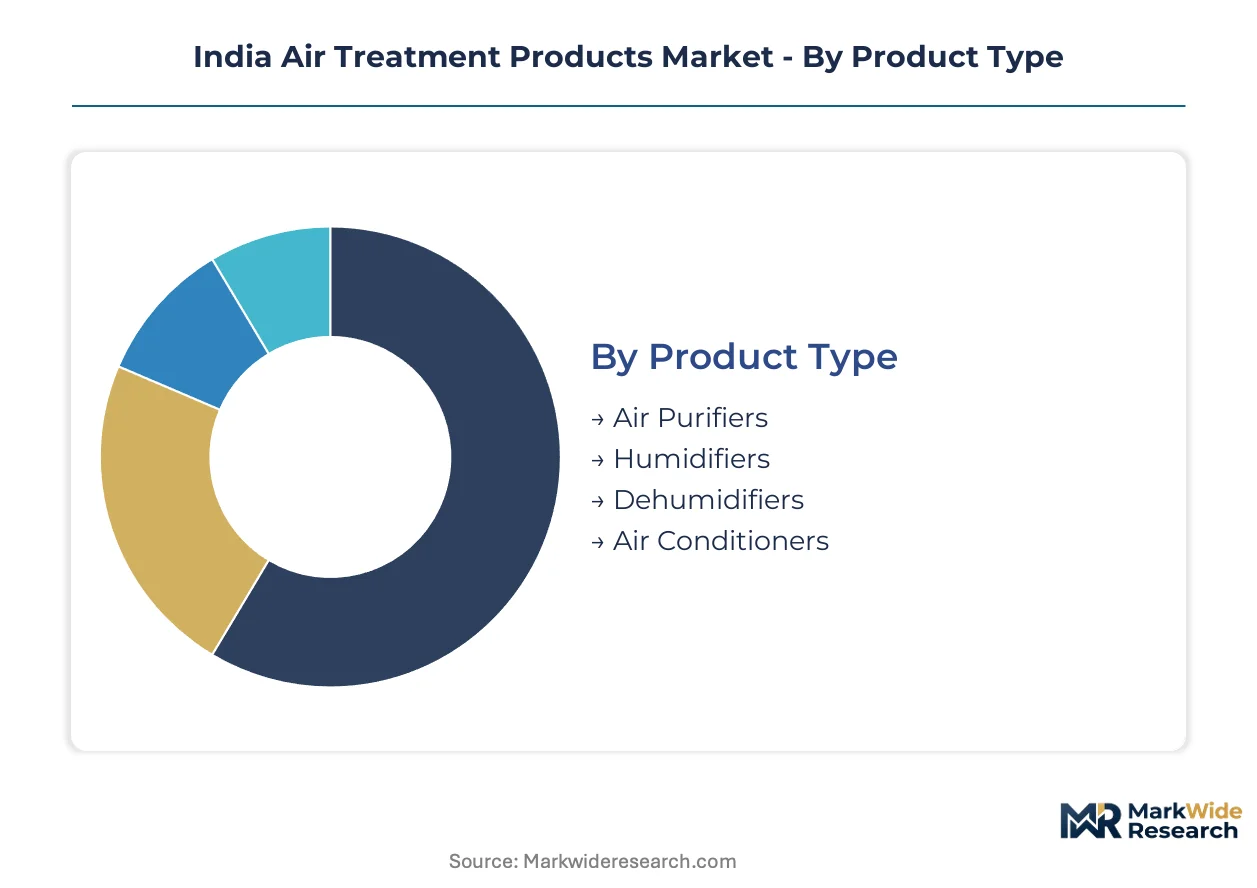
Segmentation in India's air treatment sector reveals how regulatory pressure, distribution economics, and end-use specifications fragment addressable markets. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
BIS Compulsory Registration Scheme mandates apply differentially across electromechanical categories, with electronic air purifiers facing the strictest energy performance testing protocols while compressor-based systems navigate CEA efficiency norms.
- Air Purifiers:HEPA and multi-stage filtration systems dominate residential volume in Delhi NCR and Mumbai where AQI deterioration accelerates replacement cycles. BIS certification timelines now extend laboratory validation periods, compressing shelf space for non-compliant brands in modern trade channels.
- Air Conditioners:Split and window units integrate compressor technology where PLI scheme disbursements are redirecting component sourcing toward Gujarat and Tamil Nadu manufacturing clusters. Captive production of rotary compressors separates margin-resilient incumbents from assembly-reliant entrants facing copper and rare-earth magnet volatility.
- Humidifiers:Ultrasonic and evaporative designs serve pharmaceutical cleanrooms and residential winter markets in northern India.
- Dehumidifiers:Desiccant and refrigeration-based systems address industrial process integrity in coastal Maharashtra and Karnataka data centers.
Air conditioners handle the majority of throughput; air purifiers are gaining share fastest on regulatory consolidation and metropolitan health awareness.
Technology:
Cost tier stratification separates premium multi-stage configurations from basic single-technology units, with price-to-performance ratios determining penetration depth across residential versus commercial end-uses.
- HEPA:High-efficiency particulate absorption media rated from H11 to H14 specifications remain the volume baseline for residential installations. Domestic non-woven synthetic production cannot yet match Korean and German suppliers on efficiency-to-pressure-drop ratios, constraining margin expansion for local fabricators.
- Activated Carbon:Adsorption systems for VOC and odor control penetrate premium commercial specifications in hospitals and hyperscale data centers across Hyderabad and Chennai. Multi-stage configurations combining carbon with HEPA and UV-C command pricing premiums that basic filtration cannot approach.
- UV-C:Ultraviolet germicidal irradiation systems face growing specification in pharmaceutical cleanrooms and healthcare facilities.
- Ionizer:Electrostatic precipitation technologies occupy economy-tier residential positioning with limited BIS certification complexity.
HEPA technology anchors current volume; activated carbon configurations are expanding most quickly on commercial segment demand for multi-stage treatment.
End User:
Application maturity varies sharply, with industrial deployments requiring extended documentation traceability that exceeds residential certification requirements while automotive integration remains nascent.
- Residential:Metropolitan clusters in Maharashtra, Delhi NCR, and Karnataka concentrate demand for HEPA and multi-stage systems as urban AQI deterioration shortens replacement cycles. Online distribution channels are capturing disproportionate growth here, enabling direct-to-consumer brands to bypass traditional dealer networks through filter subscription programs and remote diagnostics.
- Commercial:Hospitals, data centers, and pharmaceutical cleanrooms specify activated-carbon and UV-C multi-stage configurations with documentation requirements that exceed residential standards. This segment represents the steepest margin pool as specification complexity limits viable supplier bases.
- Industrial:Large-scale cooling and dehumidification systems face CEA efficiency norms that create specification advantages for domestic manufacturers meeting Bureau of Energy Efficiency standards.
- Automotive:Cabin air filtration integration remains underdeveloped relative to global benchmarks, presenting forward opportunity as OEM specification tightens.
Residential channels move the greatest unit volume; commercial specifications are climbing the fastest on margin expansion and compliance-driven supplier consolidation.
Distribution Channel:
Customer type and geography interact to fragment channel economics, with urban tech-savvy buyers prioritizing convenience while project-based industrial contracts retain relationship-driven procurement patterns.
- Online:E-commerce platforms capture disproportionate residential growth in Bangalore and Pune where mobile-enabled filter subscriptions and remote diagnostics displace authorized service network margins. Direct-to-consumer brands leverage this channel to bypass tiered dealer structures entirely.
- Retail:Modern trade and electronics specialty stores dominate tier-2 and tier-3 city penetration where Eureka Forbes and similar brands deploy deep rural distribution infrastructure. BIS certification mandates are consolidating shelf space for compliant manufacturers here.
- Direct Sales:Project-based industrial contracts for chillers, dehumidifiers, and cleanroom systems require relationship-driven procurement with extended service agreements.
- Wholesale:Bulk procurement channels serve contractor networks and institutional buyers with volume pricing structures.
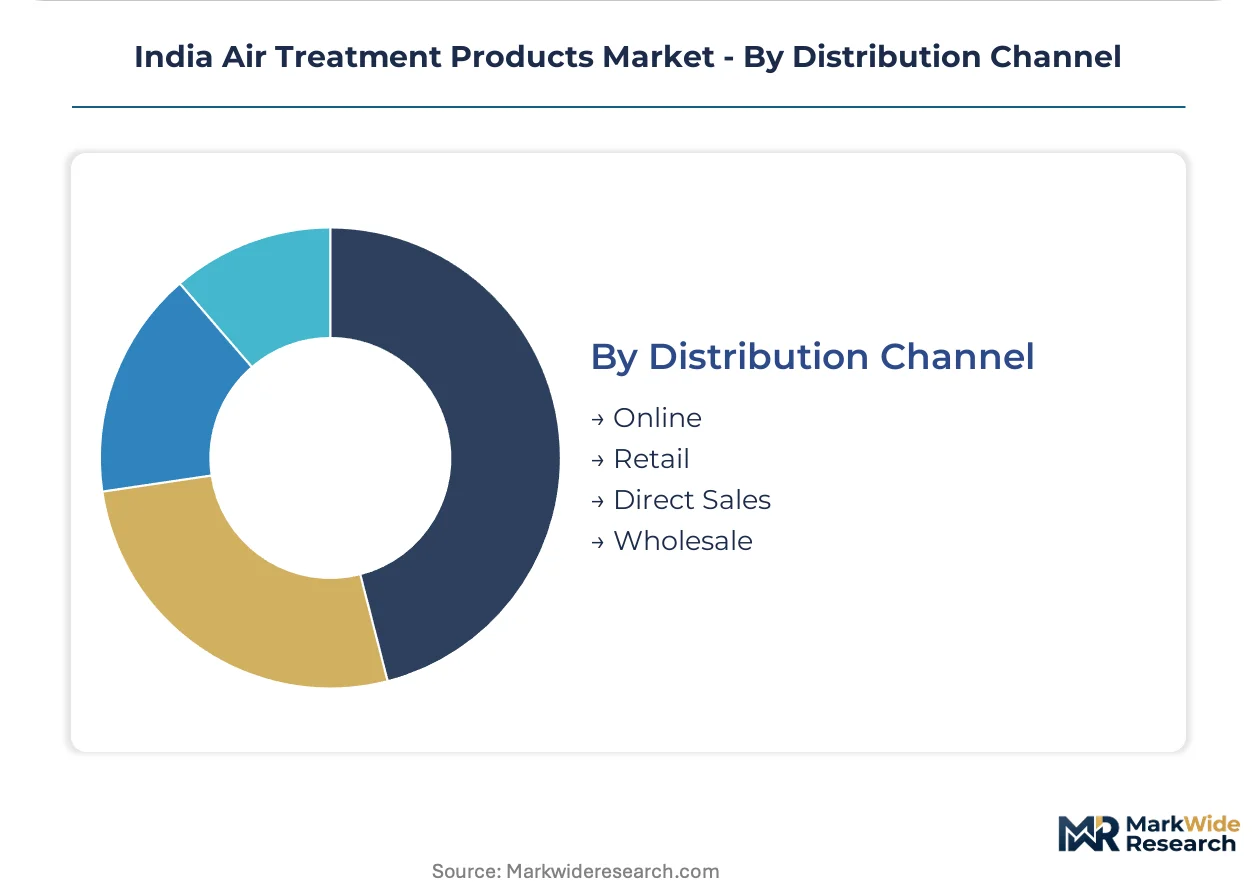
Retail maintains the widest geographic footprint; online channels are gaining share fastest on metropolitan convenience preference and subscription model traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Indian states, with metropolitan buyers absorbing premium multi-stage systems while tier-3 markets gravitate toward basic filtration units. This demand bifurcation shapes regional distribution strategies and margin structures.
Maharashtra
Mumbai's deteriorating AQI drives replacement cycles for HEPA systems in residential high-rises. BIS Compulsory Registration Scheme mandates eliminate non-compliant brands from modern trade shelves. Pune's IT corridor accelerates adoption of IoT-enabled purifiers with subscription-based filter services.
Delhi NCR
Seasonal particulate spikes create acute demand surges for activated-carbon and UV-C multi-stage configurations. CEA efficiency norms govern industrial cooling deployments in Gurugram's manufacturing zones. The region's hospital and pharmaceutical cleanroom clusters specify documentation-heavy procurement protocols.
Karnataka
Bangalore's data center expansion specifies precision climate control for hyperscale facilities. PLI scheme disbursements redirect compressor sourcing toward Tamil Nadu-adjacent supply chains. The state's tech-savvy buyer base favors direct-to-consumer brands with mobile-enabled diagnostics over traditional dealer networks.
Gujarat
Industrial dehumidification demand concentrates in Ahmedabad's pharmaceutical and textile processing corridors. State-level building energy codes tighten specifications for large-scale cooling installations. Surat's diamond polishing industry generates specialized air quality requirements for particulate control.
Tamil Nadu
Chennai's automotive and electronics manufacturing clusters drive industrial air treatment specifications. DGFT import monitoring affects refrigeration-grade steel availability for heat exchanger fabrication. Coimbatore's SME density creates fragmented procurement patterns for mid-capacity systems.
India Air Treatment Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive compressor production separating margin-resilient incumbents from assembly-dependent challengers. The market structure rewards backward integration into motors, control systems, and heat exchangers while penalizing brands reliant on ASEAN component imports. Two strategic archetypes dominate: vertically integrated manufacturers with domestic fabrication depth, and distribution-heavy specialists penetrating rural markets through tier-2 and tier-3 infrastructure. Competitive moves center on PLI-linked capacity expansion in Gujarat and Tamil Nadu clusters, and filter subscription models that displace traditional after-sales service margins.
Among Japanese-integrated multinationals, Daikin Industries Ltd exemplifies the captive-production archetype through compressor manufacturing depth. Eureka Forbes Ltd and Havells India Ltd represent contrasting domestic strategies—one anchored in rural distribution density, the other in in-house motor and control-system fabrication. These three occupy distinct competitive positions without overlapping capability profiles.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Honeywell International Inc |
| Koninklijke Philips NV |
| Dyson Ltd |
| Panasonic Corporation |
| Xiaomi Corporation |
| Eureka Forbes Ltd |
| Havells India Ltd |
| Blue Star Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for compressor and heat exchanger capacity lock in supply access for integrated manufacturers while insulating them from copper and rare-earth magnet volatility that erodes assembly-reliant competitors. This contract-structure pattern concentrates pricing power with Daikin Industries Ltd and Havells India Ltd, forcing brands without captive production to absorb margin compression or accelerate backward integration into motors and control systems.
Pricing Analysis
Filter subscription and extended service contracts drive lifetime value as direct-to-consumer brands displace traditional dealer margins. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified multi-stage configurations from basic HEPA units, with certification grade and after-sales bundling as primary differentiation drivers. Cost compression in the economy tier intensifies because domestic non-woven synthetic production cannot match Korean and German HEPA efficiency-to-pressure-drop ratios. Tier-2 and tier-3 buyers exhibit highest price sensitivity, while commercial cleanroom specifications show lowest elasticity due to documentation-heavy procurement protocols.
Supply Chain Analysis
China and South Korea anchor refrigeration-grade steel and specialty alloy production for heat exchanger coils, while Japan and Germany control premium HEPA filter media. Domestic manufacturing draws from copper cathode imports, rare-earth magnets for compressor motors, and Korean synthetic non-wovens. Single-source vulnerability in specialty alloy supply exposes domestic fabricators to forex and tariff risk. Distribution runs through project-based direct sales for industrial contracts, e-commerce platforms for metropolitan residential buyers, and deep rural dealer networks for tier-2 and tier-3 penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where BIS certification entrenchment creates switching costs that lock hospital and pharmaceutical buyers into compliant supplier relationships.
For Market Incumbents: Shield margin resilience by accelerating captive compressor production in Gujarat and Tamil Nadu PLI-linked clusters before copper volatility deepens. Consolidate channel control through filter subscription platforms that displace authorized service network economics, particularly in Bangalore and Pune where tech-savvy buyers prioritize mobile-enabled diagnostics over brand heritage. For New Entrants and Emerging Players: Anchor in tier-2 and tier-3 city penetration across Madhya Pradesh and Rajasthan where Eureka Forbes-style rural distribution infrastructure remains underdeveloped. Target the automotive cabin air filtration segment, which lags global OEM specification benchmarks and presents white-space opportunity before tightening standards close the window. Pursue direct-to-consumer e-commerce launch with subscription-based filter replacement to bypass entrenched dealer networks. For Investors and Strategic Acquirers: Distribution-heavy specialists with established tier-2 and tier-3 infrastructure command scarcity premium as online brands struggle to replicate rural penetration. Long-term viability hinges on regulatory entrenchment through BIS certification depth and PLI-linked domestic component ecosystems. Monitor PLI scheme disbursement velocity as inflection indicator for capital reallocation toward backward-integrated manufacturing archetypes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production insulates margins from ASEAN import volatility and copper price swings. |
| Filter Subscription Platform Launch | Direct-to-consumer models displace traditional dealer margins in metropolitan residential channels. |
| BIS Certification Pre-Emption | Extended laboratory validation cycles consolidate shelf space for compliant manufacturers in modern trade. |
| Tier-2 and Tier-3 Distribution Expansion | Rural infrastructure density captures underpenetrated demand in Madhya Pradesh and Rajasthan. |
| Multi-Stage Configuration Development | Activated-carbon and UV-C combinations command premium pricing in hospital and data center specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS registration databases, DGFT import monitoring records, and CEA efficiency norm filings. Interviews with compressor manufacturing executives, HVAC procurement leads at hyperscale data centers, pharmaceutical cleanroom engineering directors, and aftermarket service network heads inform demand-side validation. Secondary sources include Bureau of Energy Efficiency technical circulars, PLI scheme disbursement disclosures, and state-level building energy code notifications. Bottom-up product-level shipment analysis triangulates against top-down manufacturing capacity assessments across Gujarat and Tamil Nadu clusters.
Segmentation dimensions modeled span product type, technology tier, end-use application, and distribution channel across the analysis window. The analytical framework incorporates residential replacement cycle dynamics driven by metropolitan AQI deterioration, commercial specification complexity in healthcare and data center verticals, and channel shift velocity toward e-commerce platforms. CAGRs derive from installed base growth, penetration rate assumptions, and price trajectory modeling for component-intensive versus assembly-reliant competitive archetypes. Industry-specific inputs include BIS testing protocol revision timelines and PLI-linked domestic component sourcing shifts.
Decision-makers should treat outputs as directional under assumptions of sustained BIS enforcement stringency and PLI scheme continuity; material deviation in regulatory timelines or component import policy would warrant model refresh. Specific risks include abrupt BIS protocol revisions extending certification cycles, copper and rare-earth magnet price spikes compressing assembler margins, and state-level building energy code fragmentation complicating national product strategies. Recalibration cycles align with material shifts in PLI disbursement velocity and BIS laboratory capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Fumigant Products Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Global Animal Disinfectants Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Asia-Pacific Agricultural Disinfectants Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Global Mold Inhibitors Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market