
 Salon Disinfectants Market | 2026-2036
Salon Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Salon Disinfectants Market Analytics
Buyer concentration among multi-location salon chains is realigning procurement toward enterprise-grade disinfectant contracts. Ecolab leverages its institutional hygiene infrastructure to serve national franchise networks. Clorox Professional Products Company anchors retail distribution through big-box salon supply channels. Diversey Holdings, Ltd. competes on concentrated formulations that reduce shipping costs for high-volume buyers.
Salon disinfectants are antimicrobial formulations designed to eliminate pathogens on non-porous surfaces, tools, and skin-contact equipment in personal care settings, typically achieving bactericidal, virucidal, and fungicidal efficacy within standardized contact times. Instrument disinfectants lead product-type revenue due to mandatory autoclave-alternative protocols for metal tools between clients. Wipes represent the fastest-growing form segment as technicians prioritize single-use convenience over mixing concentrates. Hair salons dominate application demand, though barbershops show rising per-visit consumption as beard-service sanitation standards tighten.
EPA registration under FIFRA governs efficacy claims and label compliance for salon disinfectants sold in the United States, while OSHA bloodborne pathogen standards mandate workplace exposure controls. State cosmetology boards enforce inspection protocols that penalize non-compliant sanitation logs, directly shaping repurchase frequency. Stakeholders must monitor evolving hospital-grade efficacy expectations migrating from medical settings into personal care licensing requirements.
Market Dynamics
Hospital-grade efficacy standards are migrating from medical settings into personal care licensing requirements, forcing formulation upgrades and supplier consolidation across the salon disinfectants supply base.
Growth Catalysts
- State Cosmetology Board Mandates:California, Texas, and Florida now require documented sanitation logs with EPA-registered disinfectants, directly accelerating repurchase frequency among licensed salons.
- Nail Salon Procurement Acceleration:Faster tool-turnover protocols in nail services are driving demand for hospital-grade instrument disinfectants as autoclave alternatives.
- Beard-Service Sanitation Standards:Tightening hygiene protocols in barbershops for facial hair services are expanding per-visit disinfectant consumption beyond traditional hair salons.
Market Restraints
- EPA Registration Timelines:FIFRA compliance requirements create 12-18 month delays for new disinfectant formulations entering the United States market.
- Quaternary Ammonium Compound Supply:Concentrated QAC feedstock availability fluctuates with industrial chemical production cycles, squeezing margin stability for concentrate manufacturers.
- Autoclave Residual Demand:Some state boards still permit heat sterilization for metal instruments, limiting complete displacement by chemical disinfectants in certain jurisdictions.
Strategic Opportunities
- Single-Use Wipe Formats:Pre-saturated disinfectant wipes eliminate mixing errors and appeal to technician convenience preferences in high-turnover service environments.
- Multi-Location Chain Contracts:Enterprise procurement consolidation among national franchise networks favors suppliers with institutional-scale logistics infrastructure.
- Concentrated Formulation Shipping:Dilutable concentrates reduce freight costs and carbon footprint for high-volume buyers in remote or distributed salon networks.
Industry Challenges
- OSHA Bloodborne Pathogen Training:Salon operators struggle to maintain compliant exposure control plans and documentation across high staff-turnover environments.
- Cross-Contamination Protocol Adherence:Technicians frequently bypass full contact-time requirements between clients, creating liability exposure and regulatory audit risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salon Disinfectants Market |
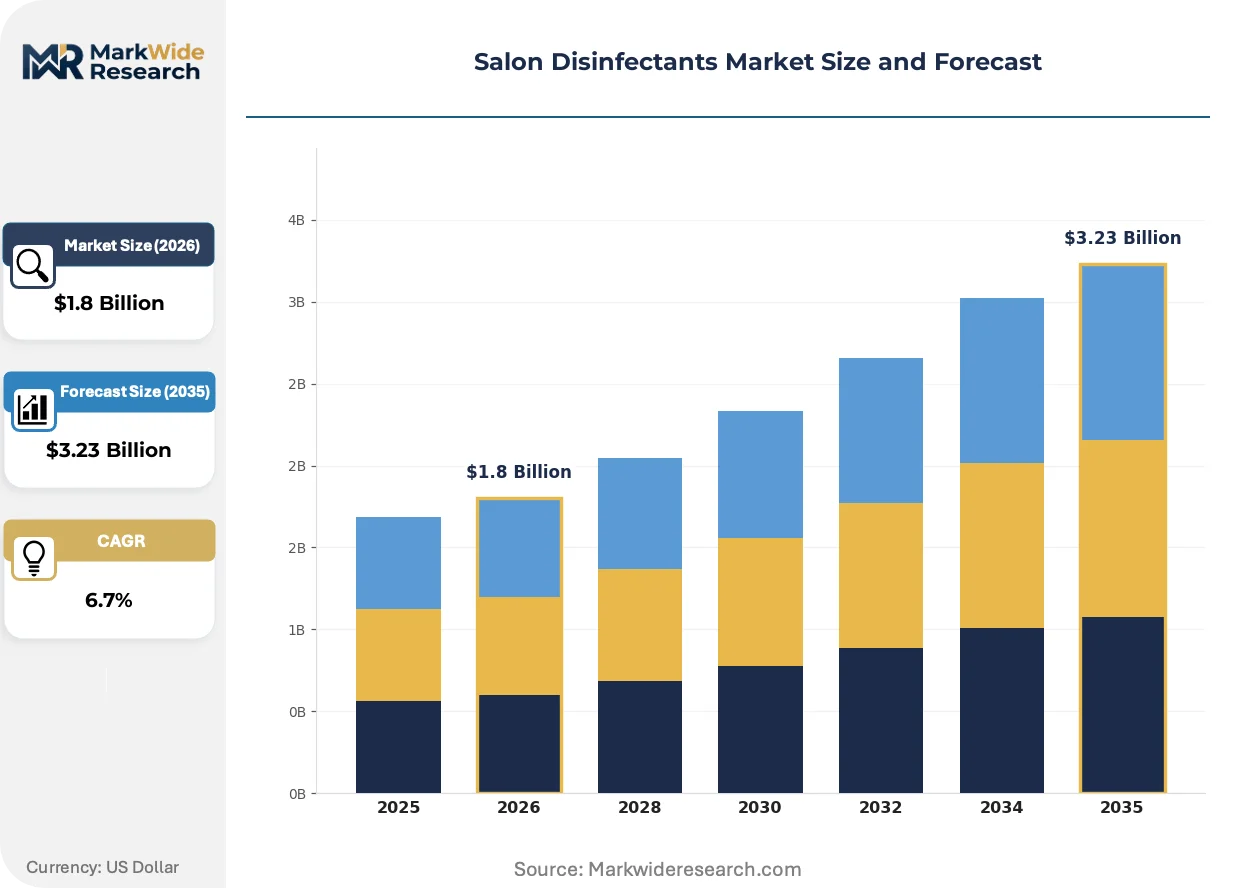
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Disinfectants, Instrument Disinfectants, Hand Sanitizers, Fogging Solutions Application: Hair Salons, Nail Salons, Spas, Barbershops Form: Aerosols, Liquids, Wipes, Concentrates End User: Salon Owners, Technicians, Customers, Distributors |
| Companies Covered | Barbicide, Clorox Professional Products Company, Diversey Holdings, Ltd., Ecolab, Zep Inc., Reckitt Benckiser Group plc, 3M Company, The Procter & Gamble Company, GOJO Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salon Disinfectants Market Evolving Landscape
Formulation chemistry, regulatory stringency, and procurement centralization are converging to reshape competitive positioning in salon disinfectants, with convenience formats and compliance automation emerging as primary differentiation vectors.
Accelerated hydrogen peroxide formulations are rewriting efficacy benchmarks for salon surface disinfection. Nail salons and barbershops are adopting these chemistries faster than hair salons due to shorter service intervals. The technology is compressing the viable shelf life of legacy phenolic and alcohol-based alternatives.
EPA's evolving guidance on emerging viral pathogens is tightening label claim requirements for disinfectants marketed to personal care settings. Manufacturers must now submit additional efficacy data for enveloped viruses, extending registration timelines. Instrument disinfectants face the steepest compliance burden as states align licensing exams with hospital-grade standards.
Buyer concentration among multi-location chains is consolidating supplier relationships around enterprise-grade contracts with compliance reporting features. Independent distributors and small-format retailers are losing share to direct procurement platforms. California and Texas exhibit the most pronounced shift as franchise density concentrates in these states.
Salon Disinfectants Market Segmentation
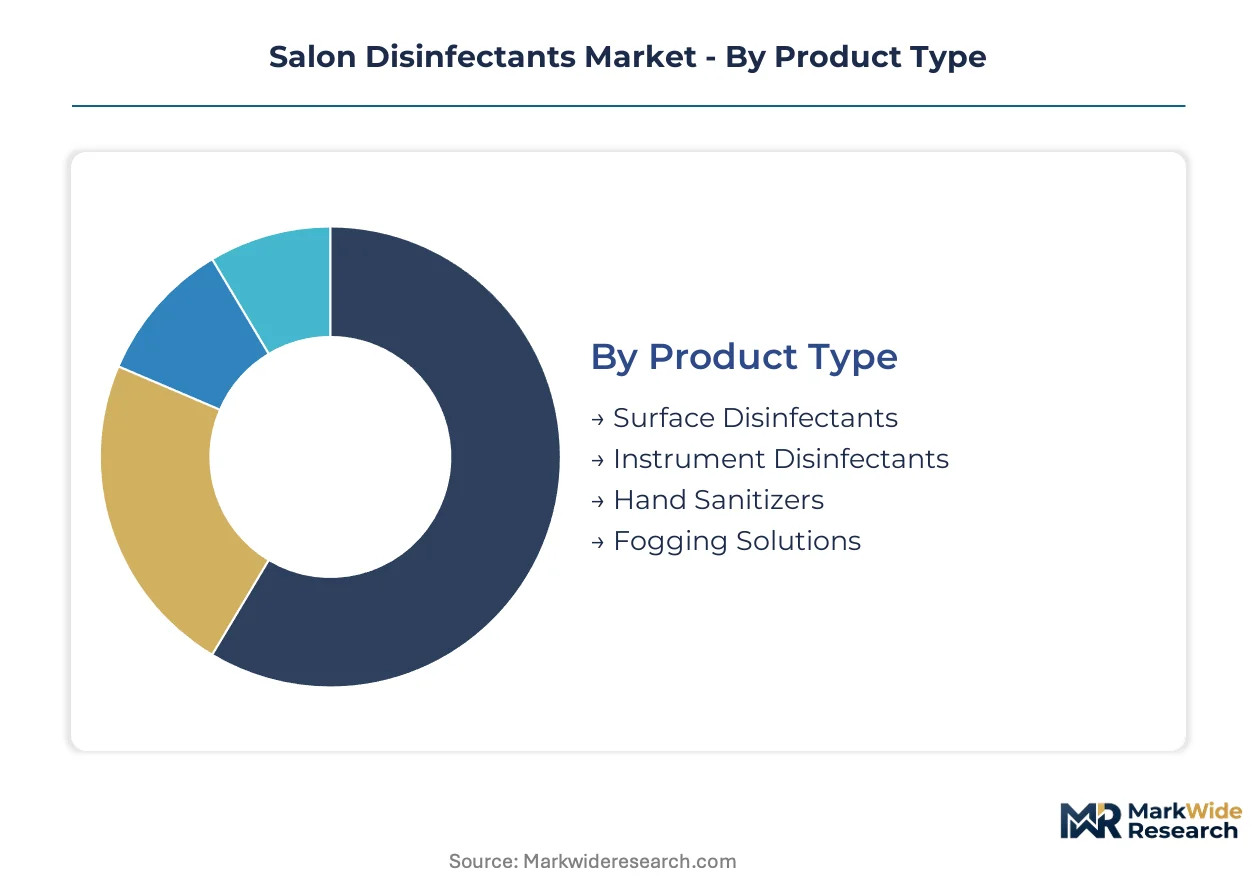
Salon disinfectant procurement patterns diverge sharply across product chemistry, service application, and user workflow. Each segmentation axis reveals distinct margin structures and compliance burdens that reshape supplier priorities.
Product Type:
Supply concentration tilts toward instrument-grade formulations as state boards tighten autoclave-alternative mandates.
- Surface Disinfectants:Broad-spectrum antimicrobial solutions formulated for countertops, chairs, and non-porous workstation surfaces. Demand clusters in California and Texas where inspection log requirements are most stringent.
- Instrument Disinfectants:High-level chemistries achieving sporicidal efficacy on metal tools between clients. Nail salons in Florida drive fastest uptake as faster service turnover compresses sterilization windows.
- Hand Sanitizers:Alcohol-based or benzalkonium chloride formulations for technician hand hygiene between procedures.
- Fogging Solutions:Aerosolized or ultra-low volume dispensing systems for whole-room sanitation protocols.
Today's leader: Instrument Disinfectants. Tomorrow's challenger: Fogging Solutions.
Application:
Volume concentration tracks salon density per capita, with service-type differentiation driving format preferences.
- Hair Salons:The largest installed base of disinfectant consumption, dominated by surface wipes and spray formats for workstation turnover. California's franchise concentration sustains enterprise procurement contracts.
- Nail Salons:Specialized demand for rapid-cycling instrument disinfectants as dip-powder and gel services accelerate tool reuse frequency. Texas leads nail salon density nationally.
- Spas:Premium-positioned facilities requiring extended-contact surface disinfectants for treatment rooms.
- Barbershops:Rising per-visit consumption driven by beard-service sanitation standards tightening across Florida and Texas licensing jurisdictions.
Hair Salons anchor current procurement volume. Nail Salons are gaining share fastest on hospital-grade migration.
Form:
Margin concentration favors concentrates for high-volume buyers, while convenience premiums accrue to single-use formats.
- Aerosols:Pressurized spray delivery for rapid surface coverage in high-turnover stations.
- Liquids:Ready-to-use pour bottles dominating independent salon procurement through distributor channels.
- Wipes:Pre-saturated substrates eliminating mixing errors and contact-time compliance gaps. Technician preference in multi-station franchises is climbing the fastest.
- Concentrates:Dilutable formulations reducing freight costs for national chains with centralized supply operations.
Wipes command the steepest convenience premium. Concentrates deliver the strongest unit economics at scale.
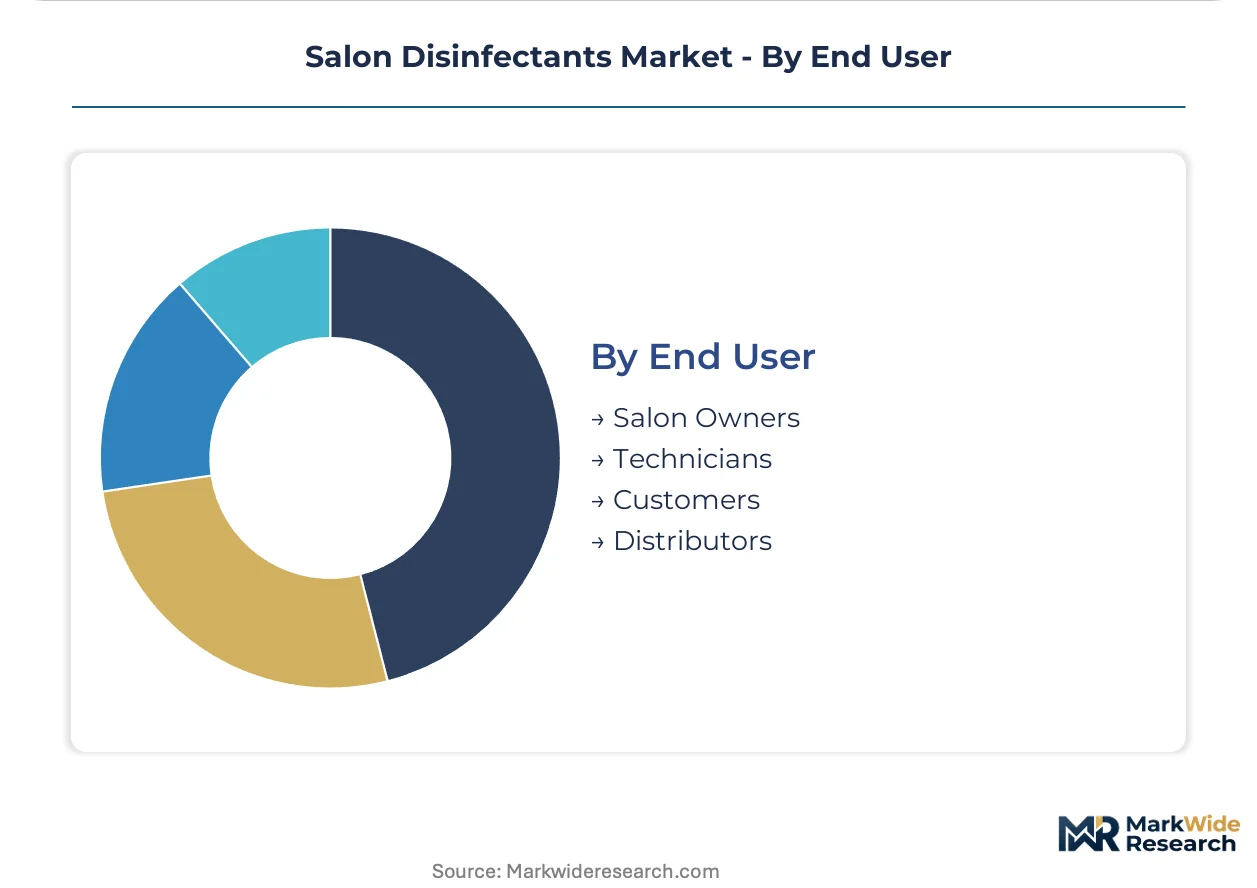
End User:
Procurement authority concentration among multi-location owners is displacing technician-driven purchasing.
- Salon Owners:Enterprise-grade contract negotiators prioritizing compliance documentation and bulk pricing. National franchise networks in California and Texas dominate this segment.
- Technicians:Individual practitioners selecting convenience formats for personal workstation efficiency. Wipes and small-volume sprays dominate their preference set.
- Customers:Minimal direct procurement, though visible sanitation protocols influence service provider selection.
- Distributors:Intermediaries consolidating independent salon demand, losing share to direct manufacturer platforms.
Salon Owners control the largest contract value. Technicians drive the steepest format innovation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed cosmetologists concentrate in states with dense urban populations and high service-sector employment, creating procurement gravity around inspection-intensive jurisdictions. Salon disinfectant demand tracks directly to workforce density and state board enforcement rigor.
United States
California, Texas, and Florida host the nation's highest salon density per capita, with California's Board of Barbering and Cosmetology mandating documented sanitation logs that accelerate repurchase cycles. EPA registration under FIFRA governs all efficacy claims, while OSHA bloodborne pathogen standards enforce workplace exposure controls. Los Angeles and Miami metropolitan clusters drive enterprise contract consolidation among multi-location chains.
Canada
Provincial cosmetology associations in Ontario and British Columbia are adopting hospital-grade disinfection standards aligned with Health Canada guidance. Health Canada's PMRA regulates antimicrobial product claims, creating parallel compliance burdens to the US EPA system. Toronto and Vancouver salon concentrations favor concentrated formulations that reduce cross-border freight costs.
Germany
The Federal Institute for Drugs and Medical Devices enforces medical-grade hygiene expectations that migrate into personal care licensing through state chamber of commerce regulations. REACH compliance adds formulation chemistry constraints distinct from North American requirements. Berlin and Munich salon networks demonstrate early adoption of accelerated hydrogen peroxide technologies.
United Kingdom
The Health and Safety Executive's COSHH regulations intersect with local authority environmental health inspections to create layered compliance for salon operators. British Beauty Council standards increasingly reference NHS-grade disinfection protocols. London's franchise salon density supports direct procurement platform growth at distributor expense.
France
ANSM oversight of biocidal products under EU BPR creates registration complexity for disinfectant suppliers entering the French market. Regional health agencies in Île-de-France and Provence-Alpes-Côte d'Azur conduct unannounced salon inspections with sanitation documentation requirements. Paris luxury spa segments sustain premium pricing for extended-contact surface formulations.
Salon Disinfectants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Institutional hygiene conglomerates leverage logistics infrastructure to capture national franchise contracts, while chemical specialists compete on concentrated formulation economics. Three archetypes dominate: diversified industrial hygiene providers, retail-distributed consumer brands, and formulation-focused chemical specialists. Capacity expansion and compliance automation represent the dominant competitive moves as registration timelines lengthen.
Among diversified industrial hygiene providers, Ecolab and Diversey Holdings, Ltd. exemplify the institutional-scale archetype with enterprise contract capabilities. Clorox Professional Products Company anchors retail distribution through established big-box salon supply channels. These three occupy positions spanning direct institutional sales, concentrated formulation supply, and mass-market accessibility respectively.
| Leading Market Players |
|---|
| Barbicide |
| Clorox Professional Products Company |
| Diversey Holdings, Ltd. |
| Ecolab |
| Zep Inc. |
| Reckitt Benckiser Group plc |
| 3M Company |
| The Procter & Gamble Company |
| GOJO Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Hospital-grade versus standard-grade efficacy certification splits procurement into two distinct pricing bands, with EPA-registered formulations commanding premium positioning through specialized distribution while commodity concentrates compete on freight-adjusted unit economics in high-volume chain contracts.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for instrument-grade disinfectants as regional formulators expand production to serve nail salon density. Three-tier pricing structure across premium hospital-grade, standard EPA-registered, and economy non-registered levels tracks directly to state board enforcement rigor. Cost compression in the economy tier intensifies because independent distributors consolidate purchasing power. National franchise networks exhibit lowest price sensitivity; independent technicians show highest sensitivity to per-wipe premiums.
Supply Chain Analysis
EPA registration and state cosmetology board qualification requirements gate supplier participation, forcing raw material traceability through documented chemical sourcing. Quaternary ammonium compound production concentrates in the United States, Germany, and China, with formulation finishing distributed across regional blending facilities. Supply chains draw from isopropyl alcohol, benzalkonium chloride, and hydrogen peroxide feedstocks. Single-source vulnerability exists for accelerated hydrogen peroxide precursor chemicals. Distribution runs through direct manufacturer platforms for national chains, independent distributors for standalone salons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory intensity into procurement frequency, with California's documented sanitation log mandate accelerating repurchase cycles and compressing supplier switching costs.
For Market Incumbents: Anchor enterprise contract retention by embedding compliance automation features that generate inspection-ready documentation for multi-location salon operators. Deepen backward integration into quaternary ammonium compound production to offset feedstock volatility squeezing concentrate margins. Counter direct procurement platform growth by acquiring independent distributors with dense technician relationships in Florida and Texas. For New Entrants and Emerging Players: Direct-to-technician subscription platforms represent the most penetrable route, bypassing entrenched distributor relationships by delivering pre-saturated wipe formats on predictable replenishment schedules. Target nail salon independents in Texas where hospital-grade migration outpaces established supplier coverage. Lead with contact-time compliance apps that log usage automatically for state board inspections. For Investors and Strategic Acquirers: Consolidation pressure builds where EPA registration timelines exceed 18 months and smaller formulators lack capital to navigate emerging viral pathogen efficacy requirements. Acquisition candidates with existing FIFRA registrations and concentrated formulation capabilities offer strongest long-term viability across the projection horizon. Monitor California Board of Barbering and Cosmetology rulemaking as the inflection signal for hospital-grade standard adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Investment | Accelerates market access by satisfying FIFRA compliance requirements before state board rule changes tighten. |
| Concentrated Formulation Capacity | Reduces freight costs for national salon chains with centralized supply operations in California and Texas. |
| Compliance Automation Platform | Generates inspection-ready sanitation logs that satisfy California and Florida cosmetology board mandates. |
| Direct Procurement Channel | Bypasses independent distributors losing share to manufacturer platforms in Los Angeles and Miami metro clusters. |
| Accelerated Hydrogen Peroxide R&D | Positions suppliers ahead of legacy phenolic displacement in nail salons and barbershops with shorter service intervals. |
Research Methodology
Coverage spans the United States, Canada, Germany, the United Kingdom, and France, with primary inputs from each jurisdiction combined with secondary validation. Interviews with salon chain procurement directors, state cosmetology board inspectors, EPA registration consultants, and independent distributor principals anchored demand-side and regulatory intelligence. Secondary sources included EPA FIFRA registration databases, OSHA bloodborne pathogen guidance documents, state board inspection protocols, and customs trade data on quaternary ammonium compound imports. Bottom-up salon density modeling and top-down chemical consumption estimates were triangulated against manufacturer shipment disclosures.
Granularity-level modeling captured product type, application segment, form factor, and end-user procurement authority across national and sub-national geographies. Segmentation dimensions included instrument versus surface disinfectant chemistry, hair salon versus nail salon versus barbershop service type, and wipes versus concentrates versus liquids versus aerosols. CAGRs were derived from regression analysis on historical procurement frequency data adjusted for regulatory mandate implementation schedules. Forecast inputs incorporated EPA registration pipeline timelines and state cosmetology board rulemaking calendars.
The model assumes a particular technology adoption path for accelerated hydrogen peroxide formulations; alternative pathways for legacy phenolic retention would alter the outlook for chemistry migration timelines. Forecasts reflect assumptions on state board inspection enforcement intensity and salon chain consolidation rates. A model refresh is warranted upon material change in EPA emerging viral pathogen guidance or California cosmetology board mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Asia-Pacific Agricultural Disinfectants Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Fumigant Products Market
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
Artificial Preservatives Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Disinfecting Wipes Market