
 Antimicrobial Chemicals Market | 2026-2036
Antimicrobial Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Chemicals Market Outlook
Asset-light toll manufacturing and third-party formulation leasing is narrowing the capital barrier for mid-scale entrants in antimicrobial chemical production. BASF SE leverages its integrated petrochemical feedstock position to control quaternary ammonium compound costs across European supply chains. DuPont sustains technology leadership in halogenated biocide stabilization, while Microban International specializes in brand-licensed antimicrobial additive platforms for consumer goods manufacturers.
Antimicrobial chemicals are functional biocides and microbiostatic agents formulated with active ingredients such as quaternary ammonium salts, triclosan derivatives, or silver-ion carriers, designed to inhibit microbial growth on surfaces, in fluids, or within material matrices. These compounds serve industrial and commercial purposes ranging from hospital disinfection protocols to food contact surface preservation and textile odor control. Quaternary ammonium compounds occupy the largest share of product-type revenue due to their broad-spectrum efficacy and compatibility with aqueous delivery systems. The coatings form category is expanding fastest as manufacturers integrate antimicrobial functionality directly into polymer substrates for healthcare and hospitality end users. Agriculture applications remain a developing margin pool, constrained by soil microbiome toxicity concerns and residue accumulation limits.
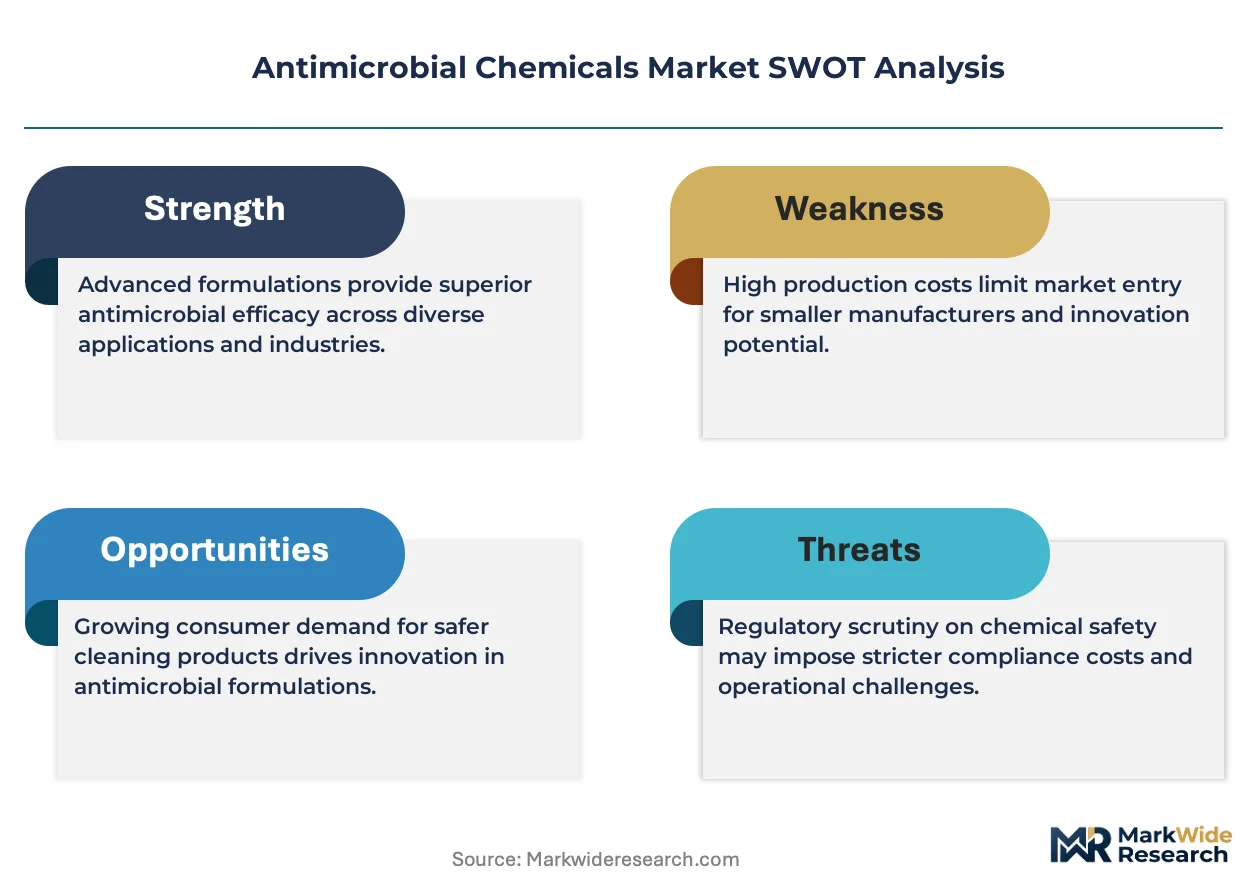
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act govern antimicrobial chemical commercialization in the United States, while REACH authorization processes in Europe restrict legacy biocide actives such as certain isothiazolinones. China's Ministry of Ecology and Environment enforces GB standards for antimicrobial additives in consumer products, creating a fragmented compliance landscape for multinational suppliers. Stakeholders must monitor evolving substance ban lists across EPA, ECHA, and MEE jurisdictions to anticipate reformulation cycles and secure early-mover positions in next-generation active ingredient platforms.
Market Dynamics
REACH authorization timelines and EPA registration bottlenecks are compressing commercialization windows for legacy biocide actives, forcing reformulation investments and supplier consolidation across European and North American supply chains.
Growth Catalysts
- Hospital-acquired infection protocols:Healthcare facilities in the United States, Germany, and China are mandating surface disinfection frequencies that expand quaternary ammonium compound consumption in clinical settings.
- REACH authorization pressure:European ECHA substance bans on isothiazolinones are accelerating migration toward silver-ion and polymeric biguanide alternatives with cleaner toxicological profiles.
- Food contact surface mandates:Food processing regulators in North America and Asia-Pacific are tightening microbial load limits, driving antimicrobial coating integration into conveyor systems and preparation equipment.
Market Restraints
- Petrochemical feedstock volatility:Quaternary ammonium compound production depends on ethylene oxide and fatty alcohol derivatives subject to crude-linked price swings.
- Active ingredient concentration:Three multinational suppliers control over 70% of halogenated biocide precursor manufacturing, creating single-source vulnerability.
- Soil microbiome toxicity:Agricultural applications face residue accumulation limits that restrict dosing rates below economic thresholds for broad-acre crops.
Strategic Opportunities
- Antimicrobial textile licensing:Consumer goods manufacturers in India and Southeast Asia seek brand-affiliated additive platforms for apparel and home furnishing differentiation.
- Dual carbon alignment:China's MEE enforcement of GB standards creates preferential procurement pathways for bio-based and low-VOC antimicrobial formulations.
- Polymer substrate integration:Healthcare device OEMs are embedding silver-ion carriers directly into catheter and implant materials, bypassing surface coating limitations.
Industry Challenges
- EPA registration timelines:New active ingredient approvals under FIFRA require 18-36 month review cycles that delay product launches and strain R&D capitalization.
- Toxicology data generation:Chronic exposure studies and environmental fate modeling demand specialized contract research capabilities scarce outside Western Europe and North America.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Chemicals Market |
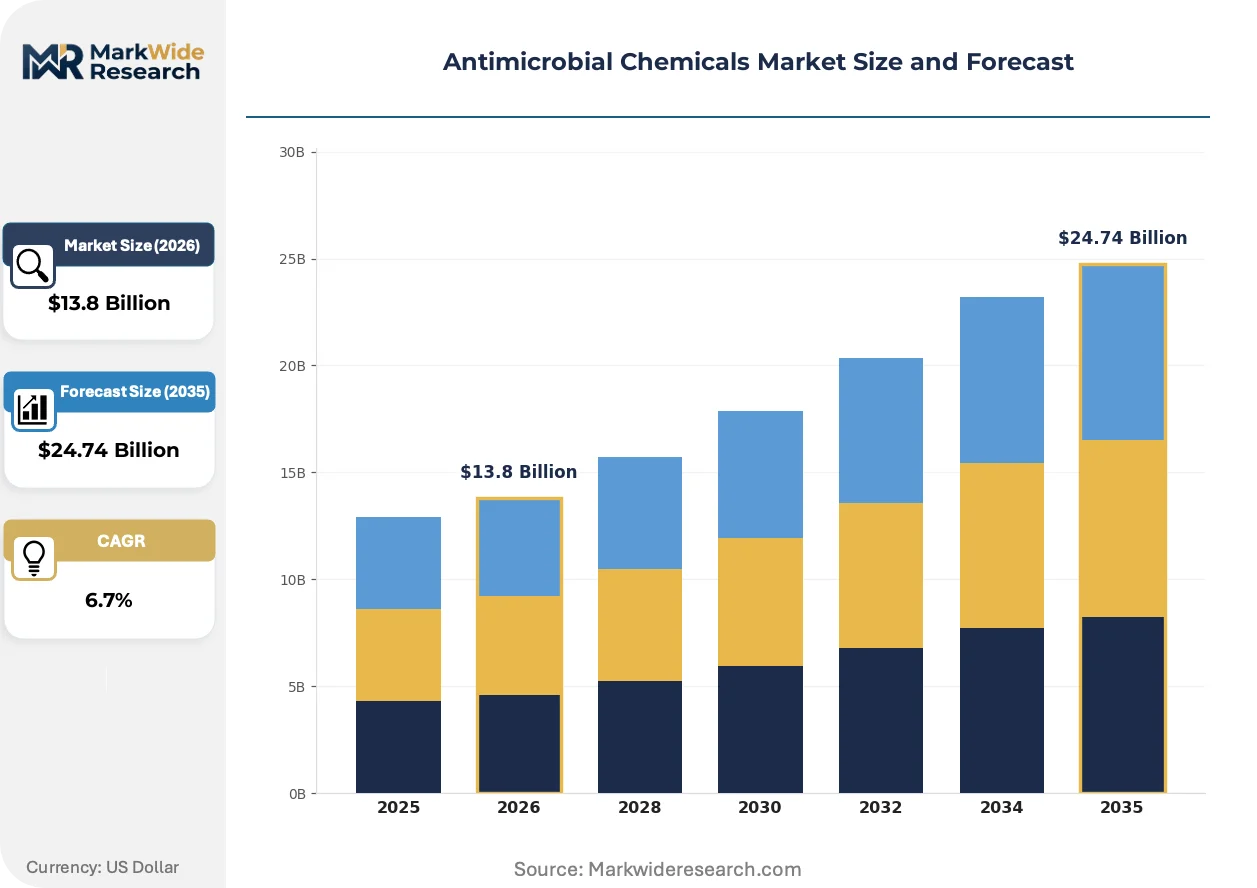
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.74 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Compounds, Halogenated Compounds, Phenolic Compounds, Alcohols Application: Textiles, Food Processing, Water Treatment, Agriculture End User: Healthcare, Hospitality, Manufacturing, Household Form: Aqueous Solutions, Powders, Granules, Coatings |
| Companies Covered | BASF SE, DuPont, Microban International, Sanitized AG, Avient Corporation, Clariant, Milliken & Company, Lonza, Arxada AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Chemicals Market Strategic Shifts
Formulation science is converging with materials engineering as antimicrobial functionality migrates from surface coatings into bulk polymer matrices, reshaping competitive capabilities across chemical and manufacturing value chains.
Encapsulation technologies using cyclodextrin and liposome carriers are digitizing release kinetics for silver-ion and triclosan alternatives, enabling sustained antimicrobial efficacy over 90-day cycles. Medical device manufacturers in Germany and Switzerland are qualifying these systems for implantable applications. The technology is digitizing quality assurance protocols by embedding RFID-readable batch codes directly into coating substrates.
ECHA's 2024-2027 substance evaluation roadmap is accelerating phase-outs of CMH-activated biocides across European industrial cleaning applications. Manufacturers are pre-registering replacement actives under the Biocidal Products Regulation to secure transitional supply continuity. Coatings formulators serving hospitality and transportation sectors face the most compressed reformulation timelines.
Healthcare procurement consortiums are consolidating supplier panels around vertically integrated chemical manufacturers with in-house toxicology and regulatory affairs capabilities. Group purchasing organizations in the United States are disqualifying toll-manufactured formulations without direct active ingredient sourcing transparency. This concentration is most visible in acute care networks across Texas, California, and Florida hospital systems.
Antimicrobial Chemicals Market Segmentation
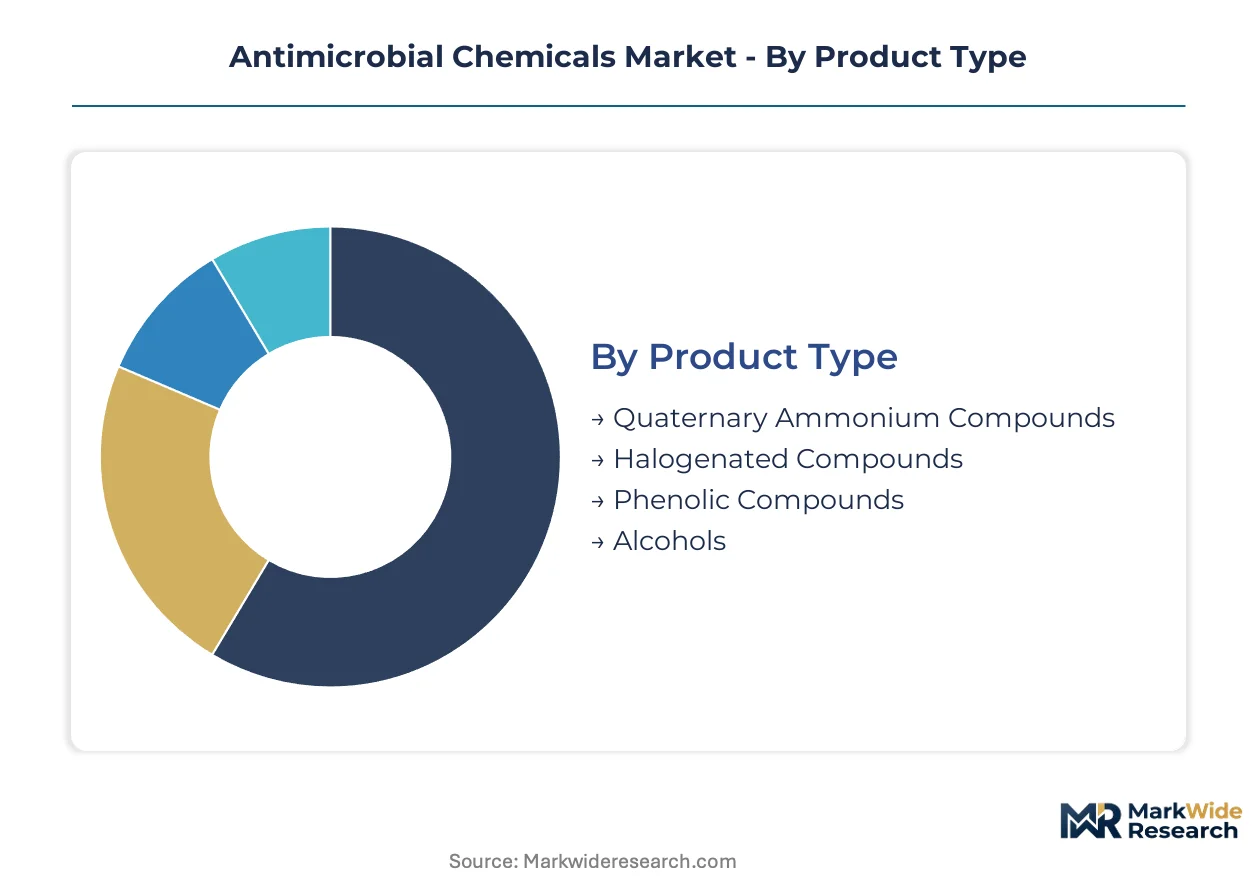
Antimicrobial chemical suppliers configure their portfolios across four intersecting dimensions that determine pricing power and regulatory exposure. Product type and application form the technical foundation, while end-user concentration and delivery format dictate channel strategy and margin structure.
Product Type:
Mature quaternary ammonium compounds dominate commercial volumes, while emerging silver-ion and polymeric alternatives capture reformulation-driven substitution.
- Quaternary Ammonium Compounds:These cationic surfactants disrupt microbial cell membranes through electrostatic interaction with phospholipid bilayers. Hospital disinfection protocols in the United States and Germany are mandating higher application frequencies that expand consumption in clinical surface cleaners. EPA registration familiarity and aqueous compatibility sustain their position despite REACH pressure on certain chain lengths.
- Halogenated Compounds:Chlorine and bromine-releasing biocides deliver rapid oxidation-based microbial kill across broad pH ranges. Water treatment facilities in China and industrial cooling systems in Texas represent concentrated demand nodes, though three multinational suppliers control precursor manufacturing and create supply vulnerability.
- Phenolic Compounds:These aromatic biocides persist on surfaces through protein denaturation mechanisms. Legacy formulations face ECHA evaluation under the Biocidal Products Regulation, compressing their viable application window.
- Alcohols:Ethanol and isopropanol formulations provide rapid evaporation and minimal residue for healthcare hand hygiene. Food processing plants in California and pharmaceutical cleanrooms in Switzerland specify USP-grade specifications that command quality premiums.
Quaternary ammonium compounds handle the majority of throughput; coatings-integrated silver-ion alternatives are gaining share fastest as healthcare device OEMs embed functionality directly into polymer substrates.
Application:
Application segmentation reflects divergent regulatory stringency and performance requirements across consumer-facing and industrial end uses.
- Textiles:Antimicrobial finishing for apparel and home furnishings uses silver-ion carriers and quaternary ammonium microencapsulation to control odor-causing bacteria. Licensing agreements with brand-recognized additive platforms are expanding in India and Southeast Asia as manufacturers seek differentiation.
- Food Processing:Conveyor systems and preparation equipment require FDA and EFSA-compliant surface treatments that withstand aggressive cleaning cycles. North American regulators are tightening microbial load limits on contact surfaces, driving coating integration into stainless steel infrastructure.
- Water Treatment:Cooling towers and potable water systems deploy halogenated biocides and oxidizing agents to control Legionella and biofilm formation. China's MEE enforcement of discharge standards is shifting procurement toward bio-based formulations with lower environmental persistence.
- Agriculture:Seed treatments and post-harvest preservation face soil microbiome toxicity constraints that restrict dosing rates below economic thresholds for broad-acre cereal crops. Residue accumulation limits in European markets are narrowing the viable product pipeline.
Food processing commands the highest specification premiums; textile licensing is expanding most quickly as consumer goods manufacturers in India and Vietnam adopt brand-affiliated additive platforms.
End User:
End-user segmentation tracks infection control infrastructure investment cycles and procurement consolidation patterns across institutional and consumer markets.
- Healthcare:Acute care networks in Texas, California, and Florida are consolidating supplier panels around vertically integrated manufacturers with in-house toxicology capabilities. Group purchasing organizations are disqualifying toll-manufactured formulations lacking active ingredient sourcing transparency.
- Hospitality:Hotels and cruise operators specify antimicrobial coatings for high-touch surfaces and HVAC systems to reduce liability exposure. ECHA's substance evaluation roadmap is compressing reformulation timelines for industrial cleaning applications across European properties.
- Manufacturing:Electronics and pharmaceutical cleanrooms demand ISO-compliant disinfection protocols with documented batch traceability. German and Swiss device manufacturers are qualifying encapsulated release systems for sustained 90-day efficacy cycles.
- Household:Consumer disinfectants and treated plastics face price sensitivity that limits penetration of premium silver-ion formulations. China's GB standards for antimicrobial additives in consumer products create preferential pathways for low-VOC and bio-based alternatives.
Healthcare absorbs the most rigorous compliance investment; hospitality procurement is climbing fastest as post-pandemic liability protocols institutionalize surface treatment specifications.
Form:
Form segmentation captures the technical migration from surface application to bulk material integration.
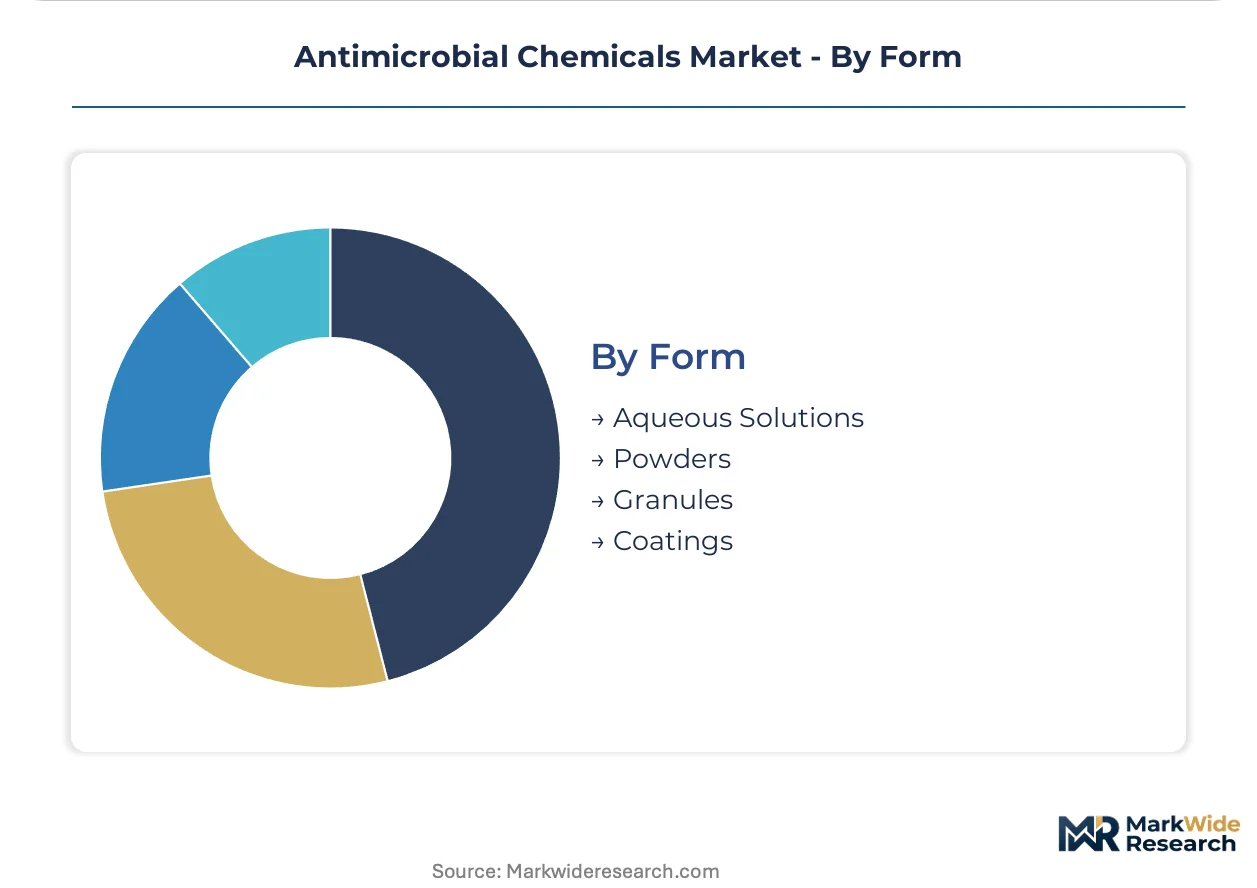
- Aqueous Solutions:Ready-to-use and concentrate formulations dominate healthcare and food service disinfection due to spray application compatibility. Compatibility testing with quaternary ammonium compounds against specific surface materials determines specification approval.
- Powders:Dry formulations enable precise dosing in industrial laundry and water treatment applications where liquid shipping costs are prohibitive. Solubility kinetics and dust exposure controls influence procurement decisions.
- Granules:Controlled-release pellets serve agricultural and aquaculture applications requiring sustained antimicrobial presence. Soil microbiome toxicity concerns are constraining expansion beyond specialty crop segments.
- Coatings:Polymer-integrated antimicrobial functionality is displacing surface treatments in healthcare devices and hospitality fixtures. Medical device OEMs in Germany and Switzerland are embedding silver-ion carriers directly into catheter and implant materials.
Aqueous solutions maintain the largest installed base; coatings are expanding most steeply as materials engineering converges with formulation science.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in antimicrobial chemicals concentrates in German and Swiss specialty chemical clusters, while volume manufacturing gravitates toward Chinese coastal provinces with integrated feedstock access. This asymmetry shapes procurement patterns across healthcare and industrial disinfection supply chains.
United States
Hospital-acquired infection protocols in Texas, California, and Florida acute care networks are mandating higher surface disinfection frequencies. EPA registration requirements under FIFRA govern commercialization timelines for new active ingredients. Group purchasing organizations in the Southeast are consolidating supplier panels around manufacturers with in-house toxicology capabilities.
Germany
Medical device OEMs in Baden-Württemberg and Bavaria are qualifying encapsulated silver-ion release systems for implantable applications. ECHA substance evaluation roadmaps are accelerating phase-outs of legacy isothiazolinone biocides. The Rhine-Ruhr chemical corridor hosts vertically integrated quaternary ammonium compound production with captive ethylene oxide feedstock.
China
Food processing infrastructure expansion in Shandong and Jiangsu provinces is driving antimicrobial coating integration into stainless steel equipment. MEE enforcement of GB standards for antimicrobial additives creates preferential pathways for low-VOC formulations. Yangtze River Delta manufacturers are backward-integrating into bio-based active ingredient precursors.
Switzerland
Pharmaceutical cleanroom specifications in Basel and Zurich are demanding documented batch traceability for disinfection protocols. Swissmedic oversight of medical device antimicrobial claims aligns with EU MDR transitional provisions. The Swiss chemical cluster specializes in halogenated biocide stabilization for water treatment applications.
India
Textile manufacturers in Gujarat and Tamil Nadu are licensing brand-affiliated antimicrobial additive platforms for apparel exports. BIS standards for antimicrobial-treated consumer products are tightening labeling requirements. The Mumbai-Pune industrial corridor is attracting toll manufacturing investments for mid-scale quaternary ammonium compound formulation.
Antimicrobial Chemicals Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in active ingredient and masterbatch supply. The antimicrobial chemicals market exhibits moderate consolidation, with three multinational suppliers controlling the majority of halogenated biocide precursor manufacturing. Strategic archetypes include integrated petrochemical conglomerates with captive feedstock positions, specialty additive platforms licensing brand-affiliated technologies, and toll manufacturers serving regional formulation demand. Dominant competitive moves encompass backward integration into ethylene oxide derivatives and strategic partnerships with healthcare procurement consortiums.
Among German and Swiss specialty chemical groups, BASF SE and Lonza occupy positions spanning integrated active ingredient production through formulated delivery systems. DuPont exemplifies the technology-led archetype in halogenated biocide stabilization, while Microban International represents the brand-licensing model for consumer goods additive platforms. Sanitized AG anchors the European textile antimicrobial finishing segment. These named entities illustrate the geographic clustering of competitive capability around German chemical infrastructure and Swiss precision manufacturing traditions.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| Microban International |
| Sanitized AG |
| Avient Corporation |
| Clariant |
| Milliken & Company |
| Lonza |
| Arxada AG |
| Others |
Value Chain & Pricing Dynamics
Three multinational suppliers controlling halogenated biocide precursor manufacturing concentrate margin capture upstream, while downstream formulators compete on specification premiums and regulatory compliance speed. This asymmetry forces mid-scale entrants toward toll manufacturing arrangements that sacrifice pricing power for market access.
Pricing Analysis
Configured-to-order pricing for EPA-registered quaternary ammonium formulations commands 40-60% premiums over standard-grade industrial biocides. Three-tier pricing structure across premium, standard, and economy levels separates healthcare-grade specifications with full toxicological documentation from food-service and industrial tiers. Cost compression in standard-grade quaternary ammonium compounds is intensifying because ethylene oxide feedstock volatility transmits directly to formulation costs. Hospital procurement consortiums exhibit lowest price sensitivity due to liability-driven specification mandates, while household consumer disinfectants face acute pressure from private-label alternatives.
Supply Chain Analysis
Extended payment terms from German and Swiss medical device OEMs now stretch 90-120 days, forcing mid-tier formulators toward supply-chain finance facilities. Manufacturing concentrates in Germany, China, and the United States, with the Rhine-Ruhr corridor hosting captive ethylene oxide production and Yangtze River Delta sites backward-integrated into bio-based precursors. Raw material sourcing draws from fatty alcohol derivatives, silver-ion carriers, and halogenated intermediates. Single-source vulnerability in halogenated biocide precursors creates structural risk. Distribution runs through regional chemical distributors with formulation technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial chemical markets reward service-attach models where regulatory compliance consulting and reformulation support expand faster than commodity biocide volumes. Technical service contracts for EPA registration navigation now generate recurring revenue streams exceeding base chemical margins.
For Market Incumbents: Entrench position by acquiring toxicology contract research capabilities scarce outside Western Europe and North America, insulating against REACH-driven reformulation cycles. Deepen upstream control over ethylene oxide derivatives through long-term offtake agreements with Rhine-Ruhr petrochemical complexes. Consolidate supplier panels around vertically integrated manufacturers before group purchasing organizations disqualify toll-manufactured alternatives. For New Entrants and Emerging Players: Establish a beachhead in India's textile antimicrobial licensing segment, where brand-affiliated additive platforms face limited domestic competition and export demand from Southeast Asian apparel manufacturers accelerates. Target food processing coating integration in Shandong and Jiangsu provinces, where stainless steel equipment expansion outpaces qualified local formulators. Lead with MEE-compliant low-VOC formulations to secure preferential procurement pathways under China's dual carbon alignment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty additive platforms lacking in-house active ingredient production. Long-term viability over a 5-10 year window favors manufacturers with captive regulatory affairs capabilities spanning EPA, ECHA, and MEE jurisdictions. Watch ECHA substance evaluation announcements as inflection indicators for replacement active ingredient demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Derivatives | Captive feedstock supply from Rhine-Ruhr complexes insulates BASF and Lonza from crude-linked price volatility. |
| EPA Registration Fast-Track Investment | In-house toxicology capabilities compress 18-36 month FIFRA review timelines for DuPont and emerging competitors. |
| Silver-Ion Encapsulation Technology Licensing | Medical device OEMs in Baden-Württemberg qualify 90-day release systems for implantable catheter applications. |
| Joint Venture with Chinese MEE-Compliant Formulators | Preferential procurement pathways open for low-VOC antimicrobial coatings in Yangtze River Delta food processing infrastructure. |
| Long-Term Supply Agreement with Hospital GPOs | Acute care networks in Texas and Florida consolidate panels around manufacturers with full active ingredient sourcing transparency. |
Study Parameters
The analysis maps quaternary ammonium compounds, halogenated biocides, silver-ion carriers, and polymeric biguanides, each validated through plant managers at German chemical complexes, procurement leads at Texas hospital group purchasing organizations, distribution channel partners in India, and technical R&D directors at Swiss medical device manufacturers. Primary interview findings triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA registration databases. Bottom-up volume estimates from end-use consumption patterns converged with top-down value projections across product type and application segments.
Assumptions held fixed include REACH authorization timelines, EPA registration bottlenecks, and ethylene oxide feedstock price linkage to crude benchmarks; variables included ECHA substance ban acceleration rates and China MEE enforcement intensity across the analysis window. Segmentation dimensions modeled encompass product type tier, end-use industry, form factor, and regional regulatory cluster. CAGRs derived from regression analysis of historical volume trends against projected infection control infrastructure investment cycles. Forecast inputs incorporated hospital-acquired infection protocol adoption rates and food processing microbial load limit tightening trajectories.
Stress conditions across ethylene oxide price volatility bands, ECHA evaluation acceleration scenarios, and China dual carbon policy enforcement levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory continuity and petrochemical feedstock market structure. Macroeconomic contraction, unanticipated substance bans, or breakthrough bio-based active ingredient commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Hypochlorite Bleaches Market
Disinfectants and Preservatives
Continuously Sterilized Product Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Sulfuryl Fluoride Market
Disinfectants and Preservatives
Surface Disinfectant Chemicals Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Sterilants Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market