
 Disinfectants Market | 2026-2036
Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfectants Market Intelligence
Skilled formulation chemists with dual expertise in antimicrobial efficacy and regulatory compliance is rotating toward contract manufacturers and private-label producers, tightening talent availability for branded innovators. Reckitt Benckiser leverages its hospital-grade portfolio to sustain shelf presence across North American and European retail channels. Ecolab anchors its position through captive service relationships with food processing and hospitality chains, embedding chemical supply into broader hygiene management contracts.
Disinfectants are antimicrobial chemical formulations, typically containing active concentrations of quaternary ammonium compounds, sodium hypochlorite, or accelerated hydrogen peroxide, designed to destroy pathogenic microorganisms on inanimate surfaces through oxidation or protein denaturation. Their primary commercial purpose spans healthcare-acquired infection prevention, food safety sanitation, and public health bioburden reduction in high-contact environments. Liquid formulations dominate institutional procurement due to dilution economics and compatibility with existing mop-bucket and spray-dispenser infrastructure, while hydrogen peroxide-based chemistries represent the fastest-expanding active ingredient class as end users seek alternatives to chlorine and quaternary ammonium compounds amid respiratory and skin sensitization concerns. Surface disinfection applications command the largest share of professional spending, though air sanitization protocols accelerated by ventilation-focused building codes are redirecting some capital toward misting and vapor-phase systems.
The EPA regulates disinfectant efficacy claims through its pesticide registration framework under FIFRA, requiring substantiated kill claims against specified pathogen classes before products enter interstate commerce. The EU Biocidal Products Regulation mandates active substance approval and product authorization through ECHA, creating a dual-track compliance burden that favors larger registrants with dedicated regulatory affairs capacity. FDA oversight intersects at healthcare settings where disinfectants contact medical device surfaces, triggering additional validation requirements. Stakeholders must monitor pending substance evaluations under BPR review programs and EPA re-registration timelines to anticipate portfolio rationalization and substitution pressures.
Market Dynamics
Hospital procurement consolidation through group purchasing organizations is compressing supplier margins and forcing reformulation investments to meet emerging viral pathogen efficacy standards.
Growth Catalysts
- EPA Emerging Viral Pathogen Guidance:Efficacy validation requirements for SARS-CoV-2 and influenza strains are expanding hospital formulary refresh cycles and premium product uptake.
- Food processing sanitation mandates:FSMA preventive controls and HACCP protocol tightening in meat and dairy facilities are accelerating automated dispensing system deployments.
- Accelerated hydrogen peroxide chemistries:Respiratory and dermal sensitization concerns around quaternary ammonium compounds are redirecting institutional volume toward peroxide-based alternatives.
Market Restraints
- Active ingredient supply concentration:Chinese manufacturers dominate quaternary ammonium compound precursors, exposing formulators to freight cost volatility and customs delays.
- EU Biocidal Products Regulation substance review timelines:ECHA evaluation backlogs for quaternary ammonium compounds and sodium hypochlorite are extending product authorization windows beyond 36 months.
- Electrostatic sprayer capital requirements:Touchless application infrastructure demands upfront equipment investment that smaller long-term care operators cannot absorb.
Strategic Opportunities
- India healthcare infrastructure expansion:Ayushman Bharat hospital accreditation standards are creating first-time demand for EPA-registered chemistries in tier-2 and tier-3 cities.
- Air sanitization protocol adoption:ASHRAE ventilation-focused building codes are redirecting capital toward hydrogen peroxide vapor and misting systems in US commercial real estate.
- On-site generation systems:Electrolyzed water and ozone generation hardware eliminates transport costs and shelf-life constraints for foodservice and hospitality chains.
Industry Challenges
- Formulation chemist scarcity:Dual expertise in antimicrobial efficacy testing and EPA/FIFRA registration dossier preparation is rotating toward contract manufacturers, draining branded innovator talent pools.
- Legacy dispensing infrastructure incompatibility:Existing mop-bucket and spray-bottle systems in aged healthcare facilities cannot accommodate concentrated hydrogen peroxide dilution protocols without corrosion-resistant hardware replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfectants Market |
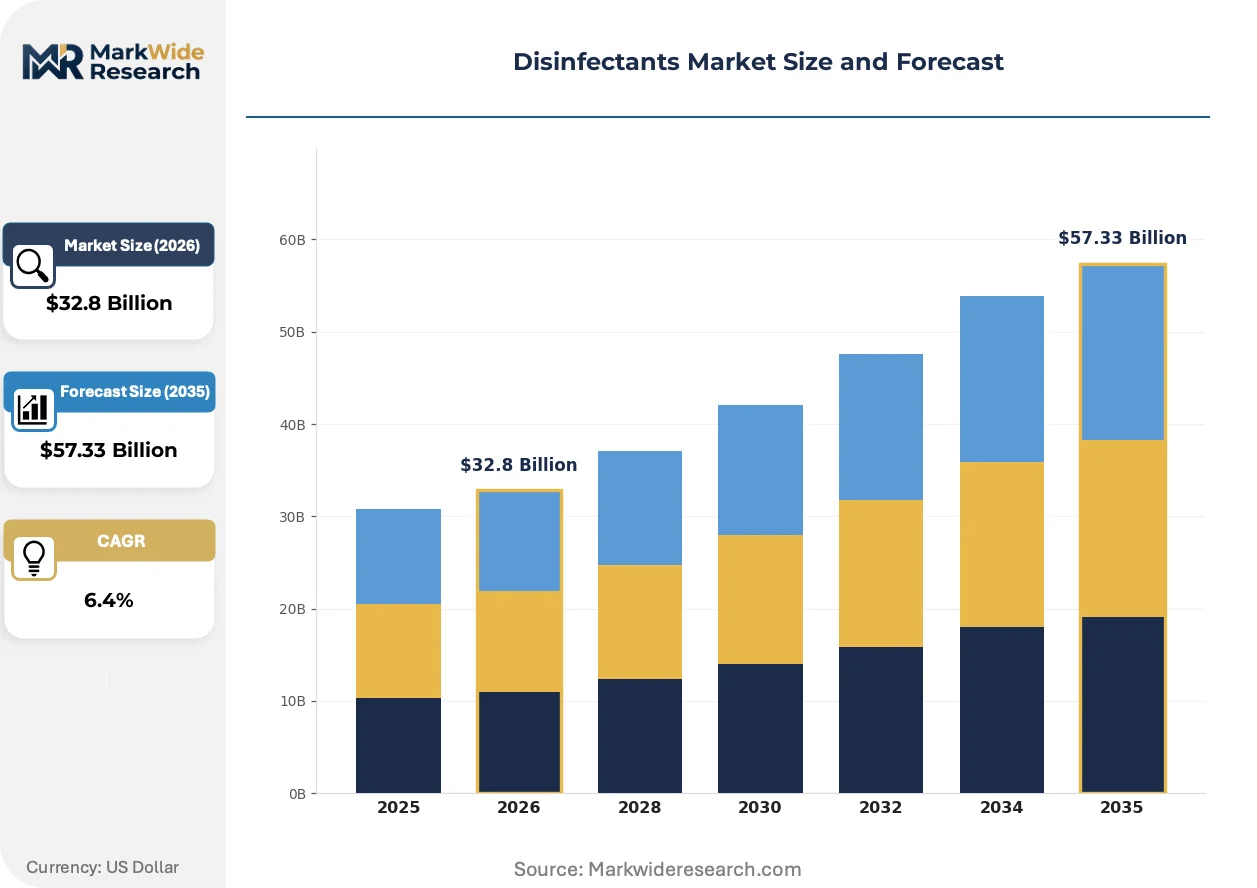
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Wipes, Sprays, Tablets Active Ingredient: Alcohol, Chlorine, Quaternary Ammonium Compounds, Hydrogen Peroxide End User: Healthcare Facilities, Households, Food Industry, Education Sector Application: Surface Disinfection, Hand Hygiene, Water Treatment, Air Sanitization |
| Companies Covered | Reckitt Benckiser, Procter & Gamble, 3M, The Clorox Company, Ecolab, STERIS, SC Johnson, GOJO Industries, Diversey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfectants Market Strategic Shifts & Innovations
Electrostatic and ultrasonic application technologies are compressing labor time per square meter while reformulation chemistry shifts away from respiratory irritants.
Electrostatic sprayer technology applies charged disinfectant droplets that wrap around complex surfaces and penetrate crevices inaccessible to conventional trigger-spray methods. Hospital environmental services departments in the United States are adopting these systems at accelerating rates to reduce terminal cleaning time per patient room. The hardware footprint is miniaturizing from backpack units to handheld cordless devices, expanding addressable use cases into ambulatory clinics and dental practices.
The EU Biocidal Products Regulation review program is accelerating substance evaluation timelines for quaternary ammonium compounds and sodium hypochlorite, forcing formulators to pre-position alternative actives ahead of potential non-approval decisions. Product authorization dossier costs are concentrating market share among registrants with dedicated ECHA liaison capacity. Healthcare and foodservice segments in Germany and France are responding by diversifying active ingredient exposure across hydrogen peroxide, peracetic acid, and lactic acid formulations.
Group purchasing organizations in the United States hospital sector are unbundling chemical supply from equipment and service contracts, forcing suppliers to compete on per-liter pricing rather than captive hygiene management relationships. This disintermediation is most visible in the acute care segment, where GPOs like Vizient and Premier are consolidating volume and standardizing specification tiers across member health systems.
Disinfectants Market Segmentation
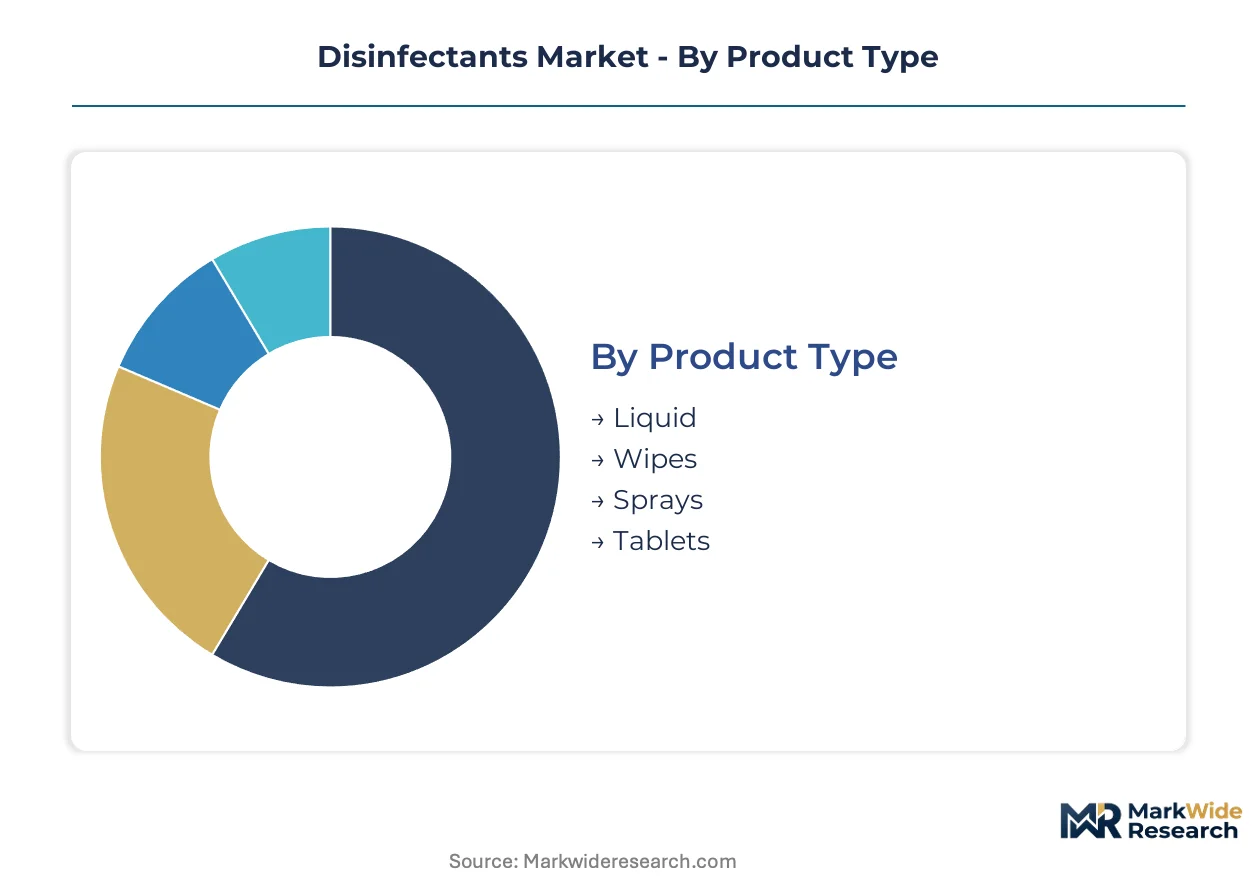
Segmentation reveals how substitution pressures and regulatory compliance burdens concentrate differently across formulation chemistries and delivery formats. Procurement patterns diverge sharply between institutional buyers with captive service contracts and retail consumers sensitive to shelf price and skin sensitization warnings.
Product Type:
Liquid concentrates face the steepest substitution threat from on-site generation systems and pre-moistened formats that eliminate dilution error and corrosion risk in aged healthcare infrastructure.
- Liquid:Concentrated formulations requiring dilution dominate hospital procurement through bulk dispensing systems and mop-bucket protocols. Food processing chains in the United States specify these for automated CIP systems where per-liter economics outweigh labor costs.
- Wipes:Pre-saturated substrates eliminate dilution variability and reduce cross-contamination risk in terminal cleaning workflows. Ambulatory clinics and dental practices favor these for point-of-use convenience despite higher per-application cost.
- Sprays:Trigger-dispensed solutions target retail consumers and small commercial operators without capital for electrostatic hardware. Compatibility concerns with legacy spray bottles limit hydrogen peroxide concentration levels.
- Tablets:Effervescent formats reduce freight weight and storage footprint for hospitality chains and remote healthcare facilities. Dissolution time variability creates formulation consistency challenges in hard water regions.
Liquid formulations anchor the volume base while wipes gain share at the steepest rate in outpatient and long-term care settings.
Active Ingredient:
Cost tier stratification separates commodity chlorine chemistry from premium peroxide formulations, with quaternary ammonium compounds occupying a contested middle ground facing respiratory sensitization scrutiny.
- Alcohol:Ethanol and isopropanol solutions deliver rapid evaporation and minimal residue for hand hygiene and electronics surface protocols. FDA oversight of healthcare hand rub claims creates registration barriers for new entrants.
- Chlorine:Sodium hypochlorite remains the default for water treatment and food contact surface sanitation due to low raw material cost. ECHA substance review timelines under BPR are extending authorization windows beyond three years.
- Quaternary Ammonium Compounds:QACs balance surface compatibility and residual activity for daily environmental cleaning in hospitals. Supply concentration among Chinese precursor manufacturers exposes formulators to freight volatility and customs delays.
- Hydrogen Peroxide:Accelerated formulations with silver or peracetic acid activators achieve sporicidal claims without respiratory irritant profiles. ASHRAE ventilation-focused building codes are redirecting capital toward vapor-phase deployment in US commercial real estate.
Chlorine chemistry anchors the volume base while hydrogen peroxide climbs the fastest amid institutional preference shifts away from respiratory and dermal sensitizers.
End User:
Customer type determines whether procurement runs through group purchasing organization consolidation or fragmented retail selection, with starkly different margin and specification requirements.
- Healthcare Facilities:Acute care systems specify EPA-registered hospital-grade chemistries through GPO contracts that unbundle chemicals from equipment. Ayushman Bharat accreditation standards in India are creating first-time demand in tier-2 and tier-3 cities.
- Households:Retail consumers select based on scent profiles, skin sensitivity labeling, and viral claim prominence without technical specification review. E-commerce penetration is compressing brand loyalty and accelerating private-label substitution.
- Food Industry:Meat and dairy processors deploy automated dispensing systems under FSMA preventive controls and HACCP protocol tightening. FSIS inspection frequency creates zero-tolerance compliance environments.
- Education Sector:K-12 districts and universities balance budget constraints with absenteeism reduction claims, favoring bulk liquid contracts with simplified training requirements. Electrostatic sprayer capital requirements strain smaller district maintenance budgets.
Healthcare facilities anchor the volume base while food industry applications expand most quickly under sanitation mandate tightening.
Application:
Application maturity varies from established surface protocols to emerging air sanitization modalities where building code evolution is redirecting capital expenditure.
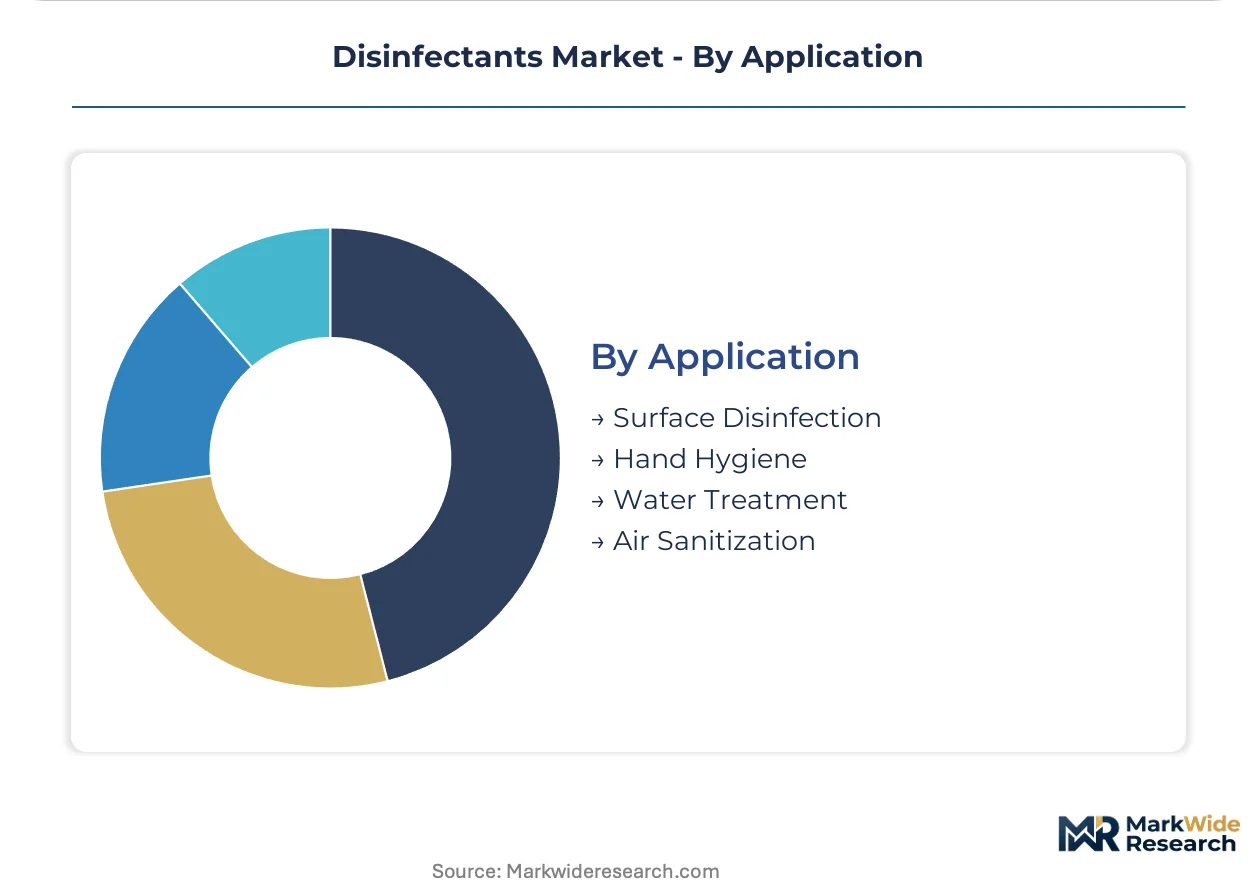
- Surface Disinfection:Terminal cleaning of patient rooms and food contact equipment commands the largest professional spending share. Electrostatic application technology is compressing labor time per square meter while raising hardware compatibility requirements.
- Hand Hygiene:Healthcare hand rub and surgical scrub formulations operate under FDA antiseptic monograph constraints distinct from EPA surface disinfectant oversight. Alcohol concentration minimums face flammability storage regulations.
- Water Treatment:Municipal and industrial systems specify chlorine-based residual disinfection with established dosing infrastructure. On-site electrolyzed water generation is displacing bulk hypochlorite delivery in foodservice chains.
- Air Sanitization:Hydrogen peroxide vapor and misting systems address ventilation-focused ASHRAE standards in US commercial real estate. Validation of airborne pathogen reduction claims lacks standardized test methods.
Surface disinfection anchors the volume base while air sanitization gains share at the steepest rate under building code evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply between geographies: the United States channels volume through consolidated purchasing organizations, while India and Brazil rely on fragmented distributor networks serving accreditation-driven first-time buyers.
United States
Acute care systems drive demand through Vizient and Premier group purchasing contracts that unbundle chemicals from equipment leases. EPA's emerging viral pathogen guidance for SARS-CoV-2 claims is forcing formulary refreshes across 6,000 hospital facilities. The Dallas-Fort Worth metroplex anchors environmental services staffing concentration for terminal cleaning protocol training.
Germany
Meat and dairy processors under FSMA-equivalent HACCP tightening specify automated dispensing systems for food contact surfaces. ECHA's Biocidal Products Regulation review of quaternary ammonium compounds is extending authorization timelines beyond 36 months. The Rhine-Ruhr industrial corridor concentrates chemical formulators pre-positioning peracetic acid alternatives ahead of potential QAC non-approvals.
India
Ayushman Bharat hospital accreditation standards are creating first-time EPA-registered chemistry demand in tier-2 and tier-3 cities previously served by unregistered commodities. CDSCO alignment with international efficacy validation protocols is raising import registration barriers. The Maharashtra-Gujarat pharmaceutical belt houses contract manufacturers pivoting from API production to disinfectant formulation for domestic hospital chains.
China
Quaternary ammonium compound precursor manufacturers dominate global active ingredient supply, exposing formulators to freight cost volatility and Shanghai port customs delays. NMPA tightening of disinfectant registration dossier requirements is consolidating domestic production among larger registrants. The Yangtze River Delta chemical cluster maintains concentration of QAC intermediate production for export markets.
Brazil
Food processing sanitation mandates under ANVISA preventive controls are accelerating automated dispensing adoption in meatpacking facilities. Hospital infection control protocol expansion in São Paulo and Rio de Janeiro state health systems is redirecting procurement toward hospital-grade chemistries. The São Paulo industrial corridor anchors Latin American formulation capacity serving Mercosur regional demand.
Disinfectants Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in a structure that rewards regulatory affairs capacity and captive service relationships. Multinational chemical suppliers with dedicated EPA and ECHA liaison teams capture hospital and food processing volume through specification-grade portfolios. Private-label contract manufacturers absorb reformulation investments for retail channel clients lacking in-house regulatory expertise. The dominant competitive moves involve backward integration into active ingredient supply and geographic expansion through distributor acquisition in emerging hospital markets.
Within the integrated leader tier, Reckitt Benckiser and Ecolab exemplify divergent positioning archetypes. Reckitt Benckiser represents the retail-branded multinational leveraging hospital-grade portfolio credibility to sustain shelf presence across North American and European mass-market channels. Ecolab occupies a position defined by captive service relationships with food processing and hospitality chains, embedding chemical supply into broader hygiene management contracts that resist pure price competition. The Clorox Company sits within the heritage brand defender archetype, managing portfolio transitions amid active ingredient substitution pressures and respiratory sensitization claim repositioning.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| Procter & Gamble |
| 3M |
| The Clorox Company |
| Ecolab |
| STERIS |
| SC Johnson |
| GOJO Industries |
| Diversey |
| Others |
Cost & Logistics Intelligence
Bulk concentrate manufacturing scale in Chinese quaternary ammonium compound facilities anchors global price floors while simultaneously concentrating supply vulnerability. This scale asymmetry permits tier-1 formulators to defend margin through captive offtake contracts, yet leaves mid-tier competitors exposed to spot-market volatility in precursor chemicals.
Pricing Analysis
Long-term offtake agreements between hospital group purchasing organizations and integrated chemical suppliers dominate institutional procurement, compressing spot-market participation to fragmented foodservice and education segments. Price differentiation rests on EPA registration tier and dilution-equipment bundling rather than active ingredient cost alone. Pricing pressure stems from GPO unbundling of chemical supply from service contracts, forcing per-liter competition. Retail consumers exhibit highest price sensitivity, while acute care systems prioritize formulary compliance over unit cost.
Supply Chain Analysis
Inventory lead times for quaternary ammonium compound precursors stretch 60-90 days from Yangtze River Delta manufacturers to North American formulators, creating working capital intensity for non-integrated players. Active ingredient supply concentrates in China, with secondary capacity in Germany and India for peracetic acid alternatives. Raw material dependencies span benzalkonium chloride intermediates, hydrogen peroxide feedstock, and specialized non-woven substrates for wipes. Single-source vulnerability in Chinese QAC precursors exposes formulators to customs clearance delays. Distribution runs through distributor networks in emerging markets and direct GPO contracts in the United States hospital sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disinfectant demand sits in early-cycle expansion as ASHRAE ventilation codes and emerging viral pathogen protocols create first-time specification requirements across commercial real estate and long-term care facilities.
For Market Incumbents: Shield formulary position through backward integration into hydrogen peroxide active supply and pre-positioning of vapor-phase application hardware ahead of BPR substance review outcomes. ECHA evaluation timelines for quaternary ammonium compounds threaten portfolio rationalization; incumbents should accelerate peracetic acid registration dossiers in Germany and France. Channel control through captive service relationships with food processing chains resists pure price competition from GPO-unbundled hospital supply. For New Entrants and Emerging Players: Differentiate on air sanitization modality specialization rather than competing in saturated surface disinfection segments. India's tier-2 and tier-3 hospital markets under Ayushman Bharat accreditation standards offer penetrable white space with first-time EPA-registered chemistry demand. Target education sector procurement through simplified training protocols and electrostatic sprayer leasing models that circumvent capital constraints in K-12 districts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with dual EPA and ECHA registration capacity over pure-play branded innovators. Long-term viability hinges on regulatory affairs infrastructure rather than formulation chemistry alone. Acquisition targets should demonstrate established liaison capacity with EPA Office of Pesticide Programs and ECHA biocidal products committee. The signal to watch is BPR substance evaluation acceleration for quaternary ammonium compounds, which would trigger forced substitution demand and favor registrants with pre-approved alternative actives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Supply | Captive hydrogen peroxide production insulates margin from Chinese QAC precursor volatility. |
| ECHA Pre-Registration Dossier Investment | Peracetic acid authorization ahead of potential QAC non-approval secures European hospital access. |
| Electrostatic Hardware Leasing Programs | Equipment-as-a-service models bypass capital constraints in long-term care and education segments. |
| On-Site Generation System Deployment | Electrolyzed water hardware eliminates freight costs and shelf-life limits for hospitality chains. |
| GPO Contract Unbundling Response | Standalone chemical pricing competitiveness preserves volume in acute care procurement consolidation. |
Research Approach
A spread of perspectives from formulation chemists, hospital environmental services directors, GPO contracts managers, and food processing sanitation supervisors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA registration databases, ECHA biocidal products review filings, FDA antiseptic monograph updates, and customs trade data on quaternary ammonium compound precursor shipments. Bottom-up volume estimates from end-use segment procurement patterns were triangulated against top-down capacity assessments from active ingredient manufacturers.
Segmentation dimensions modeled span formulation type, active ingredient chemistry, end-user vertical, application modality, and regional regulatory cluster across the analysis window. CAGRs were derived from elasticity-adjusted demand projections tied to hospital accreditation expansion, food safety mandate tightening, and building code evolution. Industry-specific forecast inputs include ECHA substance evaluation timelines, EPA emerging viral pathogen claim validation cycles, and ASHRAE ventilation standard adoption curves.
Material uncertainties — BPR review acceleration, freight cost volatility in Chinese precursor supply, and electrostatic sprayer capital absorption rates in long-term care — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Sterilants Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Global Mold Inhibitors Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Pyrethroids Market