
 Disinfectant and Cleaning Agents Market | 2026-2036
Disinfectant and Cleaning Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfectant and Cleaning Agents Market Intelligence
The substitution of petroleum-derived surfactants with bio-based alternatives is hardening the cost structure for many surface cleaners. This shift impacts raw material sourcing and manufacturing processes for key industry participants. Ecolab Inc. leverages its scale in institutional markets to manage input cost volatility. Procter & Gamble competes on brand strength and consumer-facing innovation in residential segments, while The Clorox Company sustains its market position through a focus on bleach-based disinfecting technologies.
Disinfectant and cleaning agents are chemical formulations engineered to eliminate pathogens and remove contaminants from inert surfaces and skin. These products contain active ingredients such as alcohols, quaternary ammonium compounds, or peroxides at specific concentrations to achieve microbial kill claims. Their primary purpose is to prevent the transmission of infectious diseases. Within the application segment, healthcare represents the highest-margin category, while demand for hand sanitizers as a product type exhibits elasticity tied to public health concerns.
Market access is governed by stringent regulatory bodies like the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under its Biocidal Products Regulation. These agencies mandate rigorous testing for efficacy claims and safety, directly influencing formulation and labeling. In China, the National Medical Products Administration (NMPA) oversees approvals for medical-grade disinfectants. Future product development must balance microbial efficacy against emerging environmental sustainability targets and user safety profiles.
Market Dynamics
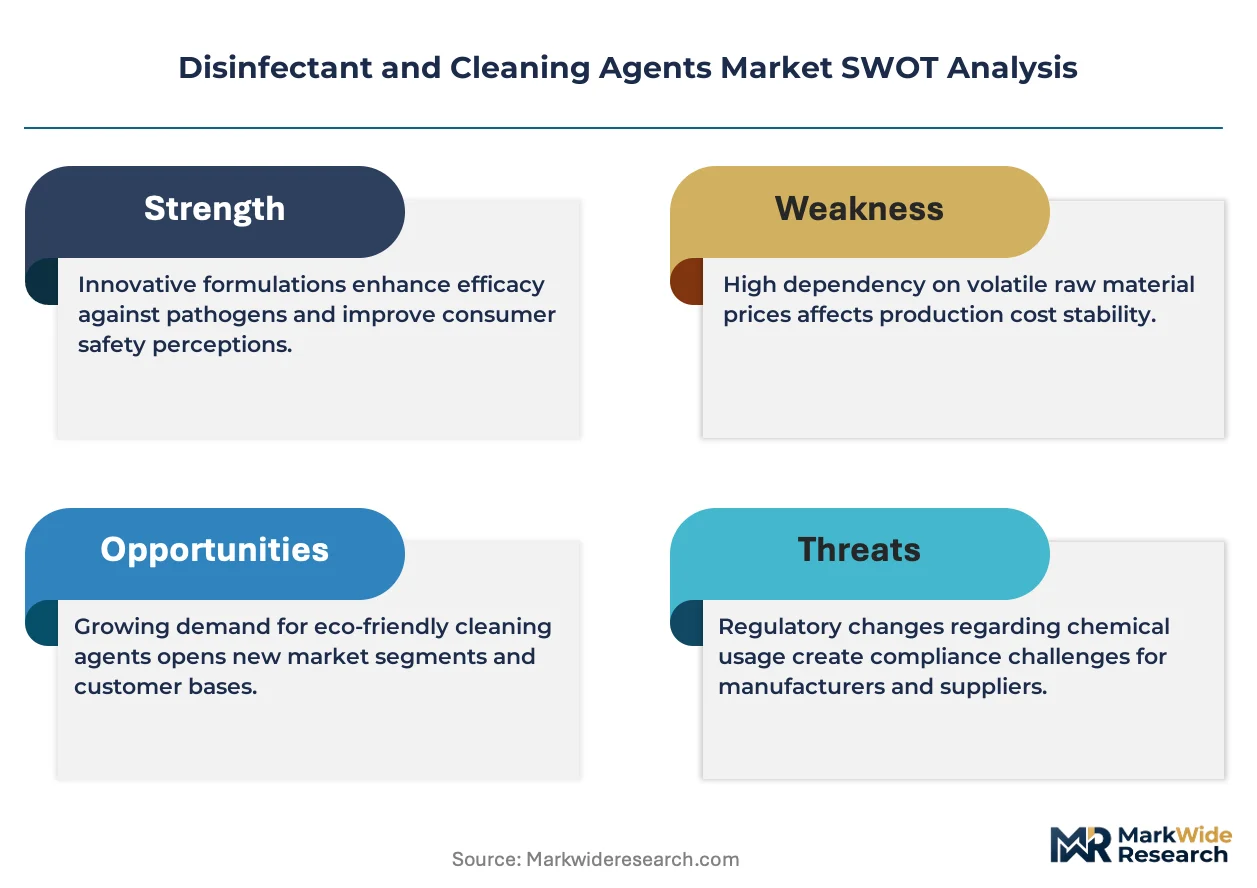
The central structural force shaping the market is the regulatory mandate for proven efficacy and environmental safety. Agencies like the US EPA and ECHA are compelling manufacturers to re-engineer formulations, balancing microbial kill claims against sustainability profiles and user safety.
Growth Catalysts
- Healthcare Infection Control:Heightened infection prevention protocols in hospitals and clinics, reinforced by public health bodies, sustain demand for high-efficacy, medical-grade disinfectants to combat healthcare-associated infections.
- China's Public Health Modernization:The expansion of healthcare infrastructure and rising public health standards in China create concentrated demand for a wide range of cleaning and disinfecting agents in both institutional and consumer settings.
- Efficacy Verification Demand:Consumer and institutional buyer insistence on products with validated antimicrobial claims, supported by visible on-label data, drives investment in rigorous testing and certification processes for market access.
Market Restraints
- Bio-based Input Costs:The industry-wide pivot from petroleum-derived surfactants to higher-cost bio-based alternatives is increasing raw material expenses and creating volatility in the manufacturing cost structure for surface cleaners.
- Regulatory Approval Timelines:Navigating the lengthy and expensive product registration processes mandated by the US EPA and the ECHA under its Biocidal Products Regulation acts as a significant barrier to market entry for new formulations.
- Formulation Trade-offs:The technical challenge of maintaining disinfectant potency against resistant pathogens while removing certain active ingredients due to environmental or health concerns limits formulation options for manufacturers.
Strategic Opportunities
- Smart Dispensing Integration:Combining disinfectant products with IoT-enabled dispensing systems offers an opportunity to provide data-driven compliance monitoring and usage optimization for institutional customers like hospitals and food service providers. *High-Touch Electronics Disinfection: Development of specialized, non-corrosive cleaning agents for sensitive electronic surfaces in sectors like consumer electronics and automotive interiors represents a nascent, high-value application segment.
- Southeast Asian Market Development:Targeting markets in countries like Vietnam and Indonesia, where hygiene standards are rising alongside economic development, offers a significant runway for growth in both consumer and institutional product categories.
Industry Challenges
- Supply Chain Reconfiguration:Shifting raw material sourcing from established petrochemical supply chains to a fragmented and developing network of bio-based feedstock suppliers presents significant logistical and quality control challenges.
- Cross-Jurisdictional Compliance:The operational burden of managing disparate and constantly evolving regulatory documentation and labeling requirements across key markets, including China's NMPA and Health Canada, consumes substantial corporate resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfectant and Cleaning Agents Market |
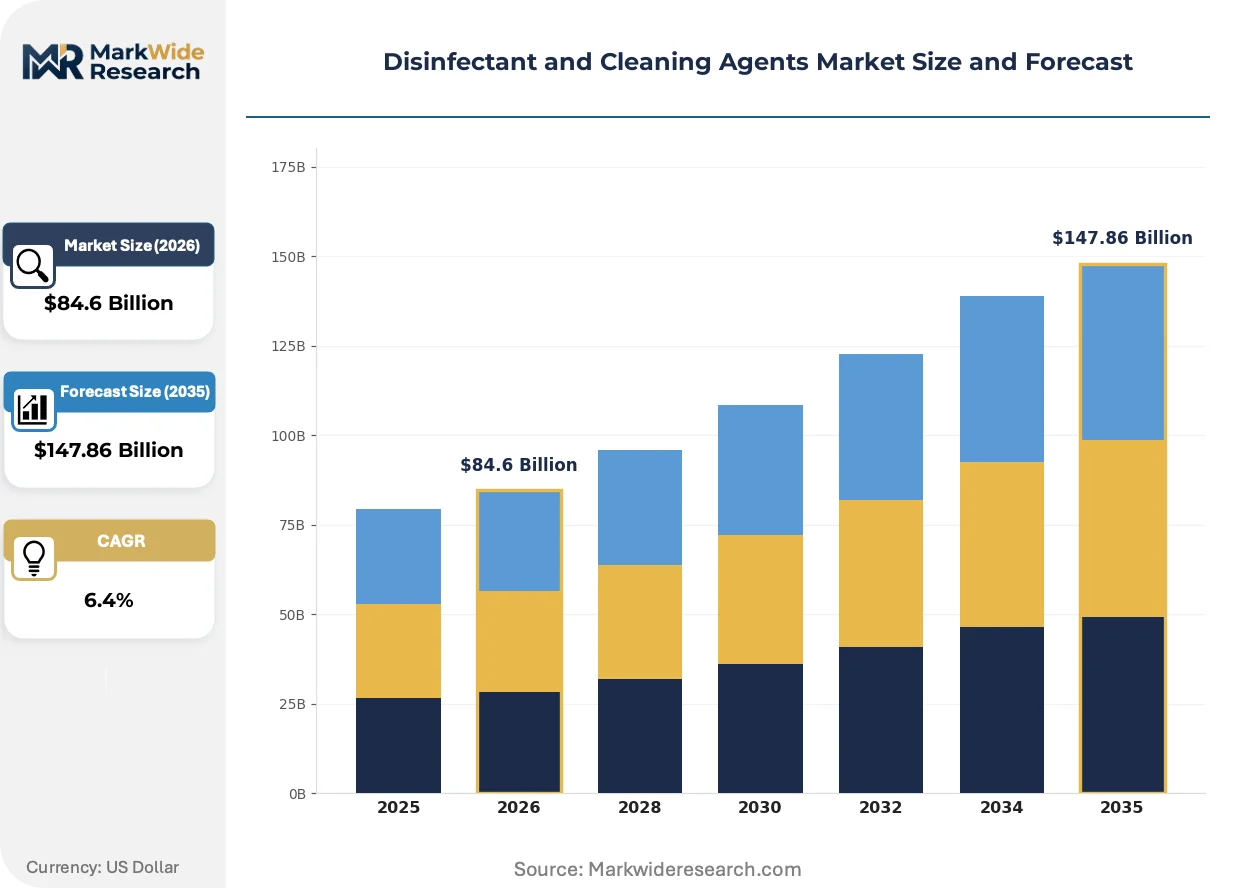
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $147.86 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Hand Sanitizers, Disinfecting Wipes, Antimicrobial Sprays Application: Residential, Commercial, Healthcare, Industrial Formulation: Liquid, Foam, Gel, Powder End User: Households, Hospitals, Schools, Restaurants |
| Companies Covered | Ecolab Inc., STERIS plc, Reckitt Benckiser Group PLC, SC Johnson Professional USA, Diversey Holdings Ltd., Procter & Gamble, The Clorox Company, GOJO Industries, Inc., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfectant and Cleaning Agents Market Strategic Shifts & Innovations
Product development is increasingly defined by the need to meet stringent sustainability targets without compromising microbial efficacy. This dynamic pushes innovation in both chemical composition and digital service integration, altering the competitive landscape for manufacturers.
Electrostatic spray technology applies a positive charge to disinfectant droplets, enabling them to wrap around and evenly coat complex surfaces. Healthcare facilities and public transit authorities are the primary adopters, seeking to improve disinfection coverage and efficiency. This method of application is electrifying the professional cleaning services sector by enabling faster, more thorough sanitization with less chemical waste.
The European Union's Biocidal Products Regulation (BPR) mandates a rigorous authorization process for all active substances and biocidal products sold within the EU. Its industrial consequence is a consolidation of the active substance portfolio, as manufacturers withdraw less profitable chemistries. Formulators of surface disinfectants are most affected, forcing them to reformulate products using approved actives and update safety data sheets.
A significant behavioral shift is the institutional buyer's preference for products with third-party environmental certifications, such as Green Seal or UL ECOLOGO. This trend is disrupting traditional purchasing, which often prioritized cost per unit over total lifecycle impact, favoring suppliers with transparent sustainability reporting. The shift is most visible in the education and corporate real estate verticals, particularly in North America and Western Europe.
Disinfectant and Cleaning Agents Market Segmentation
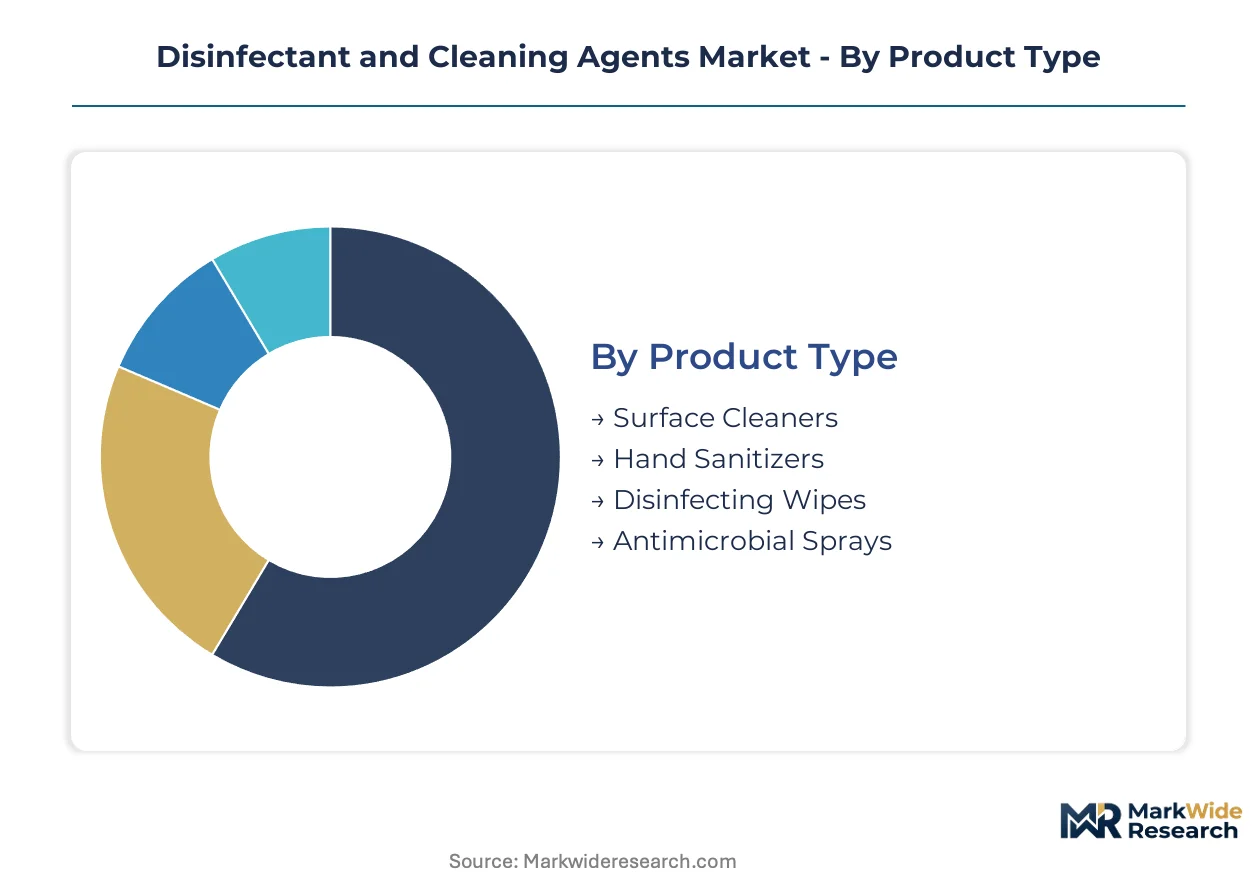
The Disinfectant and Cleaning Agents Market segments reveal varied product compositions and end-user requirements. Understanding these distinctions helps manufacturers align product development with specific application needs and regulatory compliance. Each segment presents unique challenges and opportunities for market participants.
Product Type:
The capital expenditure required for manufacturing different product types varies significantly, with large-scale liquid production facilities demanding substantial upfront investment.
- Surface Cleaners:These chemical formulations remove dirt, grime, and pathogens from inert surfaces, often containing surfactants, solvents, and disinfectants. Demand concentrates in commercial and institutional settings, driven by routine hygiene protocols and public health mandates.
- Hand Sanitizers:Typically alcohol-based or quaternary ammonium compound solutions, hand sanitizers reduce microbial load on skin without water. Public health concerns and infectious disease outbreaks in regions like China periodically surge demand for these portable products.
- Disinfecting Wipes:Pre-moistened towelettes impregnated with disinfectant solutions offer convenience for quick surface sanitization. Residential and light commercial applications demonstrate consistent purchasing patterns.
- Antimicrobial Sprays:These aerosol or pump-spray products deliver active ingredients to surfaces for broad-spectrum pathogen elimination. Healthcare facilities and public transportation utilize these for comprehensive disinfection.
Most installed capacity flows through Surface Cleaners. Expansion is steepest in Hand Sanitizers.
Application:
Profit margins differ across applications, with healthcare applications typically commanding higher prices due to stringent efficacy and regulatory requirements.
- Healthcare:This segment includes medical-grade disinfectants and sterilants used in hospitals, clinics, and long-term care facilities to prevent healthcare-associated infections. Regulatory bodies like the US EPA and European ECHA enforce strict approval processes for these critical products.
- Commercial:Products for offices, retail spaces, hospitality, and food service fall into this category, focusing on general hygiene and public safety. Compliance with local health codes and corporate sustainability goals influences purchasing decisions in North America.
- Residential:Household cleaning and disinfecting products target consumer convenience and effectiveness for daily use. Brand strength and perceived safety drive purchasing behavior in Western Europe.
- Industrial:Heavy-duty cleaning agents and disinfectants are utilized in manufacturing, agriculture, and sanitation sectors. These applications require robust formulations capable of handling tough contaminants and large-scale operations.
Demand concentration is highest in Healthcare, with Commercial showing significant penetration.
Formulation:
The volume of product sold across different formulations highlights consumer preference and application suitability.
- Liquid:These ready-to-use or concentrated solutions are the most common form, allowing for versatile application methods like spraying, wiping, or mopping. This formulation dominates the residential and commercial cleaning sectors due to its ease of use.
- Foam:Foam formulations offer extended contact time on vertical surfaces and reduced dripping, often used in hand sanitizers and specialized surface cleaners. Healthcare settings increasingly adopt foam hand sanitizers for improved adherence.
- Gel:Gel formulations provide controlled application and reduced evaporation, particularly popular for hand sanitizers. Public health campaigns in China have boosted the adoption of gel-based hand hygiene products.
- Powder:Concentrated powder formulations require dilution before use, offering cost-effectiveness for bulk purchasing and reduced shipping weight. Industrial and institutional buyers often prefer powders for their economic benefits.
Liquid dominates production volume, while Gel exhibits strong growth in specialized uses.
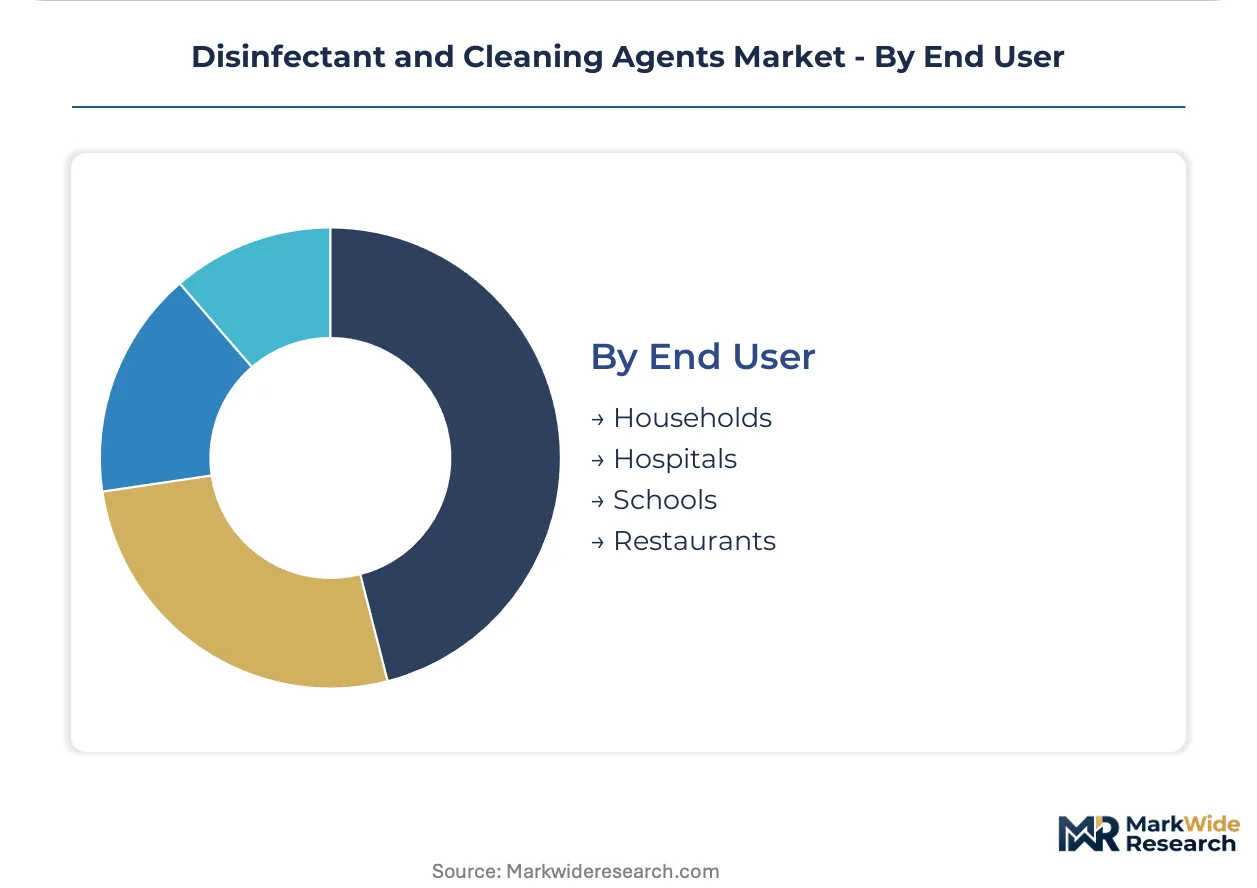
End User:
Customer type segmentation reflects distinct purchasing behaviors and regulatory environments.
- Households:Individual consumers purchasing products for personal and home hygiene represent a large volume segment. Brand loyalty and perceived value influence purchasing decisions across the United States.
- Hospitals:Medical institutions require high-efficacy, regulatory-approved disinfectants for infection control and patient safety. Procurement is driven by strict protocols and validation from agencies like the US EPA.
- Schools:Educational facilities procure cleaning and disinfecting agents to maintain healthy learning environments. Budget constraints often influence product selection, balancing cost with efficacy.
- Restaurants:Food service establishments utilize specialized cleaners and sanitizers to meet health and safety regulations. These businesses prioritize products with rapid kill times and food-safe approvals.
Households represent the largest consumer base, and Hospitals are rapidly expanding their procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's public health modernization drives significant demand for disinfectant and cleaning agents across institutional and consumer settings. This global market experiences varied growth patterns influenced by regional regulatory frameworks and healthcare infrastructure development. Each country presents unique opportunities and compliance requirements for market participants.
China
Expanding healthcare infrastructure and rising public health standards create concentrated demand for cleaning and disinfecting agents. The National Medical Products Administration (NMPA) oversees approvals for medical-grade disinfectants, influencing product availability. The Yangtze River Delta region drives significant manufacturing and consumption within the country.
United States
Heightened infection prevention protocols in hospitals and consumer insistence on validated antimicrobial claims sustain demand for high-efficacy products. The US Environmental Protection Agency (EPA) mandates rigorous testing for efficacy claims and safety. California's medical device industry and innovation hubs influence product development for advanced disinfection solutions.
Germany
Stringent EU Biocidal Products Regulation (BPR) and institutional buyer preference for environmental certifications shape product development. The European Chemicals Agency (ECHA) enforces rigorous authorization processes for active substances. North Rhine-Westphalia hosts chemical manufacturers developing sustainable and compliant formulations.
India
Rapid urbanization and rising disposable incomes contribute to a growing consumer and institutional market for hygiene products. The Bureau of Indian Standards (BIS) sets quality benchmarks for disinfectants and cleaning agents. Maharashtra's industrial zones are expanding production capacity for various cleaning agent categories.
Brazil
A growing healthcare sector and increasing consumer awareness of hygiene drive demand for disinfectant products. ANVISA, the national health surveillance agency, regulates health products including disinfectants. São Paulo state concentrates manufacturing and distribution for the domestic market.
Disinfectant and Cleaning Agents Market Key Industry Players
Product reformulation and portfolio optimization dominates the current landscape, as manufacturers adapt to evolving regulatory mandates and sustainability targets. The market structure features large diversified chemical conglomerates alongside specialized disinfectant providers and consumer brand leaders. Competitive moves center on product innovation, geographic expansion into emerging markets, and strategic partnerships for technology integration.
At the enterprise scale, Ecolab Inc. exemplifies a strategy of leveraging its institutional market presence to manage input cost volatility and expand service offerings. Procter & Gamble, a global consumer goods giant, occupies a position focused on brand strength and consumer-facing innovation in residential segments. The Clorox Company anchors its market position through a dedicated focus on bleach-based disinfecting technologies, maintaining its efficacy claims.
| Leading Market Players |
|---|
| Ecolab Inc. |
| STERIS plc |
| Reckitt Benckiser Group PLC |
| SC Johnson Professional USA |
| Diversey Holdings Ltd. |
| Procter & Gamble |
| The Clorox Company |
| GOJO Industries, Inc. |
| 3M Company |
Cost & Logistics Intelligence
Specialized chemical engineering talent in North Rhine-Westphalia influences premium disinfectant pricing, creating distinct pricing-tier spreads compared to regions with lower skilled labor costs.
Pricing Analysis
Input cost pass-through from bio-based surfactants hardens the cost structure for surface cleaners, impacting final product pricing. The dominant pricing model for institutional buyers is contract-based long-term offtake, while residential segments are primarily per-unit transactional. Price differentiation stems from validated efficacy claims and brand strength, particularly for premium medical-grade disinfectants and those with specific US EPA or European ECHA approvals. Upward pricing pressure originates from regulatory mandates for sustainable raw materials, with residential consumers exhibiting the highest price sensitivity compared to healthcare facilities.
Supply Chain Analysis
Reverse logistics for chemical products primarily involves waste disposal protocols, governed by environmental regulations. Geographic supply concentration for key active ingredients centers on China for basic chemical precursors and Germany for specialized formulations. The market draws from a narrow base of raw materials including alcohols and quaternary ammonium compounds. A structural supply chain risk is commodity price volatility for ethanol, impacting manufacturing costs. Downstream distribution for institutional products operates through direct sales, while consumer products reach households via established retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, where lower manufacturing costs in India for commodity cleaning agents contrast with stringent regulatory compliance expenses in the European Union.
For Market Incumbents: Deepen investment in R&D for next-generation bio-based active ingredients to counter the threat of petroleum-derived surfactant bans. Strengthen channel partnerships with hospitals and long-term care facilities to reinforce market share against new entrants focusing on niche applications. Pursue strategic acquisitions of companies with advanced green chemistry patents to accelerate portfolio transformation. Continuous investment in regulatory certification for new formulations ensures compliance with evolving US EPA and ECHA standards.
For New Entrants and Emerging Players: A significant price-point gap between premium medical-grade disinfectants and economy household cleaners creates an entry opportunity for specialized formulations. Target the nascent high-touch electronics disinfection segment with non-corrosive, certified products. Southeast Asian markets, particularly Vietnam and Indonesia, offer significant penetration potential for consumer and commercial hygiene products. A direct-to-consumer digital marketing strategy emphasizing environmental sustainability can capture environmentally conscious buyers.
For Investors and Strategic Acquirers: Chemical conglomerates are the most active acquirers in this space, seeking to diversify their portfolios and meet sustainability mandates. The market exhibits long-term viability over the next decade, driven by sustained public health concerns and infrastructure growth in emerging economies. Target acquisition archetypes include specialized green chemistry firms with proprietary bio-based formulations or digital solution providers for smart dispensing systems. Regulatory updates on permissible active ingredient concentrations serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Surfactant R&D | Develops sustainable formulations, reducing reliance on petroleum-derived inputs for surface cleaners. |
| Smart Dispensing System Integration | Enhances compliance monitoring and usage optimization for institutional customers like hospitals. |
| Healthcare Channel Expansion | Secures high-margin contracts and strengthens presence in critical infection control applications. |
| Southeast Asian Market Entry | Captures new demand in rapidly urbanizing economies with rising hygiene standards. |
| Regulatory Certification Investment | Ensures market access and strengthens efficacy claims under US EPA and ECHA mandates. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform market projections. Primary insights came from R&D chemists, hospital procurement managers, retail category buyers, and regulatory affairs specialists. Secondary validation drew from customs data, US EPA and ECHA regulatory filings, and company financial reports. This approach ensured robust bottom-up and top-down triangulation of market data.
The forecast window was anchored to historical reference periods to establish baseline market performance. The analytical framework modeled key segments including product type, application, formulation, and end user. Compound annual growth rates were derived from historical trends and projected growth drivers. Industry-specific forecast inputs included bio-based raw material availability and evolving public health expenditure patterns across key geographies.
Caveats apply where new pathogen outbreaks or major regulatory shifts could materially shift the outlook. Forecasts reflect assumptions concerning economic stability and sustained public health focus. Practitioners should monitor evolving environmental sustainability targets and new active ingredient approvals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
Disinfectant Chemicals Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
Artificial Preservatives Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Sterilants Market
Disinfectants and Preservatives
Disinfectant Fogging and Misting Chemicals for Large Facilities Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
Continuously Sterilized Product Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market