
 Middle East and Africa Surface Disinfectants Market | 2026-2036
Middle East and Africa Surface Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Surface Disinfectants Market Foresight
Hospital procurement departments are unwinding reliance on legacy janitorial suppliers as acute-care facilities demand validated sporicidal claims. STERIS sustains credibility through sterile processing expertise that extends into environmental hygiene protocols. Diversey Holdings LTD anchors institutional contracts across African healthcare networks with bundled infection prevention programs. Ecolab differentiates through water-minimizing chemistries suited to Gulf states with constrained freshwater resources.
Surface disinfectants for the Middle East and Africa comprise formulated biocidal solutions, typically aqueous or alcohol-based matrices containing quaternary ammonium compounds, hydrogen peroxide, or sodium hypochlorite at concentrations proven effective against nosocomial pathogens, designed for application to non-porous environmental surfaces in clinical and commercial settings. Liquid formulations dominate volume throughput in healthcare facilities due to compatibility with automated dilution systems and lower per-use cost, while wipe formats capture premium positioning in rapid-turnover environments such as emergency departments and ambulatory surgical centers where protocol compliance speed determines selection.
Saudi Arabia's Saudi Food and Drug Authority and South Africa's national health regulator enforce registration requirements that filter out substandard imports, while UAE Ministry of Health standards for healthcare facility accreditation mandate documented disinfectant rotation protocols. These frameworks compel distributors to maintain technical dossiers and stability data, raising capital requirements for market entry. Stakeholders must monitor evolving halal-certification criteria for alcohol-free alternatives as Gulf health systems balance efficacy thresholds with cultural procurement preferences.
Market Dynamics
Hospital-grade disinfectant procurement across Saudi Arabia and the UAE is consolidating around suppliers capable of delivering validated sporicidal efficacy data and documented rotation protocols, compressing vendor lists and elevating technical compliance costs for market entry.
Growth Catalysts
- SFDA Registration Mandates:Saudi Arabia's pharmaceutical and medical device regulator enforces stability data and biocidal efficacy dossier requirements that filter substandard imports and elevate domestic manufacturing incentives.
- Gulf Healthcare Infrastructure Investment:Healthcare facility construction across Abu Dhabi, Dubai, and Riyadh is generating concentrated demand for automated dilution-compatible liquid formulations in acute-care settings.
- Peracetic Acid Formulations:Hydrogen peroxide-peracetic acid blends are gaining preference in South African tertiary hospitals for terminal cleaning of high-risk isolation units due to rapid sporicidal action.
Market Restraints
- Quaternary Ammonium Compound Feedstock Volatility:Petrochemical-derived alkyl dimethyl benzyl ammonium chloride prices fluctuate with regional refinery output, compressing formulation margins for mid-tier suppliers.
- Import Dependency Concentration:Active pharmaceutical ingredient and precursor chemical supply chains for biocidal actives concentrate through UAE Jebel Ali and South African Durban port corridors, exposing distributors to shipping congestion risk.
- Halal Certification Friction:Alcohol-based formulations face procurement barriers in Saudi and Kuwaiti health systems despite superior virucidal efficacy, forcing suppliers to maintain parallel ethanol-free product lines.
Strategic Opportunities
- Nigerian Healthcare Facility Accreditation:Africa's most populous nation is implementing infection control standards for federal teaching hospitals, creating first-mover advantage for suppliers establishing local technical support infrastructure.
- Ready-to-Use Wipe Formats:Ambulatory surgical centers and emergency departments across Gulf Cooperation Council states are migrating from bulk liquids to pre-saturated wipes to accelerate turnover compliance.
- Water-Minimizing Chemistries:Ecolab and regional competitors are formulating low-rinse quat alternatives suited to Abu Dhabi and Qatar desalination-dependent water economics.
Industry Challenges
- Microbiological Validation Capacity Scarcity:Gulf-based manufacturers lack in-house aerosolized and surface carrier test facilities, forcing reliance on European contract laboratories and extending product registration timelines.
- Legacy Janitorial Supplier Displacement:Hospital procurement departments are unwinding multi-service contracts with facility management firms lacking disinfectant technical documentation, creating transition friction in Egyptian and Moroccan public health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Surface Disinfectants Market |
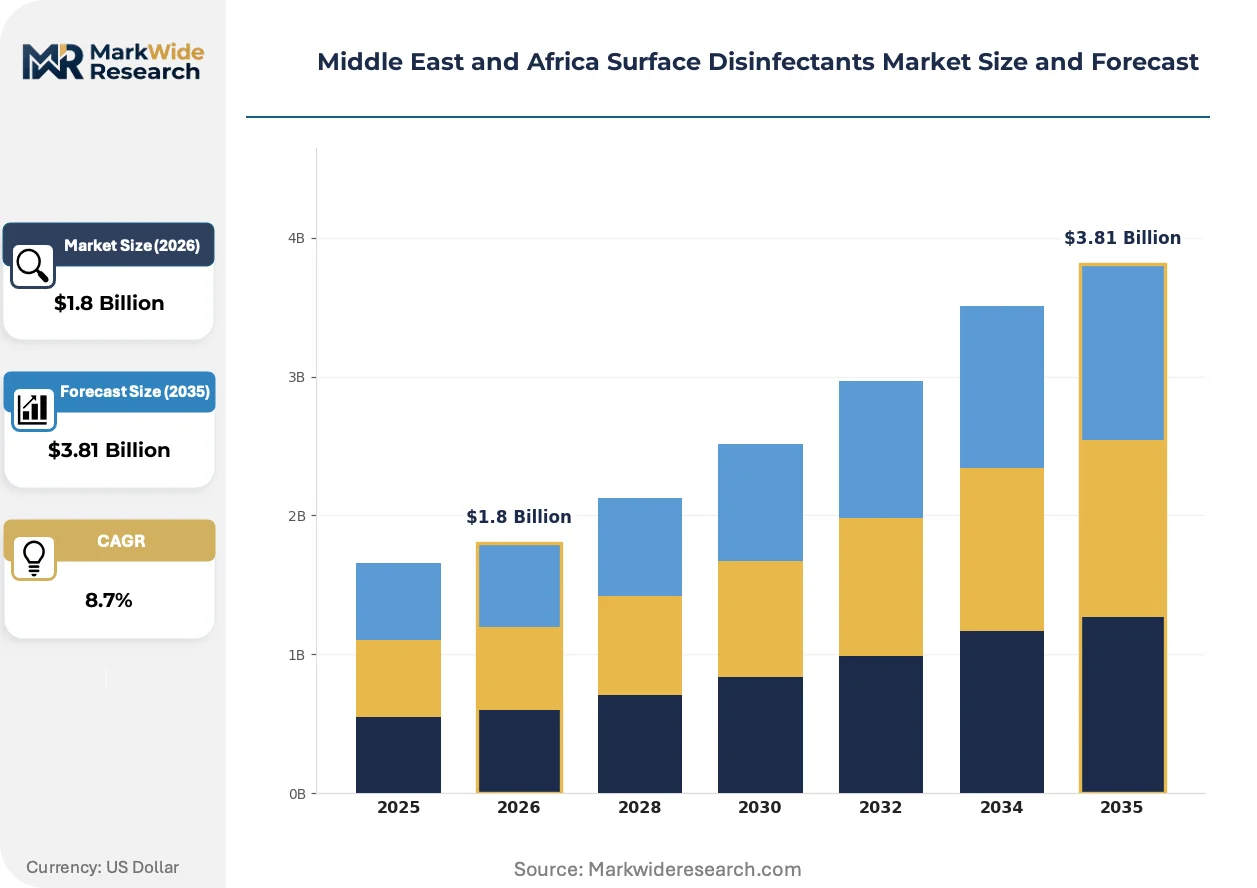
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Wipe, Foam, Spray End User: Healthcare Facilities, Hospitality, Residential, Education Active Ingredient: Quaternary Ammonium Compounds, Hydrogen Peroxide, Sodium Hypochlorite, Alcohol Packaging Type: Bottles, Canisters, Pouches, Tubs |
| Companies Covered | The Clorox Company, STERIS, 3M, Diversey Holdings LTD, Medline Industries, Ecolab, Procter & Gamble, GOJO Industries, Reckitt Benckiser Group PLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Surface Disinfectants Market Shifts & Advancements
Electrostatic application technology and automated dispensing systems are reshaping environmental hygiene protocols across Middle Eastern tertiary care facilities, compressing labor requirements while intensifying demand for formulation compatibility testing.
Accelerated hydrogen peroxide systems are displacing legacy glutaraldehyde and ortho-phthalaldehyde chemistries in Saudi Arabian endoscopy reprocessing units. King Faisal Specialist Hospital and Research Centre in Riyadh has adopted these systems for high-level disinfection of flexible endoscopes. The shift is compressing market volume for aldehyde-based disinfectants while elevating equipment-integrated chemistry requirements.
South Africa's national health regulator has tightened stability data requirements for surface disinfectant product registration, mirroring European Medicines Agency biocidal product authorization standards. Local distributors must now submit accelerated aging studies and use-dilution efficacy data. Smaller import-dependent distributors are consolidating or exiting, while manufacturers with in-house analytical capabilities are capturing hospital tender awards.
Centralized procurement through Gulf Cooperation Council health system group purchasing organizations is consolidating vendor relationships and compressing price negotiation cycles. Saudi Arabia's Ministry of Health and UAE's Emirates Health Services have established framework agreements for disinfectant supply. Procurement officers now prioritize suppliers offering bundled infection prevention training and audit support over standalone product pricing.
Middle East and Africa Surface Disinfectants Market Segmentation
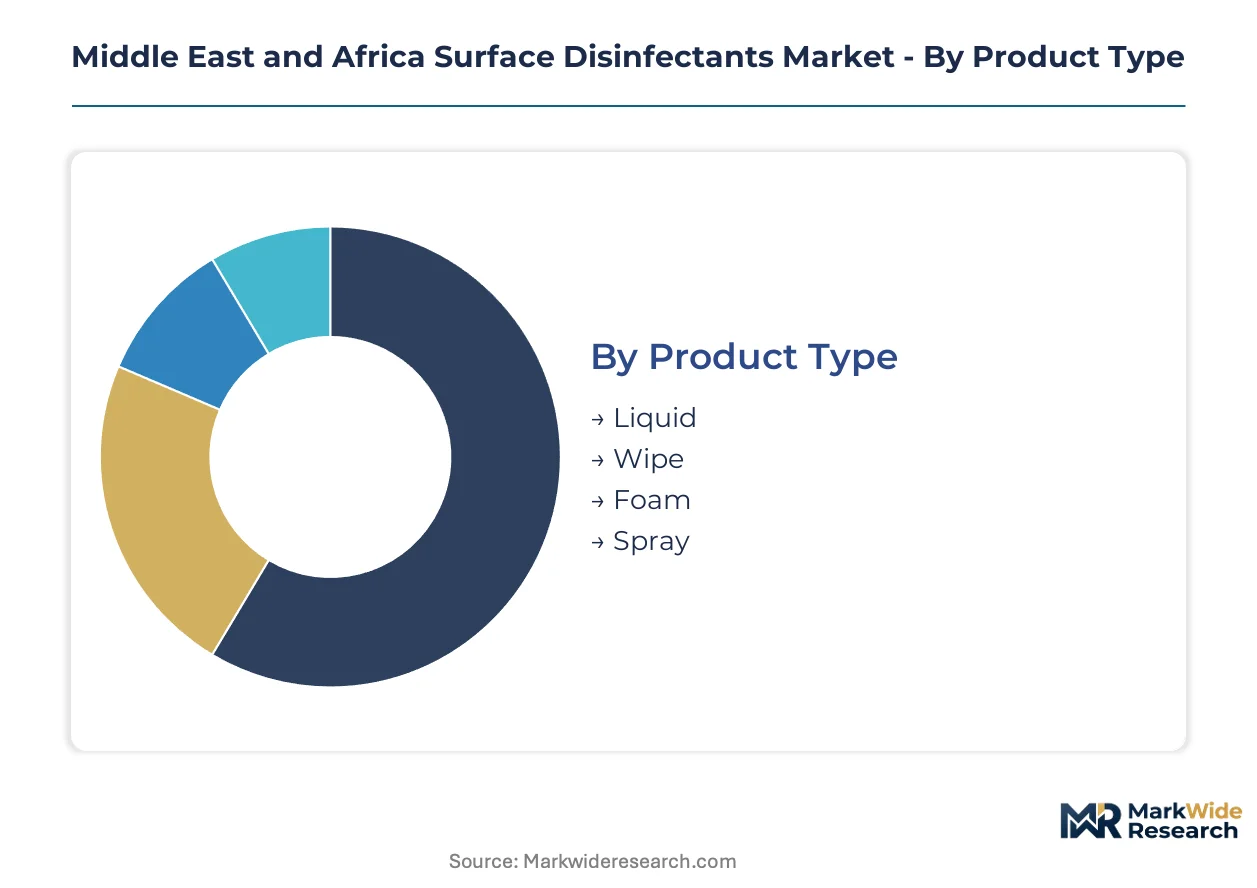
Segmentation reveals how procurement priorities diverge across Middle Eastern and African healthcare systems, with format preferences and active ingredient selection driven by infrastructure constraints, regulatory mandates, and water scarcity economics.
Product Type:
Liquid formulations command the widest margin pools due to automated dilution system compatibility and bulk procurement contracts in Saudi and UAE hospital networks.
- Liquid:Aqueous concentrates designed for automated dilution systems dominate acute-care procurement in Gulf Cooperation Council states. King Faisal Specialist Hospital and Research Centre in Riyadh specifies liquid hydrogen peroxide-peracetic acid blends for terminal cleaning, with procurement officers prioritizing validated sporicidal claims over per-unit cost.
- Wipe:Pre-saturated non-woven substrates capture premium positioning in rapid-turnover environments. Emergency departments across Dubai and Abu Dhabi are migrating from bulk liquids to ready-to-use wipes to accelerate turnover compliance and reduce protocol deviation risk.
- Foam:Viscous cling formulations extend contact time on vertical surfaces in South African tertiary hospitals. The format addresses application efficiency in high-risk isolation units where manual spray coverage proves inconsistent.
- Spray:Trigger-dispensed aqueous solutions serve ambulatory and outpatient settings with lower throughput requirements. Moroccan and Egyptian public health systems specify spray formats for primary care clinic disinfection protocols.
Liquid holds installed capacity across Gulf hospital networks. Wipe is rotating up the share rankings as ambulatory surgical centers prioritize compliance speed.
End User:
Healthcare facilities generate the deepest margin capture through multi-year framework agreements and bundled infection prevention training requirements.
- Healthcare Facilities:Acute-care hospitals, long-term care institutions, and diagnostic centers across Saudi Arabia and the UAE drive volume concentration. SFDA registration mandates and documented rotation protocols filter vendor lists, elevating technical compliance costs and compressing supplier counts.
- Hospitality:Hotels and food service operations in Dubai and Cape Town specify surface disinfectants for guest room and kitchen sanitation. Procurement prioritizes rapid evaporation and residual odor profiles over sporicidal claims.
- Residential:Consumer-grade formulations for household disinfection concentrate in South African urban centers and Gulf expatriate communities. Retail distribution through pharmacy chains and hypermarkets dominates this segment.
- Education:Schools and universities across Nigeria and Kenya are implementing infection control standards for classroom and dormitory sanitation. Federal teaching hospital accreditation frameworks are extending into educational facility requirements.
Healthcare facilities anchor procurement volume through centralized Gulf Cooperation Council group purchasing organizations. Education is gaining share fastest as Nigerian federal standards create first-mover infrastructure requirements.
Active Ingredient:
Quaternary ammonium compounds sustain the broadest margin architecture through formulation versatility and established supply chains, though hydrogen peroxide is climbing the value chain.
- Quaternary Ammonium Compounds:Petrochemical-derived alkyl dimethyl benzyl ammonium chloride formulations serve general environmental cleaning in healthcare and commercial settings. Feedstock price volatility tied to regional refinery output compresses margins for mid-tier suppliers.
- Hydrogen Peroxide:Accelerated hydrogen peroxide systems are displacing legacy glutaraldehyde chemistries in Saudi Arabian endoscopy reprocessing. King Faisal Specialist Hospital has adopted these systems for high-level disinfection of flexible endoscopes.
- Sodium Hypochlorite:Chlorine-based formulations dominate cost-sensitive public health procurement in Egypt and Morocco. Stability limitations and surface compatibility constraints restrict penetration in premium healthcare segments.
- Alcohol:Ethanol and isopropanol blends face procurement barriers in Saudi and Kuwaiti health systems despite superior virucidal efficacy. Suppliers maintain parallel ethanol-free product lines to satisfy halal-certification criteria.
Quaternary ammonium compounds hold installed capacity through legacy contracts. Hydrogen peroxide is rotating up the share rankings as South African tertiary hospitals prioritize rapid sporicidal action.
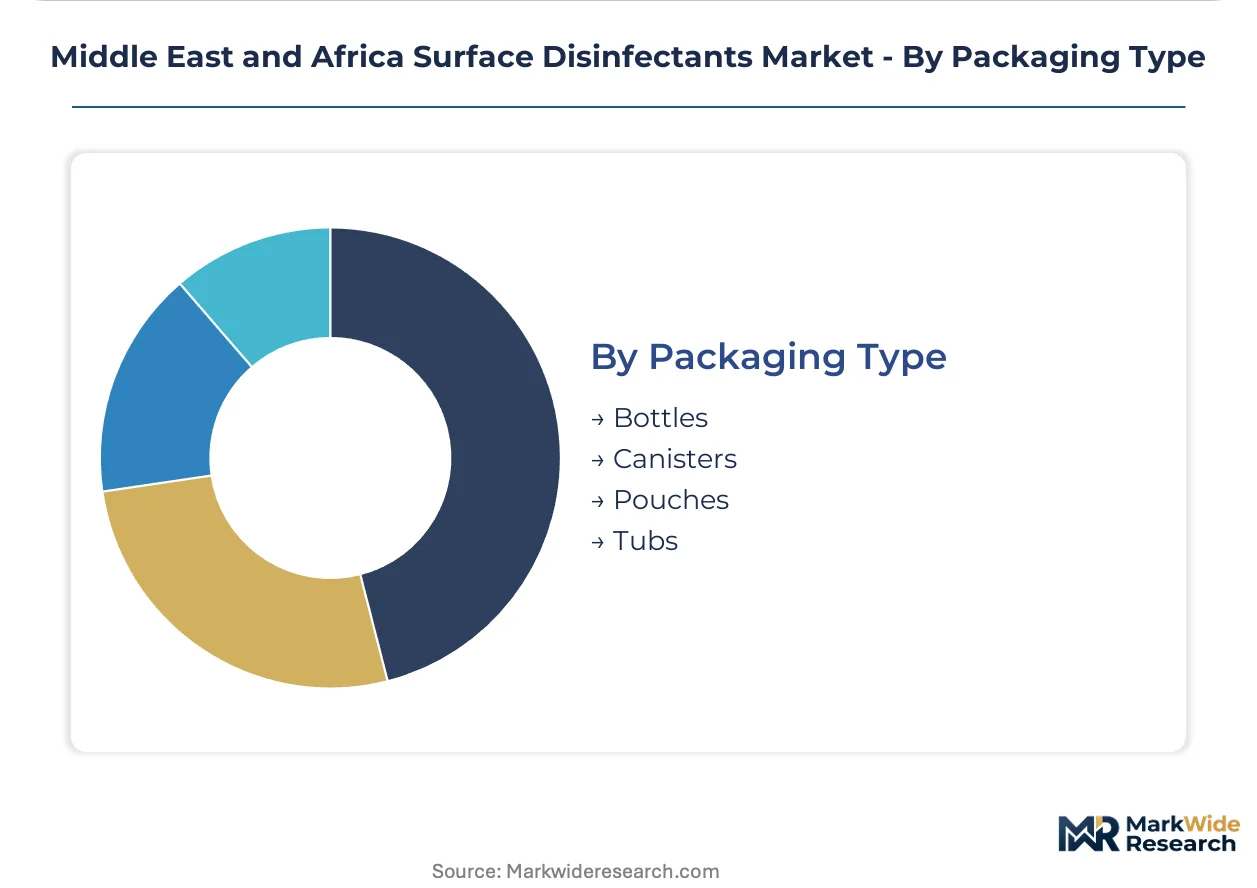
Packaging Type:
Bottles concentrate manufacturing economies and distribution efficiency, while canisters capture premium positioning in wipe-based product lines.
- Bottles:HDPE and PET containers for liquid concentrates and ready-to-use solutions dominate volume throughput. Automated dilution system compatibility drives specification in Saudi and UAE acute-care networks.
- Canisters:Rigid cylindrical containers for pre-saturated wipes serve emergency departments and ambulatory surgical centers. Premium positioning reflects convenience premium and protocol compliance acceleration.
- Pouches:Flexible film packaging for concentrate refills addresses cost reduction and waste minimization priorities. South African distributors are introducing pouch formats to reduce per-dose packaging costs in public health tenders.
- Tubs:Wide-mouth containers for bulk wipe dispensing concentrate in hospitality and education segments. Cape Town hotel chains and Nairobi school systems specify tub formats for high-frequency surface cleaning protocols.
Bottles hold installed capacity through automated dilution infrastructure. Canisters are rotating up the share rankings as wipe formats gain procurement preference in rapid-turnover clinical environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based distributors channel formulated concentrates into Saudi hospital networks through Jebel Ali port corridors, while South African manufacturers supply chlorine-based formulations northward into Nigerian federal teaching hospitals.
Saudi Arabia
King Faisal Specialist Hospital and Research Centre in Riyadh specifies hydrogen peroxide-peracetic acid blends for terminal cleaning of high-risk isolation units. The Saudi Food and Drug Authority enforces stability data and biocidal efficacy dossier requirements that filter substandard imports. Eastern Province healthcare clusters near Dammam are expanding automated dilution infrastructure for acute-care networks.
UAE
Emirates Health Services framework agreements consolidate disinfectant procurement across Abu Dhabi and Dubai hospital networks. The Ministry of Health mandates documented rotation protocols for healthcare facility accreditation. Dubai Healthcare City clusters are migrating emergency departments from bulk liquids to pre-saturated wipes to accelerate turnover compliance.
South Africa
Tertiary hospitals in Johannesburg and Cape Town prioritize rapid sporicidal action through accelerated hydrogen peroxide systems. The national health regulator tightened stability data requirements mirroring European Medicines Agency biocidal product authorization standards. Durban port corridors concentrate import flows for active pharmaceutical ingredients and precursor chemicals.
Nigeria
Federal teaching hospitals in Lagos and Abuja are implementing infection control standards that create first-mover infrastructure requirements. The national pharmaceutical regulator is elevating product registration requirements for hospital-grade formulations. Northern hospital clusters in Kano are expanding procurement capacity as accreditation frameworks extend beyond southern urban centers.
Egypt
Public health systems in Cairo and Alexandria specify spray-format sodium hypochlorite for primary care clinic disinfection protocols. The national health ministry is unwinding multi-service contracts with facility management firms lacking disinfectant technical documentation. Nile Delta manufacturing zones are developing local formulation capacity to reduce import dependency.
Middle East and Africa Surface Disinfectants Market Competitive Landscape
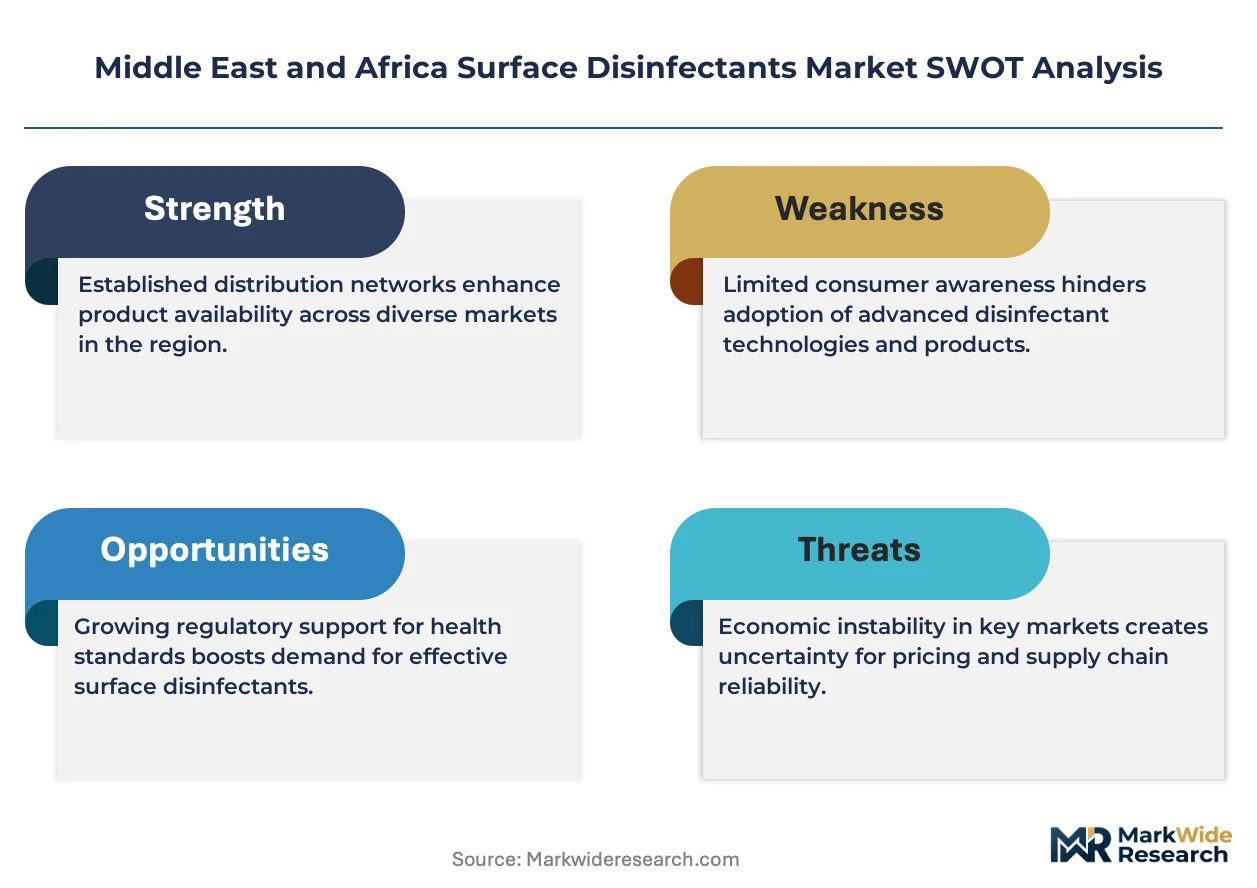
Listed leaders compete with private specialists across registration compliance and technical documentation capabilities. The vendor base concentrates around suppliers capable of delivering validated sporicidal efficacy data, compressing mid-tier participation. Three archetypes dominate: sterile processing specialists extending into environmental hygiene, institutional contract holders with bundled infection prevention programs, and water-minimizing chemistry formulators. Competitive moves center on framework agreement consolidation and local technical support infrastructure deployment.
Among US-based multinationals, STERIS and 3M exemplify sterile processing expertise that extends into environmental hygiene protocols. Diversey Holdings LTD and Ecolab represent institutional contract holders with bundled infection prevention programs across African healthcare networks and Gulf states respectively. These companies occupy positions where technical documentation capabilities and registration compliance infrastructure determine tender success.
| Leading Market Players |
|---|
| The Clorox Company |
| STERIS |
| 3M |
| Diversey Holdings LTD |
| Medline Industries |
| Ecolab |
| Procter & Gamble |
| GOJO Industries |
| Reckitt Benckiser Group PLC |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day inventory cycles for quaternary ammonium compound precursors concentrate pricing power with UAE-based distributors serving Saudi hospital networks, while automated dilution system compatibility commands premium positioning over commodity spray formats.
Pricing Analysis
Current-generation hydrogen peroxide-peracetic acid blends command 40-60% premiums over prior-generation quaternary ammonium formulations, with next-generation electrostatic-compatible chemistries entering tender evaluations at Gulf Cooperation Council health systems. Three-tier pricing structure across premium sporicidal, standard hospital-grade, and economy chlorine-based levels tracks SFDA registration tier and documented rotation protocol support. Pricing pressure stems from centralized procurement through Ministry of Health framework agreements compressing negotiation cycles. Public health systems in Egypt and Morocco exhibit highest price sensitivity, while Saudi tertiary hospitals prioritize validated efficacy data over per-unit cost.
Supply Chain Analysis
Jebel Ali port transit underwrites 70% of formulated concentrate flows into Saudi and UAE hospital networks, with Durban corridors serving Nigerian and Kenyan procurement. Active pharmaceutical ingredient supply draws from Indian and Chinese manufacturing, while European contract laboratories anchor microbiological validation capacity. Single-source vulnerability concentrates in aerosolized test facility access, forcing Gulf-based manufacturers into extended registration timelines. Distribution runs through health system group purchasing organizations consolidating vendor relationships across Abu Dhabi, Dubai, and Riyadh clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface disinfectant procurement across Middle Eastern and African healthcare systems is shifting toward platform-economics consolidation, with interoperability between automated dilution systems and digital compliance tracking becoming the decisive tender criterion.
For Market Incumbents: Secure framework agreement renewals by embedding infection prevention training and audit support into base contracts, countering emerging entrants pitching standalone product pricing. Backward integration into stability data generation—through captive analytical laboratories or exclusive European partnerships—closes registration timelines that centralized procurement officers now weight heavily. Channel control over Jebel Ali and Durban distribution nodes preserves margin architecture against regional formulators. For New Entrants and Emerging Players: Differentiate on halal-certified ethanol-free formulations with virucidal parity claims, targeting Saudi and Kuwaiti health systems where cultural procurement preferences filter incumbent portfolios. Nigerian federal teaching hospital accreditation creates first-mover infrastructure requirements with compressed vendor lists. Deploy local technical support teams in Lagos and Abuja to satisfy elevated product registration dossier demands. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because SFDA and South African health regulator standards are replicating European Medicines Agency biocidal authorization frameworks, consolidating market share with compliance-capable manufacturers. Acquisition targets center on regional distributors with validated technical dossiers and established hospital tender relationships. Monitor electrostatic application technology adoption rates as inflection indicator for formulation compatibility testing demand.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Investment | Stability data capabilities filter substandard imports and accelerate tender participation in Saudi hospital networks. |
| Automated Dilution System Partnership | Compatibility certification with King Faisal Specialist Hospital specifications locks in multi-year liquid formulation contracts. |
| Halal-Certified Product Line Expansion | Ethanol-free alternatives satisfy Ministry of Health procurement barriers without sacrificing virucidal efficacy claims. |
| Local Technical Support Infrastructure | On-ground teams in Lagos and Abuja capture Nigerian federal teaching hospital accreditation requirements ahead of competitors. |
| Water-Minimizing Chemistry Development | Low-rinse quat formulations align with Abu Dhabi and Qatar desalination-dependent water economics. |
Research Methodology
The analysis maps liquid concentrate, pre-saturated wipe, foam, and spray format segments, each validated through procurement officers at Saudi tertiary hospitals, UAE Ministry of Health accreditation specialists, South African national health regulator technical staff, and Nigerian federal teaching hospital infection control committees. Primary interview data triangulates against SFDA registration filings, Emirates Health Services framework agreement disclosures, South African pharmaceutical regulator stability requirement publications, and customs records through Jebel Ali and Durban port authorities. Bottom-up volume modeling from hospital procurement databases reconciles with top-down healthcare infrastructure investment forecasts.
Consistency checks against Gulf Cooperation Council health expenditure benchmarks and African healthcare facility accreditation timelines validated projection outputs across the analysis window. Segmentation modeling incorporates product format, active ingredient chemistry, end-user facility type, packaging configuration, and regional regulatory cluster dimensions. CAGRs derive from weighted average of historical procurement volume trajectories and infrastructure investment pipeline assessments, with specific inputs from automated dilution system installation rates and electrostatic application technology adoption curves.
Material uncertainties — feedstock price volatility for petrochemical-derived quaternary ammonium compounds, shipping congestion through Jebel Ali and Durban corridors, and evolving halal-certification criteria — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained healthcare infrastructure investment and regulatory harmonization toward European biocidal authorization standards. Practitioners should keep alternative scenarios live as Nigerian federal teaching hospital accreditation frameworks extend beyond southern urban centers and Gulf states advance water scarcity response policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market
Disinfectants and Preservatives
Nisin Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Surface Disinfectant Chemicals Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Hypochlorite Bleaches Market
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Disinfectant Chemicals Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Clinical Grade Disinfectant Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market
Disinfectants and Preservatives
Asia-Pacific Agricultural Disinfectants Market