
 Preservative Blends Market | 2026-2036
Preservative Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Preservative Blends Market Outlook
Buyer concentration among cosmetics multinationals is expanding as mid-sized personal care brands fragment across direct-to-consumer channels. BASF SE leverages its integrated phenoxyethanol supply chain to serve both premium and mass-market formulators. Lonza Group anchors its position through microbiological testing capabilities that pair with preservative sales. Croda International Plc differentiates via bio-based ethylhexylglycerin production, targeting brands seeking naturally derived antimicrobial systems.
Preservative blends are synergistic combinations of two or more antimicrobial agents—commonly phenoxyethanol with ethylhexylglycerin or organic acids with chelators—engineered to achieve broad-spectrum microbial control at lower total use concentrations than single-component systems. These formulations typically operate across pH ranges of 3.0 to 8.0 and serve primarily to protect water-containing products from bacterial and fungal spoilage during shelf life and consumer use. Liquid formulations dominate current volume due to ease of incorporation into emulsion manufacturing processes, while bio-based ingredient sources represent the fastest-expanding margin pool as clean-label requirements intensify across Cosmetics and Food & Beverages applications. Synthetic sources still occupy the largest revenue share, though fermented alternatives are gaining technical validation for replacement of paraben and formaldehyde-releasing chemistries.
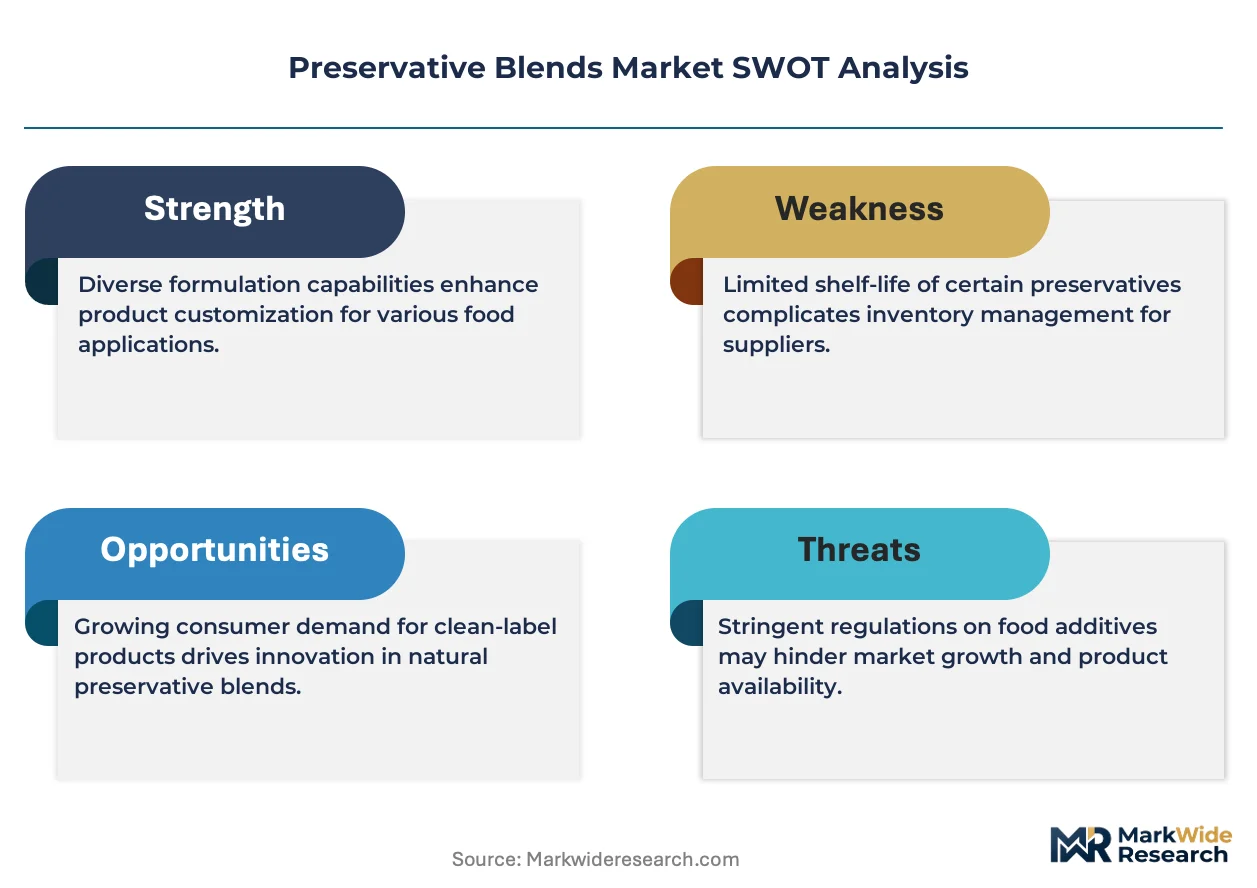
REACH restrictions on methylisothiazolinone concentrations and the FDA's modernized cosmetic safety framework are forcing reformulation cycles across European and North American manufacturing bases. ECHA's ongoing substance evaluations and state-level disclosure requirements in California are tightening compliance costs for synthetic preservative suppliers. Stakeholders must monitor regulatory divergence between EU hazard-based and US risk-based assessment paradigms when allocating R&D budgets across regional formulation pipelines.
Market Dynamics
EU REACH restrictions on methylisothiazolinone and isothiazolinone derivatives are forcing accelerated reformulation cycles across cosmetics and personal care manufacturing, redirecting procurement toward phenoxyethanol-ethylhexylglycerin systems and bio-based alternatives.
Growth Catalysts
- REACH Phase-Down Mandates:Concentration caps on isothiazolinones under ECHA substance evaluations are compelling manufacturers to adopt broad-spectrum phenoxyethanol blends with lower regulatory risk profiles.
- Clean-Label Positioning:Cosmetics brands seeking naturally derived positioning are driving technical validation of fermented organic acids and chelator combinations as paraben replacements.
- Water-Based Formulation Expansion:Rising SKU counts in skin care and hair care segments with high water content are expanding addressable volume for liquid preservative systems.
Market Restraints
- Feedstock Cost Volatility:Ethylene oxide and phenol price swings tied to crude oil benchmarks compress margin stability for phenoxyethanol producers.
- Technical Efficacy Ceilings:Bio-based alternatives face performance gaps against synthetic benchmarks in high-pH formulations and extended shelf-life requirements.
- Regulatory Divergence Friction:Misalignment between EU hazard-based and US risk-based safety assessments forces duplicative testing protocols for multinational suppliers.
Strategic Opportunities
- India Personal Care Expansion:FSSAI cosmetic safety modernization and rising middle-class consumption in Maharashtra and Gujarat create underpenetrated demand for mid-tier preservative systems.
- Food & Beverage Crossover:Clean-label requirements in plant-based beverages and refrigerated sauces are opening technical applications for organic acid-chelator blends beyond traditional cosmetics.
- Microbiome-Friendly Positioning:Selective antimicrobial technologies that preserve beneficial skin flora represent whitespace for premium positioning in dermatological and baby care segments.
Industry Challenges
- Microbiological Validation Timelines:Extended challenge testing protocols for novel bio-based actives stretch product development cycles and delay commercialization.
- Formulation Integration Complexity:Compatibility screening with emerging emulsifier systems and natural thickeners requires specialized technical service capabilities that strain mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preservative Blends Market |
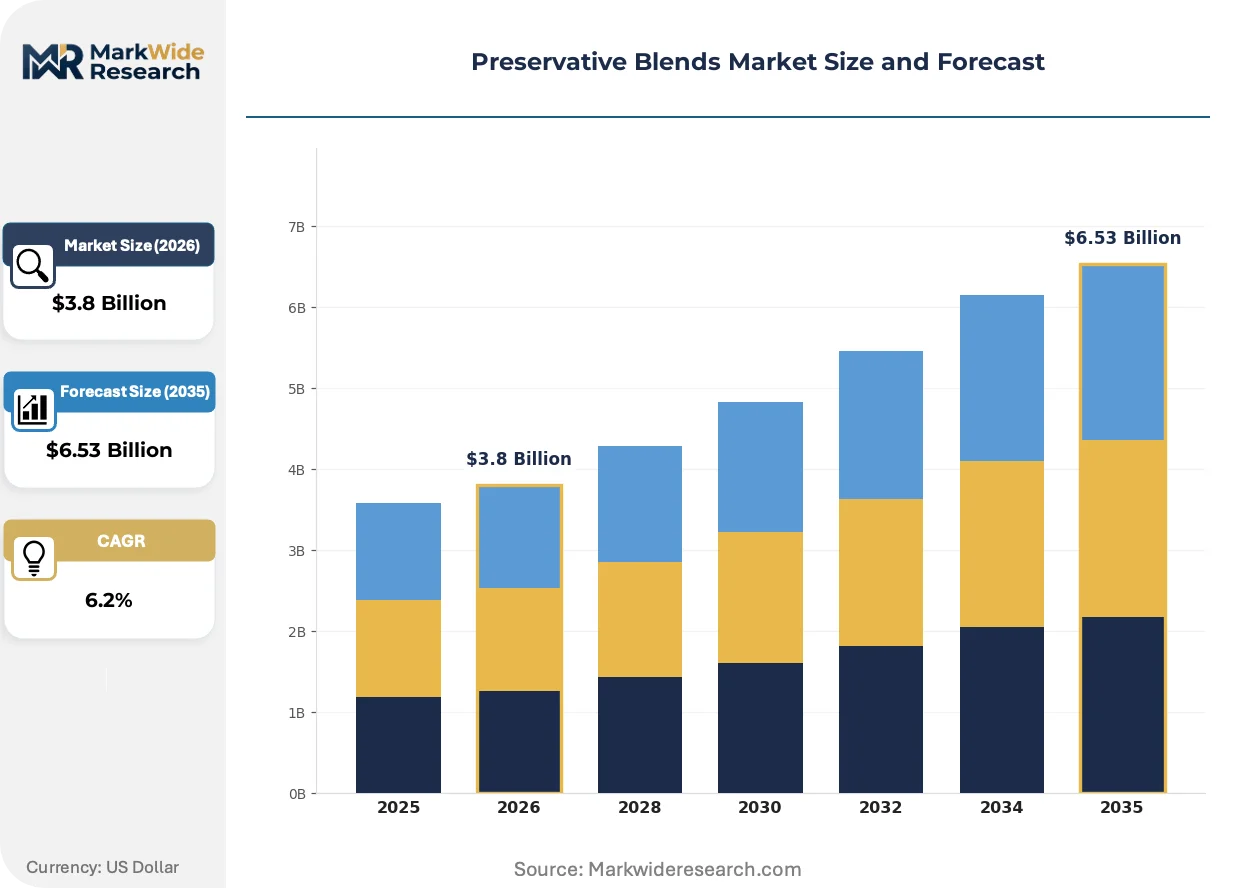
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Liquid, Powder, Gel, Emulsion Application: Cosmetics, Food & Beverages, Pharmaceuticals, Cleaning Products Ingredient Source: Natural, Synthetic, Fermented, Bio-based End User: Manufacturers, Retailers, Distributors, Food Producers |
| Companies Covered | BASF SE, Lonza Group, Clariant AG, DuPont de Nemours, Corbion N.V., Symrise AG, Evonik Industries AG, Ashland Global Holdings, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preservative Blends Market Strategic Shifts
Fermentation-derived antimicrobial compounds are absorbing capital allocation and technical development resources across the supplier base, compressing the timeline for viable paraben replacement while reshaping competitive positioning around bio-based credibility.
Enzymatic biosynthesis of ethylhexylglycerin from plant-derived glycerol feedstocks is absorbing R&D investment from specialty chemical producers seeking to decouple from petrochemical supply chains. Premium cosmetics formulators in Germany and France are accelerating qualification timelines for these materials. The technology is absorbing regulatory compliance burdens by preemptively addressing ECHA substance evaluation criteria for persistent, bioaccumulative, and toxic endpoints.
REACH authorization requirements for formaldehyde-releasing preservatives are tightening disclosure obligations and accelerating phase-out timelines across European manufacturing. The regulation is compressing demand for DMDM hydantoin and diazolidinyl urea in rinse-off products. German and French formulators are responding with accelerated adoption of phenoxyethanol-ethylhexylglycerin systems validated under the EU Cosmetics Regulation.
Direct-to-consumer brand proliferation is fragmenting buyer concentration and compressing minimum order quantities across the customer base. Mid-sized personal care brands are bypassing traditional distribution channels to source preservative blends through specialized chemical distributors and co-manufacturing networks. This pattern is most visible in California and New York, where indie beauty incubators are driving demand for flexible, low-volume preservative procurement with rapid technical support turnaround.
Preservative Blends Market Segmentation
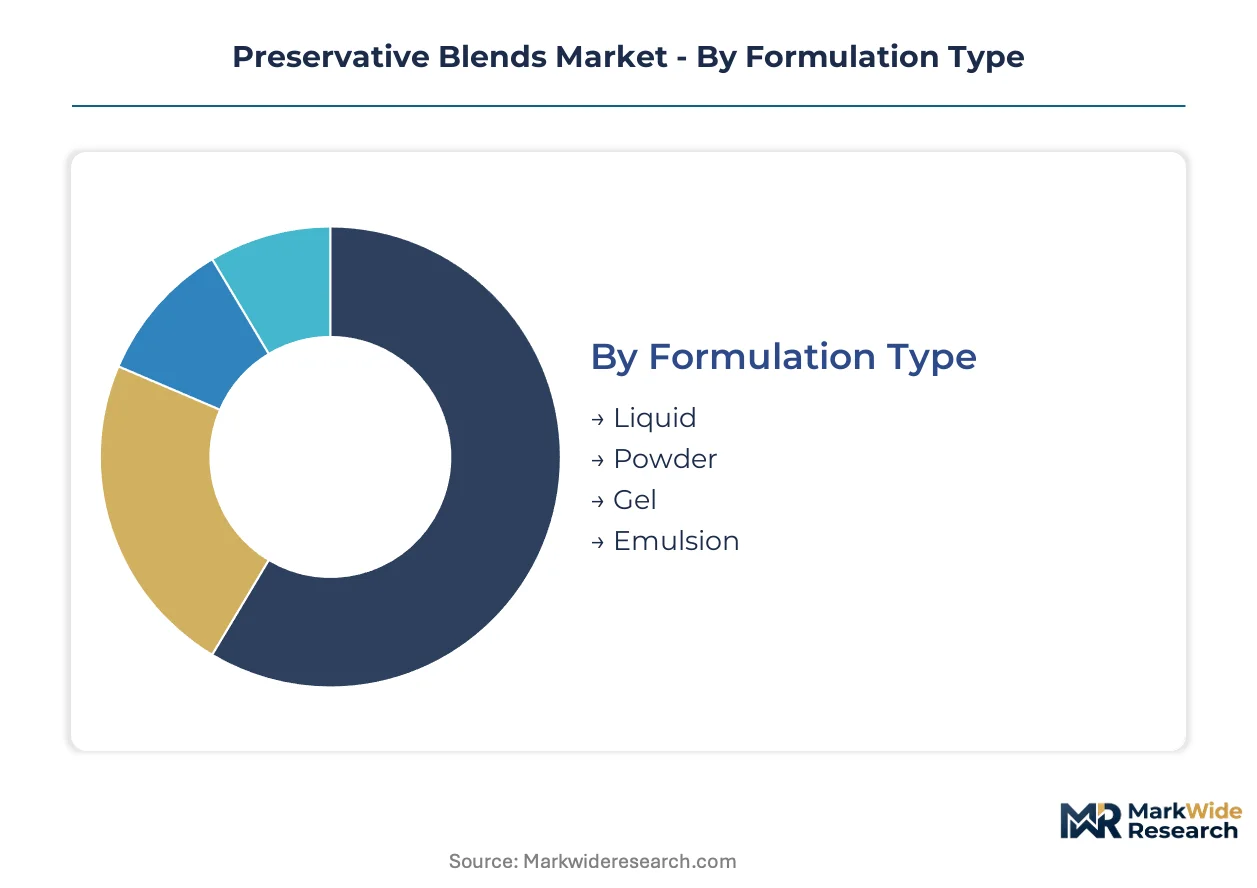
Preservative blend suppliers engineer distinct formulations around manufacturing integration constraints and end-use microbial challenges. Segmentation reveals where capital deployment concentrates and which technical specifications command formulation priority.
Formulation Type:
Liquid systems demand the heaviest upfront investment in dedicated blending vessels and inert gas protection infrastructure.
- Liquid:Homogeneous solutions of phenoxyethanol-ethylhexylglycerin or organic acid-chelator combinations dissolve readily into emulsion manufacturing without heating cycles. Cosmetics manufacturers in Germany's Rhine-Main cluster specify these for high-volume skin care production where rapid incorporation minimizes batch cycle times.
- Emulsion:Pre-dispersed active phases stabilize water-in-oil matrices for sensitive formulations requiring uniform antimicrobial distribution. Premium hair care brands in France source these for leave-in conditioners where phase separation risks spoilage claims.
- Powder:Spray-dried or crystalline actives suit dry powder cosmetics and instant beverage mixes with zero water activity.
- Gel:Thickened aqueous bases target small-batch artisanal producers needing precision dosing control.
Liquid absorbs the bulk of installed capacity; emulsion is expanding most quickly.
Application:
End-use selection determines regulatory pathway complexity and technical service intensity.
- Cosmetics:Broad-spectrum systems must satisfy EU Cosmetics Regulation Annex V positive lists and California Safe Cosmetics Program disclosure rules. Water-based skin care and hair care SKUs in Germany and France drive procurement of phenoxyethanol blends as REACH restricts isothiazolinone alternatives.
- Food & Beverages:Organic acid-chelator combinations face EFSA food additive evaluations and FDA GRAS self-determination pathways. Plant-based beverage manufacturers in California adopt these for clean-label positioning against synthetic benzoates.
- Pharmaceuticals:USP and EP compliance for injectable and ophthalmic preparations demands endotoxin-controlled manufacturing environments.
- Cleaning Products:Hard surface disinfectant claims trigger EPA registration timelines distinct from cosmetic preservative approvals.
Cosmetics commands the deepest technical service relationships; food and beverage applications are climbing the fastest.
Ingredient Source:
Feedstock provenance shapes margin structure and regulatory pre-positioning.
- Synthetic:Petrochemical-derived phenoxyethanol and ethylhexylglycerin offer batch-to-batch consistency and lowest unit economics. Established supply chains from BASF's Ludwigshafen complex serve mass-market cosmetics with full REACH registration dossiers.
- Bio-based:Plant-derived glycerol feedstocks for ethylhexylglycerin biosynthesis preempt ECHA PBT screening while satisfying Sephora and Ulta clean-label vendor requirements. French premium formulators accelerate qualification timelines for these materials.
- Natural:Extract-based systems from rosemary, grapefruit seed, and tea tree oil face standardization challenges for broad-spectrum efficacy claims.
- Fermented:Microbially produced organic acids and bacteriocins absorb R&D capital for paraben replacement validation.
Synthetic maintains the largest production footprint; bio-based is gaining share fastest.
End User:
Customer scale and channel structure determine pricing architecture and minimum order economics.
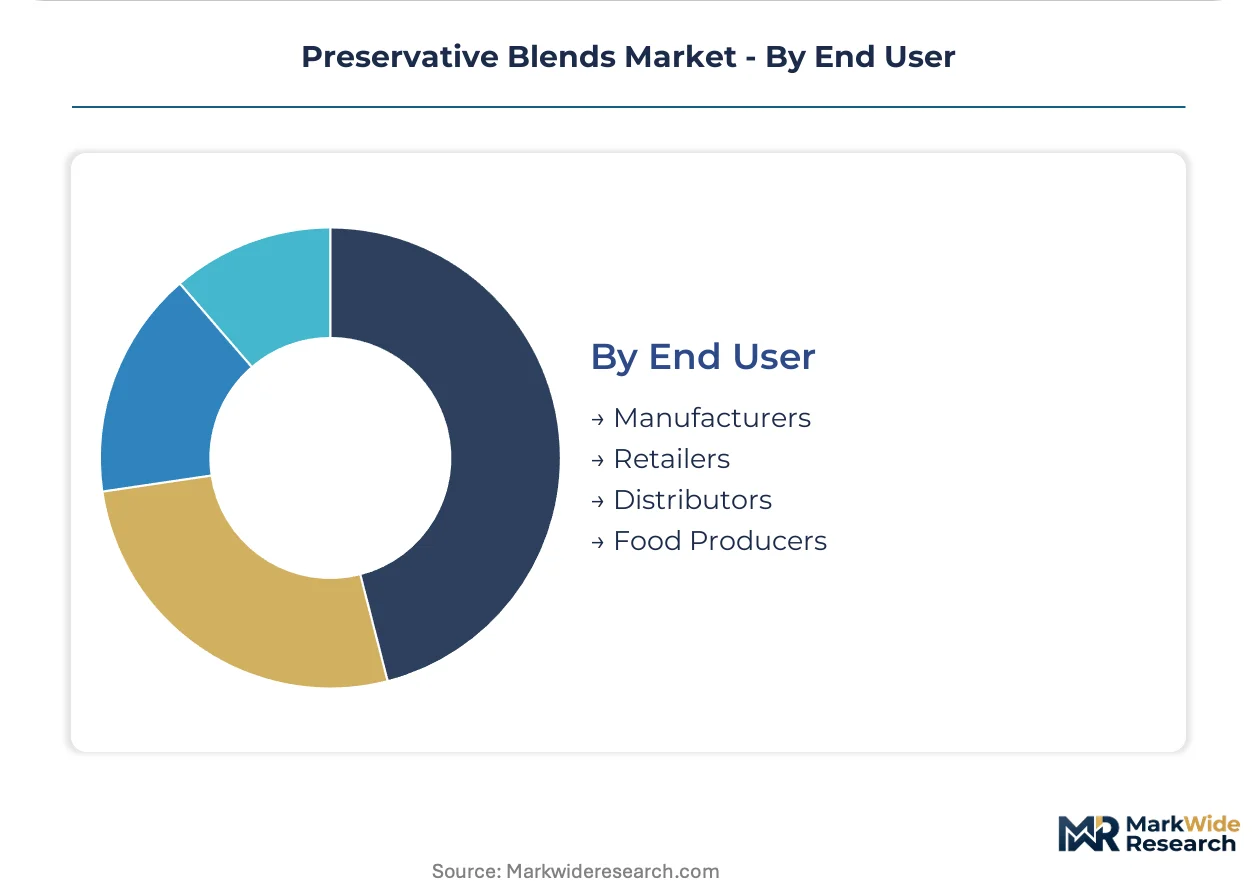
- Manufacturers:Integrated cosmetics and food production facilities in Germany's chemical corridor negotiate multi-year supply agreements with technical service riders for formulation troubleshooting. These buyers specify custom phenoxyethanol-ethylhexylglycerin ratios for proprietary preservation systems.
- Food Producers:Beverage and sauce manufacturers in California and New York source organic acid blends through specialized distributors for refrigerated clean-label lines.
- Distributors:Regional chemical distributors aggregate fragmented indie beauty demand in California and New York, compressing order quantities and expanding technical support overhead.
- Retailers:Private-label cosmetics programs at mass-market chains specify standard preservative blends with locked formulations.
Manufacturers anchor volume commitments; food producers are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's chemical corridor, where specialty producers near Frankfurt and Ludwigshafen anchor European supply. France and the United States follow as formulation hubs. India's personal care sector is expanding procurement of mid-tier systems.
Germany
Cosmetics manufacturers in the Rhine-Main cluster specify liquid phenoxyethanol-ethylhexylglycerin systems for high-volume skin care production. ECHA substance evaluations on isothiazolinones are accelerating reformulation cycles toward REACH-registered alternatives. BASF's Ludwigshafen complex supplies mass-market formulators with integrated phenoxyethanol production.
France
Premium hair care brands in Paris source emulsion-based pre-dispersed actives for leave-in conditioners requiring phase stability. ANSM cosmetic safety oversight aligns with EU Cosmetics Regulation Annex V enforcement. French formulators are qualifying bio-based ethylhexylglycerin from plant-derived glycerol feedstocks ahead of ECHA PBT screening.
United States
Indie beauty incubators in California and New York are fragmenting buyer concentration through direct-to-consumer channels. FDA modernized cosmetic safety guidance and California Safe Cosmetics Program disclosure rules are tightening compliance requirements. Specialized chemical distributors in these states aggregate low-volume procurement with rapid technical support.
India
Rising middle-class consumption in Maharashtra and Gujarat is expanding addressable volume for mid-tier preservative systems. FSSAI cosmetic safety modernization is elevating manufacturing standards for domestic and export markets. Mumbai-based formulators are sourcing organic acid-chelator blends for plant-based beverage lines targeting clean-label positioning.
Switzerland
Swissmedic pharmaceutical compliance requirements are driving demand for endotoxin-controlled preservative systems in injectable applications. Precision manufacturing around Basel serves both domestic drug producers and cross-border EU supply. Specialty distributors here focus on USP and EP validation documentation for high-specification procurement.
Preservative Blends Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based credentialing and microbiome-friendly positioning. The supplier base organizes around three archetypes: integrated petrochemical majors with captive feedstock access, specialty chemical houses with microbiological testing capabilities, and fermentation-focused innovators validating paraben replacements. Dominant competitive moves include backward integration into glycerol feedstocks and strategic partnerships with indie beauty distributors for technical service coverage.
Among European-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify scale-driven archetypes with integrated phenoxyethanol supply chains. Lonza Group occupies a position within the testing-anchored tier, pairing microbiological validation services with preservative sales. These three represent distinct strategic postures: petrochemical integration, technical service bundling, and regulatory pre-positioning through REACH dossier depth.
| Leading Market Players |
|---|
| BASF SE |
| Lonza Group |
| Clariant AG |
| DuPont de Nemours |
| Corbion N.V. |
| Symrise AG |
| Evonik Industries AG |
| Ashland Global Holdings |
| Croda International Plc |
| Others |
Value Chain & Pricing Dynamics
Backward integration into ethylene oxide and phenol feedstocks anchors pricing power for established phenoxyethanol producers while compressing margin flexibility for non-integrated suppliers facing crude oil benchmark volatility. This structural asymmetry concentrates margin capture in Germany's Rhine-Main chemical corridor where captive supply chains serve mass-market cosmetics formulators with locked-in cost positions.
Pricing Analysis
Volume-mass-market tiers absorb commodity pressure while premium bio-based tiers command margin expansion. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered synthetic systems from fermented alternatives and unvalidated natural extracts. Cost compression in standard phenoxyethanol blends is intensifying because ethylene oxide price swings transmit directly to non-integrated producers. Indie beauty distributors in California exhibit highest price sensitivity; pharmaceutical manufacturers in Switzerland show lowest sensitivity due to USP validation requirements.
Supply Chain Analysis
Single-source vulnerability sits with China's glycerol feedstock concentration for bio-based ethylhexylglycerin production. Manufacturing gravity centers on Germany, China, and the United States for phenoxyethanol and ethylhexylglycerin synthesis. The supply chain draws from ethylene oxide, phenol, and plant-derived glycerol as core inputs. Tariff exposure on Chinese glycerol derivatives threatens bio-based production economics. Distribution runs through specialized chemical distributors aggregating fragmented indie beauty demand in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as REACH compliance costs and extended microbiological validation timelines force sub-scale suppliers toward exit or acquisition. ECHA substance evaluation burdens disproportionately disadvantage mid-tier players lacking integrated testing capabilities.
For Market Incumbents: Anticipate regulatory divergence between EU hazard-based and US risk-based paradigms by maintaining parallel dossier depth for phenoxyethanol-ethylhexylglycerin systems. Prioritize backward integration into glycerol feedstocks to decouple from petrochemical price volatility. Defend against fermentation-focused innovators by accelerating microbiome-friendly positioning in dermatological segments.
For New Entrants and Emerging Players: Enzymatic biosynthesis of ethylhexylglycerin from plant-derived glycerol offers a technology-first wedge into premium French and German cosmetics formulators. Target India's Maharashtra and Gujarat personal care expansion as the most penetrable geography with FSSAI modernization elevating standards. Pursue co-manufacturing partnerships with Mumbai-based plant-based beverage producers seeking clean-label organic acid-chelator systems.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical houses with microbiological testing capabilities that pair with preservative sales. Long-term viability favors suppliers with REACH dossier depth and bio-based technical validation. Acquisition target archetype: fermentation-focused innovators with validated paraben replacement candidates. Watch ECHA PBT screening outcomes on bio-based alternatives as the critical inflection signal for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycerol Feedstocks | Decouples bio-based ethylhexylglycerin production from petrochemical price volatility in China. |
| Microbiome-Friendly Technology Development | Opens premium positioning in dermatological and baby care segments ahead of regulatory restrictions. |
| REACH Dossier Expansion | Preempts ECHA substance evaluation criteria for phenoxyethanol-ethylhexylglycerin system registrations. |
| India Distribution Partnership | Captures FSSAI modernization-driven demand in Maharashtra and Gujarat personal care manufacturing. |
| Food & Beverage Crossover Validation | Extends organic acid-chelator applications beyond cosmetics into California plant-based beverage lines. |
Study Parameters
Trade databases, ECHA substance evaluation records, and SEC filings from listed chemical producers formed the secondary backbone for supply-side calibration. Primary interviews with cosmetics formulators, regulatory affairs specialists at preservative suppliers, technical R&D directors, and procurement leads at German chemical clusters combined with secondary validation to triangulate demand-side parameters. Bottom-up SKU-level analysis across formulation types and end-use applications reconciled with top-down regional consumption estimates.
Historical trendline analysis of phenoxyethanol and ethylhexylglycerin production volumes established baseline growth patterns across the projection horizon. The analytical framework modeled segmentation across formulation type, application, ingredient source, and end-user scale to derive CAGRs. Industry-specific inputs included ECHA regulatory timeline assumptions, FSSAI modernization pace in India, and clean-label adoption curves in California and New York indie beauty channels.
Several conditions sit outside the modeled scope, including unannounced REACH authorization expansions, breakthrough fermentation technologies displacing synthetic benchmarks, and geopolitical disruptions to Chinese glycerol supply. Forecasts reflect documented assumptions about regulatory implementation timelines and technical validation success rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Hypochlorous Acid Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Warehouse Fumigants Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Chlorinators Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Pyrethroids Market