
 IV Disinfecting Caps Market | 2026-2036
IV Disinfecting Caps Market Size, Share, and Industry Trends Forecast 2026-2036
IV Disinfecting Caps Market Foresight
Outpatient infusion centers and long-term care facilities are redrawing procurement priorities away from traditional hospital-centric purchasing. B. Braun Melsungen AG anchors European manufacturing scale through vertically integrated polypropylene molding operations. 3M Company differentiates via proprietary antimicrobial coating technologies embedded in cap substrates. Merit Medical Systems, Inc. competes aggressively in the interventional radiology channel where procedure volume sustains premium pricing.
IV disinfecting caps are sterile closure devices applied to needleless connectors and catheter hubs, typically injection-molded from medical-grade polypropylene or silicone with integrated foam or antimicrobial additives to maintain aseptic barriers between administrations. Their primary purpose is preventing microbial ingress during intermittent intravenous therapy, particularly for central venous access devices. Single-use antimicrobial caps command the strongest margin pools due to infection-prevention premiums, while reusable variants face structural decline amid single-patient-use mandates. Hospital application segments dominate absolute volume, though homecare channels represent the fastest-growing demand arc as parenteral therapy shifts beyond acute settings.
FDA enforces 510(k) clearance pathways for cap devices with antimicrobial claims, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa accessories. The EPA regulates residual disinfectant chemistry in antimicrobial formulations, directly constraining material innovation cycles. Stakeholders must monitor evolving Joint Commission infection control standards and CMS quality metrics, as reimbursement linkages to CLABSI rates increasingly influence cap specification decisions at the facility level.
Market Dynamics
Hospital infection control committees are mandating antimicrobial IV cap protocols as CMS quality metrics tie CLABSI rates directly to reimbursement penalties, forcing procurement departments to elevate cap specification from commodity purchasing to clinical risk management.
Growth Catalysts
- FDA 510(k) Antimicrobial Claims Pathway:Clearance requirements for residual disinfectant efficacy are accelerating clinical validation investments and differentiating compliant suppliers from commodity molders.
- Homecare Parenteral Therapy Expansion:Patient discharge protocols for long-term antibiotic and chemotherapy administration are extending cap demand beyond acute care into ambulatory settings.
- Polypropylene Molding Scale Concentration:Vertically integrated European manufacturers are capturing margin pools through captive resin-to-device production, lowering unit costs for high-volume hospital contracts.
Market Restraints
- Medical-Grade Polypropylene Feedstock Volatility:Pharmaceutical-grade resin supply concentrates among three European petrochemical suppliers, exposing molders to input cost spikes and allocation constraints.
- EPA Residual Disinfectant Chemistry Limits:Antimicrobial formulation innovation cycles compress as environmental toxicity thresholds constrain active ingredient selection for cap substrates.
- Reusable Cap Substitution Collapse:Single-patient-use mandates from Joint Commission standards are structurally eliminating refurbishment service models regardless of cost efficiency.
Strategic Opportunities
- Japan Acute Care Infrastructure Modernization:Hospital consolidation programs and infection control investment waves are opening premium cap adoption in tertiary centers previously served by basic closures.
- Interventional Radiology Procedure Volume:Image-guided vascular access expansion creates dedicated channel demand for specialized hub designs with integrated antimicrobial barriers.
- EU MDR Class IIa Clinical Evidence Requirements:Stricter accessory validation standards are raising competitive barriers and creating first-mover advantage for manufacturers with established notified body relationships.
Industry Challenges
- ISO 13485 Quality Management System Implementation:Small and mid-size molders face certification timeline compression as notified body audit backlogs extend device registration schedules.
- Legacy Catheter Hub Compatibility:Proprietary luer designs from incumbent connector manufacturers force cap suppliers to maintain multi-SKU inventories and custom tooling investments.
- Sterilization Validation Capacity Bottlenecks:Gamma and ethylene oxide facility constraints are extending production lead times for antimicrobial formulations requiring terminal sterilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV Disinfecting Caps Market |
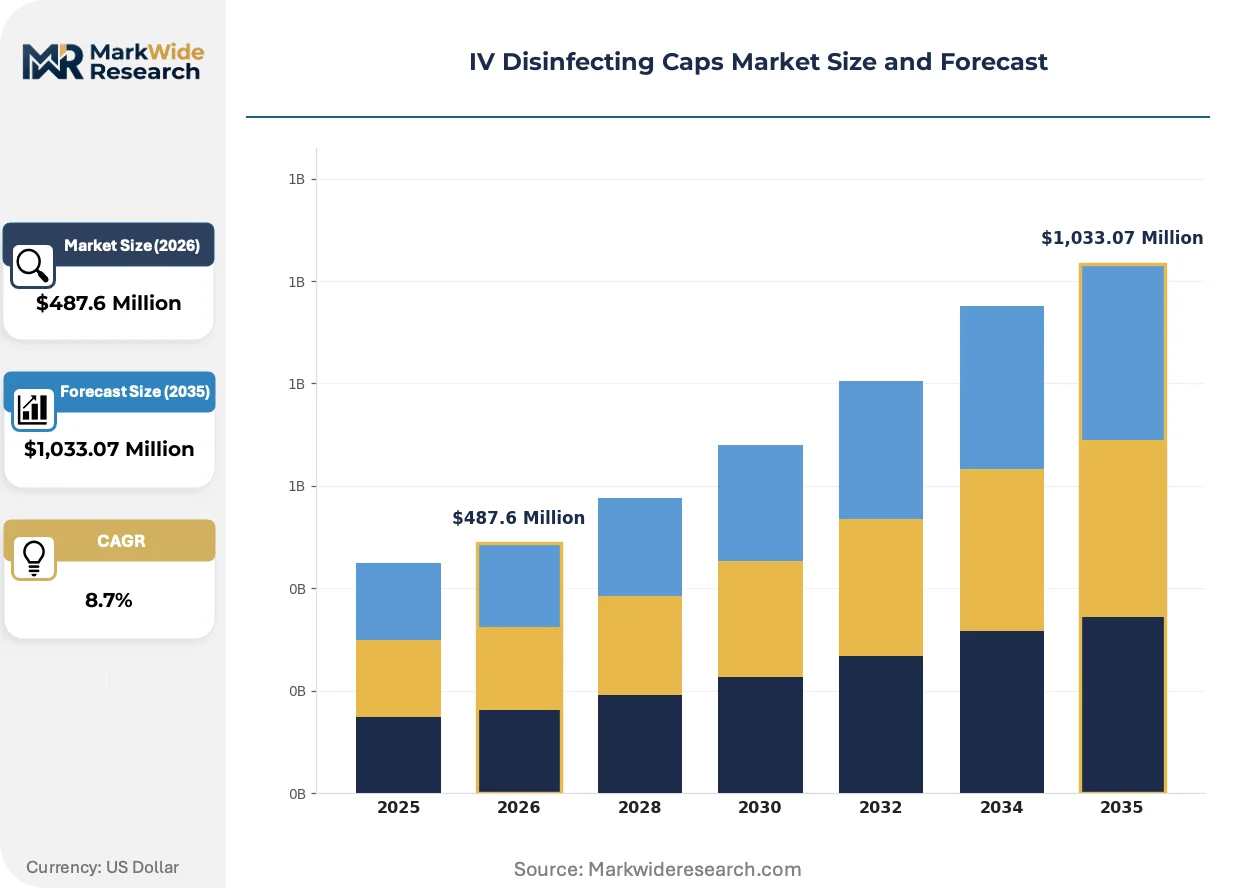
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Caps, Reusable Caps, Antimicrobial Caps, Standard Caps Material: Polypropylene, Silicone, PVC, Foam Application: Hospital, Homecare, Long-Term Care Facilities, Emergency Services End User: Clinics, Pharmacies, Hospitals, Healthcare Providers |
| Companies Covered | B. Braun Melsungen AG, Merit Medical Systems, Inc., 3M Company, Cardinal Health, Inc., Teleflex Incorporated, Becton, Dickinson and Company, Baxter International Inc., Medline Industries, Inc., ICU Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV Disinfecting Caps Market Shifts & Advancements
Antimicrobial material science and regulatory evidence requirements are converging to reshape competitive positioning, with differentiation shifting from mechanical design to validated clinical outcomes and supply chain traceability.
Silver-ion and chlorhexidine-impregnated polymer formulations are fragmenting the traditional foam-based cap segment. Outpatient infusion centers in Germany and the United States are piloting these substrates for extended-dwell catheter protocols. The technology is fragmenting procurement specifications as infection prevention committees demand documented microbial kill-rate data over commodity pricing.
EU Medical Device Regulation clinical evidence requirements for Class IIa accessories are tightening post-market surveillance obligations. Manufacturers must now maintain periodic safety update reports and vigilance systems for cap devices with antimicrobial claims. Interventional radiology departments across France, Germany, and Italy are responding by consolidating supplier relationships toward vendors with established MDR technical documentation capabilities.
Hospital procurement committees are elevating total-cost-of-infection metrics over unit price in cap selection criteria. Group purchasing organizations are restructuring contract tiers around CLABSI reduction guarantees rather than volume discounts. This behavioral shift is most pronounced in United States health systems participating in CMS Hospital-Acquired Condition Reduction Program penalties.
IV Disinfecting Caps Market Segmentation
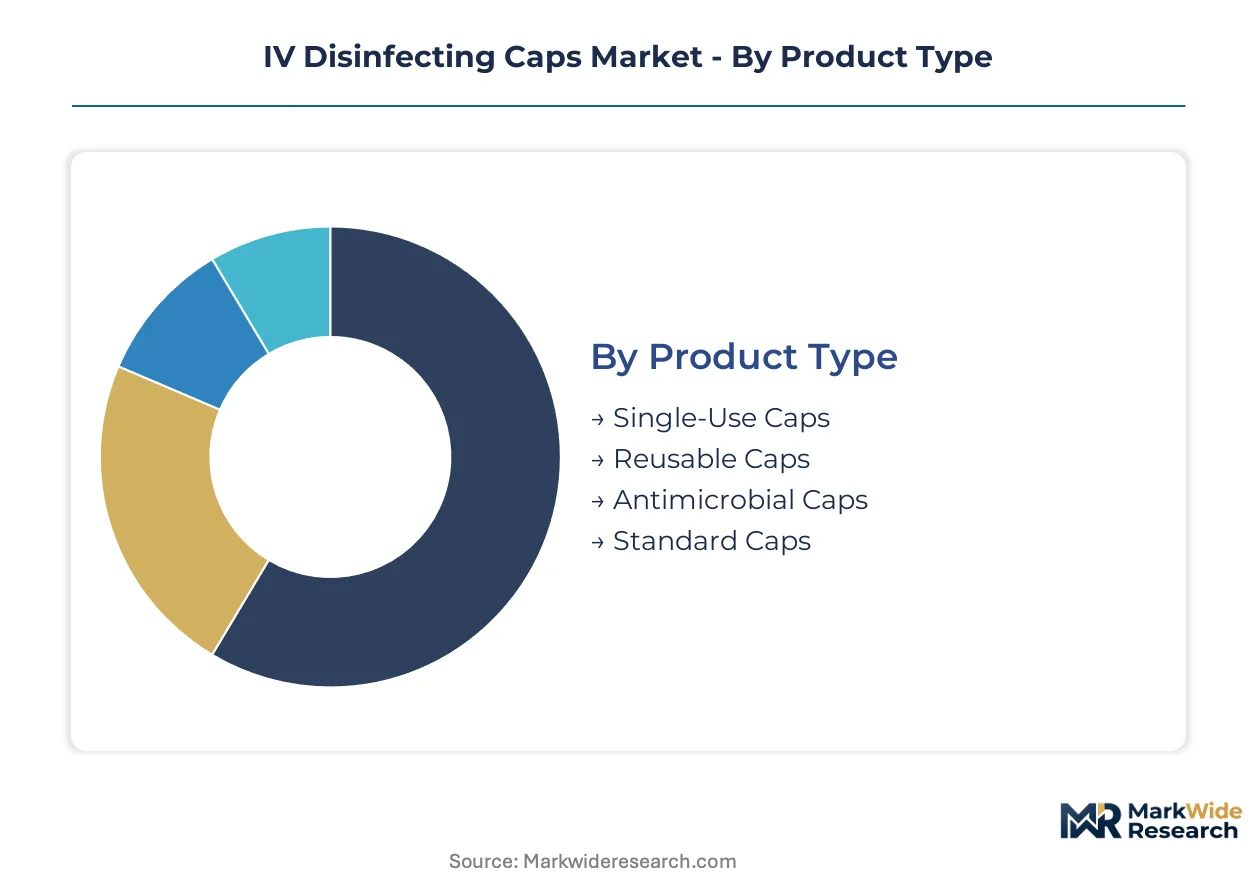
IV disinfecting cap procurement varies sharply across clinical settings and material specifications. Manufacturers must align production capacity with infection control mandates that differ by care environment and regulatory jurisdiction.
Product Type:
Domestic hospital systems drive volume for single-use antimicrobial variants, while export demand concentrates on standard closure formats for cost-sensitive procurement channels.
- Single-Use Caps:Injection-molded polypropylene devices with integrated foam barriers, designed for terminal sterilization and immediate disposal after catheter access. United States acute care systems specify these for CLABSI prevention protocols tied to CMS reimbursement penalties.
- Antimicrobial Caps:Substrates impregnated with silver-ion or chlorhexidine formulations providing sustained microbial kill rates between administrations. German outpatient infusion centers are piloting extended-dwell protocols with these substrates for chemotherapy patients.
- Reusable Caps:Silicone-based designs withstanding gamma sterilization cycles for limited reprocessing, now structurally declining under Joint Commission single-patient-use mandates.
- Standard Caps:Basic mechanical closures without antimicrobial claims, serving price-sensitive procurement in emerging markets and backup inventory positions.
Single-use antimicrobial caps command the established base. The steepest expansion runs through standard caps as basic infection control spreads to previously underserved health systems.
Material:
Cost tiers separate pharmaceutical-grade formulations from commodity resin alternatives, with premium specifications concentrating in tertiary centers and export markets.
- Polypropylene:Medical-grade homopolymer resins meeting USP Class VI biocompatibility standards, dominating high-volume hospital contracts through favorable sterilization compatibility. Vertically integrated European molders capture margin pools via captive resin-to-device production.
- Silicone:Platinum-cured elastomers offering superior compression set resistance for repeated hub connections. Japanese manufacturers favor this substrate for precision-molded designs in interventional radiology applications.
- PVC:Plasticized formulations for cost-constrained procurement, facing structural displacement as DEHP plasticizer regulations tighten across European and North American jurisdictions.
- Foam:Open-cell polyurethane or polyethylene inserts providing physical barriers against microbial ingress, commonly paired with polypropylene outer shells in hybrid cap constructions.
Polypropylene formulations anchor current volume. Silicone substrates are climbing the fastest as procedure specialization demands enhanced mechanical performance.
Application:
Customer type fragmentation is redrawing traditional channel structures, with acute care dominance giving way to distributed care models.
- Hospital:Centralized procurement through infection control committees specifying antimicrobial protocols for ICU, oncology, and surgical units. United States health systems participating in CMS Hospital-Acquired Condition Reduction Program elevate cap selection to clinical risk management.
- Homecare:Patient-administered parenteral therapy for long-term antibiotics, chemotherapy, and hydration protocols. German ambulatory care networks are expanding cap dispensing through specialty pharmacy channels.
- Long-Term Care Facilities:Skilled nursing and rehabilitation centers with intermittent IV access needs, increasingly subject to state-level infection control inspections.
- Emergency Services:Pre-hospital and trauma settings requiring rapid catheter hub protection under field conditions, prioritizing single-use convenience over antimicrobial sophistication.
Hospital procurement commands the established base. Homecare channels are gaining share fastest as discharge protocols extend parenteral therapy beyond acute settings.
End User:
Volume concentration differs from value concentration, with high-throughput facilities separated from specialized intervention sites by pricing tolerance and protocol complexity.
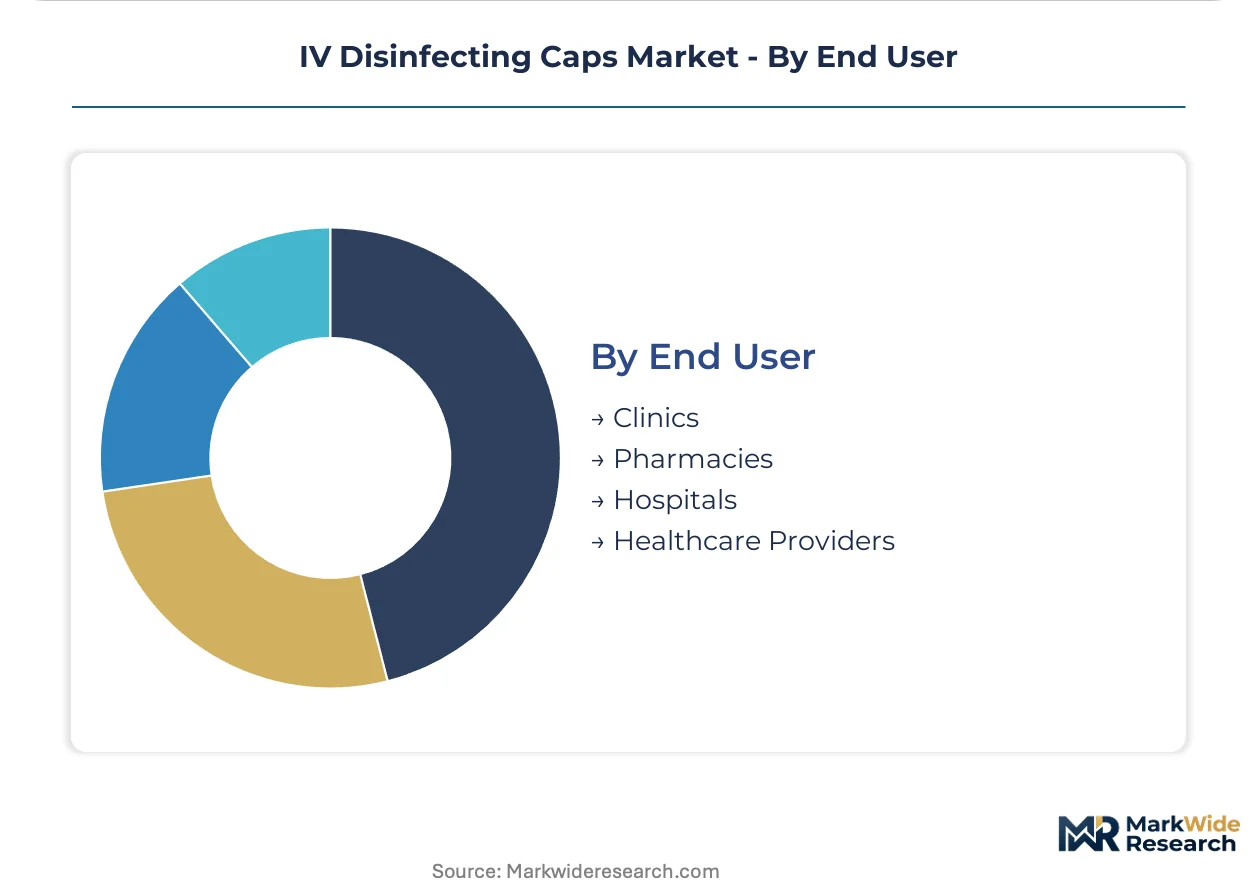
- Hospitals:Integrated delivery networks with dedicated infection prevention staff, group purchasing organization contracts, and direct manufacturer relationships for antimicrobial cap portfolios.
- Clinics:Outpatient infusion and dialysis centers with procedure volume sustaining premium pricing for specialized hub designs.
- Healthcare Providers:Individual practitioner and small group practices with dispersed purchasing patterns, typically served through distributor intermediaries.
- Pharmacies:Retail and specialty pharmacy channels dispensing caps alongside home infusion supplies, expanding as patient self-administration protocols proliferate.
Hospitals command the established base. Pharmacies are expanding most quickly as channel integration between drug and device dispensing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites European distribution efficiency for medical device manufacturers serving acute care networks across the continent.
United States
CMS Hospital-Acquired Condition Reduction Program penalties drive antimicrobial cap specification in ICU and oncology units. FDA 510(k) clearance pathways for residual disinfectant claims constrain supplier qualification. Boston's medical device cluster concentrates interventional radiology hub design innovation.
Germany
Outpatient infusion centers in Bavaria and North Rhine-Westphalia pilot silver-ion formulations for extended-dwell chemotherapy protocols. EU MDR Class IIa clinical evidence requirements tighten post-market surveillance for antimicrobial accessories. Melsungen's vertically integrated polypropylene molding operations anchor European manufacturing scale.
Japan
Hospital consolidation programs and tertiary center modernization waves open premium cap adoption in Tokyo and Osaka metropolitan areas. PMDA sterilization validation standards enforce material traceability for silicone formulations. Nagoya's precision molding corridor supports specialized interventional radiology device production.
United Kingdom
NHS infection control procurement frameworks elevate CLABSI prevention metrics above unit pricing in cap selection criteria. MHRA alignment with EU MDR technical documentation requirements extends registration timelines for antimicrobial claims. London's medical technology cluster concentrates specialty pharmacy channel integration for homecare dispensing.
India
Central line insertion volume expansion in Delhi-NCR and Mumbai tertiary centers drives basic closure demand amid cost-constrained procurement. CDSCO medical device rules impose quality management system requirements on imported antimicrobial accessories. Gujarat's pharmaceutical packaging corridor attracts contract molding investments for export-oriented production.
IV Disinfecting Caps Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and manufacturing scale. The vendor base stratifies between multinational device conglomerates with established FDA and EMA relationships and regional molders serving price-sensitive procurement channels. Three archetypes dominate: vertically integrated resin-to-device manufacturers, technology licensors with proprietary antimicrobial coatings, and distributor-aligned commodity suppliers. Competitive moves concentrate on M&A for regulatory dossier acquisition and gamma sterilization facility expansion.
Within the integrated manufacturing tier, B. Braun Melsungen AG exemplifies European captive polypropylene production from resin through finished device. Among technology-differentiated players, 3M Company occupies a position anchored by proprietary substrate formulations. Merit Medical Systems, Inc. represents channel specialization in interventional radiology where procedure volume sustains premium positioning.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Merit Medical Systems, Inc. |
| 3M Company |
| Cardinal Health, Inc. |
| Teleflex Incorporated |
| Becton, Dickinson and Company |
| Baxter International Inc. |
| Medline Industries, Inc. |
| ICU Medical, Inc. |
| Others |
Supply & Pricing Matrix
Chlorhexidine-impregnated polymer substitution for traditional foam barriers is redrawing procurement economics, concentrating premium formulation supply in Germany and the United States while compressing margins on basic mechanical closures sourced from Asian contract molders.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement through group purchasing organization contracts, with antimicrobial cap portfolios commanding three-tier pricing stratification across FDA-cleared premium formulations, standard single-use variants, and economy-grade basic closures. Price differentiation hinges on sterilization validation documentation and CLABSI reduction guarantees rather than unit manufacturing cost. Pricing pressure intensifies in the standard cap segment as Indian and Chinese molders expand export capacity for emerging market tenders. Homecare channels exhibit lowest price sensitivity due to reimbursement bundling with infusion services, while long-term care facilities face acute budget constraints driving commodity substitution.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and Red Sea container rerouting are elevating landed costs for European resin shipments to North American molding facilities. Pharmaceutical-grade polypropylene supply concentrates in Germany, Belgium, and the Netherlands, with medical device manufacturers drawing from captive petrochemical complexes along the Rhine corridor. Raw material dependencies encompass USP Class VI homopolymer resins, platinum-cured silicone elastomers, and silver-ion antimicrobial masterbatches. Single-source vulnerability pervades gamma sterilization capacity, with terminal sterilization services bottlenecked at facilities in France and the United States. Distribution runs through hospital-centered logistics networks, with specialty pharmacy channels gaining share for homecare dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IV disinfecting caps occupy an early-cycle expansion phase as homecare parenteral therapy penetration accelerates and infection control mandates extend beyond tertiary centers into ambulatory networks.
For Market Incumbents: Fortify regulatory dossier depth through accelerated FDA 510(k) antimicrobial claim submissions and backward integration into pharmaceutical-grade resin compounding to offset European feedstock volatility. Emerging Asian molders with cost-advantaged production threaten standard cap margins, making certification investment the priority defensive lever for premium positioning. For New Entrants and Emerging Players: Anchor in Japanese tertiary center modernization programs and German outpatient infusion center pilot programs for extended-dwell catheter protocols, where clinical evidence requirements have delayed incumbent penetration. Specialty pharmacy channel integration for homecare cap dispensing offers the most penetrable go-to-market angle against hospital-centric supply relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European molders possessing captive resin-to-device production and established EU MDR notified body relationships. The five-to-ten year viability window favors acquisition targets with gamma sterilization facility ownership and antimicrobial formulation IP. The signal to watch is CMS quality metric expansion beyond CLABSI to encompass outpatient vascular access infections.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Antimicrobial Claim Submission | Clearance pathways differentiate compliant suppliers from commodity molders in United States acute care procurement. |
| Gamma Sterilization Facility Expansion | Capacity additions alleviate terminal sterilization bottlenecks constraining antimicrobial cap production lead times. |
| Specialty Pharmacy Channel Partnership | Integration with home infusion dispensing networks captures fastest-growing demand arc beyond hospital settings. |
| Silver-Ion Polymer Formulation Development | Substrate innovation fragments procurement specifications toward documented microbial kill-rate performance. |
| EU MDR Technical Documentation Investment | Notified body relationships create competitive barriers under stricter Class IIa accessory validation standards. |
Research Methodology
A standing panel of hospital infection control committee chairs, GPO contracts managers, biomedical engineers, and specialty pharmacy dispensing directors provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Hospital-Acquired Condition Reduction Program penalty schedules, and hospital procurement contract repositories. Bottom-up facility-level demand modeling triangulated against top-down resin consumption estimates from European petrochemical trade associations.
Consistency checks validated volume and value outputs against antimicrobial cap shipment data from German and United States customs records, with segmentation dimensions spanning product type, material formulation, application setting, and end-user channel. CAGRs were derived from procedure volume elasticity modeling and infection control protocol adoption curves. Forecast inputs incorporated central line insertion rates, homecare parenteral therapy discharge protocols, and regulatory enforcement intensity indices.
Underlying assumptions cover sustained CMS reimbursement linkages to CLABSI metrics and EU MDR implementation timelines, with deviation risk concentrated in sterilization facility capacity constraints and pharmaceutical-grade resin supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
India Air Treatment Products Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Antibacterial Products Market
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Fumigant Products Market