
 Global Cosmetic Preservatives Market | 2026-2036
Global Cosmetic Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Preservatives Market Foresight
Capital-intensity divergence between integrated multinationals and specialty chemical houses is rotating competitive advantage toward backward-integrated supply chains. BASF leverages captive petrochemical feedstocks to control phenoxyethanol cost structures across European and Asian manufacturing nodes. Lonza sustains premium positioning in halal-certified preservation systems through dedicated Swiss production facilities. Evonik competes on fermentation-derived organic acids, anchoring its portfolio in biotechnology rather than synthetic chemistry.
Cosmetic preservatives comprise antimicrobial and antioxidant compounds formulated at concentrations between 0.01% and 2.0% to inhibit microbial proliferation in water-containing personal care products. These substances function primarily to extend shelf stability, prevent contamination during consumer use, and comply with microbiological safety standards mandated by health authorities. Organic acids represent the fastest-expanding product category as brands replace traditional formaldehyde releasers in response to dermatological sensitization concerns. Skincare applications command the dominant value share within the application dimension, though haircare preservation is gaining traction amid sulfate-free formulation complexities that elevate pH-stabilization requirements.
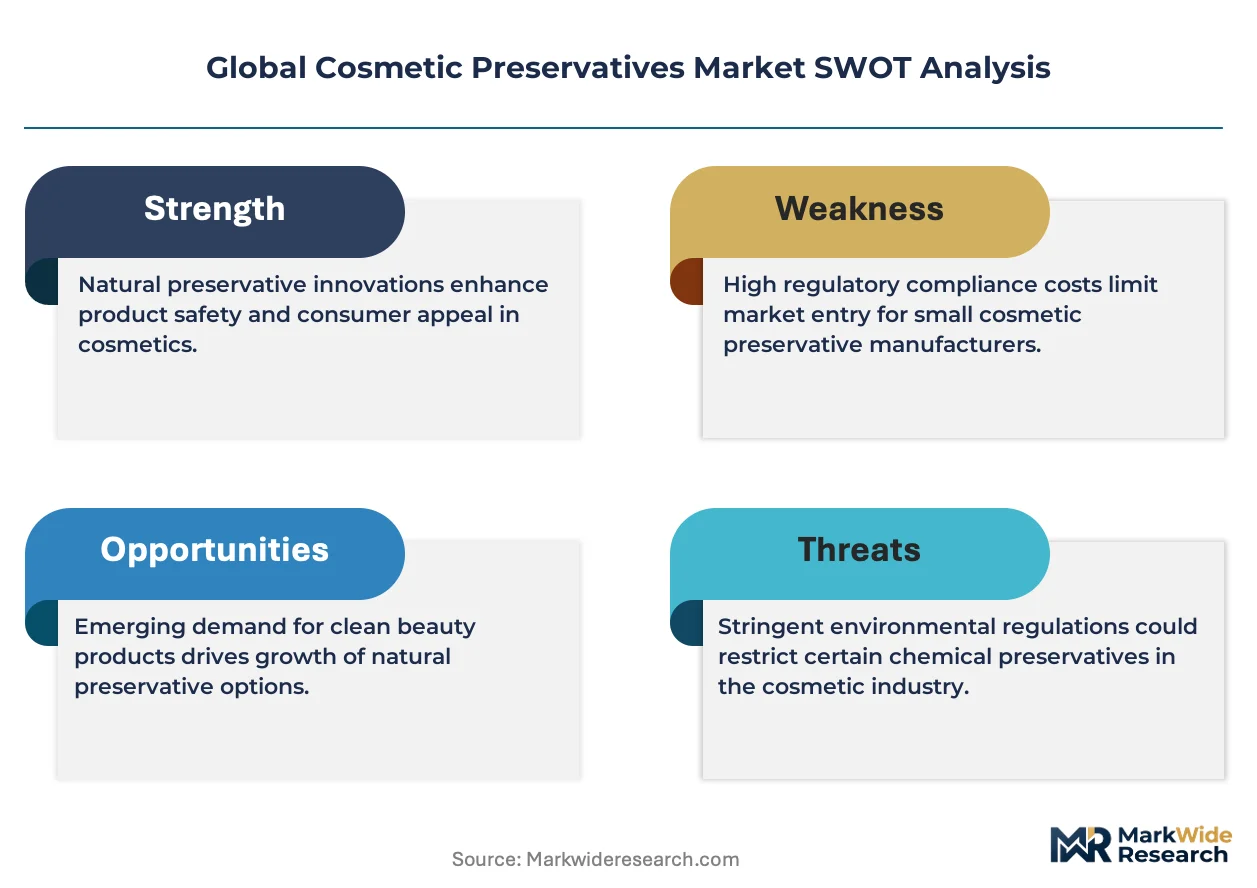
The EU's REACH regulation and the FDA's cosmetic ingredient scrutiny under modernized authority constrain preservative approval pathways, elevating compliance costs for novel antimicrobial submissions. China's NMPA and SAMR enforce GB standards that diverge from Western concentration limits, fragmenting global formulation strategies. Japan's METI maintains distinct quarantine requirements for imported preservative raw materials, adding procedural friction for non-domestic suppliers. Stakeholders must monitor regulatory divergence between major economies while building modular formulation platforms capable of rapid regional adaptation.
Market Dynamics
Preservative formulation is bifurcating between synthetic chemistry and biotechnology pathways as ECHA's REACH restrictions on isothiazolinones force immediate reformulation across European supply chains. This regulatory compression is redistributing competitive advantage toward fermentation-derived alternatives and backward-integrated feedstock control.
Growth Catalysts
- Clean-label procurement:Skincare brands in South Korea and France are mandating paraben-free systems, accelerating demand for phenoxyethanol and organic acid alternatives.
- REACH regulatory pressure:The EU's tightening concentration limits on methylisothiazolinone are compelling manufacturers to invest in novel antimicrobial R&D pipelines.
- Halal certification expansion:Swiss and Malaysian production facilities are capturing premium positioning through dedicated halal-compliant preservation systems for Southeast Asian export markets.
Market Restraints
- Feedstock cost volatility:Phenol and ethylene oxide price swings directly compress phenoxyethanol margin structures for non-integrated producers.
- Supply concentration risk:German and Chinese petrochemical clusters control over 60% of key synthetic preservative precursors, creating geographic chokepoints.
- Technical substitution ceiling:Natural extracts demonstrate inferior broad-spectrum efficacy against Pseudomonas aeruginosa compared to synthetic benchmarks.
Strategic Opportunities
- Underpenetrated halal markets:Indonesia and Nigeria present whitespace for certified preservation systems as domestic cosmetic production scales.
- Biotechnology convergence:CRISPR-edited yeast strains and precision fermentation are enabling cost-competitive organic acid production at industrial scale.
- Direct-to-brand distribution:E-procurement platforms are disintermediating traditional chemical distributors for mid-size cosmetic manufacturers.
Industry Challenges
- Microbiology talent scarcity:Qualified preservative efficacy testing specialists command premium compensation across contract research organizations.
- Multi-jurisdiction compliance timelines:Simultaneous FDA, NMPA, and ECHA submission requirements extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Preservatives Market |
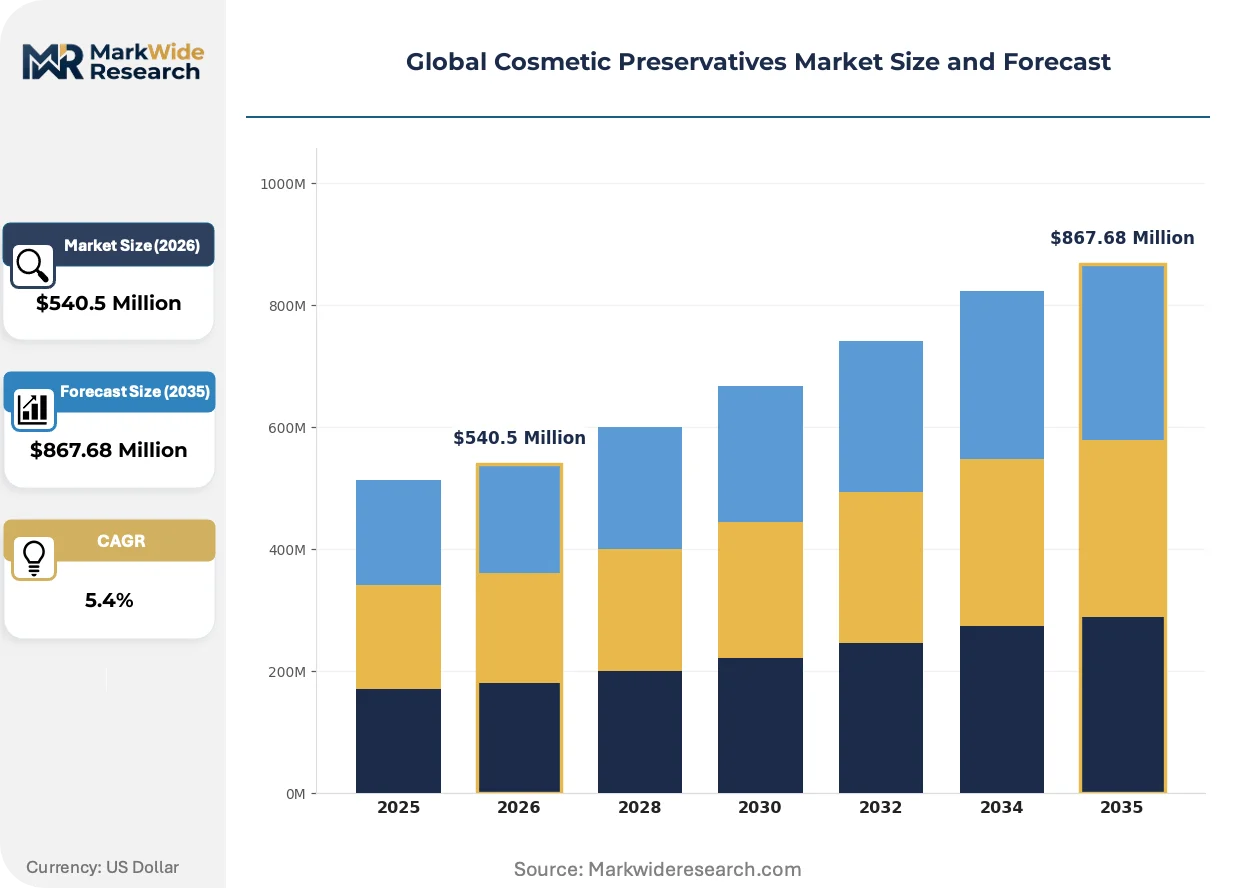
| Market Size in 2026 | $540.5 Million |
| Market Size in 2035 | $867.68 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabens, Phenoxyethanol, Formaldehyde Releasers, Organic Acids, Isothiazolinones, Sulfates Application: Skincare, Haircare, Color Cosmetics, Oral Care, Personal Hygiene, Fragrance End User: Cosmetic Manufacturers, Contract Manufacturing, Retail Brands, Private Label, Salons, Dermatology Clinics Form: Liquid, Powder, Emulsion, Gel, Aerosol, Paste |
| Companies Covered | Clariant, Evonik, BASF, Akema Fine Chemicals, Symrise, Ashland, Dow, Inolex, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Preservatives Market Shifts & Advancements
Biotechnology-derived preservation systems are capturing formulation share from petrochemical alternatives as capital allocation shifts toward fermentation infrastructure. Three distinct vectors are reshaping competitive positioning.
Precision fermentation of organic acids is decomposing the historical cost advantage of synthetic benzoic acid and sorbic acid production. K-beauty exporters in South Korea are adopting these biotech alternatives at scale for extended shelf-life claims. The technology is decomposing incumbent pricing power in mid-tier preservation segments.
ECHA's 2023-2025 REACH amendments restricting isothiazolinone concentrations are forcing immediate reformulation across European cosmetic manufacturing. Suppliers are redirecting R&D expenditure toward phenoxyethanol blends and organic acid synergies. Haircare applications face the steepest compliance costs due to rinse-off product classification complexities.
Ingredient transparency mandates are compressing brand procurement cycles as clean-label requirements harden into retailer standards. Sephora and Ulta Beauty are enforcing restricted substance lists that exceed regulatory minimums in the United States. Skincare verticals in California and New York are experiencing the most acute supplier switching pressure.
Global Cosmetic Preservatives Market Segmentation
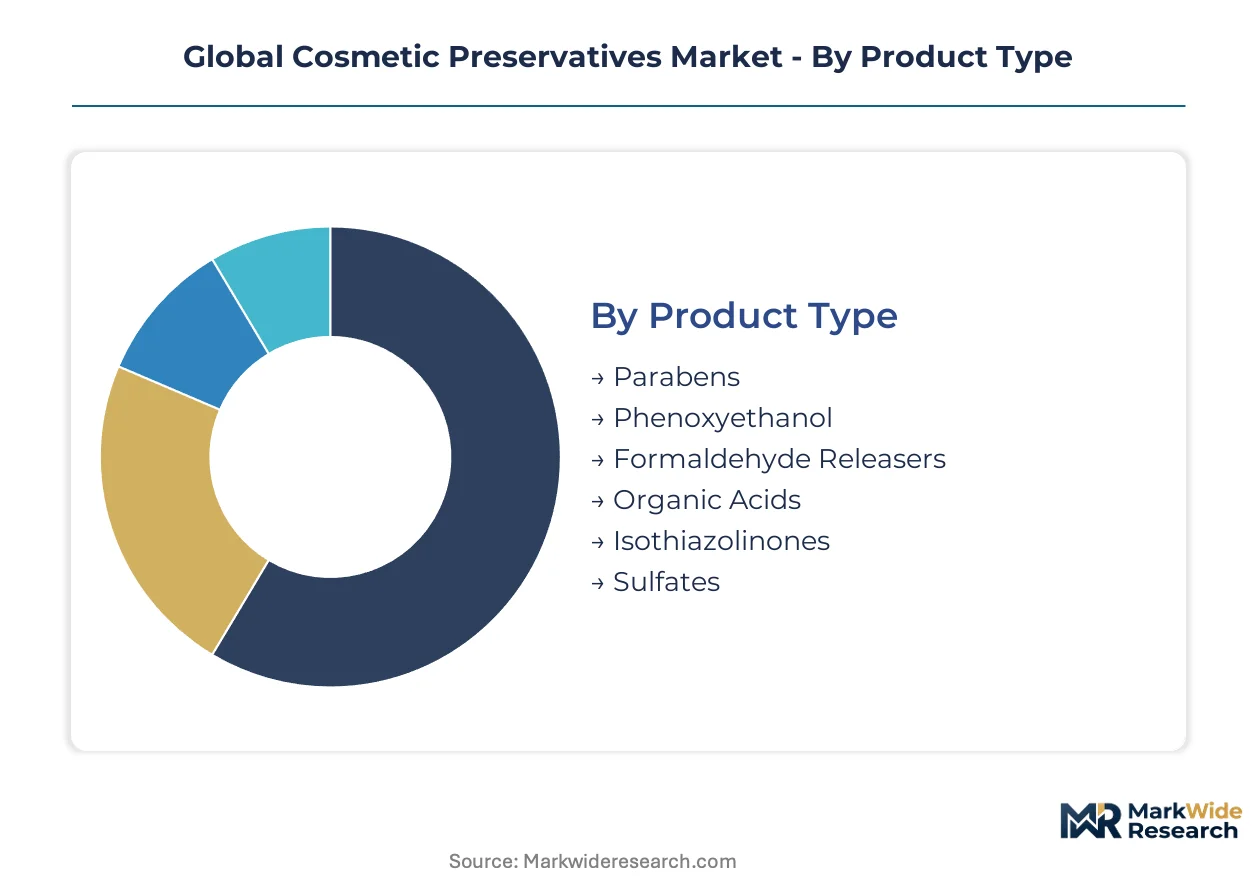
Preservative selection cascades through formulation chemistry, regulatory compliance, and end-use performance requirements. Each segmentation dimension reveals distinct procurement patterns and margin structures across cosmetic manufacturing tiers.
Product Type:
Domestic production clusters in Germany, China, and Switzerland anchor supply for phenoxyethanol and parabens, while organic acid fermentation capacity concentrates in South Korea and Denmark for K-beauty and Nordic natural cosmetic export markets.
- Phenoxyethanol:A glycol ether synthesized from phenol and ethylene oxide, functioning as a broad-spectrum antimicrobial effective against Gram-negative bacteria. Demand concentrates in French and German skincare manufacturing, where ECHA REACH restrictions on isothiazolinones have accelerated substitution timelines. Reformulation costs for legacy systems sustain premium pricing for phenoxyethanol blends.
- Organic Acids:Fermentation-derived benzoic acid, sorbic acid, and their salts provide pH-dependent preservation in natural-positioned formulations. South Korean K-beauty exporters and Danish organic brands drive procurement volume, capitalizing on biotechnology scale economies and clean-label positioning. The category gains share fastest as brands replace formaldehyde releasers.
- Parabens:Ester compounds of p-hydroxybenzoic acid retain cost advantages in emerging market mass cosmetics despite clean-label headwinds in premium European and North American segments.
- Formaldehyde Releasers:DMDM hydantoin and imidazolidinyl urea release formaldehyde gradually; dermatological sensitization concerns compress usage to budget haircare and industrial applications.
- Isothiazolinones:Methylisothiazolinone and methylchloroisothiazolinone face ECHA concentration caps that have triggered emergency reformulation across European rinse-off and leave-on categories.
- Sulfates:Sodium lauryl sulfate and related compounds serve dual preservative-surfactant functions primarily in oral care and cleansing applications.
Phenoxyethanol holds the largest share; momentum sits with organic acids.
Application:
Skincare and haircare command disproportionate R&D investment due to water content, pH variability, and extended consumer use patterns that elevate microbiological risk profiles.
- Skincare:Water-based serums, creams, and lotions require robust preservation against Pseudomonas aeruginosa and Candida albicans contamination. South Korean, French, and Californian brands enforce the strictest clean-label procurement standards, driving phenoxyethanol and organic acid adoption. The segment absorbs the highest per-unit preservative expenditure due to premium positioning and regulatory scrutiny.
- Haircare:Shampoos and conditioners present formulation complexity from sulfate-free surfactant systems that alter pH stability and preservative efficacy. ECHA's rinse-off classification distinctions create compliance cost asymmetries between European and other markets. The segment is climbing the fastest as sulfate-free trends elevate preservation technical requirements.
- Color Cosmetics:Anhydrous and low-water formulations reduce absolute preservative load, though mascara and liquid foundations require specialized systems.
- Oral Care:Toothpastes and mouthwashes leverage alcohol, fluoride, and surfactant synergies that modify traditional preservative selection.
- Personal Hygiene:Deodorants and antiperspirants employ preservative-free or low-preservation strategies through alcohol bases and packaging design.
- Fragrance:High alcohol content provides intrinsic preservation, limiting antimicrobial additive requirements to water-containing ancillary products.
Skincare dominates absolute value; haircare shows steepest expansion trajectory.
End User:
Procurement scale and technical capability diverge sharply between multinational cosmetic houses and contract manufacturers serving mid-tier brands.
- Cosmetic Manufacturers:Integrated beauty houses such as L'Oréal, Estée Lauder, and Amorepacific maintain dedicated preservative R&D teams and direct supplier relationships. These entities drive industry-wide clean-label standards through restricted substance lists exceeding regulatory minimums. Their volume concentration enables backward integration negotiations with phenol and fermentation feedstock suppliers.
- Contract Manufacturing:Organizations like Cosmax, Intercos, and Kolmar Korea formulate across multiple brand portfolios, requiring modular preservation platforms adaptable to divergent client specifications. The segment expands most quickly as direct-to-consumer brands outsource production.
- Retail Brands:Sephora Collection, Ulta Beauty private label, and Boots No. 7 leverage distributor scale for preservative procurement standardization.
- Private Label:Supermarket and pharmacy chains prioritize cost-optimized preservation meeting baseline regulatory compliance.
- Salons:Professional-use hair color and treatment products require specialized preservation for oxidative and alkaline formulations.
- Dermatology Clinics:Medical-grade skincare demands preservative systems validated for compromised skin barrier applications.
Cosmetic manufacturers hold the largest share; contract manufacturing captures fastest growth.
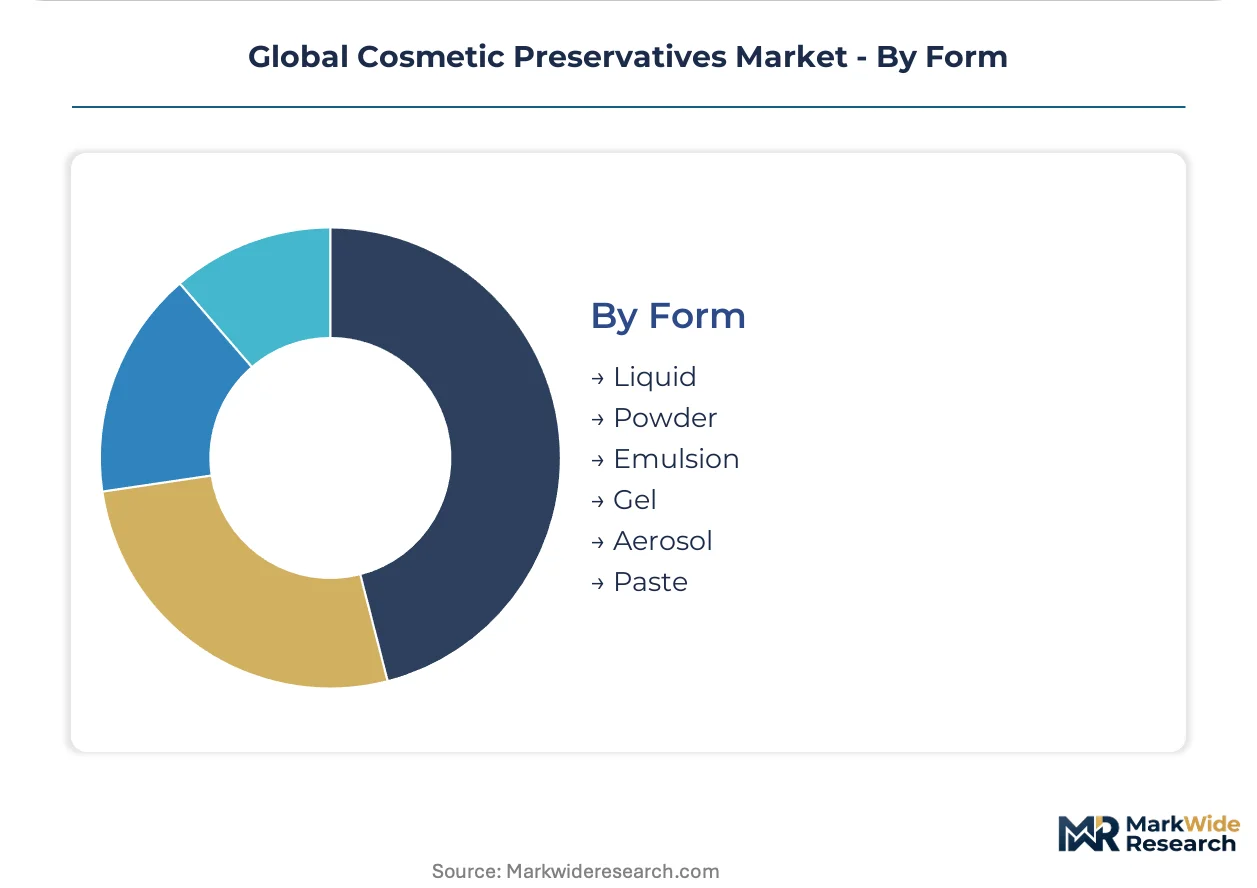
Form:
Physical state determines manufacturing integration, stability requirements, and dosing precision across cosmetic production lines.
- Liquid:Phenoxyethanol and organic acid solutions integrate directly into aqueous phases, dominating high-volume skincare and haircare production. German and Chinese liquid preservative suppliers control capacity for phenol-derived chemistries.
- Powder:Benzoic acid, sorbic acid, and paraben powders offer extended shelf stability and precise dosing in dry blend operations. The form is expanding most quickly for natural cosmetic brands seeking preservative-free claims through powder-as-ingredient positioning.
- Emulsion:Preservative-lipid combinations serve dual function in water-in-oil and oil-in-water systems.
- Gel:Thickened preservative matrices enable controlled release in transparent cosmetic formulations.
- Aerosol:Pressurized delivery systems require preservative compatibility with propellants and valve mechanics.
- Paste:High-viscosity preservation for toothpaste and hair styling compounds.
Liquid forms command the largest share; powder formats gain momentum fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for cosmetic preservatives diverges sharply between premium skincare markets and mass-market emerging economies. German and French buyers absorb reformulation costs from ECHA REACH restrictions with minimal volume contraction. Indonesian and Nigerian procurement remains acutely price-sensitive, compressing margins for non-integrated suppliers.
United States
Clean-label procurement from Sephora and Ulta Beauty enforces restricted substance lists exceeding FDA minimums. The Modernization of Cosmetics Regulation Act expands pre-market notification requirements for novel antimicrobials. California's Proposition 65 litigation exposure drives preservative substitution in Los Angeles and San Francisco formulation clusters.
Germany
BASF's Ludwigshafen complex anchors European phenoxyethanol supply through captive phenol feedstocks. ECHA's 2023-2025 REACH amendments on isothiazolinones force emergency reformulation across Rhine-Ruhr cosmetic manufacturing. Frankfurt specialty chemical distributors service mid-tier brands with modular preservation platforms.
China
NMPA and SAMR enforce GB standards with concentration limits diverging from Western norms, fragmenting global formulation strategies. Yangtze River Delta cosmetic contract manufacturers scale domestic preservative procurement for local brands. Shanghai's free-trade zones facilitate import of Swiss and German halal-certified preservation systems.
South Korea
K-beauty export growth drives specialized procurement for extended shelf-life claims in water-rich essence formulations. MFDS cosmetic safety assessments prioritize dermatological tolerability data for preservative approvals. Seoul-Incheon production clusters adopt fermentation-derived organic acids at scale for clean-label positioning.
Switzerland
Lonza maintains dedicated halal-certified production facilities capturing premium positioning for Southeast Asian export markets. Swissmedic's stringent cosmetic ingredient oversight validates preservative safety dossiers for global brand acceptance. Basel's biotechnology corridor concentrates precision fermentation capacity for organic acid manufacturing.
Global Cosmetic Preservatives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence rotating advantage toward backward-integrated supply chains. The upper tier controls phenol and ethylene oxide feedstocks for phenoxyethanol cost structures. Mid-tier players compete on fermentation-derived organic acids and certification specializations. Dominant competitive moves include captive petrochemical integration and biotechnology infrastructure investment.
Within the integrated multinational tier, BASF and Dow exemplify petrochemical-backed preservation manufacturing. Evonik occupies a position anchoring biotechnology-derived alternatives through fermentation expertise. Lonza represents the halal-certification specialization vector with dedicated Swiss production assets.
| Leading Market Players |
|---|
| Clariant |
| Evonik |
| BASF |
| Akema Fine Chemicals |
| Symrise |
| Ashland |
| Dow |
| Inolex |
| Lonza |
| Others |
Supply & Pricing Matrix
ECHA's REACH certification regime gates both supplier qualification and price differentiation simultaneously, as halal and organic certifications compound compliance costs while creating tiered procurement access for Southeast Asian and European buyers.
Pricing Analysis
After-sales technical service and reformulation support drive lifetime value for phenoxyethanol and organic acid suppliers serving mid-tier cosmetic manufacturers. Three-tier pricing structure across premium halal-certified, standard REACH-compliant, and economy paraben-based levels stratifies the market. Cost compression in synthetic chemistry tiers is intensifying because phenol and ethylene oxide feedstock volatility squeezes non-integrated producers. Contract manufacturers exhibit the highest price sensitivity due to thin margin structures, while integrated beauty houses absorb premium positioning costs.
Supply Chain Analysis
Inventory buffers and lead-time variability distinguish fermentation-derived organic acids from petrochemical synthetics, with biotech batches requiring 6-8 week cultivation cycles versus continuous chemical synthesis. German, Chinese, and Swiss production clusters anchor phenoxyethanol supply, while South Korean and Danish facilities concentrate organic acid fermentation capacity. Raw material flows draw from phenol crackers, ethylene oxide plants, and precision fermentation feedstocks. Single-source vulnerability concentrates in Ludwigshafen and Yangtze River Delta petrochemical nodes. Distribution runs through specialty chemical distributors and direct e-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as modular formulation systems enable rapid regional adaptation across divergent regulatory clusters, with interoperability between clean-label and halal certification standards emerging as the critical ecosystem shift.
For Market Incumbents: Secure captive phenol and ethylene oxide feedstocks through backward integration into German and Chinese petrochemical infrastructure to defend margin structures against feedstock volatility. Deepen fermentation capacity investments in Basel and Seoul-Incheon corridors to preempt biotechnology substitution threats from precision organic acid producers. For New Entrants and Emerging Players: Modular formulation services for mid-tier contract manufacturers represent the most penetrable white-space, as Cosmax and Kolmar Korea seek rapid regional adaptation capabilities. Target Indonesia and Nigeria with dedicated halal-certified production systems. Pursue direct-to-brand e-procurement channels to bypass established distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical houses holding REACH-compliant portfolios but lacking biotechnology infrastructure. Five-to-ten year viability hinges on fermentation scale economics displacing synthetic cost structures. Monitor CRISPR-edited yeast strain patent filings as the inflection signal for organic acid production cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Feedstocks | BASF's Ludwigshafen complex demonstrates captive supply control over phenoxyethanol cost structures. |
| Precision Fermentation Scale-Up | Evonik's biotechnology anchor enables organic acid cost parity with synthetic benzoic acid production. |
| Halal Certification Infrastructure | Lonza's Swiss facilities capture premium positioning for Southeast Asian cosmetic export markets. |
| Direct E-Procurement Platform Launch | Disintermediation of traditional distributors accelerates mid-tier brand acquisition cycles. |
| Modular Formulation System Development | Adaptable preservation platforms reduce multi-jurisdiction compliance timelines for contract manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic formulators, regulatory affairs specialists, procurement leads at contract manufacturers, and biotechnology R&D directors, then refined against customs trade data, ECHA REACH submission databases, SEC chemical sector filings, and MFDS cosmetic safety assessments. Bottom-up volume estimates triangulated with top-down market sizing across product type, application, end user, and form segmentation dimensions.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each modeled segment. Product type stratification by synthetic versus biotechnology origin, application tier by water-content and pH complexity, and regional regulatory cluster by REACH, FDA, and NMPA divergence frames the analytical structure. CAGRs derive from segment-level growth rate reconciliation against macroeconomic and regulatory scenario inputs, with fermentation capacity buildout and isothiazolinone restriction timelines as key forecast drivers.
Underlying assumptions cover regulatory enforcement continuity, feedstock price correlation stability, and biotechnology yield improvement curves, with deviation risk concentrated in ECHA amendment timing and Chinese GB standard harmonization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Sodium Nitrite Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Disinfectant Fogging and Misting Chemicals for Large Facilities Market
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Continuously Sterilized Product Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Vaporized Hydrogen Peroxide Sterilization Systems Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Latin America Cosmetic Preservatives Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
Global Animal Disinfectants Market