
 Diquat Dibromide Market | 2026-2036
Diquat Dibromide Market Size, Share, and Industry Trends Forecast 2026-2036
Diquat Dibromide Market Insights
The manufacturing scale gap between integrated producers and formulation-only players is rotating competitive advantage toward backward-integrated suppliers with captive bromine access. BASF SE leverages its Ludwigshafen chemical complex to sustain captive dibromide precursor supply. Bayer CropScience anchors its position through proprietary formulation technology that improves rainfastness in tropical conditions. Syngenta International competes via granular formulation specialization tailored to mechanized Brazilian soybean operations.
Diquat dibromide is a bipyridinium herbicide formulated as a dibromide salt, typically applied at 0.5–2.0 kg active ingredient per hectare for rapid contact desiccation of broadleaf weeds and grasses prior to harvest. The compound functions through electron diversion in Photosystem I, generating reactive oxygen species that rupture cell membranes within hours of application. Agricultural applications dominate volume throughput, though aquatic weed control programs in irrigation districts represent a higher-margin segment where formulation precision commands premium pricing. Liquid concentrates lead formulation type demand in North American row-crop markets, while granules gain share in Asian rice paddy systems where manual application persists. Distributor networks still control the bulk of offline volume in developing markets, though farm-level digital procurement is eroding their margin capture.
EPA re-registration reviews under the Federal Insecticide, Fungicide, and Rodenticide Act shape product label restrictions and buffer zone mandates in the United States. ECHA's classification of diquat as a substance of very high concern under REACH is restricting formulation and import permissions across European member states. Brazil's ANVISA is tightening residue tolerance protocols for export-oriented soybean and cotton producers. Stakeholders must monitor regulatory divergence between major agricultural economies to anticipate formulation reformulation requirements and market access shifts.
Market Dynamics
Glyphosate resistance proliferation across major row-crop systems is redirecting herbicide procurement toward contact alternatives with distinct modes of action, compressing the effective window for pre-harvest desiccation and elevating formulation performance requirements.
Growth Catalysts
- Resistance Management Mandates:EPA label restrictions on glyphosate rotational use in the United States are accelerating diquat adoption in integrated weed control programs across corn and soybean rotations.
- Pre-Harvest Desiccation Protocols:Brazil's soybean belt is standardizing contact herbicide applications for harvest uniformity, with Mato Grosso state agencies publishing technical guidance for mechanized operations.
- Aquatic Weed Control Expansion:Irrigation district maintenance budgets in water-stressed agricultural regions are allocating increased resources to rapid-acting herbicides for canal and reservoir management.
Market Restraints
- Bromine Feedstock Concentration:Captive bromine access is concentrated among integrated chemical producers with Dead Sea or Arkansas brine operations, elevating input cost volatility for formulation-only competitors.
- REACH SVHC Classification:ECHA's substance of very high concern designation is restricting formulation permissions and import authorizations across European member states.
- Paraquat Substitution Ceiling:Regulatory bans on paraquat in multiple jurisdictions have already captured available substitution demand, limiting incremental volume expansion from further restrictions.
Strategic Opportunities
- Rice Paddy Mechanization:Southeast Asian granule formulation demand is rising as Vietnam and Thailand expand mechanized transplanting and direct-seeding operations requiring precise aquatic weed control.
- Rainfastness Premium Positioning:Tropical agriculture zones with intense precipitation patterns are creating pricing power for formulations with enhanced adhesion and reduced wash-off coefficients.
- Digital Procurement Platforms:Farm-level e-commerce channels in developing markets are eroding traditional distributor margin capture and enabling direct manufacturer-to-grower relationships.
Industry Challenges
- Formulation Chemist Scarcity:Bipyridinium salt stability expertise is concentrated among legacy agrochemical R&D centers, constraining new entrant product development timelines.
- Residue Testing Infrastructure:Export-oriented producers in Brazil face capacity bottlenecks at ANVISA-accredited laboratories for pre-shipment maximum residue limit verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diquat Dibromide Market |
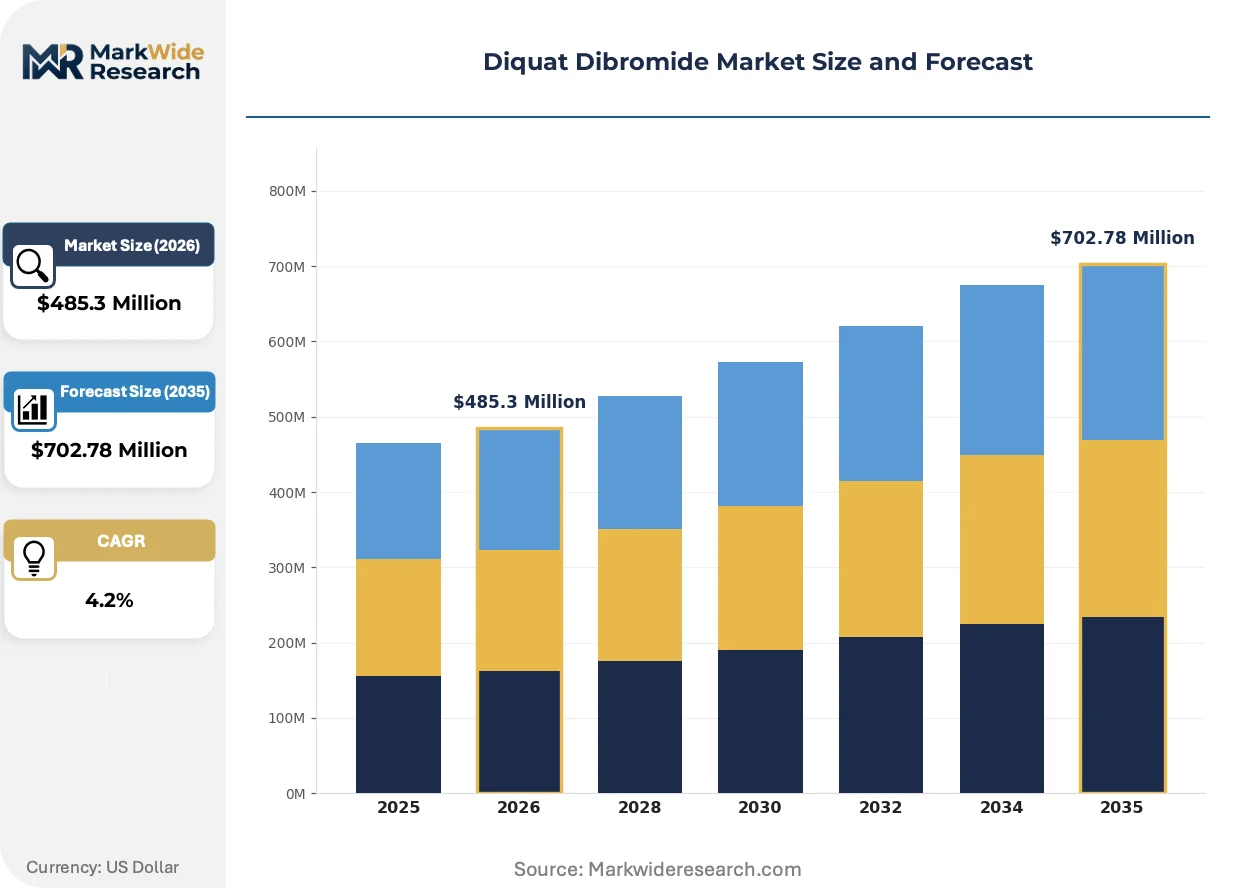
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $702.78 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agricultural, Aquatic, Horticultural, Industrial Formulation Type: Granules, Liquid, Concentrate, Emulsifiable Distribution Channel: Online, Offline, Distributors, Retailers End User: Farmers, Landscapers, Nurseries, Greenhouses |
| Companies Covered | BASF SE, Bayer CropScience SE, Corteva Agriscience, Adama Agricultural Solutions, FMC Corporation, Syngenta International, Nufarm, UPL, Sumitomo Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diquat Dibromide Market Trends and Innovations
Formulation chemistry and application precision are converging to address rainfastness requirements and resistance management protocols, while regulatory classification pressures are compressing accessible market geography.
Encapsulated diquat formulations with controlled-release polymer matrices are decomposing the traditional trade-off between rapid contact activity and extended rainfastness protection. Large-scale soybean operations in Brazil's Cerrado region are adopting these advanced formulations at accelerated procurement cycles. The technology is decomposing volume-based pricing models by enabling premium positioning tied to performance guarantees rather than active ingredient concentration.
ECHA's classification of diquat dibromide as a substance of very high concern under REACH Article 57 is triggering authorization requirements and downstream user notification obligations across EU member states. Industrial consequence includes reformulation cost burdens and label restriction tightening for desiccant applications in cereal and potato crops. German and French formulators are responding with product portfolio reallocation toward non-bipyridinium alternatives and accelerated registration dossier preparation for substitute chemistries.
Direct-to-farm digital procurement platforms are displacing traditional distributor networks as the primary volume channel in developing agricultural economies. Brazilian cooperatives and large-scale farming enterprises are consolidating purchase decisions through integrated supply platforms that aggregate chemical, seed, and equipment procurement. This channel compression is most visible in Mato Grosso and Paraná states, where digital penetration in input purchasing exceeds regional averages and erodes legacy distributor margin structures.
Diquat Dibromide Market Segmentation
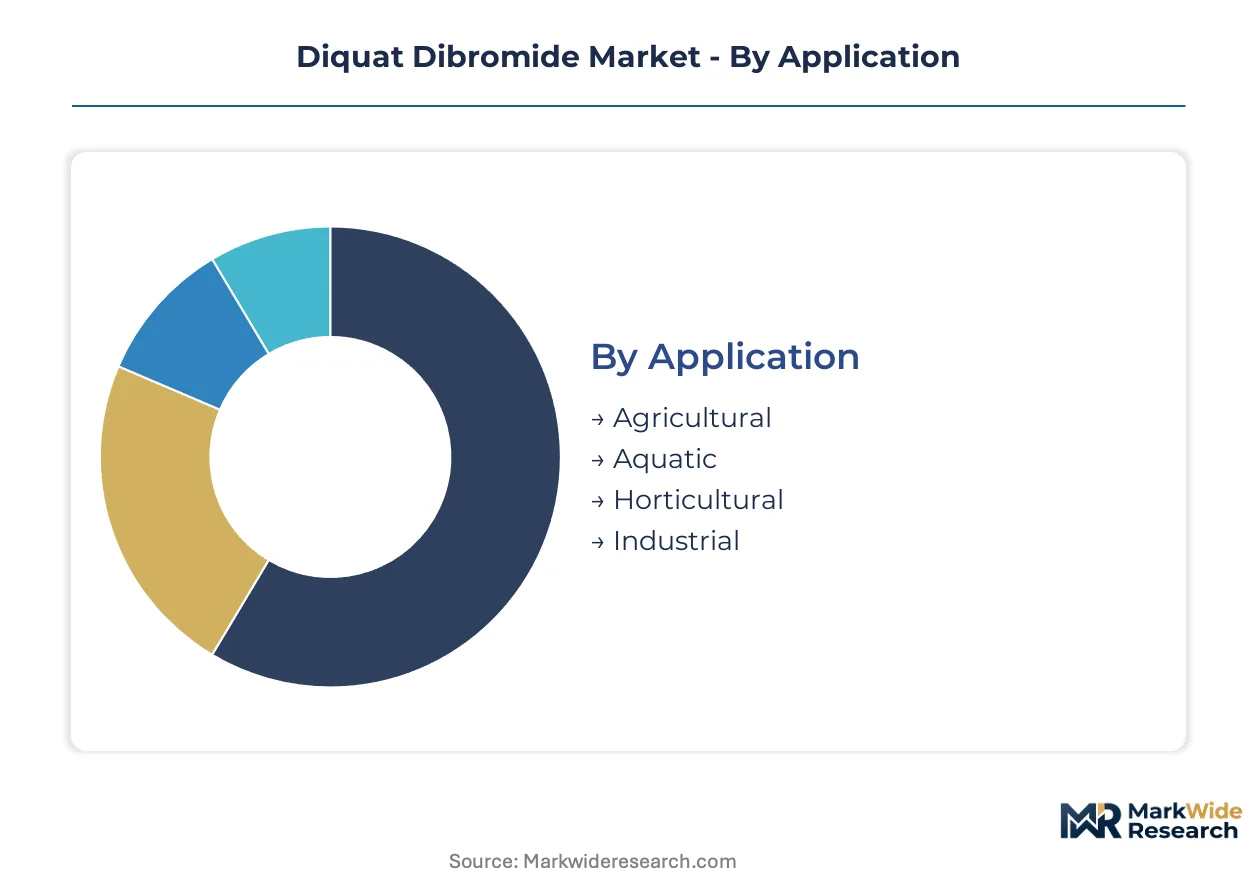
Diquat dibromide procurement patterns diverge sharply across end-use contexts, with agricultural desiccation driving volume scale while aquatic applications command formulation premiums. Understanding these segment boundaries clarifies where backward-integrated suppliers extract margin versus where formulation specialists compete on performance.
Application:
Brazilian soybean operations anchor agricultural demand through export-oriented pre-harvest protocols, while European aquatic programs concentrate procurement among specialized contractors serving irrigation districts.
- Agricultural:Pre-harvest desiccation of soybeans, cotton, and cereals consumes the majority of active ingredient volume, with Mato Grosso state agencies standardizing contact herbicide protocols for mechanized harvesting. Brazilian export producers face ANVISA residue verification requirements that elevate formulation precision demands.
- Aquatic:Canal and reservoir maintenance in water-stressed irrigation districts commands premium pricing for rapid-acting formulations, with formulation precision requirements exceeding agricultural specifications. Procurement concentrates among district maintenance contractors in the western United States and Australia's Murray-Darling basin.
- Horticultural:Orchard floor management and nursery bed preparation utilize lower application rates, with demand fragmented across Mediterranean citrus producers and Southeast Asian tropical fruit operations.
- Industrial:Non-crop vegetation control along railways and industrial sites represents a price-sensitive segment with standardized specification requirements and limited formulation differentiation.
Agricultural commands the established base. The steepest expansion runs through aquatic.
Formulation Type:
Cost tiers separate rainfastness-optimized concentrates from commodity liquids, with granule premiums reflecting Southeast Asian mechanization investments.
- Liquid:Standard aqueous solutions dominate North American row-crop procurement through established distributor networks, with rainfastness additives determining price positioning in tropical precipitation zones.
- Concentrate:High-load formulations reduce freight costs for Brazilian interior logistics, with encapsulated polymer matrices from BASF Ludwigshafen commanding performance guarantees rather than active ingredient pricing.
- Granules:Slow-release matrices suit Asian rice paddy systems where manual application persists, with Vietnam and Thailand driving mechanized transplanting demand that favors precise granule distribution.
- Emulsifiable:Oil-based systems penetrate waxy weed cuticles in specialty horticultural applications, with limited volume relative to aqueous alternatives.
Liquid formulations hold the volume anchor. Concentrate climbs the fastest on freight optimization and encapsulation premiums.
Distribution Channel:
Customer type stratification separates cooperative procurement through legacy distributors from large-scale farm direct purchasing eroding traditional margin capture.
- Distributors:Multi-brand agronomic service providers still control the majority of developing market volume, with technical support bundling justifying margin retention in fragmented farmer bases.
- Offline:Physical retail and cooperative procurement dominates smallholder segments in India and sub-Saharan Africa where credit relationships and agronomic advice drive loyalty.
- Online:Farm-level e-commerce platforms in Brazil's Mato Grosso and Paraná states aggregate chemical, seed, and equipment procurement, compressing distributor intermediation.
- Retailers:Branded garden center channels serve horticultural and consumer segments with premium positioning distinct from agricultural commodity pricing.
Distributors retain the established infrastructure. Online channels gain share fastest through cooperative consolidation.
End User:
Scale concentration separates plantation-level procurement with direct manufacturer relationships from fragmented nursery demand served through retail intermediaries.
- Farmers:Large-scale soybean and cotton producers in Brazil's Cerrado region negotiate direct supply agreements, with digital procurement platforms aggregating purchase decisions across input categories.
- Landscapers:Commercial vegetation management contractors in Australia and the southern United States specify rapid-acting contact herbicides for client-visible results.
- Nurseries:Containerized production systems require precise weed control without root zone damage, with procurement fragmented across regional supplier relationships.
- Greenhouses:Controlled environment agriculture demands low-volatility formulations with restricted worker re-entry intervals, with European operations facing REACH SVHC notification obligations.
Farmers command the volume base. Landscapers expand most quickly through commercial service contract growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil's soybean belt exhibit low price elasticity due to export-driven residue compliance requirements, while European aquatic contractors face high elasticity as REACH authorization costs trigger substitution toward non-bipyridinium alternatives.
Brazil
Mato Grosso and Paraná state agencies standardize pre-harvest desiccation protocols for mechanized soybean harvesting. ANVISA tightens residue tolerance verification for export-oriented producers. The Cerrado region anchors procurement concentration where large-scale farming enterprises negotiate direct supply agreements.
United States
EPA label restrictions on glyphosate rotational use accelerate diquat adoption in corn-soybean rotations across the Midwest. The Federal Insecticide, Fungicide, and Rodenticide Act shapes buffer zone mandates and re-registration timelines. Arkansas brine operations supply captive bromine feedstock to integrated chemical producers.
Germany
ECHA's REACH Article 57 SVHC classification restricts formulation permissions and triggers downstream user notification obligations. The Ludwigshafen chemical complex sustains backward-integrated dibromide precursor supply. German formulators reallocate portfolios toward substitute chemistries.
China
Domestic agrochemical manufacturers expand granule formulation capacity for Southeast Asian rice paddy exports. The Ministry of Ecology and Environment enforces dual carbon goals that elevate production compliance costs. Yangtze River Delta chemical clusters concentrate bipyridinium salt processing expertise.
Australia
Murray-Darling basin irrigation districts allocate maintenance budgets to rapid-acting aquatic weed control programs. The Therapeutic Goods Administration and state-level environmental regulators coordinate chemical access permits. Queensland and New South Wales canal contractors concentrate premium formulation procurement.
Diquat Dibromide Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with backward-integrated chemical complexes dominating feedstock security while formulation specialists compete on rainfastness performance. The market structures around three tiers: integrated producers with captive bromine access, multinational agrochemical conglomerates with proprietary formulation platforms, and regional blenders serving price-sensitive industrial segments. Strategic moves center on encapsulation polymer R&D partnerships and direct-to-farm digital channel expansion.
Among the integrated chemical producers, BASF SE anchors the backward-integrated tier through its Ludwigshafen complex operations, while Bayer CropScience SE exemplifies formulation technology specialization. Syngenta International occupies a position within the granular formulation segment tailored to mechanized Brazilian soybean operations. These three represent the dominant competitive archetypes: captive supply security, proprietary application technology, and regional mechanization alignment.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience SE |
| Corteva Agriscience |
| Adama Agricultural Solutions |
| FMC Corporation |
| Syngenta International |
| Nufarm |
| UPL |
| Sumitomo Chemical Company |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day dibromide precursor lead times concentrate pricing power among Dead Sea and Arkansas brine operators with captive bromine access, while formulation-only competitors absorb input cost volatility through inventory buffers. This supply concentration enables backward-integrated producers to enforce term-contract premiums against spot-market buyers in Brazil's soybean belt.
Pricing Analysis
After-sales technical service contracts drive lifetime value for encapsulated formulation producers serving Brazil's Cerrado operations. Three-tier pricing structure across performance-guaranteed concentrates, standard aqueous solutions, and commodity industrial grades separates rainfastness-optimized products from volume-based alternatives. Pricing pressure stems from ANVISA residue testing cost absorption by export-oriented producers. Smallholder rice farmers in Southeast Asia exhibit highest price sensitivity, while Brazilian cooperatives negotiate least sensitive direct supply agreements.
Supply Chain Analysis
Inventory positions at Ludwigshafen and Arkansas brine operations determine downstream formulation availability for peak desiccation windows. Supply concentrates in Israel, the United States, and China, with dibromide salt processing expertise anchored in Yangtze River Delta chemical clusters. Bromine feedstock draws from Dead Sea evaporation ponds and Arkansas underground brine formations. Single-source vulnerability runs through concentrated bromine access. Distribution runs through cooperative procurement platforms eroding legacy distributor intermediation in Mato Grosso and Paraná states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry opportunities as digital procurement platforms displace traditional distributor networks and residue compliance requirements splinter buyer segments by export orientation.
For Market Incumbents: Consolidate formulation technology leadership through encapsulation polymer R&D partnerships targeting rainfastness performance guarantees. Secure captive bromine access via long-term brine supply agreements or backward integration into Arkansas operations. Channel control through direct-to-farm digital platforms defends margin position against cooperative procurement consolidation. For New Entrants and Emerging Players: Anchor in Southeast Asian rice paddy mechanization demand for slow-release granule formulations as Vietnam and Thailand expand transplanting operations. Target aquatic weed control contractors in Australia's Murray-Darling basin where premium pricing tolerates new supplier qualification. Pursue go-to-market partnerships with irrigation district maintenance procurement offices. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because REACH SVHC classification in Europe and glyphosate resistance mandates in the Americas create divergent regional growth profiles. Acquisition candidates include regional blenders with ANVISA registration dossiers and Southeast Asian granule formulation specialists. Monitor ECHA authorization renewal timelines as inflection indicator for European market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Polymer R&D Partnership | BASF Ludwigshafen collaboration enables rainfastness performance guarantees for Brazilian Cerrado operations. |
| Backward Integration into Bromine Feedstock | Arkansas brine operation acquisition secures captive dibromide precursor supply against Dead Sea concentration. |
| Direct-to-Farm Digital Platform Launch | Mato Grosso cooperative procurement aggregation erodes legacy distributor margin capture. |
| ANVISA Registration Dossier Acquisition | Brazilian regional blender purchase accelerates residue compliance verification capacity. |
| Southeast Asian Granule Capacity Expansion | Vietnam and Thailand mechanized rice paddy demand favors precise slow-release distribution systems. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with agrochemical formulation chemists, Brazilian cooperative procurement managers, irrigation district maintenance contractors, and ANVISA regulatory affairs specialists; and secondary validation through customs trade data, EPA re-registration filings, ECHA SVHC dossiers, and SEC agrochemical segment disclosures. Bottom-up volume modeling triangulated against top-down market sizing.
Across the analysis window, forecasts applied segmentation by formulation type, application end-use, distribution channel, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for glyphosate resistance proliferation rates and pre-harvest desiccation protocol adoption curves. Industry-specific inputs included ANVISA residue tolerance revision schedules and ECHA authorization timeline assumptions.
Material uncertainties — regulatory reclassification, bromine feedstock supply disruption, and cooperative procurement platform consolidation velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Disinfectant Chemicals Market
Disinfectants and Preservatives
Continuously Sterilized Product Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Disinfectant Fogging and Misting Chemicals for Large Facilities Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market