
 Europe Disinfectant Wipes Market | 2026-2036
Europe Disinfectant Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Disinfectant Wipes Market Foresight
Healthcare facility procurement is consolidating around pre-saturated wipes that eliminate mixing errors and reduce cross-contamination risk. Kimberly-Clark leverages its institutional distribution network to sustain contract renewals across European hospital systems. STERIS differentiates through validated sterility claims that anchor its position in surgical suites and pharmaceutical cleanrooms. Reckitt Benckiser Group competes on brand recognition in food service and household channels where repeat purchase rates drive volume.
Europe disinfectant wipes are non-woven substrates impregnated with active biocidal solutions, typically quaternary ammonium compounds, alcohol blends, or chlorine-releasing agents, designed for surface decontamination without additional dilution or equipment. Alcohol-based formulations dominate clinical settings where rapid evaporation and broad-spectrum efficacy against enveloped viruses are required. Non-alcohol-based segments are gaining structural share in industrial and food service applications where flammability restrictions and material compatibility with sensitive equipment create specialized demand pools. Soft pack packaging leads in healthcare due to space efficiency and controlled dispensing, while canisters retain household penetration through countertop visibility and moisture retention.
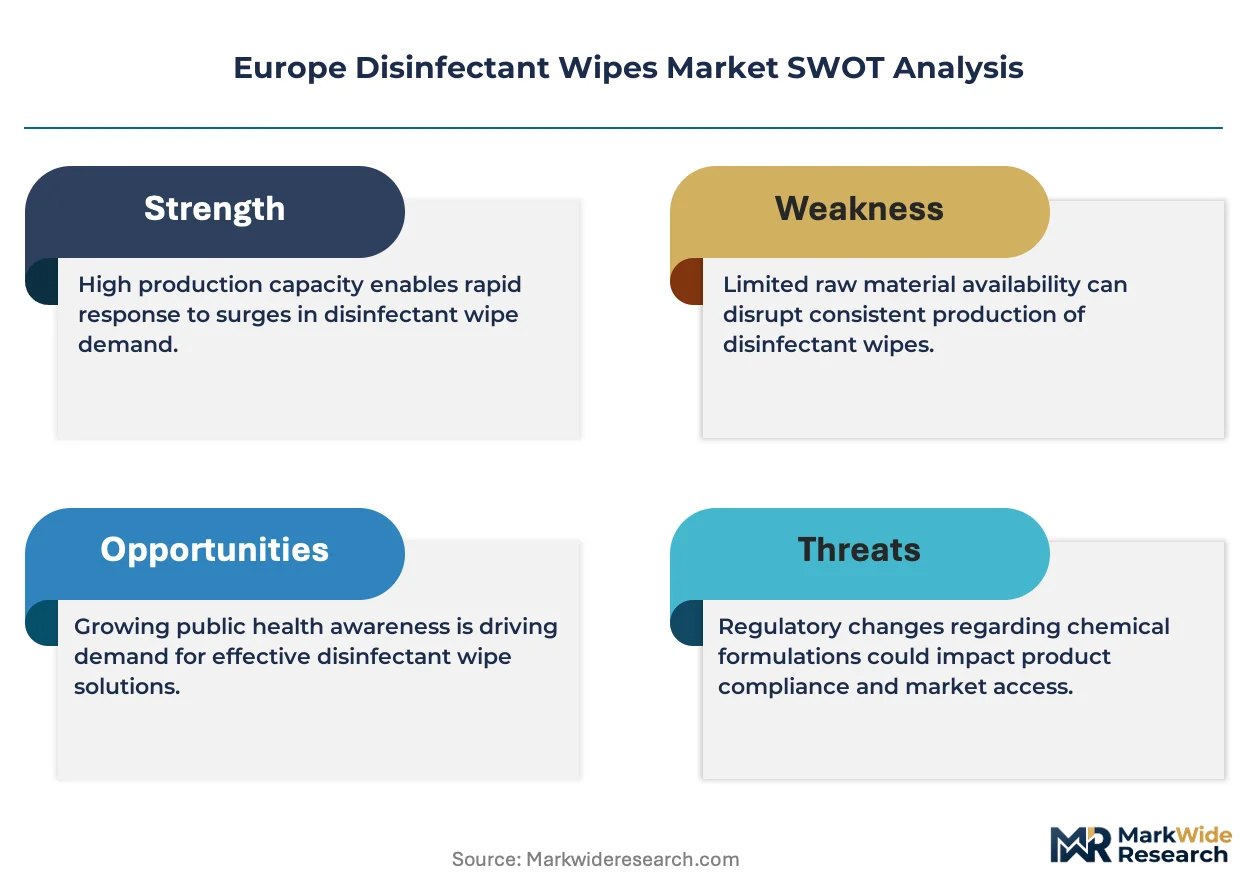
EMA biocidal product guidance, REACH substance restrictions, and EU Medical Device Regulation classification requirements collectively determine which active ingredients and substrate materials gain market access across member states. ECHA's ongoing substance evaluations are forcing reformulation cycles that favor quaternary ammonium and peracetic acid alternatives over legacy phenolic compounds. Stakeholders must monitor regulatory divergence between EU harmonized frameworks and national transposition variations that create compliance complexity for multi-country distribution strategies.
Market Dynamics
REACH substance evaluations and ECHA's biocidal product guidance are forcing simultaneous reformulation cycles across European manufacturers, compressing development timelines while elevating compliance costs for active ingredient suppliers.
Growth Catalysts
- EU Medical Device Regulation classification:Surgical suite protocols now mandate validated sterility claims for surface disinfection, expanding demand for pre-saturated formats that eliminate mixing protocols.
- Food service safety audits:HACCP-aligned inspection regimes in France and Germany require documented wipe-based sanitation cycles, creating procedural stickiness for institutional buyers.
- Quaternary ammonium compound advancement:Next-generation QAC formulations achieve phenolic-level efficacy without ECHA-restricted substances, opening regulatory-compliant pathways for legacy product replacements.
Market Restraints
- Isopropanol price volatility:Alcohol-based wipe production faces feedstock cost swings tied to European petrochemical capacity constraints and energy input fluctuations.
- Substrate supply concentration:Spunlace non-woven supply clusters in Germany and Italy create geographic vulnerability for converters dependent on just-in-time material flows.
- Biocidal Product Regulation renewal timelines:ECHA's active substance approval processes extend 18-36 months, freezing formulation innovation windows for pending evaluations.
Strategic Opportunities
- Peracetic acid wipe expansion:Sporicidal efficacy without chlorine corrosion opens pharmaceutical cleanroom and endoscope reprocessing applications previously blocked by material incompatibility.
- Central and Eastern Europe hospital procurement modernization:Poland and Romania healthcare infrastructure investments are adopting Western European infection control protocols, creating first-mover advantages for compliant suppliers.
- Refill pouch distribution models:Concentrate-to-wipe systems reduce transport emissions and packaging waste, aligning with EU Green Deal circular economy targets for institutional tenders.
Industry Challenges
- Formulation chemist scarcity:Biocidal regulatory science expertise concentrates in Basel and Frankfurt corridors, constraining R&D scaling for mid-tier manufacturers.
- MDR technical documentation burden:Class I medical device reclassification demands clinical evidence packages that extend product launch timelines 12-18 months.
- Cross-border notification fragmentation:National transposition variations between Germany's BfArM and France's ANSM create compliance complexity for multi-country distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Disinfectant Wipes Market |
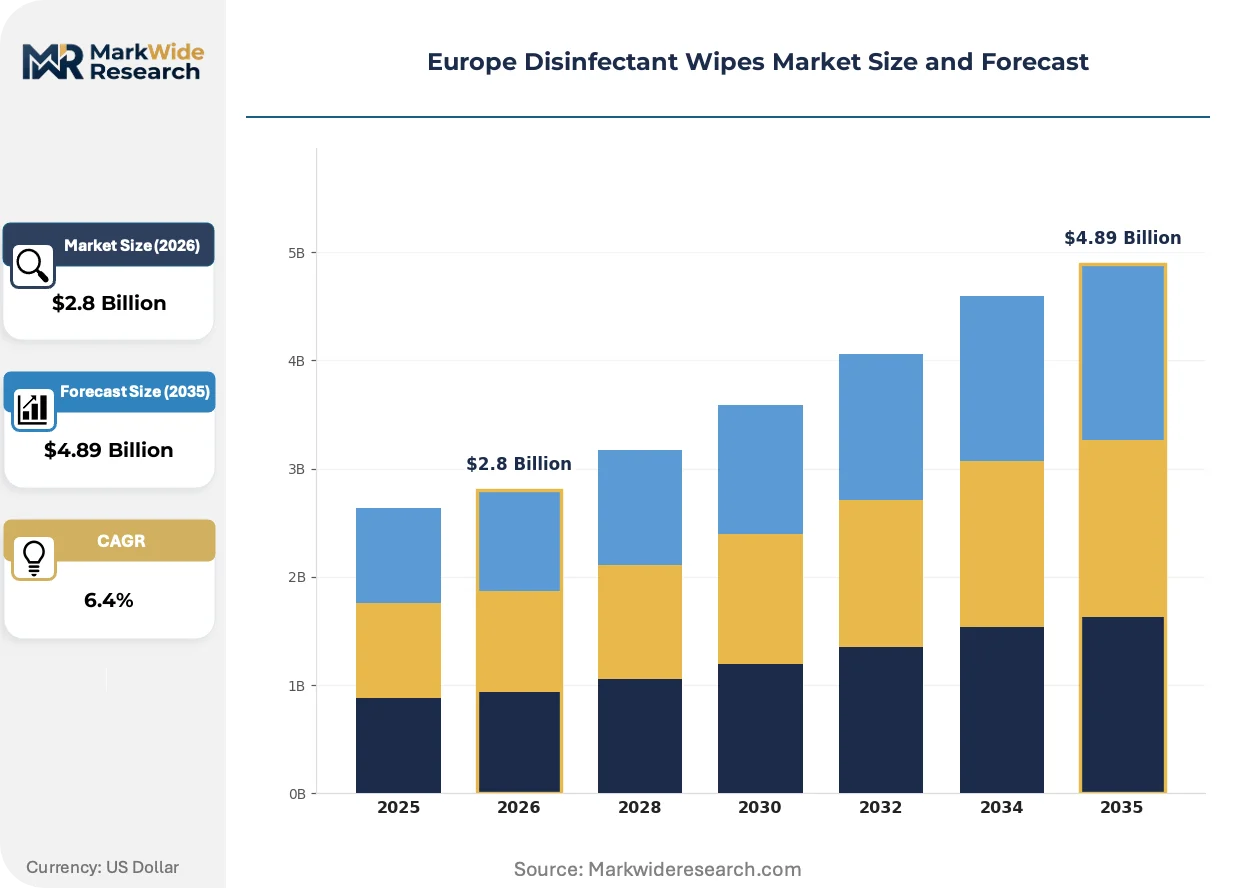
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol-based, Non-alcohol-based, Antimicrobial, Bleach-based End User: Household, Healthcare Facilities, Food Service, Industrial Packaging Type: Soft Packs, Canisters, Boxes, Bucket Distribution Channel: Online Retail, Supermarkets, Pharmacies, Wholesale |
| Companies Covered | Kimberly-Clark, STERIS, Reckitt Benckiser Group, GOJO Industries, Johnson & Johnson, Procter & Gamble, Ecolab, 3M, The Clorox Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Disinfectant Wipes Market Shifts & Advancements
Substrate engineering and active ingredient delivery systems are converging to address material compatibility gaps that previously blocked wipe penetration in precision manufacturing environments.
Cellulose-polyester hybrid substrates are unifying absorbency and lint-control properties in single-layer constructions. Semiconductor fabrication facilities in the Netherlands and Ireland are adopting these materials for cleanroom surface protocols. The technology is unifying previously separate wipe categories—general purpose and critical environment—into consolidated SKU portfolios that reduce procurement complexity.
ECHA's 2024-2026 substance evaluation roadmap prioritizes phenol and formaldehyde-releasing actives for restriction, accelerating QAC and peracetic acid migration. Industrial laundries and food processing plants face equipment replacement costs for dispensing systems incompatible with new chemistries. German chemical suppliers are pre-positioning alternative active portfolios to capture switching volumes during the 2025-2027 transition window.
Hospital procurement departments are consolidating surface disinfection contracts under single-source frameworks that bundle wipes, sprays, and compliance documentation. Group purchasing organizations in the United Kingdom and Scandinavia are displacing fragmented supplier relationships with multi-year agreements tying volume commitments to infection rate performance metrics. This concentration is most visible in NHS Trust procurement centralization, where 40% of acute trusts now operate under collaborative purchasing vehicles.
Europe Disinfectant Wipes Market Segmentation
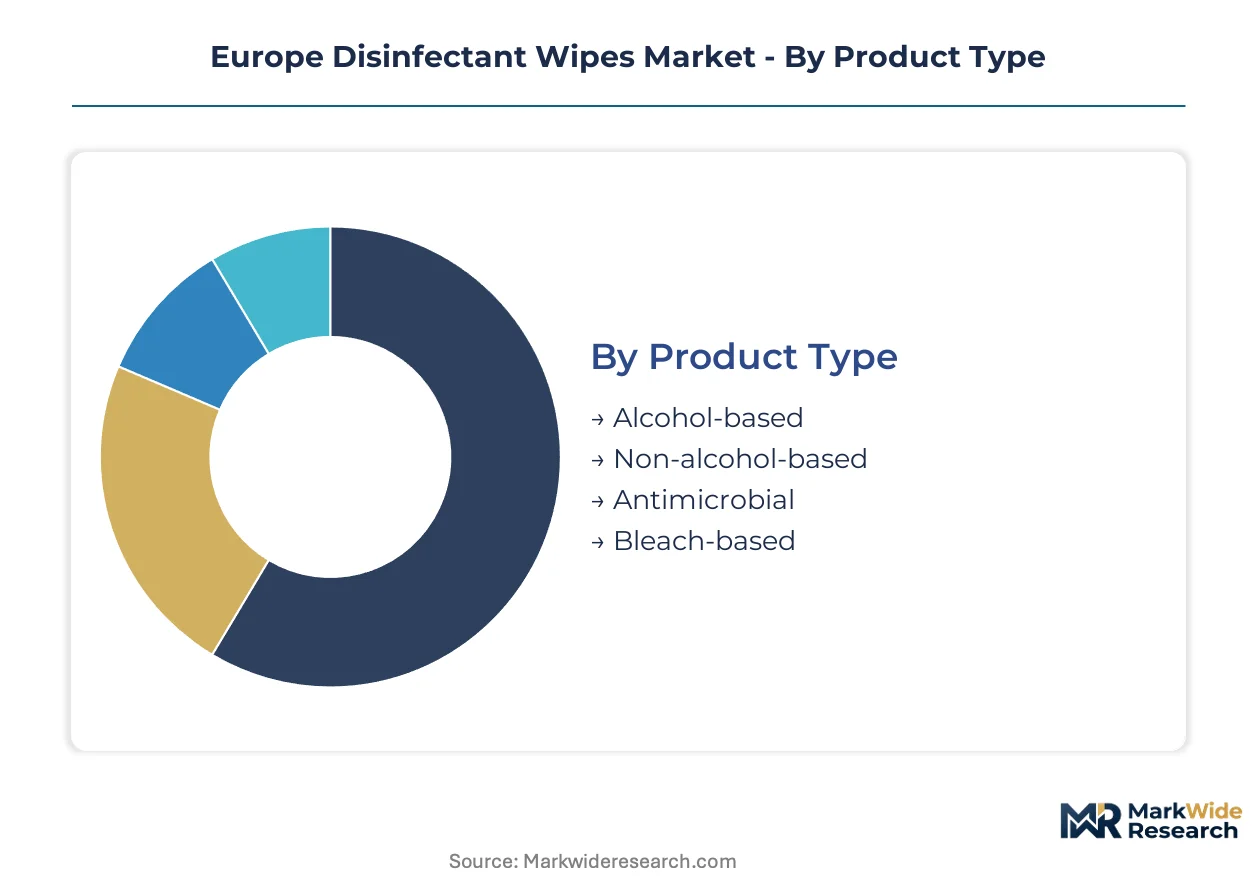
Europe disinfectant wipes segmentation reveals divergent technical requirements across clinical precision, food safety compliance, and household convenience. Manufacturers configure substrate chemistries and active ingredient loadings to match specific contamination risks and surface compatibility constraints rather than pursuing universal formulations.
Product Type:
Standardization dominates commodity segments while specialty formulations command customization premiums based on kill-claim validation and material compatibility testing.
- Alcohol-based:Isopropanol and ethanol blends impregnated at 60-70% concentration deliver rapid evaporation and broad-spectrum virucidal efficacy. German hospital procurement centralization and NHS Trust collaborative purchasing vehicles are concentrating demand for validated sterility claims in surgical suites and emergency departments where dwell time minimization matters.
- Non-alcohol-based:Quaternary ammonium compound and peracetic acid formulations address flammability restrictions in industrial settings and material sensitivity in electronics manufacturing. French food processing plants and Dutch semiconductor fabrication facilities are expanding procurement of these chemistries as REACH substance evaluations restrict legacy phenolic alternatives.
- Antimicrobial:Persistent-residue actives including silver ion and PHMB formulations for extended surface protection in high-touch healthcare environments.
- Bleach-based:Sodium hypochlorite-impregnated substrates for sporicidal applications in pharmaceutical cleanrooms and outbreak response protocols where corrosion tolerance permits.
Leading the category by volume: Alcohol-based. Growing fastest: Non-alcohol-based.
End User:
Institutional buyers prioritize compliance documentation and infection rate performance metrics while household purchasers respond to brand recognition and shelf visibility.
- Healthcare Facilities:Acute care hospitals, outpatient clinics, and long-term care institutions operating under EU Medical Device Regulation classification requirements. Procurement departments in United Kingdom NHS Trusts and Scandinavian group purchasing organizations are consolidating surface disinfection contracts under single-source frameworks bundling wipes, sprays, and compliance documentation tied to infection rate performance metrics.
- Household:Residential consumers purchasing through supermarkets and online retail channels where repeat purchase rates and countertop visibility drive volume. United Kingdom and German markets show highest penetration of canister formats emphasizing moisture retention and convenience.
- Food Service:Restaurants, catering operations, and food processing plants subject to HACCP-aligned inspection regimes in France and Germany requiring documented wipe-based sanitation cycles.
- Industrial:Manufacturing facilities, pharmaceutical cleanrooms, and precision electronics environments where lint control and material compatibility determine substrate selection.
Highest procurement sophistication: Healthcare Facilities. Steepest expansion trajectory: Food Service.
Packaging Type:
Dispensing format selection balances space efficiency, moisture retention, and controlled access requirements across institutional and consumer contexts.
- Soft Packs:Flexible film pouches with resealable closures optimized for space-constrained storage and controlled single-wipe dispensing. Healthcare facilities across Germany and France favor this format for cart-based protocols and isolation room restocking where package footprint reduction matters.
- Canisters:Rigid plastic containers with airtight lids maintaining solution saturation over extended use periods. Household penetration concentrates in United Kingdom and German markets where countertop visibility and brand differentiation drive placement.
- Boxes:Cardboard enclosures with pop-up dispensing for cost-sensitive institutional procurement and bulk distribution models.
- Bucket:Large-capacity refillable systems for industrial laundries and food processing plants with high-volume consumption patterns.
Dominant format by institutional volume: Soft Packs. Gaining share fastest in sustainability-focused procurement: Boxes.
Distribution Channel:
Channel selection reflects purchase frequency, regulatory documentation requirements, and buyer sophistication segmentation across consumer and institutional markets.
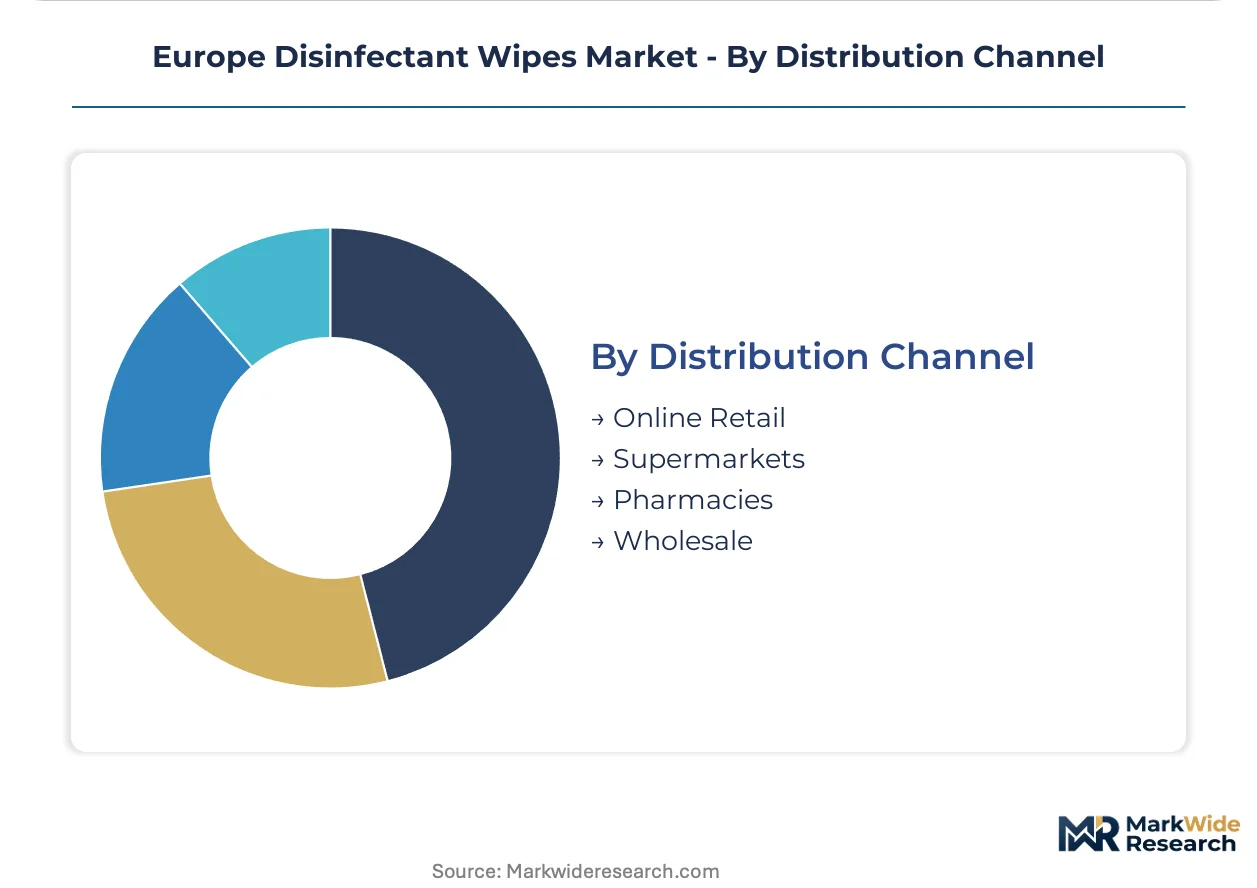
- Online Retail:E-commerce platforms serving household replenishment and small healthcare facility procurement with subscription models and bulk pricing tiers. United Kingdom and German markets show highest penetration of direct-to-institution platforms bypassing traditional distribution.
- Supermarkets:Mass-market retail chains dominating household volume through high-visibility placement and promotional pricing. France and United Kingdom supermarket consolidation is displacing fragmented independent pharmacy distribution for consumer-grade products.
- Pharmacies:Community and hospital pharmacy networks emphasizing clinical credibility and healthcare professional recommendation for premium formulations.
- Wholesale:Institutional supply distributors and group purchasing organization channels managing multi-site healthcare and food service contracts with consolidated invoicing and compliance documentation.
Largest volume channel: Wholesale. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany dominates European disinfectant wipe production capacity, while consumption concentrates across Western European healthcare systems. Central and Eastern European markets are accelerating procurement modernization as EU infection control protocols extend eastward.
Germany
Hospital procurement centralization and BfArM regulatory leadership drive institutional demand for validated sterility formats. REACH substance evaluations force active ingredient transitions across Rhineland chemical corridors. Bavarian spunlace non-woven clusters supply substrate materials to converters serving pharmaceutical cleanrooms.
United Kingdom
NHS Trust collaborative purchasing vehicles consolidate 40% of acute trust surface disinfection contracts under single-source frameworks. MHRA medical device classification requirements extend MDR compliance timelines for domestic suppliers. Greater London procurement hubs bundle wipes with infection rate performance metrics.
France
ANSM notification requirements and HACCP-aligned food safety audits create procedural stickiness for institutional buyers. Quaternary ammonium compound adoption accelerates as ECHA restricts legacy phenolic alternatives. Auvergne-Rhône-Alpes food processing clusters expand documented wipe-based sanitation cycles.
Netherlands
Semiconductor fabrication facilities in Eindhoven adopt cellulose-polyester hybrid substrates for cleanroom surface protocols. EMA biocidal product guidance shapes formulation standards for export-oriented manufacturers. Rotterdam distribution infrastructure supports just-in-time material flows to German and Belgian converters.
Poland
Healthcare infrastructure investments adopt Western European infection control protocols, creating first-mover advantages for compliant suppliers. National transposition of EU Medical Device Regulation lags core markets by 12-18 months. Warsaw procurement offices centralize hospital system contracting for pre-saturated formats.
Europe Disinfectant Wipes Market Competitive Landscape
Top-tier vendors anchor hospital and pharmaceutical procurement channels, while mid-tier specialists compete on food service and industrial compliance documentation. The vendor base stratifies across three tiers: multinational hygiene conglomerates with institutional distribution networks, regional chemical converters with substrate engineering capabilities, and private-label assemblers serving cost-sensitive retail channels. Dominant competitive moves include M&A to capture ECHA-compliant formulation portfolios and capacity expansion into Central European manufacturing zones.
Among US-based multinationals, Kimberly-Clark and STERIS exemplify divergent archetypes within institutional healthcare supply. Kimberly-Clark occupies a position tied to contract renewal velocity across European hospital systems, while STERIS represents validated sterility claim specialization for surgical suites and pharmaceutical cleanrooms. Reckitt Benckiser Group anchors the consumer-facing tier where brand recognition and repeat purchase rates determine shelf placement economics.
| Leading Market Players |
|---|
| Kimberly-Clark |
| STERIS |
| Reckitt Benckiser Group |
| GOJO Industries |
| Johnson & Johnson |
| Procter & Gamble |
| Ecolab |
| 3M |
| The Clorox Company |
| Others |
Supply & Pricing Matrix
NHS Trust collaborative purchasing vehicles and German hospital procurement centralization concentrate buyer power, compressing contract margins while elevating compliance documentation costs as non-negotiable table stakes for market access.
Pricing Analysis
Margin tightening in standard alcohol-based formulations reflects REACH-driven reformulation cycles and isopropanol feedstock volatility. Three-tier pricing structure across validated sterility, clinical-grade, and economy levels separates surgical suite premiums from food service procurement. Cost-down pressure on mid-tier converters accelerates because spunlace substrate supply clusters in Bavaria and northern Italy create geographic bottlenecks. Household purchasers through United Kingdom and German supermarkets show highest price elasticity, while pharmaceutical cleanroom buyers accept sustained premiums for peracetic acid validated claims.
Supply Chain Analysis
EU Medical Device Regulation domestic-content requirements and ECHA biocidal product guidance are reshaping active ingredient sourcing toward Rhineland chemical corridors and compliant QAC suppliers. Substrate engineering draws from German spunlace non-woven clusters, Italian converter capacity, and Dutch cellulose-polyester hybrid development. Single-source vulnerability concentrates in Bavarian material flows for healthcare soft-pack formats. Distribution runs through wholesale institutional channels and direct-to-hospital platforms bypassing traditional pharmaceutical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quaternary ammonium compound and peracetic acid formulations are displacing legacy phenolic chemistries as ECHA substance evaluations restrict formaldehyde-releasing actives, creating formulation-transition arbitrage for prepared suppliers.
For Market Incumbents: To counter mid-tier converter encroachment on food service HACCP contracts, anchor hospital system renewals through infection rate performance guarantees bundled with compliance documentation. Backward integration into spunlace substrate production in Central European manufacturing zones secures material flows against Italian supply concentration. For New Entrants and Emerging Players: Enter via Poland and Romania healthcare infrastructure modernization, where EU Medical Device Regulation transposition lags core markets by 12-18 months. Target pharmaceutical cleanroom peracetic acid segments where material compatibility testing creates specialist barriers. Pursue refill pouch distribution models aligned with EU Green Deal circular economy procurement criteria. For Investors and Strategic Acquirers: The window for entry favors regional chemical converters with ECHA-compliant formulation portfolios and substrate engineering capabilities. Long-term viability rests on capturing 2025-2027 phenolic-replacement switching volumes. Watch ECHA active substance approval timelines as inflection indicator for formulation innovation windows freezing or releasing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spunlace Substrate Production | Bavarian and Polish manufacturing zones reduce dependency on Italian supply clusters. |
| Peracetic Acid Formulation Portfolio Expansion | Sporicidal efficacy without chlorine corrosion opens pharmaceutical cleanroom applications. |
| Refill Pouch Distribution Model Launch | Concentrate-to-wipe systems align with EU Green Deal institutional tender requirements. |
| Hospital System Partnership with Infection Rate Metrics | NHS Trust collaborative purchasing vehicles bundle performance guarantees with volume commitments. |
| ECHA-Compliant QAC Formulation Pre-Positioning | German chemical suppliers capture phenolic-replacement switching volumes during transition window. |
Research Methodology
Multi-period observation of ECHA substance evaluation timelines, hospital procurement centralization patterns, and REACH compliance cost trajectories anchored the trend analysis, supplemented by interviews with infection control officers, pharmaceutical cleanroom managers, food safety auditors, group purchasing organization contract managers, and spunlace non-woven plant engineers. Secondary validation drew from ECHA biocidal product databases, EU Medical Device Regulation technical documentation filings, NHS procurement disclosure records, Cefic chemical industry reports, and customs trade flow data. Bottom-up volume modeling and top-down market sizing triangulated segment estimates.
Segment-weighting across product type, end user, packaging format, and distribution channel dimensions structured the analytical framework. CAGRs were derived from normalized growth rate convergence across independent projection methods. Industry-specific forecast inputs included ECHA active substance approval pipeline status, hospital procurement contract renewal cycles, and food service HACCP audit expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance restriction acceleration or spunlace supply disruption scenarios. Forecasts reflect documented assumptions regarding regulatory timeline adherence and procurement modernization velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Asia-Pacific Agricultural Disinfectants Market
Disinfectants and Preservatives
Antibacterial Products Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Global Mold Inhibitors Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
MMA Triazine Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
India Air Treatment Products Market