
 North America Disinfectant Wipes Market | 2026-2036
North America Disinfectant Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Disinfectant Wipes Market Analytics
Aftermarket service revenue from dispenser fleet management and restocking logistics is narrowing as manufacturers consolidate control over point-of-use consumption data. The Clorox Company leverages its retail shelf presence and healthcare channel partnerships to sustain volume leadership across both consumer and institutional tiers. Kimberly-Clark Corporation anchors its position through captive nonwoven substrate production, while PDI competes aggressively in acute-care settings with EPA-registered hospital disinfectant formulations.
Disinfectant wipes are nonwoven substrates impregnated with antimicrobial chemistries—typically quaternary ammonium compounds, sodium hypochlorite, or isopropyl alcohol at concentrations between 0.5% and 5.5%—engineered for one-step cleaning and disinfection of hard, non-porous surfaces in clinical, commercial, and residential environments. Alcohol-based formulations dominate acute-care procurement due to fast kill times against enveloped viruses, while biodegradable product types are gaining fastest in educational institutions and municipal facilities responding to state-level procurement preferences. Healthcare end users command the deepest margin pools owing to validation requirements and formulary stickiness, whereas residential demand fragments across price-sensitive retail channels.
EPA registration under FIFRA governs efficacy claims and label chemistry, while OSHA bloodborne pathogen standards mandate surface disinfection protocols in healthcare and industrial workplaces. State regulators in California enforce Proposition 65 disclosure requirements and green chemistry restrictions that push manufacturers toward lower-toxicity active ingredients. Stakeholders must monitor evolving EPA List N renewal criteria and state procurement mandates to anticipate which chemistries and substrate formats will retain market access.
Market Dynamics
Hospital-grade formulation mandates from the EPA's emerging viral pathogens guidance are compressing supply chains toward validated chemistries while green chemistry laws in California and New York simultaneously force substrate and active ingredient substitutions.
Growth Catalysts
- Terminal cleaning protocol expansion:Healthcare facilities across the U.S. Northeast corridor are institutionalizing wipe-based disinfection for patient room turnover, creating formulary stickiness for validated products.
- Proposition 65 disclosure alignment:California's toxic chemical labeling requirements are accelerating manufacturer investment in quaternary ammonium alternatives that preempt litigation risk.
- Aging hospital infrastructure:Dense institutional networks in Boston, New York, and Philadelphia sustain above-average consumption rates for surface disinfection products.
Market Restraints
- Fluctuating isopropyl alcohol feedstock costs:Energy price volatility and refinery capacity constraints create margin compression for alcohol-based formulation producers.
- Captive nonwoven substrate concentration:Kimberly-Clark's in-house supply control and limited third-party spunlace capacity create bottlenecks for new entrants seeking hospital-grade material specifications.
- EPA FIFRA registration timelines:The 12-24 month efficacy validation process creates regulatory lag that delays chemistry innovation cycles.
Strategic Opportunities
- Municipal facility procurement mandates:State-level green chemistry preferences in New York and Vermont are opening specification windows for biodegradable substrate formats in schools and government buildings.
- Acute-care fast-kill positioning:Alcohol-based formulations with sub-30 second contact times are capturing share in emergency departments and surgical suites where throughput drives purchasing decisions.
- Direct dispenser fleet contracting:Manufacturers are bypassing distributor intermediaries to capture point-of-use consumption data and secure recurring restock revenue streams.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required to balance antimicrobial efficacy with substrate compatibility and EPA label compliance is concentrating among a limited talent pool.
- OSHA bloodborne pathogen standard integration:Healthcare employers must reconcile surface disinfection protocols with employee exposure limits, creating compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Disinfectant Wipes Market |
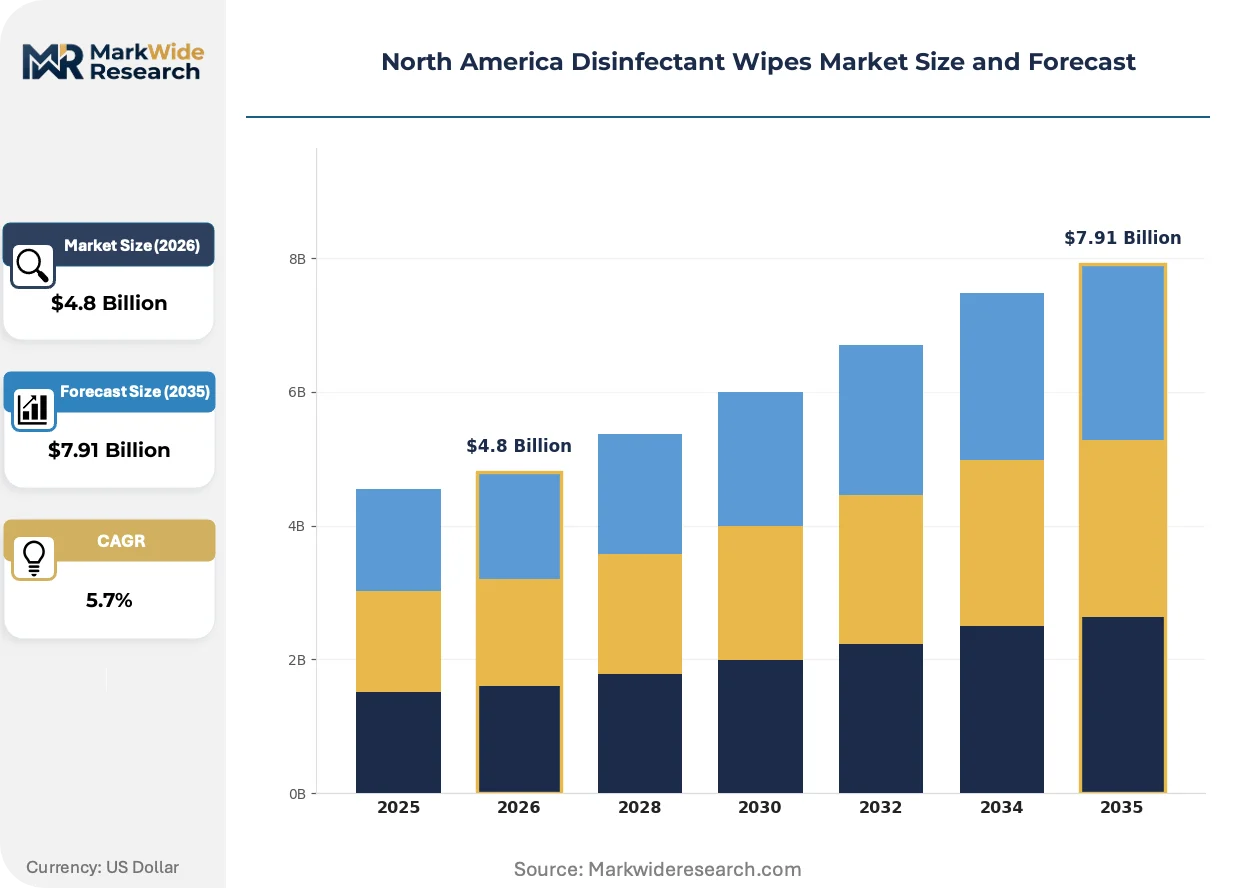
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Alcohol-Based, Antimicrobial, Biodegradable End User: Healthcare, Educational Institutions, Industrial Facilities, Residential Packaging Type: Canisters, Pouches, Single-Use Packs, Bulk Packaging Distribution Channel: Online Retail, Supermarkets, Pharmacies, Wholesale |
| Companies Covered | The Clorox Company, Reckitt Benckiser Group PLC, Procter & Gamble, Kimberly-Clark Corporation, SC Johnson & Son, Ecolab, GOJO Industries, PDI, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Disinfectant Wipes Market Evolving Landscape
Formulation chemistry and substrate engineering are converging to address simultaneous demands for faster kill kinetics, lower toxicity profiles, and biodegradability in institutional procurement specifications.
Plant-derived quaternary ammonium compounds synthesized from renewable feedstocks are rendering obsolete petroleum-based benzalkonium chloride formulations in municipal and educational procurement channels. Facility managers in California school districts and Vermont state buildings are specifying these alternatives to meet green chemistry mandates. The structural consequence is a bifurcation in R&D investment between legacy chemistries serving acute-care markets and bio-based platforms targeting sustainability-driven buyers.
EPA List N renewal criteria are tightening efficacy documentation requirements for emerging viral pathogen claims, forcing manufacturers to maintain active clinical testing programs. The industrial consequence is elevated compliance costs that favor larger registrants with dedicated regulatory affairs teams. Hospital procurement committees are responding by consolidating supplier relationships toward entities with demonstrated renewal track records, compressing vendor diversity in acute-care settings.
Subscription-based dispenser programs are displacing transactional case-lot purchasing in long-term care and corporate facility management. Sodexo, Aramark, and regional facility service providers are consolidating consumption data through captive IoT-enabled dispensers that automate reorder triggers. This pattern is most visible in the U.S. Southeast, where nursing home chains and commercial real estate operators prioritize labor cost reduction over unit price negotiation.
North America Disinfectant Wipes Market Segmentation
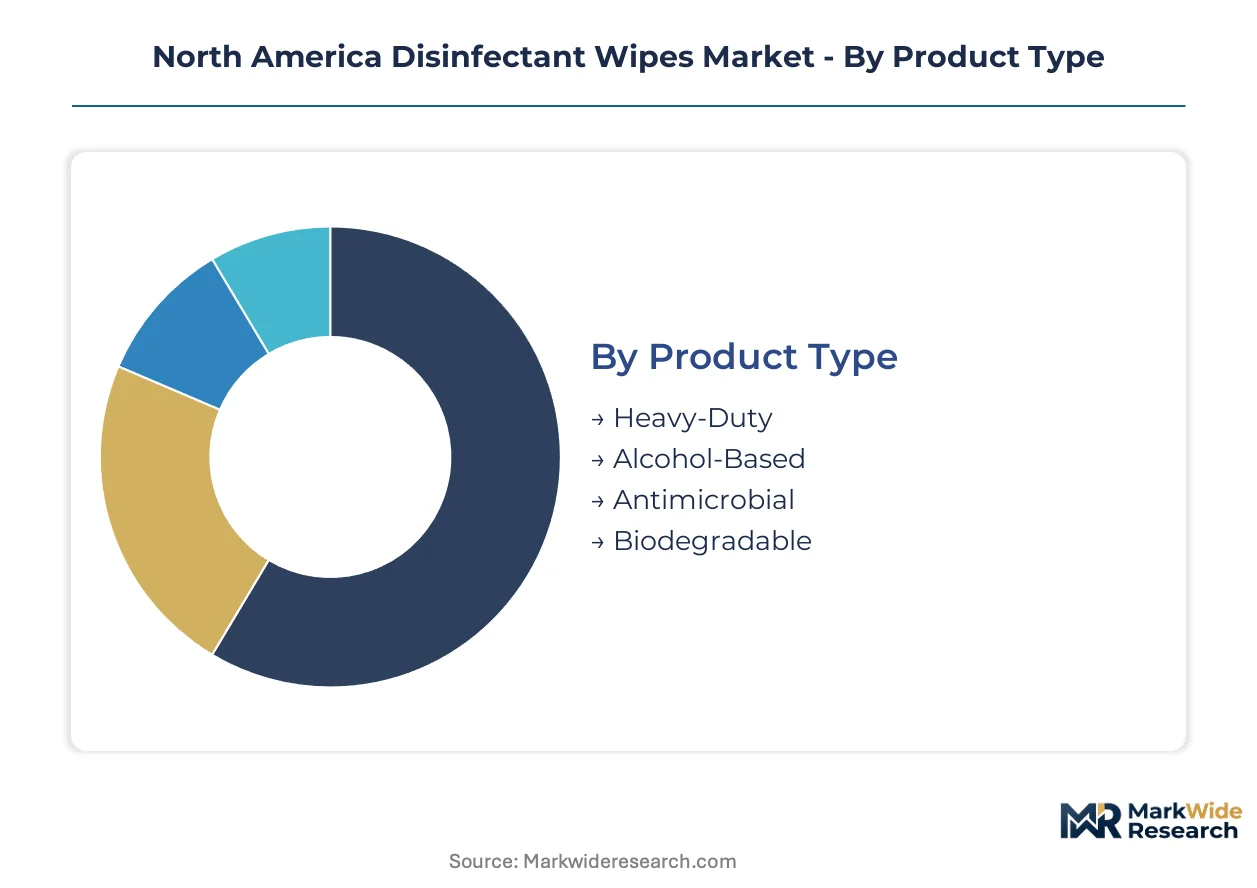
Segmentation in the North America Disinfectant Wipes Market reveals distinct procurement patterns across formulation chemistry, institutional end-use, packaging format, and channel structure. Each dimension carries unique margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Cost tier differentiation separates premium hospital-grade formulations from economy residential offerings, with active ingredient chemistry and substrate engineering driving price stratification.
- Heavy-Duty:Quaternary ammonium and sodium hypochlorite formulations engineered for terminal cleaning protocols in acute-care settings. Demand concentrates across the U.S. Northeast corridor where aging hospital infrastructure sustains elevated consumption rates for validated chemistries.
- Alcohol-Based:Isopropyl alcohol concentrations between 0.5% and 5.5% deliver sub-30 second kill times against enveloped viruses. Emergency departments and surgical suites in Boston and Philadelphia prioritize these formulations where patient throughput drives purchasing decisions.
- Antimicrobial:Broad-spectrum formulations targeting bacteria and fungi in commercial and light industrial environments. Food processing facilities and logistics warehouses specify these for routine surface maintenance.
- Biodegradable:Plant-derived substrates with renewable quaternary ammonium compounds. California school districts and Vermont state buildings mandate these alternatives under green chemistry procurement preferences.
Heavy-Duty holds installed capacity. Biodegradable is rotating up the share rankings.
End User:
Application context determines formulation specification, validation requirements, and pricing power across institutional and residential environments.
- Healthcare:EPA-registered hospital disinfectants with documented efficacy against emerging viral pathogens. The EPA's List N renewal criteria and OSHA bloodborne pathogen standards create formulary stickiness and deep margin pools.
- Educational Institutions:K-12 districts and university facilities balance cost containment with state-level green chemistry mandates. California's Proposition 65 disclosure requirements accelerate shifts toward lower-toxicity alternatives.
- Industrial Facilities:Manufacturing plants and warehousing operations prioritize bulk formats and fast-evaporation chemistries compatible with production schedules.
- Residential:Price-sensitive demand fragments across retail channels with limited brand loyalty and minimal regulatory compliance burden.
Healthcare commands the deepest margin pools. Educational Institutions are expanding specification windows fastest.
Packaging Type:
Volume and usage frequency dictate format selection, with institutional procurement favoring efficiency and residential channels prioritizing convenience and shelf appeal.
- Canisters:Rigid plastic containers with moisture-sealing lids for high-frequency access points. Nursing stations and patient rooms in U.S. Northeast hospitals standardize on this format.
- Pouches:Flexible resealable packaging for mid-volume commercial users seeking portability and reduced storage footprint.
- Single-Use Packs:Individually wrapped wipes for field service, travel, and controlled distribution environments.
- Bulk Packaging:Refill cartons and dispenser-compatible rolls for facility management contracts with automated restocking systems.
Canisters dominate acute-care installed base. Bulk Packaging is gaining share in facility service contracts.
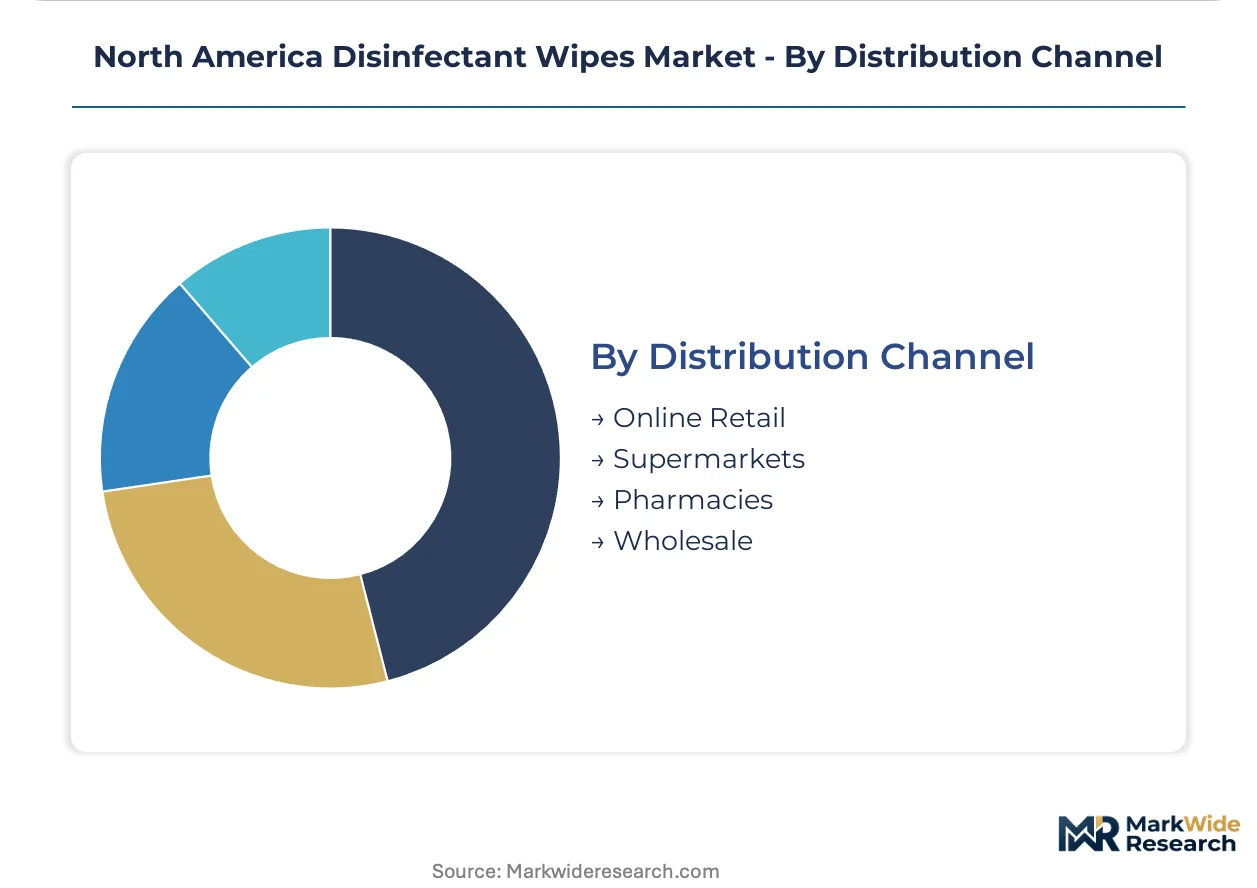
Distribution Channel:
Customer type and purchase scale determine channel selection, with institutional buyers consolidating through direct contracting and residential consumers fragmenting across retail touchpoints.
- Online Retail:Subscription programs and direct-to-consumer replenishment for residential and small commercial accounts. The channel captures recurring revenue through automated reorder triggers.
- Supermarkets:Mass-market shelf presence for household disinfectant wipes with promotional pricing driving volume.
- Pharmacies:Healthcare-adjacent positioning for alcohol-based and antimicrobial formulations targeting home health and first-aid applications.
- Wholesale:Case-lot distribution to facility management providers, janitorial supply houses, and institutional procurement cooperatives.
Wholesale retains institutional volume leadership. Online Retail is climbing the fastest in recurring revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in Mexico exhibit acute price sensitivity, while institutional purchasers across the U.S. Northeast corridor demonstrate minimal elasticity as validated chemistries command formulary premiums. This demand-elasticity contrast shapes regional investment priorities and margin capture strategies.
United States
The U.S. Northeast corridor sustains the densest concentration of acute-care procurement, with Boston, New York, and Philadelphia hospital networks institutionalizing terminal cleaning protocols. EPA's emerging viral pathogens guidance and List N renewal criteria create regulatory stickiness for validated formulations. California's Proposition 65 disclosure requirements and green chemistry mandates accelerate shifts toward quaternary ammonium alternatives in municipal and educational procurement channels.
Canada
Health Canada and PMRA registration requirements parallel EPA standards while maintaining distinct efficacy documentation protocols that favor established registrants. Ontario and Quebec healthcare systems consolidate purchasing through provincial procurement cooperatives, compressing vendor diversity. The Greater Toronto Area anchors institutional demand as aging hospital infrastructure sustains above-average consumption rates for surface disinfection products.
Mexico
Price-sensitive residential demand dominates volume as retail channels fragment across informal distribution networks and modern trade formats. Federal Commission for the Protection against Sanitary Risk (COFEPRIS) regulates antimicrobial claims with evolving alignment to U.S. EPA standards. Mexico City Metro and Nuevo León industrial corridors generate concentrated institutional demand from manufacturing facilities and healthcare systems seeking validated chemistries.
North America Disinfectant Wipes Market Competitive Landscape
Capability concentration sits with substrate engineering specialists; scale advantage sits with retail distribution incumbents. The market structures around three tiers: integrated nonwoven producers controlling upstream material specifications, formulation specialists with dedicated regulatory affairs capacity, and retail-brand houses leveraging shelf presence. Strategic moves center on direct dispenser fleet contracting to capture point-of-use consumption data and captive substrate capacity expansion to secure hospital-grade material access.
Within the integrated substrate tier, Kimberly-Clark Corporation exemplifies backward control over spunlace production. The Clorox Company and PDI occupy positions across the formulation-regulatory spectrum, with the former anchoring retail channel dominance and the latter representing acute-care specialization. These three entities collectively illustrate the capability-scale tradeoffs defining competitive positioning.
| Leading Market Players |
|---|
| The Clorox Company |
| Reckitt Benckiser Group PLC |
| Procter & Gamble |
| Kimberly-Clark Corporation |
| SC Johnson & Son |
| Ecolab |
| GOJO Industries |
| PDI |
| 3M |
| Others |
Value Network & Pricing Analysis
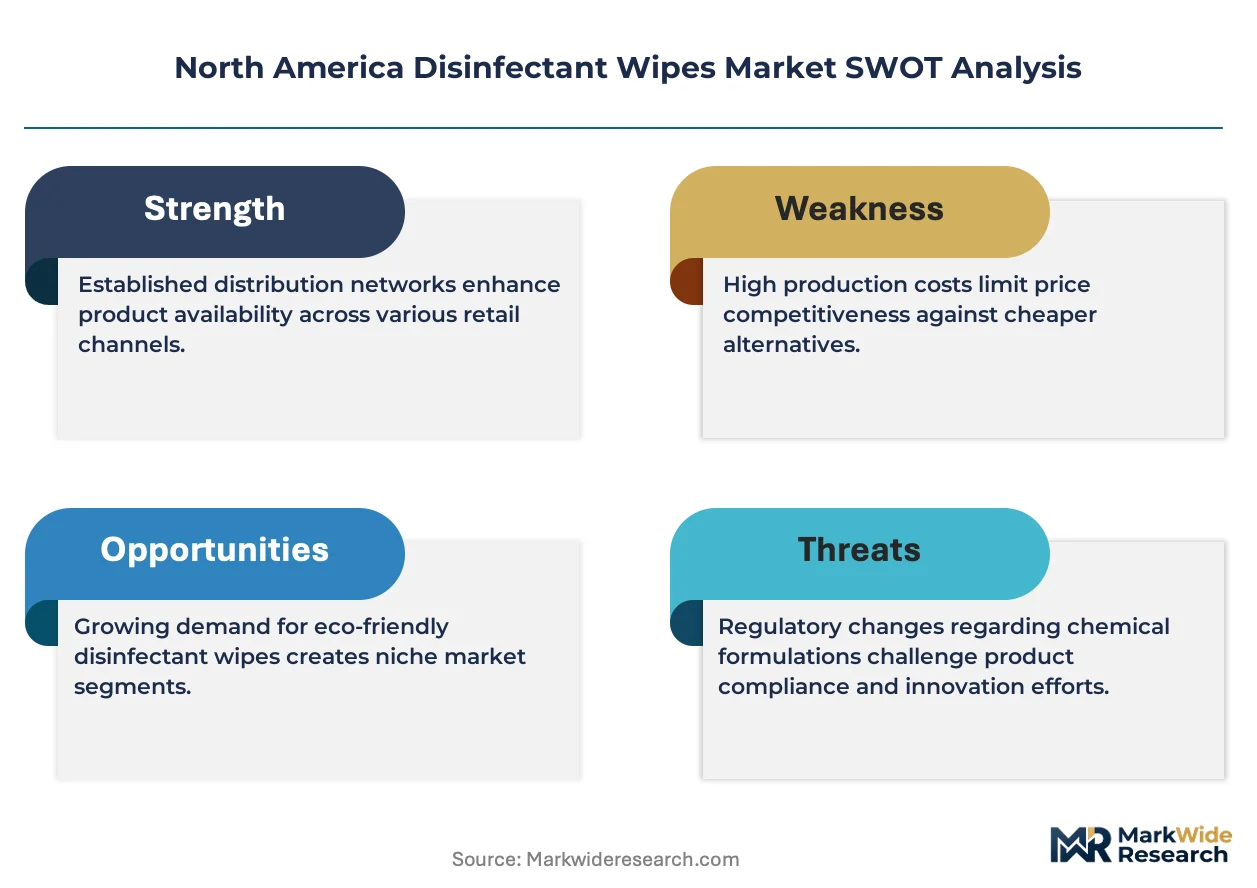
Isopropyl alcohol feedstock volatility compresses margin spreads across formulation tiers while simultaneously forcing substrate sourcing decisions toward captive nonwoven capacity. This dual pressure mechanism stratifies pricing power between integrated producers with backward material control and formulation specialists exposed to spot chemical markets.
Pricing Analysis
Dispenser fleet management contracts now anchor lifetime value capture for institutional tier suppliers. Three-tier pricing structure across premium hospital-grade, validated commercial, and economy residential levels reflects EPA registration burden and substrate engineering differentiation. Cost compression in alcohol-based formulations is intensifying because energy price volatility feeds directly into active ingredient input costs. Residential buyers through supermarket and online channels exhibit acute price sensitivity, whereas healthcare procurement committees demonstrate minimal elasticity for validated chemistries with documented emerging viral pathogen efficacy.
Supply Chain Analysis
Extended payment terms from facility management consolidators like Sodexo and Aramark are restructuring working capital requirements for mid-tier manufacturers. Spunlace nonwoven substrate production concentrates in the United States, Canada, and Mexico, with Kimberly-Clark's captive capacity creating access bottlenecks for new entrants. Formulation chemistry draws from quaternary ammonium compound feedstocks, isopropyl alcohol refined from petroleum derivatives, and plant-derived alternatives synthesized from renewable agricultural inputs. Single-source vulnerability sits with limited third-party spunlace capacity meeting hospital-grade material specifications. Distribution runs through wholesale case-lot channels for institutional volume, with direct dispenser fleet contracting displacing traditional distributor intermediaries in long-term care and corporate facility segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-era inventory destocking cyclicality, with hospital capital expenditure renewal now driving procurement normalization. The replacement cycle for aging dispenser infrastructure sustains demand visibility across the acute-care segment.
For Market Incumbents: Pre-empt formulation chemist scarcity by anchoring regulatory affairs capacity and captive substrate engineering teams. Secure EPA List N renewal track records to consolidate hospital procurement committee relationships against emerging bio-based entrants. Defensive consolidation around point-of-use consumption data through IoT-enabled dispenser fleets closes specification windows for competitors.
For New Entrants and Emerging Players: Mexico's price-sensitive residential channels remain structurally underpenetrated by validated institutional brands, creating white-space for economy-tier positioning. Vermont and New York municipal procurement mandates for biodegradable substrates open specification windows for plant-derived quaternary ammonium alternatives. Target facility service providers in the U.S. Southeast nursing home corridor with subscription-based dispenser programs that prioritize labor cost reduction over unit price negotiation.
For Investors and Strategic Acquirers: EPA List N renewal criteria tightening reshapes the acquisition landscape toward registrants with dedicated clinical testing infrastructure and demonstrated efficacy documentation. Long-term viability across the analysis window favors entities balancing acute-care validation depth with sustainability-positioned SKU expansion for educational and municipal channels. The signal to watch is state-level green chemistry mandate proliferation beyond California and New York, which would accelerate biodegradable substrate format adoption and compress legacy petroleum-based formulation valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Nonwoven Capacity Expansion | Kimberly-Clark's spunlace control secures hospital-grade material access against third-party bottlenecks. |
| Direct Dispenser Fleet Contracting | IoT-enabled restocking systems capture point-of-use data from Sodexo and Aramark consolidators. |
| Bio-Based Formulation Platform | Plant-derived quaternary ammonium compounds preempt Proposition 65 litigation risk in California procurement. |
| EPA List N Renewal Investment | Active clinical testing programs maintain emerging viral pathogen claim validity for hospital formulary retention. |
| Subscription Revenue Model Transition | Automated reorder triggers through dispenser fleets displace transactional case-lot purchasing in long-term care. |
Research Methodology
The analysis maps hospital-grade formulations, commercial antimicrobial variants, alcohol-based acute-care products, and biodegradable alternatives, each validated through procurement directors at GPO-affiliated health systems, EPA regulatory affairs consultants, nonwoven substrate engineers, and facility management executives at nursing home chains. Primary fieldwork combined structured interviews with secondary validation against EPA registration databases, Health Canada PMRA filings, customs trade records for isopropyl alcohol feedstocks, and hospital procurement cooperative contract disclosures. Bottom-up demand modeling across end-use segments triangulated against top-down formulation chemistry production capacity assessments.
Assumptions held fixed include EPA FIFRA registration timelines and OSHA bloodborne pathogen standard enforcement intensity, while variables included state-level green chemistry mandate adoption rates and isopropyl alcohol feedstock price volatility. The projection framework segmented by formulation chemistry tier, institutional end-use vertical, packaging format efficiency, and distribution channel structure across the modeling period. CAGRs derived from hospital capital expenditure renewal patterns, educational institution procurement cycle timing, and residential channel inventory restocking velocity. Industry-specific inputs incorporated EPA List N renewal criteria evolution and spunlace nonwoven capacity utilization rates.
Practitioners should monitor state-level procurement mandate expansion, captive substrate capacity additions, and dispenser fleet contract penetration for early signals of structural shift. Forecasts reflect documented assumptions; deviation in regulatory enforcement intensity, feedstock cost trajectories, or hospital capital allocation priorities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Asia-Pacific Agricultural Disinfectants Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Disinfecting Wipes Market