
 Global Benzalkonium Chloride Market | 2026-2036
Global Benzalkonium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Benzalkonium Chloride Market Foresight
The benzalkonium chloride supply landscape is rebalancing as pharmaceutical-grade specifications diverge sharply from commodity industrial grades, with purity thresholds and chain-length specificity now determining contract pricing rather than volume alone. Lonza Group anchors its position through captive alkylamine supply chains that sustain margin control across European pharmaceutical accounts. Stepan Company competes in North American sanitization markets with specialized C12-C14 blends that differentiate its portfolio from standard quaternary ammonium offerings. Kao Corporation leverages its integrated fatty alcohol platform in Asia to extend cost advantages in cosmetic-grade production.
Benzalkonium chloride is a quaternary ammonium compound comprising a mixture of alkylbenzyldimethylammonium chlorides with chain lengths typically ranging from C8 to C18, synthesized via quaternization of benzyl chloride with tertiary amines, functioning primarily as a cationic surfactant with broad-spectrum antimicrobial activity against bacteria, fungi, and enveloped viruses. The pharmaceutical grade commands the densest margin pool due to USP-NF monograph compliance burdens and sterility validation requirements, while industrial grades in water treatment applications remain volume-heavy but price-compressed. Liquid formulations dominate disinfectant channels, though powder variants are gaining traction in crop protection formulations where transport economics favor concentrated inputs.
EPA antimicrobial efficacy guidelines, EU REACH biocidal product regulation, and USP-NF monograph standards collectively elevate compliance costs for cross-border suppliers while creating barriers against uncertified entrants. FDA oversight of ophthalmic and parenteral preservative applications further narrows the approved supplier base for pharmaceutical manufacturers. Stakeholders must monitor evolving EPA and ECHA hazard classifications that could trigger reformulation mandates or usage restrictions across key end-use segments.
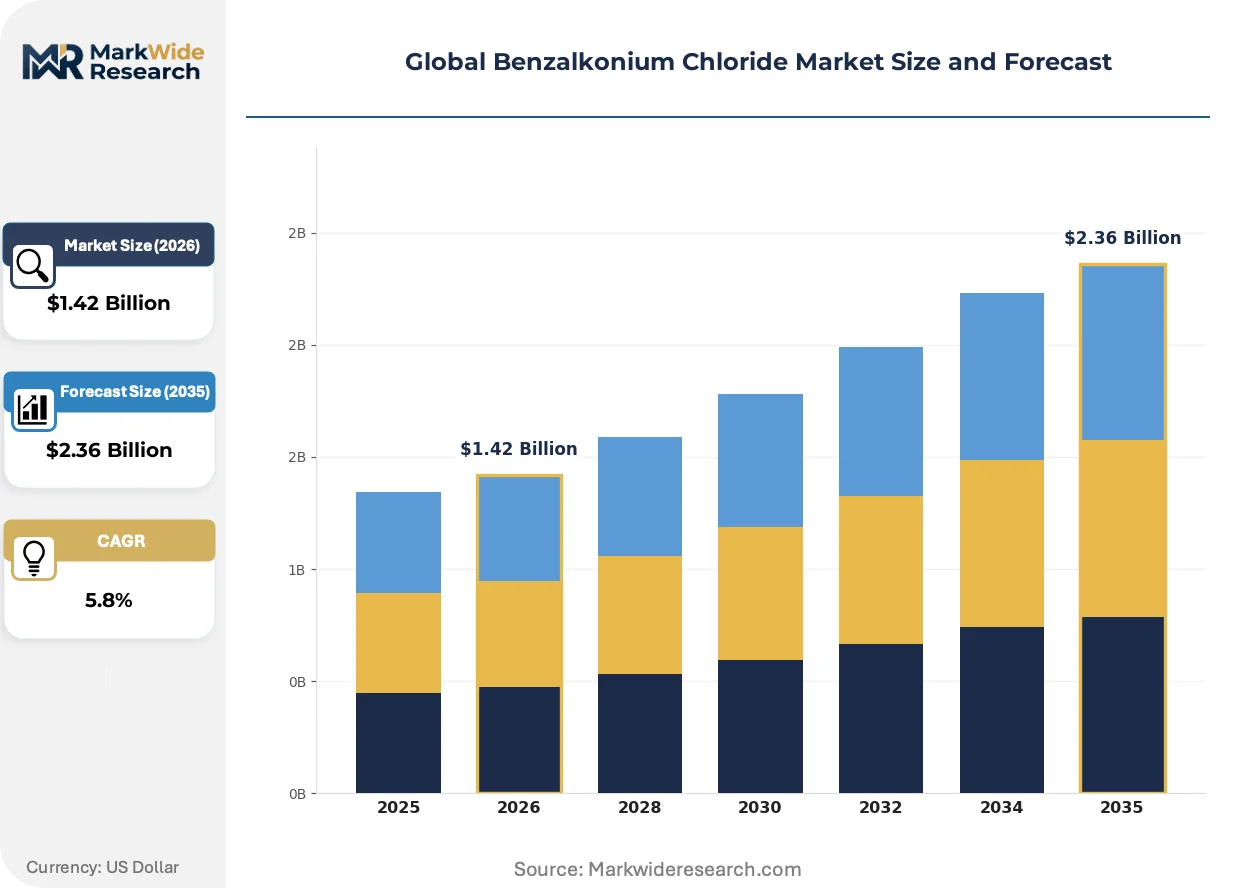
Market Dynamics
EPA's tightened antimicrobial efficacy standards are forcing reformulation across North American hospital disinfectant suppliers, while pharmaceutical-grade purity thresholds are diverging contract pricing from commodity industrial grades.
Growth Catalysts
- Hospital-grade disinfectant protocols:US healthcare systems are mandating enhanced surface disinfection in acute care settings, expanding benzalkonium chloride deployment in EPA-registered hard surface cleaners.
- REACH biocidal product authorization:EU suppliers completing BPR dossier submissions are securing five-year exclusivity windows in professional hygiene channels, locking out non-compliant imports.
- India's pharmaceutical manufacturing corridor:Active pharmaceutical ingredient producers in Gujarat and Telangana are scaling benzalkonium chloride procurement for ophthalmic and parenteral preservative applications.
Market Restraints
- Alkylamine feedstock volatility:Palm kernel oil and coconut oil price swings in Southeast Asia transmit directly to fatty alcohol costs, compressing margins for non-integrated quaternary ammonium compound manufacturers.
- European supply concentration:Lonza Group's captive alkylamine production in Switzerland and Germany limits third-party access to pharmaceutical-grade precursors, constraining new entrant scale-up.
- Alcohol-based sanitizer substitution:Isopropanol and ethanol formulations retain cost advantages in consumer hand hygiene, capping benzalkonium chloride penetration in retail channels.
Strategic Opportunities
- Brazilian agrochemical formulation growth:ANVISA-registered crop protection producers are adopting benzalkonium chloride as a tank-mix adjuvant, creating demand for powder concentrates with favorable transport economics.
- Cosmetic-grade chain-length specificity:C12-C14 optimized blends for leave-on skin applications command premium pricing in Japanese and South Korean personal care markets.
- Dual-use pharmaceutical-industrial licensing:Suppliers securing USP-NF monograph compliance can cross-sell into water treatment applications with minimal incremental validation costs.
Industry Challenges
- Sterility validation timelines:Pharmaceutical manufacturers face 18-24 month USP-NF certification cycles for parenteral preservative applications, delaying revenue recognition.
- Chain-length analytical capability gaps:Gas chromatography expertise for C8-C18 distribution verification remains concentrated in contract laboratories, creating quality control bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Benzalkonium Chloride Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Emulsion, Solution Grade: Pharmaceutical, Industrial, Cosmetic, Agricultural Application: Disinfectants, Preservatives, Sanitizers, Biocides, Surfactants End User: Pharmaceutical Manufacturers, Personal Care Producers, Water Treatment Facilities, Crop Protection Companies |
| Companies Covered | Kao Corporation, Novo Nordisk Pharmatech, Lonza Group, Evonik, Nouryon, Stepan Company, BASF, Merck KGaA, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Benzalkonium Chloride Market Shifts & Advancements
Continuous processing technology and regulatory data requirements are compressing batch cycle times while elevating documentation burdens across the benzalkonium chloride value chain.
Membrane filtration-based purification is decentralizing pharmaceutical-grade production by enabling on-site solvent recovery and reducing dependency on centralized distillation infrastructure. Regional API manufacturers in India and China are adopting skid-mounted systems to bypass toll processing constraints. This distributed model is compressing logistics costs and shortening lead times for sterile-grade shipments.
REACH biocidal product regulation dossier requirements are elevating toxicological study costs for EU market access. Suppliers without existing environmental fate data must commission new aquatic toxicity testing, disproportionately burdening mid-scale manufacturers. Professional hygiene formulators are consolidating supplier relationships to reduce BPR compliance duplication across their portfolios.
Long-term supply agreements with alkylamine producers are displacing spot market purchasing among North American disinfectant manufacturers. Hospital procurement departments are locking in eighteen-month contracts with Stepan Company and Lonza to secure EPA-registered active ingredient supply. This contract densification is visible most acutely in US acute care networks facing Joint Commission audit pressures.
Global Benzalkonium Chloride Market Segmentation
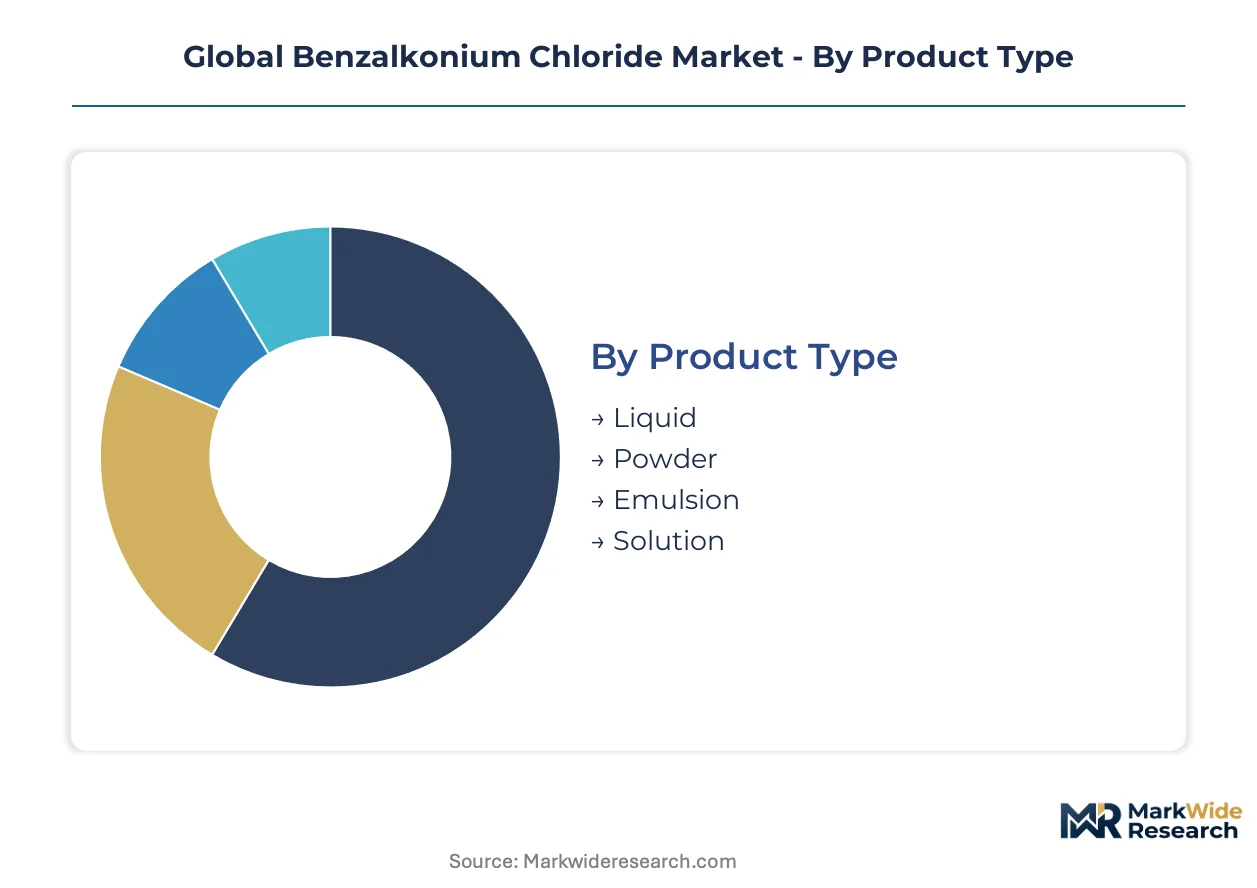
Benzalkonium chloride's formulation diversity creates distinct margin pools across physical states and purity grades. Each segment carries unique regulatory burdens and end-use specifications that reshape supplier economics.
Product Type:
Physical form selection hinges on transport economics and downstream processing requirements, with concentrated formats displacing dilute solutions in long-haul supply chains.
- Liquid:Aqueous solutions at 50-80% concentration serve as the standard feedstock for EPA-registered hospital disinfectants and FDA-regulated ophthalmic formulations. Demand concentrates in US acute care networks where Joint Commission audit protocols mandate validated active ingredient sourcing.
- Powder:Spray-dried concentrates at 95%+ purity enable freight cost savings for Brazilian crop protection formulators and Indian API manufacturers. ANVISA-registered tank-mix adjuvants favor this format for shelf stability.
- Emulsion:Oil-in-water dispersions stabilize C12-C14 optimized blends for leave-on cosmetic applications in Japanese personal care markets.
- Solution:Pre-diluted formulations at 10-20% concentration streamline compounding for mid-scale water treatment operators in Germany.
Volume placements concentrate in Liquid; the faster expansion belongs to Powder.
Grade:
Purity thresholds now determine contract pricing more than volume scale, with USP-NF monograph compliance creating insurmountable barriers for uncertified suppliers.
- Pharmaceutical:USP-NF monograph compliance mandates sterility validation and chain-length specificity for parenteral and ophthalmic preservatives. FDA oversight narrows the approved supplier base to Lonza and select integrated manufacturers.
- Industrial:Standard quaternary ammonium specifications serve water treatment and general surface disinfection with price-compressed, volume-heavy economics.
- Cosmetic:C12-C14 optimized blends command premium pricing in South Korean and Japanese leave-on skin applications where METI cosmetic safety standards apply.
- Agricultural:ANVISA-registered biocidal specifications support Brazilian crop protection formulators adopting tank-mix adjuvant protocols.
Revenue pools peak in Pharmaceutical; Agricultural climbs fastest on Latin American agrochemical expansion.
Application:
End-use functionality dictates regulatory pathway complexity, with human-contact applications carrying disproportionate compliance burdens versus industrial biocidal uses.
- Disinfectants:EPA-registered hard surface cleaners dominate US hospital procurement, with eighteen-month supply contracts locking in Stepan and Lonza volumes.
- Preservatives:Ophthalmic and parenteral applications require 18-24 month USP-NF certification cycles, delaying revenue recognition for new entrants.
- Sanitizers:Hand hygiene formulations face substitution pressure from isopropanol and ethanol in US retail channels.
- Biocides:EU REACH BPR dossier submissions secure five-year exclusivity windows for professional hygiene suppliers.
- Surfactants:Cationic surface activity supports emulsion stabilization in cosmetic and agrochemical formulations.
Contract density peaks in Disinfectants; Preservatives expand on Indian API manufacturing growth.
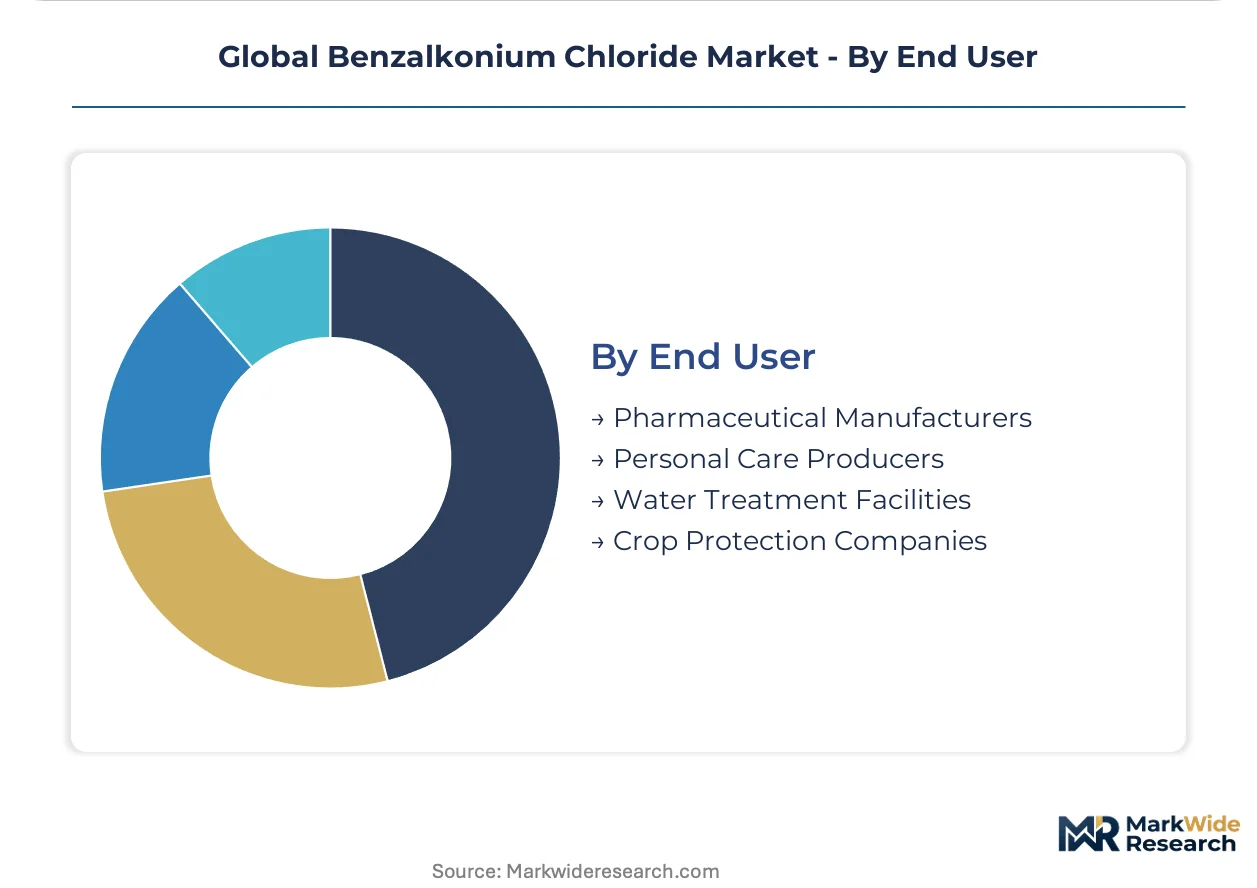
End User:
Customer concentration varies sharply by validation requirements, with pharmaceutical accounts demanding multi-year supplier relationships versus spot purchasing in industrial segments.
- Pharmaceutical Manufacturers:Indian API producers in Gujarat and Telangana scale benzalkonium chloride procurement for ophthalmic and parenteral applications under CDSCO oversight.
- Personal Care Producers:Japanese and South Korean formulators specify C12-C14 chain-length optimized blends for leave-on skin products.
- Water Treatment Facilities:German and US municipal operators favor industrial-grade liquid formulations for algae and biofilm control.
- Crop Protection Companies:Brazilian ANVISA-registered producers adopt powder concentrates for tank-mix adjuvant economics.
Procurement consolidation centers on Pharmaceutical Manufacturers; Crop Protection Companies gain share fastest on Latin American agrochemical growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's pharmaceutical manufacturing corridor anchors procurement intensity for benzalkonium chloride, with API producers clustering around Ahmedabad and Vadodara to serve ophthalmic preservative demand. Regulatory divergence across major economies is fragmenting supplier qualification pathways. Industrial clusters in Switzerland, Germany, and Japan concentrate pharmaceutical-grade production capacity.
United States
EPA-registered hospital disinfectant demand concentrates in acute care networks across Texas, California, and New York. The Agency's tightened antimicrobial efficacy standards are forcing reformulation timelines for hard surface cleaner suppliers. Stepan Company anchors North American supply through specialized C12-C14 blend production.
India
API manufacturers in Telangana and Gujarat scale benzalkonium chloride procurement for parenteral and ophthalmic preservatives. CDSCO oversight mandates sterility validation protocols that extend supplier qualification cycles. Hyderabad's formulation corridor is expanding tank-mix adjuvant adoption for crop protection exports.
Germany
REACH biocidal product regulation dossier submissions dominate professional hygiene channel access across Bavaria and North Rhine-Westphalia. ECHA environmental fate data requirements are elevating toxicological study costs for mid-scale manufacturers. Lonza Group's captive alkylamine production in Switzerland and Germany constrains third-party precursor access.
Japan
Cosmetic-grade C12-C14 optimized blends command premium pricing in Tokyo and Osaka personal care markets. METI cosmetic safety standards apply stringent chain-length specificity for leave-on skin applications. Kao Corporation leverages integrated fatty alcohol platforms to extend cost advantages in premium formulations.
Brazil
ANVISA-registered crop protection producers in São Paulo and Minas Gerais adopt powder concentrates for tank-mix adjuvant economics. Powder variants enable freight cost savings for agrochemical formulators serving Latin American export markets. Regional distributors are consolidating procurement relationships to reduce regulatory compliance duplication.
Global Benzalkonium Chloride Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade and regulatory-certification dimensions. The vendor base stratifies into three tiers: integrated alkylamine producers with captive supply chains, specialized quaternary ammonium compound manufacturers with EPA-registered portfolios, and regional toll processors serving industrial-grade water treatment applications. Two dominant competitive moves are reshaping positioning: backward integration into fatty alcohol feedstocks to control margin erosion from palm kernel oil volatility, and dual-use licensing strategies that cross-sell USP-NF compliant material into industrial channels with minimal incremental validation.
Within the integrated producer tier, Lonza Group, Kao Corporation, and Stepan Company exemplify divergent geographic anchoring strategies. Lonza represents the European pharmaceutical-grade specialist archetype with captive alkylamine production. Kao occupies a position as the Asia-Pacific cosmetic-grade leader leveraging integrated fatty alcohol platforms. Stepan exemplifies the North American disinfectant-focused supplier with EPA-registered active ingredient specialization. These three anchors collectively demonstrate how feedstock control and regulatory certification create defensible margin tiers.
| Leading Market Players |
|---|
| Kao Corporation |
| Novo Nordisk Pharmatech |
| Lonza Group |
| Evonik |
| Nouryon |
| Stepan Company |
| BASF |
| Merck KGaA |
| Solvay SA |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap alkylamine producers in Southeast Asia anchor feedstock supply for benzalkonium chloride manufacturing, translating palm kernel oil cost volatility directly into contract pricing discipline for non-integrated quaternary ammonium compound manufacturers. Their concentrated ownership structures enable long-term offtake negotiations that buffer pharmaceutical-grade buyers from spot market swings while exposing industrial-grade purchasers to sharper price adjustments.
Pricing Analysis
USP-NF monograph compliance anchors value-based pricing for pharmaceutical-grade benzalkonium chloride, with sterility validation and chain-length specificity commanding substantial premiums over standard industrial specifications. Price differentiation separates FDA-approved parenteral preservative grades from commodity water treatment tiers, with certification burden and volume scale as twin drivers. Cost compression in industrial grades is intensifying because alcohol-based sanitizer substitution caps pricing power in consumer channels. Hospital procurement departments exhibit lowest price sensitivity due to Joint Commission audit mandates, while municipal water treatment operators remain most responsive to volume discounts.
Supply Chain Analysis
Freight economics favor powder concentrate formats for long-haul routes serving Brazilian agrochemical formulators and Indian API manufacturers, compressing logistics costs against liquid shipment alternatives. Supply concentrates in Switzerland, Germany, and Japan for pharmaceutical-grade production, with India and China expanding for industrial and agricultural tiers. Raw material dependencies rest on palm kernel oil and coconut oil fatty alcohols from Southeast Asia, benzyl chloride from Chinese petrochemical corridors, and tertiary amine intermediates from European specialty chemical producers. Single-source vulnerability persists in alkylamine precursors where Lonza's captive production limits third-party access. Distribution runs through direct long-term contracts with hospital procurement networks and toll processing arrangements for regional water treatment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA antimicrobial efficacy standards and USP-NF monograph requirements erect formidable barriers against uncertified entrants, entrenching compliant incumbents with validated supply relationships.
For Market Incumbents: Cement pharmaceutical-grade margin pools through captive alkylamine supply chain investments in Switzerland and Germany, insulating against palm kernel oil volatility while locking in Lonza-scale procurement advantages. Deepen EPA-registered active ingredient portfolios to defend against isopropanol and ethanol substitution in North American hospital disinfectant channels. Joint Commission audit pressures sustain contract density for validated suppliers. For New Entrants and Emerging Players: Regional toll processors serving Indian API manufacturers represent the most penetrable entry channel, bypassing 18-24 month USP-NF certification cycles through contract manufacturing arrangements. Target Brazilian ANVISA-registered crop protection formulators adopting powder concentrate tank-mix adjuvants, where regulatory compliance duplication creates white-space for specialized distributors. Skid-mounted membrane filtration systems enable distributed pharmaceutical-grade production without centralized distillation infrastructure. For Investors and Strategic Acquirers: REACH biocidal product regulation dossier submissions securing five-year exclusivity windows are the leading indicator that professional hygiene channel access is consolidating around compliant suppliers with existing environmental fate data. Long-term viability favors integrated producers with backward control over fatty alcohol feedstocks and dual-use licensing capabilities spanning pharmaceutical and industrial grades. Watch for alkylamine supply agreement renegotiations as signals of margin compression or expansion across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Feedstocks | Captive supply of palm kernel oil derivatives insulates margin from Southeast Asia commodity volatility. |
| Dual-Use Pharmaceutical-Industrial Licensing | USP-NF compliance enables cross-selling into water treatment with minimal incremental validation burden. |
| Long-Term Supply Agreement with Hospital Networks | Eighteen-month contracts with US acute care systems lock in EPA-registered active ingredient volumes. |
| Skid-Mounted Membrane Filtration Deployment | On-site solvent recovery decentralizes production for Indian and Chinese API manufacturers. |
| REACH BPR Dossier Completion | Five-year EU exclusivity windows professional hygiene channels against non-compliant import competition. |
Research Methodology
Independent corroboration across plant managers at quaternary ammonium compound facilities, procurement leads at downstream pharmaceutical OEMs, and distribution channel partners underwrites the qualitative findings in this analysis. Primary interviews with technical R&D directors and regulatory affairs specialists were combined with secondary validation from EPA registration databases, USP-NF monograph publications, customs and trade flow records, and SEC filings from disclosed market participants. Bottom-up volume triangulation across grade tiers and end-use applications was cross-checked against top-down market sizing from production capacity assessments.
Rate-of-change decomposition across the analysis window disaggregated growth drivers by product type, grade tier, application functionality, and end-user concentration. Segmentation modeling incorporated pharmaceutical versus industrial purity specifications, liquid versus powder physical formats, and regional regulatory cluster variations. CAGRs were derived from regression analysis of historical shipment data and forward projection of hospital disinfectant procurement trends, API manufacturing expansion in India, and agrochemical formulation growth in Brazil.
Caveats apply where EPA efficacy guideline revisions, ECHA hazard reclassifications, or palm kernel oil supply disruptions could materially shift the outlook for pricing and volume trajectories. Forecasts reflect assumptions about regulatory stability and feedstock cost continuity that may not hold across the projection horizon. Stakeholders should weight assumptions against their own operating context and risk tolerance for certification timeline delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Aluminum Phosphide Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Calcium Borate Market
Chemicals
Etidronic Acid Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Piroctone Olamine Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Hexachloroethane Market
Chemicals
p-Coumaric Acid Market
Chemicals
Deicing Fluid Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Anticoagulant Rodenticides Market