
 PET Scanners Market | 2026-2036
PET Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
PET Scanners Market Intelligence
German engineering houses is broadening the installed base of digital PET platforms across European university hospitals. Siemens Healthineers leverages its detector manufacturing depth to sustain premium positioning in hybrid imaging. GE Healthcare anchors North American service contracts through its predictive analytics infrastructure. Koninklijke Philips N.V. competes on workflow integration, connecting PET scanners to enterprise imaging networks.
Positron emission tomography scanners detect gamma rays emitted by positron-emitting radiopharmaceuticals, typically achieving spatial resolution of 4-5 millimeters with lutetium-based scintillation crystals to map metabolic activity in vivo. These systems serve primarily as diagnostic instruments for cancer staging, neurodegenerative assessment, and myocardial viability evaluation. PET/CT configurations dominate installed value due to their reimbursement advantages and clinical familiarity, while PET/MRI systems capture the fastest expansion in pediatric neurology and prostate imaging where radiation dose reduction matters. Time-of-Flight technology leads new system sales as its signal-to-noise improvements shorten scan durations and lower tracer requirements.
The FDA regulates radiopharmaceutical companion diagnostics and scanner software as medical devices under 21 CFR 892, while the Nuclear Regulatory Commission governs cyclotron and hot lab operations that feed PET scanner utilization. European installations face CE marking under the Medical Device Regulation plus EMA oversight of radiotracer manufacturing that shapes site qualification requirements. Stakeholders must monitor reimbursement volatility for diagnostic radiopharmaceuticals under the Medicare Hospital Outpatient Prospective Payment System, as payment methodology shifts directly influence scanner utilization economics and replacement timing.
Market Dynamics
Digital PET detector technology is compressing scan times while expanding clinical throughput, forcing capital equipment replacement cycles to accelerate across hospital networks. The shift from analog to silicon photomultiplier arrays is redistributing competitive advantage toward semiconductor manufacturing capabilities.
Growth Catalysts
- Oncology Precision Medicine:Tumor-agnostic therapy protocols require molecular imaging biomarkers for patient stratification. Academic medical centers are expanding PET scanner fleets to support basket trial enrollment.
- Medicare Diagnostic Radiopharmaceutical Reimbursement:The Hospital Outpatient Prospective Payment System now bundles tracer costs with technical fees. This policy shift incentivizes higher scanner utilization rates to amortize fixed radiopharmaceutical expenses.
- Time-of-Flight Signal Processing:Lutetium-based scintillation crystals with sub-300 picosecond coincidence timing windows are improving lesion detectability. Siemens Healthineers and GE Healthcare have integrated this architecture into their flagship platforms.
Market Restraints
- Cyclotron Supply Concentration:North American hospitals depend on a limited network of commercial radiopharmaceutical suppliers for fluorodeoxyglucose production. Geographic distance from cyclotron facilities creates cold-chain logistics vulnerabilities.
- Capital Equipment Intensity:PET/CT system prices exceed three million dollars per installation. Community hospitals face debt financing constraints that delay replacement of aging gamma camera infrastructure.
- Regulatory Divergence:The FDA's 21st Century Cures Act breakthrough device pathway accelerates scanner software approvals, while the Nuclear Regulatory Commission maintains stringent hot lab licensing requirements. This bifurcation creates compliance complexity for multi-site health systems.
Strategic Opportunities
- Pediatric Neurology PET/MRI:Radiation dose reduction protocols favor hybrid magnetic resonance integration over CT-based configurations. Children's hospitals represent an underpenetrated installation base with distinct procurement criteria.
- India Diagnostic Infrastructure:The country's PLI scheme for medical device manufacturing is attracting component assembly investments. Domestic production of scintillation crystals could reduce import dependence for South Asian hospital networks.
- AI-Enabled Quantitative Imaging:Deep learning algorithms for standardized uptake value quantification are converging with scanner hardware. This technology pairing enables remote diagnostic support for rural imaging centers lacking specialized nuclear medicine physicians.
Industry Challenges
- Cyclotron Engineer Shortage:Radiopharmaceutical production facilities require certified nuclear pharmacists and cyclotron operators. Training pipeline gaps constrain expansion of regional tracer distribution networks.
- Legacy PACS Integration:Digital PET platforms must interface with hospital enterprise imaging archives built for CT and MRI DICOM standards. Vendor-neutral archive compatibility adds implementation timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Scanners Market |
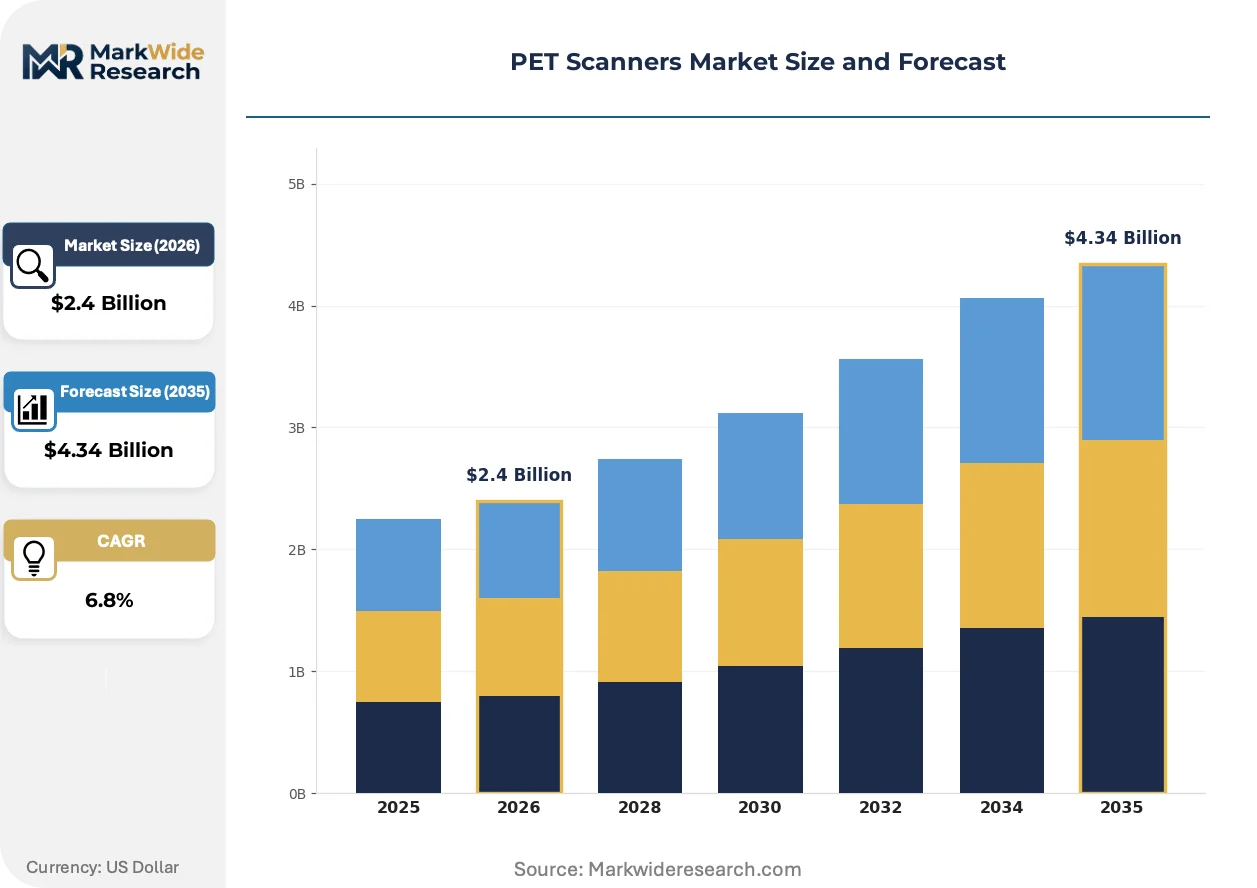
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dedicated PET, PET/CT, PET/MRI, Mobile PET End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Cancer Treatment Centers Technology: Time-of-Flight, Anger Camera, Scintillation Detector, Solid State Detector Application: Oncology, Neurology, Cardiology, Infectious Diseases |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems, United Imaging Healthcare, Mediso Ltd., Positron Corporation, Shimadzu Corporation, Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Scanners Market Strategic Shifts & Innovations
Artificial intelligence is penetrating every layer of PET scanner operation from acquisition protocols to radiopharmaceutical dosing algorithms. These computational advances are compressing the gap between hardware performance and clinical interpretation speed.
Deep learning-based attenuation correction is automating the elimination of CT-based density maps from PET/MRI acquisitions. Pediatric neurology departments at university hospitals are adopting this approach to remove ionizing radiation from brain metabolism studies. The technology is automating the standardization of quantitative biomarker extraction across multi-center clinical trials.
The EU Medical Device Regulation's Class IIa classification for PET reconstruction software is extending conformity assessment timelines. Manufacturers must now submit clinical evidence for algorithm-assisted diagnostic outputs. European university hospitals are delaying procurement decisions until notified body certifications clarify liability boundaries for AI-augmented interpretations.
Hospital procurement departments are consolidating imaging equipment purchasing through multi-year managed equipment service agreements. Independent imaging centers are losing access to competitive financing as manufacturers prioritize health system partnerships. This concentration is most visible in the United States, where integrated delivery networks now control over half of new PET scanner installations.
PET Scanners Market Segmentation
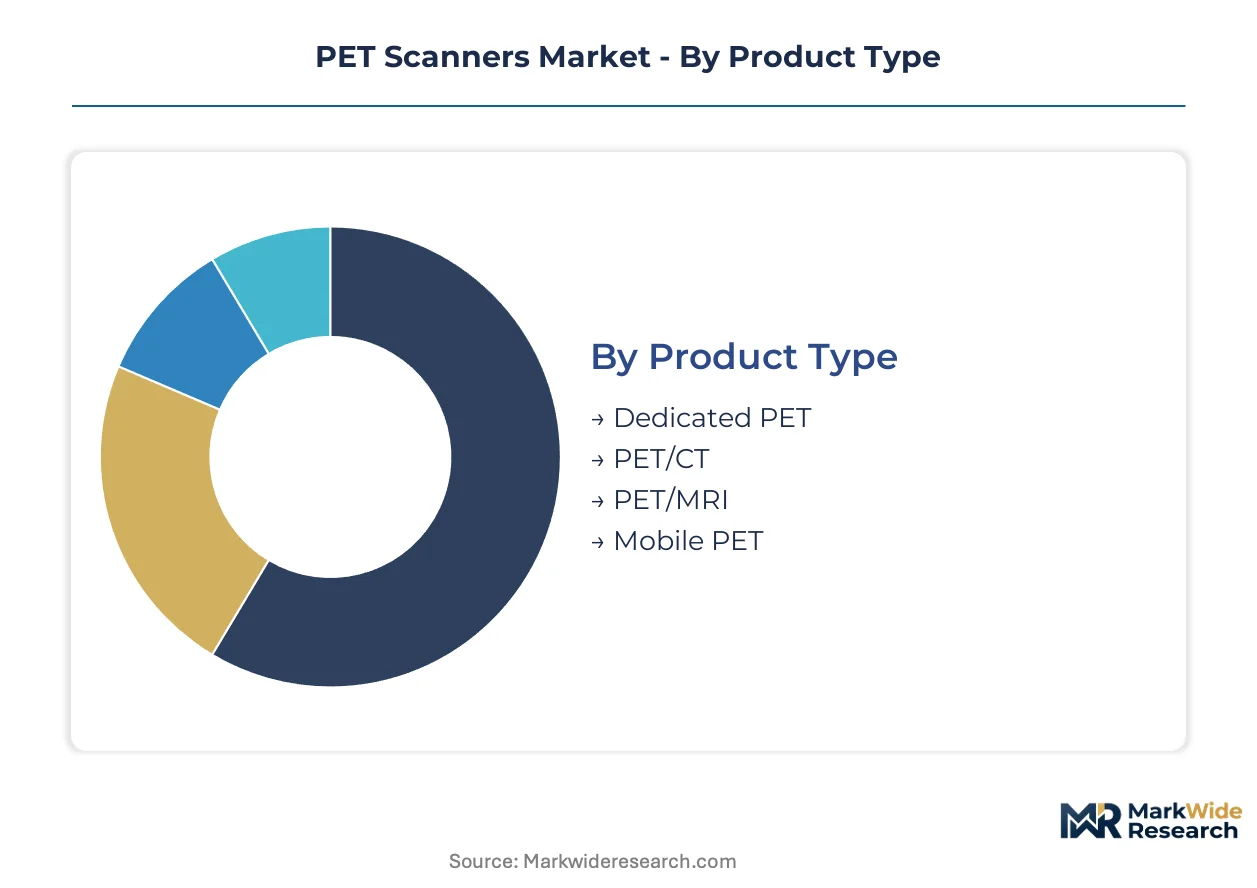
PET scanner procurement patterns diverge sharply between integrated hybrid systems and standalone configurations, with reimbursement economics and clinical workflow demands driving distinct buyer behaviors across hospital networks. Understanding these segment boundaries clarifies how capital allocation priorities shift between academic medical centers and community imaging providers.
Product Type:
Standalone PET systems serve discrete diagnostic niches while hybrid architectures dominate high-throughput hospital environments where space constraints and reimbursement bundling favor multifunctional platforms.
- PET/CT:Dual-modality systems combine metabolic imaging with anatomical localization through integrated gantries sharing a common patient table. United States hospital networks concentrate procurement here due to Medicare reimbursement advantages for fused imaging studies under the Hospital Outpatient Prospective Payment System.
- PET/MRI:Hybrid magnetic resonance configurations eliminate ionizing radiation from the anatomical component, enabling pediatric neurology protocols and serial prostate imaging where cumulative dose concerns constrain CT-based alternatives. Children's hospitals and academic research centers drive installations.
- Dedicated PET:Standalone positron emission systems without anatomical correlation capability occupy budget-constrained community settings and mobile service fleets.
- Mobile PET:Trailer-mounted systems extend scanner access to rural hospitals lacking fixed cyclotron infrastructure or sufficient patient volume for capital justification.
Volume placements concentrate in PET/CT configurations; the faster expansion belongs to PET/MRI systems.
End User:
Procurement authority and financing mechanisms fragment across institutional types, with integrated delivery networks consolidating purchasing power while independent imaging centers face capital access constraints.
- Hospitals:Academic medical centers anchor fleet expansion for precision medicine trials, while community hospitals delay replacement cycles amid debt financing pressures. Siemens Healthineers and GE Healthcare prioritize multi-year managed equipment service agreements with these integrated networks.
- Diagnostic Imaging Centers:Independent outpatient facilities concentrate on high-utilization PET/CT platforms for oncology staging, constrained by limited access to competitive manufacturer financing relative to health system partnerships.
- Research Institutions:University hospitals and national laboratories drive PET/MRI adoption for neurodegenerative biomarker studies and radiopharmaceutical development protocols.
- Cancer Treatment Centers:Dedicated oncology facilities prioritize throughput-optimized Time-of-Flight systems for therapeutic monitoring and clinical trial enrollment.
Capital deployment clusters at academic medical centers; independent imaging centers face narrowing financing access.
Technology:
Detector architecture evolution is redistributing competitive advantage toward semiconductor manufacturing capabilities as silicon photomultiplier arrays displace legacy photomultiplier tube designs.
- Time-of-Flight:Sub-300 picosecond coincidence timing windows improve signal-to-noise ratios, shortening scan durations and reducing radiopharmaceutical dose requirements. Siemens Healthineers and GE Healthcare have integrated this architecture into flagship platforms serving high-volume United States hospital networks.
- Scintillation Detector:Lutetium-based crystal arrays remain the dominant signal conversion technology, with lutetium-yttrium oxyorthosilicate and lutetium fine silicate compositions balancing light output and decay time constants.
- Anger Camera:Legacy analog positioning electronics persist in refurbished systems and developing market installations where capital constraints outweigh performance requirements.
- Solid State Detector:Direct conversion semiconductors promise improved energy resolution but face manufacturing scale challenges for large-area detector panels.
New system sales gravitate toward Time-of-Flight architectures; Anger Camera technology persists in secondary markets.
Application:
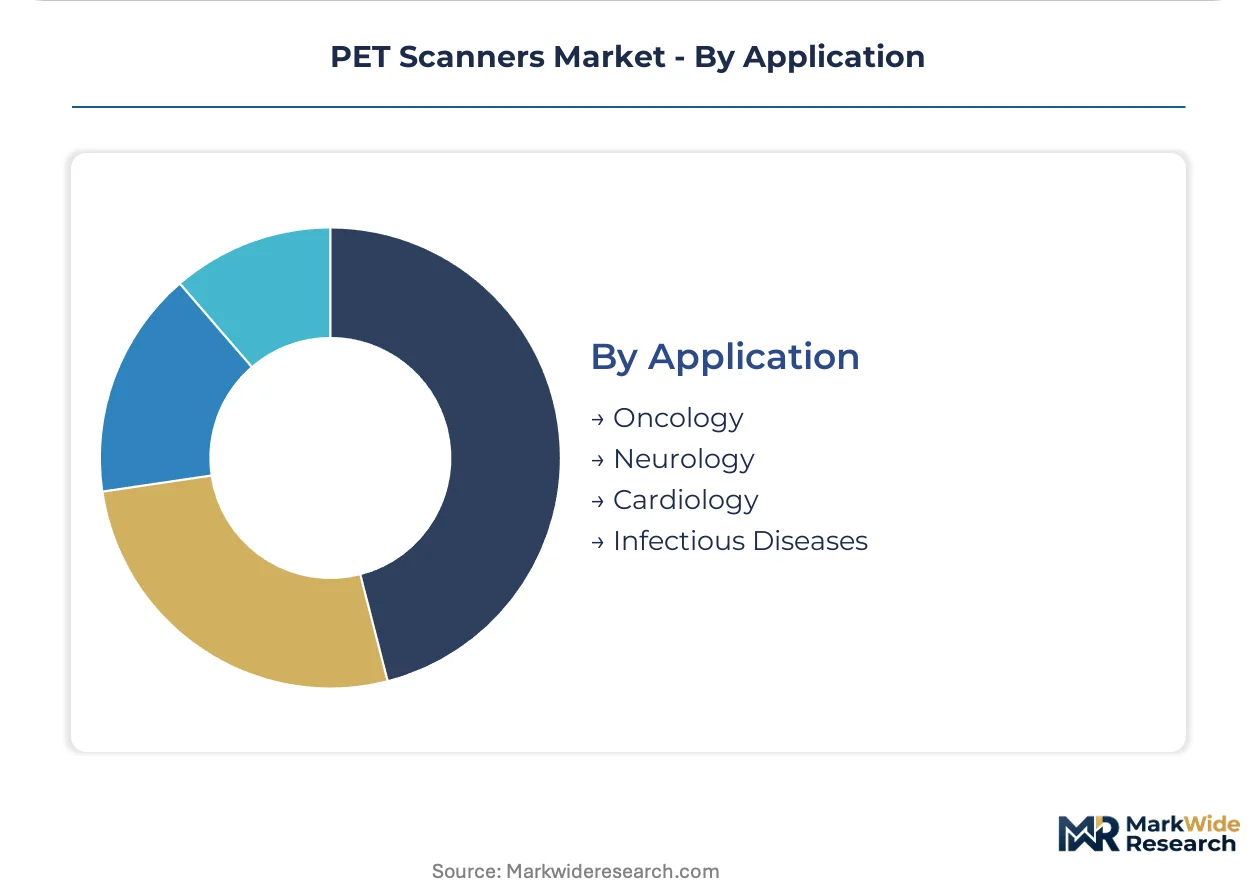
Clinical demand concentrates where molecular imaging biomarkers directly influence therapeutic decision-making, with oncology protocols generating the majority of scanner utilization hours.
- Oncology:Tumor staging, restaging, and treatment response assessment consume the preponderance of scanner capacity across hospital networks. FDG-PET dominates, with novel radiopharmaceuticals expanding into prostate-specific membrane antigen and somatostatin receptor targeting.
- Neurology:Amyloid and tau imaging for Alzheimer's disease diagnosis drives PET/MRI installations at memory disorder centers, with FDA-approved radiotracers enabling reimbursement for cognitive impairment workups.
- Cardiology:Myocardial viability assessment and sarcoidosis evaluation represent niche applications, constrained by competing functional imaging modalities and limited procedure reimbursement.
- Infectious Diseases:FDG-PET localizes occult infection and monitors therapeutic response in immunocompromised patients, though clinical adoption remains below oncology and neurology penetration.
Scanner utilization hours concentrate in oncology; neurology biomarker imaging climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lutetium mining and processing capacity concentrates in China and the United States, anchoring detector crystal supply chains for digital PET platforms across hospital networks worldwide.
United States
Medicare reimbursement for diagnostic radiopharmaceuticals under the Hospital Outpatient Prospective Payment System drives scanner procurement cycles at academic medical centers. The FDA's 21st Century Cures Act breakthrough device pathway accelerates software approvals for next-generation digital systems. The Boston-Cambridge corridor anchors precision medicine trial enrollment, expanding PET fleet deployments for oncology biomarker studies.
Germany
University hospitals in Bavaria and Baden-Württemberg lead European adoption of PET/MRI configurations for neurodegenerative research protocols. The EU Medical Device Regulation's Class IIa classification for reconstruction software extends conformity assessment timelines for manufacturers. Siemens Healthineers leverages detector manufacturing depth from its Erlangen headquarters to sustain premium positioning across German hospital networks.
China
Domestic production of lutetium-based scintillation crystals under the NMPA medical device registration pathway reduces import dependence for South Asian hospital networks. The country's dual carbon goals pressure manufacturers to improve energy efficiency in cyclotron operations. Shanghai and Beijing anchor radiopharmaceutical manufacturing clusters serving tier-one city hospital procurement.
Japan
Aging demographics and amyloid imaging reimbursement for Alzheimer's diagnosis expand PET scanner utilization at memory disorder centers. The PMDA oversees radiopharmaceutical companion diagnostics alongside METI industrial policy supporting domestic manufacturing. The Kansai region around Osaka concentrates refurbished system exports to Southeast Asian markets.
India
The PLI scheme for medical device manufacturing attracts component assembly investments for detector modules and gantry systems. CDSCO regulatory harmonization with IMDRF standards accelerates import substitution for digital PET platforms. Maharashtra and Karnataka host emerging installation bases at private hospital chains expanding nuclear medicine departments.
PET Scanners Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue hybrid imaging specialization and AI-enabled workflow integration. The vendor base concentrates around three strategic archetypes: diversified imaging conglomerates with cyclotron-to-scanner vertical control, mid-scale specialists in pediatric and research configurations, and regional assemblers leveraging domestic content requirements. Competitive moves center on multi-year managed equipment service agreements with integrated delivery networks and semiconductor manufacturing partnerships for silicon photomultiplier sourcing.
Among diversified imaging conglomerates, Siemens Healthineers and GE Healthcare exemplify the detector-manufacturing-depth archetype, while Koninklijke Philips N.V. occupies a position emphasizing workflow integration with enterprise imaging networks. These three anchors represent distinct strategic vectors: semiconductor manufacturing capabilities, predictive analytics infrastructure, and software-centric connectivity platforms.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| United Imaging Healthcare |
| Mediso Ltd. |
| Positron Corporation |
| Shimadzu Corporation |
| Hitachi Ltd. |
| Others |
Cost & Logistics Intelligence
Captive cyclotron-to-scanner vertical integration by Siemens Healthineers and GE Healthcare anchors premium pricing power through radiopharmaceutical supply control, while unbundled service contracts expose independent imaging centers to cost volatility across North American hospital networks.
Pricing Analysis
Multi-year managed equipment service agreements bundle preventive maintenance, software updates, and cyclotron supply guarantees into premium-tier contracts, while basic hardware-only purchases occupy the economy tier without radiopharmaceutical logistics support. Price differentiation separates FDA breakthrough-designated Time-of-Flight systems from refurbished Anger Camera platforms on detector performance and reimbursement eligibility. Cost compression in the mid-tier intensifies as semiconductor manufacturing partnerships reduce silicon photomultiplier array costs. Community hospitals exhibit the highest price sensitivity due to debt financing constraints, whereas academic medical centers prioritize throughput metrics over acquisition cost.
Supply Chain Analysis
India's PLI scheme for medical device manufacturing and China's NMPA domestic-content requirements are reshaping sourcing patterns for detector modules and gantry assemblies across Asian hospital procurement. Lutetium mining concentrates in China and the United States, with scintillation crystal fabrication drawing from German and Japanese precision optics capabilities. Single-source vulnerability pervades the commercial radiopharmaceutical network, where geographic distance from cyclotron facilities creates cold-chain logistics exposure. Distribution runs through manufacturer-direct sales teams for integrated delivery networks and third-party leasing brokers for independent imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET scanners market functions as a vertical-integration race where radiopharmaceutical supply control and semiconductor manufacturing capabilities determine sustainable margin structures.
For Market Incumbents: Anchor service contract renewal rates through predictive analytics infrastructure that locks hospital networks into multi-year managed equipment service agreements. Deepen cyclotron network partnerships to defend against emerging entrants with AI-enabled workflow software. Prioritize silicon photomultiplier manufacturing scale-up to offset detector cost compression. For New Entrants and Emerging Players: The price-point gap between premium Time-of-Flight systems and economy-tier refurbished platforms creates entry space for mid-range digital PET configurations with modular upgrade paths. Target pediatric neurology departments at children's hospitals where PET/MRI radiation dose protocols favor specialized hybrid configurations over generic oncology platforms. Pursue software-centric go-to-market positioning emphasizing AI-enabled quantitative imaging for rural imaging centers lacking nuclear medicine physician coverage. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified imaging conglomerates seeking semiconductor manufacturing depth or radiopharmaceutical vertical control. Long-term viability favors vendors with cyclotron-to-scanner integration and recurring service revenue streams exceeding fifty percent of total revenue. Monitor FDA breakthrough device designation velocity as an inflection indicator for next-generation digital PET platform adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Partnership | Secures radiopharmaceutical supply control under Medicare bundling pressures. |
| Silicon Photomultiplier Manufacturing Scale-Up | Reduces detector costs and accelerates digital PET platform replacement cycles. |
| AI-Enabled Quantitative Imaging Development | Enables remote diagnostic support for rural imaging centers lacking specialized physicians. |
| PET/MRI Pediatric Configuration Specialization | Captures fastest-expanding segment in children's hospitals prioritizing radiation dose reduction. |
| Managed Equipment Service Agreement Expansion | Locks integrated delivery networks into multi-year recurring revenue streams. |
Research Approach
Independent corroboration across hospital procurement committees, biomedical engineers, GPO contracts managers, and nuclear medicine physicians underwrites the qualitative findings on scanner replacement timing and financing constraints. Primary interviews with cyclotron operators and radiopharmaceutical manufacturing executives combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital capital expenditure disclosures established demand-side parameters. Bottom-up installation tracking and top-down manufacturer revenue triangulation anchored market sizing across product configurations.
Comparable-period analysis anchored the forecast window to historical replacement cycles observed through Medicare claims data and hospital capital budget cycles. The analytical framework segmented by product type, end user, detector technology, and clinical application across the projection horizon. CAGRs derived from logistic diffusion modeling of digital PET adoption curves and price elasticity estimates for bundled service contracts. Inputs included semiconductor manufacturing capacity expansion timelines and radiopharmaceutical reimbursement policy trajectories under the Hospital Outpatient Prospective Payment System.
Inputs from hospital procurement databases and manufacturer service contract disclosures were available through the study window; gaps in independent imaging center financing terms introduce uncertainty bands around community hospital replacement timing assumptions. Forecasts reflect documented assumptions regarding Medicare bundling policy stability and cyclotron network expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Phosphor Plate Scanners Market
Imaging
Thermal Camera Market
Imaging
Camera Technology Market
Imaging
IR Camera Market
Imaging
IP Camera Market
Imaging
Computational Photography Market
Imaging
Global Microscopy Market
Imaging
Fiducial Markers Market
Imaging
Digital Camera Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Handheld Retinal Scanners Market
Imaging
Semiconductor Microscopes Market
Imaging
Global Mobile Image Sensor Market
Imaging
SWIR Camera Market
Imaging
Global Image Processing Systems Market
Imaging
X Ray Tubes Market