
 Europe Proximity Sensors Market | 2026-2036
Europe Proximity Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Proximity Sensors Market Foresight
REACH compliance is decoupling low-cost Asian suppliers from European industrial procurement channels. Sick AG leverages in-house photoelectric manufacturing to sustain margins amid certification costs. Pepperl+Fuchs GmbH anchors its position through channel control across German automotive Tier-1 networks. Infineon Technologies AG differentiates via R&D intensity in smart sensor integration for Industry 4.0 deployments.
Proximity sensors detect object presence without physical contact, typically operating via inductive, capacitive, photoelectric, or ultrasonic principles with detection ranges from millimeters to several meters and response times under one millisecond; they serve primarily as automation triggers in manufacturing safety systems and quality control loops. Inductive sensors dominate metal-detection applications in automotive welding lines, while photoelectric variants capture the fastest expansion in packaging and logistics conveyor systems. Smart sensors with embedded digital processing command premium positioning as OEMs prioritize predictive maintenance capabilities over basic switching functions.
EMA medical device standards, CE marking machinery directives, and RoHS substance restrictions collectively shape product design rules and market access conditions across European member states. The EU AI Act is extending compliance obligations to sensor networks with embedded decision-making algorithms, particularly in healthcare and autonomous manufacturing contexts. Stakeholders must monitor how ECHA substance candidate list updates affect inductive coil coatings and housing polymers before reformulation cycles accelerate.
Market Dynamics
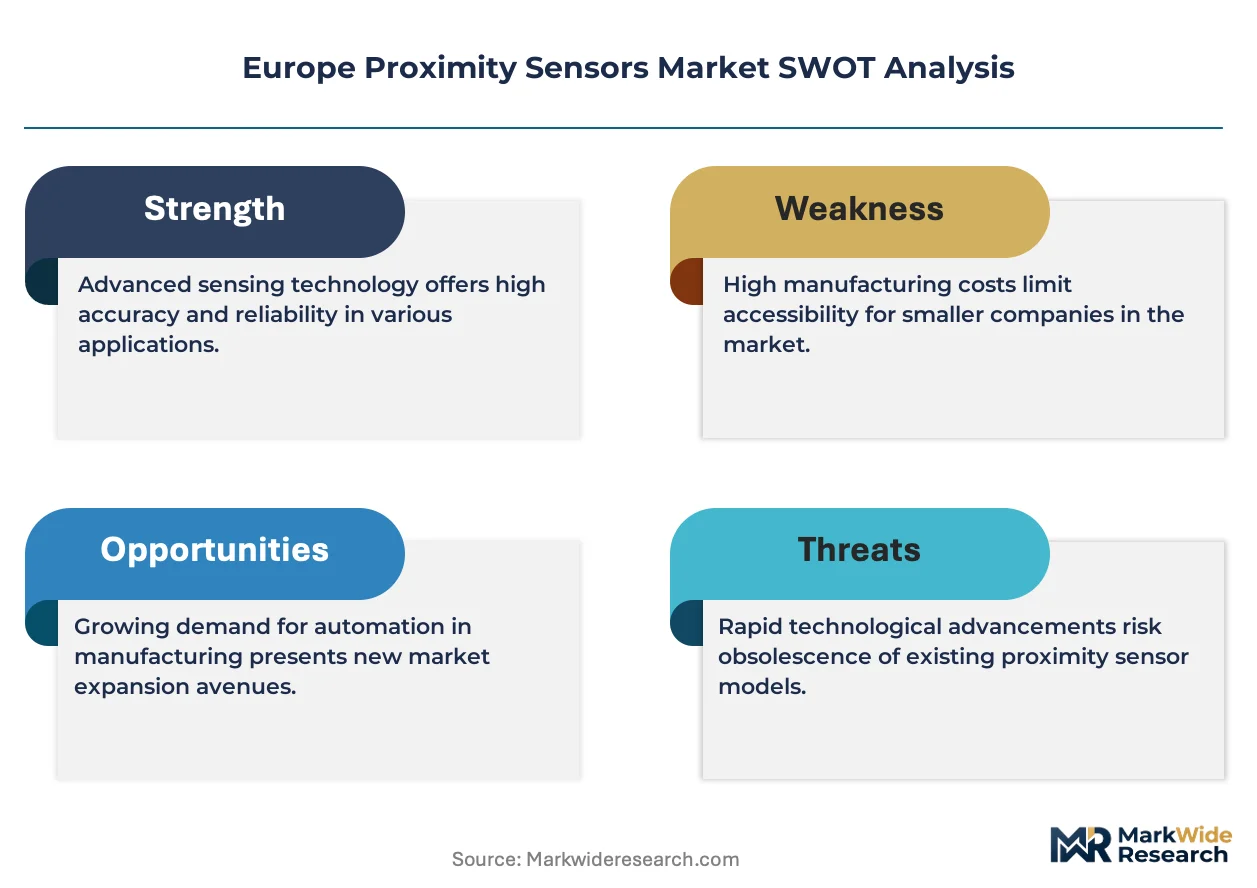
EU Green Deal decarbonization mandates are forcing automotive and industrial OEMs to reshore sensor procurement from carbon-intensive Asian supply chains toward European-certified manufacturers, compressing supplier qualification timelines and amplifying regional production capacity investments.
Growth Catalysts
- REACH substance restrictions:European chemical safety rules are excluding non-compliant Asian suppliers from industrial procurement channels, creating protected demand pools for certified domestic producers serving German automotive welding lines.
- Electric powertrain assembly expansion:German OEMs are scaling inductive sensor deployment for battery module positioning and motor assembly verification, generating concentrated demand in Bavaria and Baden-Württemberg manufacturing corridors.
- Industry 4.0 predictive maintenance:Smart sensors with embedded edge computing are commanding premium positioning as French and Italian aerospace manufacturers prioritize downtime reduction over basic switching functionality.
Market Restraints
- Copper and rare earth price volatility:Inductive coil windings depend on copper cathode and neodymium magnet inputs subject to commodity exchange fluctuations, squeezing margin stability for mid-tier sensor fabricators.
- Photoelectric component supply concentration:High-performance LED emitters and photodiode receivers concentrate in Taiwanese and South Korean foundries, exposing European assemblers to geopolitical transit risks and extended lead times.
- EU AI Act algorithmic compliance:Sensor networks with embedded decision-making capabilities face expanded documentation and conformity assessment obligations, particularly in healthcare and autonomous manufacturing contexts.
Strategic Opportunities
- Polish and Romanian industrial automation:Eastern European manufacturing clusters remain underpenetrated for smart proximity sensing, offering first-mover positioning for vendors establishing localized technical service presence.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive components are incentivizing European sensor reshoring, creating captive demand for domestic inductive and capacitive sensor production.
- Photoelectric-ultrasonic sensor fusion:Hybrid detection systems combining optical precision with acoustic ranging are opening specification wins in food packaging and pharmaceutical cleanroom applications where single-technology sensors fail.
Industry Challenges
- Embedded firmware engineering scarcity:Smart sensor development requires rare combinations of analog circuit design and machine learning optimization expertise, constraining product roadmap velocity for mid-cap specialists.
- CE marking machinery directive recertification:Updated safety integrity requirements for collaborative robotics are forcing sensor manufacturers through extended third-party assessment cycles before market re-entry.
- Legacy PLC integration complexity:Brownfield manufacturing facilities running proprietary industrial Ethernet protocols demand custom gateway development, fragmenting engineering resources across incompatible customer environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Proximity Sensors Market |
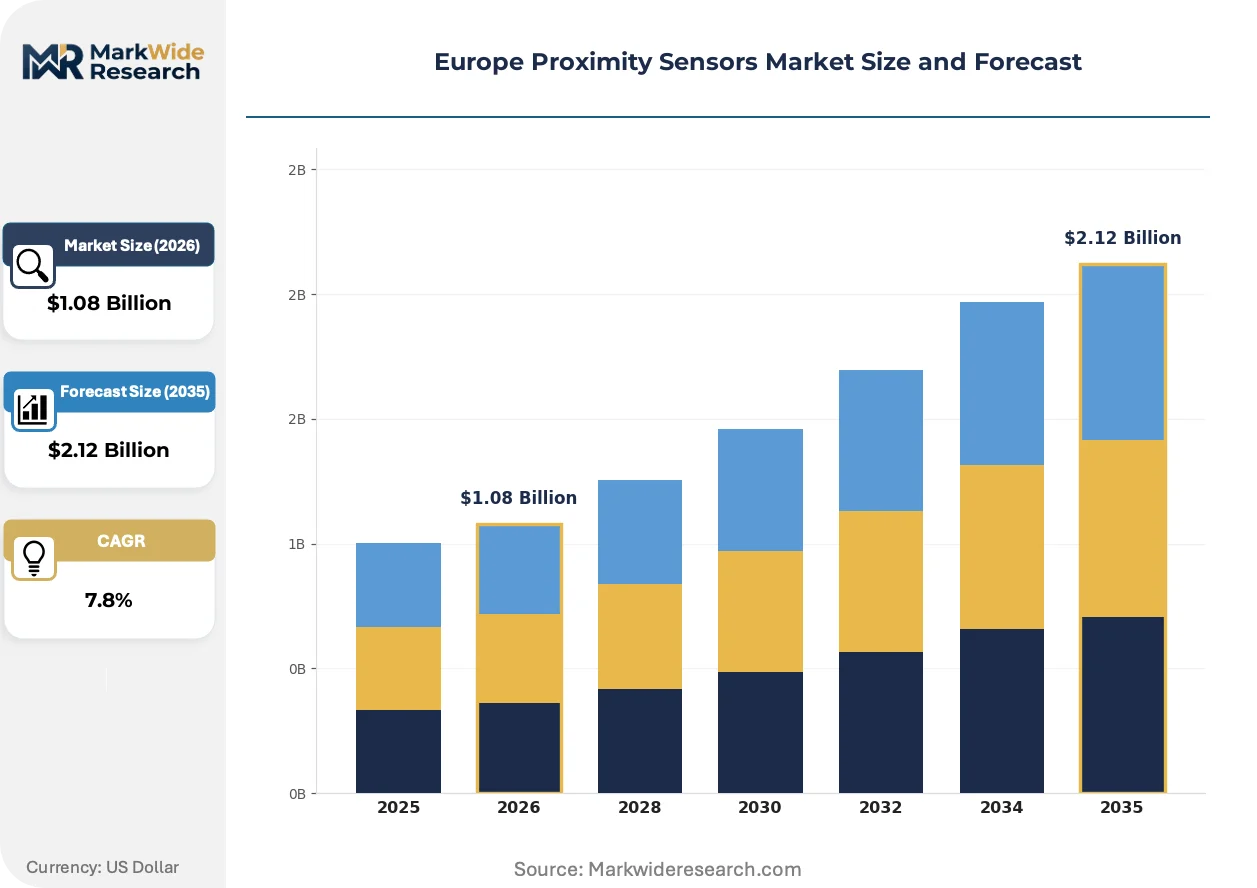
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inductive Sensors, Capacitive Sensors, Photoelectric Sensors, Ultrasonic Sensors Technology: Analog, Digital, Smart Sensors, Networking End User: Automotive, Manufacturing, Consumer Electronics, Healthcare Installation: Fixed Mount, Adjustable Mount, Flush Mount, Surface Mount |
| Companies Covered | Sick AG, STMicroelectronics, TE Connectivity, Pepperl+Fuchs GmbH, Infineon Technologies AG, NXP Semiconductors, Omron Corporation, Balluff GmbH, ifm electronic GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Proximity Sensors Market Shifts & Advancements
Photoelectric sensing architectures are converging with embedded AI inference, while regulatory pressure on supply chain carbon intensity accelerates regional manufacturing consolidation. These forces are compressing product lifecycles and elevating service-based revenue models.
Time-of-flight photoelectric sensors are integrating millimeter-wave radar co-processing to eliminate false triggers in high-dust metalworking environments. German automotive Tier-1 suppliers are specifying these hybrid units for welding robot collision avoidance, where single-technology sensors generate unacceptable downtime. The convergence is integrating predictive maintenance capabilities directly into the sensing layer, bypassing separate edge gateway investments.
EU AI Act algorithmic transparency mandates are extending conformity assessment obligations to sensor networks with embedded classification logic. Industrial machinery OEMs must now document decision pathways for safety-critical proximity triggers in collaborative robotics deployments. French and Italian aerospace precision manufacturers face the steepest compliance burden, as their quality systems already demand full sensor traceability for AS9100 certification maintenance.
Sensor-as-a-service contracting is displacing capital equipment purchases among mid-sized packaging OEMs in Spain and Portugal. Per-detection pricing models bundle hardware, calibration, and predictive analytics, transferring obsolescence risk from plant operators to sensor vendors. Iberian food and beverage conveyor system builders are piloting these arrangements most aggressively, motivated by compressed capital allocation cycles and uncertain production volume forecasts.
Europe Proximity Sensors Market Segmentation
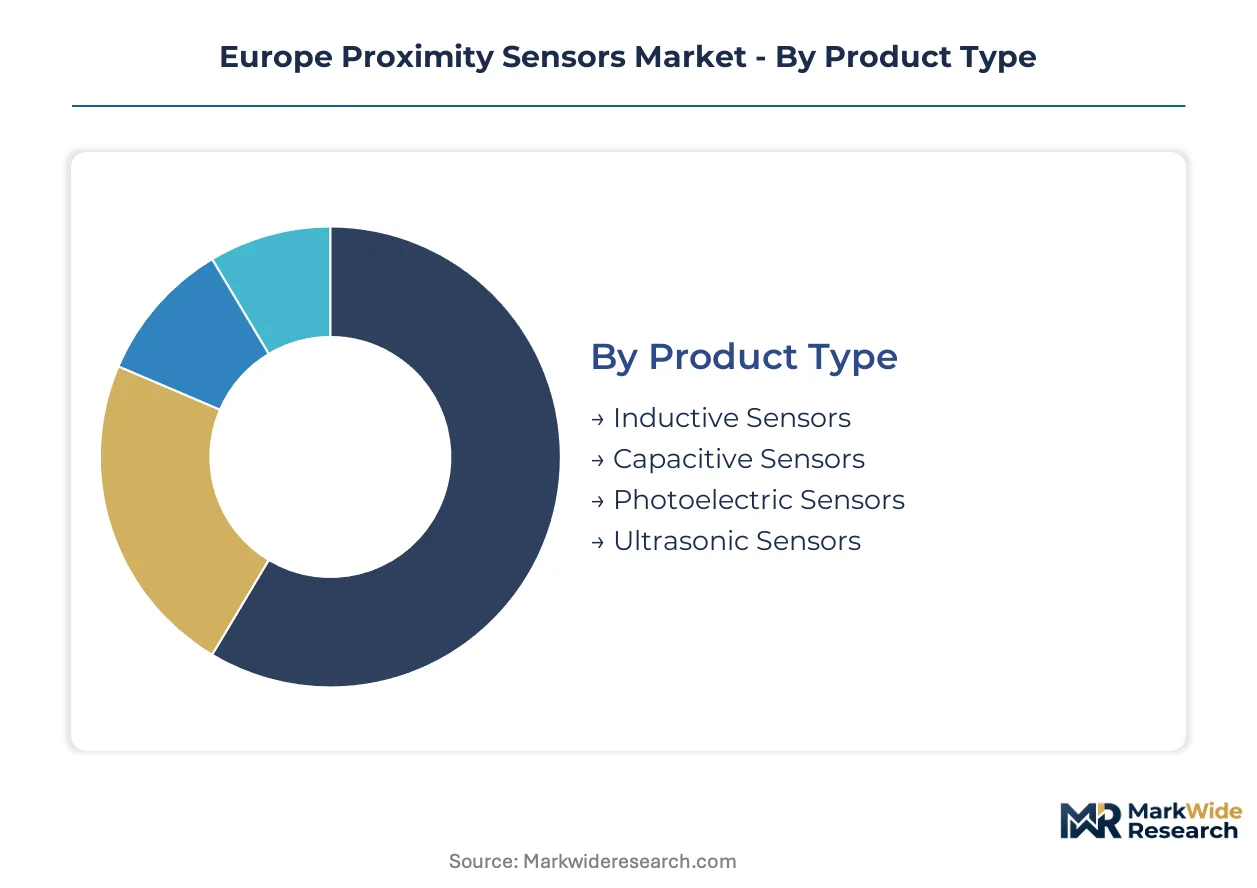
Proximity sensor segmentation in Europe reflects divergent technical requirements across automotive welding lines, aerospace precision cells, and packaging automation. Specification choices determine compliance pathways under REACH substance rules and CE machinery directives.
Product Type:
Detection principles align with target material properties and environmental conditions, shaping procurement specifications across German automotive corridors and French aerospace clusters.
- Inductive Sensors:Electromagnetic field disruption detects ferrous and non-ferrous metals without physical contact. German OEMs specify these for battery module positioning in Bavarian electric powertrain assembly lines, where weld spatter immunity outweighs range limitations. REACH-compliant coil coatings from domestic suppliers protect margins against Asian import restrictions.
- Photoelectric Sensors:Light beam interruption or reflection enables non-metallic detection at extended ranges. French and Italian aerospace manufacturers deploy these for precision component verification, driven by Industry 4.0 predictive maintenance integration and downtime reduction mandates.
- Capacitive Sensors:Detects metallic and non-metallic targets through dielectric constant variation. Deployed in pharmaceutical cleanrooms where liquid level sensing and powder detection are required.
- Ultrasonic Sensors:Acoustic pulse time-of-flight measurement operates independent of target color or transparency. Food packaging lines in Spain and Portugal specify these for transparent film and liquid detection where optical methods fail.
Mature deployment sits with inductive sensors in automotive metalworking. Newer deployment is concentrated in photoelectric variants for logistics and packaging conveyor systems.
Technology:
Signal processing architectures determine integration complexity with legacy PLC networks and edge computing infrastructure.
- Smart Sensors:Embedded microprocessors enable local data preprocessing and predictive maintenance algorithms. German Tier-1 automotive suppliers prioritize these for welding robot collision avoidance, transferring analytics from separate gateway hardware into the sensing layer. EU AI Act documentation obligations apply to embedded decision pathways.
- Digital:Discrete on/off output with standardized communication protocols. Polish and Romanian industrial automation clusters favor these for brownfield PLC integration where analog infrastructure is absent.
- Analog:Continuous voltage or current output proportional to target distance. Legacy machinery in Italian manufacturing corridors retains these for proportional control loops.
- Networking:Industrial Ethernet and fieldbus integration for distributed sensor architectures. Aerospace precision manufacturers in France specify these for full traceability under AS9100 quality systems.
Volume concentration rests with digital output variants in cost-sensitive Eastern European installations. Premium positioning accrues to smart sensors commanding predictive maintenance contracts.
End User:
Application environments dictate housing specifications, response time requirements, and certification burdens under sector-specific directives.
- Automotive:Welding line proximity triggers and powertrain assembly verification dominate German demand in Baden-Württemberg and Bavaria. EU Green Deal reshoring incentives concentrate procurement with European-certified manufacturers.
- Manufacturing:General automation spans metalworking, packaging, and material handling across diversified European industrial bases. Sensor-as-a-service contracting is displacing capital purchases among Iberian mid-sized OEMs.
- Healthcare:EMA medical device standards and MDR conformity assessment govern surgical robot positioning and diagnostic equipment. Embedded AI triggers face expanded EU AI Act algorithmic transparency obligations.
- Consumer Electronics:Miniaturized proximity detection for smartphones and wearables. Assembly lines in Eastern Europe handle contract manufacturing with RoHS substance restrictions.
Procurement value concentrates in automotive Tier-1 networks. Fastest specification evolution occurs in healthcare as surgical robotics expand.
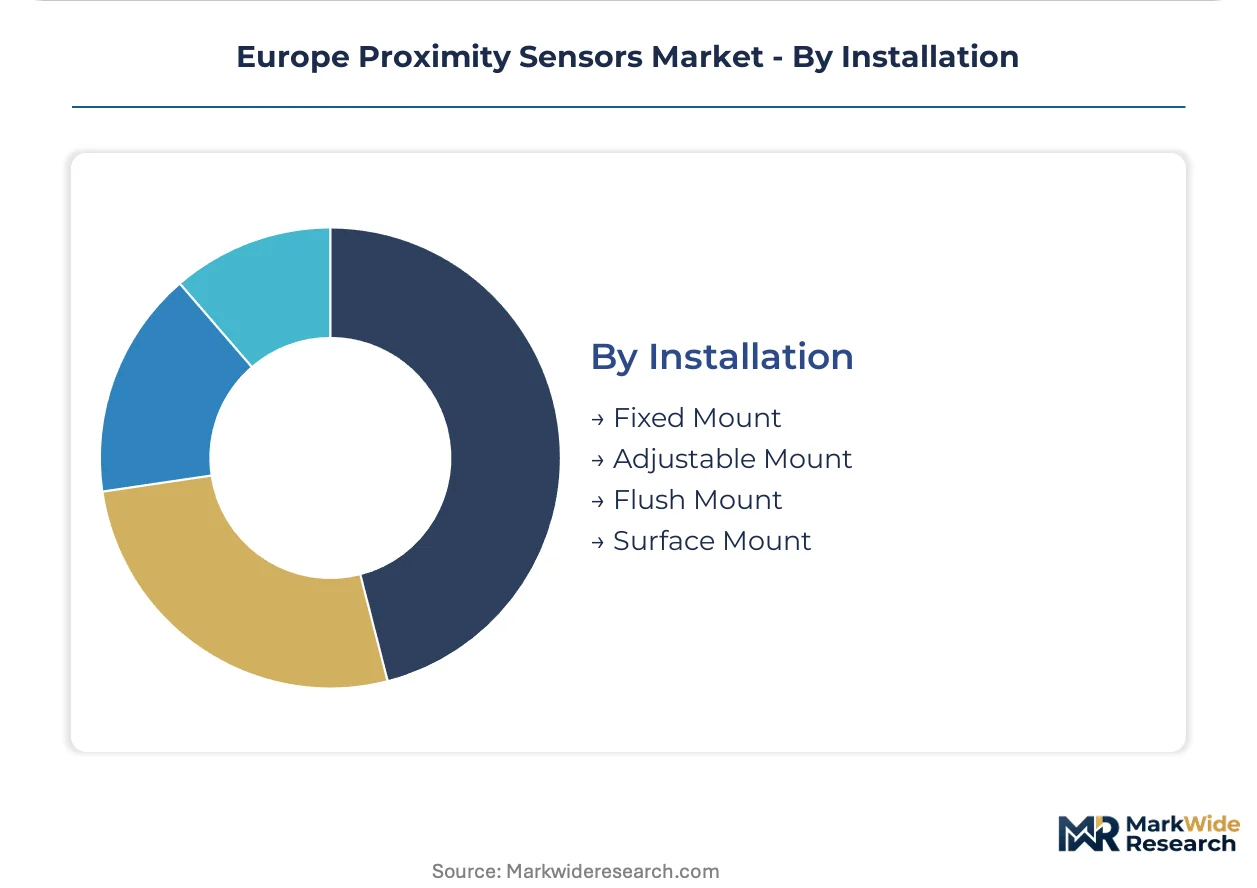
Installation:
Mechanical mounting configurations determine environmental sealing ratings and integration labor requirements.
- Fixed Mount:Rigid bracket attachment for permanent positioning in high-vibration welding environments. German automotive lines specify these for repeatability in multi-shift operations.
- Flush Mount:Recessed installation with sensing face aligned to surrounding surface. Food and pharmaceutical cleanrooms in France and Italy favor these for hygienic design and CIP/SIP compatibility.
- Adjustable Mount:Articulated positioning brackets enable range and angle modification. Packaging OEMs in Spain and Portugal deploy these for format change flexibility.
- Surface Mount:Direct attachment to flat panels without recessing. Consumer electronics assembly and compact machinery applications.
Standardization favors fixed mount in high-volume automotive. Customization demand clusters around flush mount for regulated cleanroom environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric powertrain assembly and aerospace precision manufacturing concentrate sensor procurement across German automotive corridors and French-Italian industrial clusters. REACH compliance and EU Green Deal carbon border adjustments are reshoring supply chains toward European-certified producers. Regional demand fragments across specialized applications rather than consolidating around standardized specifications.
Germany
Baden-Württemberg and Bavaria host concentrated electric vehicle powertrain assembly lines requiring inductive sensors for battery module positioning. KBA vehicle certification mandates and EU Green Deal reshoring incentives channel procurement toward domestic Tier-1 networks. Stuttgart and Munich manufacturing corridors see Sick AG and Pepperl+Fuchs GmbH anchoring supply relationships through embedded technical service teams.
France
Aerospace precision manufacturers in Toulouse and Paris-Saclay clusters specify photoelectric sensors with predictive maintenance integration for downtime reduction. ANSM quality system oversight and EASA airworthiness requirements extend conformity documentation burdens to sensor networks. Île-de-France and Occitanie regions concentrate specification evolution as AS9100-certified suppliers prioritize full component traceability.
Italy
Emilia-Romagna and Lombardy machinery builders deploy smart sensors for packaging automation and metalworking quality control. CE marking machinery directives and RoHS substance restrictions shape procurement screening for brownfield PLC integration. Turin and Bologna industrial zones represent underpenetrated pockets for sensor-as-a-service contracting among mid-sized OEMs.
Poland
Lower Silesian and Greater Poland manufacturing clusters remain underpenetrated for industrial automation sensing despite automotive component assembly expansion. EU structural fund investments and national industrial policy support automation retrofitting in legacy metalworking facilities. Wrocław and Poznań corridors offer first-mover positioning for vendors establishing localized calibration and technical service presence.
Spain
Catalonia and Madrid packaging OEMs pilot sensor-as-a-service contracting with per-detection pricing models. Iberian food and beverage conveyor builders transfer obsolescence risk to vendors through bundled hardware-calibration-analytics arrangements. Barcelona and Madrid industrial zones compress capital allocation cycles amid uncertain production volume forecasts.
Europe Proximity Sensors Market Competitive Landscape
German producers anchor the premium tier through in-house manufacturing and channel control; Asian semiconductor specialists hold component supply leverage. The vendor base stratifies across three archetypes: diversified industrial automation conglomerates with captive sensor divisions, pure-play proximity sensor fabricators with regional manufacturing footprints, and fabless design houses outsourcing production to foundry partners. Competitive moves center on backward integration into photoelectric component manufacturing and geographic expansion through technical service localization.
Within the diversified industrial tier, Sick AG and Pepperl+Fuchs GmbH occupy positions exemplifying channel dominance through German automotive Tier-1 network embedding. Infineon Technologies AG represents the semiconductor-integrated archetype, leveraging R&D intensity in smart sensor architectures for Industry 4.0 deployments. These three entities collectively illustrate how European regulatory compliance and manufacturing proximity function as defensive moats against low-cost Asian import competition.
| Leading Market Players |
|---|
| Sick AG |
| STMicroelectronics |
| TE Connectivity |
| Pepperl+Fuchs GmbH |
| Infineon Technologies AG |
| NXP Semiconductors |
| Omron Corporation |
| Balluff GmbH |
| ifm electronic GmbH |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-compliant European producers and non-compliant Asian suppliers manifests in parallel pricing ladders and sourcing configurations. Premium positioning accrues to domestic manufacturers embedding compliance costs into long-term automotive contracts, while commodity-tier procurement channels fragment across spot-market Asian imports facing carbon border adjustment exposure.
Pricing Analysis
Volume concentration in digital-output inductive sensors for Eastern European automotive assembly compresses margins through scale competition, while smart sensor premiums sustain margin pools in French aerospace predictive maintenance contracts. Price differentiation hinges on CE marking machinery directive tiers and embedded AI Act documentation bundles. Pricing pressure intensifies in photoelectric variants as Taiwanese LED emitter supply bottlenecks propagate cost volatility. Tier-1 automotive procurement teams in Germany exhibit lowest price sensitivity due to KBA certification lock-in, whereas Iberian packaging OEMs piloting sensor-as-a-service models prioritize per-detection operational expenditure over capital outlay.
Supply Chain Analysis
EU Green Deal local-content mandates and carbon border adjustment mechanisms are reshoring coil winding and housing fabrication toward Polish and Romanian manufacturing zones. Inductive sensor production draws from German copper cathode processing and domestic REACH-compliant polymer compounding, while photoelectric assemblies remain tethered to South Korean and Taiwanese LED foundries. Single-source vulnerability concentrates in neodymium magnet supply for high-temperature automotive variants. Distribution runs through German automotive Tier-1 technical service networks and French aerospace certified supplier portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart sensor architectures with embedded edge computing are displacing legacy analog-output proximity detection across European industrial automation, compressing product lifecycles and elevating firmware-intensive development requirements.
For Market Incumbents: Deploy channel control through embedded technical service teams to defend against fabless design houses penetrating via direct digital sales. Consolidate position by backward integration into photoelectric component manufacturing to reduce Taiwanese foundry dependency. Expand AS9100-certified production capacity in Toulouse and Paris-Saclay corridors to capture aerospace traceability premiums. For New Entrants and Emerging Players: Direct-to-engineer digital platforms offer lowest-friction entry into Polish and Romanian brownfield automation clusters lacking legacy distributor relationships. Target underpenetrated pharmaceutical cleanroom applications in Emilia-Romagna with capacitive sensor variants bundling CIP/SIP-compliant flush-mount housings. Prioritize sensor-as-a-service contracting models among Iberian mid-sized packaging OEMs compressing capital allocation cycles. For Investors and Strategic Acquirers: Re-rating potential sits with smart sensor specialists combining analog circuit design and machine learning optimization expertise given EU AI Act algorithmic transparency mandate expansion. Long-term viability favors acquisition targets with captive photoelectric component manufacturing and established CE marking machinery directive certification pathways. Monitor ECHA substance candidate list updates for inductive coil coating reformulation cycles as inflection indicator for domestic supplier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoelectric Components | Reduces dependency on Taiwanese LED foundries exposed to geopolitical transit risks. |
| Sensor-as-a-Service Contracting Launch | Transfers obsolescence risk to vendors among Iberian packaging OEMs. |
| AS9100 Certification Pathway Investment | Unlocks aerospace procurement channels in Toulouse and Paris-Saclay clusters. |
| Polish and Romanian Technical Service Expansion | Captures first-mover positioning in underpenetrated Eastern European automation. |
| EU AI Act Documentation Capability Buildout | Enables premium positioning for embedded decision-making sensor networks. |
Research Methodology
Independent corroboration across plant engineers at German automotive Tier-1 suppliers, procurement leads at French aerospace manufacturers, and channel partners in Polish industrial distribution underwrites the qualitative findings. Primary interviews with maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from customs trade data, SEC filings of listed sensor manufacturers, and ECHA substance restriction updates. Bottom-up segment sizing triangulates against top-down European industrial automation expenditure estimates.
Comparable-period anchoring to historical electric powertrain assembly expansion and aerospace precision manufacturing investment cycles shaped the projection horizon. The analytical framework models proximity sensor demand across detection principle, signal processing architecture, end-use industry, and regional manufacturing cluster dimensions. CAGRs were derived from segment-level growth rate synthesis incorporating REACH compliance transition timelines and EU Green Deal reshoring incentive intensity. Industry-specific forecast inputs include KBA vehicle certification trajectories and AS9100 quality system adoption rates.
Inputs from ECHA regulatory filings and German automotive production databases were available through the study window; gaps in real-time photoelectric component inventory positions introduce uncertainty bands around near-term supply constraints. Forecasts reflect documented assumptions regarding carbon border adjustment implementation pace and EU AI Act enforcement sequencing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Smart Haptic Devices Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
GCC Air Purifiers Market