
 North America Image Sensors Market | 2026-2036
North America Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Image Sensors Market Analytics
Automotive Tier-1 suppliers is reorganizing procurement priorities away from smartphone-centric vendors toward ruggedized image sensor specialists. Sony Corporation leverages its stacked CMOS fabrication expertise to anchor high-resolution automotive contracts. ON Semiconductor Corporation specializes in automotive-qualified sensors with extended temperature ranges for underhood deployment. Teledyne DALSA Inc. dominates industrial machine vision with its proprietary charge-domain readout architectures.
Image sensors are semiconductor devices that convert optical signals into electrical signals through photodiode arrays, with CMOS variants achieving sub-micron pixel pitches and CCD architectures preserving superior dynamic range for scientific instrumentation. Their primary commercial purpose spans capture, digitization, and transmission of visual data across consumer, industrial, and medical systems. CMOS sensors lead unit shipments due to lower power draw and on-chip integration, while SWIR and InGaAs variants command premium positioning in defense and process inspection where silicon responsivity terminates. Machine Vision applications sustain the fastest growth trajectory as warehouse automation and quality inspection systems proliferate across North American manufacturing.
The FCC governs electromagnetic emissions from image sensors operating near wireless bands, while FDA 510(k) pathways regulate medical imaging sensor integration into diagnostic devices. NHTSA's NCAP roadmap shapes automotive camera resolution and latency requirements for pedestrian detection compliance. Stakeholders must monitor evolving EPA conflict mineral disclosure rules affecting indium and gallium supply chains for InGaAs fabrication.
Market Dynamics
Automotive ADAS mandates and FCC equipment authorization tightening are compressing sensor procurement timelines across Detroit and Ontario manufacturing corridors. Tier-1 suppliers now prioritize ruggedized qualification over consumer-grade pixel density.
Growth Catalysts
- NHTSA NCAP Roadmap:Pedestrian detection compliance deadlines are mandating higher-resolution front-facing camera arrays across light vehicle platforms.
- Guadalajara Electronics Cluster:Contract manufacturers are expanding camera module capacity to serve North American OEM assembly plants.
- Stacked CMOS Fabrication:Sub-micron pixel pitch advances are enabling single-sensor solutions for combined visible and near-infrared imaging.
Market Restraints
- Indium Supply Concentration:InGaAs SWIR sensor fabrication depends on concentrated indium refining capacity outside North America.
- FCC Certification Friction:Radar-coexisting imaging devices face extended equipment authorization timelines for 60-64 GHz operation.
- Thermal Performance Ceiling:Silicon-based sensors exhibit responsivity termination beyond 1000 nm, limiting autonomous vehicle perception in low-visibility conditions.
Strategic Opportunities
- Mexico Nearshoring:Assembly plants in Baja California and Querétaro offer tariff-advantaged production for US-bound automotive camera modules.
- Machine Vision Convergence:Integration of time-of-flight depth sensing with traditional 2D imaging is opening warehouse automation contracts.
- EPA Conflict Mineral Disclosure:Early compliance with evolving gallium and indium traceability rules secures preferential supplier status with defense integrators.
Industry Challenges
- Automotive Qualification Timelines:AEC-Q100 stress testing and PPAP submission cycles extend sensor vendor onboarding to 18-24 months.
- Multi-Spectral Integration Complexity:Fusing SWIR, visible, and thermal streams requires specialized image signal processor firmware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Image Sensors Market |
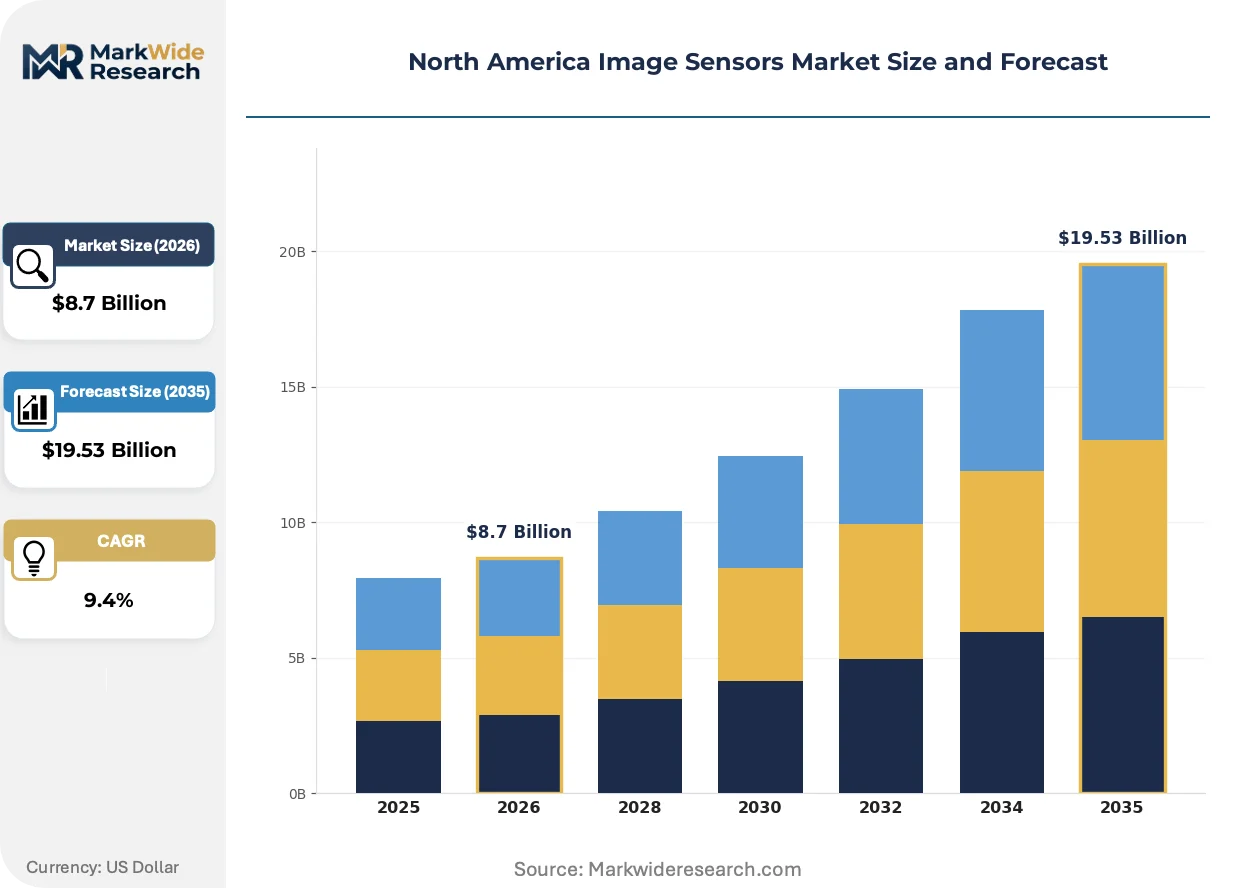
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMOS, CCD, SWIR, InGaAs End User: Consumer Electronics, Automotive, Security, Healthcare Technology: Sensing, Imaging, Processing, Display Application: Machine Vision, Surveillance, Robotics, Medical Imaging |
| Companies Covered | Sony Corporation, Samsung Electronics Co. Ltd, OmniVision Technologies Inc., ON Semiconductor Corporation, STMicroelectronics N.V, Canon Inc., Panasonic Corporation, Teledyne DALSA Inc., SK Hynix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Image Sensors Market Evolving Landscape
Sensor architectures are bifurcating between high-volume automotive qualification tracks and specialized industrial imaging stacks. Fabrication investments now favor charge-domain readout and backside illumination over conventional frontside processes.
Backside-illuminated stacked CMOS is displacing frontside-illuminated architectures in automotive surround-view applications. Tier-1 suppliers in Michigan and Ontario are adopting these sensors for 2026 model year platforms. The shift is compressing die area requirements while maintaining quantum efficiency targets under street-lighting conditions.
NHTSA's updated NCAP testing protocols now mandate nighttime pedestrian detection performance metrics. The regulation is forcing sensor vendors to demonstrate sub-100 millisecond latency from photon capture to object classification. Automotive camera module suppliers are responding by co-locating image signal processors within sensor packages.
Long-term supply agreements with foundry partners are replacing spot-market wafer purchases among qualified automotive sensor vendors. This pattern concentrates procurement leverage with vertically integrated IDMs possessing captive fabrication. The restructuring is most visible in Detroit's direct sourcing relationships with Sony and ON Semiconductor fabrication facilities.
North America Image Sensors Market Segmentation
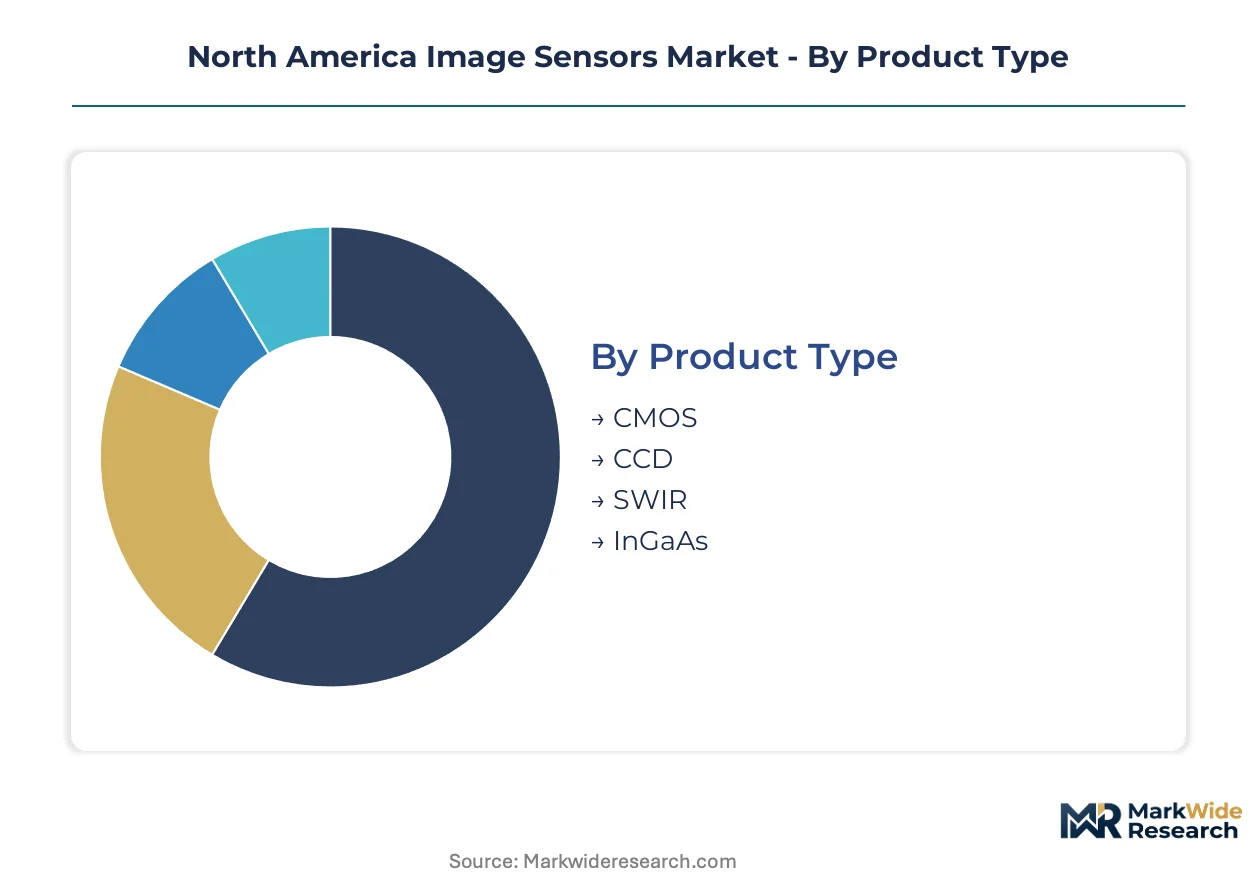
Image sensor procurement patterns diverge sharply across end-use verticals, with automotive qualification tracks demanding distinct supply chain configurations from consumer electronics channels. Understanding these segment boundaries clarifies where fabrication investments and regulatory compliance resources must concentrate.
Product Type:
CMOS sensors flow through high-volume contract manufacturing channels serving Detroit and Guadalajara automotive clusters, while CCD and specialty compound semiconductor variants move through lower-volume, qualification-intensive distribution paths.
- CMOS:Stacked backside-illuminated architectures now anchor automotive surround-view and ADAS front-camera deployments. Detroit Tier-1 suppliers are consolidating procurement around sub-micron pixel pitch devices that maintain quantum efficiency under street-lighting conditions.
- SWIR:Short-wave infrared sensors utilizing InGaAs photodiode arrays enable autonomous vehicle perception beyond silicon's 1000 nm responsivity termination. NHTSA nighttime pedestrian detection mandates are accelerating procurement of these devices for low-visibility operating conditions.
- CCD:Charge-coupled devices retain dominance in scientific instrumentation requiring superior dynamic range. Medical imaging OEMs specify these sensors for diagnostic equipment where photon noise floors must remain minimal.
- InGaAs:Indium gallium arsenide focal plane arrays command premium positioning in defense and industrial process inspection. EPA conflict mineral disclosure rules are complicating supply chain qualification for these devices.
CMOS dominates installed base. SWIR is where expansion concentrates.
End User:
Cost tier stratification separates automotive AEC-Q100 qualified sensors from consumer-grade devices, with healthcare and security applications occupying intermediate price-performance bands.
- Automotive:ADAS deployment timelines compress sensor vendor onboarding to 18-24 month PPAP submission cycles. Michigan and Ontario manufacturing corridors are absorbing the bulk of qualified CMOS capacity expansion.
- Consumer Electronics:Smartphone camera module demand has plateaued as procurement priorities shift toward ruggedized automotive specialists. Remaining volume concentrates in Mexico's Guadalajara electronics cluster for North American OEM assembly.
- Security:Surveillance camera networks require extended temperature range operation and low-light sensitivity. Federal procurement specifications favor domestic final assembly for critical infrastructure deployments.
- Healthcare:FDA 510(k) pathways regulate sensor integration into diagnostic devices. Endoscopy and ophthalmology applications specify CCD architectures for their superior dynamic range performance.
Automotive commands highest average selling prices. Machine vision integration is gaining share fastest among security and healthcare procurement.
Technology:
Supply concentration varies by technology layer, with sensing and imaging functions consolidating around captive fabrication while processing and display integration fragments across fabless design houses.
- Sensing:Photodiode array fabrication concentrates in vertically integrated IDMs with captive foundry capacity. Long-term wafer supply agreements are displacing spot-market purchases among qualified automotive vendors.
- Imaging:Charge-domain readout architectures from Teledyne DALSA anchor industrial machine vision deployments. Backside illumination processes are displacing frontside alternatives in high-performance segments.
- Processing:Image signal processor co-location within sensor packages is accelerating to meet NHTSA sub-100 millisecond latency mandates. Fabless design houses compete on firmware optimization for multi-spectral fusion.
- Display:Viewfinder and EVF integration requirements differ markedly between consumer camera OEMs and automotive head-up display suppliers. Resolution specifications diverge across these channels.
Sensing captures the largest fabrication capital allocation. Processing is climbing the fastest as latency requirements tighten.
Application:
Customer type segmentation separates OEM direct procurement from contract manufacturer-mediated sourcing, with machine vision and robotics applications favoring distributor channels for smaller lot sizes.
- Machine Vision:Warehouse automation and quality inspection systems are proliferating across North American manufacturing. Time-of-flight depth sensing integration with traditional 2D imaging is opening new contract opportunities.
- Surveillance:Municipal and federal security infrastructure deployments specify extended operational temperature ranges. FCC equipment authorization for radar-coexisting imaging devices adds certification friction to procurement timelines.
- Robotics:Autonomous mobile robots require compact multi-camera arrays with synchronized triggering. Baja California and Querétaro assembly plants offer tariff-advantaged production for US-bound modules.
- Medical Imaging:Diagnostic device integration demands FDA 510(k) clearance for sensor subsystems. End-use concentration in Minnesota and Massachusetts medical device clusters shapes regional demand patterns.
Machine vision shows steepest expansion trajectory. Surveillance maintains largest cumulative installed base among industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports camera module assemblies northward to Detroit and Ontario automotive plants, creating a tightly integrated North American supply corridor that compresses procurement timelines for Tier-1 suppliers.
United States
NHTSA NCAP pedestrian detection mandates drive sensor procurement from Michigan and Ohio assembly corridors. The FCC's equipment authorization rules for radar-coexisting imaging devices tighten certification pathways for 60-64 GHz operation. Detroit's Tier-1 supplier base is consolidating direct sourcing relationships with vertically integrated fabrication facilities.
Canada
Ontario's automotive manufacturing belt absorbs qualified CMOS capacity for ADAS platform integration. Health Canada regulates medical imaging sensor integration through device licensing pathways comparable to FDA frameworks. Waterloo-Toronto technology corridors host machine vision startups serving warehouse automation contracts.
Mexico
Guadalajara's electronics cluster expands camera module capacity for North American OEM final assembly. Mexican trade agreements provide tariff-advantaged production positioning for US-bound automotive components. Baja California and Querétaro assembly plants specialize in compact multi-camera arrays for robotics applications.
North America Image Sensors Market Competitive Landscape
Player mix skews toward diversified semiconductor conglomerates with captive fabrication capacity. Market structure concentrates procurement leverage among vertically integrated IDMs possessing long-term foundry agreements. Two strategic archetypes dominate: stacked CMOS specialists serving automotive resolution requirements, and charge-domain readout architects anchoring industrial machine vision. Competitive moves center on backward integration into wafer supply and co-location of image signal processors within sensor packages.
Among Asia-Pacific-based conglomerates, Sony Corporation and Samsung Electronics Co. Ltd occupy positions as scale-driven fabrication anchors. ON Semiconductor Corporation exemplifies the automotive-qualified specialist archetype with extended temperature range capabilities. Teledyne DALSA Inc. represents the industrial imaging tier with proprietary readout architectures.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics Co. Ltd |
| OmniVision Technologies Inc. |
| ON Semiconductor Corporation |
| STMicroelectronics N.V |
| Canon Inc. |
| Panasonic Corporation |
| Teledyne DALSA Inc. |
| SK Hynix Inc. |
| Others |
Value Network & Pricing Analysis
Long-term wafer supply agreements between automotive-qualified sensor vendors and vertically integrated IDMs lock in fabrication capacity and price visibility across the 18-24 month PPAP submission cycles governing Detroit and Ontario procurement corridors.
Pricing Analysis
Current-generation stacked CMOS sensors command substantial premiums over prior-generation frontside-illuminated alternatives, while next-generation InGaAs SWIR devices remain priced at specialist tiers inaccessible to mainstream automotive procurement. Three-tier pricing structure across AEC-Q100 qualified, industrial-grade, and consumer-grade certification levels separates automotive Tier-1 contracts from security and medical imaging channels. Cost compression in consumer-grade CMOS modules is intensifying because smartphone-centric vendors are redirecting excess capacity toward automotive qualification tracks. Security integrators exhibit highest price sensitivity due to municipal budget constraints, while defense procurement maintains lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Strategic stockpiling of indium and gallium feedstock is displacing just-in-time inventory preferences among InGaAs sensor fabricators responding to EPA conflict mineral disclosure uncertainties. Photodiode array fabrication concentrates in Taiwan, South Korea, and Japan, while final camera module assembly clusters in Mexico's Guadalajara corridor and Michigan's Detroit manufacturing belt. InGaAs focal plane array production rests on concentrated indium refining capacity outside North America, creating single-source vulnerability for defense and autonomous vehicle perception systems. Distribution runs through direct OEM procurement channels for automotive volumes and specialized industrial distributors for machine vision lot sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Image sensor procurement is shifting toward platform-centric ecosystem economics where firmware-integrated sensor-processor subsystems displace discrete component sourcing, driven by NHTSA latency mandates requiring sub-100 millisecond photon-to-classification performance.
For Market Incumbents: Consolidate backward integration into captive wafer supply to defend against fabless competitors facing allocation constraints during automotive demand surges. Expand AEC-Q100 qualification capacity in Ontario and Michigan corridors to capture Tier-1 supplier consolidation toward ruggedized specialists. Prioritize image signal processor co-location within sensor packages as the primary R&D lever against latency compliance deadlines. For New Entrants and Emerging Players: Multi-spectral fusion firmware development services represent a critical service-layer gap where vertically integrated incumbents under-serve mid-tier machine vision integrators. Target warehouse automation and quality inspection applications in Waterloo-Toronto technology corridors as the most penetrable segment given distributor channel fragmentation. Pursue partnership-based go-to-market angles with robotics OEMs in Baja California and Querétaro assembly plants seeking tariff-advantaged module sourcing. For Investors and Strategic Acquirers: Fabless design houses possessing proprietary charge-domain readout architectures and established FDA 510(k) clearance pathways represent the most attractive acquisition target archetype for long-term viability across the medical imaging and defense procurement windows. Monitor FCC equipment authorization timeline compression for radar-coexisting imaging devices as the primary inflection signal indicating regulatory barrier height for new sensor entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Supply | Captive fabrication capacity secures allocation priority during automotive demand cycles and insulates against spot-market volatility. |
| Image Signal Processor Co-location | Package-level integration meets NHTSA sub-100 millisecond latency mandates for pedestrian detection compliance. |
| Guadalajara Module Assembly Expansion | Mexican trade agreements provide tariff-advantaged production positioning for US-bound automotive camera volumes. |
| InGaAs SWIR Qualification Investment | Extended responsivity beyond silicon's 1000 nm termination enables autonomous vehicle perception in low-visibility conditions. |
| EPA Conflict Mineral Compliance Program | Early gallium and indium traceability documentation secures preferential supplier status with defense integrators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, NHTSA regulatory dockets, and FCC equipment authorization databases to validate procurement pattern shifts across automotive and industrial channels. Primary interviews engaged Tier-1 supplier procurement directors, CMOS foundry planning officers, medical device regulatory affairs leads, and machine vision system integrators. Bottom-up sensor shipment estimates triangulate against top-down semiconductor capital expenditure disclosures from vertically integrated IDMs.
Segmentation dimensions modeled span product type, end-use vertical, technology layer, and application category across the projection horizon. CAGRs derive from regression analysis of historical qualification timeline compression and ADAS penetration assumptions. Forecast inputs incorporate NHTSA NCAP roadmap compliance deadlines and Guadalajara electronics cluster capacity expansion trajectories without year-specific anchoring.
Material uncertainties — indium supply disruption, FCC certification timeline extension, and AEC-Q100 qualification bottleneck accumulation — sit outside the modeled envelope. Forecasts reflect assumptions regarding foundry capacity allocation continuity and trade agreement stability. Revision becomes warranted when automotive camera module demand growth exceeds qualified supplier onboarding capacity by sustained margins.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Microscopy Market
Imaging
Photography Equipment Market
Imaging
Global Automotive Imaging Market
Imaging
Near Infra-Red Imaging Market
Imaging
Infrared Imaging Market
Imaging
Plenoptic Camera Market
Imaging
Global Whole Slide Imaging Market
Imaging
Photoconductor Drums Market
Imaging
Global Acoustic Cameras Market
Imaging
EUV Mask Inspection System Market
Imaging
Photoacoustic Tomography Market
Imaging
Multi Camera System Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Printed Image Sensors Market
Imaging
Virtual Reality Camera Market
Imaging
Sub-Micrometer Computed Tomography Market