
 Visualiser Market | 2026-2036
Visualiser Market Size, Share, and Industry Trends Forecast 2026-2036
Visualiser Market Outlook
Data scientist and clinical imaging specialist talent pools is rotating toward hybrid AI-radiology competencies, tightening supply for traditional hardware engineering roles. Siemens Healthineers leverages its dual expertise in diagnostic equipment and enterprise software to anchor integrated visualization platforms across European hospital networks. GE HealthCare Technologies Inc. competes through deep backward integration into detector arrays and image-reconstruction chipsets. Philips sustains its position via specialized clinical workflow tools that bridge PACS environments with real-time surgical displays.
A visualiser is an electro-optical device that captures, processes, and projects physical objects or digital imagery through high-resolution sensors with optical zoom ratios typically exceeding 20x and real-time frame rates above 30 fps, serving primarily to enable collaborative visual communication in education, healthcare, and enterprise settings. Desktop visualisers retain dominant volume share in institutional procurement, though 3D visualisers command disproportionate margin pools as surgical navigation and anatomical modeling applications expand. Document cameras occupy a mature replacement cycle in K-12 education, while portable scanners are capturing incremental share in hybrid corporate training environments where mobility requirements have intensified.
FDA 510(k) premarket notification requirements shape software-as-medical-device classifications for AI-enhanced visualisation tools, while CE marking under the EU MDR imposes clinical evidence thresholds on diagnostic display systems. ISO 13485 quality management standards govern manufacturing processes for devices deployed in patient-facing clinical workflows. Stakeholders must monitor evolving regulatory divergence between US and European software validation requirements as they calibrate product development roadmaps and market entry sequencing.
Market Dynamics
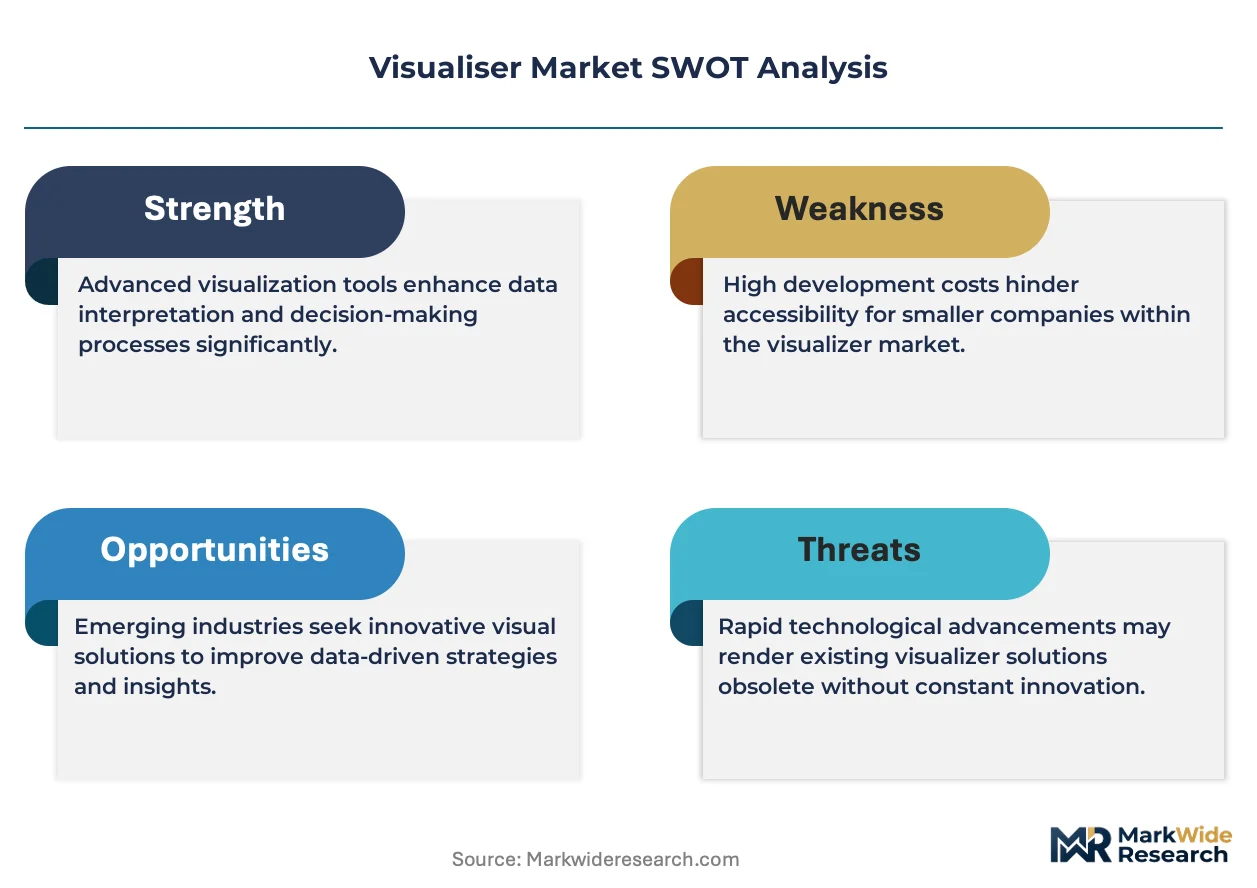
Medical imaging departments are consolidating procurement around AI-enhanced visualization workstations, compressing vendor qualification timelines and reshaping competitive positioning around software certification velocity rather than hardware specifications alone.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification for AI-enhanced radiological software is compressing vendor certification cycles in the United States. Diagnostic imaging suites are expanding procurement of integrated 3D visualization platforms.
- German University Hospital Expansion:Siemens Healthineers and medical centers in Berlin and Munich are driving adoption of integrated 3D visualization suites for surgical planning and anatomical modeling applications.
- Hybrid AI-Radiology Competency Migration:Data scientist and clinical imaging specialist talent pools are rotating toward hybrid skill sets, tightening supply for traditional hardware engineering roles and elevating software-centric vendors.
Market Restraints
- CMOS Sensor Supply Concentration:High-resolution image sensor fabrication concentrates among Taiwanese and South Korean foundries, exposing visualiser manufacturers to geographic supply risk and input cost volatility.
- EU MDR Clinical Evidence Thresholds:CE marking under the EU Medical Device Regulation imposes rigorous clinical validation requirements on diagnostic display systems, extending time-to-market for European entrants.
- Smartphone Camera Substitution:Advanced mobile device cameras with optical zoom and document scanning capabilities are capturing price-sensitive segments in corporate training and informal education settings.
Strategic Opportunities
- India Medical Infrastructure Buildout:Government hospital modernization programs and diagnostic center expansion in tier-2 cities are creating demand for portable visualization systems with localized software interfaces.
- AI-Assisted Surgical Navigation Convergence:Integration of real-time 3D visualization with robotic surgical platforms is opening premium-margin opportunities in neurosurgical and orthopedic planning workflows.
- Subscription-Based Service Models:Cloud-enabled visualization platforms with per-procedure licensing are displacing capital-intensive hardware purchases in ambulatory surgical centers and private clinic networks.
Industry Challenges
- ISO 13485 Quality System Implementation:Device manufacturers face complex documentation and audit requirements for patient-facing clinical workflows, straining mid-tier engineering organizations.
- PACS-Legacy System Integration:Enterprise imaging archives built on proprietary DICOM implementations require costly middleware development for seamless real-time surgical display connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Visualiser Market |
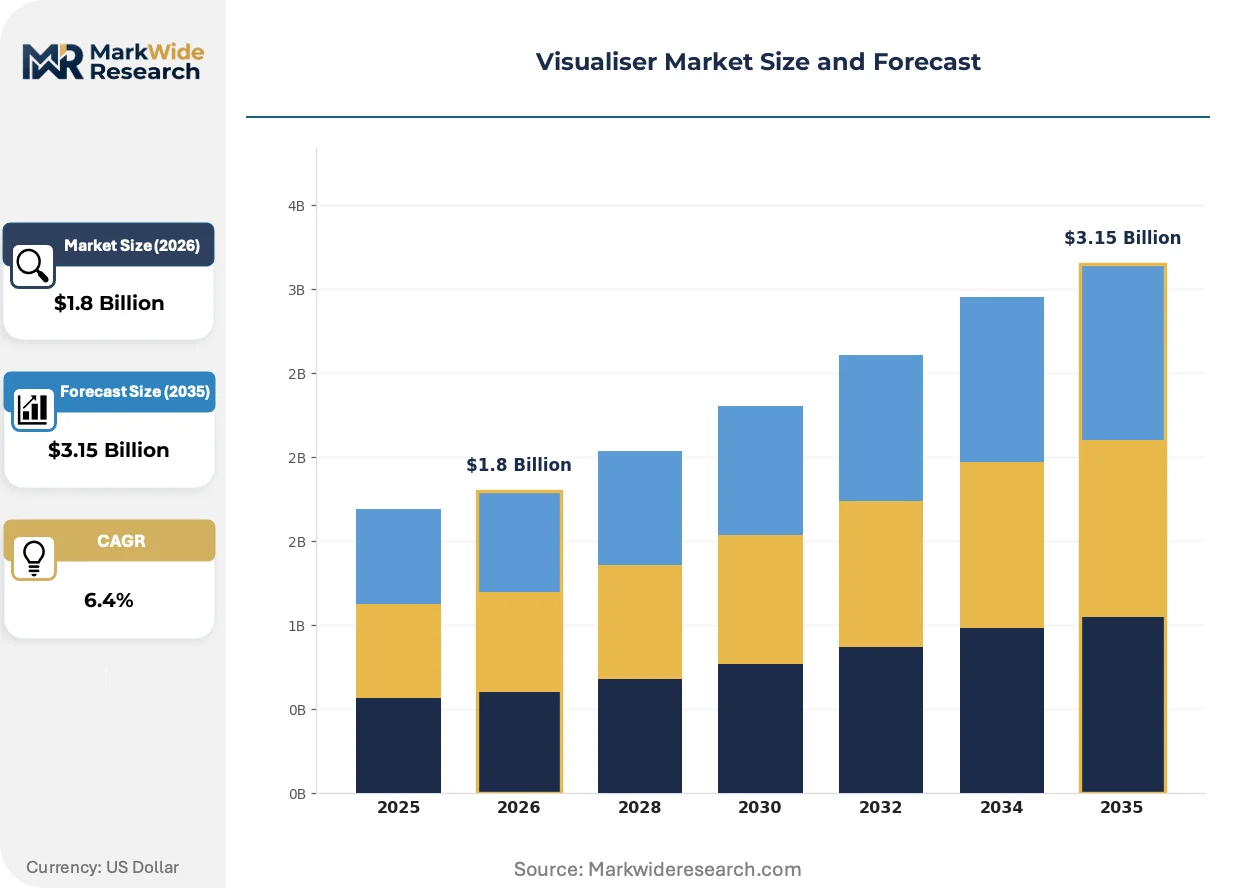
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Visualisers, Document Cameras, Portable Scanners, 3D Visualisers Application: Education, Corporate Training, Teleconferencing, Event Management Technology: Digital Imaging, Optical Zoom, HD Resolution, Real-time Processing End User: Schools, Universities, Businesses, Event Organizers |
| Companies Covered | Siemens Healthineers, GE HealthCare Technologies Inc., Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Agfa-Gevaert Group, Carestream Health, TeraRecon Inc., Pro Medicus Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Visualiser Market Strategic Shifts
Computational imaging and edge AI processing are compressing form factors while expanding real-time analytical capabilities, fundamentally altering how visualization hardware is architected and where it deploys.
Portable visualization systems with embedded neural processing units are miniaturizing without sacrificing optical performance. Ambulatory surgical centers and field medical units are adopting pocket-sized document cameras with 4K capture and wireless projection. This compression is miniaturizing the addressable market for traditional desktop visualisers while expanding total accessible volume in mobile-first healthcare environments.
CE marking under the EU MDR is tightening clinical evidence requirements for diagnostic display systems. Manufacturers must now submit prospective performance validation data for software-as-medical-device classifications, elevating development costs and favoring established players with dedicated regulatory affairs functions. European university hospitals are responding by consolidating procurement around vendors with proven MDR compliance track records.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisitions, demanding à-la-carte maintenance options and cloud-based remote diagnostics. German and Dutch healthcare networks are leading this shift, pressuring traditional vendors to restructure pricing architectures and service delivery models. The disintermediation of bundled service agreements is compressing recurring revenue streams for hardware-centric manufacturers.
Visualiser Market Segmentation
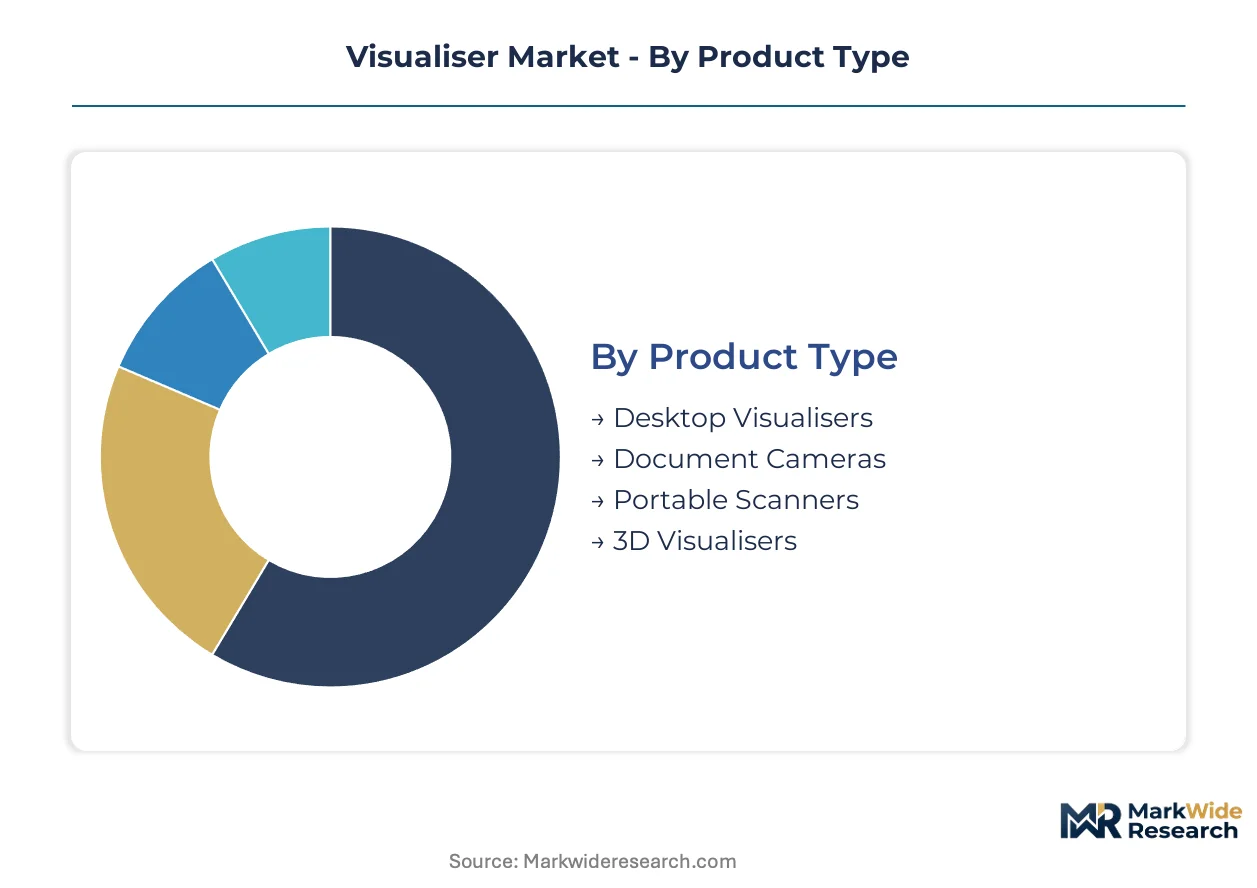
Product architecture and use-case specificity determine procurement patterns across institutional buyers. Substitution threats from smartphone cameras and cloud-based collaboration tools fragment demand along mobility and integration requirements.
Product Type:
Smartphone camera substitution pressures document cameras most severely, while 3D visualisers face minimal displacement risk due to specialized surgical navigation requirements.
- Desktop Visualisers:Stationary electro-optical systems with optical zoom exceeding 20x and real-time frame rates above 30 fps anchor institutional procurement volume. University hospitals in Germany and corporate training centers in the United States drive replacement cycles through integrated software suite requirements.
- 3D Visualisers:Volumetric capture systems with embedded neural processing units enable real-time anatomical modeling and surgical navigation workflows. Siemens Healthineers anchors European adoption through integrated visualization suites in Berlin and Munich university medical centers.
- Document Cameras:Mature replacement-cycle hardware in K-12 education faces intensifying price pressure from smartphone scanning applications.
- Portable Scanners:Pocket-sized 4K capture devices with wireless projection capabilities capture incremental share in hybrid corporate training environments.
Desktop visualisers anchor the volume base while 3D visualisers gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive surgical planning from price-sensitive corporate training deployments.
- Education:K-12 institutions and universities procure document cameras and desktop visualisers through centralized district purchasing, with replacement cycles extending as smartphone substitution intensifies.
- Corporate Training:Hybrid work environments drive demand for portable scanners with wireless projection, displacing fixed-installation hardware in distributed workforce settings.
- Teleconferencing:Enterprise video collaboration platforms integrate visualiser functionality through software APIs, compressing standalone hardware addressable market.
- Event Management:Live presentation and exhibition applications require high-luminance projection compatibility and rapid setup capabilities.
Education retains the largest installed base while corporate training applications expand most quickly.
Technology:
Supply concentration in Taiwanese and South Korean CMOS foundries shapes component availability across all technology tiers.
- Digital Imaging:Computational photography algorithms embedded in neural processing units compress form factors without sacrificing capture quality. FDA 510(k) pathways accelerate AI-enhanced radiological software certification in the United States.
- Real-time Processing:Edge AI architectures enable sub-100ms latency for surgical navigation applications, commanding premium pricing in neurosurgical workflows.
- Optical Zoom:Mechanical lens systems exceeding 20x magnification ratios remain essential for pathology specimen documentation.
- HD Resolution:4K capture standards become baseline expectations in university hospital procurement specifications.
Digital imaging dominates component cost structures while real-time processing commands the steepest margin expansion trajectory.
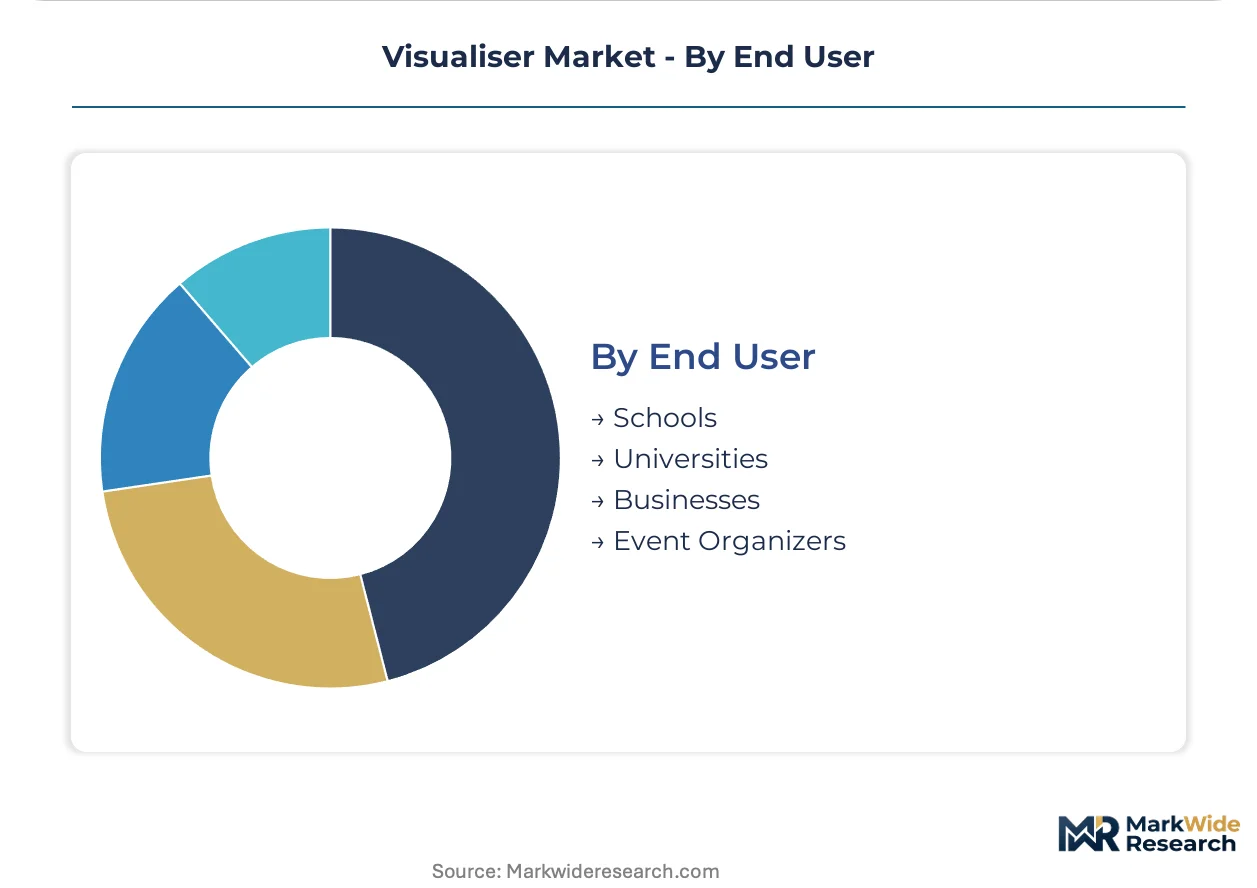
End User:
Customer type determines regulatory compliance burden and service contract structuring.
- Schools:K-12 districts prioritize total cost of ownership and durability specifications over advanced feature sets, consolidating procurement around established vendor relationships.
- Universities:Medical schools and research institutions drive adoption of AI-enhanced visualization workstations for surgical planning and diagnostic review.
- Businesses:Corporate training departments unbundle after-sales service contracts, demanding à-la-carte maintenance and cloud-based remote diagnostics.
- Event Organizers:Rental and staging companies prioritize rapid deployment compatibility and ruggedized transport cases over integration depth.
Universities anchor premium-tier procurement while businesses drive fastest adoption of subscription-based service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor procurement velocity in the United States, while CE marking under EU MDR shapes vendor qualification timelines across Europe. Demand clusters in German university medical centers, US diagnostic imaging suites, and emerging Asian healthcare infrastructure.
United States
Diagnostic imaging departments in university hospitals are consolidating procurement around AI-enhanced visualization workstations. FDA 510(k) premarket notification requirements compress certification cycles for software-as-medical-device classifications. Boston and Stanford medical centers drive adoption of integrated 3D surgical planning platforms.
Germany
Siemens Healthineers anchors integrated visualization suite deployment across Berlin and Munich university medical centers. CE marking under EU MDR imposes rigorous clinical evidence thresholds on diagnostic display systems. The Baden-Württemberg medical technology corridor concentrates regulatory affairs expertise and manufacturing quality systems.
China
Government hospital modernization programs in tier-2 cities are creating demand for portable visualization systems with localized software interfaces. NMPA medical device registration pathways govern software validation requirements for AI-enhanced radiological tools. The Yangtze River Delta clusters domestic visualiser manufacturing and neural processing unit integration capabilities.
Japan
Medical imaging specialists are rotating toward hybrid AI-radiology competencies, tightening supply for traditional hardware engineering roles. PMDA software-as-medical-device classifications require prospective clinical validation for diagnostic AI tools. The Kanto region around Tokyo concentrates precision optical component fabrication and edge AI processing development.
India
Diagnostic center expansion in Maharashtra and Karnataka is generating procurement of cost-optimized visualization hardware with subscription-based service models. CDSCO medical device rules govern import licensing and quality system requirements for patient-facing equipment. The Delhi-NCR corridor anchors healthcare IT integration services and localized software interface development.
Visualiser Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Diagnostic equipment conglomerates with software capabilities anchor premium-tier positioning, while specialized visualization vendors compete on certification velocity and workflow integration. Three archetypes dominate: integrated healthcare technology conglomerates, specialized medical imaging software vendors, and precision optical component suppliers. Competitive moves center on regulatory certification acceleration and strategic partnerships with university medical centers for clinical validation.
Among integrated healthcare technology conglomerates, Siemens Healthineers and GE HealthCare Technologies Inc. represent the dominant archetype combining diagnostic hardware with enterprise software platforms. Koninklijke Philips N.V. occupies a position bridging PACS environments with real-time surgical displays. Specialized medical imaging software vendors exemplified by TeraRecon Inc. and Pro Medicus Limited sit within the certification-velocity tier, competing on FDA 510(k) pathway expertise and AI-enhanced radiological tool validation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare Technologies Inc. |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Agfa-Gevaert Group |
| Carestream Health |
| TeraRecon Inc. |
| Pro Medicus Limited |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements with Taiwanese and South Korean CMOS foundries lock in sensor supply visibility for tier-one visualiser manufacturers while insulating procurement costs from spot-market volatility. These multi-year contracts anchor pricing predictability for FDA 510(k) certified devices while squeezing margin flexibility for mid-tier vendors locked into shorter purchasing cycles.
Pricing Analysis
Price spreads between German university hospital procurement and Indian diagnostic center tenders exceed threefold across equivalent 3D visualization suites. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and after-sales service bundling. Cost compression in document camera tiers is intensifying because smartphone camera substitution erodes replacement-cycle economics. K-12 districts exhibit highest price sensitivity while neurosurgical planning units demonstrate lowest elasticity due to workflow integration requirements.
Supply Chain Analysis
Inventory lead times for neural processing units stretch to twenty-six weeks following foundry allocation constraints at advanced node fabrication. Supply concentrates in Taiwan, South Korea, and Japan for high-resolution image sensors, precision optical assemblies, and edge AI chipsets. Single-source vulnerability runs through TSMC's dominance in sub-7nm neural processing unit production. Distribution runs through authorized medical device distributors with ISO 13485 certified warehousing for patient-facing clinical workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-enabled visualization platforms with per-procedure licensing are expanding recurring revenue pools faster than hardware replacement cycles, repositioning this market as a service-attach opportunity where software subscription retention exceeds capital equipment margins.
For Market Incumbents: Compound defensive positioning through backward integration into detector array fabrication and captive neural processing unit supply chains. Smartphone camera substitution threatens document camera margins while CE marking under EU MDR elevates compliance costs for challengers. Prioritize certification velocity investments to maintain procurement committee preference in German university hospital networks. For New Entrants and Emerging Players: Lead with AI-assisted surgical navigation modules targeting ambulatory surgical centers in India's tier-2 cities where localized software interfaces command premium positioning. Portable visualization systems with embedded neural processing units represent the most penetrable white space. Pursue hospital system partnerships for clinical validation data generation ahead of regulatory submission. For Investors and Strategic Acquirers: Capital is best deployed toward specialized medical imaging software vendors with demonstrated FDA 510(k) pathway expertise and proven MDR compliance track records. Long-term viability over the next decade hinges on recurring revenue mix and regulatory certification velocity rather than hardware scale. Monitor NMPA software-as-medical-device classification timelines as inflection indicator for China market access trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined premarket notification compresses vendor certification cycles for AI-enhanced radiological software in United States diagnostic imaging suites. |
| CE Marking Pathway Investment | EU MDR clinical evidence thresholds favor established players with dedicated regulatory affairs functions in German hospital procurement. |
| Hospital System Partnership | University medical centers in Berlin and Munich provide clinical validation data for integrated 3D visualization suite deployment. |
| Software Companion Development | Cloud-enabled platforms with per-procedure licensing displace capital-intensive hardware purchases in ambulatory surgical centers. |
| Reimbursement Strategy | Subscription-based service models align with unbundled after-sales contract demands from Dutch and German healthcare networks. |
Study Parameters
A standing panel of hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs leads provided ongoing calibration across the study period. Primary interview data combined with FDA 510(k) filing records, EU MDR notified body documentation, hospital procurement databases, and GPO contract repositories. Bottom-up vendor shipment analysis triangulated against top-down healthcare IT expenditure estimates.
Consistency checks validated volume and value outputs against external benchmarks from medical device trade associations and healthcare capital expenditure surveys. Segmentation modeling spanned product architecture, application specificity, technology tier, and end-user type across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in surgical navigation and diagnostic imaging workflows.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway velocity or prolonged CMOS sensor supply constraints would require recalibration. Forecasts reflect documented assumptions regarding AI-radiology competency migration and regulatory divergence between US and European software validation requirements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Uncooled Infrared Imaging Market
Imaging
Camera with Flip Screen Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Acoustic Microscopy Market
Imaging
Global Microbolometer Market
Imaging
Global Thermal Imager Market
Imaging
Image Intensifier Market
Imaging
Camcorder Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Smart Camera Market
Imaging
Global 3D Camera Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Global 3D Imaging Market
Imaging
High-Power Objective Lens Market
Imaging
Microscope Digital Cameras Market
Imaging
EUV Mask Inspection System Market