
 Photography Ring Flash Market | 2026-2036
Photography Ring Flash Market Size, Share, and Industry Trends Forecast 2026-2036
Photography Ring Flash Market Insights
CE marking compliance for electrical and electronic equipment sold in Europe is collapsing the supplier base, eliminating smaller assemblers who lack testing infrastructure. Godox Photo Equipment Co. Ltd. leverages captive manufacturing in Shenzhen to absorb certification costs across high-volume LED ring flash lines. Profoto AB anchors its position through premium-tier positioning and direct-to-studio channel control in Western Europe. Neewer Inc. competes aggressively on price through Amazon-centric distribution, targeting hobbyists and emerging creators with battery-powered TTL models.
A photography ring flash is a circular lighting device that mounts around a camera lens, typically employing LED arrays or xenon tubes with color temperatures ranging from 3200K to 5600K, designed to produce shadowless, evenly distributed illumination for close-subject imaging. The primary commercial purpose is to eliminate harsh shadows in macro, portrait, and dental photography while creating distinctive circular catchlights in subjects' eyes. LED technology segments are gaining structural momentum as thermal efficiency and dimming precision attract studio operators seeking continuous-light workflows. Professional photographers represent the most concentrated margin pool, though educational institutions are emerging as a volume anchor as university photography programs standardize equipment kits. Wireless technology integration is displacing optical triggering in professional settings, driven by reliability demands in multi-light setups.
The Federal Communications Commission regulates radio-frequency emissions from wireless triggering systems in the United States, while the EU's REACH framework restricts hazardous substances in circuit boards and battery housings. Japan's METI enforces energy-efficiency benchmarks under the Top Runner program, shaping product development priorities for manufacturers targeting that market. China's SAMR oversees mandatory CCC certification for domestic electrical product sales, creating a parallel compliance track for brands serving both export and local demand. Stakeholders must monitor how divergent battery transportation rules across aviation authorities reshape portable product design and distribution economics.
Market Dynamics
LED ring flash technology is decomposing traditional xenon tube architectures as continuous-light workflows penetrate professional studios, while the EU's Ecodesign for Sustainable Products Regulation forces modular, repairable designs that reshape manufacturing economics.
Growth Catalysts
- Content Creator Professionalization:Portrait and fashion photography studios are expanding lighting inventories to serve the creator economy's infrastructure demands.
- REACH Compliance Infrastructure:European hazardous substance restrictions in circuit boards and battery housings are accelerating consolidation among certified manufacturers.
- China Domestic Scale:E-commerce channel density and manufacturing cluster concentration in Shenzhen are compressing cost curves for enthusiast-grade equipment.
Market Restraints
- Xenon Tube Supply Concentration:Specialty gas discharge component sourcing remains concentrated among Japanese and German suppliers, creating input cost volatility.
- Aviation Battery Transport Rules:Divergent lithium-ion shipping restrictions across FAA, EASA, and CAAC authorities fragment portable product distribution economics.
- Optical Triggering Obsolescence:Line-of-sight synchronization technology faces substitution pressure from radio-frequency systems, stranding legacy accessory investments.
Strategic Opportunities
- Educational Institution Standardization:University photography programs are emerging as volume anchors for standardized equipment kit procurement.
- Wireless-TTL Convergence:Radio-frequency triggering combined with through-the-lens metering is opening multi-light setup automation in commercial studios.
- India Import Substitution:PLI scheme incentives for electronics manufacturing are creating local assembly opportunities for brands serving South Asian demand.
Industry Challenges
- Certification Timeline Compression:CE marking, FCC Part 15, and CCC testing queues are extending product launch cycles by 4-8 months.
- Legacy Studio Integration:Existing Profoto and Broncolor ecosystem lock-in creates switching friction for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photography Ring Flash Market |
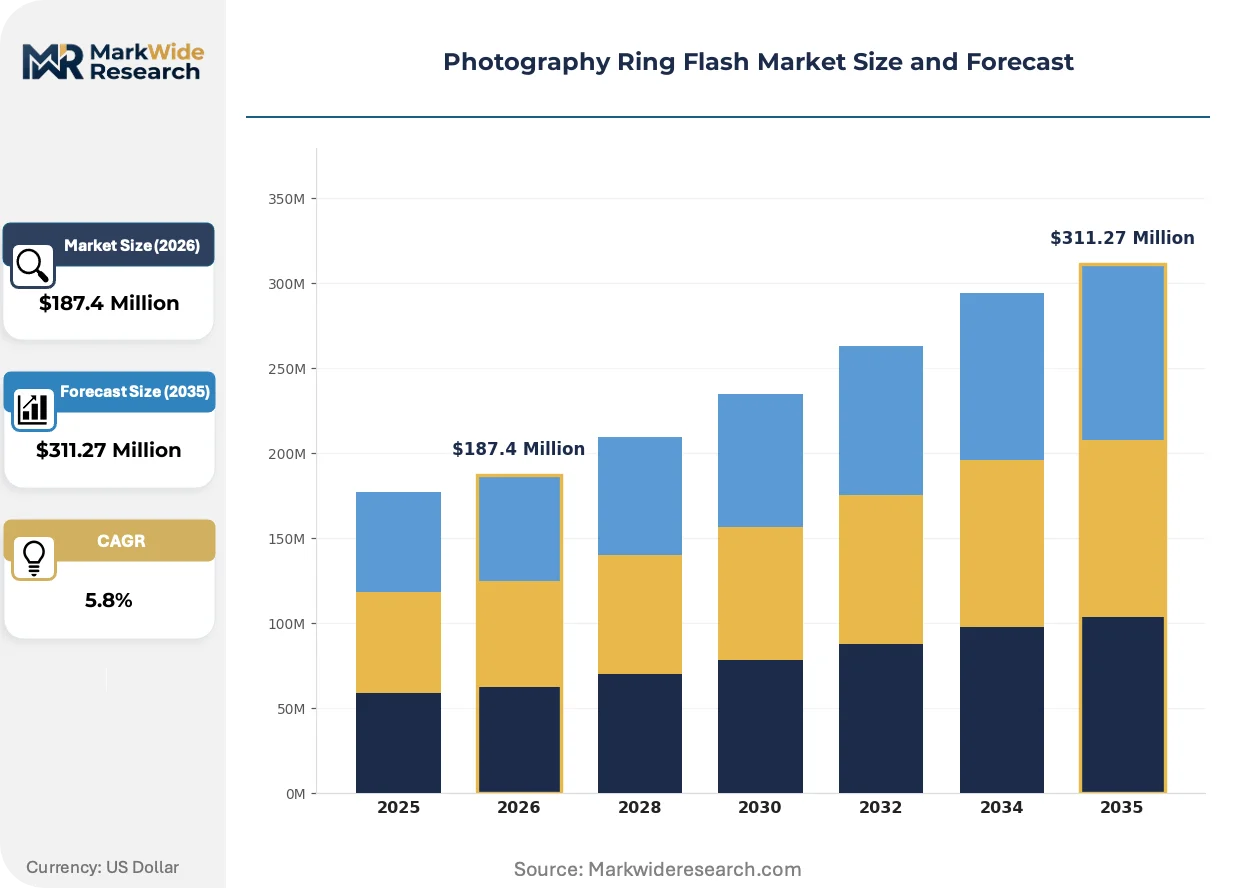
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TTL, Manual, LED, Battery-Powered Application: Macro Photography, Portrait Photography, Fashion Photography, Wildlife Photography End User: Professional Photographers, Hobbyists, Studios, Educational Institutions Technology: Optical, Electronic, Hybrid, Wireless |
| Companies Covered | Godox Photo Equipment Co. Ltd., Neewer Inc., Profoto AB, Westcott, Rotolight, SIRUI, Panasonic Corporation, Canon Inc., Nikon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photography Ring Flash Market Trends and Innovations
Photography ring flash technology is fragmenting along workflow lines as continuous LED and pulsed xenon architectures serve divergent professional needs, with regulatory pressure and procurement model evolution accelerating category restructuring.
LED array ring flash systems is decomposing xenon tube dominance in macro and portrait applications. Dental photography clinics and cosmetic surgery documentation centers are adopting 5600K continuous-light rigs for real-time exposure preview. The technology is decomposing the traditional strobe-recycle workflow, compressing setup times and enabling video-hybrid production from single lighting investments.
Japan's METI Top Runner program is enforcing energy-efficiency benchmarks that exceed global baselines for standby power and luminous efficacy. Manufacturers targeting Japanese distribution must redesign thermal management and driver circuitry to meet these thresholds. Professional-tier products face the steepest redesign costs, pushing some brands toward market exit or premium repositioning.
Direct-to-studio channel control is displacing traditional distributor networks in Western Europe. Profoto and similar premium brands are building owned-service relationships with rental houses and commercial studios. Germany's concentration of fashion and advertising production centers is making this shift most visible in Berlin, Hamburg, and Munich metropolitan clusters.
Photography Ring Flash Market Segmentation
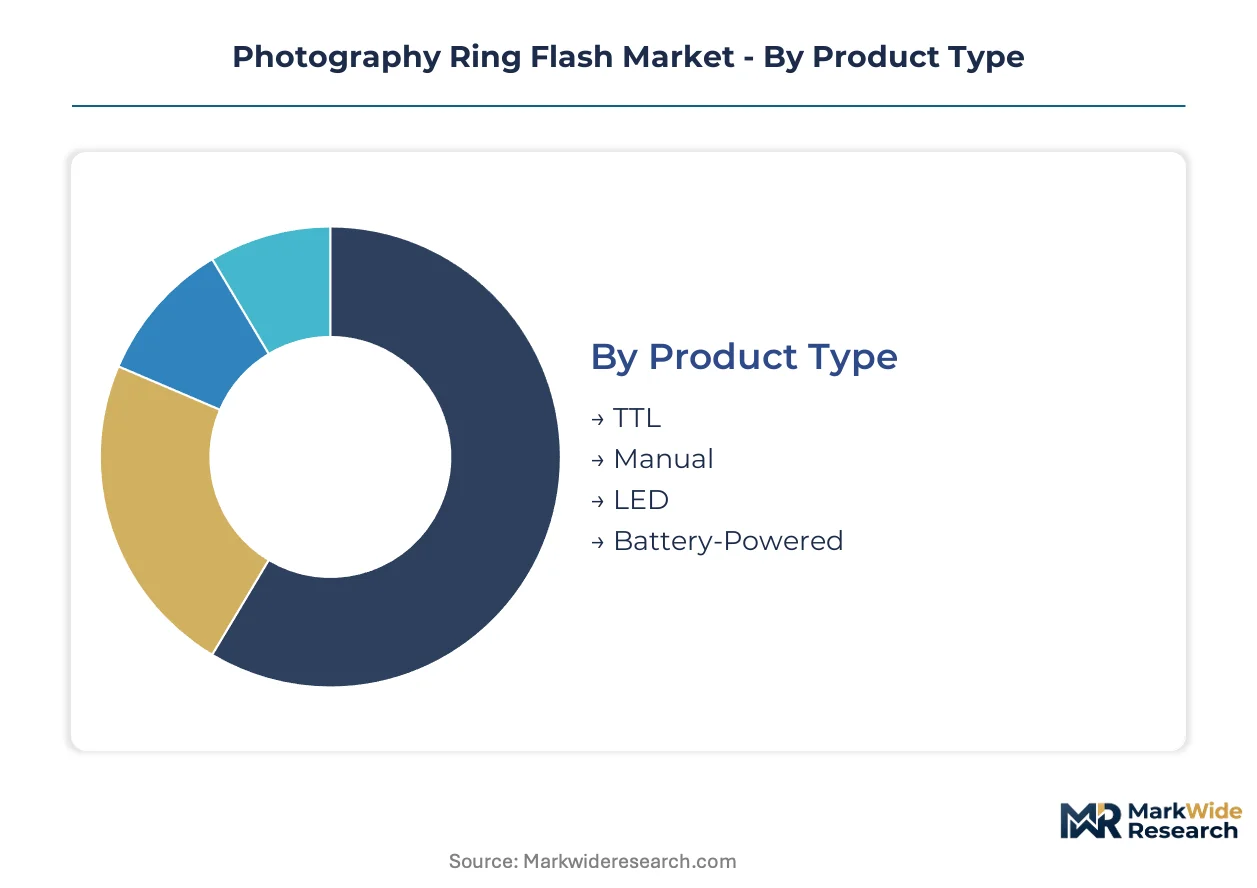
Photography ring flash procurement patterns diverge sharply across user sophistication tiers and workflow requirements. Segment boundaries are hardening as LED continuous-light systems displace legacy xenon architectures in professional settings.
Product Type:
Margins concentrate in TTL-enabled units where through-the-lens metering commands premium positioning against manual alternatives.
- TTL:Automated exposure synchronization with camera metering systems eliminates manual power adjustment in dynamic shooting environments. Wedding and event photographers in Germany and the United States drive replacement cycles as multi-brand compatibility becomes table stakes.
- LED:Continuous-light arrays operating at 3200K-5600K enable real-time exposure preview and video-hybrid workflows. Studio operators in Shenzhen and Los Angeles are standardizing these rigs for portrait and product photography where setup efficiency outweighs absolute output power.
- Manual:Fixed-output designs with dial-based power control serve budget-conscious enthusiasts and controlled-environment specialists. Entry-level Amazon listings dominate volume.
- Battery-Powered:Lithium-ion portable units target location photographers facing aviation transport restrictions on larger power cells. Field documentation teams in Australia and Canada prioritize these for remote access shoots.
TTL holds installed capacity. LED is rotating up the share rankings.
Application:
Volume splits between clinical precision work and creative commercial production, with divergent specification requirements.
- Portrait Photography:Shadowless facial illumination and circular catchlight generation define professional studio standards. Fashion houses in Milan and New York specify color-accurate 5600K output for editorial consistency.
- Macro Photography:Extreme close-subject imaging demands uniform circumferential light distribution without hotspot falloff. Dental clinics in Japan and Switzerland specify these systems for intraoral documentation where shadow elimination affects diagnostic accuracy.
- Fashion Photography:High-output requirements for full-body coverage and rapid recycle times distinguish this segment. Campaign production schedules in Paris and London demand reliability under pressure.
- Wildlife Photography:Extended reach and weather sealing specifications serve nature documentarians. Field biologists in Kenya and Costa Rica deploy portable ring flash for specimen photography where natural light proves insufficient.
Portrait Photography anchors current procurement volumes. Macro Photography is climbing the fastest as medical documentation standards tighten.
End User:
Professional tiers generate disproportionate margin contribution despite smaller absolute unit counts.
- Professional Photographers:Full-time practitioners with established client relationships and equipment depreciation schedules. Commercial studios in Hamburg and Sydney refresh inventories on 24-36 month cycles.
- Studios:Rental houses and production facilities maintaining standardized lighting inventories for client consistency. Multi-location chains in France and the United Kingdom centralize procurement decisions.
- Hobbyists:Enthusiast creators purchasing through e-commerce channels with price elasticity driving brand switching. YouTube tutorial consumption correlates with purchase timing.
- Educational Institutions:University photography programs and technical colleges standardizing equipment kits for student cohorts. Public procurement frameworks in California and Bavaria shape vendor selection.
Professional Photographers command pricing power. Educational Institutions are expanding fastest as curriculum standardization accelerates.
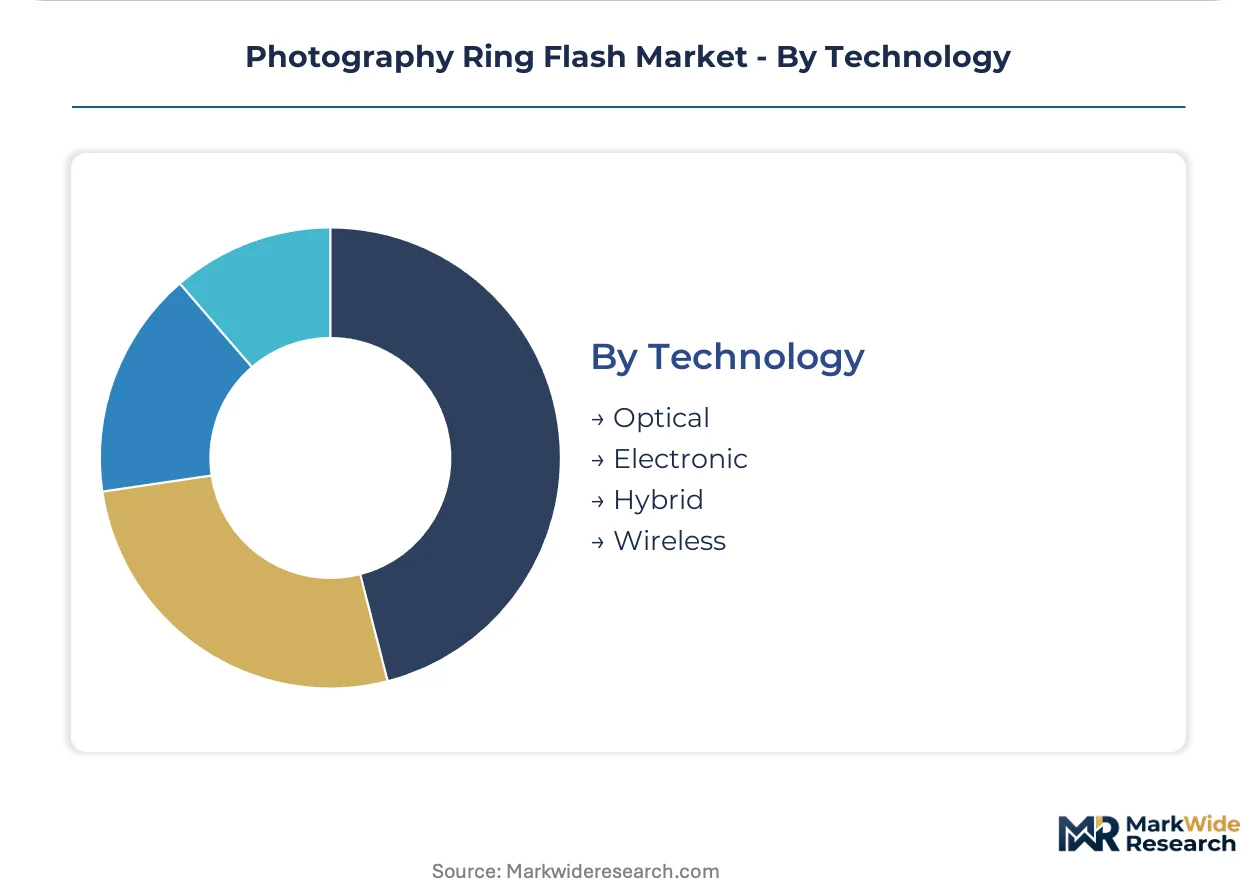
Technology:
Triggering architecture determines reliability in multi-light configurations and shapes ecosystem lock-in dynamics.
- Wireless:Radio-frequency transmission systems operating on 2.4GHz or proprietary bands eliminate line-of-sight constraints. FCC Part 15 compliance in the United States and CE marking in Europe create certification barriers for new entrants.
- Hybrid:Dual-mode systems supporting both optical slave and radio-frequency triggering for backward compatibility. Rental houses in Toronto and Amsterdam specify these for flexible fleet deployment.
- Electronic:Hardwired sync connections via PC socket or proprietary ports for absolute reliability in interference-dense environments. Legacy studio infrastructure in Chicago and Tokyo retains these for mission-critical applications.
- Optical:Line-of-sight slave triggering using preflash detection faces obsolescence pressure from radio systems. Remaining demand concentrates in entry-level bundled kits.
Wireless dominates new installations. Hybrid configurations are gaining share fastest as rental fleets seek operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and regulatory harmonization initiatives are redirecting manufacturing investment and procurement patterns across major photography equipment markets. Fiscal support for domestic electronics assembly in Asia and tightening energy-efficiency mandates in Europe are creating divergent competitive conditions for ring flash producers.
United States
Commercial studios in Los Angeles and New York drive professional-grade equipment refresh cycles as content production professionalizes. FCC Part 15 compliance for wireless triggering systems creates certification barriers that favor established suppliers with testing infrastructure. Seattle and Austin metropolitan clusters concentrate post-production facilities that influence upstream lighting procurement specifications.
Germany
Fashion houses in Berlin, Hamburg, and Munich specify color-accurate 5600K output for editorial consistency, anchoring premium-tier demand. REACH restrictions on hazardous substances in circuit boards accelerate consolidation among certified manufacturers. The Ruhr Valley industrial corridor hosts specialized electronics assemblers serving studio rental houses with repairable, modular designs.
China
E-commerce channel density and manufacturing cluster concentration in Shenzhen compress cost curves for enthusiast-grade equipment. SAMR mandatory CCC certification creates parallel compliance tracks for brands serving domestic and export demand. The Pearl River Delta ecosystem enables captive production of LED driver circuitry and thermal management components.
Japan
Dental clinics in Tokyo and Osaka specify ring flash systems for intraoral documentation where shadow elimination affects diagnostic accuracy. METI Top Runner program enforces energy-efficiency benchmarks exceeding global baselines for standby power. Nagoya industrial corridor hosts precision optics fabricators supplying LED array components to regional equipment integrators.
India
University photography programs in Maharashtra and Karnataka standardize equipment kits for student cohorts, creating institutional volume anchors. PLI scheme incentives for electronics manufacturing create local assembly opportunities for brands serving South Asian demand. Bengaluru technology corridor concentrates post-production startups influencing lighting procurement preferences.
Photography Ring Flash Market Competitive Landscape
Player mix skews toward vertically integrated electronics specialists and premium-tier lighting houses with direct channel control. The vendor base separates into three strategic archetypes: Shenzhen-based scale manufacturers absorbing certification costs across high-volume lines, Scandinavian premium brands anchoring position through studio-direct relationships, and Amazon-centric price competitors targeting hobbyist segments. Consolidation pressures concentrate among optical triggering legacy suppliers facing substitution by radio-frequency systems, while M&A activity targets wireless-TTL technology assets and regional distribution networks.
Within the vertically integrated tier, Godox Photo Equipment Co. Ltd. and Neewer Inc. exemplify Shenzhen-based scale manufacturers leveraging captive production to absorb CE marking and FCC certification costs across LED ring flash portfolios. Profoto AB occupies a position representing Scandinavian premium-tier positioning with direct-to-studio channel control in Western Europe. These three anchors illustrate the structural divergence between cost-competitive enthusiast supply and professional-grade ecosystem lock-in.
| Leading Market Players |
|---|
| Godox Photo Equipment Co. Ltd. |
| Neewer Inc. |
| Profoto AB |
| Westcott |
| Rotolight |
| SIRUI |
| Panasonic Corporation |
| Canon Inc. |
| Nikon Corporation |
| Others |
Pricing and Supply Chain Analysis
LED driver circuitry substitution for xenon tube assemblies is redrawing procurement geography toward Shenzhen manufacturing clusters while collapsing the historical premium attached to Japanese and German specialty gas discharge components. This input shift enables cost absorption across high-volume production runs but simultaneously compresses margin pools for legacy suppliers tethered to xenon architectures.
Pricing Analysis
Cost-plus contracts with xenon tube indexation dominate legacy procurement relationships between European studio rental houses and Japanese component suppliers. Three-tier pricing structure across premium, standard, and economy levels separates Profoto's direct-channel positioning from Godox's e-commerce penetration and Neewer's Amazon-centric hobbyist targeting. Pricing pressure stems from Shenzhen manufacturers absorbing CE marking and FCC certification costs across LED ring flash portfolios. Hobbyists exhibit highest price sensitivity, while professional studios prioritize color accuracy and wireless-TTL reliability over unit economics.
Supply Chain Analysis
China, Japan, and Germany anchor distinct supply chain functions for photography ring flash production. Shenzhen feeds LED array fabrication and thermal management component sourcing, Nagoya supplies precision optics for Japanese domestic brands, and the Ruhr Valley hosts specialized electronics assemblers serving repairable design mandates. Raw material dependencies span lithium-ion cells from South Korea, rare earth phosphors for LED color rendering, and copper winding stock for driver transformers. Single-source vulnerability concentrates in xenon tube gas discharge technology held by two Japanese suppliers. Distribution runs through Amazon Marketplace for enthusiast tiers, direct-to-studio relationships for premium positioning, and educational procurement frameworks for institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photography ring flash demand sits in early-cycle expansion as university photography programs standardize equipment kits and content creator professionalization extends beyond traditional studio boundaries.
For Market Incumbents: Secure wireless-TTL patent positions against Shenzhen manufacturers reverse-engineering radio-frequency triggering protocols. Consolidate certification infrastructure investments to absorb CE marking, FCC Part 15, and CCC testing costs across product generations. Channel control through direct studio relationships in Berlin, Hamburg, and Munich rental houses defends margin position against Amazon-centric price competition. For New Entrants and Emerging Players: Differentiate on repairable design compliance with EU Ecodesign for Sustainable Products Regulation requirements ahead of incumbent repositioning cycles. Target educational institution procurement frameworks in California and Bavaria where standardization creates volume anchors with lower competitive density. Deploy hybrid wireless-optical triggering architectures to capture rental fleet flexibility demands in Toronto and Amsterdam. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors vertically integrated LED electronics specialists over xenon-dependent legacy suppliers. Long-term viability centers on captive manufacturing scale and certification infrastructure ownership. Acquisition targets should demonstrate SAMR CCC compliance for China domestic access and METI Top Runner energy-efficiency redesign capability. Wireless-TTL protocol standardization across Canon, Nikon, and Sony camera bodies serves as the critical inflection signal for multi-brand compatibility value capture.| Strategic Initiative | Industry Significance |
|---|---|
| LED Continuous-Light Platform Launch | Enables video-hybrid workflows for portrait studios in Los Angeles and Shenzhen compressing setup times. |
| Wireless-TTL Protocol Integration | Eliminates optical triggering obsolescence risk while capturing multi-light automation demand in commercial studios. |
| Educational Institution Partnership | Locks in standardized equipment kit procurement through California and Bavaria public framework compliance. |
| Repairable Design Certification | Anticipates EU Ecodesign for Sustainable Products Regulation enforcement while differentiating against disposable alternatives. |
| Shenzhen Manufacturing Scale-Up | Absorbs CE marking and FCC Part 15 certification costs across high-volume LED ring flash production lines. |
Research Methodology
A standing panel of commercial studio owners, university photography program directors, dental clinic equipment managers, and e-commerce category buyers provided ongoing calibration throughout the research process. Primary fieldwork combined structured interviews with secondary validation against customs records, Amazon Marketplace transaction data, and SAMR CCC certification filings. Bottom-up demand modeling across TTL, LED, manual, and battery-powered product tiers triangulated against top-down macroeconomic indicators for professional services and educational expenditure.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application workflow, end-user sophistication tier, and triggering technology architecture. CAGRs were derived from fitted growth curves incorporating educational institution procurement acceleration, content creator professionalization rates, and regulatory compliance timeline compression. Industry-specific forecast inputs captured aviation battery transport rule divergence across FAA, EASA, and CAAC authorities.
Material uncertainties — regulatory timeline shifts, xenon tube supply disruption, and wireless protocol standardization delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding LED cost curve compression and REACH compliance infrastructure consolidation among certified manufacturers. Recalibration cycles align with material shifts in EU Ecodesign enforcement schedules and China domestic e-commerce penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Video Microscopes Market
Imaging
Photography Equipment Market
Imaging
Digital Microscope Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Borescope Market
Imaging
Webcam Market
Imaging
Gel Imaging Documentation Market
Imaging
Specific Imaging Solution Market
Imaging
Thermal Imaging Systems Market
Imaging
Camera Technology Market
Imaging
Handheld Imaging Devices Market
Imaging
CMOS Camera Market
Imaging
Industrial Camera Market
Imaging
Computer Aided Detection Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
LCD Digital Microscope Market