
 Digital Recording System Market | 2026-2036
Digital Recording System Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Recording System Market Analytics
The EU AI Act is expanding compliance obligations for cloud-based recording platforms that deploy automated transcription and content moderation algorithms. Sony Corporation leverages its cinema camera heritage to dominate high-end video capture segments, while Blackmagic Design Pty. Ltd. competes aggressively on price-performance in digital cinema workflows. Zoom Corporation anchors the portable audio recorder category through deep podcast creator loyalty and firmware innovation cycles.
A digital recording system encompasses hardware and software architectures that convert analog sound or optical images into discrete digital signals, typically sampling audio at 44.1 kHz or higher and video at 10-bit 4:2:2 color depth for professional fidelity. These systems serve broadcast, cinema, music production, and corporate communication by enabling non-destructive editing, cloud collaboration, and multi-format distribution. Cloud-based solutions are capturing the fastest expansion as remote production workflows normalize, while analog recording persists in niche audiophile segments where hardware resale margins remain elevated. Digital mixers concentrate profit pools in live event and broadcast verticals due to Dante networking integration and persistent software upgrade revenue.
FCC equipment authorization mandates shape US market access for wireless microphone and transmitter modules, while EU RoHS and REACH restrictions govern substance thresholds in circuit assemblies and battery packs. Japan's METI enforces energy efficiency benchmarks for battery-powered field recorders, affecting product design cycles for OEMs serving East Asian distribution channels. Stakeholders must monitor evolving encryption export controls and regional content localization mandates that could fragment platform deployment architectures.
Market Dynamics
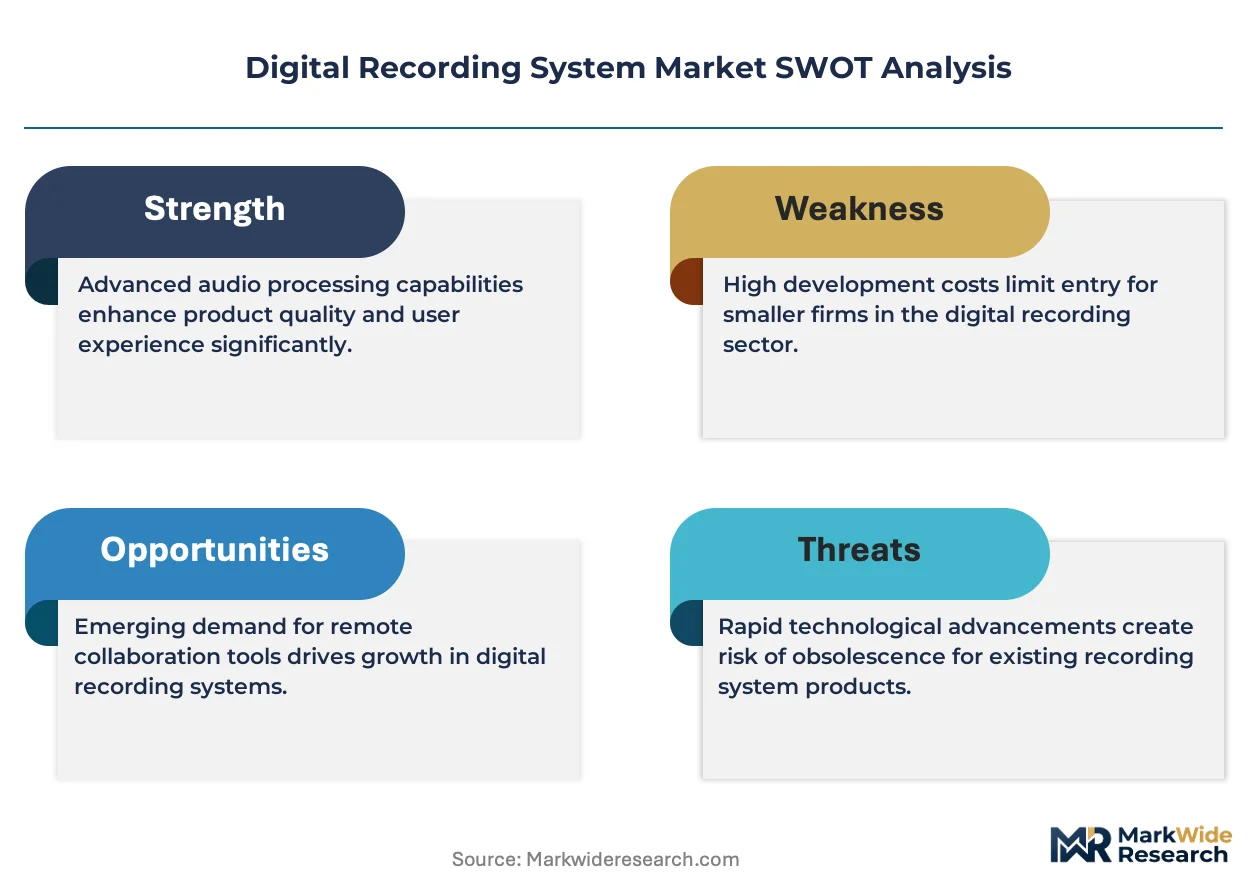
Cloud-native production workflows are compressing hardware refresh cycles while forcing incumbent vendors to rearchitect software licensing models around subscription revenue streams.
Growth Catalysts
- Remote podcast production:Independent creators in Los Angeles and New York clusters demand portable multi-track systems with Dante networking. This end-use segment is pulling field recorder innovation toward battery efficiency and wireless redundancy.
- EU AI Act compliance:Automated transcription and content moderation algorithms now face mandatory risk classification. Cloud-based recording platforms must reengineer data processing pipelines to meet these obligations.
- 10-bit 4:2:2 color depth:Cinema and broadcast verticals require this specification for professional fidelity. Camera manufacturers are prioritizing sensor and codec development to capture this specification tier.
Market Restraints
- Lithium-ion supply concentration:Battery pack sourcing for field recorders depends on East Asian cell manufacturers. OEMs face input cost volatility and logistics concentration risk.
- FCC equipment authorization timelines:Wireless microphone and transmitter modules require certification before US market entry. These procedural delays extend product launch windows by quarters.
- Analog hardware resale margins:Niche audiophile segments sustain elevated secondhand prices for vintage tape machines. This substitute threat constrains pricing power for entry-level digital converters.
Strategic Opportunities
- India content creator economy:Underpenetrated relative to per-capita media consumption growth. Localized firmware and regional language interfaces could capture this white space.
- ISO/IEC 27001 certification:Enterprise buyers now mandate this information security standard for cloud recording platforms. Vendors achieving this certification unlock corporate communication verticals.
- AI-powered noise reduction:Machine learning inference at the edge converges with low-latency DSP architectures. This technology pairing enables real-time processing on battery-powered devices.
Industry Challenges
- Dante networking certification:Live event and broadcast verticals require this audio-over-IP standard. Engineering teams must maintain protocol expertise alongside proprietary codec development.
- Legacy analog integration:Studios with substantial tape machine investments face complex signal path reconfiguration. Hybrid workflow design consumes professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Recording System Market |
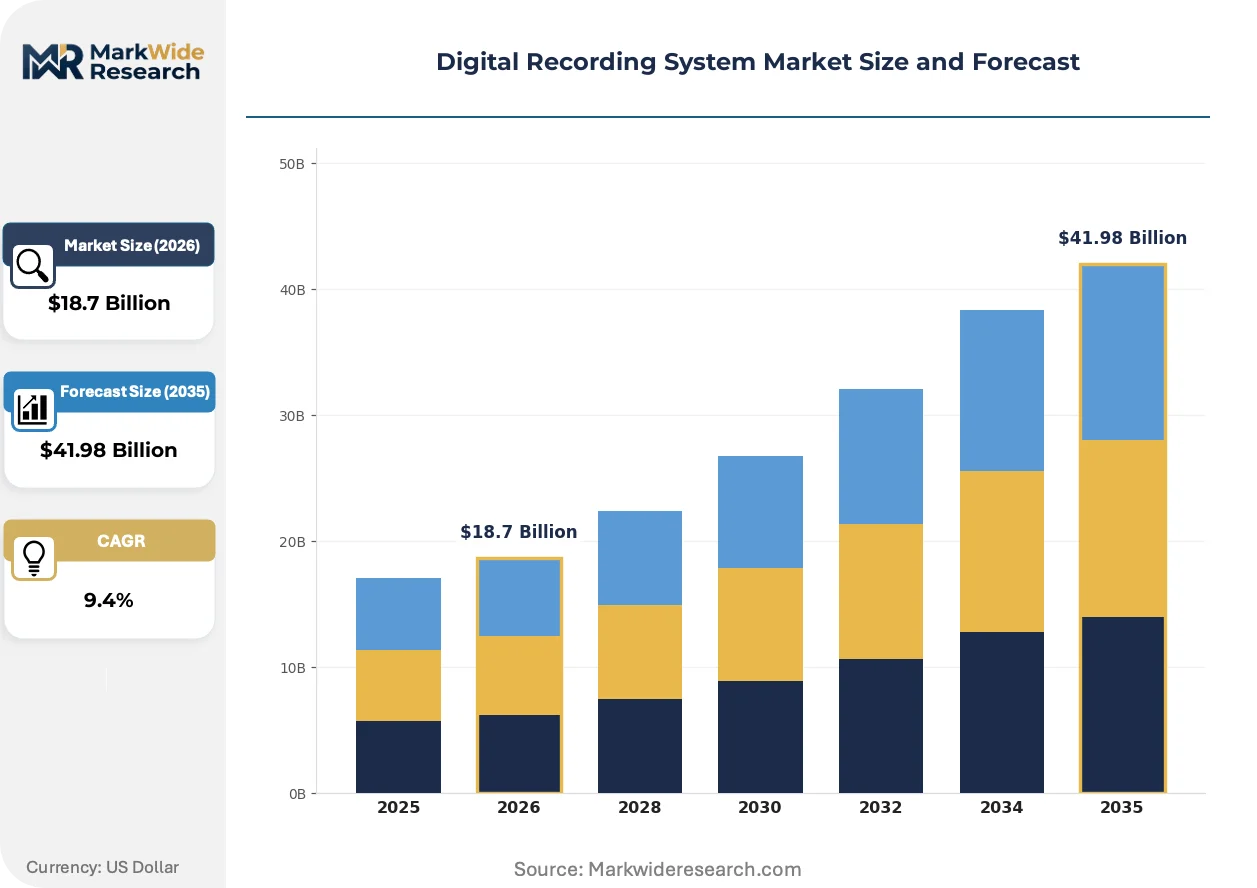
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Devices, Video Cameras, Voice Recorders, Digital Mixers End User: Musicians, Filmmakers, Podcasters, Education Institutions Technology: Analog Recording, Digital Recording, Cloud-Based Solutions, Hybrid Systems Deployment: On-Premise, Cloud, Hybrid, Remote Access |
| Companies Covered | Sony Corporation, Olympus Corporation, Zoom Corporation, Koninklijke Philips N.V., Panasonic Corporation, JVCKENWOOD Corporation, Blackmagic Design Pty. Ltd., ARRI AG, Ricoh Imaging Company Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Recording System Market Evolving Landscape
Computational photography and edge AI are redefining capture device architectures, while regulatory fragmentation around content authentication is forcing platform-level investments in provenance tracking.
Neural noise suppression is automating post-production workflows for podcast creators and field journalists. These algorithms now run on ARM-based DSP cores within portable recorders. Adoption is accelerating among independent creators who lack dedicated audio engineering support, compressing the traditional separation between capture and finished content.
REACH substance restrictions are reshaping circuit assembly supply chains for EU-bound equipment. Manufacturers must document SVHC thresholds in solder joints and battery housings. Professional field recorder OEMs serving European distribution channels are requalifying component vendors to maintain CE marking compliance.
Creator economy participants are consolidating purchasing around integrated hardware-software bundles. Subscription platforms that include cloud storage and collaborative editing are displacing perpetual-license DAW sales. This pattern concentrates most visibly in United States media production clusters where creator tooling budgets flow through platform-native marketplaces.
Digital Recording System Market Segmentation
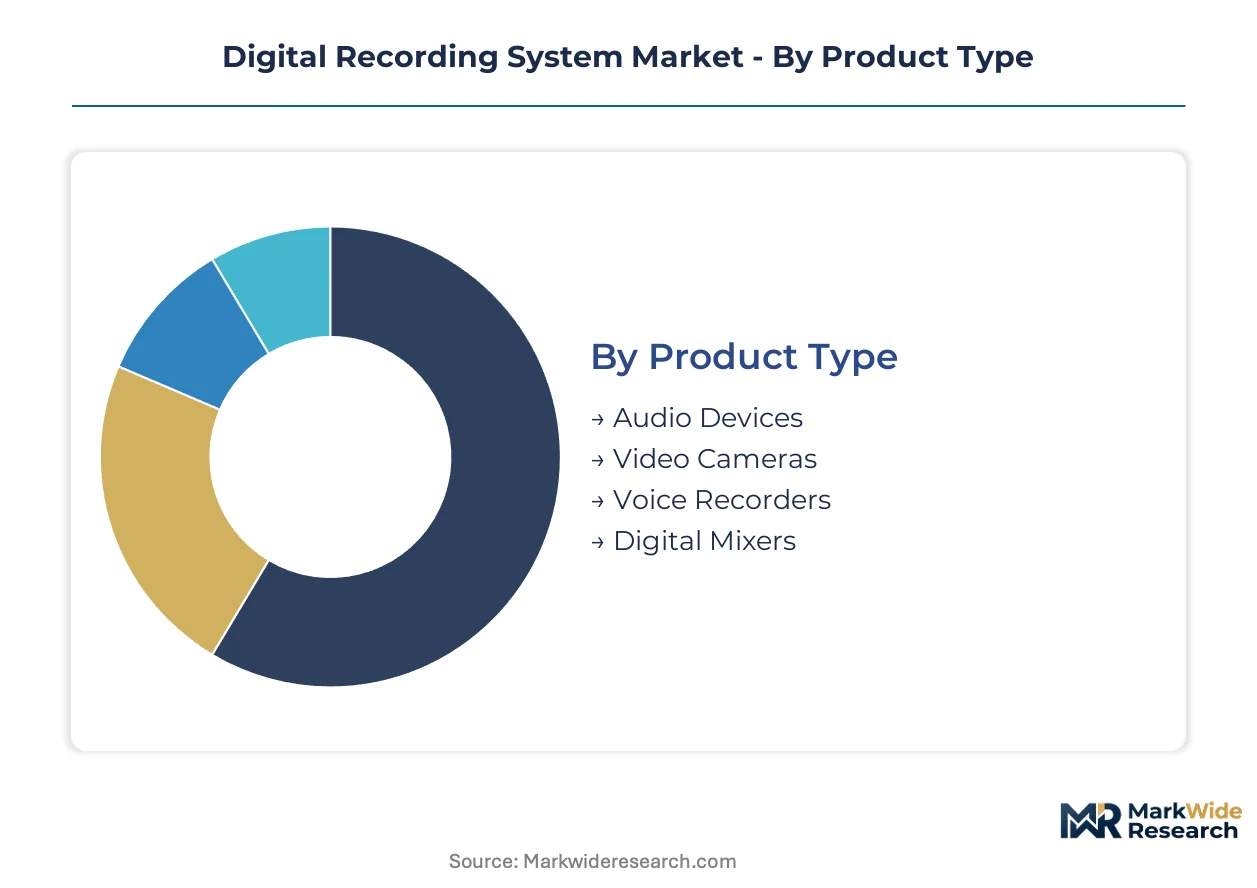
Segmentation reveals how technical specifications, deployment architectures, and creator workflows fragment purchasing patterns across the digital recording system landscape. Understanding these divisions exposes where hardware margins concentrate versus where subscription revenue scales.
Product Type:
Technical sophistication and integration depth separate winners from commodity players across hardware categories.
- Audio Devices:Field recorders and USB interfaces sample at 44.1 kHz minimum, with 96 kHz/24-bit specifications commanding premium positioning. Podcasters in Los Angeles and New York clusters drive demand for multi-track portability with Dante networking integration.
- Video Cameras:Cinema bodies capture 10-bit 4:2:2 color depth for broadcast compliance, while mirrorless hybrids serve creator economy price points. Filmmakers prioritize sensor size and codec flexibility over resolution specifications alone.
- Voice Recorders:Single-purpose handheld units emphasize battery efficiency and one-touch operation. Journalists and interviewers favor discrete form factors with extended recording capacity.
- Digital Mixers:Dante-enabled consoles anchor live event and broadcast workflows through persistent software upgrade revenue. Physical fader banks persist despite touchscreen alternatives.
Mature deployment sits with digital mixers in fixed installation environments. Newer deployment is concentrated in portable audio devices serving distributed creator teams.
End User:
Professional credential requirements and budget authority create distinct purchasing cadences across customer types.
- Musicians:Home studio builders prioritize AD/DA converter quality and low-latency monitoring. This segment exhibits hardware loyalty cycles tied to album production schedules rather than annual refresh patterns.
- Filmmakers:Production companies amortize camera bodies across project budgets, prioritizing rental house compatibility and lens mount ecosystems. Color science consistency matters more than raw specification sheets.
- Podcasters:Independent creators consolidate spending around integrated hardware-software bundles with cloud collaboration features. Firmware innovation cycles and creator community loyalty anchor brand selection.
- Education Institutions:Universities and conservatories balance curriculum standardization against procurement budget constraints. Volume purchasing agreements and training certification programs influence vendor selection.
Volume concentration rests with education institutions through multi-year replacement cycles. Margin expansion is climbing the fastest among podcasters adopting subscription-integrated workflows.
Technology:
Signal processing architecture determines workflow flexibility, archival durability, and compliance surface area.
- Analog Recording:Tape machines and vinyl cutting lathes persist in niche audiophile segments where hardware resale margins remain elevated. Studios with substantial legacy investments face complex signal path reconfiguration for hybrid workflows.
- Digital Recording:PCM-based systems at 44.1 kHz/16-bit minimum enable non-destructive editing and multi-format distribution. This architecture dominates broadcast, cinema, and music production verticals.
- Cloud-Based Solutions:Remote production workflows normalize browser-based collaboration and automated transcription pipelines. EU AI Act compliance obligations now mandate risk classification for content moderation algorithms.
- Hybrid Systems:Edge capture with cloud post-production bridges latency requirements and distributed team access. Corporate communication verticals increasingly mandate ISO/IEC 27001 certification for these deployments.
Installed base weight sits with digital recording in professional facilities. Steepest expansion trajectory belongs to cloud-based solutions as remote production workflows normalize.
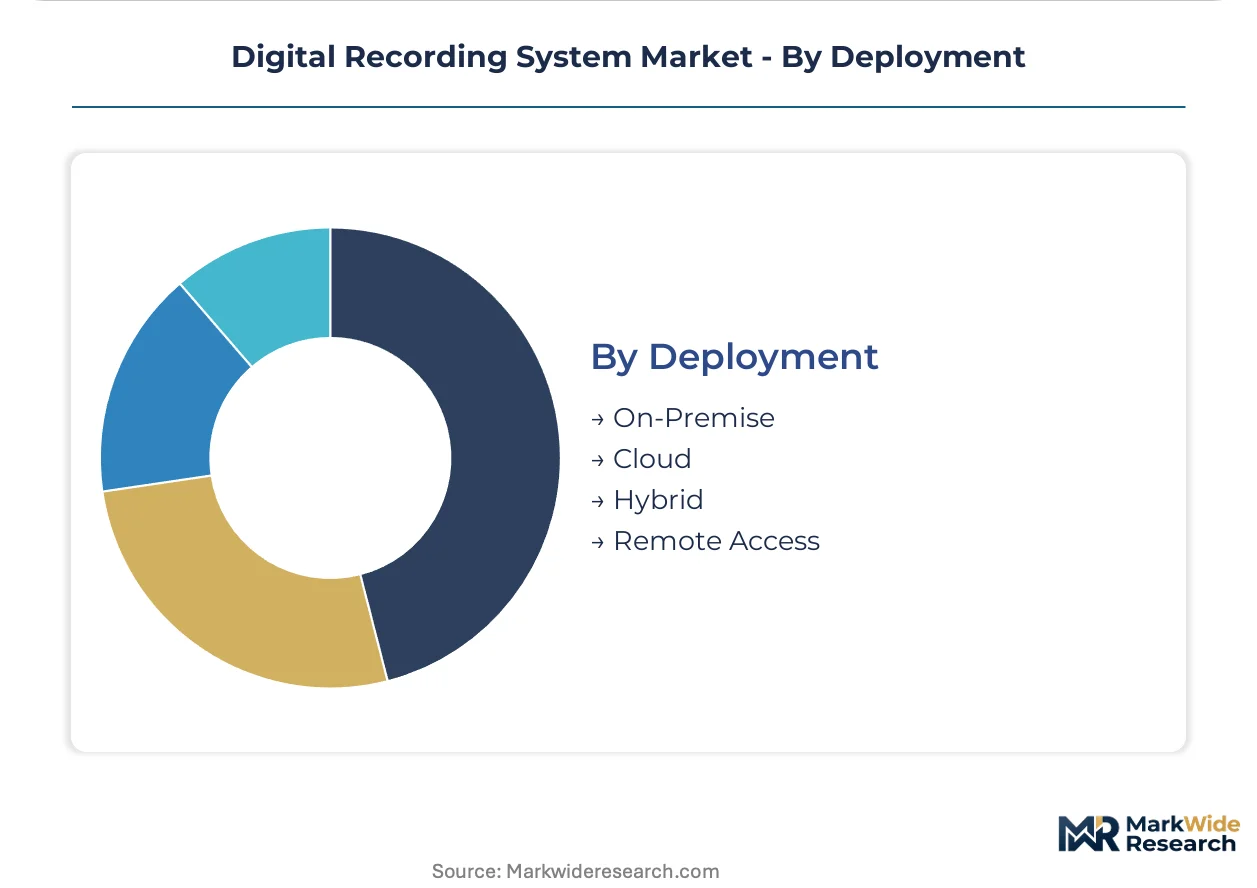
Deployment:
Infrastructure control and data residency requirements shape architecture selection across regulated and unregulated use cases.
- On-Premise:Local hardware ownership satisfies broadcasters and government entities with strict content custody requirements. Capital expenditure treatment and depreciation schedules appeal to established production companies.
- Cloud:Subscription licensing converts hardware refresh cycles into recurring revenue while enabling distributed team collaboration. FCC equipment authorization timelines for wireless modules still require physical hardware certification.
- Hybrid:Local capture with cloud storage and editing balances latency performance against backup redundancy. Live event verticals require this architecture for real-time monitoring with post-event distribution.
- Remote Access:Browser-based control surfaces and file management enable location-independent production supervision. Security authentication and encryption export controls complicate cross-border deployments.
Legacy dominance persists with on-premise installations in broadcast and cinema facilities. Emerging adoption clusters around remote access as creator economy participants prioritize flexibility over physical presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles and New York anchor creator economy demand for portable multi-track systems with Dante networking, while regulatory fragmentation across major economies reshapes product compliance and market access strategies.
United States
Podcasters and independent content creators in Los Angeles and New York media production clusters pull field recorder innovation toward battery efficiency and wireless redundancy. FCC equipment authorization mandates shape US market access for wireless microphone and transmitter modules, extending product launch windows. Corporate communication verticals in these coastal hubs increasingly mandate ISO/IEC 27001 certification for cloud recording platforms.
Germany
Broadcast and live event verticals in Berlin and Munich drive demand for Dante-enabled digital mixers with persistent software upgrade revenue. EU RoHS and REACH restrictions govern substance thresholds in circuit assemblies and battery packs for EU-bound equipment. Professional field recorder OEMs serving German distribution channels are requalifying component vendors to maintain CE marking compliance.
Japan
Camera manufacturers in Tokyo and Osaka prioritize sensor and codec development for 10-bit 4:2:2 color depth specifications in cinema and broadcast applications. METI enforces energy efficiency benchmarks for battery-powered field recorders, affecting product design cycles for OEMs serving East Asian distribution channels. Hybrid workflow design for studios with substantial tape machine investments consumes professional services capacity in these metropolitan centers.
United Kingdom
Education institutions in London and Manchester balance curriculum standardization against procurement budget constraints through multi-year replacement cycles. GDPR compliance obligations intersect with cloud-based recording platform deployments, mandating data residency controls. Volume purchasing agreements and training certification programs influence vendor selection across these academic clusters.
India
Content creator economy expansion in Mumbai and Bengaluru remains underpenetrated relative to per-capita media consumption growth. BIS standards and TRAI regulations shape equipment certification and spectrum allocation for wireless recording devices. Localized firmware and regional language interfaces could capture this white space as creator tooling budgets flow through platform-native marketplaces.
Digital Recording System Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with cinema heritage and specialized audio innovators with deep creator loyalty. Incumbent vendors face pressure to rearchitect software licensing models around subscription revenue streams as cloud-native production workflows compress hardware refresh cycles. Three archetypes dominate: heritage cinema camera manufacturers, portable audio specialists with firmware innovation cycles, and broadcast equipment conglomerates with Dante networking integration. Strategic moves concentrate on M&A for codec and sensor technology, plus geographic expansion into underpenetrated creator economies.
Within the heritage cinema tier, Sony Corporation and ARRI AG exemplify sensor and color science positioning built on decades of broadcast and theatrical deployment. Zoom Corporation anchors the portable audio specialist archetype through deep podcast creator loyalty and rapid firmware iteration. Blackmagic Design Pty. Ltd. occupies a price-performance position in digital cinema workflows, competing aggressively on codec flexibility against established premium tiers. These three represent distinct strategic postures: vertical integration into proprietary imaging pipelines, community-driven product development cycles, and aggressive margin compression through modular system architecture.
| Leading Market Players |
|---|
| Sony Corporation |
| Olympus Corporation |
| Zoom Corporation |
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| JVCKENWOOD Corporation |
| Blackmagic Design Pty. Ltd. |
| ARRI AG |
| Ricoh Imaging Company Ltd |
| Others |
Value Network & Pricing Analysis
EU REACH substance restrictions gate qualified supply for European-bound field recorders and digital mixers, with SVHC documentation requirements filtering component vendors and sustaining premium-tier pricing access for CE-marked equipment. Manufacturers serving German broadcast verticals absorb compliance costs into landed pricing, while buyers lacking REACH-ready supply chains face market exclusion.
Pricing Analysis
Value-based pricing anchored to Dante networking integration and firmware upgrade continuity dominates live event and broadcast verticals. Pricing stratifies across professional certification tiers, with ISO/IEC 27001-certified cloud platforms commanding corporate communication premiums over uncertified alternatives. Cost compression in entry-level audio interfaces intensifies as creator economy bundles displace perpetual-license DAW sales. Podcasters in Los Angeles and New York clusters exhibit lowest price sensitivity due to platform-integrated workflow loyalty, while education institutions face acute budget constraints driving volume procurement negotiations.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion cells compel field recorder OEMs to qualify suppliers across China, South Korea, and Japan. Battery pack assembly draws from East Asian cell manufacturers, with Sony and Panasonic heritage brands anchoring premium-tier sourcing. Single-source vulnerability concentrates in rare earth magnet supply for microphone capsules, exposing wireless transmitter module production to export control disruption. Distribution runs through authorized dealer networks for professional cinema equipment, while creator economy audio devices increasingly flow through direct-to-consumer platform marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native production workflows are displacing on-premise hardware refresh cycles, with edge AI inference engines replacing legacy DSP architectures in portable recording devices.
For Market Incumbents: Deepen firmware innovation cycles to defend podcast creator loyalty against subscription-platform bundling threats. Secure backward integration into ARM-based DSP core supply to reduce dependency on third-party semiconductor vendors. Accelerate ISO/IEC 27001 certification investment to capture corporate communication verticals mandating information security compliance.
For New Entrants and Emerging Players: EU AI Act risk classification requirements in Germany open a window for compliance-native cloud recording platforms to capture broadcast and live event verticals. Target underpenetrated India content creator economy through localized firmware and Hindi-language interfaces. Pursue white-label partnerships with platform-native marketplaces serving United States media production clusters.
For Investors and Strategic Acquirers: Persistent software upgrade revenue attach rates in Dante-enabled digital mixers is the leading indicator that live event and broadcast equipment vendors warrant long-term viability framing. Prioritize acquisition targets with proprietary codec development capabilities and established CE marking compliance infrastructure. Watch FCC equipment authorization timeline extensions as the signal for wireless module supply constraints affecting hardware launch cadence.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 27001 Certification Investment | Unlocks enterprise cloud recording platform procurement mandating information security standards. |
| Dante Networking Integration Partnership | Captures live event verticals requiring audio-over-IP protocol compatibility for broadcast workflows. |
| Edge AI Noise Reduction Development | Enables real-time processing on battery-powered field recorders for independent podcast creators. |
| India Localization Program | Addresses underpenetrated content creator economy through regional language firmware interfaces. |
| REACH Compliance Infrastructure Buildout | Maintains CE marking access for EU-bound professional recording equipment against substance restrictions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this digital recording system market assessment. Primary interviews with broadcast engineering directors, podcast production facility operators, OEM procurement managers, and cloud platform product leads combined with FCC equipment authorization databases, EU ECHA SVHC registrations, METI energy efficiency filings, and SEC 10-K disclosures from diversified electronics conglomerates. Bottom-up unit shipment modeling triangulated against top-down value estimates derived from disclosed segment revenues.
Granularity-level modeling deployed product type, end user vertical, deployment architecture, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from segment-level growth rate synthesis applied to base-year value allocations. Forecast inputs incorporated Dante networking adoption curves in live event verticals, lithium-ion cell price trajectories affecting field recorder manufacturing costs, and EU AI Act implementation timelines reshaping cloud platform compliance investment.
The model assumes a particular technology adoption path; alternative pathways for edge AI inference engines replacing cloud-based post-production would alter the outlook for hybrid system deployment architectures. Deviation in FCC equipment authorization processing timelines or REACH substance restriction expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
SAS Hard Disk Drives Market
Data Storage
China Solid-State Drive Market
Data Storage
Americas Flash Memory Market
Data Storage
Transparent Cache Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Global Portable Data Storage Market
Data Storage
Powered Storage Devices Market
Data Storage
Next-Generation Storage Market
Data Storage
Storage Virtualization Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Hardware Storage Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
Transparent Caching Market
Data Storage
Data Center Storage Solutions Market