
 CCD Image Sensors Market | 2026-2036
CCD Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
CCD Image Sensors Market Outlook
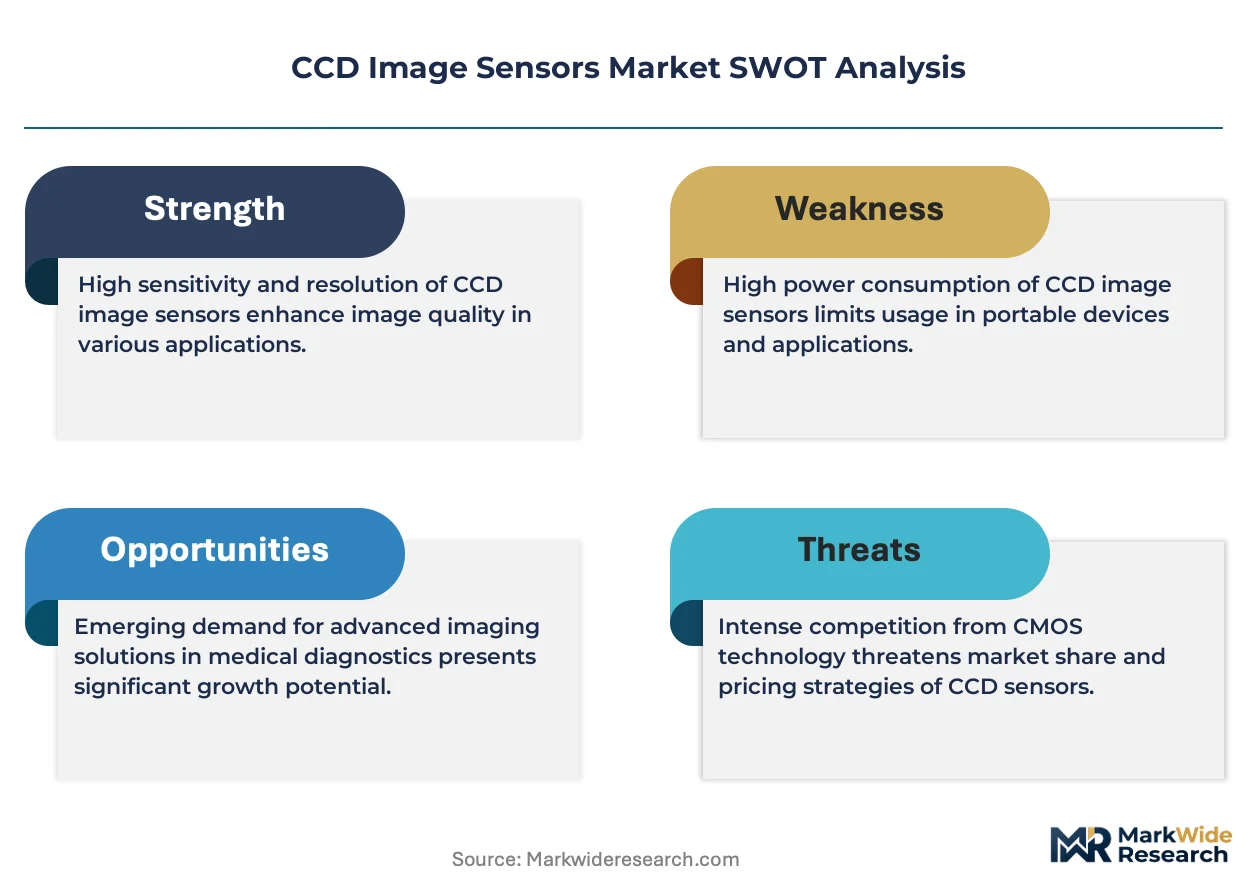
The EU RoHS directive is decoupling legacy CCD manufacturing from lead-based solder processes, forcing fabs to retool bonding and packaging lines. Onsemi leverages its vertically integrated foundry network to sustain wafer supply for high-reliability industrial CCDs. Sony Semiconductor Solutions Corporation anchors the premium segment through proprietary back-illuminated architectures. Hamamatsu Photonics dominates niche scientific instrumentation with cryogenically cooled sensor modules.
CCD image sensors are charge-coupled devices that transfer photogenerated charge packets through a series of MOS capacitors under clocked gate voltages, typically fabricated on epitaxial silicon wafers with pixel pitches ranging from 2.2 µm to 24 µm depending on resolution and sensitivity targets. Their primary commercial purpose is high-fidelity photon-to-electron conversion in applications where uniform pixel response and low read noise outweigh CMOS speed advantages. Back-illuminated CCDs command premium positioning in microscopy and astronomical imaging due to enhanced quantum efficiency from thinned substrates with rear-side illumination. Medical imaging end users drive stable volume for frame-transfer architectures in fluoroscopy and digital radiography systems. Industrial automation applications favor interline-transfer designs for their electronic shutter capability without mechanical complexity.
The EPA regulates hazardous substance thresholds in US-manufactured CCD assemblies, while ECHA REACH restrictions govern cadmium and lead content in European-bound sensor modules. Japan's METI enforces energy-efficiency benchmarks that shape power budgets for consumer electronics CCD integration. The EU AI Act's emerging requirements for imaging system traceability will extend compliance obligations into surveillance and robotics deployments. Stakeholders must weigh the cost of sustaining CCD production lines against the accelerating performance convergence of stacked CMOS alternatives.
Market Dynamics
CCD fabrication is consolidating around legacy specialty foundries as mainstream capacity pivots to CMOS, concentrating supply for scientific and medical-grade sensors among a shrinking pool of qualified suppliers in Japan and the United States.
Growth Catalysts
- EU RoHS exemptions:Time-limited waivers for lead-based solders in high-reliability imaging equipment sustain European demand for CCD modules in industrial inspection systems.
- Back-illuminated architectures:Thinned silicon substrates with rear-side illumination are penetrating fluorescence microscopy, where quantum efficiency above 90% outweighs CMOS cost advantages.
- Hamamatsu-Tokyo cluster:Japan's precision optics corridor maintains concentrated CCD design expertise and captive epitaxial wafer supply for scientific instrumentation.
Market Restraints
- ECHA REACH cadmium thresholds:Restrictions on heavy metals in electronic components force reformulation of CCD packaging materials, extending qualification timelines for European-bound sensors.
- Epitaxial silicon supply concentration:Specialty 6-inch and 8-inch silicon wafers for CCD fabrication depend on a limited number of Japanese and US suppliers, creating input vulnerability.
- CMOS substitution:Stacked backside-illuminated CMOS sensors with global shutter capability are capturing frame-transfer applications in machine vision and broadcast.
Strategic Opportunities
- Cryogenically cooled scientific modules:Astronomical observatories and spectroscopy labs require deep-cooled CCDs where dark current suppression below 0.001 e-/pixel/second remains unmatched.
- US EPA hazardous substance thresholds:Domestic content incentives in federal imaging procurement create preference for US-assembled CCD modules in defense and aerospace applications.
- Digital pathology scanners:Whole-slide imaging systems are adopting large-format CCDs for color fidelity in histology, opening a clinical diagnostic channel distinct from radiology.
Industry Challenges
- Process engineer scarcity:CCD-specific expertise in charge transfer efficiency optimization and buried-channel fabrication is retiring without replacement pipelines in Western universities.
- Dual qualification burden:Manufacturers must simultaneously maintain ISO 13485 for medical imaging and IEC 60601 for radiology equipment, duplicating audit cycles.
- Legacy system integration:Frame-transfer CCDs in installed fluoroscopy suites require signal chain compatibility with 1990s-era digital acquisition hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CCD Image Sensors Market |
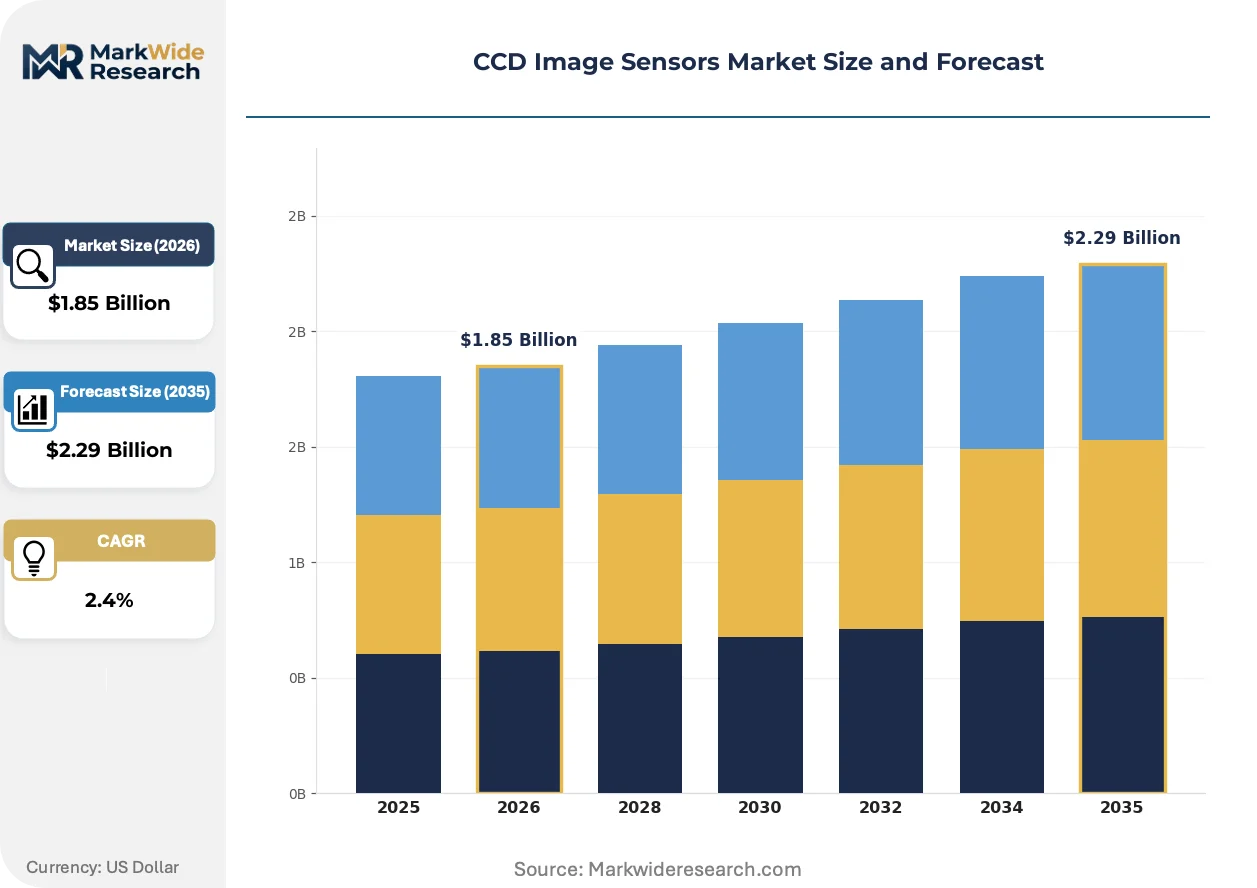
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interline Transfer, Frame Transfer, Front Illuminated, Back Illuminated End User: Consumer Electronics, Medical Imaging, Industrial Automation, Automotive Technology: Analog, Digital, High-Speed, Low-Light Application: Surveillance, Photography, Robotics, Microscopy |
| Companies Covered | Onsemi, Sony Semiconductor Solutions Corporation, Hamamatsu Photonics, STMicroelectronics, Samsung, Teledyne DALSA, FRAMOS GmbH, Canon, Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CCD Image Sensors Market Strategic Shifts
Sensor architecture is bifurcating between performance-optimized CCDs for photon-starved environments and cost-optimized CMOS for high-volume imaging, with hybrid approaches emerging at the boundary.
Deep-depletion CCDs on high-resistivity silicon substrates are electrifying near-infrared astronomy and Raman spectroscopy by extending sensitivity beyond 1000 nm. Observatories in Chile and Hawaii are retrofitting telescope focal planes with these devices. The technology is compressing the addressable market for InGaAs focal plane arrays in scientific applications.
Japan's METI energy-efficiency benchmarks are tightening standby power limits for imaging equipment containing CCDs. Medical device OEMs are redesigning power management circuits to meet these thresholds. The regulation is accelerating adoption of low-clock-voltage CCD drivers in fluoroscopy systems destined for Japanese hospitals.
Academic research labs are consolidating purchasing through shared instrumentation facilities rather than individual PI grants. Core microscopy centers at US National Institutes of Health-funded institutions now specify multi-user service contracts. This concentration is shifting vendor relationships from unit sales to performance-guaranteed uptime agreements in North American life science markets.
CCD Image Sensors Market Segmentation
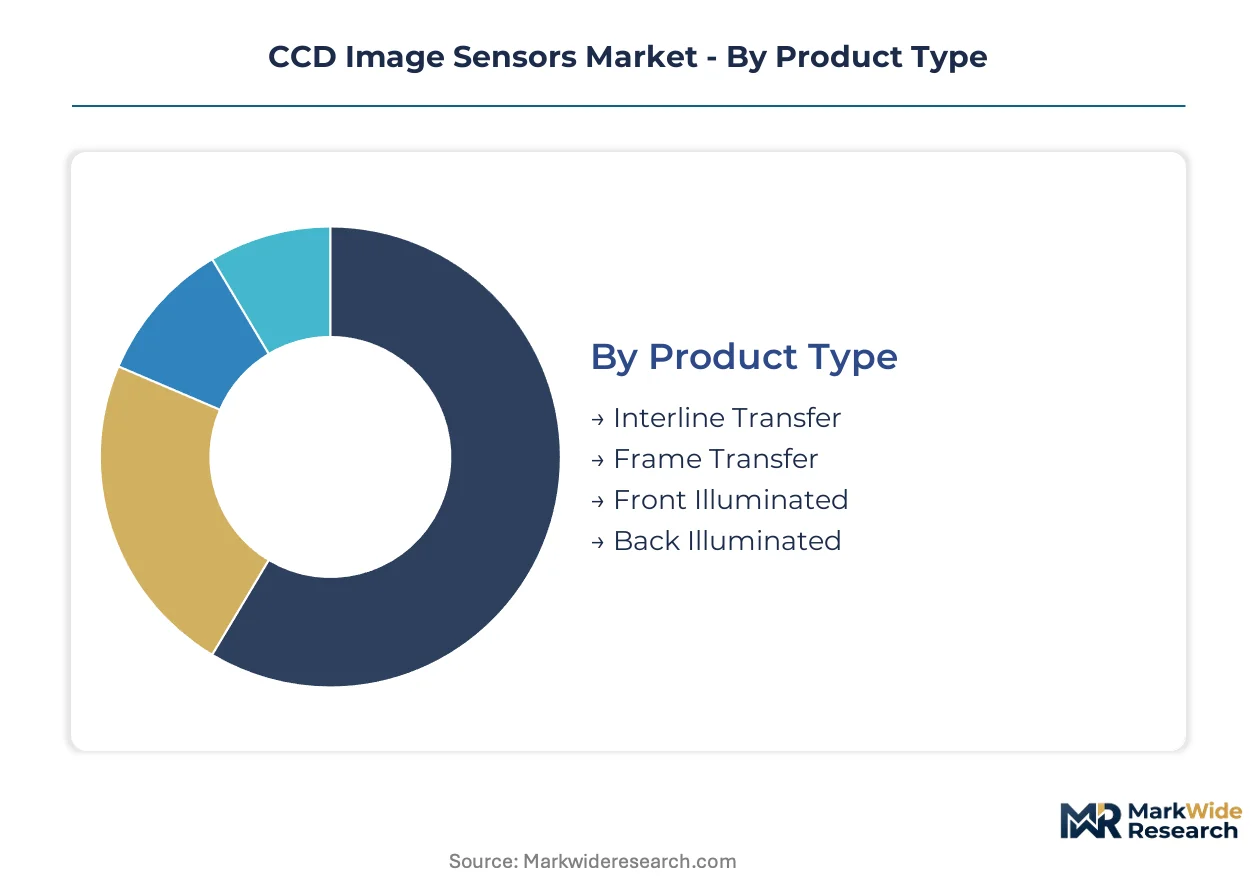
CCD sensor architecture dictates integration depth across standalone scientific instruments versus embedded medical and industrial systems. Segmentation reveals where thinned silicon substrates and cryogenic cooling justify premium positioning against CMOS alternatives.
Product Type:
Interline transfer designs dominate embedded medical and industrial applications where electronic shuttering eliminates mechanical complexity. Frame transfer architectures serve standalone scientific instruments requiring maximum fill factor.
- Interline Transfer:Photodiodes pair with vertical CCD registers for electronic shutter control without mechanical blades. Demand concentrates in Japan's fluoroscopy equipment manufacturers facing METI standby power regulations. Frame-transfer compatibility with legacy 1990s digital acquisition hardware sustains replacement volumes.
- Frame Transfer:Full imaging area captures photons before rapid vertical shift to masked storage zones. Astronomical observatories in Chile and Hawaii specify these for deep-cooled focal planes where dark current suppression below 0.001 e-/pixel/second remains unmatched.
- Front Illuminated:Standard polysilicon gate structures on epitaxial silicon dominate cost-sensitive industrial inspection in the United States.
- Back Illuminated:Thinned substrates with rear-side illumination command premium positioning in fluorescence microscopy systems.
Interline transfer leads volumes today; back illuminated is gaining share fastest.
End User:
Medical imaging generates stable replacement demand for frame-transfer architectures in radiology suites. Industrial automation favors interline designs for machine vision throughput.
- Medical Imaging:Digital radiography and fluoroscopy systems require ISO 13485-certified sensors with IEC 60601 electrical safety compliance. Hamamatsu Photonics anchors supply for Japanese hospital procurement. Whole-slide pathology scanners are opening clinical diagnostic channels beyond radiology.
- Consumer Electronics:Legacy camcorder and digital camera segments face accelerating CMOS displacement. METI energy-efficiency benchmarks are tightening standby power limits for remaining CCD-integrated equipment.
- Industrial Automation:Electronic shutter capability supports high-speed inspection without mechanical latency.
- Automotive:Limited adoption persists in specialized driver monitoring research platforms.
Medical imaging commands margin premiums; industrial automation shows steepest expansion trajectory.
Technology:
Analog output dominance persists in scientific instrumentation where external digitization preserves signal chain flexibility. Digital integration serves embedded systems with space constraints.
- Analog:Voltage output to external ADCs allows customized signal conditioning for spectroscopy. Research-grade systems in US National Institutes of Health-funded core facilities specify analog interfaces for multi-instrument compatibility.
- Digital:On-chip ADC integration reduces component count for portable medical devices. Japanese OEMs are redesigning power management circuits to meet METI standby thresholds.
- High-Speed:Multi-tap output architectures support kilohertz frame rates for particle physics detection.
- Low-Light:Deep-depletion variants on high-resistivity silicon extend sensitivity beyond 1000 nm for Raman spectroscopy.
Analog leads installed base; low-light is climbing the fastest.
Application:
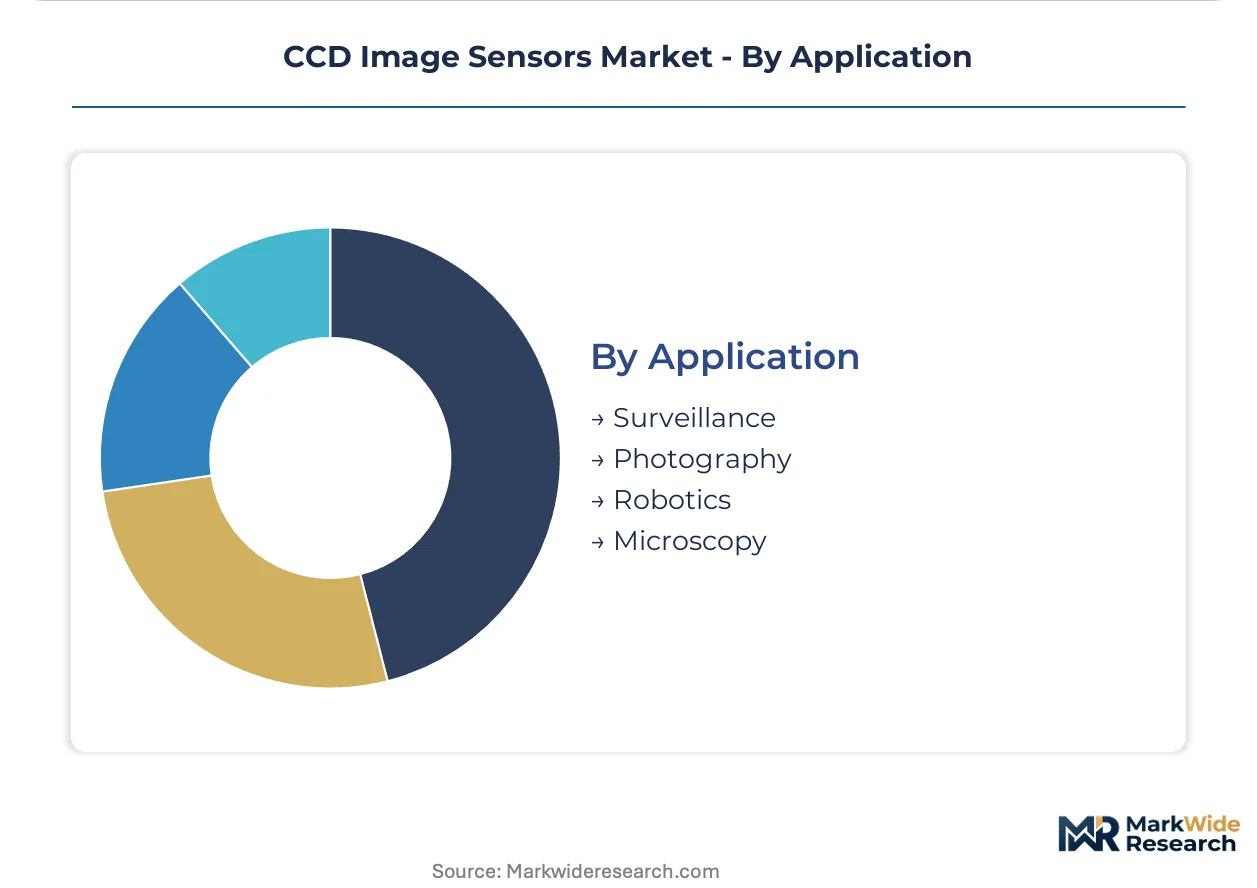
Microscopy and surveillance represent opposing integration models—standalone scientific instruments versus networked embedded systems.
- Microscopy:Back-illuminated sensors with quantum efficiency above 90% dominate fluorescence life science research. US academic core facilities are consolidating purchasing through shared instrumentation centers with performance-guaranteed uptime contracts.
- Surveillance:Low-light CCDs persist in specialized perimeter monitoring where uniform pixel response outweighs CMOS cost advantages. The EU AI Act's emerging imaging system traceability requirements will extend compliance obligations.
- Photography:Professional medium-format digital backs retain niche CCD adoption for color rendering characteristics.
- Robotics:Machine vision guidance systems are transitioning to stacked CMOS with global shutter capability.
Microscopy leads revenue concentration; surveillance maintains stable replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers with CCD-specific expertise in charge transfer efficiency optimization are retiring fastest in Western universities, concentrating remaining talent in Japanese precision optics clusters and select US defense corridors.
United States
Defense and aerospace procurement drives demand for US-assembled CCD modules under domestic content incentives. The EPA regulates hazardous substance thresholds in manufactured sensor assemblies. Greater Boston anchors scientific instrumentation demand through NIH-funded core microscopy facilities.
Japan
Hamamatsu and Tokyo precision optics clusters sustain concentrated CCD design expertise and captive epitaxial wafer supply. METI enforces energy-efficiency benchmarks that reshape power budgets for medical imaging equipment. Kanto region hospitals are redesigning fluoroscopy systems to meet tightening standby power limits.
Germany
Industrial inspection systems sustain European demand through time-limited EU RoHS exemptions for lead-based solders. ECHA REACH restrictions govern cadmium and lead content in sensor modules bound for European markets. Bavaria's machine vision OEMs face extended qualification timelines for reformulated packaging materials.
Switzerland
Scientific instrumentation exports drive stable demand for cryogenically cooled sensor modules in spectroscopy applications. Swissmedic alignment with EU MDR streamlines medical device certification for European-bound products. Zurich-region research institutes specify deep-cooled CCDs for photon-starved environments.
United Kingdom
Astronomical observatory procurement sustains niche demand for deep-depletion CCDs in near-infrared applications. The country's national research funding councils prioritize domestic content in telescope focal plane retrofits. Scotland's instrumentation specialists serve observatories in Chile and Hawaii with thinned silicon substrates.
CCD Image Sensors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a consolidating supplier base where legacy specialty foundries now dominate CCD fabrication. The market structure concentrates among vertically integrated Japanese conglomerates, European industrial component specialists, and US defense-focused fabricators. Three archetypes prevail: captive foundry operators with in-house epitaxial wafer supply, fabless designers licensing process technology, and scientific instrumentation integrators bundling cryogenic cooling systems. Competitive moves center on securing qualified foundry capacity and navigating dual medical-industrial certification burdens.
Among Japan-based fabricators, Sony Semiconductor Solutions Corporation and Hamamatsu Photonics occupy positions at opposite ends of the performance spectrum, with the former exemplifying premium-tier back-illuminated architectures and the latter anchoring cryogenically cooled scientific modules. Onsemi represents the vertically integrated North American archetype with captive foundry networks sustaining high-reliability industrial supply. These three entities collectively illustrate how geographic clustering around precision optics corridors and defense procurement corridors shapes competitive positioning in a shrinking qualified supplier pool.
| Leading Market Players |
|---|
| Onsemi |
| Sony Semiconductor Solutions Corporation |
| Hamamatsu Photonics |
| STMicroelectronics |
| Samsung |
| Teledyne DALSA |
| FRAMOS GmbH |
| Canon |
| Sharp Corporation |
| Others |
Value Chain & Pricing Dynamics
Epitaxial silicon wafer spot indices cascade through CCD fabrication into three distinct pricing tiers: cryogenically cooled scientific modules command premium positioning, industrial-grade interline transfer sensors occupy the mid-market, and front-illuminated devices for legacy consumer applications face persistent cost compression. Japanese foundry concentration around Hamamatsu and Tokyo amplifies pricing power for back-illuminated architectures, while US defense procurement sustains domestic assembly premiums.
Pricing Analysis
Unbundled sensor modules compete against bundled cryogenic cooling systems in scientific procurement, while medical OEMs favor integrated digital outputs with on-chip ADCs. Pricing stratifies across premium, standard, and economy tiers based on quantum efficiency certification and ISO 13485 compliance grade. Cost compression in the consumer tier intensifies as CMOS substitution accelerates, with machine vision buyers exhibiting highest price sensitivity and astronomical observatories remaining least elastic.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale medical equipment demand, while specialty distributors serve fragmented scientific instrumentation labs. Supply concentrates in Japan, the United States, and Germany for qualified CCD fabrication, with raw material flows drawing from epitaxial silicon suppliers in Kagoshima and Texas. Single-source vulnerability around thinned silicon substrate processing creates chokepoint exposure. Distribution runs through authorized technical distributors with field application engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier shift toward cryogenically cooled scientific modules, justified by irreplaceable dark current performance in photon-starved applications.
For Market Incumbents: To counter CMOS substitution in frame-transfer applications, anchor capacity in Japanese precision optics corridors for captive epitaxial wafer supply, and deepen certification investment in dual ISO 13485-IEC 60601 qualification to defend medical imaging pricing power.
For New Entrants and Emerging Players: The premium-to-economy price gap in scientific instrumentation opens white-space targeting of mid-tier fluorescence microscopy labs with service-contract bundling, and penetration of digital pathology scanner OEMs seeking color-fidelity alternatives to CMOS in histology applications.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialty foundry operators possessing in-house buried-channel process expertise. Long-term viability hinges on 5-10 year demand continuity from astronomical observatory retrofit cycles. Watch Hamamatsu-Tokyo cluster talent migration as inflection signal for supply-side consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Cooling System Integration | Deep-cooled modules command premium positioning in Chile and Hawaii observatories. |
| Dual Certification Investment | Simultaneous ISO 13485 and IEC 60601 qualification opens Japanese hospital procurement. |
| Epitaxial Wafer Backward Integration | Captive silicon supply insulates against Japanese substrate concentration risk. |
| Digital Output Architecture Migration | On-chip ADC integration meets METI standby power thresholds for fluoroscopy systems. |
| Scientific Service Contract Pivot | Performance-guaranteed uptime agreements align with NIH core facility consolidation. |
Study Parameters
Multiple input streams — primary interviews with CCD process engineers and medical device procurement managers, secondary validation through ECHA REACH filings and METI energy-efficiency disclosures, and trade data reconciliation — were synthesized across bottom-up and top-down triangulation. Stakeholder consultations included scientific instrumentation OEMs, hospital biomedical engineering directors, and specialty foundry operations heads. Secondary sources encompassed EPA hazardous substance thresholds, EU RoHS exemption registers, and Japanese semiconductor production statistics.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeling across sensor architecture, cooling requirement, end-use application, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and technology substitution elasticity. Industry-specific forecast inputs included astronomical observatory capital expenditure pipelines and digital pathology scanner adoption curves.
The model assumes a particular technology adoption path; alternative pathways for stacked backside-illuminated CMOS would alter the outlook. Forecasts reflect assumptions around RoHS exemption continuity and epitaxial silicon supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Global Trail Camera Market
Imaging
Automotive Compact Camera Module Market
Imaging
Uncooled Infrared Camera Market
Imaging
Global Image Signal Processor Market
Imaging
Facial Recognition Machine Market
Imaging
Thermal Imaging Market
Imaging
Hyperspectral Cameras Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
Global Panoramic Camera Market
Imaging
Event Camera Market
Imaging
US Near Infrared Imaging Market
Imaging
AI-Based Fever Detection Camera Market