
 Multi Camera System Market | 2026-2036
Multi Camera System Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Camera System Market Outlook
Embedded vision engineering talent scarcity is unwinding supply timelines across the multi camera system value chain. Bosch leverages its Tier-1 automotive relationships to sustain long-term assembly contracts for surround-view modules. Continental AG anchors European OEM demand through integrated ADAS camera platforms. Sony Corporation dominates image sensor supply for high-resolution multi-camera arrays.
A multi camera system coordinates two or more imaging devices through synchronized capture, stitching algorithms, and unified data processing to deliver panoramic or multi-angle visual output. These systems typically operate at 30-60 frames per second with latency below 50 milliseconds for real-time applications. Wired cameras occupy the largest revenue share due to reliability requirements in automotive and broadcast environments, while cloud integration represents the fastest-expanding technology segment as remote production workflows proliferate. IP technology underpins enterprise security deployments where centralized management and analytics integration drive procurement decisions.
NHTSA mandates rear-visibility standards that directly shape automotive camera system specifications, while FCC regulations govern wireless transmission protocols for consumer and commercial devices. The EU AI Act introduces conformity requirements for automated image analysis in public surveillance applications. Stakeholders must weigh regulatory compliance timelines against technology refresh cycles when allocating product development resources.
Market Dynamics
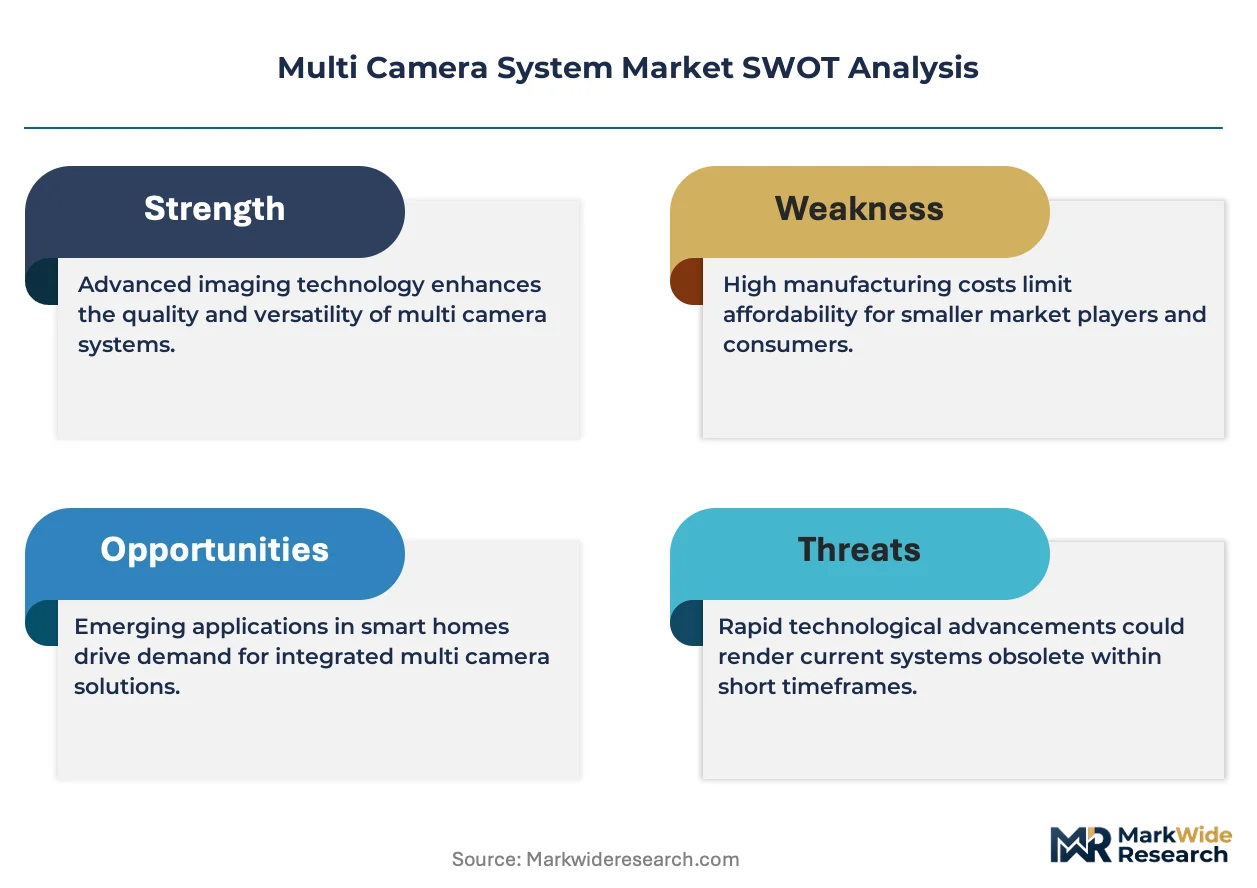
Camera miniaturization and AI-driven image processing are compressing product development cycles while forcing suppliers to reconfigure assembly partnerships around real-time processing capabilities rather than discrete hardware sales.
Growth Catalysts
- Automotive surround-view mandates:NHTSA rear-visibility standards in the United States and equivalent safety frameworks in Germany compel OEMs to integrate multi-camera arrays into vehicle platforms.
- Cloud production workflows:Remote broadcast and enterprise security deployments are consolidating camera feeds through centralized analytics platforms, expanding recurring software revenue attachment.
- AI Act surveillance compliance:The EU AI Act creates conformity requirements for automated image analysis that favor certified multi-camera system vendors with established European manufacturing footprints.
Market Restraints
- Image sensor supply concentration:High-resolution array production depends on a limited supplier base concentrated in East Asian fabrication facilities, exposing procurement timelines to geopolitical friction.
- Wireless protocol limitations:FCC transmission standards constrain bandwidth for consumer-grade multi-camera setups, capping resolution and frame-rate specifications below wired alternatives.
- Embedded vision talent scarcity:Synchronized capture and stitching algorithm development requires specialized firmware engineers whose limited availability extends product validation schedules.
Strategic Opportunities
- India industrial automation:Factory digitization initiatives under the PLI scheme create first-mover positioning for multi-camera quality inspection and robotic guidance systems.
- Edge-AI convergence:On-device neural processing unit integration with traditional image sensors enables low-latency analytics without cloud dependency, opening defense and critical infrastructure applications.
- Subscription-based security monitoring:Managed service providers are bundling hardware deployment with remote monitoring, shifting revenue from one-time equipment sales to recurring contracts.
Industry Challenges
- Firmware integration complexity:Synchronizing heterogeneous camera modules from different sensor vendors requires custom driver development that strains engineering bandwidth.
- CE marking timeline compression:The EU AI Act conformity assessment process adds validation stages that conflict with automotive platform refresh schedules.
- Legacy coaxial infrastructure:Industrial and broadcast facilities with installed analog cabling face capital-intensive retrofitting to support IP-based multi-camera architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Camera System Market |
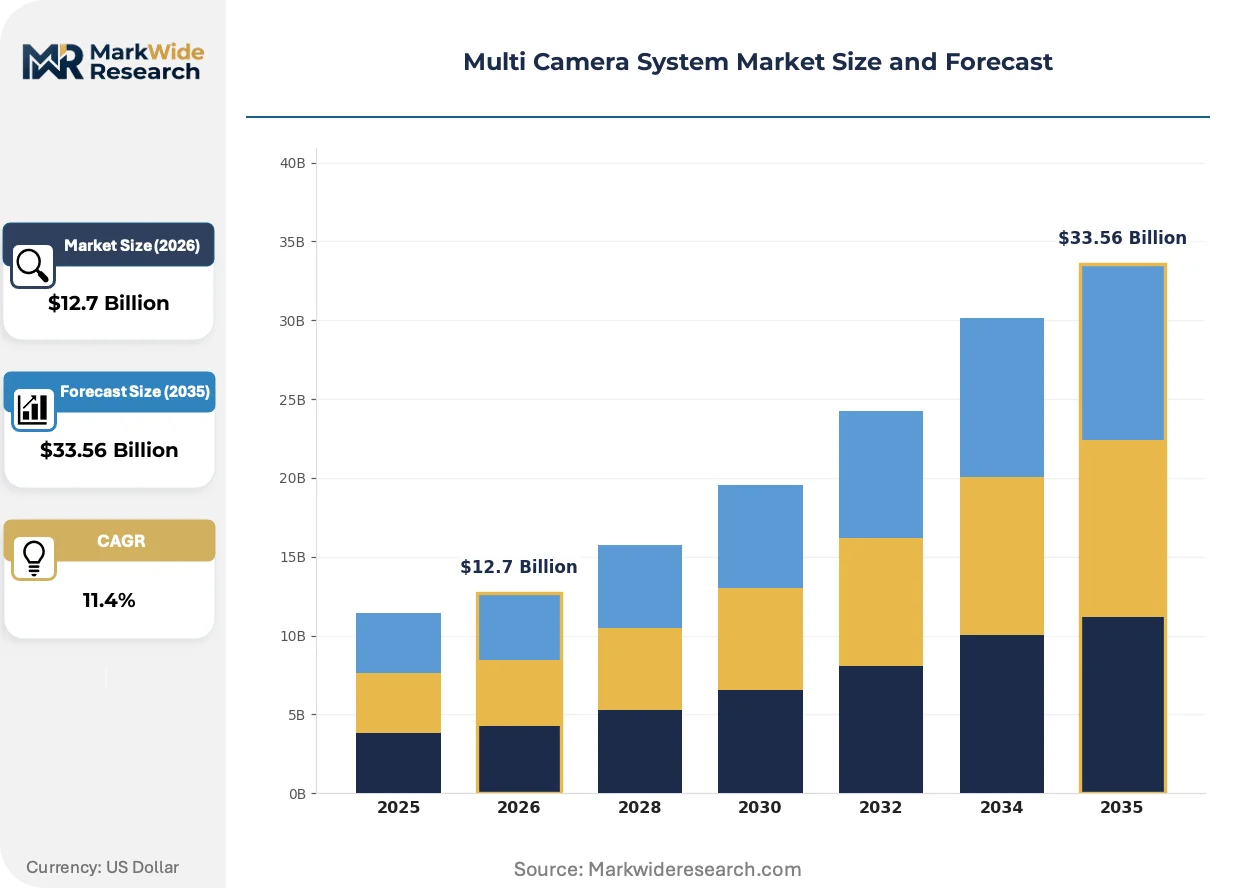
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Cameras, Wired Cameras, Surveillance Systems, Action Cameras Application: Security Monitoring, Live Streaming, Event Coverage, Sports Broadcasting End User: Households, Commercial Establishments, Government Agencies, Media Organizations Technology: IP Technology, Analog Technology, Cloud Integration, HD Streaming |
| Companies Covered | Bosch, Continental AG, Delphi Technologies, Denso Corporation, Valeo, Magna International, Aptiv, Panasonic, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Camera System Market Strategic Shifts
Computational imaging and edge processing architectures are fragmenting traditional hardware-centric business models, with software-defined functionality now determining competitive differentiation more than optical specifications alone.
Time-of-flight depth sensing is bifurcating from stereoscopic depth estimation in automotive and robotics applications. German OEMs are adopting solid-state lidar-integrated camera modules for ADAS redundancy, while consumer electronics manufacturers favor passive stereo arrays for cost-constrained products. This technical split is compressing vendor margins in mid-tier positioning systems as buyers consolidate around one architecture or the other.
The EU AI Act's risk-based classification for biometric identification systems is forcing surveillance equipment vendors to reengineer firmware for auditability and human oversight. Industrial consequence includes mandatory conformity assessment procedures that add six to twelve months to product launch timelines. Public sector procurement in France and Germany now prioritizes vendors with established notified body relationships.
Enterprise security buyers are consolidating vendor relationships around platforms offering unified video management software rather than discrete camera hardware. System integrators in the United States are displacing traditional distribution channels with direct-to-end-user subscription bundles. This channel compression is most visible in municipal and educational institution deployments where total cost of ownership calculations now dominate specification decisions.
Multi Camera System Market Segmentation
Multi camera system procurement channels diverge sharply across segments, with automotive OEMs favoring direct Tier-1 contracts while enterprise security flows through systems integrators. Understanding these channel dynamics exposes where pricing power concentrates and where margin compression threatens.
Product Type:
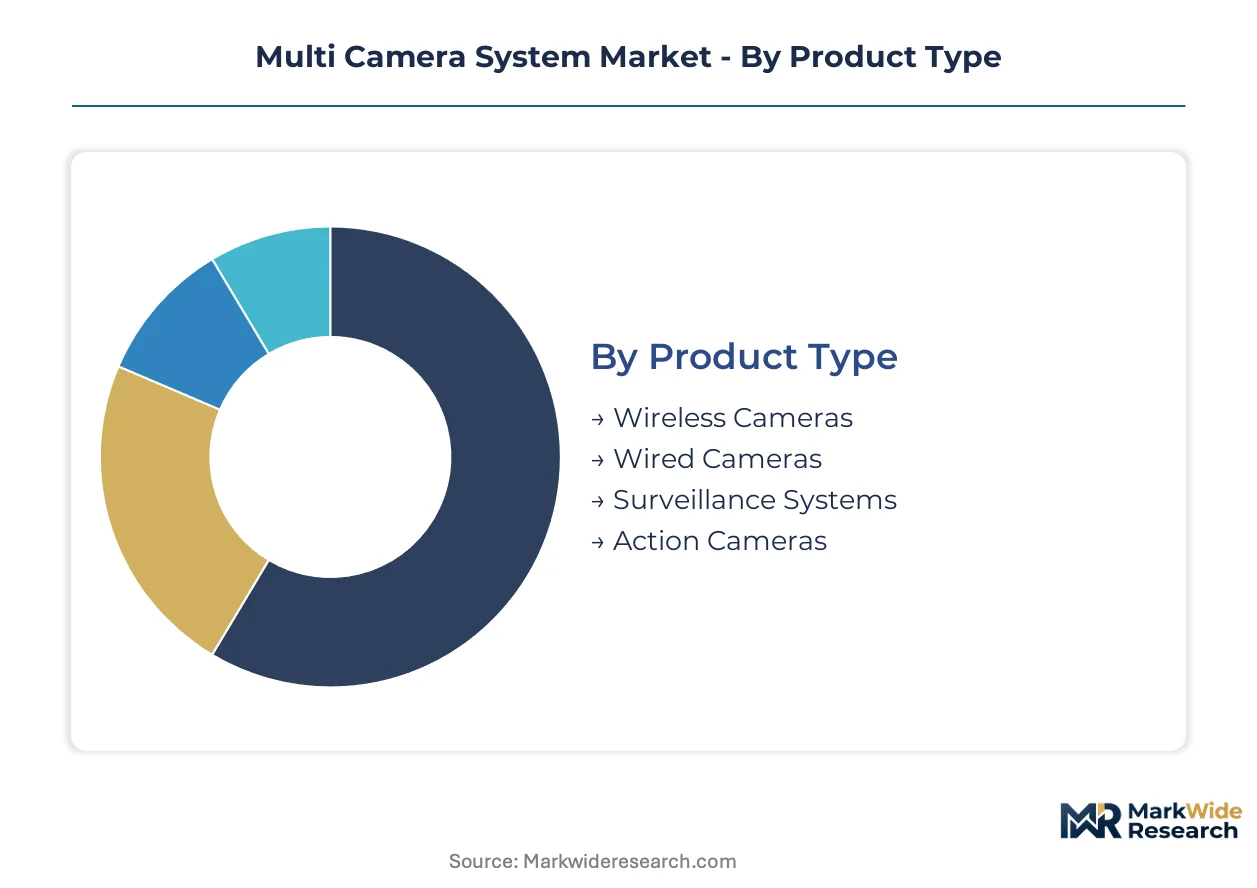
Wired configurations dominate industrial and broadcast procurement through established distribution partnerships, while wireless variants increasingly bypass traditional channels via direct-to-consumer platforms.
- Wired Cameras:Coaxial and Ethernet-tethered units deliver sub-50 millisecond latency with 30-60 frames per second synchronization for automotive surround-view and broadcast environments. German OEMs and US media networks anchor procurement through long-term assembly contracts with Tier-1 suppliers.
- Wireless Cameras:Battery-operated modules operating under FCC transmission constraints serve consumer live-streaming and mobile event coverage. FCC bandwidth limitations cap resolution below wired alternatives, compressing margins in consumer-grade segments.
- Surveillance Systems:Fixed-position arrays with centralized management software dominate enterprise security deployments through systems integrator channels.
- Action Cameras:Ruggedized portable units target sports and adventure content creators via direct e-commerce and specialty retail.
By volume, Wired Cameras lead. By growth pace, Wireless Cameras are expanding most quickly.
Application:
Cost tier differentiation separates premium broadcast specifications from commoditized residential security, with mid-tier commercial applications driving the bulk of unit economics.
- Security Monitoring:Enterprise and municipal deployments require IP-based architectures with centralized analytics integration. The EU AI Act conformity requirements favor vendors with established notified body relationships in France and Germany.
- Sports Broadcasting:Ultra-high-definition multi-angle capture with real-time stitching commands premium pricing through dedicated broadcast technology distributors. Live production workflows are consolidating feeds through cloud-based remote production platforms.
- Live Streaming:Individual creators and small production houses drive volume through consumer electronics retail and direct-to-consumer channels.
- Event Coverage:Corporate and entertainment venues balance portability with professional output specifications through rental and systems integrator channels.
Security Monitoring captures the largest revenue pool. Sports Broadcasting carries the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with government and media buyers imposing certification requirements that residential and small commercial segments ignore.
- Commercial Establishments:Retail, hospitality, and corporate campuses deploy IP-based surveillance with recurring software subscriptions. US systems integrators are displacing traditional distribution with bundled hardware-monitoring packages.
- Government Agencies:Municipal, federal, and defense procurement mandates CE marking, FCC certification, and EU AI Act conformity for biometric applications. Validation timelines extend six to twelve months beyond commercial product launches.
- Households:Residential buyers prioritize ease-of-installation and mobile app integration through consumer electronics and home improvement retail.
- Media Organizations:Broadcast networks and production companies demand broadcast-grade specifications with minimal latency through specialized broadcast technology vendors.
Commercial Establishments generate the highest unit volumes. Government Agencies impose the most demanding compliance barriers.
Technology:
Supply concentration in image sensor fabrication and processing silicon shapes which technology architectures achieve cost-competitive scale.
- IP Technology:Network-based camera architectures with Power over Ethernet and centralized video management software dominate enterprise security. ONVIF and proprietary protocols create vendor lock-in dynamics in large-scale deployments.
- Cloud Integration:Edge-to-cloud architectures enable remote production workflows and managed security services with recurring revenue attachment. This segment is climbing the fastest as broadcast and security operations consolidate infrastructure.
- Analog Technology:Legacy coaxial installations persist in industrial facilities and budget-constrained municipal deployments facing capital-intensive retrofit decisions.
- HD Streaming:High-definition transmission protocols serve mid-tier commercial and prosumer segments balancing quality against bandwidth constraints.
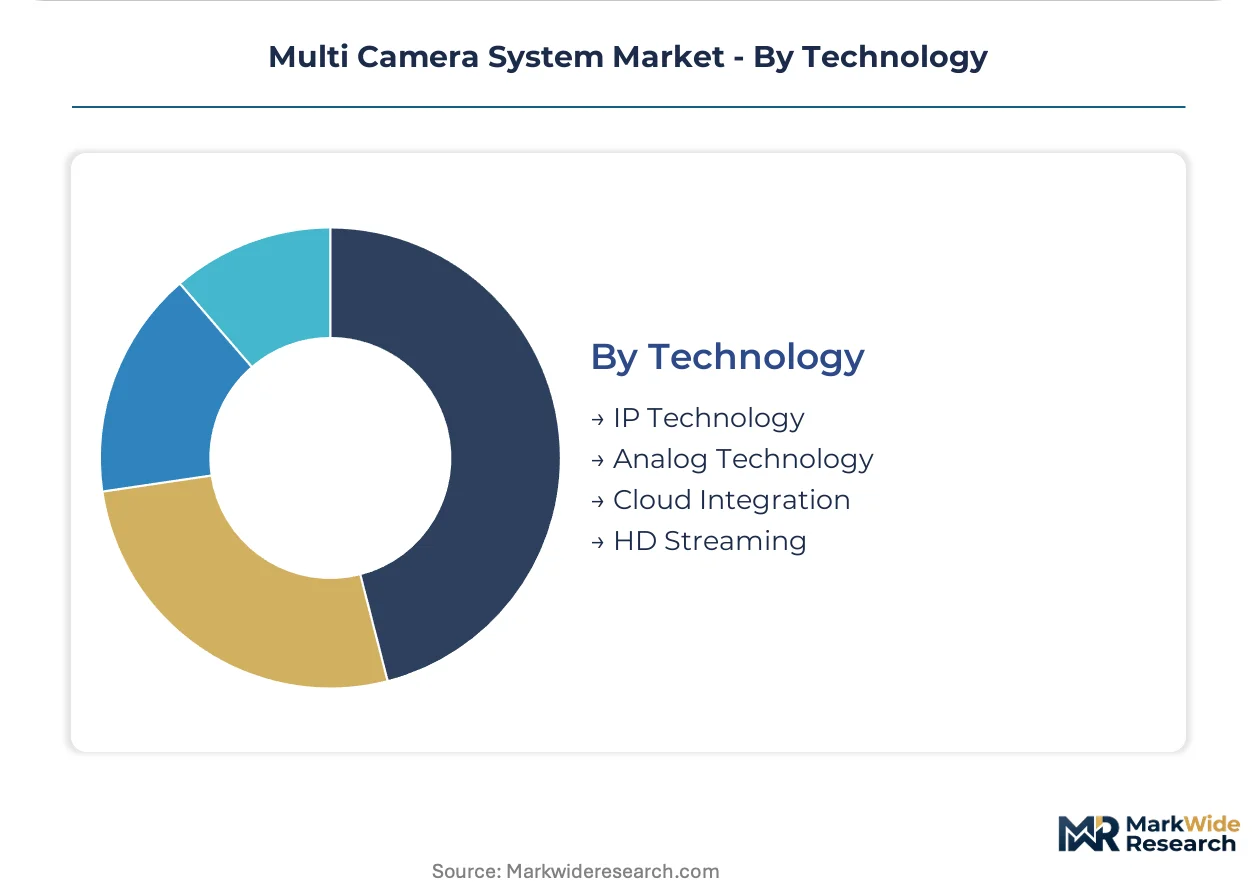
IP Technology holds the installed base majority. Cloud Integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA regulations in the United States anchor the largest automotive camera procurement market, with German and Chinese manufacturing clusters driving component supply and system integration respectively.
United States
NHTSA rear-visibility mandates and FCC transmission protocols shape OEM and consumer product specifications. The IRA's clean vehicle incentives accelerate electric platform camera integration. Detroit-area Tier-1 suppliers coordinate surround-view module assembly for domestic automakers.
Germany
EU AI Act conformity requirements and KBA type-approval processes extend validation timelines for surveillance and biometric systems. CE marking obligations favor established notified body relationships. Stuttgart and Munich host integrated ADAS camera platform development for European OEMs.
China
MIIT standards for intelligent connected vehicles and GB certification requirements govern domestic multi-camera system deployment. SAMR market supervision ensures quality compliance. Shenzhen and Shanghai concentrate image sensor fabrication and AI-driven processing module manufacturing.
Japan
METI industrial policy and JIS standards guide precision imaging equipment production for automotive and broadcast applications. PMDA oversight applies to medical imaging multi-camera configurations. Nagoya and Tokyo anchor stereoscopic depth estimation technology development.
India
PLI scheme incentives for electronics manufacturing and BIS certification requirements attract multi-camera system assembly investment. TRAI spectrum regulations affect wireless surveillance deployments. Tamil Nadu and Karnataka industrial corridors host quality inspection and robotic guidance system pilots.
Multi Camera System Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with consolidated Tier-1 automotive suppliers commanding premium assembly contracts while specialized imaging component vendors capture sensor-level margins. The market structure tiers into three strategic groups: vertically integrated automotive electronics conglomerates, precision imaging sensor specialists, and regional contract manufacturers serving aftermarket segments. Dominant competitive moves include strategic partnerships around AI-driven processing capabilities and geographic expansion into India and Southeast Asia to capture PLI-linked manufacturing incentives.
Within the automotive Tier-1 tier, Bosch and Continental AG exemplify the vertically integrated archetype that controls surround-view module assembly through long-term OEM relationships. Sony Corporation occupies a distinct position as the precision imaging anchor, with its sensor supply dominance extending across high-resolution multi-camera arrays for automotive, broadcast, and surveillance applications. Denso Corporation represents the Japan-based specialist archetype with established JIS-compliant manufacturing footprints serving both domestic and export markets.
| Leading Market Players |
|---|
| Bosch |
| Continental AG |
| Delphi Technologies |
| Denso Corporation |
| Valeo |
| Magna International |
| Aptiv |
| Panasonic |
| Sony Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day image sensor lead times concentrate procurement leverage among East Asian foundries, compressing margins for downstream assemblers while amplifying pricing power at the sensor tier. This inventory dynamic forces automotive Tier-1 suppliers into long-term offtake contracts that lock in component costs years ahead of platform launches.
Pricing Analysis
Price spreads between German-engineered ADAS modules and Chinese-assembled consumer arrays span roughly three-to-one, with certification grade and volume scale as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified automotive units from commercial surveillance systems and uncertified consumer hardware. Cost compression in the wireless consumer tier intensifies because FCC bandwidth constraints cap performance specifications below wired alternatives. Residential buyers exhibit highest price sensitivity, while government agencies accept premium positioning for CE-marked and EU AI Act-compliant configurations.
Supply Chain Analysis
TSMC wafer fabrication and Sony sensor packaging in Taiwan and Japan create chokepoints that tether multi-camera system output to East Asian semiconductor capacity. High-resolution image sensors, neural processing units, and specialized optical lenses draw from concentrated supplier bases in South Korea, China, and Japan. Single-source vulnerability in advanced CMOS fabrication exposes procurement timelines to geopolitical friction and export control uncertainty. Distribution runs through direct Tier-1 contracts for automotive OEMs and systems integrator channels for enterprise security deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around NHTSA, CE marking, and EU AI Act conformity creates sticky incumbent positions that new entrants struggle to replicate without multi-year validation timelines.
For Market Incumbents: Fortify sensor-level backward integration to reduce exposure to Sony supply concentration, while deepening KBA and FCC certification investment to extend platform lock-in with European and US automakers. Emerging Chinese imaging module vendors threaten margin compression in the mid-tier surround-view segment.
For New Entrants and Emerging Players: Differentiate on edge-AI processing capabilities for India's PLI-linked industrial automation pilots, where quality inspection and robotic guidance applications remain underpenetrated by established automotive suppliers. Target municipal security deployments in France and Germany through notified body partnerships as the fastest compliance pathway.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because conformity assessment timelines and OEM platform integration cycles create durable revenue visibility for certified vendors. Acquisition focus should center on imaging firmware specialists with embedded vision engineering depth. The signal to watch is MIIT standard acceleration for intelligent connected vehicles in China, which would reshape sensor procurement geography.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Processing Module Development | On-device neural processing enables low-latency analytics for defense and critical infrastructure without cloud dependency. |
| Notified Body Certification Investment | EU AI Act conformity relationships in France and Germany accelerate public sector procurement timelines by six to twelve months. |
| India Manufacturing Footprint Expansion | PLI scheme incentives for electronics manufacturing attract assembly investment for quality inspection and robotic guidance systems. |
| Long-term Sensor Supply Agreement | Fixed-price offtake contracts with Sony or Samsung reduce exposure to wafer fabrication capacity constraints and price volatility. |
| Cloud-Integrated Platform Launch | Remote production workflows and managed security services shift revenue from equipment sales to recurring software subscriptions. |
Study Parameters
A spread of perspectives from Tier-1 supplier procurement officers, OEM platform engineers, systems integrator technical leads, and enterprise security buyers converged on the working assumptions around camera miniaturization timelines and AI-driven processing adoption curves. Primary interview insights combined with secondary validation from NHTSA regulatory filings, FCC equipment authorization databases, EU AI Act implementation guidance, and automotive production registration data. Bottom-up unit economics across wired, wireless, and cloud-integrated configurations triangulated against top-down market sizing from image sensor shipment volumes and Tier-1 assembly contract values.
Segmentation dimensions modeled include product architecture, application vertical, end-user procurement sophistication, and technology protocol across the analysis window. CAGRs derive from fitted growth curves against historical adoption patterns in automotive surround-view mandates and enterprise security refresh cycles. Forecast inputs incorporate MIIT intelligent connected vehicle targets, PLI scheme electronics manufacturing incentives, and EU AI Act conformity assessment capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained automotive platform electrification, stable East Asian semiconductor fabrication access, and consistent regulatory enforcement timelines would require recalibration. Forecasts reflect documented assumptions around image sensor yield improvements and embedded vision engineering talent availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
SDI Camera Market
Imaging
X-Ray Microscopes Market
Imaging
Digital Microscope Market
Imaging
Digital Camera Market
Imaging
Machine Vision Market
Imaging
Digital X-Ray Technology Market
Imaging
Global Automotive Imaging Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Virtual Reality Camera Market
Imaging
Gel Imaging Documentation Market
Imaging
Ingaas Image Sensor Market
Imaging
Smart Camera Market
Imaging
Global Broadcast Cameras Market
Imaging
APAC Image Sensors Market
Imaging
Global Computed Radiography Market
Imaging
Infrared Imaging Software Market