
 North America Data Center Server Market | 2026-2036
North America Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Server Market Intelligence
The gap between general-purpose and accelerated computing architectures is narrowing as AI training and inference workloads penetrate enterprise and government fleets. Dell Inc leverages its supply chain scale to dominate rack and blade configurations for Fortune 500 refresh cycles. Hewlett Packard Enterprise sustains differentiation through its liquid-cooled systems aimed at high-density AI clusters. Super Micro Computer Inc anchors its position in the ultra-high-power segment with modular designs that appeal to cloud providers building at hyperscale.
Data center servers are enterprise-grade computing platforms engineered with multi-socket processors, ECC memory, redundant power supplies, and remote management controllers to deliver continuous uptime for mission-critical workloads. Rack servers occupy the largest installed base across North American facilities, though blade servers command premium positioning in space-constrained metropolitan deployments. Edge installations represent the fastest-growing structural category as latency-sensitive applications in manufacturing, autonomous systems, and smart infrastructure push compute closer to data sources.
The U.S. Environmental Protection Agency and Department of Energy shape procurement through ENERGY STAR server specifications and data center efficiency benchmarking programs, while the Federal Risk and Authorization Management Program (FedRAMP) constrains which hardware configurations qualify for federal cloud contracts. California's Title 24 building efficiency standards and emerging state-level carbon disclosure rules in New York and Illinois add compliance layers that favor equipment with verified power-usage effectiveness ratings. Stakeholders must monitor how NIST cybersecurity framework updates and anticipated SEC climate disclosure requirements will reshape hardware refresh timelines and supplier qualification criteria.
Market Dynamics
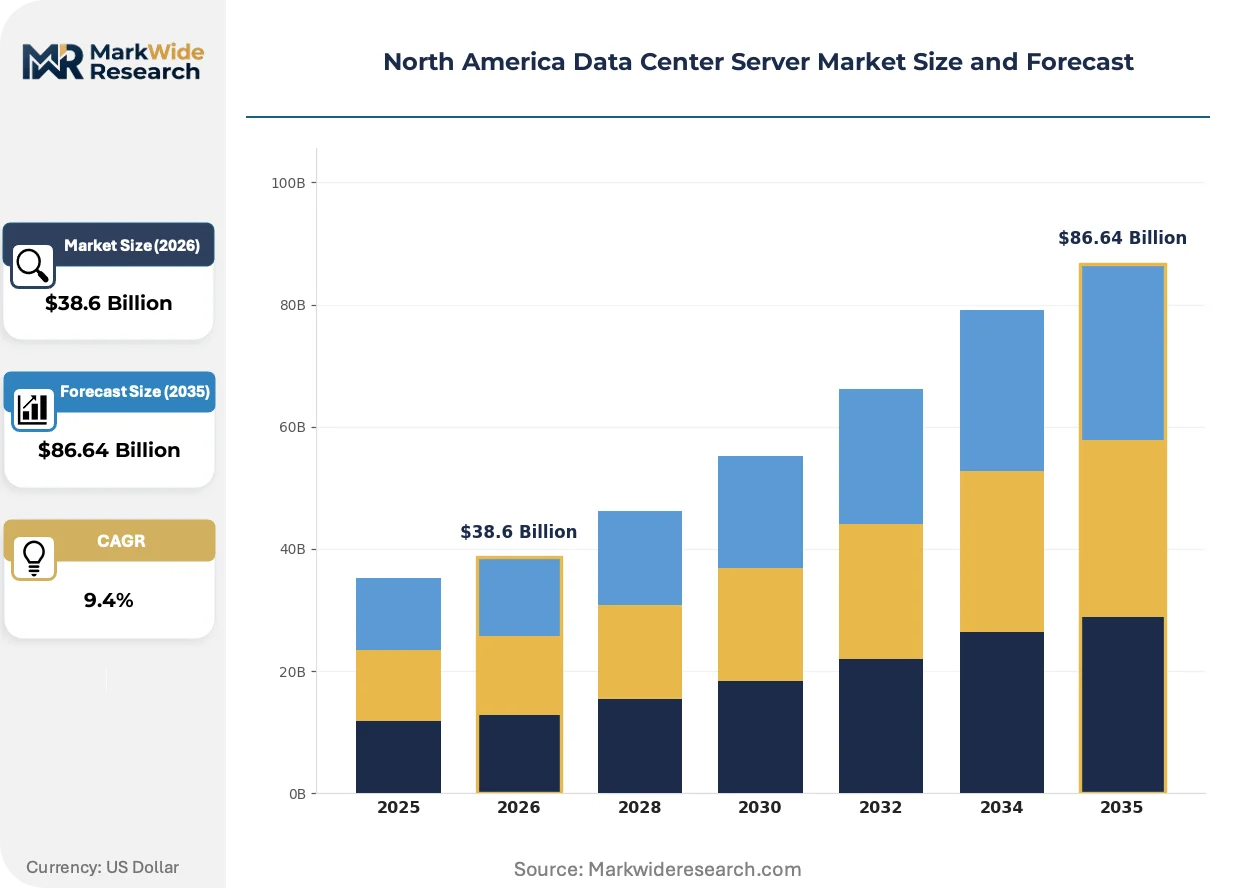
The convergence of AI inference workloads at the edge and hyperscale cloud expansion is compressing refresh cycles and forcing power-density upgrades across colocation and enterprise facilities throughout the United States and Canada.
Growth Catalysts
- Liquid cooling adoption:The U.S. Department of Energy's efficiency benchmarking programs and state-level renewable energy mandates in California and New York are accelerating immersion and direct-to-chip cooling retrofits in facilities exceeding 50kW per rack.
- FedRAMP authorization pathways:Federal cloud procurement requirements are filtering hardware configurations toward pre-qualified server architectures, creating pull-through demand from systems integrators serving defense and civilian agencies.
- Northern Virginia fiber density:The concentration of dark fiber and utility-scale power purchase agreements in Loudoun and Prince William counties continues to attract multi-megawatt deployments from cloud operators expanding training clusters.
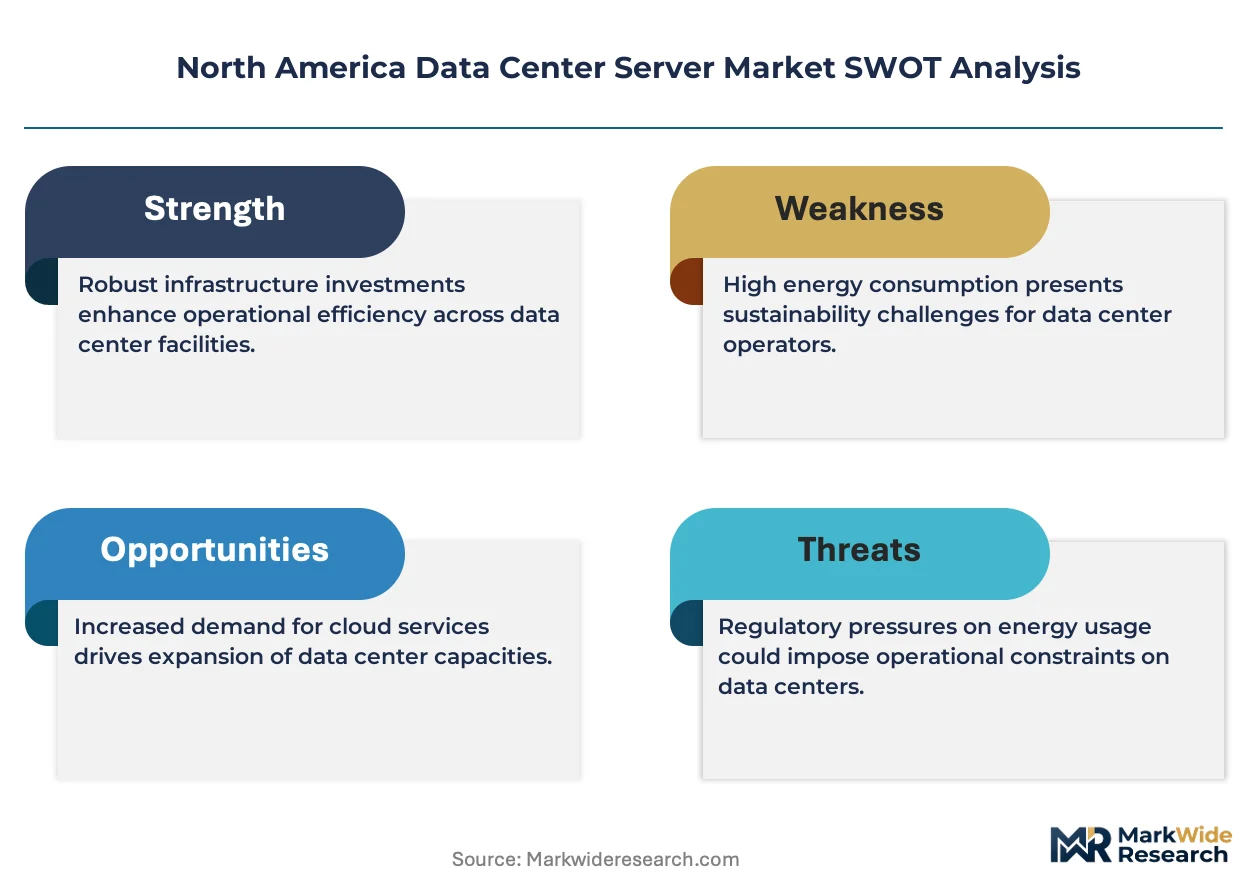
Market Restraints
- GPU supply concentration:Accelerated computing hardware remains concentrated among a limited set of foundry and packaging providers, creating allocation bottlenecks for AI-optimized server builds.
- Interconnection permitting delays:Transmission upgrade queues at ERCOT and PJM interconnection points are extending commissioning timelines for new facilities in Texas and Mid-Atlantic markets.
- Legacy x86 refresh drag:Enterprises with amortization schedules tied to five-year depreciation cycles are deferring generational upgrades despite performance-per-watt advantages of newer architectures.
Strategic Opportunities
- Modular edge deployments:Manufacturing automation and autonomous logistics in the U.S. Midwest are creating demand for micro data centers with 15-50kW footprints positioned within 10 milliseconds of operational technology networks.
- Carbon disclosure alignment:Anticipated SEC climate disclosure requirements and existing California Title 24 standards are positioning verified power-usage effectiveness ratings as procurement differentiators for ESG-mandated buyers.
- Optical interconnect convergence:The integration of co-packaged optics with server NICs is reducing electrical signaling losses and enabling new rack-scale architectures for high-performance computing workloads.
Industry Challenges
- Liquid cooling infrastructure retrofit:Facilities engineered for air-cooled densities face structural and plumbing reconfiguration costs when accommodating immersion tanks or rear-door heat exchangers.
- Supply chain qualification timelines:Component substitutions driven by semiconductor allocation constraints are triggering re-certification delays under NIST cybersecurity framework requirements for federal-bound systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Server Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Microservers End User: Cloud Providers, Enterprises, Government Agencies, Colocation Providers Installation: On-Premises, Off-Site, Hybrid, Edge Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Dell Inc, Hewlett Packard Enterprise, Lenovo Group Limited, Cisco Systems Inc, International Business Machines Corporation, Super Micro Computer Inc, Fujitsu Limited, Huawei Technologies Co Ltd, Inspur Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Server Market Strategic Shifts & Innovations
Compute architectures are fragmenting across latency-optimized edge nodes and throughput-optimized training clusters, forcing suppliers to maintain parallel design tracks while standardizing management interfaces.
Direct liquid cooling is digitizing thermal management in high-density AI clusters. Hyperscale operators in Phoenix and Dallas-Fort Worth are deploying immersion and cold-plate systems at 100kW-plus rack densities. This technology is digitizing facility operations by integrating coolant flow, temperature, and server telemetry into unified control planes that optimize energy usage effectiveness in real time.
The U.S. Environmental Protection Agency's ENERGY STAR server specifications and Department of Energy data center efficiency programs are tightening idle-state power limits. These mandates are compressing allowable thermal design power envelopes for volume servers. Federal and state procurement offices are responding by inserting efficiency benchmarks into RFP scoring criteria, favoring configurations with dynamic voltage-frequency scaling capabilities.
Enterprise buyers are consolidating server procurement through managed infrastructure contracts rather than capital purchases. Colocation providers and cloud-adjacent systems integrators are capturing this spend shift by offering hardware-as-a-service models with embedded refresh guarantees. This pattern is most visible among financial services and healthcare verticals in the U.S. Northeast, where OpEx preference and compliance overhead are driving outsourcing decisions.
North America Data Center Server Market Segmentation
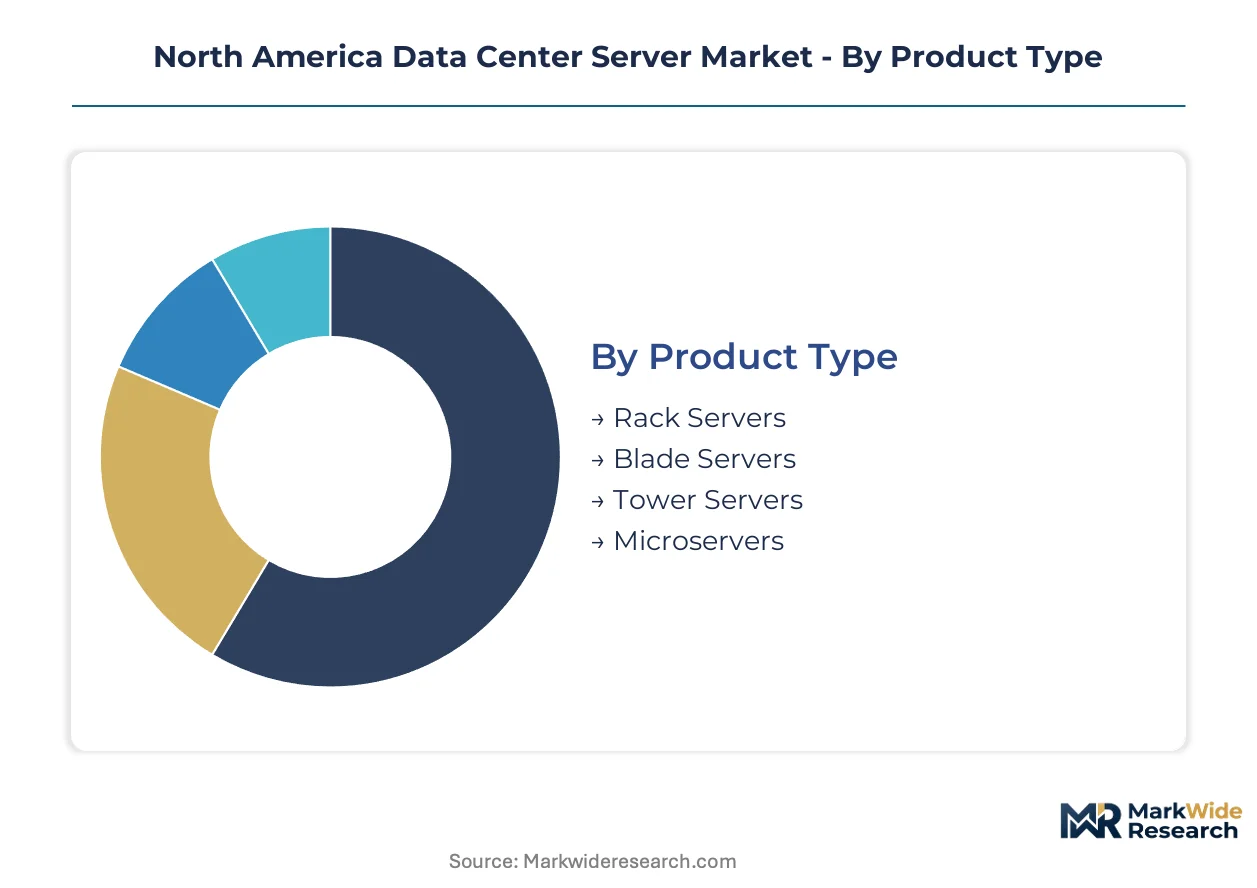
Server procurement patterns across North America diverge sharply by deployment scale and workload type, with hyperscale operators driving volume while edge installations compress refresh timelines. Understanding these segment boundaries clarifies where suppliers can capture margin versus where price competition dominates.
Product Type:
Rack servers turn over slowest at enterprise accounts with five-year depreciation schedules, while blade configurations in metropolitan colocation refresh fastest due to space constraints and power-density upgrades.
- Rack Servers:Standardized 1U-4U enclosures with hot-swappable components dominate Fortune 500 refresh cycles. Demand concentrates in Dallas-Fort Worth and Phoenix where cloud providers provision multi-megawatt training clusters under utility-scale power purchase agreements.
- Blade Servers:High-density shared infrastructure modules with centralized power and cooling appeal to space-constrained facilities. Northern Virginia colocation operators deploy these configurations to maximize compute per square foot within existing building envelopes.
- Tower Servers:Standalone vertical enclosures suited to branch office and small business deployments. These systems serve distributed enterprise locations across the U.S. Midwest with moderate compute requirements.
- Microservers:Compact single-socket units optimized for lightweight web serving and content delivery. Hyperscale operators deploy these at the network edge to reduce latency for streaming and caching workloads.
Rack servers anchor the volume base while blade servers gain share at the steepest rate.
End User:
Cost tiers separate capital-constrained buyers from those prioritizing operational flexibility and compliance certification.
- Cloud Providers:Hyperscale operators with direct-to-fab foundry relationships and custom silicon programs. These buyers command the steepest volume discounts and drive industry-wide standards for power efficiency and rack-scale management.
- Enterprises:Fortune 500 manufacturers, financial services firms, and healthcare systems with hybrid infrastructure requirements. U.S. Northeast healthcare verticals favor OpEx procurement models to reduce compliance overhead.
- Government Agencies:Federal civilian and defense buyers constrained by FedRAMP authorization pathways and NIST cybersecurity framework requirements. Procurement filters toward pre-qualified server architectures with verified supply chain provenance.
- Colocation Providers:Wholesale and retail data center operators leasing space to enterprise and cloud tenants. These intermediaries capture hardware spend shift through managed infrastructure contracts with embedded refresh guarantees.
Cloud providers anchor the volume base while government agencies expand procurement most quickly under federal cloud modernization mandates.
Installation:
Geographic dispersion and latency requirements create distinct margin profiles across deployment locations.
- On-Premises:Enterprise-owned facilities with dedicated power and cooling infrastructure. These deployments concentrate in legacy manufacturing corridors across Ohio, Michigan, and Illinois where operational technology integration demands local compute.
- Off-Site:Third-party colocation and wholesale data center leases. Northern Virginia's fiber density attracts the densest concentration of off-site capacity in North America.
- Hybrid:Split workloads across owned facilities and cloud resources. Financial services firms in New York and Boston favor this model to balance regulatory data sovereignty with burst capacity needs.
- Edge:Distributed micro data centers positioned within 10 milliseconds of operational networks. Autonomous logistics and smart manufacturing in the U.S. Midwest drive the steepest expansion trajectory for this category.
On-premises deployments anchor the volume base while edge installations expand most quickly.
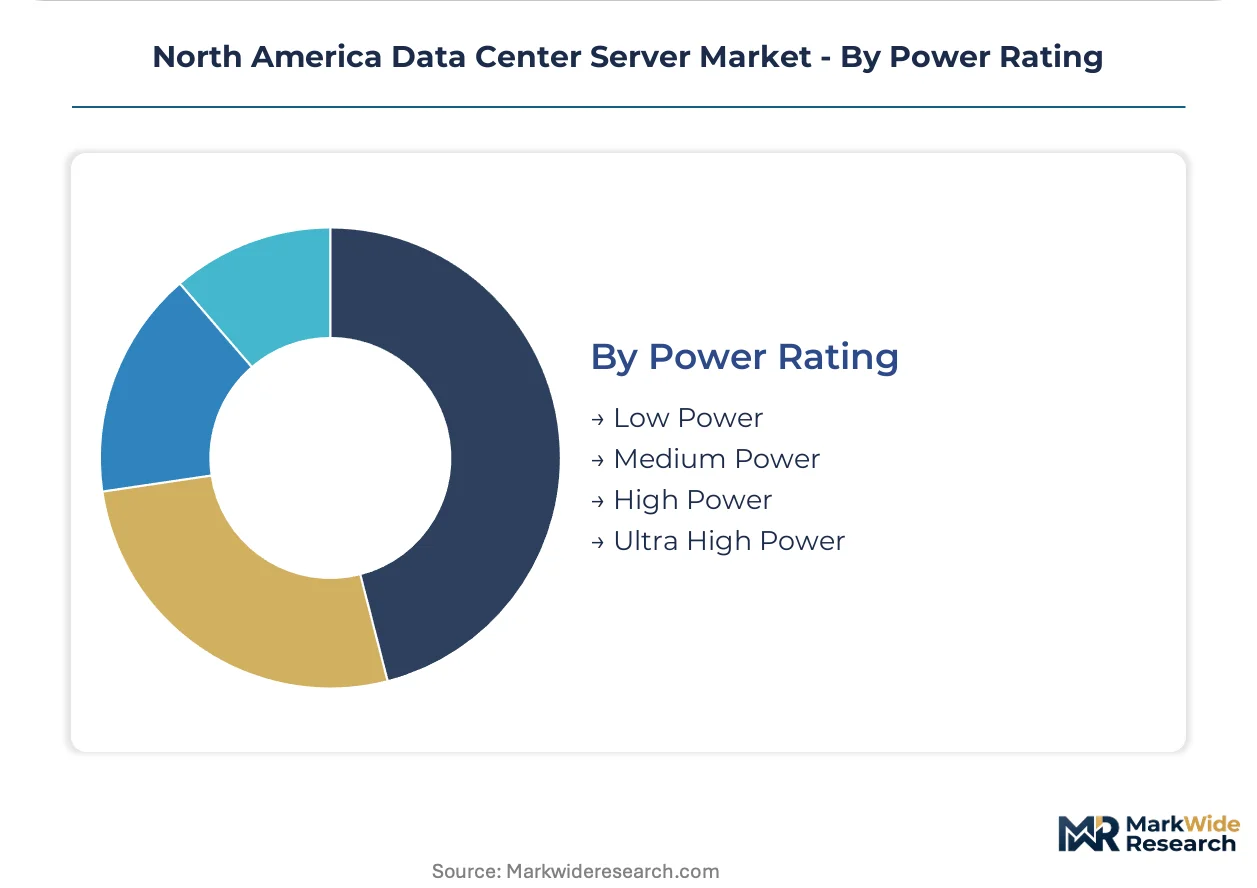
Power Rating:
Supply concentration in accelerated computing silicon shapes availability and pricing across power tiers.
- Low Power:Sub-150W processors for lightweight virtualization and storage serving. These systems populate remote branch offices across Canada where energy costs and cooling capacity are constrained.
- Medium Power:150-300W mainstream processors for general-purpose enterprise workloads. This tier captures the largest unit volume across North American corporate data centers.
- High Power:300-500W processors with dense memory configurations for in-memory analytics. Cloud providers in Dallas-Fort Worth deploy these for real-time data processing pipelines.
- Ultra High Power:500W-plus accelerated computing nodes with GPU or custom AI silicon. Phoenix hyperscale facilities lead North American deployment of liquid-cooled racks at these densities.
Medium power configurations anchor the volume base while ultra high power systems climb the fastest under AI training cluster expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian server shipments flow southward to hyperscale facilities across the United States, while Mexican assembly operations supply rack-scale components to Texas and Arizona cloud clusters. This cross-border trade pattern concentrates procurement leverage within U.S. enterprise and government buyers.
United States
Federal cloud modernization mandates and AI training cluster expansion drive procurement velocity. The EPA's ENERGY STAR server specifications and DOE efficiency benchmarking programs constrain allowable thermal design power envelopes. Northern Virginia's Loudoun and Prince William counties host the densest concentration of multi-megawatt deployments, where utility-scale power purchase agreements attract hyperscale operators building liquid-cooled training infrastructure.
Canada
Hyperscale operators leverage Quebec's hydroelectric surplus and Ontario's fiber density for cost-competitive capacity expansion. Natural Resources Canada and provincial regulators enforce energy efficiency standards that favor equipment with dynamic voltage-frequency scaling. Toronto and Montreal data center corridors attract cloud providers seeking carbon-neutral power sourcing for ESG-mandated enterprise clients.
Mexico
Nearshoring manufacturing automation and cross-border logistics networks generate edge compute demand for latency-sensitive operational technology integration. The Secretariat of Economy and federal energy regulatory frameworks govern industrial power allocation for data center loads. Querétaro and Nuevo León industrial corridors emerge as assembly hubs for rack-scale server components destined for U.S. Southwest hyperscale facilities.
Texas
ERCOT grid dynamics and renewable energy certificate markets reshape power procurement strategies for Dallas-Fort Worth training clusters. The Public Utility Commission of Texas and municipal economic development authorities negotiate tax incentive packages for multi-hundred-megawatt facilities. Austin and San Antonio technology corridors concentrate enterprise data center investment alongside semiconductor fabrication expansion.
California
Title 24 building efficiency standards and state-level carbon disclosure rules layer compliance complexity onto hardware refresh decisions. The California Energy Commission and Air Resources Board enforce idle-state power limits that accelerate generational turnover. Silicon Valley and Los Angeles Basin facilities prioritize liquid cooling retrofits to maintain deployment density under tightening thermal regulations.
North America Data Center Server Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers defined by volume scale and compliance certification requirements. The vendor base stratifies between hyperscale-direct suppliers with custom silicon programs and enterprise-focused integrators serving regulated verticals. Three archetypes dominate: full-stack infrastructure vendors, modular system specialists, and component-assembly contract manufacturers. Competitive positioning hinges on FedRAMP pre-qualification speed and liquid cooling system integration capabilities.
Among U.S.-based infrastructure vendors, Dell Inc and Hewlett Packard Enterprise exemplify the full-stack archetype with broad enterprise coverage, while Super Micro Computer Inc occupies a position within the modular specialist tier serving cloud-adjacent deployments. These three anchors represent distinct procurement pathways: direct volume relationships with hyperscale operators, managed service bundling for Fortune 500 refresh cycles, and rapid-turn custom configurations for latency-optimized edge clusters.
| Leading Market Players |
|---|
| Dell Inc |
| Hewlett Packard Enterprise |
| Lenovo Group Limited |
| Cisco Systems Inc |
| International Business Machines Corporation |
| Super Micro Computer Inc |
| Fujitsu Limited |
| Huawei Technologies Co Ltd |
| Inspur Group |
| Others |
Cost & Logistics Intelligence
Undercapacity in advanced packaging and foundry nodes for AI accelerators is compressing supplier margins while amplifying pricing power for tier-one cloud providers with direct allocation agreements. This utilization squeeze forces enterprise buyers toward longer-term contracts and pre-qualified configurations that bypass spot-market volatility.
Pricing Analysis
Current-generation AI-optimized servers command substantial premiums over prior-generation x86 configurations, while next-generation liquid-cooled rack architectures are pre-selling at contracted rates before volume availability. Three-tier pricing structure across premium liquid-cooled AI clusters, standard air-cooled enterprise racks, and economy tower configurations for branch offices stratifies the market. Cost compression in standard enterprise tiers is intensifying because hyperscale direct procurement is bypassing traditional channel markups. Cloud providers exhibit the lowest price sensitivity due to performance-per-watt calculations, while mid-market enterprises with amortization schedules face the highest budget constraints.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese ODMs and Mexican assembly operations serving North American hyperscale facilities. Supply concentrates in Taiwan for advanced GPU and custom AI silicon packaging, the United States for high-value system integration and firmware development, and Mexico for rack-scale mechanical assembly and logistics staging. Raw material dependencies center on high-bandwidth memory substrates, liquid cooling fluids and cold-plate alloys, and specialized power delivery components. Single-source vulnerability in advanced semiconductor packaging creates allocation risk during demand surges. Distribution runs through direct hyperscale relationships, systems integrator channels for federal and enterprise accounts, and colocation provider managed infrastructure contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against cloud-native disaggregated compute architectures that bypass traditional server form factors entirely. The threat of custom silicon programs and ARM-based cloud-native designs requires immediate strategic response.
For Market Incumbents: Pre-empt cloud-native disaggregation by accelerating liquid cooling integration capabilities and securing FedRAMP pre-qualification velocity for federal procurement windows. Backward integration into high-bandwidth memory supply channels defends allocation priority during semiconductor shortages. Channel control through colocation provider managed infrastructure partnerships captures OpEx-shifted enterprise spend.
For New Entrants and Emerging Players: Canadian edge compute corridors around Toronto and Montreal represent underpenetrated white space where hydroelectric power sourcing attracts ESG-mandated enterprise clients. Autonomous logistics micro data centers in the U.S. Midwest offer second entry point with compressed sales cycles and reduced hyperscale competitive pressure. Go-to-market positioning through systems integrators with existing federal relationships accelerates credibility building.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled AI infrastructure sub-segments as rack densities exceed 100kW and facility retrofit costs escalate. Long-term viability favors suppliers with demonstrated thermal management integration and hyperscale reference architectures. Acquisition target archetype: modular system specialists with direct liquid cooling IP and established cloud provider relationships. Signal to watch: hyperscale capex guidance revisions and foundry allocation announcements as demand inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling System Integration | Phoenix hyperscale facilities now require 100kW-plus rack densities under EPA thermal regulations. |
| FedRAMP Pre-Qualification Acceleration | Federal cloud modernization mandates filter procurement toward pre-authorized hardware configurations. |
| Direct Foundry Relationships | Cloud providers with custom silicon programs command allocation priority during GPU supply constraints. |
| Edge Micro Data Center Deployment | Midwest manufacturing automation demands sub-10ms latency positioning near operational technology networks. |
| Hardware-as-a-Service Model Expansion | U.S. Northeast healthcare verticals favor OpEx procurement to reduce compliance overhead and refresh risk. |
Research Approach
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, SEC 10-K filings, and Department of Energy efficiency benchmarking reports. Primary interviews engaged data center facility engineers, federal procurement officers, cloud provider infrastructure planners, and colocation provider sales directors. Secondary validation drew from EPA ENERGY STAR specifications, FedRAMP authorized product listings, and ERCOT interconnection queue data. Bottom-up server shipment estimates triangulate against top-down infrastructure investment tracking.
Forecast inputs include modeled expansion across rack, blade, and edge form factors; power rating tiers from sub-150W through 500W-plus accelerated computing; and installation types spanning on-premises, off-site colocation, hybrid, and edge deployments. Server procurement patterns by cloud provider, enterprise, government agency, and colocation intermediary segment the demand outlook. CAGRs derive from facility pipeline tracking, utility-scale power purchase agreement announcements, and generational refresh cycle compression signals. AI training cluster buildouts and liquid cooling retrofit penetration serve as primary volume drivers across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native silicon designers or ARM ecosystem entrants would shift outcomes beyond modeled ranges. Supply chain disruption from foundry allocation constraints, interconnection permitting delays, or NIST cybersecurity framework revisions could compress or extend refresh timelines. Cross-checking against hyperscaler announced facility deployments and state-level renewable energy mandate progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Retail Colocation Market
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Brazil Data Center Physical Security Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Vietnam Data Center Power Market