
 United States Data Center Market | 2026-2036
United States Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
United States Data Center Market Outlook
Software-defined power management is decoupling infrastructure provisioning from physical site ownership, enabling more flexible capacity planning. Amazon Web Services Inc. leverages its custom silicon program to sustain cost advantages in AI training clusters. Microsoft Corporation anchors its expansion strategy around nuclear energy partnerships for baseload carbon-free compute. Equinix Inc. differentiates through distributed interconnection fabrics that compete with centralized hyperscale campuses.
A data center constitutes a purpose-built facility housing servers, storage systems, networking equipment, and power distribution infrastructure designed to process, store, and transmit digital information at enterprise scale, typically maintaining temperatures between 18 and 27 degrees Celsius through precision cooling systems. These facilities serve as the physical backbone for cloud computing, artificial intelligence inference, and enterprise IT operations. Colocation providers capture the most stable margin pools by aggregating fragmented enterprise demand, while hybrid cloud deployments are expanding fastest as regulated industries seek workload portability between on-premises and off-premises environments. Disaster recovery services command premium pricing from BFSI end users requiring sub-hour recovery point objectives.
EPA emissions standards and FERC interconnection rules are tightening siting requirements for new hyperscale facilities, pushing developers toward renewable energy certificates and behind-the-meter generation. OSHA workplace safety mandates and state-level building codes in Virginia, Texas, and Arizona shape operational compliance costs across the national footprint. State utility commissions in Georgia and Ohio are reforming rate structures to accommodate gigawatt-scale load additions. Stakeholders must evaluate water-stressed locations against emerging cooling technology alternatives as permitting timelines extend and community opposition intensifies.
Market Dynamics
Generative AI compute demand is compressing data center deployment timelines from 24 months to under 12 months, forcing operators to pre-position land and power entitlements before workload commitments materialize.
Growth Catalysts
- IRA clean energy incentives:Tax credits for solar, wind, and battery storage are accelerating renewable power purchase agreements for hyperscale facilities in Texas and Arizona.
- Edge inference workloads:Latency-sensitive AI applications are dispersing compute capacity toward secondary metros including Columbus, Salt Lake City, and Atlanta.
- Liquid cooling adoption:Direct-to-chip and immersion systems are unlocking rack densities above 100 kilowatts per cabinet for GPU clusters.
Market Restraints
- Transformer supply concentration:Domestic manufacturing capacity for high-voltage electrical transformers remains insufficient, extending lead times to 36 months for substation equipment.
- FERC interconnection queues:Backlogs exceeding 1,000 gigawatts across regional transmission organizations are delaying grid connections for new facilities in PJM and ERCOT territories.
- Water stress exposure:Evaporative cooling dependence in Phoenix and Las Vegas is triggering municipal moratoriums on new industrial water allocations.
Strategic Opportunities
- Nuclear SMR partnerships:Small modular reactor deployments in Ohio and Tennessee offer carbon-free baseload power independent of renewable intermittency.
- Secondary market penetration:Enterprise colocation demand in Minneapolis, Detroit, and Portland remains underserved relative to hyperscale concentration on the coasts.
- Heat reuse monetization:District heating integrations with municipal utilities in northern climates are converting waste thermal output into revenue streams.
Industry Challenges
- Electrical trades shortage:Licensed high-voltage electricians and substation technicians command 40 percent wage premiums above construction industry medians, constraining build velocity.
- Permitting timeline volatility:County-level zoning disputes in Loudoun County, Virginia and Prince William County are extending approval cycles beyond historical baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Data Center Market |
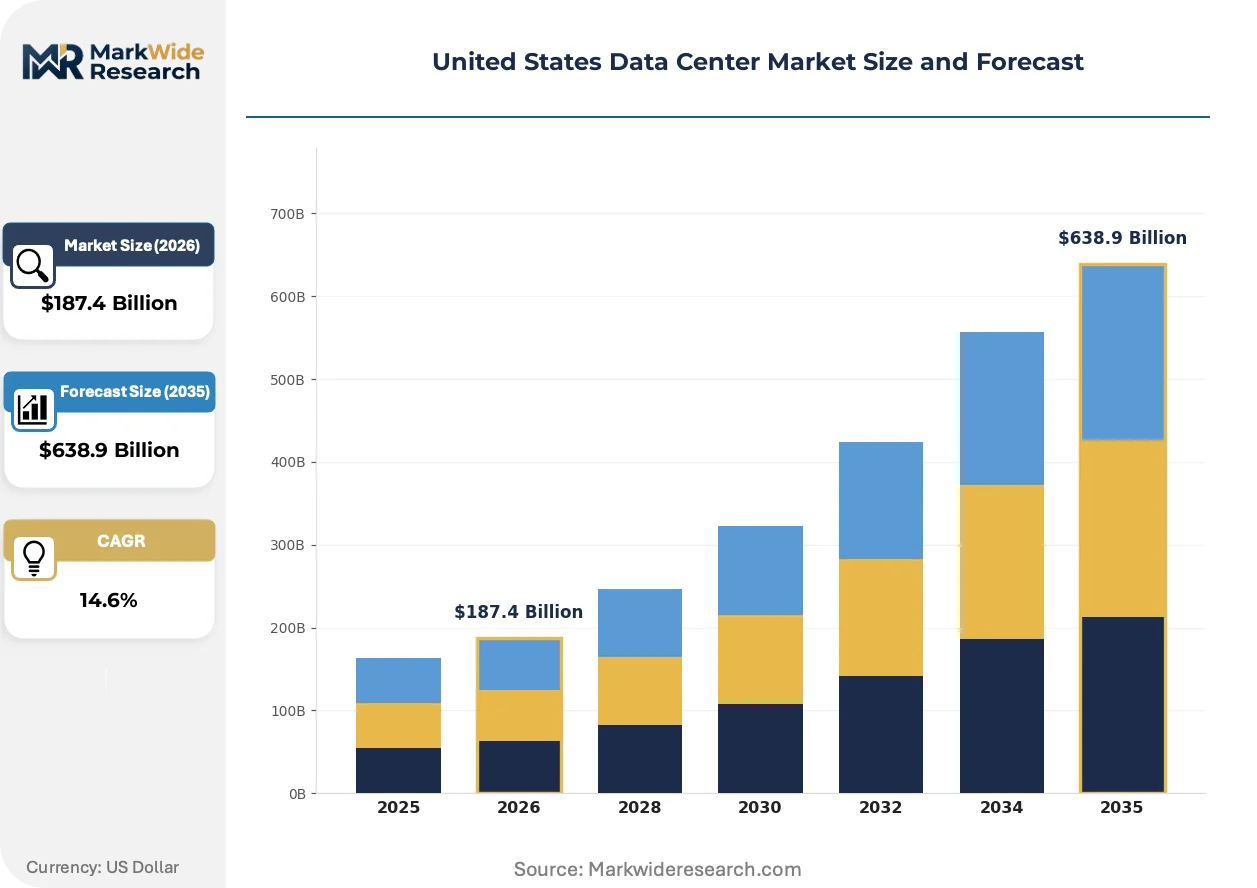
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Services, Dedicated Hosting, Hybrid Cloud Service Type: Infrastructure as a Service, Platform as a Service, Disaster Recovery, Backup Services End User: IT & Telecommunications, BFSI, Healthcare, Government Deployment Model: On-Premises, Off-Premises, Multi-Cloud, Private Cloud |
| Companies Covered | Digital Realty Trust Inc., Equinix Inc., Amazon Web Services Inc., Microsoft Corporation, Google LLC, QTS Data Centers, Vantage Data Centers, CyrusOne, Meta Platforms Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Data Center Market Strategic Shifts
Software-defined infrastructure is dissolving traditional boundaries between compute, storage, and networking layers, enabling workload portability across heterogeneous facility architectures without physical reconfiguration.
Modular data center designs are decentralizing deployment authority from centralized engineering teams to regional site managers. Retail and wholesale colocation operators are standardizing 250-kilowatt prefabricated units for rapid assembly. This architecture is decentralizing capital allocation decisions and compressing facility commissioning from 18 months to 90 days in satellite markets.
EPA emissions performance standards for stationary combustion turbines are tightening nitrogen oxide limits for on-site natural gas generation. The rule is forcing operators to retire legacy backup systems or install selective catalytic reduction. Facilities in California and the Northeast are responding by oversizing battery storage to eliminate runtime dependencies on fossil fuel generators.
Enterprise procurement teams are consolidating vendor relationships from multi-provider architectures to single-source hyperscale contracts with workload portability guarantees. Financial services and healthcare buyers are driving this consolidation to simplify compliance attestation. The pattern is most pronounced in Illinois and Massachusetts where state privacy regulations amplify vendor due diligence burdens.
United States Data Center Market Segmentation
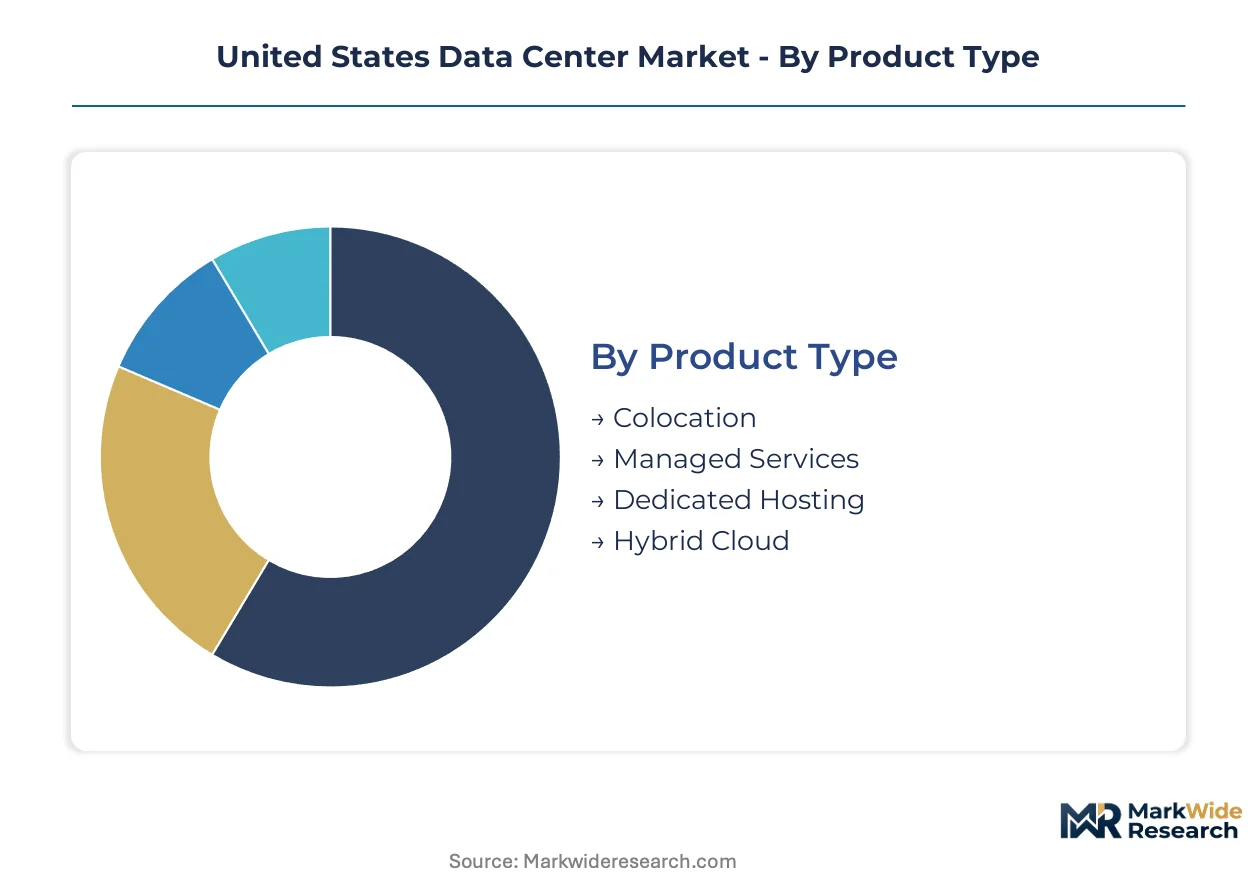
Workload portability requirements and regulatory compliance burdens are fragmenting procurement patterns across deployment architectures. Understanding where demand concentrates versus where margins stabilize requires disaggregating service models from underlying infrastructure ownership structures.
Product Type:
Standalone facility ownership separates capital-intensive builds from operational service delivery, while embedded infrastructure models embed compute within broader enterprise IT contracts.
- Colocation:Third-party facilities lease power, cooling, and physical security to multiple tenants sharing common infrastructure. Demand concentrates among financial services firms in Northern Virginia and Dallas seeking proximity to cloud on-ramps without hyperscale commitments. FERC interconnection delays in PJM territory constrain new supply additions despite backlog depth.
- Managed Services:Operators assume full responsibility for server administration, patch management, and capacity planning under recurring contracts. Healthcare systems in Massachusetts and Illinois favor this model to satisfy HIPAA audit requirements without expanding internal IT headcount. Labor scarcity for certified database administrators limits provider scalability.
- Dedicated Hosting:Single-tenant server deployments offer hardware isolation without facility ownership burdens.
- Hybrid Cloud:Workload orchestration across on-premises and off-premises environments enables burst capacity for seasonal demand spikes.
Volume placements concentrate in Colocation; the faster expansion belongs to Hybrid Cloud.
Service Type:
Abstraction depth determines pricing power — infrastructure primitives commoditize fastest while application-layer orchestration retains differentiation.
- Infrastructure as a Service:Raw compute, storage, and network resources delivered through programmatic APIs with metered consumption. State government contracts in Ohio and Georgia are consolidating procurement under statewide IaaS vehicles to reduce shadow IT proliferation. IRA clean energy credits are reshaping provider site selection toward Texas wind corridors.
- Disaster Recovery:Synchronous and asynchronous replication services maintaining recovery point objectives under one hour for mission-critical workloads. BFSI end users in New York and California command premium pricing for active-active configurations spanning seismic zones. EPA emissions standards for backup generation are extending commissioning timelines.
- Platform as a Service:Managed runtime environments abstracting operating system maintenance from application developers.
- Backup Services:Immutable object storage for ransomware-resistant data protection with air-gapped retention policies.
Contract value concentrates in Disaster Recovery; Platform as a Service is climbing the fastest.
End User:
Regulatory intensity and data sovereignty requirements segment procurement authority across verticals.
- BFSI:Banks, insurers, and capital markets firms operate under SEC cybersecurity disclosure rules and state-level data residency mandates. Multi-cloud deployments are expanding most quickly as firms disaggregate critical workloads across providers to satisfy operational resilience supervision. FedRAMP authorization requirements filter vendor eligibility for federal-facing subsidiaries.
- Healthcare:Hospital systems and payers navigate HIPAA security rule enforcement and state privacy laws in California and Massachusetts. Edge inference workloads for diagnostic imaging are dispersing capacity toward secondary metros including Columbus and Salt Lake City. OSHA workplace safety mandates shape facility staffing ratios.
- IT & Telecommunications:Technology vendors and carriers consuming wholesale capacity for resale or internal platform engineering.
- Government:Federal, state, and municipal agencies procuring through FedRAMP, StateRAMP, and agency-specific authorization frameworks.
Procurement scale concentrates in BFSI; Healthcare is gaining share fastest.
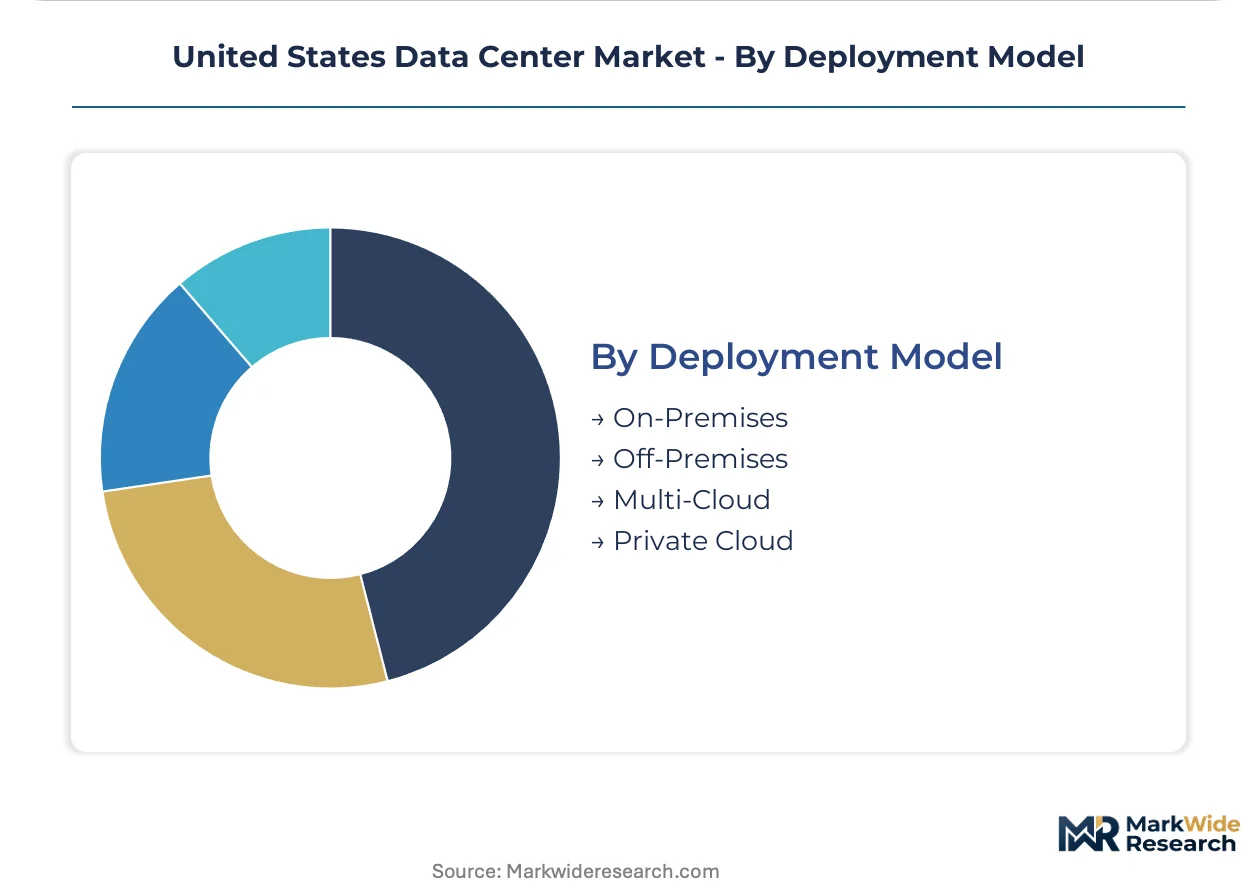
Deployment Model:
Control retention versus operational offload defines the architectural spectrum from captive facilities to fully abstracted consumption.
- Off-Premises:Workloads execute in third-party facilities with no customer capital deployed in physical infrastructure. Hyperscale cloud providers anchor expansion in Northern Virginia, Phoenix, and Dallas to serve generative AI training clusters. Water stress exposure in Arizona is triggering cooling technology substitutions.
- Multi-Cloud:Orchestration layers distribute workloads across two or more hyperscale providers to mitigate concentration risk. Enterprise procurement teams in Illinois and Massachusetts are consolidating vendor relationships while demanding portability guarantees. Transformer supply concentration constrains facility build velocity.
- On-Premises:Customer-owned facilities retaining full operational control over hardware and environmental systems.
- Private Cloud:Dedicated infrastructure operated for single-tenant use with cloud-native management interfaces.
Existing capacity concentrates in Off-Premises; Multi-Cloud is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center capacity concentrates in coastal metros while inland regions absorb overflow from power-constrained primary markets. Consumption gravity follows fiber density and tax incentive structures rather than population distribution.
Northern Virginia
Loudoun and Prince William counties host the densest hyperscale clustering in the United States. FERC interconnection queues in PJM territory extend approval timelines beyond historical baselines. Data center operators pre-position land entitlements years ahead of workload commitments to secure power allocation.
Texas
Dallas-Fort Worth and Austin metros attract IRA clean energy credit-driven solar and wind power purchase agreements. ERCOT grid interconnection backlogs delay substation energization for new facilities. Vantage Data Centers and CyrusOne anchor multi-hundred-megawatt campuses in the Dallas metroplex.
Arizona
Phoenix and Mesa markets face municipal water allocation moratoriums for evaporative cooling-dependent designs. EPA emissions standards for backup generation extend commissioning timelines for new builds. Liquid cooling technology substitutions are unlocking development in water-stressed locations.
Ohio
Columbus and Cincinnati metros emerge as secondary markets for latency-sensitive edge inference workloads. State utility commission rate reforms accommodate gigawatt-scale load additions from hyperscale tenants. Nuclear SMR partnerships in the state offer carbon-free baseload alternatives to renewable intermittency.
Oregon
Hillsboro and Portland markets leverage hydroelectric baseload for carbon-free compute operations. OSHA workplace safety mandates shape facility staffing ratios for operational compliance. Enterprise colocation demand in Portland remains underserved relative to hyperscale concentration on the coasts.
United States Data Center Market Competitive Environment
Capital-heavy real estate owners compete with asset-light cloud operators for control of customer relationships and margin pools. The market structures around three tiers: hyperscale cloud providers integrating vertically into facility ownership, wholesale colocation specialists aggregating multi-tenant demand, and retail colocation operators serving fragmented enterprise requirements. Dominant competitive moves include strategic partnerships for clean energy procurement and modular construction techniques compressing facility commissioning timelines.
Among real estate investment trust structures, Digital Realty Trust Inc. and Equinix Inc. exemplify the wholesale-retail spectrum in third-party facility provision. Amazon Web Services Inc., Microsoft Corporation, and Google LLC occupy positions as hyperscale cloud operators with captive infrastructure development capabilities. These entities represent divergent archetypes: the REIT model monetizing multi-tenant aggregation versus the cloud model capturing workload economics through vertical integration into physical infrastructure.
| Leading Market Players |
|---|
| Digital Realty Trust Inc. |
| Equinix Inc. |
| Amazon Web Services Inc. |
| Microsoft Corporation |
| Google LLC |
| QTS Data Centers |
| Vantage Data Centers |
| CyrusOne |
| Meta Platforms Inc. |
| Others |
Value Chain & Pricing Dynamics
Hyperscale-retail bifurcation separates rack-rate colocation from long-term power purchase agreements, embedding divergent margin structures across facility ownership models and procurement contract durations. Wholesale capacity commands fixed-escalation pricing indexed to utility rates, while retail tenants absorb spot-market volatility through shorter commitment windows. This tier divergence concentrates supply chain leverage with transformer manufacturers and electrical trades contractors serving the hyperscale pipeline.
Pricing Analysis
Cost-down pressure on retail colocation accelerates because hyperscale cloud providers internalize facility economics through captive development. Contract structures stratify across premium managed services, standard colocation, and economy remote-hands tiers, with price differentiation resting on certification density and interconnection proximity. FERC interconnection delays in PJM territory compress margins for new supply additions. Financial services buyers exhibit lowest price sensitivity due to regulatory compliance mandates, while mid-market enterprises drive commoditization through aggregated procurement vehicles.
Supply Chain Analysis
Domestic-content mandates in the Inflation Reduction Act are reshaping renewable energy component sourcing toward US-based solar and battery assembly. High-voltage electrical transformer supply concentrates in Mexico, South Korea, and domestic foundries with limited spare capacity. Data center construction draws from copper busbar, precision cooling equipment, and fiber optic cable feedstocks. Single-source vulnerability in transformer manufacturing extends substation equipment procurement timelines. Distribution runs through engineering-procurement-construction contractors with hyperscale-direct relationships bypassing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around power-entitlement holders as FERC interconnection queues strand capital-light competitors without secured grid positions. Weaker developers face absorption by vertically integrated hyperscale operators or wholesale specialists with pre-positioned land portfolios.
For Market Incumbents: Lock in transformer allocation commitments through 36-month forward contracts before domestic manufacturing capacity saturates. Secure nuclear SMR offtake agreements in Ohio and Tennessee to differentiate carbon-free baseload offerings against renewable-intermittent competitors. EPA emissions standards for backup generation threaten legacy gas turbine assets; accelerate battery storage oversizing to eliminate fossil fuel runtime dependencies.
For New Entrants and Emerging Players: Begin with underserved secondary metros including Minneapolis, Detroit, and Portland where enterprise colocation demand exceeds hyperscale supply concentration. Target healthcare systems in Massachusetts and Illinois seeking HIPAA-compliant managed services without internal IT expansion. Lead with modular prefabricated designs compressing commissioning timelines to 90 days against 18-month traditional builds.
For Investors and Strategic Acquirers: Exit pathways concentrate in REIT rollup transactions as scale advantages in power procurement and interconnection queue positioning compound. Long-term viability favors operators with 500+ megawatt secured capacity pipelines across multiple ISO territories. Watch FERC queue reform legislation as the inflection signal determining whether stranded interconnection positions convert to energizable assets or write-down liabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Nuclear SMR Partnership | Secures carbon-free baseload power independent of ERCOT and PJM renewable intermittency patterns. |
| Modular Prefabrication Scale-Up | Compresses facility commissioning from 18 months to 90 days in satellite markets lacking construction labor depth. |
| Liquid Cooling Technology Adoption | Unlocks rack densities above 100 kilowatts per cabinet for GPU-intensive generative AI training clusters. |
| Transformer Supply Forward Contracting | Locks in 36-month equipment allocation ahead of domestic manufacturing capacity constraints. |
| Secondary Metro Market Entry | Captures underserved enterprise colocation demand in Minneapolis, Detroit, and Portland relative to coastal hyperscale concentration. |
Study Parameters
SEC 10-K filings, FERC interconnection queue databases, and EIA electricity market data formed the secondary backbone for capacity and pricing calibration. Primary interviews with hyperscale cloud procurement officers, data center REIT development executives, electrical utility interconnection planners, and construction trade union representatives supplied forward-looking contract structures and labor market constraints. Bottom-up facility-level capacity builds and top-down utility load growth projections were triangulated against IRA incentive utilization rates.
Bottom-up modeling aggregated individual facility announcements across Northern Virginia, Texas, Arizona, Ohio, and Oregon markets, while top-down analysis tested aggregate capacity against utility commission load forecasts. Segmentation dimensions included deployment architecture, service abstraction layer, end-user vertical, and regional regulatory cluster. CAGRs were derived from capacity-weighted average growth across these segments. Forecast inputs incorporated transformer lead time trajectories, nuclear SMR development timelines, and municipal water allocation moratorium expansion patterns.
Underlying measurement precision varies by segment; hyperscale cloud deployments carry tighter precision than fragmented enterprise colocation due to disclosure requirements. Forecasts reflect assumptions on FERC queue reform progress, IRA credit continuity, and electrical trades labor supply elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
Belgium Data Center Physical Security Market