
 Singapore Data Center Market | 2026-2036
Singapore Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Market Insights
Cloud infrastructure engineering talent scarcity is unwinding capacity expansion timelines for several operators. Amazon Web Services leverages its established Singapore region to anchor enterprise hybrid deployments across Southeast Asia. Keppel Data Centres competes through deep waterfront land positions and captive power arrangements. ST Telemedia Global Data Centres sustains multi-tenant builds with direct submarine cable access.
A data center constitutes a dedicated facility housing servers, storage systems, and networking equipment with controlled temperature, humidity, and power density typically measured in megawatts per rack. These installations enable continuous data processing, cloud service delivery, and enterprise IT outsourcing with uptime commitments often exceeding 99.99%. Colocation remains the dominant product type as enterprises shed owned infrastructure, while hyperscale deployments absorb the bulk of new power allocations from the Energy Market Authority. Edge computing represents the fastest-growing architecture as latency-sensitive applications proliferate in Singapore's financial district and port logistics corridors.
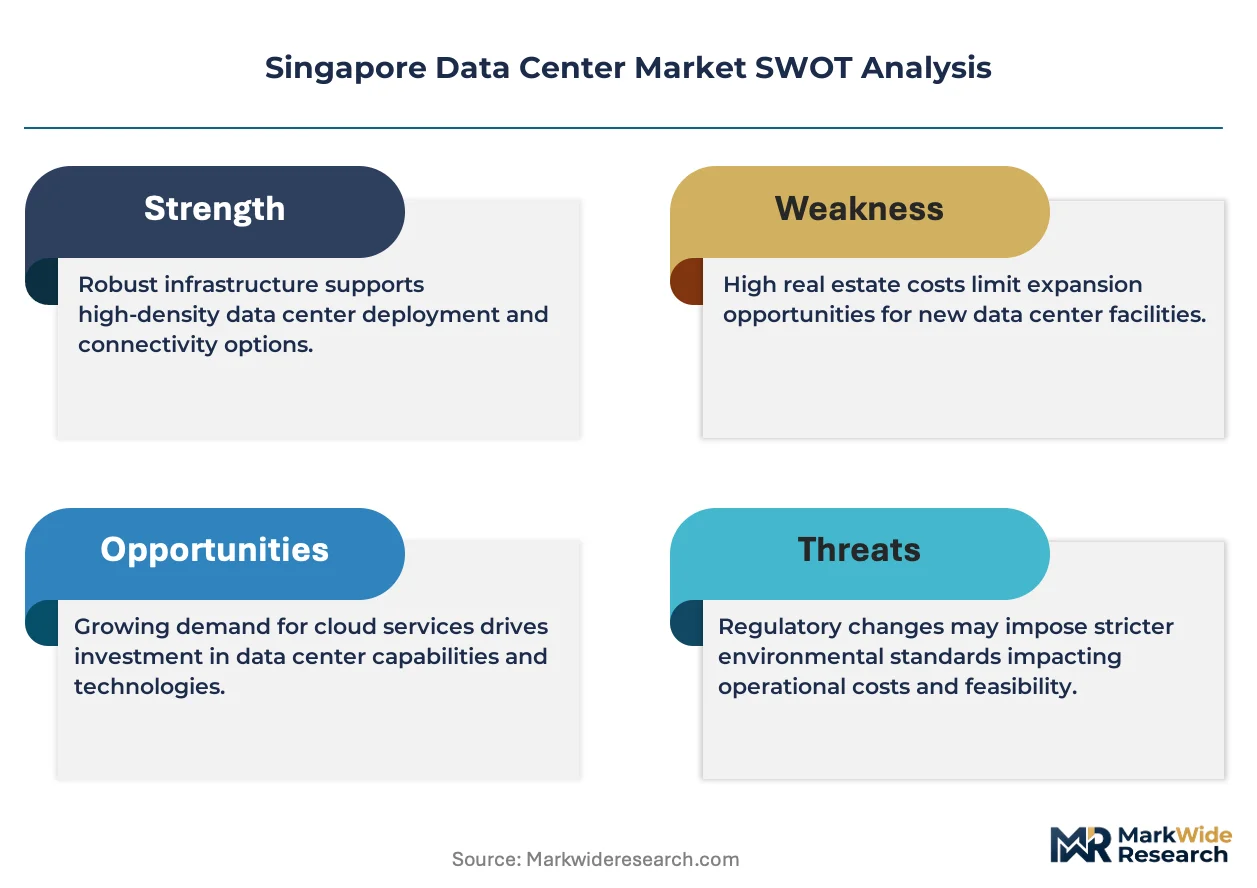
The Infocomm Media Development Authority governs data localization and cybersecurity certification under its Data Centre standards framework, while the Energy Market Authority enforces progressive efficiency benchmarks that shape cooling technology procurement. The Building and Construction Authority mandates Green Mark certification for new facilities, directly influencing capital intensity and design choices. Stakeholders must monitor policy shifts around carbon-adjusted power pricing and cross-border data flow agreements that could reshape facility economics and customer access.
Market Dynamics
Power density requirements from AI training clusters are compressing rack configurations and forcing liquid cooling retrofits across Singapore's established facilities.
Growth Catalysts
- IMDA Data Centre standards:The Infocomm Media Development Authority's efficiency mandates are accelerating equipment refresh cycles and opening procurement windows for advanced cooling systems.
- Financial services cloud migration:Digital banks and payment processors are expanding colocation footprints to meet latency requirements for real-time settlement systems.
- Jurong submarine cable cluster:Concentrated fiber landings from Southeast Asia-Europe and intra-Asia routes are anchoring hyperscale facility siting decisions.
Market Restraints
- Landed cost escalation:Waterfront industrial land scarcity in Loyang and Tuas is compressing site availability and inflating lease premiums for new entrants.
- Power procurement bottlenecks:Energy Market Authority allocation queues for high-voltage connections are extending facility commissioning timelines by 18-24 months.
- Skilled technician deficit:Local labor pools lack depth in direct liquid cooling installation and maintenance, constraining deployment velocity for next-generation builds.
Strategic Opportunities
- Tuas Port logistics corridor:Maritime automation and port digitization are generating edge computing demand for real-time container tracking and predictive maintenance.
- Green Mark Premium certification:Building and Construction Authority tiered incentives reward facilities exceeding baseline efficiency, creating margin expansion for early adopters.
- AI inference at edge:Convergence of 5G network slicing and GPU micro-servers is enabling low-latency model serving for autonomous vehicle testing zones.
Industry Challenges
- Retrofit complexity:Legacy raised-floor facilities face structural load limitations that complicate liquid cooling manifold installation and hot aisle containment.
- Cross-functional talent gaps:Facility engineering teams require simultaneous expertise in electrical infrastructure, mechanical cooling, and network architecture that training pipelines have not scaled to meet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Market |
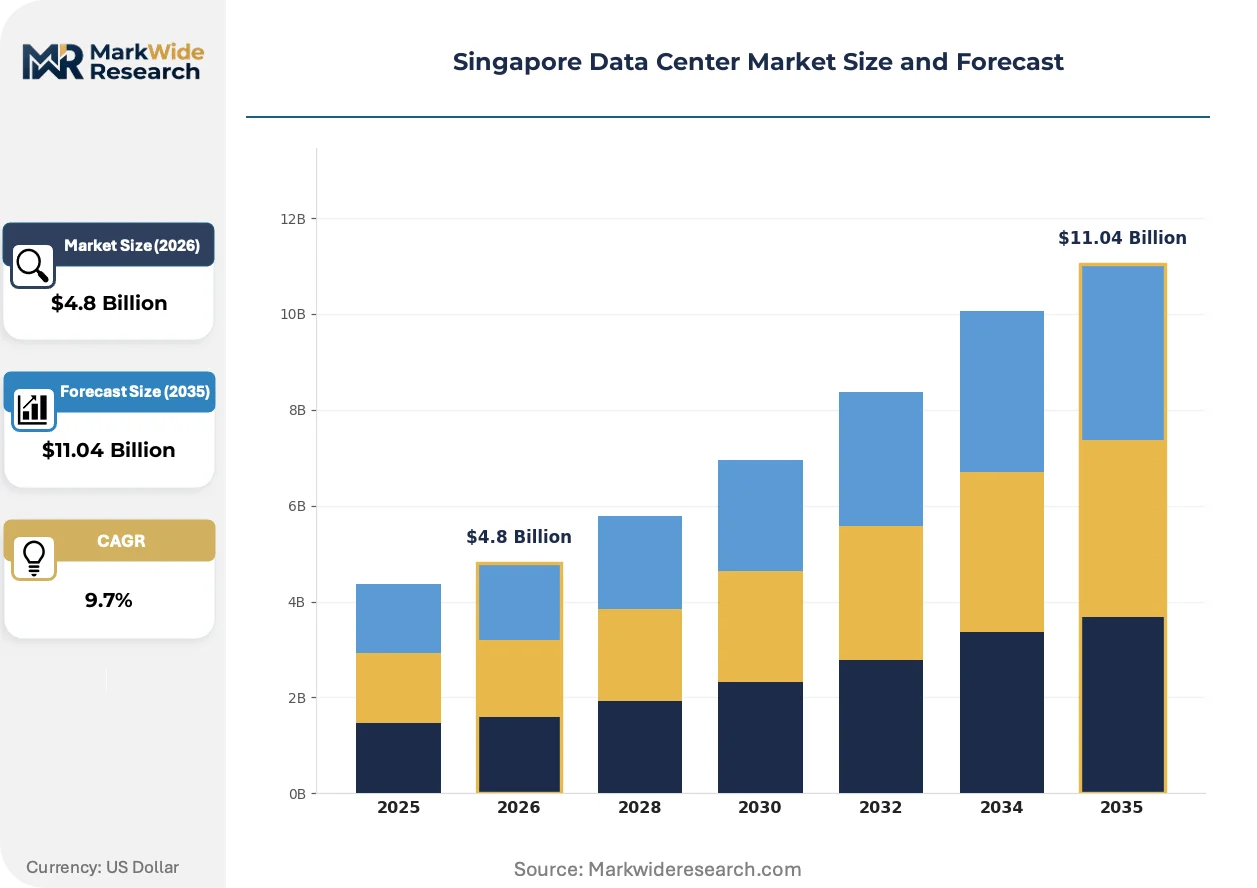
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Hyperscale, Managed Services, Edge Computing Technology: Cloud Computing, Virtualization, Cooling Solutions, Energy Efficiency End User: IT & Telecom, BFSI, Government, Healthcare Deployment: On-Premise, Off-Premise, Hybrid, Multi-Cloud |
| Companies Covered | Amazon Web Services, Google, Microsoft, Equinix, Digital Realty, Keppel Data Centres, ST Telemedia Global Data Centres, AirTrunk, NTT Global Data Centers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Market Trends and Innovations
Liquid cooling architectures are displacing traditional air-handling units as the dominant thermal management paradigm. Policy instruments are accelerating carbon accounting transparency. Procurement patterns are fragmenting as enterprise buyers unbundle managed services from pure colocation.
Immersion cooling systems using dielectric fluids are miniaturizing heat exchange footprints while enabling 50kW-plus rack densities. Hyperscale operators and AI cloud providers are adopting these systems at pilot scale in Singapore's Jurong facilities. The technology is miniaturizing mechanical plant requirements and compressing data hall spatial needs, allowing operators to extract more compute per square meter of scarce industrial land.
Singapore's Energy Market Authority is tightening progressive efficiency benchmarks under its Green Data Centre Roadmap. Facilities must now report granular power usage effectiveness metrics and disclose renewable energy procurement percentages. Colocation providers serving multinational enterprise clients are most affected, as these customers face Scope 3 emissions disclosure requirements from European headquarters.
Enterprise procurement of data center services is fragmenting across specialized providers rather than consolidating with single-vendor integrated stacks. Financial institutions are unbundling network connectivity, physical security, and remote hands services to optimize unit economics. This pattern is most visible among Singapore-based asset managers and trading desks with stringent latency requirements for co-located matching engines.
Singapore Data Center Market Segmentation
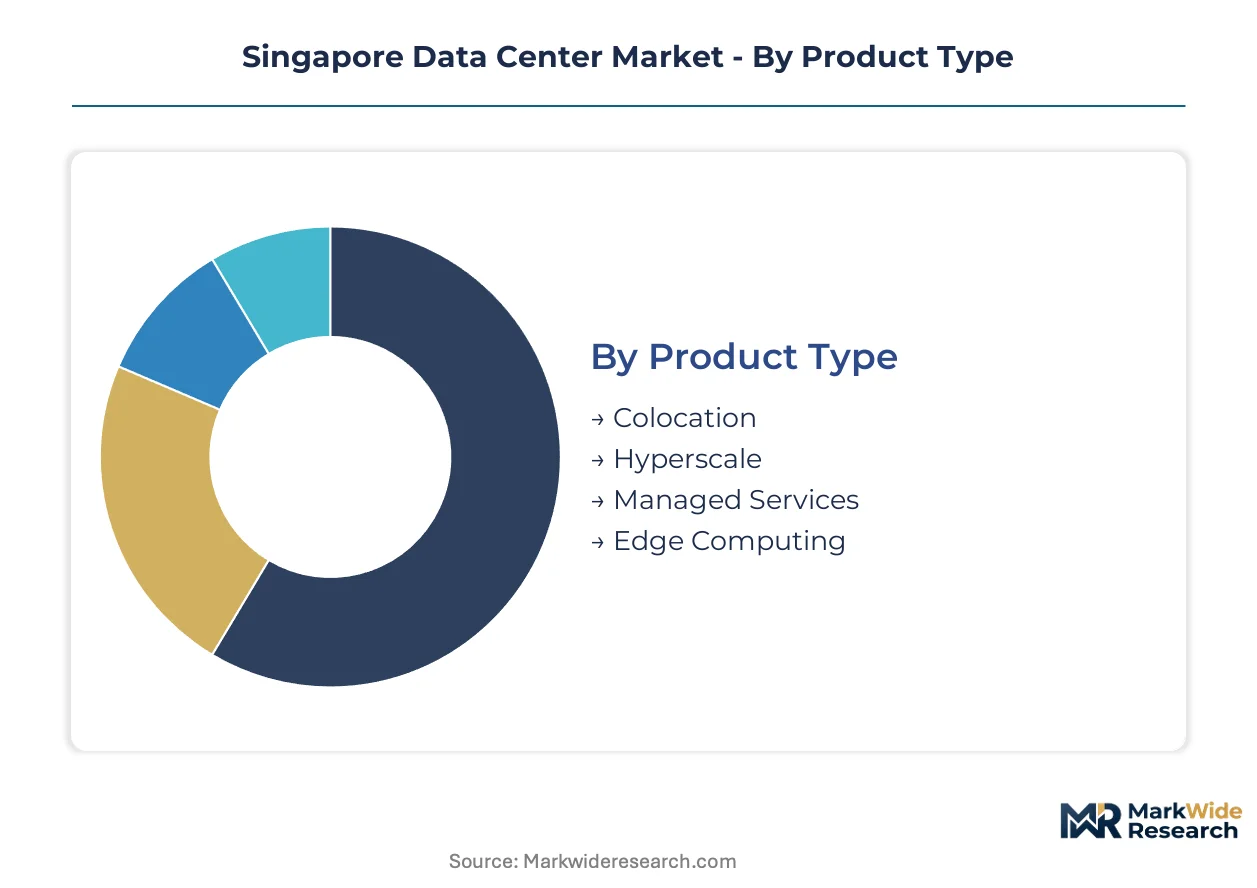
Singapore's data center market segments reflect divergent infrastructure economics and regulatory exposure. Operators must navigate distinct procurement patterns, cooling technology requirements, and customer compliance obligations across each dimension.
Product Type:
Colocation facilities face substitution pressure from hyperscale direct builds as cloud providers internalize capacity planning. Managed services confront erosion from cloud-native operational toolchains that reduce outsourcing dependency.
- Colocation:Multi-tenant facilities lease rack space, power, and cooling to enterprises shedding owned infrastructure. Singapore's financial district concentrates demand from asset managers requiring proximity to matching engines and low-latency connectivity to submarine cable landings.
- Hyperscale:Single-tenant campuses exceed 50 megawatts with standardized designs for cloud and AI training workloads. The Jurong industrial zone anchors facility siting due to concentrated fiber landings and Energy Market Authority power allocation availability.
- Managed Services:Remote hands, monitoring, and infrastructure management bundled with physical space. Demand fragments as enterprise buyers unbundle services to optimize unit economics.
- Edge Computing:Distributed micro-facilities positioned for sub-10 millisecond latency. Tuas Port logistics corridors and autonomous vehicle testing zones drive deployment for real-time container tracking and predictive maintenance.
Colocation anchors the volume base while Edge Computing gains share at the steepest rate.
Technology:
Cost tier differentiation separates premium liquid cooling deployments from baseline air-handling retrofits. Energy efficiency investments cluster in facilities serving European-headquartered enterprises with Scope 3 disclosure obligations.
- Cloud Computing:Distributed computing resources delivered over network infrastructure with on-demand provisioning. IMDA data localization requirements shape architecture decisions for multinational deployments.
- Virtualization:Software abstraction of compute, storage, and network resources enabling multi-tenancy density. Server consolidation ratios determine per-rack economics in land-constrained Singapore facilities.
- Cooling Solutions:Thermal management systems spanning air-handling units to dielectric fluid immersion. AI training clusters above 50kW per rack force liquid cooling retrofits in legacy raised-floor facilities.
- Energy Efficiency:Power usage effectiveness optimization and renewable energy procurement. Building and Construction Authority Green Mark certification tiers create margin expansion for early adopters exceeding baseline benchmarks.
Cooling Solutions commands capital deployment priority while Energy Efficiency climbs fastest as regulatory thresholds tighten.
End User:
Customer type concentration varies by compliance intensity and latency sensitivity. Financial services impose the most stringent physical security and network architecture specifications.
- IT & Telecom:Technology vendors and telecommunications operators hosting customer-facing platforms and network infrastructure. Content delivery and 5G core network functions concentrate demand in Jurong cable landing zones.
- BFSI:Banks, financial services, and insurance entities with real-time settlement and trading system requirements. Digital banks and payment processors expand footprints to meet Monetary Authority of Singapore operational resilience standards.
- Government:Public sector agencies with data sovereignty and classified processing mandates. Smart nation initiatives and digital government services drive secure facility procurement.
- Healthcare:Medical institutions and health technology platforms managing patient data and diagnostic imaging. Personal data protection requirements intersect with clinical system uptime commitments.
BFSI anchors revenue per square meter while Government expands most quickly on digitalization mandates.
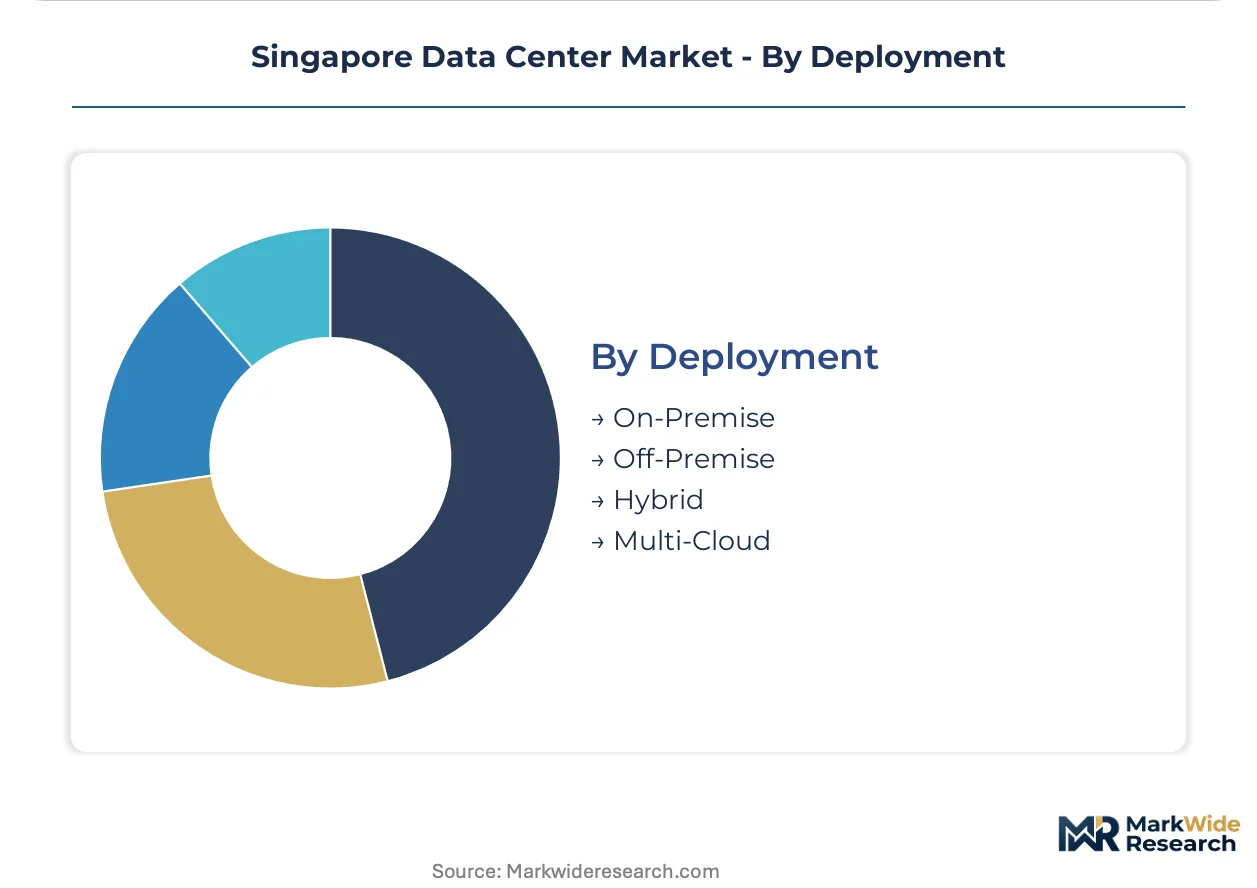
Deployment:
Maturity differentiation separates legacy on-premise estates from cloud-native architectures. Hybrid configurations dominate enterprise transition states as workload placement rationalizes across cost and performance dimensions.
- On-Premise:Enterprise-owned facilities with captive infrastructure and operational staff. Incumbents in Singapore's central business district face land lease renewal pressure and cooling retrofit costs.
- Off-Premise:Third-party facility utilization with full infrastructure outsourcing. Colocation providers capture migration from aging enterprise data halls in Tuas and Loyang industrial zones.
- Hybrid:Integrated on-premise and cloud infrastructure with workload portability orchestration. Amazon Web Services leverages its Singapore region to anchor enterprise hybrid deployments across Southeast Asia.
- Multi-Cloud:Distributed workloads across multiple hyperscale providers to mitigate vendor concentration risk. Financial institutions unbundle services across specialized providers to optimize latency and compliance posture.
Hybrid deployment anchors current enterprise commitment while Multi-Cloud gains adoption fastest among regulated sectors managing vendor risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore commands premium pricing for data center capacity versus regional alternatives, while Malaysia and Indonesia exploit land and power cost arbitrage to attract hyperscale builds. This pricing-power asymmetry is reshaping Southeast Asian facility deployment patterns as workload placement rationalizes across cost and latency dimensions.
Malaysia
Iskandar Puteri and Cyberjaya clusters absorb overflow demand from Singapore-constrained operators seeking lower land and electricity tariffs. The Malaysian Investment Development Authority's tax incentives for technology investments accelerate foreign direct investment in Johor data center zones. Kulai and Sedenak industrial parks host emerging hyperscale campuses with direct fiber links to Singapore cable landing stations.
Indonesia
Batam and Bintan islands leverage submarine cable proximity to Singapore while operating outside its regulatory perimeter. The country's national telecommunications regulator imposes data localization requirements that mandate domestic facility investment for financial services and government workloads. Nongsa Digital Park anchors cross-border capacity as operators exploit Indonesia's renewable energy procurement flexibility.
Thailand
Bangkok's Eastern Economic Corridor attracts enterprise colocation demand from regional headquarters operations requiring Thai-language support and domestic compliance certification. The Digital Economy Promotion Agency's investment privileges reduce effective tax rates for certified data center projects. Chonburi and Rayong industrial zones concentrate new builds with direct high-voltage grid connections from the Electricity Generating Authority.
Philippines
Manila and Cebu capture demand from business process outsourcing operators and gaming platforms requiring low-latency Southeast Asian connectivity. The national information and communications technology regulator enforces cybersecurity compliance frameworks that elevate facility certification requirements. Clark Freeport Zone offers tax holidays and simplified customs procedures for imported server equipment.
Vietnam
Ho Chi Minh City and Hanoi emerge as edge computing locations for manufacturing automation and port digitization across the Mekong Delta. The Ministry of Information and Communications mandates local data storage for specific categories of personal and financial information. Thu Duc City and Bac Ninh Province concentrate foreign-invested facilities with proximity to Samsung and Intel manufacturing ecosystems.
Singapore Data Center Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cloud hyperscalers driving innovation in liquid cooling and AI-optimized infrastructure while regional specialists exploit land positions and captive power arrangements. The market structure consolidates around three tiers: global hyperscalers with standardized designs, regional platform operators with multi-market footprints, and local specialists with deep regulatory relationships. Strategic differentiation runs through waterfront land access, submarine cable proximity, and Energy Market Authority power allocation queues. Competitive moves concentrate on securing industrial land in Jurong and Tuas ahead of zoning restrictions, and retrofitting legacy facilities for liquid cooling densities above 50kW per rack.
Among global hyperscalers, Amazon Web Services, Google, and Microsoft anchor enterprise hybrid deployments and AI training clusters across Southeast Asia. Regional platform operators include Equinix and Digital Realty, which occupy positions emphasizing interconnection density and multi-market consistency for multinational enterprises. Local specialists Keppel Data Centres and ST Telemedia Global Data Centres exemplify archetypes built on Singapore-specific advantages: deep waterfront land positions, direct submarine cable access, and regulatory navigation capabilities developed through decades of local operation.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Equinix |
| Digital Realty |
| Keppel Data Centres |
| ST Telemedia Global Data Centres |
| AirTrunk |
| NTT Global Data Centers |
| Others |
Pricing and Supply Chain Analysis
Long-term power purchase agreements with the Energy Market Authority lock in both electricity supply access and cost visibility for operators committing to multi-year capacity reservations. These contractual structures insulate established players from spot market volatility while constraining new entrants facing 18-24 month connection queues.
Pricing Analysis
The customization-premium spread separates liquid-cooled hyperscale deployments from standard air-handled colocation racks. Pricing stratifies across Green Mark certification tiers, with Building and Construction Authority incentives rewarding early efficiency adopters. Cost compression in baseline colocation intensifies as hyperscale direct builds absorb enterprise demand. Asset managers and trading desks exhibit lowest price sensitivity given latency requirements for submarine cable proximity.
Supply Chain Analysis
Strategic stockpiling of critical cooling components dominates procurement strategy as lead times for liquid cooling manifolds extend amid AI infrastructure buildouts. Supply concentrates in China for server hardware, Taiwan for advanced semiconductors, and Japan for precision cooling equipment. Copper and aluminum feedstock volatility complicates thermal infrastructure budgeting. Distribution runs through direct manufacturer relationships rather than distributor networks given customization requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's data center market represents a high-growth disruption as AI training clusters force liquid cooling retrofits and compress legacy facility economics. The Energy Market Authority's progressive efficiency benchmarks under its Green Data Centre Roadmap constitute the decisive regulatory inflection reshaping competitive positioning.
For Market Incumbents: Shield established Jurong and Loyang positions through captive waterfront land arrangements and direct submarine cable access. Prioritize liquid cooling retrofit partnerships to address structural load limitations in legacy raised-floor facilities. Accelerate Green Mark Premium certification to capture margin expansion before efficiency thresholds tighten further.
For New Entrants and Emerging Players: Lead with edge computing micro-facilities in Tuas Port logistics corridors where maritime automation generates underserved demand. Target autonomous vehicle testing zones and predictive maintenance applications requiring sub-10 millisecond latency. Position around unbundled service offerings as financial institutions fragment procurement across specialized providers.
For Investors and Strategic Acquirers: Regional platform operators with multi-market footprints and direct cable landing access represent the most defensible acquisition archetype. Long-term viability hinges on securing power allocation queues ahead of regulatory caps. Watch for carbon-adjusted power pricing proposals as the signal warranting portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Program | Enables 50kW-plus rack densities required by AI training clusters in Jurong facilities. |
| Green Mark Premium Certification | Captures Building and Construction Authority incentives ahead of baseline efficiency mandates. |
| Submarine Cable Landing Partnership | Secures low-latency fiber access for financial services colocation demand. |
| Tuas Port Edge Facility Development | Positions for maritime automation and port digitization workloads. |
| Power Purchase Agreement Extension | Locks in Energy Market Authority allocation before queue delays extend further. |
Research Methodology
A spread of perspectives from data center facility engineers, Energy Market Authority planning officers, enterprise IT procurement leads, and submarine cable operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through IMDA regulatory filings, Building and Construction Authority Green Mark databases, hyperscaler capex disclosures, and customs import records for cooling equipment. Bottom-up facility-level capacity tracking triangulated against top-down power allocation data from the Energy Market Authority.
Segmentation dimensions modeled span product type, cooling technology tier, end-user industry, and deployment architecture across the projection horizon. CAGRs derived from facility commissioning timelines, power density trajectories, and enterprise migration patterns. AI workload growth assumptions and IMDA efficiency benchmark schedules served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in IMDA data localization regimes and Energy Market Authority power pricing frameworks; material policy shifts would require re-modeling. Carbon-adjusted tariffs or cross-border data flow restrictions represent specific risk factors. Revision becomes warranted when liquid cooling deployment velocity crosses thresholds that compress legacy facility viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market